
 Japan Major Home Appliances Market | 2026-2036
Japan Major Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Major Home Appliances Market Foresight
Multi-source component procurement is restructuring supply relationships across Japan's appliance sector. Panasonic Corporation leverages captive semiconductor sourcing to shield production schedules from external volatility. Hitachi Global Life Solutions anchors its position through in-house compressor manufacturing, while Sharp Corporation competes aggressively in display-integrated refrigerator interfaces.
Japan major home appliances encompass electrically powered domestic equipment with rated capacities typically exceeding 100 liters for refrigeration or 5 kilograms for fabric care, engineered for continuous residential or light-commercial operation. These products incorporate hermetically sealed refrigeration circuits, inverter-driven motors, and corrosion-resistant coatings to achieve decade-long service intervals under humid summer conditions. Refrigerators command the largest revenue pool among product types, though air conditioners generate superior replacement frequency due to climate stress. Smart appliances within the technology dimension attract premium positioning, while energy-efficient variants align with utility rebate programs and tightening METI standards.
METI administers the Top Runner Program, which sets escalating efficiency benchmarks that manufacturers must meet or exceed across refrigerator and air conditioner categories. The Ministry of Economy, Trade and Industry also enforces JIS standards for electrical safety and electromagnetic compatibility, creating compliance thresholds that favor established domestic producers with dedicated certification laboratories. PMDA maintains oversight for appliances incorporating medical-grade air purification functions, a niche expanding through allergy-sensitive household demand. Stakeholders must monitor how impending revisions to carbon-neutral building codes reshape appliance specifications for new residential construction.
Market Dynamics
METI's Top Runner Program creates a regulatory ratchet that forces manufacturers to redesign core components every three to four years. This efficiency mandate compresses replacement cycles while raising engineering costs across refrigerator and air conditioner portfolios.
Growth Catalysts
- Urban densification:Tokyo's high-rise residential towers demand compact, multi-functional appliances with reduced footprint specifications.
- METI Top Runner Program:Escalating efficiency benchmarks accelerate consumer replacement of legacy units to meet new standards.
- Smart home integration:IoT-enabled appliances with remote monitoring capabilities attract premium positioning in new housing developments.
Market Restraints
- Copper and rare earth volatility:Compressor and motor manufacturers face input cost instability from concentrated Mongolian and Chinese supply.
- JIS certification complexity:Electrical safety testing timelines extend product launch windows by six to twelve months.
- Apartment size constraints:Tokyo's average residential floor area limits adoption of large-capacity refrigeration and laundry equipment.
Strategic Opportunities
- Osaka-Kobe corridor:Aging housing stock in western Japan presents replacement demand for energy-efficient cooling systems.
- Medical-grade air purification:PMDA-registered allergen filtration functions command price premiums in allergy-sensitive households.
- Utility rebate alignment:Regional power cooperatives offer installation incentives that reduce consumer payback periods for inverter-driven models.
Industry Challenges
- Semiconductor procurement:MCU shortages disrupt inverter controller production schedules and delay seasonal inventory builds.
- Refrigerant transition:Conversion from R-32 to lower-GWP alternatives requires retooling of sealed system manufacturing lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Major Home Appliances Market |
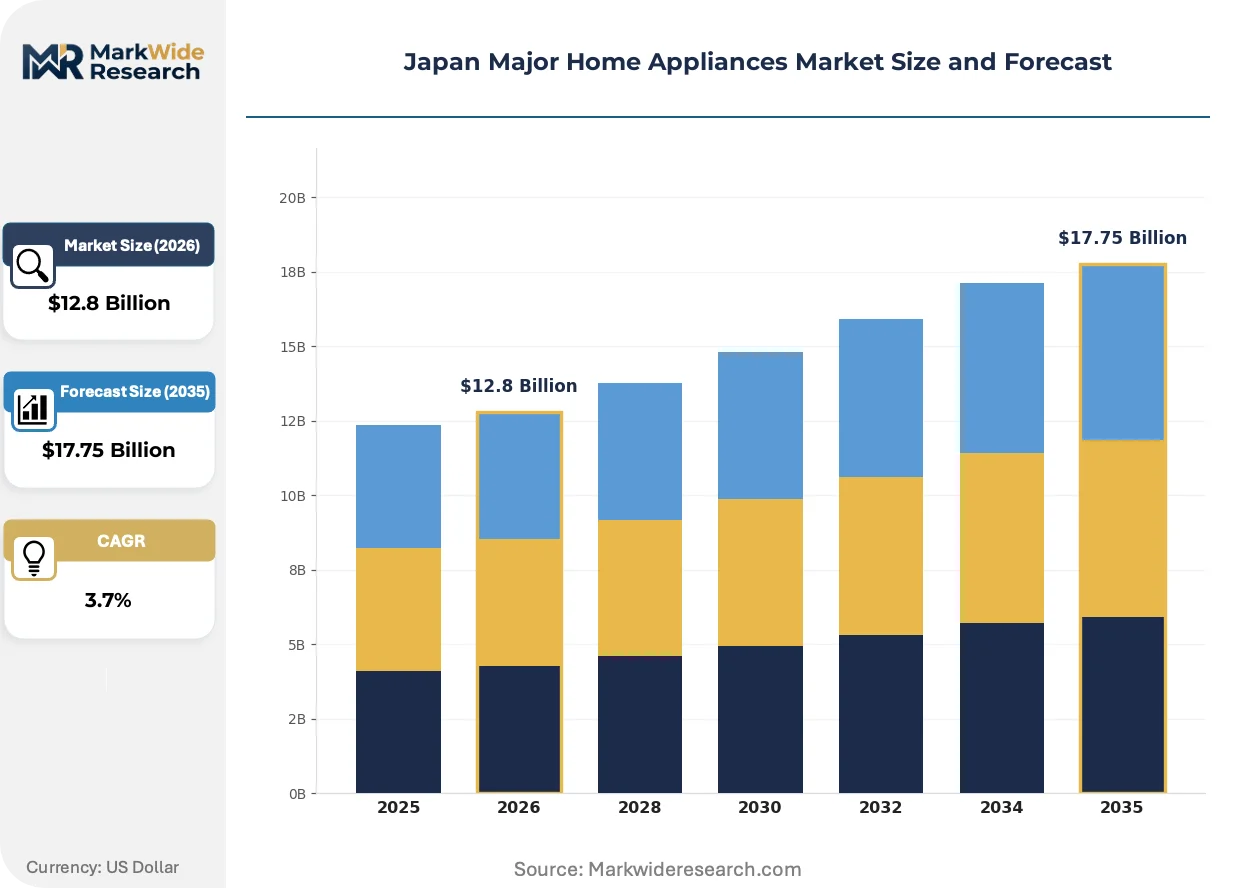
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $17.75 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Air Conditioners, Dishwashers End User: Residential, Commercial, Industrial, Hospitality Technology: Smart Appliances, Energy-Efficient, IoT-Enabled, Conventional Distribution Channel: Online Retail, Specialty Stores, Hypermarkets, Direct Sales |
| Companies Covered | Panasonic Corporation, Hitachi Global Life Solutions, Sharp Corporation, Toshiba Lifestyle Products & Services Corporation, Mitsubishi Electric Corporation, Daikin Industries, Zojirushi Corporation, Rinnai Corporation, Haier Japan, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Major Home Appliances Market Shifts & Advancements
Inverter-driven compressor technology now dominates new product introductions across cooling categories. Manufacturers are embedding connectivity modules as standard features rather than premium options.
Heat pump dryers are absorbing market share from conventional vented units in Tokyo's dense apartment complexes. Property developers specify these models for new construction where external venting is impractical. The technology is absorbing demand that previously flowed to laundromat services and shared facilities.
METI's carbon-neutral building code revisions will mandate appliance efficiency thresholds for new residential permits starting with commercial-scale developments. Builders in Yokohama and Saitama prefectures are pre-emptively sourcing compliant equipment to avoid construction delays. Air conditioner manufacturers with dedicated JIS certification laboratories capture specification advantages.
Appliance-as-service models are emerging through regional utility partnerships. Consumers in Hokkaido and Kyushu subscribe to cooling and heating equipment with maintenance bundled into monthly power bills. This arrangement displaces traditional retail purchase cycles and concentrates buyer relationships with energy retailers rather than electronics chains.
Japan Major Home Appliances Market Segmentation
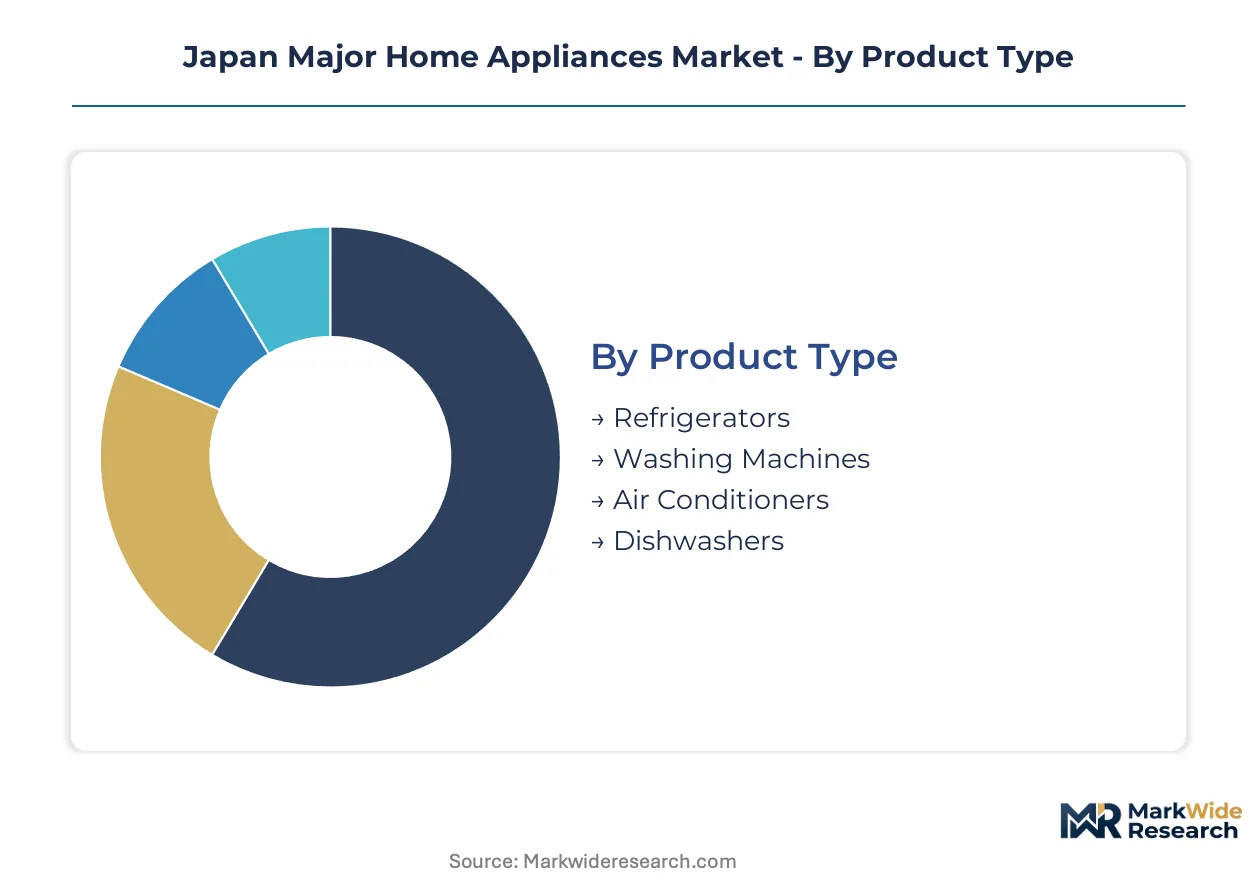
Segmentation reveals how Japan's appliance market fragments across competing value propositions. Product type and technology dimensions capture the efficiency mandates from METI, while distribution and end-user splits expose channel power shifts and housing-driven demand concentration.
Product Type:
Standalone refrigeration and climate systems dominate residential installations, while embedded multi-function units penetrate high-rise developments where space constraints override single-purpose preferences.
- Refrigerators:These units incorporate hermetically sealed circuits with inverter-driven compressors rated for decade-long service under humid summer conditions. Demand concentrates in Tokyo's high-rise residential towers, where compact multi-door configurations with reduced footprint specifications displace legacy single-door models.
- Air Conditioners:Split-system and window units feature corrosion-resistant coatings and seasonal inverter modulation to manage peak summer loads. Replacement frequency exceeds other categories due to climate stress, with Osaka-Kobe corridor aging housing stock driving cooling system upgrades.
- Washing Machines:Front-load and top-load configurations serve distinct installation constraints across Japan's varying residential floor plans.
- Dishwashers:Compact under-counter and countertop variants address Tokyo's limited kitchen footprints where manual washing previously dominated.
Volume placements concentrate in refrigerators; the faster expansion belongs to air conditioners.
End User:
Cost tier stratification separates mass residential procurement from specification-driven commercial installations, with hospitality and industrial segments demanding extended warranty terms and maintenance bundling.
- Residential:Urban high-rise buyers in Greater Tokyo Area drive adoption of space-efficient models with smart home integration capabilities. METI's Top Runner Program accelerates replacement cycles as households upgrade legacy units to meet escalating efficiency benchmarks.
- Commercial:Property developers in Yokohama and Saitama prefectures pre-emptively source compliant equipment to avoid construction delays under impending carbon-neutral building code revisions.
- Hospitality:Hotels and ryokan operators specify medical-grade air purification functions to capture allergy-sensitive travelers.
- Industrial:Light-manufacturing and food processing facilities demand continuous-duty ratings with dedicated certification laboratory validation for JIS electrical safety compliance.
Residential channels dominate unit placements; hospitality applications are climbing the fastest as tourism infrastructure expands.
Technology:
Maturity gradients separate established inverter architectures from emerging connectivity layers, with energy-efficient variants capturing utility rebate alignment and conventional models retreating to price-sensitive replacement segments.
- Smart Appliances:Connectivity modules embedded as standard features enable remote monitoring and predictive maintenance alerts. New housing developments in Tokyo specify these units for premium positioning, displacing traditional retail purchase cycles through regional utility subscription partnerships.
- Energy-Efficient:Inverter-driven compressor technology dominates new product introductions across cooling categories, with regional power cooperatives offering installation incentives that reduce consumer payback periods.
- IoT-Enabled:Appliances with embedded sensors and cloud integration support appliance-as-service models in Hokkaido and Kyushu where maintenance bundles into monthly power bills.
- Conventional:Non-connected, fixed-speed units persist in rural replacement markets and secondary housing stock where upfront cost sensitivity overrides efficiency premiums.
Energy-efficient variants command the largest placement volumes; IoT-enabled systems are gaining share fastest through utility partnership expansion.
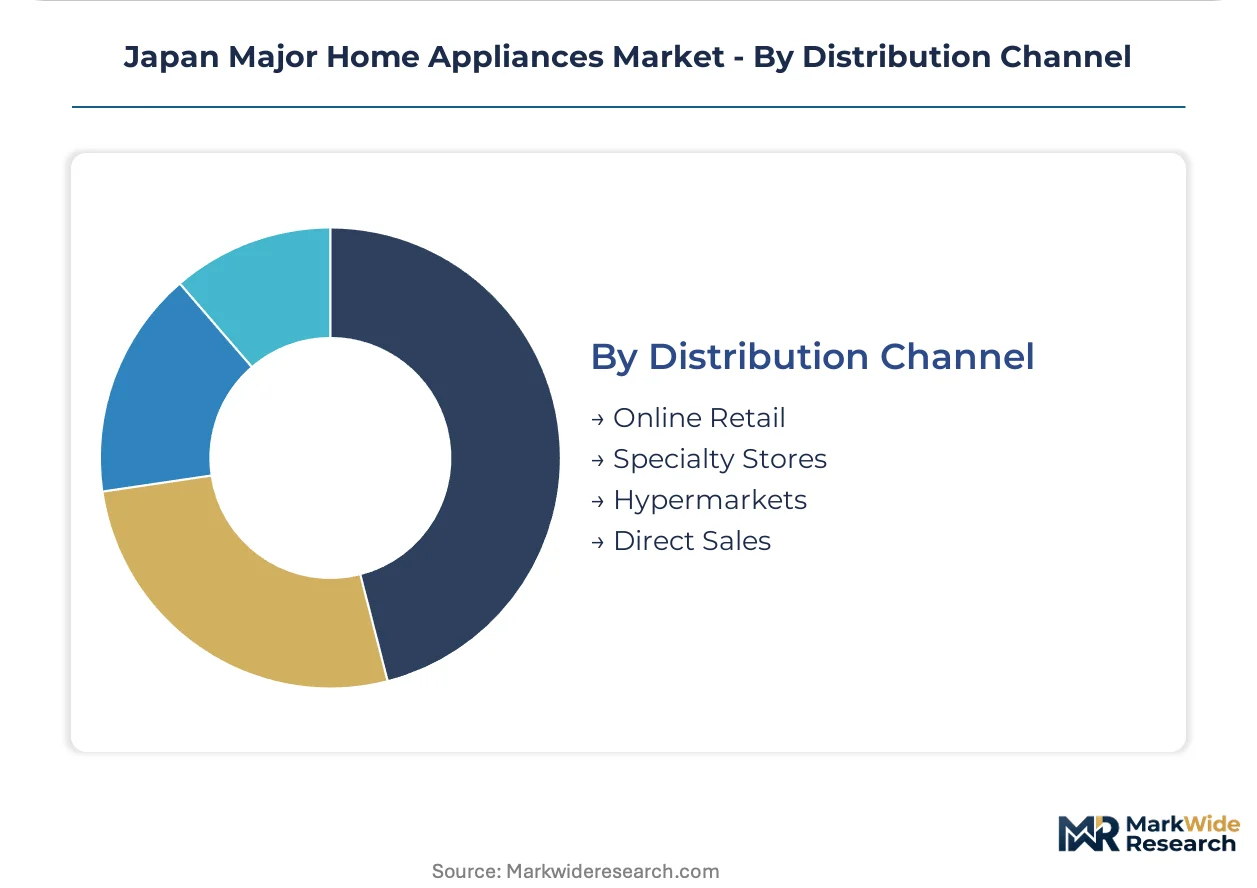
Distribution Channel:
Customer type fragmentation separates transaction-focused online retail from relationship-driven specialty channels, with hypermarket and direct sales routes competing on immediacy versus customization depth.
- Online Retail:E-commerce platforms capture replacement demand from digitally native households seeking specification comparison and delivery scheduling flexibility. Seasonal inventory builds face disruption from MCU shortages affecting inverter controller availability.
- Specialty Stores:Electronics chains and manufacturer showrooms provide JIS certification documentation and installation coordination for complex multi-system purchases.
- Hypermarkets:Mass merchandisers move high-volume standard configurations with immediate pickup availability for urgent replacement scenarios.
- Direct Sales:Manufacturer-direct channels support custom specifications for commercial-scale developments and appliance-as-service subscription arrangements.
Specialty stores retain the highest value placements; online retail is expanding most quickly as subscription models displace traditional purchase cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Japan's eastern metropolitan corridor, where high-rise residential towers and METI efficiency mandates drive replacement cycles. Regional variations reflect housing age, climate stress, and utility rebate program availability.
Kanto/Tokyo
Greater Tokyo Area buyers dominate unit placements through compact multi-door refrigeration and split-system cooling in new high-rise developments. METI's Top Runner Program accelerates turnover as households upgrade legacy equipment to meet escalating efficiency benchmarks. Yokohama and Saitama prefectures see developers pre-emptively sourcing compliant equipment to avoid construction delays under impending carbon-neutral building codes.
Kansai/Osaka
Aging housing stock across the Osaka-Kobe corridor generates replacement demand for energy-efficient cooling systems. Regional power cooperatives offer installation incentives that reduce consumer payback periods for inverter-driven models. Osaka's dense apartment complexes absorb heat pump dryer installations where external venting remains impractical.
Chubu/Nagoya
Industrial light-manufacturing facilities in Aichi Prefecture demand continuous-duty ratings with JIS electrical safety validation. Nagoya's automotive supply chain spillover supports component fabrication for compressor and motor assemblies. Local electronics chains coordinate multi-system purchases with certification documentation.
Kyushu
Regional utility partnerships in Fukuoka and Kagoshima prefectures pioneer appliance-as-service subscription models. Consumers bundle cooling and heating equipment maintenance into monthly power bills, displacing traditional retail purchase cycles. Climate stress from humid summers sustains above-average air conditioner replacement frequency.
Hokkaido
Heating-dominant load profiles in Sapporo and surrounding municipalities favor heat pump technology with seasonal inverter modulation. Utility subscription arrangements concentrate buyer relationships with energy retailers rather than electronics chains. Cold-climate engineering specifications differentiate product requirements from southern prefectures.
Japan Major Home Appliances Market Competitive Landscape
Strategic partnerships dominate the current landscape as manufacturers secure semiconductor supply and certification laboratory access. The market structure consolidates around established domestic producers with dedicated JIS testing facilities and captive component sourcing. Three archetypes prevail: diversified electronics conglomerates with captive semiconductor supply, specialized climate equipment manufacturers with in-house compressor production, and regional utility-aligned service providers. Competitive moves concentrate on backward integration into critical components and pre-emptive certification alignment with METI efficiency mandates.
Within the diversified conglomerate tier, Panasonic Corporation and Hitachi Global Life Solutions anchor positions through upstream control over semiconductor and compressor supply respectively. Sharp Corporation occupies a distinct vector through display-integrated refrigerator interfaces. These three exemplify how captive sourcing and certification infrastructure create specification advantages in Tokyo's high-rise development pipeline.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Hitachi Global Life Solutions |
| Sharp Corporation |
| Toshiba Lifestyle Products & Services Corporation |
| Mitsubishi Electric Corporation |
| Daikin Industries |
| Zojirushi Corporation |
| Rinnai Corporation |
| Haier Japan |
| Others |
Supply & Pricing Matrix
METI's refrigerant transition mandate gates qualified supply and premium-tier pricing access, as manufacturers with retooling capabilities capture specification advantages while legacy-dependent producers retreat to price-sensitive segments. Compressor and controller availability now separates compliant from non-compliant supply tiers, with JIS-certified producers commanding margin premiums in Tokyo's high-rise development pipeline.
Pricing Analysis
Volume placements concentrate in economy-tier conventional units, while margins accrue to premium smart appliances with embedded connectivity modules. Price differentiation rests on JIS certification grade and after-sales service bundling, with certified laboratory access enabling faster product launches. Pricing pressure stems from MCU shortages disrupting seasonal inventory builds, compressing margins for inverter-dependent manufacturers. Rural replacement markets exhibit highest price sensitivity, whereas commercial property developers in Yokohama and Saitama absorb premium positioning for code-compliant equipment.
Supply Chain Analysis
Direct-to-retail channels handle mass residential replacement demand, while manufacturer-direct arrangements serve commercial-scale developments and utility subscription partnerships. Component sourcing concentrates in Taiwan, South Korea, and China for semiconductors, with rare earth magnet supply anchored in Chinese and Mongolian extraction. Raw material dependencies include copper for motor windings, neodymium for compressor magnets, and silicon for controller fabrication. Single-source vulnerability in MCU supply creates production scheduling risk for inverter controller assembly. Distribution runs through electronics chains for complex multi-system purchases with installation coordination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's major home appliances sector sits in a technology-transition phase, with inverter-driven compressor architectures displacing fixed-speed legacy platforms across cooling categories. This displacement creates asymmetric opportunity windows for prepared stakeholders.
For Market Incumbents: Extend captive semiconductor sourcing arrangements to shield production schedules from external volatility, while accelerating in-house compressor manufacturing investments to match Hitachi Global Life Solutions' vertical positioning. The refrigerant transition from R-32 to lower-GWP alternatives threatens stranded manufacturing assets for laggards. Certification laboratory capacity serves as the critical lever for pre-emptive METI compliance and specification capture in carbon-neutral building code rollouts.
For New Entrants and Emerging Players: Regional utility partnerships represent the most penetrable channel vector, particularly in Hokkaido and Kyushu where appliance-as-service subscription models displace traditional retail purchase cycles. Medical-grade air purification functions offer white-space positioning in allergy-sensitive hospitality segments underserved by incumbent mass-market portfolios. A go-to-market angle bundling maintenance into monthly power bills bypasses electronics chain gatekeepers.
For Investors and Strategic Acquirers: METI's Top Runner Program revision announcements are the leading indicator that replacement cycle acceleration will concentrate value in compliant manufacturers. The five-to-ten-year viability window favors acquisition targets with dedicated JIS testing facilities and backward integration into compressor or controller production. Watch for utility partnership expansion signals in Fukuoka and Sapporo as inflection points for subscription model validation.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Manufacturing Retooling | Lower-GWP sealed system conversion aligns production with METI carbon-neutral building codes. |
| Captive Semiconductor Sourcing | MCU supply security shields inverter controller production from Taiwan foundry volatility. |
| JIS Certification Laboratory Investment | Dedicated testing capacity compresses product launch windows by six to twelve months. |
| Utility Subscription Partnership | Regional power cooperatives in Hokkaido and Kyushu displace electronics chain retail cycles. |
| Medical-Grade Air Purification Registration | PMDA-registered allergen filtration commands price premiums in hospitality and residential segments. |
Research Methodology
Trade association filings, METI efficiency benchmark disclosures, and JIS certification databases formed the secondary backbone, supplemented by customs records tracking compressor and semiconductor import flows. Primary interviews with appliance product planning directors, regional utility partnership managers, and commercial property development procurement leads validated demand assumptions across residential and commercial segments. Bottom-up unit placement estimates triangulated against top-down market value reconstructions.
Bottom-up modeling anchored forecasts, with top-down macroeconomic cross-checks for sensitivity calibration across the projection horizon. Segmentation dimensions included product type, technology tier, end-user category, and regional prefecture cluster. CAGRs derived from replacement cycle frequency analysis, efficiency mandate compliance deadlines, and housing construction permit trajectories. Climate stress indices and utility rebate program availability served as region-specific forecast inputs.
Caveats apply where semiconductor procurement disruptions or refrigerant transition timeline revisions could materially shift the outlook. Forecasts reflect assumptions regarding METI enforcement consistency and carbon-neutral building code adoption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Middle East and Africa Laundry Appliances Market
Home Appliances
Slovakia Home Appliances Market
Home Appliances
Home Appliance (Wet and Cold) Market
Home Appliances
North America Major Home Appliances Market
Home Appliances
Oman Home Appliances Market
Home Appliances
GCC Small Home Appliances Market
Home Appliances
United States Laundry Appliances Market
Home Appliances
Household Electric Steamer Cooker Market
Home Appliances
Household Fridge Market
Home Appliances
Germany Home Appliances Market
Home Appliances
China Laundry Appliances Market
Home Appliances
Japan Small Home Appliances Market
Home Appliances
Green Smart Household Appliances Market
Home Appliances
North America Electric Fireplace Market
Home Appliances
Australia Washing Machine Market
Home Appliances
Germany Household Side by Side Refrigerator Market