
 Europe Small Home Appliances Market | 2026-2036
Europe Small Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Small Home Appliances Market Foresight
Modular bundling of complementary appliances is repositioning how European consumers outfit compact kitchens. Groupe SEB leverages its multi-brand architecture to dominate the mid-premium coffee segment across France and Italy. Electrolux Group anchors its portfolio through energy-efficient Nordic design credentials that resonate in German and Scandinavian retail channels. De'Longhi S.p.A. specializes in espresso system modularity, allowing consumers to upgrade grinders and milk frothers independently.
Europe small home appliances encompass electrically powered countertop and portable devices typically operating below 2,500 watts, designed for food preparation, beverage brewing, and light cooking in residential and hospitality settings. These products incorporate thermal cut-off mechanisms, BPA-free polymers, and induction-compatible bases to meet EU safety and material standards. Coffee makers and blenders represent the most dynamic product type categories, with smart connectivity and barista-style automation commanding disproportionate margin pools. The end user base splits structurally between households seeking design-forward compact solutions and hospitality operators prioritizing throughput durability. Distribution channel dynamics favor online platforms for replacement purchases while retail stores sustain premium trial and brand experience.
The EU Ecodesign Directive, Energy Labelling Framework, and REACH compliance requirements collectively elevate material and efficiency standards for products sold across member states. EMA and national regulators enforce conformity assessment procedures that delay market entry for non-compliant manufacturers. Stakeholders must monitor evolving F-Gas Regulation implications for refrigeration-dependent appliances and anticipate CSRD-driven disclosure requirements across appliance supply chains.
Market Dynamics
The EU Ecodesign Directive and Energy Labelling Framework are compressing replacement cycles across Western European kitchens. Manufacturers now redesign thermal systems and control boards specifically to meet tightening efficiency thresholds before 2027 compliance deadlines.
Growth Catalysts
- Smart connectivity integration:Wi-Fi-enabled coffee makers and ovens allow remote scheduling and energy optimization. Urban households in Germany and France prioritize app-controlled beverage preparation.
- EU Green Deal appliance incentives:Member state rebate programs accelerate trade-ins of pre-2015 units. Italy and Spain have expanded point-of-sale subsidies for A-rated small appliances.
- Modular kitchen design:Compact urban dwellings demand stackable, multi-function devices. Copenhagen and Amsterdam housing stock drives preference for appliances under 30 centimeters in width.
Market Restraints
- Copper and rare earth magnet costs:Motor assemblies in blenders and mixers face input price volatility. Chinese processing concentration for neodymium creates supply vulnerability.
- REACH compliance complexity:ECHA substance restrictions on certain polymer additives extend product development timelines. Reformulation of housing materials adds six to nine months to launch schedules.
- Repairability mandates:France's anti-waste law requires spare part availability for ten years. Inventory carrying costs rise for manufacturers with broad SKU portfolios.
Strategic Opportunities
- Eastern European penetration:Poland and Czech Republic urban households show rising appetite for premium espresso systems. Retail infrastructure in Warsaw and Prague now supports mid-premium positioning.
- Hospitality fleet refresh:Boutique hotels across Portugal and Greece seek compact, high-throughput beverage equipment. Lease-to-own financing unlocks capital-constrained operators.
- Voice control convergence:Integration with Alexa and Google Home ecosystems differentiates at retail. Scandinavian consumers demonstrate highest adoption of hands-free kitchen commands.
Industry Challenges
- Cybersecurity certification delays:EN 303645 compliance for connected appliances extends testing protocols. Third-party lab capacity bottlenecks in Germany slow market entry.
- Embedded software talent scarcity:Firmware engineering for IoT-enabled cooking functions competes with automotive and industrial sectors. Salaries in Milan and Munich have risen sharply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Small Home Appliances Market |
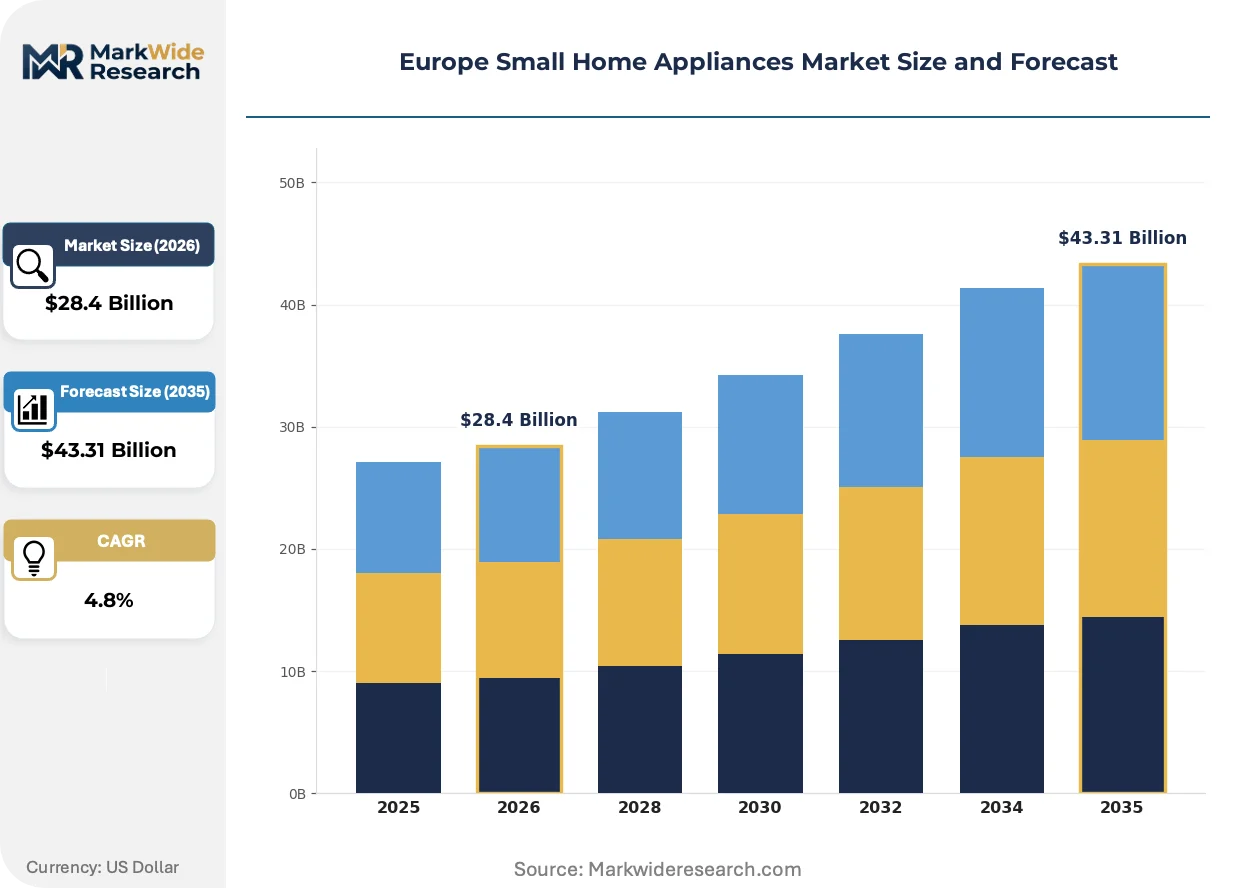
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $43.31 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blenders, Toasters, Coffee Makers, Microwaves End User: Households, Hotels, Cafes, Restaurants Distribution Channel: Online, Retail Stores, Wholesalers, Direct Sales Technology: Smart Appliances, Energy Efficient, Traditional, Portable |
| Companies Covered | De'Longhi S.p.A., Electrolux Group, Groupe SEB, Whirlpool Corporation, Miele and Cie. KG, BSH Hausgeräte GmbH, Dyson Ltd., Smeg, Koninklijke Philips N.V., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Small Home Appliances Market Shifts & Advancements
Barista-style automation and energy transparency are repositioning how European consumers evaluate small appliances. These shifts favor manufacturers with control over both thermal engineering and digital interface design.
Precision grinding and tamping mechanisms are automating espresso preparation previously requiring manual skill. Enthusiast households in Turin and Vienna adopt these systems fastest. The technology is automating away the specialty coffee shop as the default quality reference point.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in refrigeration-dependent appliances. Compressor redesigns now prioritize propane and isobutane alternatives. Wine coolers and compact refrigerators face the steepest engineering adaptation costs.
Rental and subscription models for premium coffee equipment are gaining traction among younger urban demographics. Berlin and Barcelona lead this shift, with curated bean delivery bundled into monthly fees. Traditional retail channels in these cities now compete against direct-to-consumer services emphasizing convenience over ownership.
Europe Small Home Appliances Market Segmentation
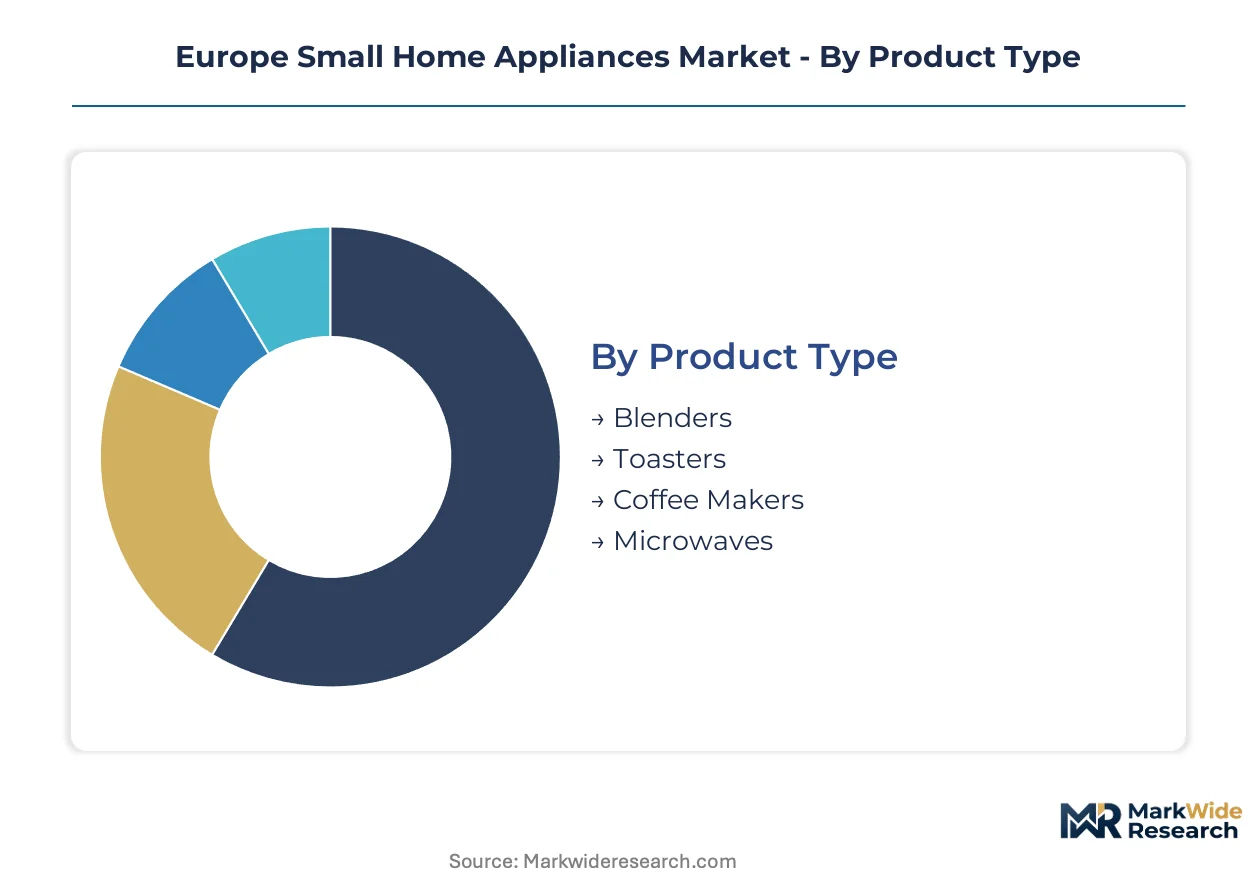
Segmentation in the Europe small home appliances market reveals divergent margin structures across connected versus conventional technologies. Manufacturers calibrate R&D allocation based on whether segments reward efficiency compliance, hospitality durability, or digital interface sophistication.
Product Type:
Standardization dominates entry-level thermal appliances while premium coffee systems embrace deep customization through modular grinder and frother configurations.
- Coffee Makers:Espresso systems incorporate precision tamping and PID temperature control for barista-grade extraction. Demand clusters in Italian and German urban households seeking café-quality automation without countertop footprint expansion. Smart connectivity and bean-to-cup modularity command disproportionate margin pools.
- Blenders:High-torque brushless motors and variable speed programming enable nut butter and hot soup functions beyond conventional smoothie preparation. German and French health-conscious consumers drive replacement cycles toward vacuum-sealed nutrient preservation models. Ecodesign Directive efficiency thresholds are accelerating motor redesigns ahead of compliance deadlines.
- Toasters:Crumb tray accessibility and browning consistency sensors differentiate mid-tier offerings. BISTRO certification requirements in France influence thermal element specifications.
- Microwaves:Inverter technology and flatbed cavity designs replace rotating turntables for space efficiency. Scandinavian kitchens under 15 square meters favor compact 20-liter formats.
Most installed capacity flows through Coffee Makers. Expansion is steepest in Blenders.
End User:
Volume concentration sits with residential replacement cycles while hospitality procurement prioritizes throughput durability and lease financing structures.
- Households:Compact urban dwellings in Amsterdam and Copenhagen drive preference for sub-30-centimeter appliances with multi-function programmability. Design-forward aesthetics and app-controlled scheduling justify premium positioning.
- Hotels:Boutique properties across Portugal and Greece seek in-room coffee systems balancing footprint constraints with brand-appropriate quality signaling. Fleet refresh cycles compress as EU Green Deal incentives accelerate trade-ins.
- Cafes:Independent operators in Warsaw and Prague adopt prosumer-grade equipment to differentiate from chain competitors. Equipment financing unlocks capital-constrained entrants.
- Restaurants:Back-of-house durability requirements favor stainless steel construction and commercial-grade safety certifications. Italian trattorias prioritize rapid heating recovery for service peaks.
Households absorb the majority of unit volume. Hospitality segments are expanding most quickly as fleet electrification mandates propagate.
Distribution Channel:
Channel strategy bifurcates between experience-dependent trial for premium positioning and convenience-driven replacement for established brands.
- Online:Platform algorithms and subscription bundling reshape discovery for replacement purchases. German consumers demonstrate highest comfort with app-controlled appliance configuration without physical inspection.
- Retail Stores:Curated showroom environments enable tactile evaluation of material quality and interface responsiveness. French and Italian premium positioning depends on trained staff demonstration of espresso extraction parameters.
- Wholesalers:Bulk procurement for hospitality chains and property management portfolios concentrates in Madrid and Milan distribution hubs. Inventory financing terms determine competitive allocation.
- Direct Sales:Manufacturer-owned channels capture full margin on subscription and rental models. Berlin and Barcelona lead equipment-as-a-service experimentation among younger demographics.
Retail Stores sustain the majority of premium trial activity. Direct Sales channels are climbing the fastest as ownership models fragment.
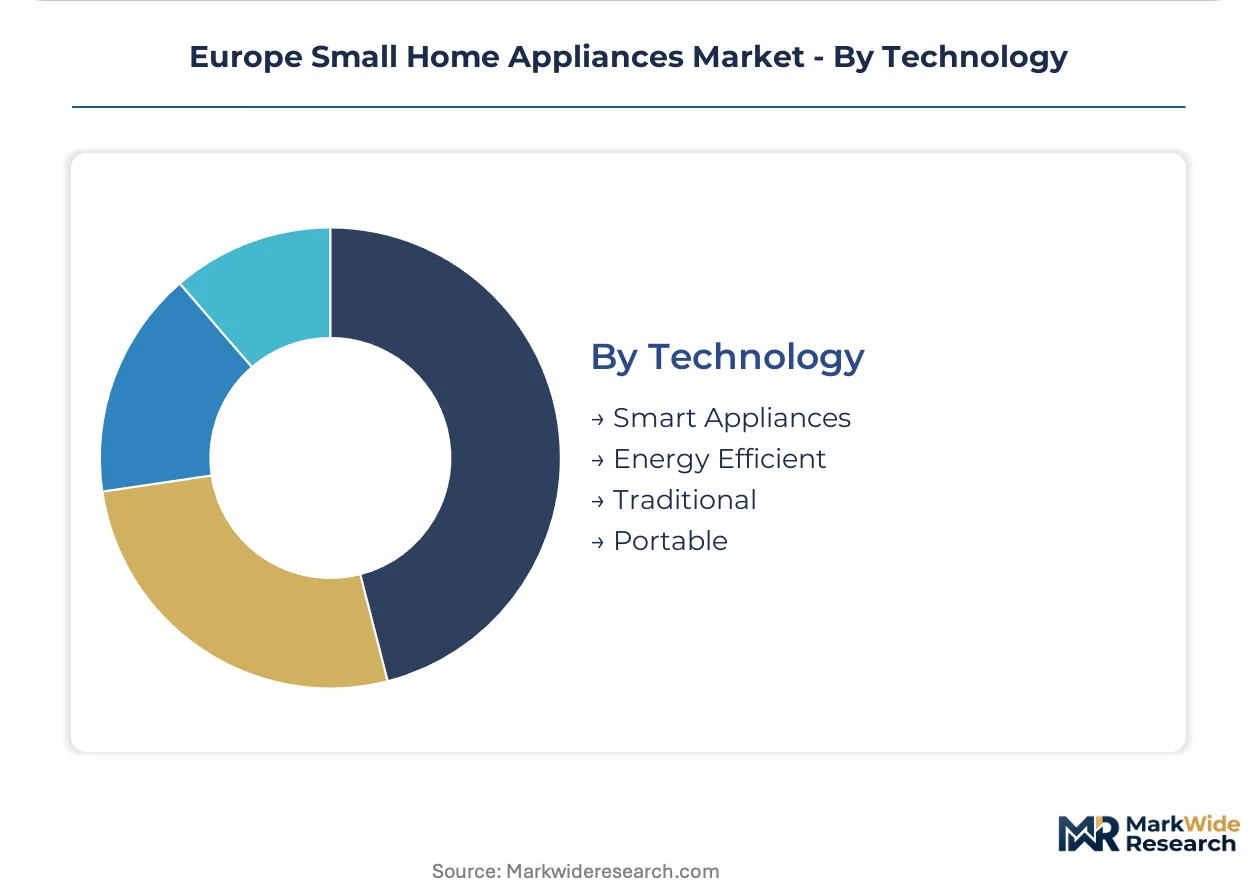
Technology:
Regulatory pressure on energy consumption and material safety is forcing convergence between efficiency compliance and digital capability integration.
- Smart Appliances:Wi-Fi-enabled scheduling and voice control integration with Alexa and Google Home ecosystems differentiate at retail. Scandinavian consumers demonstrate highest hands-free kitchen command adoption.
- Energy Efficient:A-rated thermal systems and standby power reduction meet tightening EU Ecodesign Directive thresholds. Italian and Spanish point-of-sale subsidies accelerate trade-ins of pre-compliant inventory.
- Traditional:Mechanical controls and standardized components minimize repair complexity under France's anti-waste spare part availability mandates. Rural Eastern European markets sustain demand for non-connected formats.
- Portable:Battery-powered and vehicle-compatible formats address van life and remote work mobility trends. Portuguese and Greek tourism operators adopt for outdoor hospitality service.
Energy Efficient technology carries the majority of installed base. Smart Appliances are gaining share fastest as EN 303645 cybersecurity certification pathways mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Small home appliance manufacturing first achieved industrial scale in Germany and Italy during the post-war electrification wave. These two markets established the design and engineering foundations that now define European product standards. Today, national regulatory frameworks and urban housing patterns shape distinct demand profiles across the continent.
Germany
German households prioritize energy efficiency ratings and connected kitchen ecosystems in replacement purchases. The EU Ecodesign Directive and national KBA-adjacent efficiency mandates compress product lifecycles in Berlin and Munich metropolitan areas. Bavaria's industrial corridor hosts concentrated R&D facilities for thermal system engineering.
France
French consumers drive demand for design-forward compact appliances suited to Parisian apartment dimensions. The anti-waste law mandates ten-year spare part availability, elevating inventory costs for manufacturers serving Lyon and Marseille distribution hubs. Île-de-France retail channels sustain premium brand positioning through trained demonstration staff.
Italy
Italian espresso culture sustains the continent's deepest market for automated coffee systems with modular upgrade paths. Turin and Milan households adopt precision grinding technology fastest. The Veneto region concentrates component suppliers for thermal cut-off mechanisms and BPA-free polymer housings.
Spain
Spanish point-of-sale subsidies for A-rated appliances accelerate trade-ins of pre-2015 units in Madrid and Barcelona. Younger demographics in these cities experiment with subscription-based equipment models. Andalusian hospitality operators seek compact high-throughput equipment for boutique property fleets.
Poland
Polish urban households in Warsaw and Prague-adjacent markets show rising appetite for mid-premium espresso positioning. EU Green Deal incentives extend to Eastern European member states, supporting retail infrastructure upgrades. The country's manufacturing zones increasingly supply components to Western European assembly plants.
Europe Small Home Appliances Market Competitive Landscape
Premium-margin players sit above commodity-margin players across connectivity integration and energy efficiency certification. The market structures around three tiers: multi-brand conglomerates with portfolio breadth, specialized single-category engineers, and scale-driven mass-market suppliers. Consolidation pressures favor entities with captive distribution and regulatory compliance capabilities. Competitive moves concentrate on modular platform expansion and direct-to-consumer channel development.
Within the specialized engineering tier, De'Longhi S.p.A. and Miele and Cie. KG exemplify contrasting approaches to premium positioning. Groupe SEB occupies a position spanning mid-premium and mass-market segments through multi-brand architecture. These three entities anchor the competitive landscape without representing the full vendor base.
| Leading Market Players |
|---|
| De'Longhi S.p.A. |
| Electrolux Group |
| Groupe SEB |
| Whirlpool Corporation |
| Miele and Cie. KG |
| BSH Hausgeräte GmbH |
| Dyson Ltd. |
| Smeg |
| Koninklijke Philips N.V. |
| Others |
Supply & Pricing Matrix
Firmware engineering talent concentration in Milan and Munich widens pricing-tier spreads across smart appliance portfolios. Labor-cost differentials between embedded software hubs and mechanical assembly zones in Eastern Europe compress margins on entry-level thermal products while inflating premiums for connected configurations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the European market. Certification grade under EU Ecodesign Directive thresholds and brand heritage in espresso systems drive price differentiation. Cost compression in economy tiers intensifies because Chinese motor assembly imports face input volatility. Hospitality buyers demonstrate lowest price sensitivity due to lease financing structures, while Eastern European residential segments prioritize transactional affordability.
Supply Chain Analysis
Domestic-content mandates under France's anti-waste law and Italy's repairability requirements are reshaping sourcing patterns for spare part inventories. Component manufacturing concentrates in China, Vietnam, and Poland. Neodymium magnet and copper winding supplies for motor assemblies draw from Chinese processing concentration. Single-source vulnerability in rare earth supply creates procurement risk. Distribution runs through Madrid and Milan wholesale hubs for hospitality fleet procurement, with direct-to-consumer channels expanding fastest in Berlin and Barcelona.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European small home appliances constitute a late-cycle quality story. Urban household demand in Germany and France tilts decisively toward A-rated efficiency and app-controlled scheduling specifications.
For Market Incumbents: To counter subscription-based equipment-as-a-service entrants in Berlin and Barcelona, anchor market position through backward integration into BPA-free polymer housing production and captive control over thermal cut-off mechanism suppliers. Expand certified repair center networks to satisfy France's ten-year spare part mandate. For New Entrants and Emerging Players: EU Green Deal point-of-sale subsidies in Italy and Spain open a window for mid-premium espresso system penetration. Target Warsaw and Prague hospitality operators with lease-to-own financing structures. Differentiate through voice control integration with Alexa and Google Home ecosystems. For Investors and Strategic Acquirers: Multi-brand conglomerates with captive distribution are the most active acquirer in this space. Five-to-ten year viability hinges on regulatory compliance capabilities and modular platform architecture. Acquisition targets should demonstrate EN 303645 cybersecurity certification progress and established direct-to-consumer subscription infrastructure. Monitor F-Gas Regulation compressor redesign completion rates as inflection signal for refrigeration-dependent appliance margins.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Platform Expansion | De'Longhi's grinder-frother upgrade paths demonstrate margin capture through component separability. |
| Direct-to-Consumer Subscription Launch | Berlin and Barcelona equipment-as-a-service models displace traditional retail discovery for younger demographics. |
| Energy Efficiency Certification Investment | A-rated thermal systems qualify for Italian and Spanish point-of-sale subsidies accelerating trade-in velocity. |
| Cybersecurity Compliance Pathway | EN 303645 certification unlocks smart appliance positioning in Scandinavian retail channels. |
| Spare Part Inventory Localization | France's anti-waste law mandates ten-year availability, elevating carrying costs for broad-SKU manufacturers. |
Research Methodology
Bottom-up household and hospitality procurement modeling reconciled against top-down manufacturing output tracking forms the analytical core. Primary interviews with product development directors at Groupe SEB, Electrolux, and De'Longhi combined with category buyers at Fnac-Darty and MediaMarktSaturn. Secondary validation draws from EU Ecodesign Directive compliance databases, REACH substance restriction filings, and Eurostat appliance trade flows. Triangulation against customs records and energy label registration systems ensures shipment-to-demand reconciliation.
Historical trendline analysis of replacement cycle compression and efficiency threshold adoption informs projection parameters. Segmentation dimensions span product type, end-user archetype, distribution channel, and technology tier across the analysis window. CAGRs derive from installed base turnover rates and premium mix shift assumptions. Forecast inputs incorporate EU F-Gas Regulation phase-down schedules and CSRD disclosure requirements propagating through supply chains.
Revisions become necessary when copper and rare earth price volatility exceeds historical bands or when EN 303645 lab capacity constraints delay smart appliance market entry. Forecasts reflect documented assumptions on subsidy program continuity and repairability mandate enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Argentina Home Appliances Market
Home Appliances
North America Home Heating Appliances Market
Home Appliances
Smart Small Home Appliances Market
Home Appliances
United States Home Appliances Market
Home Appliances
United Kingdom Home Appliances Market
Home Appliances
United Kingdom Small Home Appliances Market
Home Appliances
Saudi Arabia Small Home Appliances Market
Home Appliances
Smart Home Appliances Market
Home Appliances
Americas Range Hood Market
Home Appliances
Mexico Major Home Appliance Market
Home Appliances
Qatar Major Home Appliances Market
Home Appliances
Bahrain Home Appliances Market
Home Appliances
Middle East and Africa Laundry Appliances Market
Home Appliances
Europe Laundry Appliances Market
Home Appliances
South Africa Home Appliances Market
Home Appliances
European Built-In Refrigerator Market