
 United States Small Home Appliances Market | 2026-2036
United States Small Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
United States Small Home Appliances Market Analytics
Subscription-based leasing and asset-light financing models is reshaping competitive dynamics in the United States small home appliances sector, lowering barriers for direct-to-consumer entrants. SharkNinja Operating LLC leverages aggressive digital marketing to sustain brand visibility across social commerce channels. Hamilton Beach Brands Holding Company anchors its position through deep mass-retail partnerships and value-engineered product lines. Dyson Ltd. differentiates through premium engineering investment and cyclone technology leadership.
Small home appliances encompass electrically powered portable or semi-portable devices designed for domestic tasks, typically operating below 15 amps at 120V and incorporating motors, heating elements, or solid-state controls for functions including food preparation, surface cleaning, air filtration, and personal grooming. Kitchen appliances command the largest revenue pool due to high replacement frequency and countertop penetration, while air treatment appliances represent the fastest-expanding category as climate volatility intensifies indoor air quality concerns. Cleaning appliances occupy a mature margin structure where robotic automation is displacing traditional corded formats. The distribution channel dimension shows online retail capturing disproportionate growth as fulfillment infrastructure narrows delivery windows to same-day service.
The Consumer Product Safety Commission enforces mandatory safety standards for electrical hazards and fire risk in residential appliances, while the Department of Energy administers efficiency labeling rules that constrain motor and heating element specifications. California's Title 20 appliance efficiency regulations exceed federal baselines and function as a de facto national design standard given the state's market weight. Stakeholders must monitor NIST's evolving IoT cybersecurity framework, as connected appliance mandates will determine which product architectures retain market access.
Market Dynamics
California's Title 20 efficiency mandates and NIST cybersecurity standards are forcing appliance manufacturers to redesign product architectures around dual compliance requirements, compressing development cycles and raising engineering costs for connected kitchen and air treatment devices.
Growth Catalysts
- Multi-functional kitchen devices:Urban millennials in compact apartments demand space-saving appliances that combine multiple cooking functions, driving replacement cycles for single-purpose legacy units.
- IRA energy efficiency incentives:Federal tax credits for ENERGY STAR-certified appliances accelerate consumer upgrade decisions in the air treatment and cleaning categories.
- Same-day fulfillment infrastructure:Amazon's logistics network and regional micro-fulfillment centers compress delivery windows, enabling impulse purchases of small appliances previously requiring planned retail visits.
Market Restraints
- Semiconductor supply concentration:Taiwan and South Korea dominate microcontroller and power management chip fabrication, exposing appliance makers to allocation delays and price volatility.
- Copper and rare earth magnet costs:Motor and heating element manufacturing faces input cost pressure from commodity market swings and concentrated mining jurisdictions.
- Technical limitation of battery density:Cordless appliance runtime and power output remain constrained by lithium-ion cell chemistry, limiting full substitution of corded formats in high-draw categories.
Strategic Opportunities
- Subscription-based leasing models:Asset-light financing lowers barriers for direct-to-consumer entrants targeting credit-constrained households in Texas and Florida metropolitan corridors.
- IoT-enabled predictive maintenance:Connected appliance ecosystems create recurring revenue streams through filter replacement subscriptions and automated consumable replenishment.
- Air quality regulation tailwinds:Wildfire smoke exposure in Pacific Coast states and indoor pollutant awareness in Northeast urban centers expand addressable market for HEPA filtration and air monitoring devices.
Industry Challenges
- Embedded systems cybersecurity talent:NIST compliance requires firmware engineering capabilities scarce in traditional appliance manufacturing workforces concentrated in Midwest industrial zones.
- Third-party certification timelines:UL and Intertek testing backlogs for wireless connectivity and electrical safety extend product launch schedules by four to six months.
- Legacy retail inventory integration:Mass-merchandiser EDI systems and forecast-sharing protocols create friction for DTC brands attempting hybrid distribution strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Small Home Appliances Market |
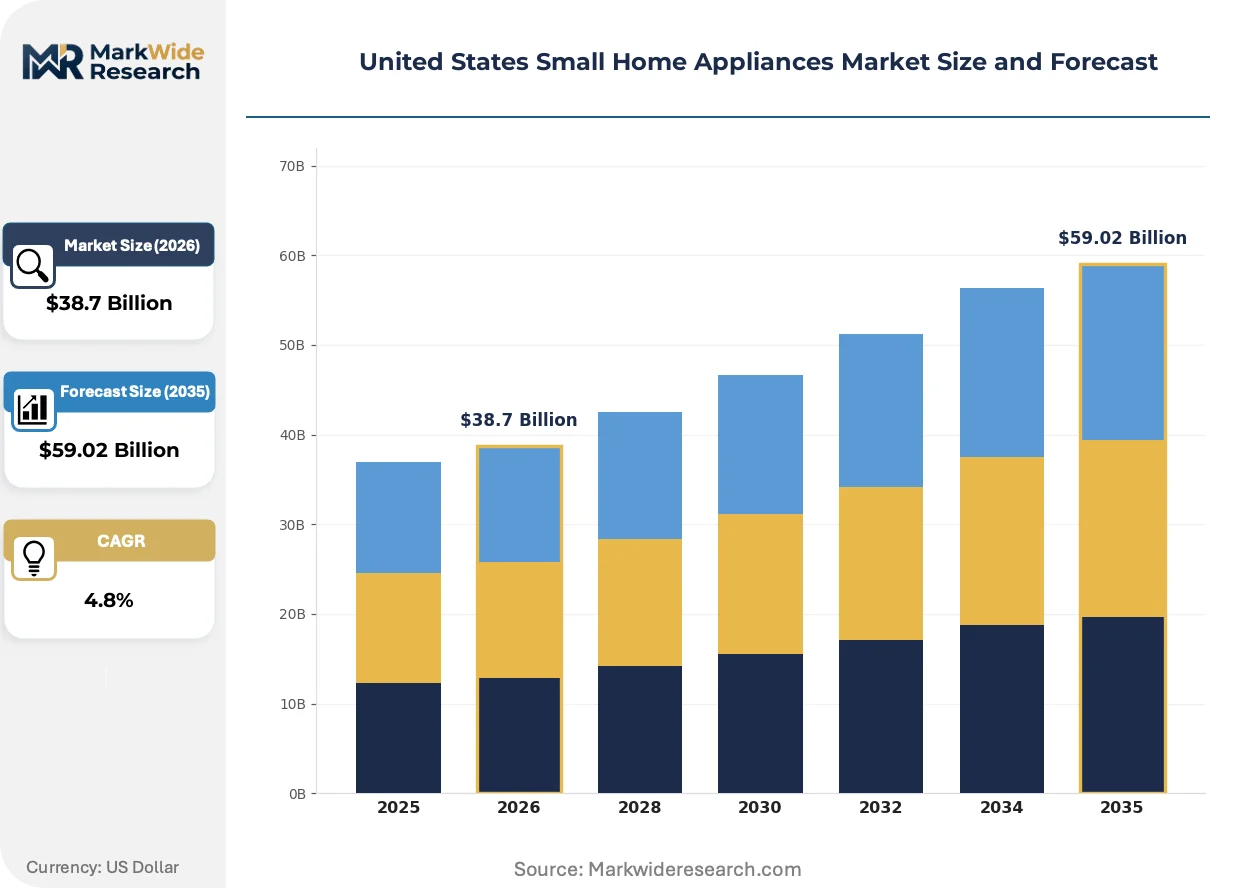
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kitchen Appliances, Cleaning Appliances, Personal Care Appliances, Air Treatment Appliances End User: Households, Restaurants, Hotels, Offices Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales Price Tier: Premium, Mid-Range, Budget, Economy |
| Companies Covered | SharkNinja Operating LLC, Hamilton Beach Brands Holding Company, Dyson Ltd., Whirlpool Corporation, Spectrum Brands, Breville Group Ltd., Panasonic Corporation, SMEG S.p.A., Robert Bosch GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Small Home Appliances Market Evolving Landscape
Three converging forces are restructuring how small appliances are engineered, sold, and serviced. Digital integration, efficiency mandates, and fulfillment acceleration are compressing traditional product lifecycles and reshaping channel economics.
Sensor-embedded cooking appliances with computer vision and automated temperature adjustment are rendering obsolete manual dial-controlled countertop ovens and stovetops. Tech-forward households in Seattle and Austin adopt these devices at replacement rates twice the national average for conventional formats. The technology is compressing price bands between premium and mass-market tiers as software features become the primary differentiation vector.
The Department of Energy's amended test procedures for standby power consumption took effect in 2025, tightening permissible wattage thresholds for always-connected devices. Manufacturers must now engineer separate low-power modes or risk delisting from federal procurement programs and utility rebate eligibility. California's Air Resources Board extends these constraints through volatile organic compound limits on appliance coatings, affecting production lines serving the West Coast.
Rental and lease-to-own arrangements for high-usage appliances are displacing outright ownership among transient young professionals in New York and Los Angeles. These consumers prioritize flexibility over equity accumulation, accepting higher lifetime costs for lower monthly obligations and bundled maintenance coverage. The model concentrates demand in coastal metropolitan statistical areas with elevated housing turnover and gig-economy employment patterns.
United States Small Home Appliances Market Segmentation
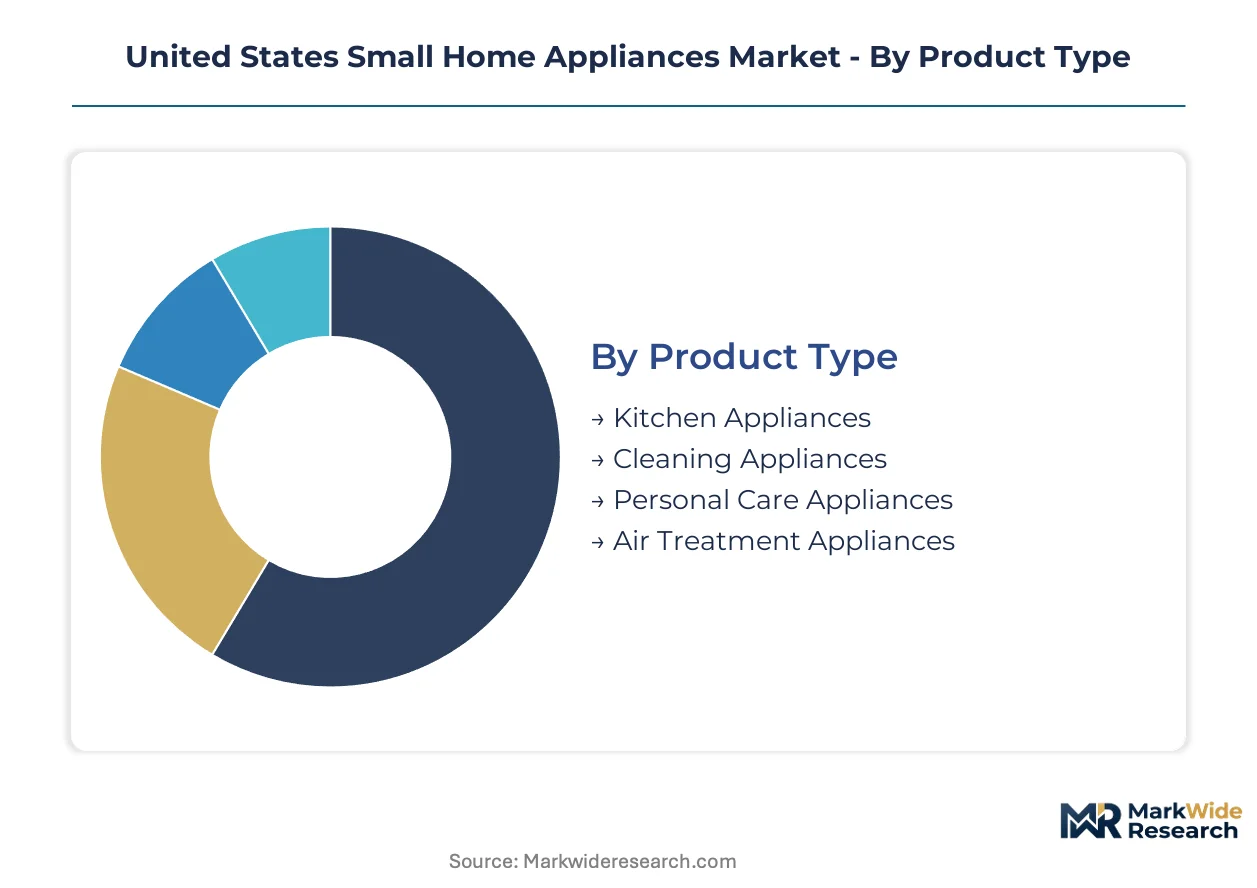
Segmentation in the United States small home appliances market reveals divergent growth mechanics across product categories and channel structures. Kitchen and cleaning appliances operate on fundamentally different replacement cycles and margin profiles. Distribution channel selection increasingly determines customer acquisition economics and brand positioning latitude.
Product Type:
Maturity varies sharply across this dimension, with established categories defending installed bases against emerging formats.
- Kitchen Appliances:Countertop devices incorporating motors, heating elements, or solid-state controls for food preparation tasks. Demand concentrates in California's tech-forward metropolitan corridors where multi-functional devices displace single-purpose legacy units. High replacement frequency and countertop penetration sustain revenue concentration despite slower growth.
- Air Treatment Appliances:HEPA filtration and air monitoring devices addressing climate volatility and wildfire smoke exposure. Pacific Coast states and Northeast urban centers drive adoption as indoor air quality awareness intensifies. This segment climbs the fastest as regulatory tailwinds and environmental stressors expand addressable market.
- Cleaning Appliances:Robotic automation displaces traditional corded formats in a mature margin structure. Cordless runtime constraints from lithium-ion chemistry limit full substitution in high-draw categories.
- Personal Care Appliances:Electrically powered grooming devices operating below 15 amps. Compact form factors suit urban millennial apartment dwellers prioritizing space efficiency.
Kitchen Appliances retains volume leadership; Air Treatment Appliances holds the steepest expansion curve.
End User:
Application context determines durability requirements, feature prioritization, and procurement authority structures.
- Households:Residential consumers driving replacement cycles through ENERGY STAR upgrade incentives and impulse purchases enabled by same-day fulfillment. Urban millennials in compact apartments demand space-saving multi-functional formats.
- Restaurants:Commercial foodservice operators requiring commercial-grade durability and NSF certification compliance. High-usage environments prioritize reliability over smart features.
- Hotels:Hospitality procurement departments balancing guest experience standards with capital expenditure constraints. Asset-light leasing models gain traction among transient property portfolios.
- Offices:Workplace amenity budgets funding breakroom appliances and air quality infrastructure. Post-occupancy wellness certifications influence specification decisions.
Households dominates unit volume; Hotels demonstrates the most rapid adoption of subscription-based financing.
Distribution Channel:
Channel economics are compressing as fulfillment infrastructure narrows delivery windows and reshapes purchase behavior.
- Online Retail:Amazon's logistics network and regional micro-fulfillment centers enable impulse purchases previously requiring planned retail visits. Digital-native entrants leverage direct-to-consumer economics without legacy retail EDI friction.
- Specialty Stores:Curated environments for premium appliance demonstration and consultative selling. Dyson and similar brands anchor presence through experiential retail in affluent suburban markets.
- Supermarkets:Mass-merchandiser partnerships delivering volume through value-engineered product lines. Hamilton Beach anchors position through deep retail integration and forecast-sharing protocols.
- Direct Sales:Manufacturer-owned channels capturing margin and customer relationship data. Subscription-based leasing models concentrate in coastal metropolitan statistical areas with elevated housing turnover.
Online Retail captures disproportionate growth velocity; Supermarkets maintains the deepest penetration in Texas and Florida corridors.
Price Tier:
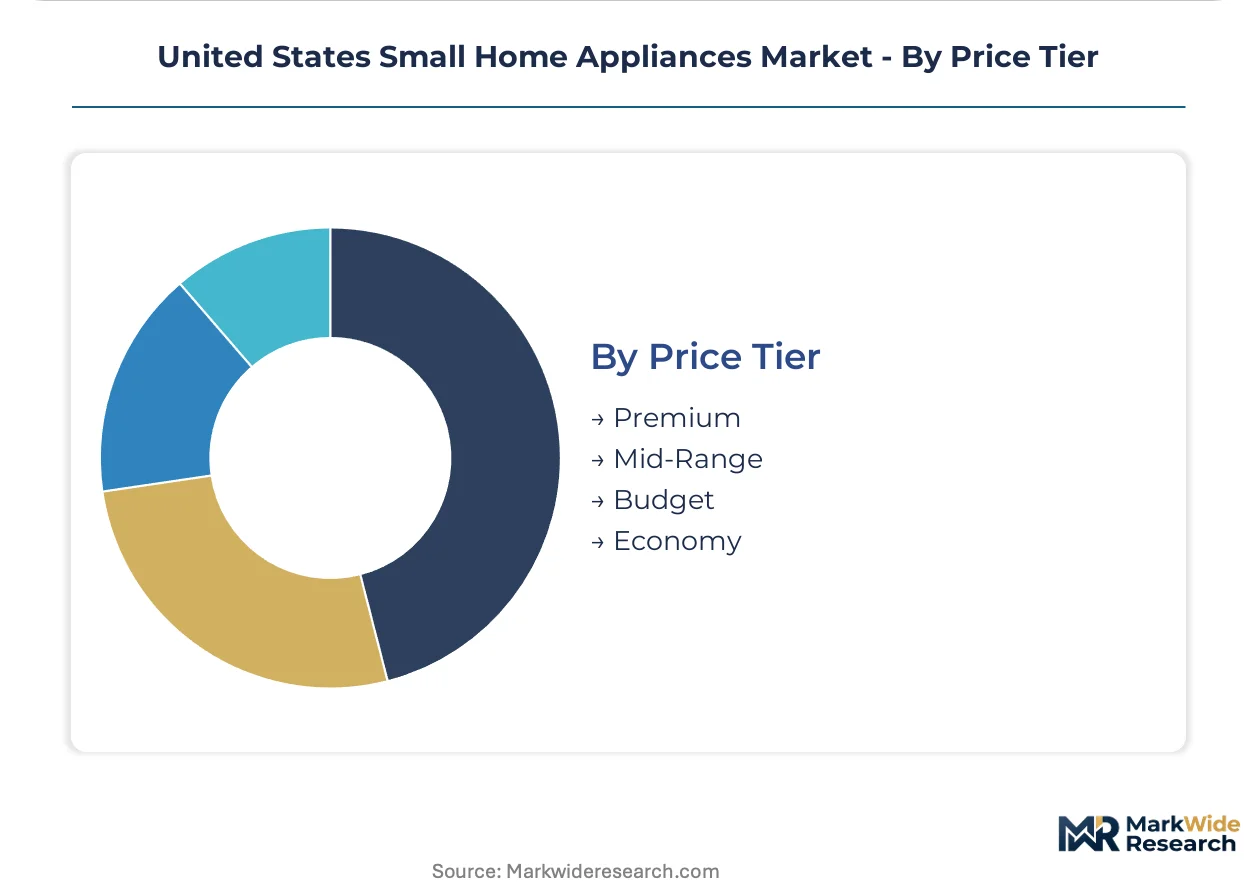
Cost stratification aligns with certification grade, performance tier, and connectivity feature depth rather than raw material differentiation alone.
- Premium:Engineering investment in cyclone technology, computer vision, and automated temperature adjustment. Tech-forward households in Seattle and Austin adopt at replacement rates twice the national average.
- Mid-Range:Balanced feature sets targeting ENERGY STAR compliance without flagship connectivity. Federal tax credits accelerate upgrade decisions in this bracket.
- Budget:Value-engineered specifications meeting baseline safety and efficiency mandates. California's Title 20 regulations function as de facto design standard given market weight.
- Economy:Entry-level pricing for credit-constrained households in asset-light leasing arrangements. Lower monthly obligations trade against higher lifetime costs.
Premium commands margin concentration; Budget demonstrates the fastest volume expansion through rental and lease-to-own displacement of ownership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a modest trade surplus in small home appliances, with domestic manufacturing concentrated in Midwest industrial corridors offsetting import dependency for premium electronics and specialized components from Asian supply nodes.
California
Tech-forward metropolitan corridors in Los Angeles and San Francisco drive replacement cycles for multi-functional kitchen devices and sensor-embedded cooking appliances. The California Air Resources Board enforces volatile organic compound limits on appliance coatings that exceed federal baselines. San Jose and San Diego host engineering talent pools developing firmware for NIST-compliant connected devices.
Texas
Houston and Dallas-Fort Worth metropolitan areas concentrate demand for asset-light leasing models among transient young professionals in gig-economy employment. Federal IRA energy efficiency incentives accelerate ENERGY STAR upgrade decisions across air treatment categories. Austin anchors a secondary demand cluster for premium smart appliances with computer vision capabilities.
New York Metro
Compact apartment living in Manhattan and Brooklyn sustains replacement frequency for space-saving countertop devices among urban millennials. The Consumer Product Safety Commission's electrical hazard standards shape product liability exposure for devices sold through regional retail networks. Newark and White Plains logistics hubs enable same-day fulfillment infrastructure for impulse appliance purchases.
Pacific Northwest
Seattle and Portland households adopt premium sensor-embedded appliances at replacement rates twice the national average for conventional formats. Wildfire smoke exposure drives HEPA filtration demand that outpaces national per-capita averages. Tacoma and Eugene manufacturing facilities assemble components for ENERGY STAR-certified air treatment devices serving West Coast markets.
Southeast
Atlanta and Miami metropolitan corridors demonstrate rapid adoption of subscription-based financing for high-usage appliances among credit-constrained households. The Department of Energy's standby power consumption test procedures constrain always-connected device specifications for products entering Florida and Georgia distribution channels. Charlotte and Nashville emerge as secondary logistics nodes supporting regional micro-fulfillment networks.
United States Small Home Appliances Market Competitive Landscape
On the supply side, the industry is structured around three distinct tiers: mass-market manufacturers anchored through deep retail partnerships, premium engineering specialists commanding cyclone and computer vision technology leadership, and diversified conglomerates leveraging cross-category scale economies. Strategic archetypes include value-engineered volume players, innovation-driven premium specialists, and platform-integrated connected device ecosystems. Dominant competitive moves center on direct-to-consumer channel expansion and firmware engineering talent acquisition for NIST cybersecurity compliance.
Within the premium-tier vector, Dyson Ltd. and Breville Group Ltd. exemplify engineering investment archetypes, while SharkNinja Operating LLC occupies a position representing aggressive digital marketing and social commerce penetration. Hamilton Beach Brands Holding Company anchors the mass-market tier through value-engineered specifications and mass-retail integration.
| Leading Market Players |
|---|
| SharkNinja Operating LLC |
| Hamilton Beach Brands Holding Company |
| Dyson Ltd. |
| Whirlpool Corporation |
| Spectrum Brands |
| Breville Group Ltd. |
| Panasonic Corporation |
| SMEG S.p.A. |
| Robert Bosch GmbH |
| Others |
Value Network & Pricing Analysis
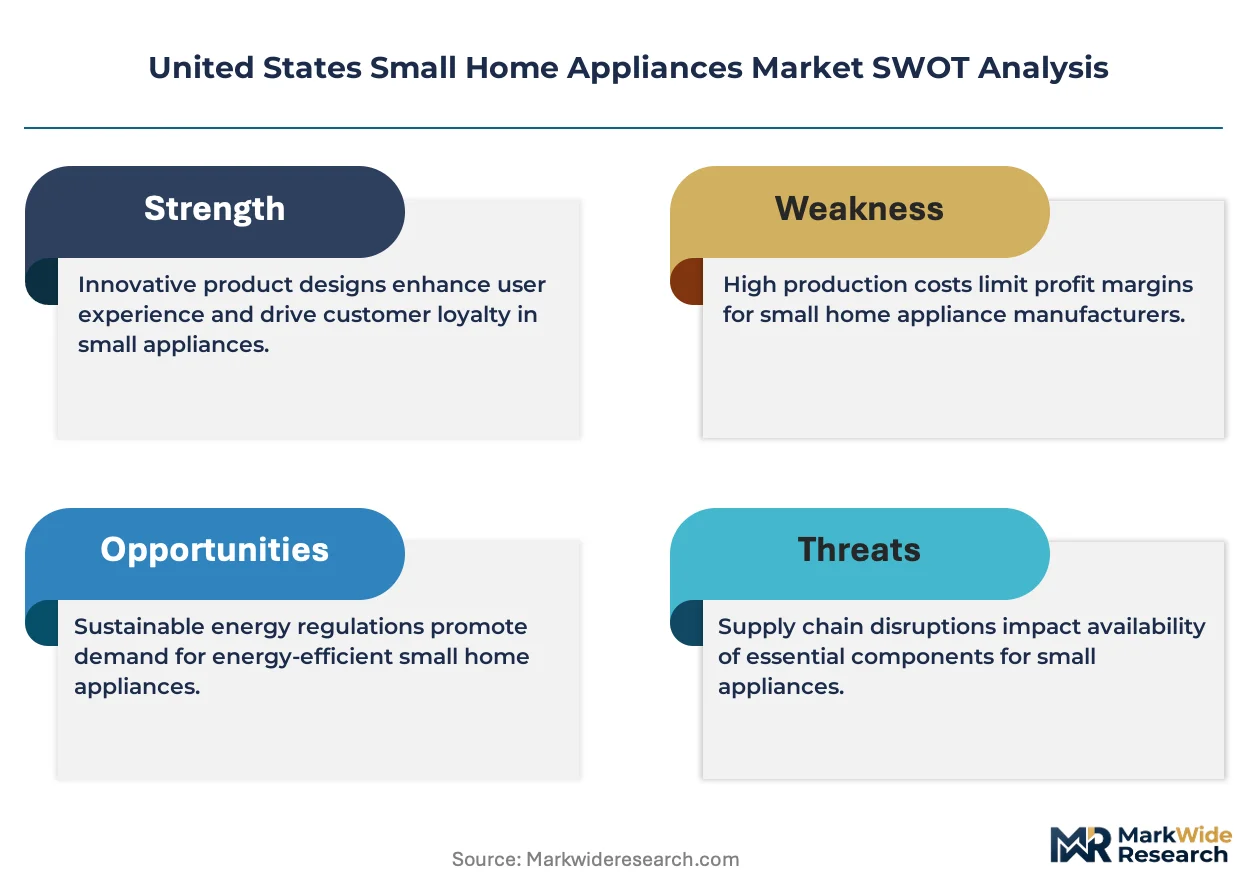
Taiwanese semiconductor foundries anchor upstream component availability, and their allocation decisions cascade directly into appliance manufacturers' margin structures across the United States small home appliances sector. NIST cybersecurity mandates for IoT-connected devices amplify engineering cost pressure, forcing trade-offs between premium feature depth and mass-market accessibility.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on ENERGY STAR certification tier and firmware complexity for NIST compliance, with premium tiers commanding substantial brand premiums. Pricing pressure stems from copper and rare earth magnet commodity volatility, compressing margins in motor-dependent categories. Budget-tier households exhibit acute price sensitivity, while tech-forward coastal consumers absorb premium markups for sensor-embedded functionality.
Supply Chain Analysis
Copper cathode and lithium-ion cell chemistry feed from concentrated mining jurisdictions in Chile, Australia, and Indonesia. Microcontroller and power management chip fabrication draws from Taiwan and South Korea, creating single-source vulnerability for connected appliance architectures. Tariff exposure on Chinese-assembled components elevates landed costs for mass-market SKUs. Distribution runs through Amazon's logistics network and regional micro-fulfillment centers, compressing delivery windows and enabling impulse purchase economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Firmware engineering talent for NIST-compliant embedded systems represents the critical scarcity constraining competitive positioning in connected small appliances. Manufacturers lacking in-house cybersecurity capabilities face extended certification timelines and delisting risk from federal procurement programs.
For Market Incumbents: Pre-empt emerging DTC entrants by deepening mass-retail data partnerships and accelerating UL certification pipelines for wireless-enabled SKUs. Acquire firmware engineering capabilities in San Jose or San Diego talent clusters to compress NIST compliance cycles. Anchor shelf space through exclusive ENERGY STAR co-marketing arrangements before IRA incentive windows narrow. For New Entrants and Emerging Players: Build out asset-light subscription financing in Houston and Dallas-Fort Worth, where transient gig-economy professionals prioritize flexibility over ownership. Target air treatment appliances in Pacific Coast states, where wildfire smoke exposure drives replacement urgency and HEPA filtration demand outpaces national averages. Launch through Amazon's same-day fulfillment infrastructure to bypass legacy retail EDI friction. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because NIST cybersecurity mandates will progressively filter market access and consolidate share among compliance-capable manufacturers. Target acquisition candidates with captive firmware engineering teams and existing UL wireless certifications. Monitor Intertek and UL testing backlog durations as an inflection signal for launch velocity compression.| Strategic Initiative | Industry Significance |
|---|---|
| NIST Cybersecurity Compliance Investment | Firmware engineering capabilities determine market access for connected kitchen and air treatment devices under evolving federal mandates. |
| Direct-to-Consumer Channel Expansion | Digital-native entrants capture margin and customer data without legacy mass-merchandiser forecast-sharing protocol friction. |
| Asset-Light Leasing Model Deployment | Subscription financing penetrates credit-constrained households in Texas and Florida metropolitan corridors with elevated housing turnover. |
| Air Treatment Product Line Extension | HEPA filtration and air monitoring SKUs address wildfire smoke exposure in Pacific Coast states and indoor pollutant awareness in Northeast urban centers. |
| Same-Day Fulfillment Infrastructure Partnership | Amazon's logistics network enables impulse purchases previously requiring planned retail visits, reshaping customer acquisition economics. |
Research Methodology
The analysis maps kitchen appliances, air treatment devices, cleaning appliances, and personal care segments, each validated through product management executives at mass-market manufacturers, firmware engineering leads at connected device specialists, category buyers at Amazon and Walmart, and procurement officers at commercial foodservice operators. Primary interview findings triangulated against Department of Energy efficiency filings, Consumer Product Safety Commission recall databases, California Air Resources Board regulatory notices, and Nielsen retail audit data. Bottom-up SKU-level volume estimates and top-down category spend analysis were reconciled to derive market sizing.
Assumptions held fixed include NIST IoT cybersecurity framework progression, IRA energy efficiency incentive continuity, and lithium-ion cell chemistry constraints on cordless runtime. The projection horizon spans kitchen, air treatment, cleaning, and personal care product types segmented by household, restaurant, hotel, and office end users, with distribution channel dynamics modeled across online retail, specialty stores, supermarkets, and direct sales. CAGRs were derived from replacement cycle analysis, regulatory tailwind assessment, and channel shift velocity. Forecast inputs incorporated semiconductor allocation patterns and copper price trajectory sensitivity.
Stress conditions across Taiwan semiconductor supply disruption, copper price spike scenarios, and NIST compliance timeline acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and risk factors including single-source chip fabrication concentration and third-party certification backlog extension. Quarterly review of UL and Intertek testing queue durations, semiconductor foundry allocation announcements, and California Title 20 regulatory amendment notices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Household Induction Cooktops Market
Home Appliances
Bahrain Small Home Appliances Market
Home Appliances
UAE Laundry Appliances Market
Home Appliances
Household Electric Steamer Cooker Market
Home Appliances
India Laundry Appliances Market
Home Appliances
North America Small Home Appliances Market
Home Appliances
United Kingdom Home Appliances Market
Home Appliances
Bahrain Home Appliances Market
Home Appliances
Qatar Small Home Appliances Market
Home Appliances
South Korea Small Home Appliances Market
Home Appliances
France Household Appliances Market
Home Appliances
Asia-Pacific Major Home Appliance Market
Home Appliances
Japan Household Appliance Market
Home Appliances
United States Major Home Appliances Market
Home Appliances
UAE Small Home Appliances Market
Home Appliances
Residential Cooker Hoods Market