
 Israel Home Needs Appliances Market | 2026-2036
Israel Home Needs Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Israel Home Needs Appliances Market Insights
Israel's Green Building Standard is pivoting developer procurement toward energy-certified appliances in new residential towers. Electra Consumer Products Ltd. leverages its domestic manufacturing footprint to supply builders with compliant cooling and laundry systems. Samsung Electronics Israel Ltd. competes through smart kitchen ecosystems that integrate with local utility demand-response programs. Tadiran Holdings anchors the climate-control segment with air treatment appliances engineered for Mediterranean humidity conditions.
Home needs appliances encompass electrically powered or gas-fueled durable goods designed for domestic food preservation, garment care, meal preparation, and environmental comfort, typically operating at 220-240V/50Hz with energy ratings measured by kilowatt-hour consumption per standardized use cycle. Refrigerators dominate replacement demand as Israeli households prioritize frost-free cooling with inverter compressors suited to extended summer heat waves. Smart appliances represent the fastest-expanding technology tier, though conventional gas cooking equipment retains share in Orthodox communities and rural periphery zones where Shabbat-mode functionality governs purchase decisions. Specialty stores control premium positioning for Miele and Bosch installations, while online retail captures volume turnover in compact urban appliance categories.
The Standards Institution of Israel enforces mandatory energy labeling under EU-aligned MEPS frameworks, compelling importers to recalibrate product portfolios for Tier 1 efficiency thresholds. The country's national electricity regulator shapes peak-load pricing that accelerates demand-response-enabled appliance adoption. Stakeholders must monitor how pending amendments to building codes in Haifa and Beersheba municipalities redirect specification requirements for rental property portfolios.
Market Dynamics
Israel's appliance sector pivots on regulatory compression from the National Infrastructure, Energy and Water Ministry, which is ratcheting mandatory efficiency tiers faster than replacement cycles allow, forcing premature obsolescence of imported inventory and reshaping procurement timelines for distributors and developers alike.
Growth Catalysts
- Building code alignment:Municipal amendments in Haifa and Beersheba now mandate energy-certified appliance specifications for rental portfolios, pulling forward replacement demand from property management companies.
- Smart grid integration:Israel's national electricity regulator deploys demand-response pricing that rewards connected refrigeration and climate systems, accelerating utility-partnered appliance upgrades in central district housing.
- New construction pipelines:Residential towers rising in Tel Aviv and Jerusalem specify inverter-compressor cooling systems as baseline, embedding premium efficiency into volume procurement channels.
Market Restraints
- Copper and rare-earth input volatility:Compressor motor laminations and permanent-magnet materials face price swings that compress OEM margin structures on mid-tier product lines.
- Import dependency concentration:Finished appliance flows concentrate through Ashdod and Haifa port corridors, exposing inventory cycles to maritime chokepoint risk and customs clearance variability.
- Shabbat-mode technical limitation:Orthodox community requirements for passive thermal retention in refrigeration constrain inverter-based efficiency gains, segmenting product development into parallel hardware tracks.
Strategic Opportunities
- Periphery zone penetration:Galilee and Negev households retain aging mechanical refrigeration, creating replacement white space for frost-free systems as grid reliability improves.
- Water-heating convergence:Heat-pump water heaters paired with solar thermal capture rewrite domestic hot-water economics, opening bundled appliance-system sales to energy-conscious developers.
- Online channel innovation:Compact urban appliance categories migrate to platform retail, enabling direct-to-installer logistics that bypass traditional showroom overhead for volume turnover.
Industry Challenges
- Field technician skill compression:Inverter electronics and connected-system diagnostics outpace vocational training pipelines, widening the gap between product complexity and service capability.
- Certification timeline friction:Standards Institution of Israel testing queues for EU-aligned MEPS Tier 1 validation extend product launch windows, delaying revenue recognition against seasonal demand peaks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Israel Home Needs Appliances Market |
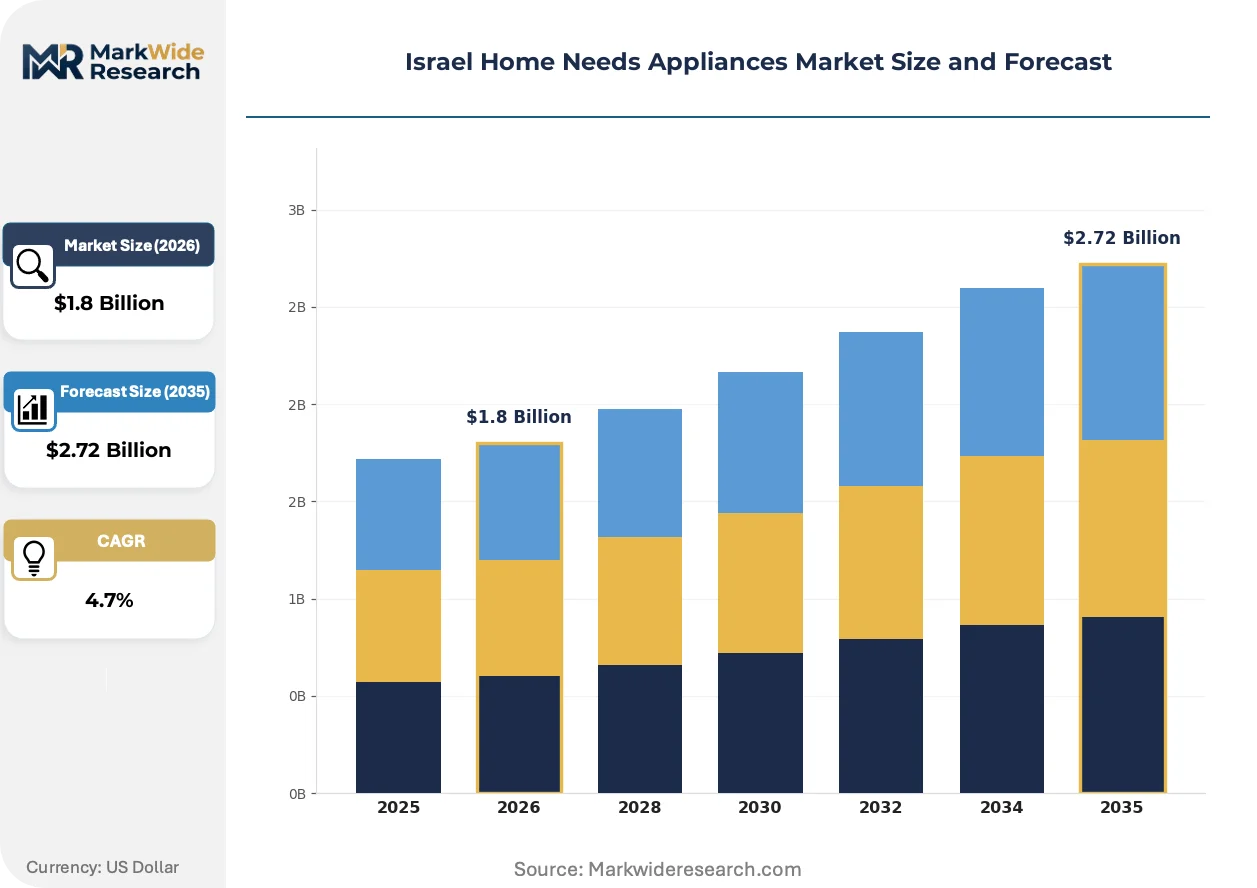
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washers, Ovens, Microwaves End User: Households, Rental Properties, Commercial Kitchens, New Constructions Technology: Smart Appliances, Energy-Efficient, Conventional, Gas Distribution Channel: Online Retail, Specialty Stores, Hypermarkets, Direct Sales |
| Companies Covered | Electra Consumer Products Ltd., Tadiran Holdings, Whirlpool Israel Ltd., BSH Home Appliances Ltd., Samsung Electronics Israel Ltd., LG Electronics Israel Ltd., Haier Israel Ltd., Bosch Home Appliances Israel, Miele Israel Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Israel Home Needs Appliances Market Trends and Innovations
Appliance intelligence is rewriting how Israeli households interact with domestic infrastructure, compressing the boundary between standalone equipment and grid-responsive assets while reshaping value capture across the supply chain.
Inverter-compressor refrigeration with variable-speed drive electronics is rewriting cooling economics for Mediterranean climate stress. Urban households in Tel Aviv and Jerusalem adopt these systems at replacement-cycle velocity. The technology is rewriting manufacturer portfolio priorities, marginalizing fixed-speed compressors in favor of efficiency-differentiated product tiers.
Israel's National Infrastructure, Energy and Water Ministry tightens appliance efficiency standards through EU-aligned MEPS frameworks with mandatory labeling thresholds. Importers must recalibrate entire product portfolios to maintain market access. The regulation most affects refrigeration and air-treatment categories, where distributors now pre-screen inventory against Tier 1 compliance before port entry.
Builder-direct specification contracts are displacing retail-channel intermediation for new residential construction in central Israel. Developers negotiate volume appliance packages with manufacturers, bypassing traditional distributor markup. This pattern concentrates most visibly in Tel Aviv metropolitan tower projects, where procurement teams bundle cooling, laundry, and cooking systems into single-source agreements.
Israel Home Needs Appliances Market Segmentation
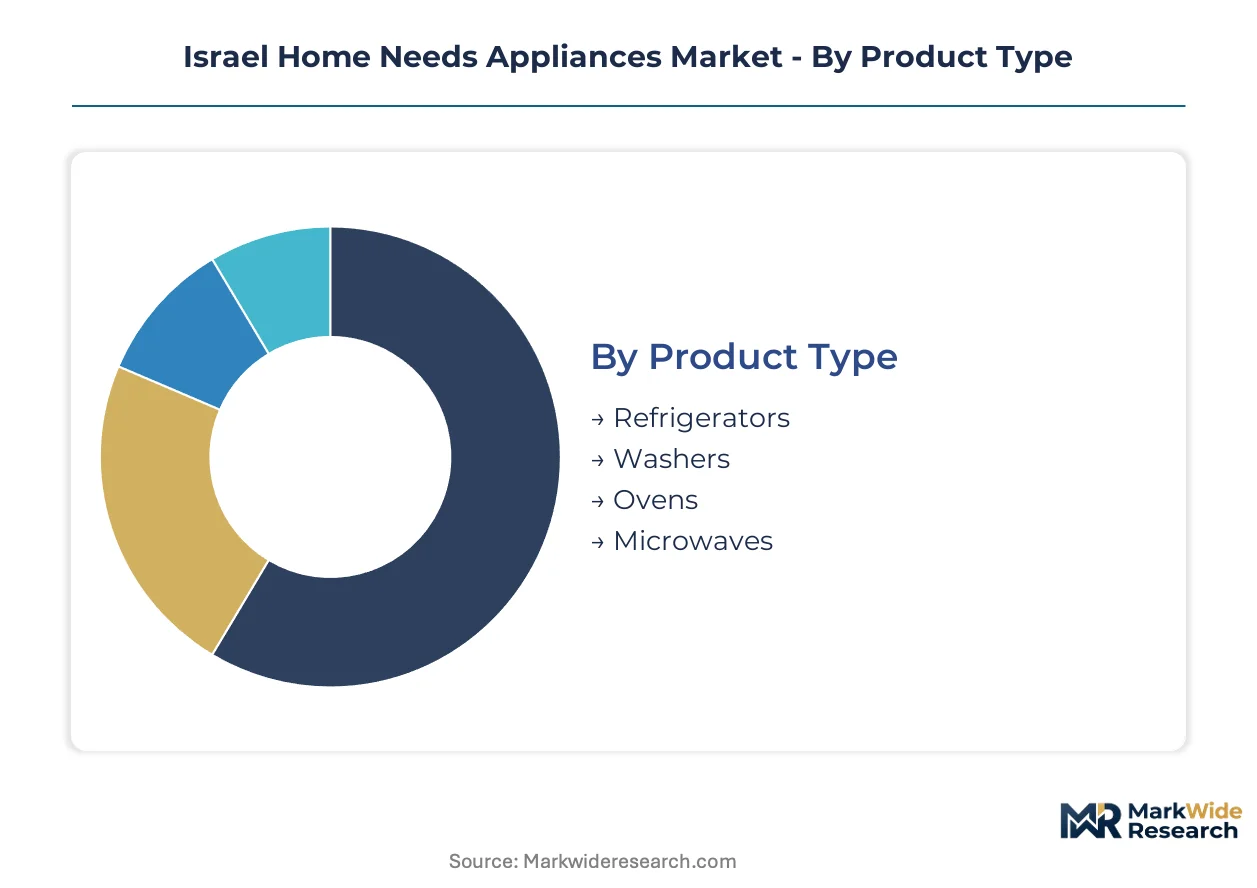
Israel's appliance market fragments across procurement channels, energy standards, and end-use requirements that reshape how manufacturers configure product portfolios. Segmentation reveals where regulatory pressure concentrates and where technology premiums command pricing power.
Product Type:
Buyers differentiate primarily by replacement urgency and climate adaptation requirements rather than discretionary upgrade cycles.
- Refrigerators:Inverter-compressor systems with frost-free cooling dominate replacement demand as Tel Aviv and Jerusalem households prioritize thermal resilience during extended summer heat waves. The National Infrastructure, Energy and Water Ministry's efficiency tiers accelerate obsolescence of fixed-speed models.
- Washers:Front-loading systems with heat-pump drying capture share in compact urban dwellings where water tariffs and space constraints govern purchase decisions. New residential towers in central Israel specify these as baseline in builder-direct contracts.
- Ovens:Built-in electric and gas variants serve distinct customer bases, with convection systems penetrating secular urban households.
- Microwaves:Compact countertop units dominate volume turnover through online retail channels targeting rental property outfitters.
Volume sits with refrigerators; growth tilts toward washers.
End User:
Procurement scale and specification authority separate segments more than usage intensity or frequency.
- Households:Individual purchasers prioritize Shabbat-mode functionality in Orthodox communities and smart connectivity in secular urban districts, creating parallel product development tracks.
- Rental Properties:Property management companies in Haifa and Beersheba face municipal mandates for energy-certified appliances, pulling forward replacement timelines.
- Commercial Kitchens:High-duty-cycle equipment requires durability certifications and service network proximity, concentrating procurement with established distributors.
- New Constructions:Developer-direct contracts bypass retail markup, bundling cooling, laundry, and cooking systems into single-source agreements for Tel Aviv metropolitan tower projects.
Revenue concentrates with new constructions; expansion accelerates fastest in rental properties.
Technology:
Regulatory alignment and grid integration capability determine which technology tiers maintain market access.
- Smart Appliances:Connected refrigeration and climate systems integrate with Israel's demand-response pricing programs, rewarding utility-partnered upgrades in central district housing.
- Energy-Efficient:Tier 1 MEPS-compliant models face mandatory labeling thresholds enforced by the Standards Institution of Israel, compelling importer portfolio recalibration.
- Conventional:Fixed-speed compressors and mechanical controls retain share in Galilee and Negev periphery zones where grid reliability and price sensitivity constrain technology adoption.
- Gas:Cooking equipment retains share in Orthodox communities and rural areas where passive thermal retention governs purchase decisions.
Installed base remains conventional; technology transition runs through energy-efficient tiers.
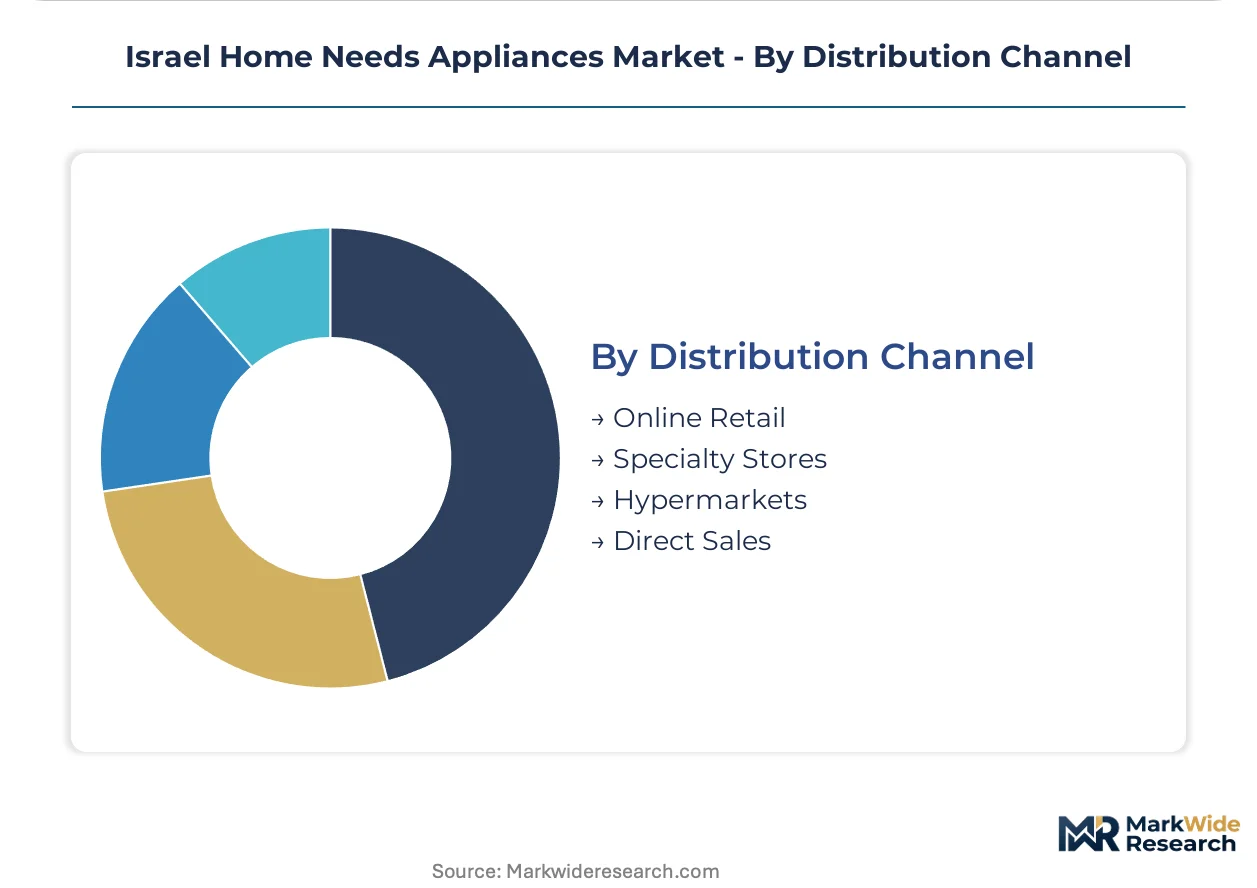
Distribution Channel:
Customer journey complexity and installation service requirements shape channel selection more than price transparency alone.
- Online Retail:Compact urban appliance categories migrate to platform retail, enabling direct-to-installer logistics that bypass traditional showroom overhead.
- Specialty Stores:Premium positioning for high-end European brands requires trained sales staff and installation coordination, protecting margin through service bundling.
- Hypermarkets:Volume turnover in mid-tier categories leverages foot traffic and promotional pricing, though energy-label compliance screening adds inventory risk.
- Direct Sales:Builder-direct contracts displace intermediation for new construction, with manufacturers negotiating volume packages that reshape procurement economics.
Transaction volume flows through online retail; value capture concentrates in specialty stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tel Aviv metropolitan towers anchor Israel's appliance demand through builder-direct procurement contracts that bundle cooling, laundry, and cooking systems into single-source agreements. Jerusalem's residential districts drive replacement cycles for Shabbat-mode compliant refrigeration. The National Infrastructure, Energy and Water Ministry's efficiency standards reshape inventory flows through Ashdod and Haifa port corridors.
Central District
Tel Aviv and surrounding municipalities concentrate new construction activity where developers specify inverter-compressor cooling as baseline. The Standards Institution of Israel enforces mandatory energy labeling that pre-screens inventory before port entry. Gush Dan's residential towers embed premium efficiency into volume procurement channels.
Jerusalem District
Orthodox community requirements for passive thermal retention govern purchase decisions for refrigeration and cooking equipment. Municipal building codes in Jerusalem prioritize energy-certified specifications for rental portfolios. The city's dense urban fabric accelerates compact washer-dryer adoption in space-constrained dwellings.
Haifa District
Port infrastructure at Haifa channels finished appliance imports from East Asian manufacturing centers. Municipal amendments mandate energy-certified appliance specifications for rental property portfolios. The city's industrial zones support service networks for commercial kitchen equipment.
Southern District
Beersheba's rental property market faces municipal mandates pulling forward replacement timelines from property management companies. Grid reliability improvements in Negev periphery zones create replacement white space for frost-free refrigeration. The district's aging mechanical appliance base contrasts with central Israel's technology adoption.
Northern District
Galilee households retain conventional fixed-speed compressors where price sensitivity constrains technology adoption. The region's periphery status delays smart grid integration and demand-response program participation. Acre and Nazareth retail channels serve price-conscious segments with mid-tier product lines.
Israel Home Needs Appliances Market Competitive Landscape
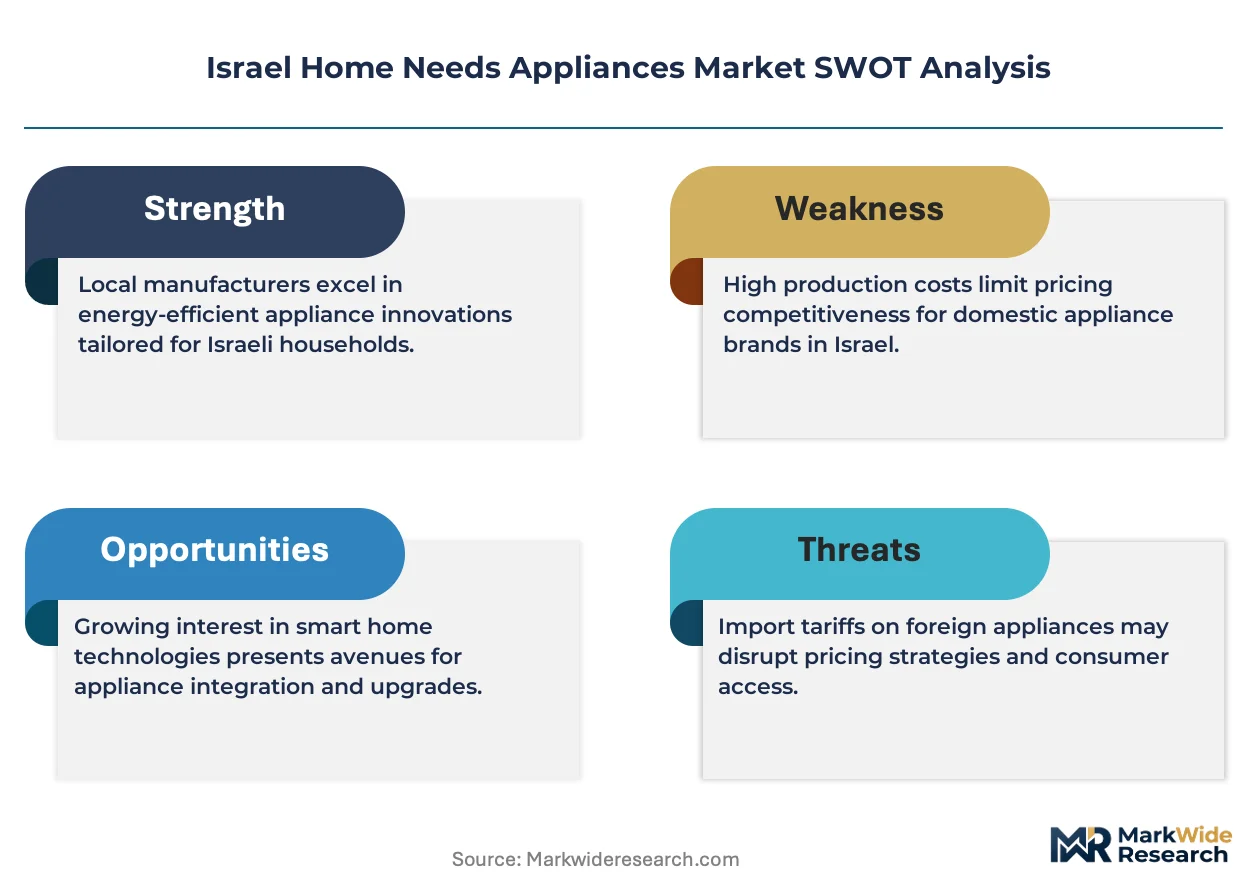
The competitive structure tilts toward diversified electronics conglomerates with domestic distribution infrastructure. Israeli appliance procurement concentrates around three strategic tiers: domestic manufacturers leveraging local production footprints, multinational subsidiaries integrating with utility demand-response programs, and premium European specialists controlling specialty retail channels. M&A activity remains subdued as market access depends on Standards Institution of Israel certification timelines rather than scale advantages. Portfolio diversification into connected-system ecosystems represents the dominant competitive vector.
Among domestic-positioned suppliers, Electra Consumer Products Ltd. and Tadiran Holdings exemplify archetypes built on local manufacturing presence and climate-specific engineering. Samsung Electronics Israel Ltd. anchors the multinational subsidiary tier, representing the pattern of global electronics conglomerates adapting smart kitchen ecosystems to national regulatory frameworks. These three companies illustrate how market access depends on distinct capability configurations rather than interchangeable scale advantages.
| Leading Market Players |
|---|
| Electra Consumer Products Ltd. |
| Tadiran Holdings |
| Whirlpool Israel Ltd. |
| BSH Home Appliances Ltd. |
| Samsung Electronics Israel Ltd. |
| LG Electronics Israel Ltd. |
| Haier Israel Ltd. |
| Bosch Home Appliances Israel |
| Miele Israel Ltd. |
| Others |
Pricing and Supply Chain Analysis
Israel's Green Building Standard gates qualified supply and premium-tier pricing access, compelling manufacturers to certify inverter-compressor systems before port entry while developers pay efficiency premiums for builder-direct contracts. The regulation compresses margin structures for uncertified inventory and rewards Tier 1 MEPS compliance with specification authority in central district towers.
Pricing Analysis
Energy-throughput metrics anchor pricing for inverter-compressor refrigeration, where kilowatt-hour savings per cooling cycle justify premium positioning against fixed-speed alternatives. Three-tier pricing structure across premium, standard, and economy levels separates MEPS Tier 1 certified systems from conventional imports and mechanical-control periphery units. Cost compression in mid-tier product lines is intensifying because copper and rare-earth input volatility squeezes OEM margins. Rental property management companies in Haifa and Beersheba exhibit highest price sensitivity due to municipal mandate compliance deadlines, while Tel Aviv metropolitan developers demonstrate lowest sensitivity given bundled procurement scale.
Supply Chain Analysis
Builder-direct procurement teams mandate dual-sourcing qualification for inverter-compressor cooling systems, requiring manufacturers to demonstrate redundant production footprints before volume contract award. Finished appliance flows concentrate through China, South Korea, and Turkey, with compressor motor laminations and permanent-magnet materials drawing from East Asian metallurgy corridors. Single-source vulnerability concentrates at Ashdod and Haifa port corridors, where maritime chokepoint risk exposes inventory cycles to customs clearance variability. Distribution runs through direct-to-installer logistics for compact urban categories and specialty store service bundling for premium European brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Israel's appliance market operates as a supply-constrained story where Standards Institution of Israel certification queues bottleneck qualified product availability and prop pricing power for certified manufacturers. This capacity limitation in testing infrastructure creates structural premiums for pre-approved inventory.
For Market Incumbents: Lock in builder-direct specification relationships with Tel Aviv and Jerusalem developers before municipal code amendments expand to additional districts. Secure captive supply of inverter electronics and compressor laminations through backward integration into component sourcing, insulating margin structures from rare-earth price volatility that threatens mid-tier product lines.
For New Entrants and Emerging Players: The mid-tier price-point gap between premium European brands and economy mechanical systems offers white-space entry through MEPS Tier 1 certified products positioned for rental property compliance mandates in Haifa and Beersheba. Target online retail channels with compact washer-dryer systems using direct-to-installer logistics that bypass traditional showroom overhead and accelerate volume turnover.
For Investors and Strategic Acquirers: Acceleration in Standards Institution of Israel certification queue lengths is the leading indicator that qualified supply scarcity will deepen pricing power for certified manufacturers. Position for five-to-ten year viability around domestic-positioned suppliers with established testing relationships and local manufacturing footprints. Monitor pending amendments to building codes in peripheral municipalities as the signal for expanded mandate-driven replacement demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Investment | Early MEPS Tier 1 testing secures port entry priority before seasonal demand peaks. |
| Builder-Direct Contracting | Volume appliance packages with Tel Aviv developers bypass distributor markup and anchor specification. |
| Component Backward Integration | In-house production of inverter electronics reduces exposure to copper and rare-earth volatility. |
| Online Channel Development | Platform retail with direct-to-installer logistics captures compact urban appliance turnover. |
| Periphery Zone Distribution | Service network expansion into Galilee and Negev unlocks replacement white space as grid reliability improves. |
Research Methodology
Document review covered customs import records, Standards Institution of Israel certification filings, and municipal building code amendments, complemented by interviews with appliance category managers at retail chains, procurement directors at residential developers, regulatory affairs specialists at import distributors, and service network heads at domestic manufacturers. Secondary validation drew from National Infrastructure, Energy and Water Ministry efficiency standard publications, port authority throughput data, and electricity regulator demand-response program disclosures. Bottom-up unit shipment estimates triangulated against top-down construction permit flows and replacement cycle assumptions.
Market sizing and growth projections across the analysis window segmented by product type, end-user category, technology tier, and distribution channel, with particular attention to builder-direct versus retail-channel procurement splits. CAGRs derived from regression analysis of historical shipment trends against regulatory milestone timing and construction pipeline data. Forecast inputs incorporated inverter-compressor adoption curves, Shabbat-mode functionality demand in Orthodox communities, and smart grid integration participation rates.
Underlying measurement precision varies by segment; new construction and rental property end-use categories carry tighter precision than dispersed household replacement demand due to visible permit and mandate documentation. Forecasts reflect assumptions regarding certification timeline resolution, copper price trajectory stabilization, and municipal code amendment propagation. Deviation in Standards Institution of Israel testing capacity expansion or maritime corridor disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
India Home Appliances Market
Home Appliances
Germany Home Appliances Market
Home Appliances
Asia-Pacific Major Home Appliance Market
Home Appliances
Germany Household Side by Side Refrigerator Market
Home Appliances
India Major Home Appliances Market
Home Appliances
GCC Small Home Appliances Market
Home Appliances
Household Refrigerator Market
Home Appliances
Colombia Home Appliances Market
Home Appliances
UK Household Appliances Market
Home Appliances
Japan Small Home Appliances Market
Home Appliances
High-End French Door Refrigerator Market
Home Appliances
Germany Small Home Appliance Market
Home Appliances
Household Refrigerators and Freezers Market
Home Appliances
Oman Home Appliances Market
Home Appliances
Kuwait Major Home Appliances Market
Home Appliances
United Kingdom Washing Machine Market