
 Saudi Arabia Microwave Ovens Market | 2026-2036
Saudi Arabia Microwave Ovens Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Microwave Ovens Market Analytics
The hospitality sector is realigning procurement patterns across Saudi Arabia's food service landscape. Samsung Electronics leverages its brand strength in built-in installations for premium hotel kitchens. LG Electronics sustains channel control through distributor networks serving Riyadh's commercial corridors. Panasonic Corporation specializes in compact countertop units targeting smaller cafés and quick-service outlets.
A microwave oven is an electric appliance that generates electromagnetic radiation at frequencies near 2.45 GHz to heat polar molecules in food, typically operating at power ratings from 600 to 1,200 watts for residential units and exceeding 1,800 watts for commercial applications. Solo microwave units occupy the volume base in residential settings across Saudi Arabia, while convection variants command margin pools as consumers seek multi-function cooking capabilities. Built-in installation types are gaining traction in new residential developments, though countertop configurations still dominate replacement cycles.
SASO technical regulations govern energy efficiency labeling and electromagnetic compatibility for appliances sold in the Kingdom. SFDA oversight extends to food-contact surface safety in commercial microwave applications, particularly within institutional catering contracts. Stakeholders must monitor evolving efficiency tiers and halal food preparation certification requirements as procurement standards tighten across Saudi Arabia's hospitality and healthcare sectors.
Market Dynamics
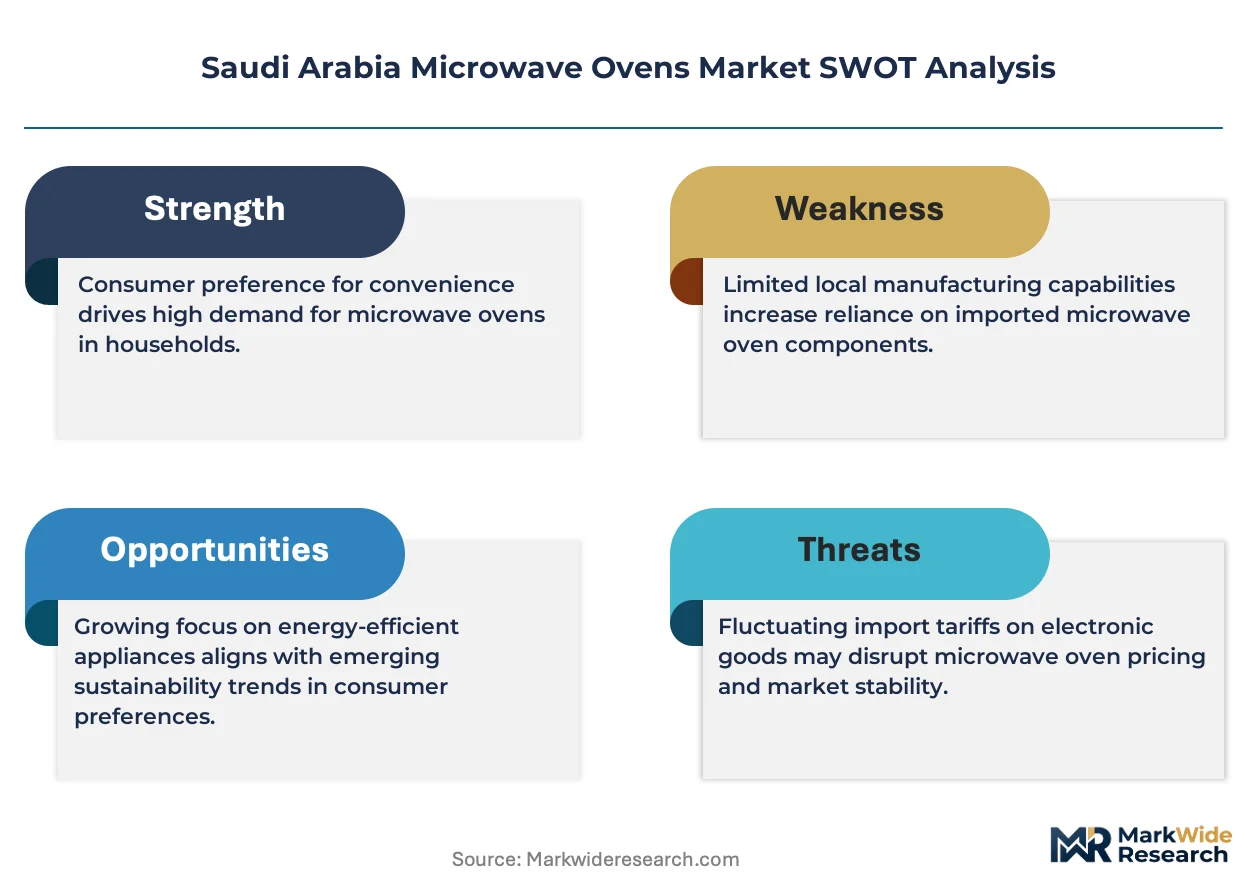
SASO energy efficiency mandates and SFDA appliance safety standards are compressing product development cycles while hospitality procurement accelerates toward commercial-grade specifications. Manufacturers must now certify across dual regulatory tracks before accessing Riyadh's food service clusters.
Growth Catalysts
- Commercial kitchen electrification:Saudi Arabia's hospitality sector is retrofitting properties with high-wattage convection microwave units to reduce gas dependency. Institutional catering contracts now specify electromagnetic cooking equipment.
- SASO energy labeling mandates:The Kingdom's efficiency tier system is pulling replacement demand toward inverter-based magnetron technologies. Retailers report accelerated trade-in activity as older units face import restrictions.
- Jeddah retail corridor expansion:New mall developments along the Red Sea coast are embedding built-in microwave configurations as standard kitchen amenities. Property developers negotiate volume procurement agreements with appliance distributors.
Market Restraints
- Magnetron component concentration:Critical vacuum tube manufacturing clusters in East Asia create single-source vulnerability for Saudi importers. Shipping disruptions compress inventory buffers to six-week averages.
- SFDA certification timelines:Food-contact surface testing protocols add four to six months to product registration cycles. Commercial units face additional electromagnetic compatibility verification.
- Induction cooktop substitution:Restaurant operators in Riyadh's premium districts are diverting capex toward induction ranges with comparable speed-to-heat performance. Microwave vendors respond with hybrid convection-infrared configurations.
Strategic Opportunities
- Healthcare institutional catering:MOHAP hospital nutrition departments require halal-certified commercial units with programmable cooking cycles. Tender volumes exceed five hundred units per major facility rollout.
- Smart kitchen convergence:IoT-enabled microwave units with remote diagnostics are penetrating Saudi Arabia's cloud kitchen segment. Operators prioritize predictive maintenance to minimize downtime in high-throughput environments.
- Asir Province retail penetration:Appliance distribution networks remain underdeveloped in southwestern mountain cities. Local distributor partnerships could capture replacement cycles in Abha and Khamis Mushait.
Industry Challenges
- Field service technician scarcity:Commercial microwave repair specialization is concentrated in Riyadh and Jeddah. Smaller cities face fourteen-day average resolution times for magnetron failures.
- Legacy electrical infrastructure:Older residential compounds in Dammam's industrial zones lack dedicated circuits for 1,800-watt commercial units. Retrofit costs deter property managers from specification upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Microwave Ovens Market |
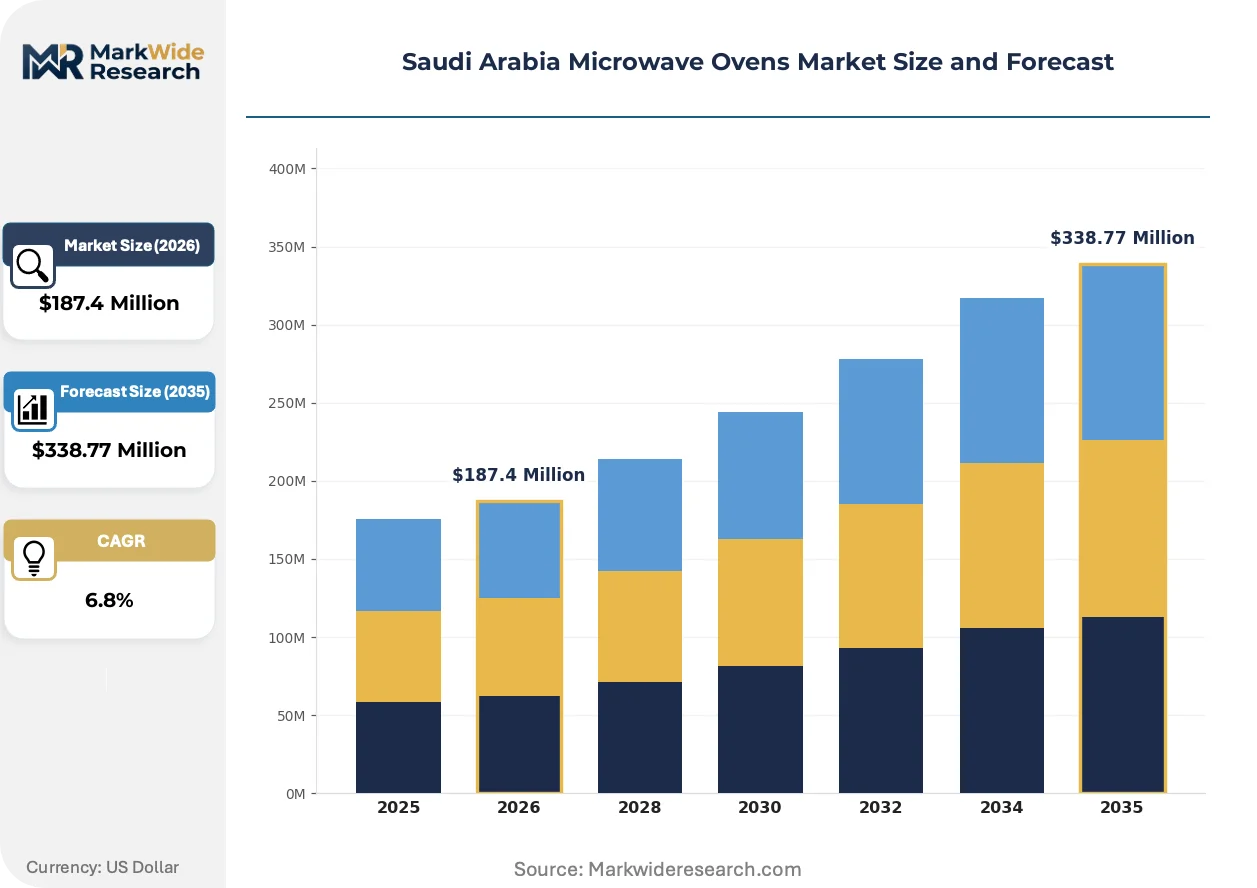
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Convection, Grill, Solo, Over-the-Range Installation Type: Built-in, Countertop, Freestanding, Under-cabinet End User: Residential, Commercial, Institutional, Hospitality Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Distributors |
| Companies Covered | Midea Group, AB Electrolux, Samsung Electronics, Sharp Electronics Corporation, Haier, LG Electronics, Whirlpool Corporation, Hommer, Panasonic Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Microwave Ovens Market Evolving Landscape
Inverter magnetron technology is compressing cooking cycle variability while smart connectivity protocols enable remote fleet management. Regulatory pressure on electromagnetic emissions is simultaneously tightening product design constraints.
Variable-frequency inverter drives are electrifying power delivery in Saudi Arabia's premium residential segment. The technology replaces mechanical power relays with solid-state switching to enable continuous heat modulation. Luxury villa developers in Riyadh's northern districts specify inverter units as standard. This capability is electrifying margin structures by differentiating product tiers beyond basic wattage specifications.
SFDA electromagnetic compatibility testing protocols are expanding scope to include commercial kitchen networking equipment. The regulation now requires shielding verification for units operating near Wi-Fi infrastructure. Hospital nutrition departments face the steepest compliance burden due to medical device proximity requirements. Manufacturers are redesigning chassis grounding systems to meet the revised emission thresholds.
Cloud kitchen operators are unbundling equipment ownership from cooking service contracts. Third-party lessors now supply microwave fleets to Jeddah's delivery-focused food ventures with maintenance-inclusive terms. Traditional distributor relationships are fragmenting as procurement authority shifts to specialized kitchen-as-a-service providers. This model concentrates most visibly in Riyadh's Al Olaya and Al Mohammadiyah districts where virtual brand density exceeds traditional restaurant counts.
Saudi Arabia Microwave Ovens Market Segmentation
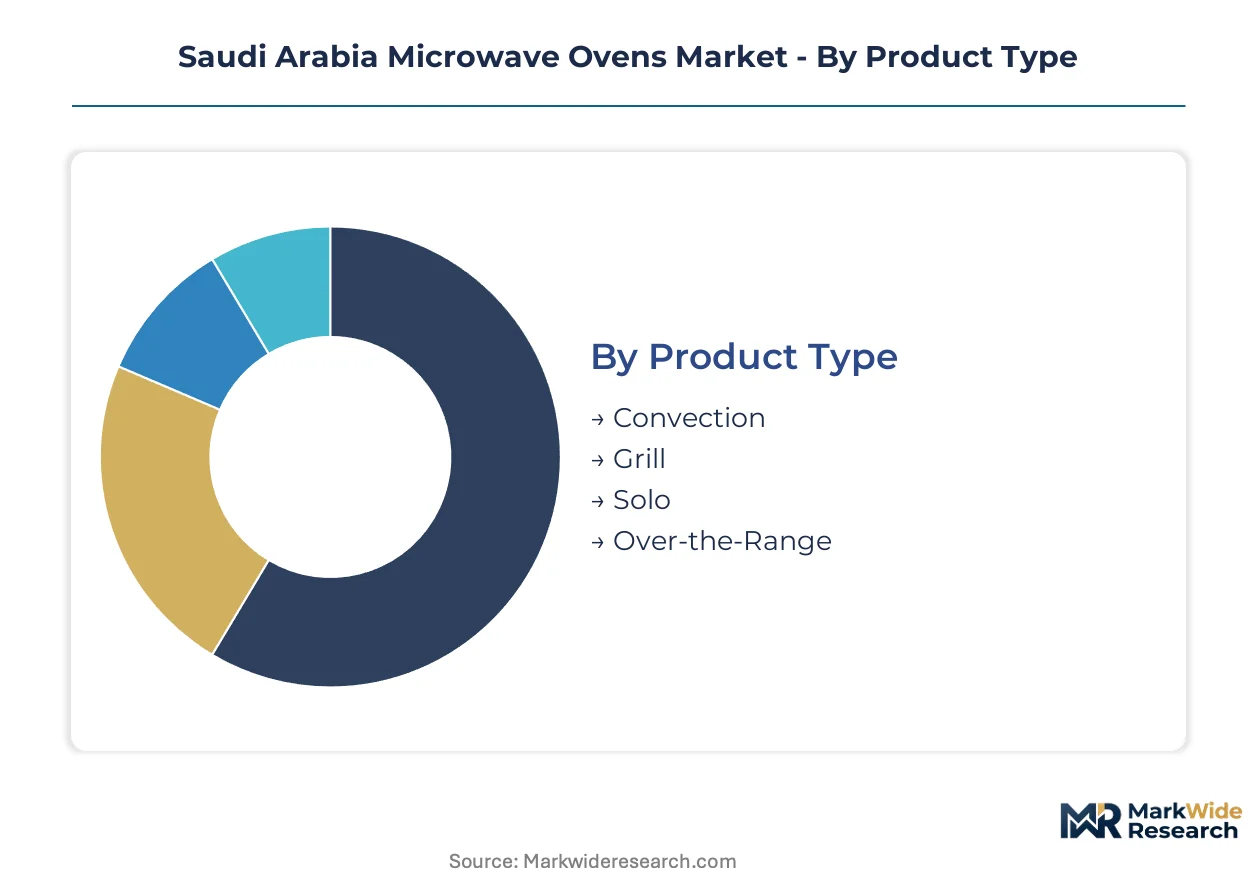
Microwave oven procurement in Saudi Arabia fragments across installation constraints, power requirements, and buyer sophistication. Upgrade cycles and replacement demand differ sharply between residential compounds and commercial food service clusters.
Product Type:
Replacement cycles vary by cooking functionality, with basic units turning over faster than multi-function configurations. SASO energy labeling accelerates obsolescence in older magnetron designs.
- Convection:Combines electromagnetic heating with forced-air circulation to enable browning and roasting functions unavailable in standard units. Saudi villa developments in Riyadh's northern districts specify convection models as standard in premium kitchen packages, driven by consumer demand for multi-appliance consolidation.
- Grill:Integrates quartz or sheath heating elements above the cooking cavity to provide direct radiant heat for surface crisping. Quick-service outlets along Jeddah's Tahlia Street favor grill-microwave hybrids to expand menu versatility without expanding kitchen footprints.
- Solo:Basic electromagnetic heating without auxiliary cooking modes dominates apartment replacement cycles and budget hospitality procurement. Volume concentrates in mass-market retail channels serving Dammam's industrial workforce housing.
- Over-the-Range:Combines microwave function with ventilation hood and cooktop lighting in a single appliance. New residential towers in Riyadh's King Abdullah Financial District embed these units to maximize spatial efficiency in compact luxury units.
Volume placements concentrate in Solo configurations; the faster expansion belongs to Convection variants.
Installation Type:
Physical integration requirements shape procurement authority, with built-in specifications controlled by property developers and countertop purchases driven by end-user discretion. Electrical infrastructure constraints in older buildings limit upgrade flexibility.
- Built-in:Designed for seamless cabinet integration with standardized trim kits and ventilation ducting. Luxury hotel renovations in Jeddah's Corniche district specify built-in convection units to achieve kitchen aesthetic uniformity.
- Countertop:Self-contained units requiring no permanent installation dominate replacement demand and rental property provisioning. Saudi Arabia's expatriate housing compounds in Riyadh's Diplomatic Quarter rely exclusively on countertop configurations for tenant flexibility.
- Freestanding:Floor-based units with integrated storage or warming drawers serve high-volume commercial kitchens. Institutional catering facilities at MOHAP hospitals specify freestanding configurations for mobility between prep stations.
- Under-cabinet:Mounts beneath overhead storage to reclaim counter space in compact kitchens. Cloud kitchen operators in Riyadh's Al Olaya district specify under-cabinet units to maximize linear footage for ingredient staging.
Countertop units command the volume base; built-in configurations are climbing the fastest as new construction accelerates.
End User:
Buyer sophistication and procurement scale separate residential replacement from institutional tender processes. Commercial operators prioritize throughput metrics; residential purchasers emphasize feature accessibility.
- Residential:Individual households and family compounds purchasing through retail channels for domestic food preparation. Riyadh's northern suburbs drive replacement demand as villa owners upgrade from basic solo units to inverter-based convection models.
- Commercial:Independent restaurants, cafés, and food service operators procuring through distributor networks. Jeddah's Red Sea tourism corridor generates concentrated demand for high-wattage commercial units with rapid cycle capabilities.
- Institutional:Government facilities, healthcare nutrition departments, and educational catering operations procuring through formal tender processes. MOHAP hospital rollouts specify programmable commercial units with halal certification documentation.
- Hospitality:Hotel chains and serviced apartment operators standardizing kitchen configurations across property portfolios. New developments along the Saudi Red Sea Project embed built-in microwave units as guest amenity standards.
Residential channels absorb the highest unit volumes; hospitality procurement is expanding most quickly as tourism infrastructure scales.
Distribution Channel:
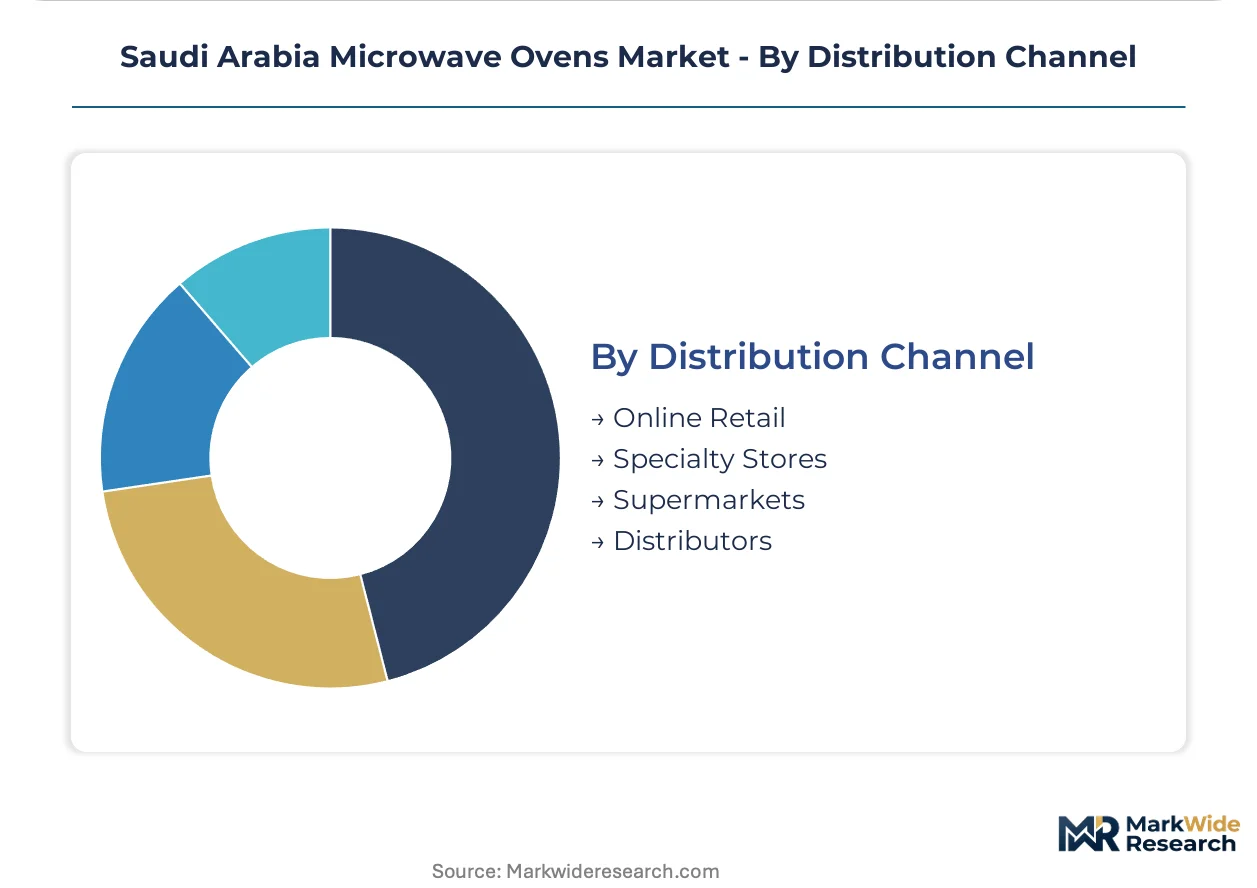
Channel control reflects buyer type and purchase urgency, with commercial procurement consolidating through specialized distributors while residential demand fragments across retail formats. Online penetration lags behind regional benchmarks due to installation service requirements.
- Online Retail:E-commerce platforms and direct-to-consumer portals serving replacement demand with delivery logistics. Riyadh's younger demographic segments drive online growth for countertop solo units with straightforward self-installation.
- Specialty Stores:Kitchen appliance showrooms offering consultation and installation coordination. Jeddah's home improvement clusters along Palestine Street concentrate specialty retail serving villa renovation projects.
- Supermarkets:Mass merchandisers and hypermarkets stocking entry-level configurations for impulse and convenience purchases. Dammam's retail corridors rely on supermarket channels for expatriate workforce housing provisioning.
- Distributors:B2B intermediaries managing commercial procurement, installation, and maintenance contracts. Hospitality procurement in Riyadh's Al Mohammadiyah district flows through specialized distributors with SFDA certification expertise.
Supermarket and specialty retail split the residential volume; distributor channels are gaining share fastest as commercial kitchen electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
King Abdullah Economic City's industrial zones are concentrating appliance assembly operations near Red Sea logistics corridors. SASO certification laboratories in Riyadh process efficiency compliance for units distributed nationwide. This geographic pattern shapes procurement routing across the Kingdom's major population centers.
Riyadh
Central Region demand concentrates in hospitality procurement for new hotel developments along King Abdullah Road. SASO energy labeling mandates accelerate replacement cycles in residential compounds. The Al Mohammadiyah and Al Olaya districts host cloud kitchen clusters specifying commercial-grade convection units.
Jeddah
Western Region retail corridors drive built-in microwave specifications for luxury residential towers. SFDA food-contact certification requirements extend product registration timelines for commercial units entering hospital nutrition departments. The Corniche district's hotel renovations prioritize aesthetic integration of built-in configurations.
Eastern Province
Dammam's industrial workforce housing generates volume demand for countertop solo units through supermarket channels. Legacy electrical infrastructure in older compounds limits wattage upgrades for commercial specifications. The region's expatriate population sustains replacement demand through mass-market retail formats.
Asir Province
Southwestern mountain cities present underdeveloped distribution networks for appliance servicing. Abha and Khamis Mushait replacement cycles lag national averages due to technician scarcity. Local distributor partnerships could capture pent-up demand as residential stock ages.
NEOM Northwest
The giga-project's smart city infrastructure embeds IoT-enabled kitchen equipment specifications from initial construction phases. Procurement frameworks prioritize predictive maintenance capabilities and remote diagnostics integration. This development establishes new technical benchmarks for subsequent hospitality projects nationwide.
Saudi Arabia Microwave Ovens Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments. Residential channels favor recognized consumer electronics brands with established retail presence. Commercial procurement consolidates through distributors managing SFDA certification and field service networks. Three archetypes dominate: Korean conglomerates with full appliance portfolios, Japanese precision manufacturers, and Chinese volume producers. Competitive moves concentrate on distributor exclusivity agreements and inverter technology licensing.
Among Korean-headquartered conglomerates, Samsung Electronics and LG Electronics exemplify the integrated appliance portfolio archetype. Panasonic Corporation represents Japanese precision manufacturing positioning in compact commercial configurations. Midea Group anchors Chinese volume production capabilities serving price-sensitive residential segments. Each occupies distinct competitive terrain without direct overlap in procurement specifications.
| Leading Market Players |
|---|
| Midea Group |
| AB Electrolux |
| Samsung Electronics |
| Sharp Electronics Corporation |
| Haier |
| LG Electronics |
| Whirlpool Corporation |
| Hommer |
| Panasonic Corporation |
| Others |
Value Network & Pricing Analysis
Inverter-magnetron certification divergence separates premium kitchen packages from mass-market countertop units, with SASO energy tier compliance requiring upstream supplier requalification that compresses margin structures at the economy end while sustaining pricing power for hospital-grade commercial configurations.
Pricing Analysis
Short lead-time premiums attach to commercial units stocked in Jeddah distributor warehouses, while spot inventory discounts emerge for older magnetron designs facing import restriction deadlines. Three-tier pricing structure across premium, standard, and economy levels tracks inverter technology adoption, with SFDA certification tier and after-sales service bundling as primary differentiation drivers. Cost compression in solo countertop segments intensifies as Chinese volume producers expand Saudi retail presence. Expatriate workforce housing in Dammam exhibits highest price sensitivity; luxury villa developers in Riyadh's northern districts show lowest.
Supply Chain Analysis
Workforce availability constraints in South Korean and Japanese magnetron manufacturing clusters extend component lead times for Saudi importers. Vacuum tube production concentrates in China, South Korea, and Japan, with magnetron assemblies and inverter drive modules as critical inputs. Single-source vulnerability in East Asian component manufacturing creates inventory buffer compression. Distribution runs through specialized appliance distributors in Riyadh and Jeddah for commercial procurement, while supermarket and online retail channels serve residential replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's microwave oven sector sits at a technology-transition inflection as inverter-based magnetron designs displace legacy mechanical relay configurations, with smart connectivity protocols now penetrating cloud kitchen procurement specifications.
For Market Incumbents: To counter induction cooktop substitution in Riyadh's premium restaurant districts, Samsung Electronics and LG Electronics should deepen backward integration into inverter drive module production and lock distributor exclusivity agreements covering SFDA certification support. Channel control through certified service networks represents the critical defensive lever against emerging Chinese volume entrants. For New Entrants and Emerging Players: IoT-enabled predictive maintenance platforms offer a technology-first wedge into Riyadh's cloud kitchen segment, where equipment-as-a-service procurement models fragment traditional distributor relationships. Asir Province's underdeveloped service infrastructure presents the most penetrable geographic white space. A distributor partnership strategy targeting Abha and Khamis Mushait with maintenance-inclusive terms captures pent-up replacement demand. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale distributors possessing SFDA certification expertise and hospital tender track records given MOHAP's accelerating institutional catering rollouts. Long-term viability favors acquirers with five-to-ten year holding capacity for kitchen electrification tailwinds. Watch for inverter technology licensing agreements as inflection signals for margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Inverter Technology Licensing | Solid-state power modulation enables SASO Tier 1 compliance and premium positioning in Riyadh villa developments. |
| SFDA Certification Investment | Food-contact surface testing capabilities accelerate hospital nutrition department tender participation. |
| Cloud Kitchen Fleet Partnership | Equipment-as-a-service contracts capture procurement authority shifting from traditional distributors. |
| Asir Province Distribution Expansion | Local partnerships in Abha and Khamis Mushait address technician scarcity and service coverage gaps. |
| Smart Connectivity Integration | IoT-enabled remote diagnostics meet NEOM technical specifications and cloud kitchen uptime requirements. |
Research Methodology
Trade customs records, SASO regulatory filings, and hospitality procurement databases formed the secondary backbone, supplemented by primary interviews with commercial kitchen equipment distributors, SFDA compliance consultants, hospital nutrition department procurement managers, and cloud kitchen operators. Bottom-up and top-down triangulation validated shipment volumes against end-user replacement cycle surveys.
Bottom-up modeling built from product-type, installation-type, end-user, and distribution channel segmentation across the analysis window, with value outputs reflecting power rating tier and smart feature inclusion. CAGRs derived from regression analysis of historical replacement patterns and hospitality construction pipelines, incorporating inverter technology adoption curves and regulatory phase-in schedules as industry-specific inputs.
Several conditions sit outside the modeled scope, including unforeseen SASO efficiency tier acceleration, magnetron supply chain disruptions beyond six-week inventory buffers, and substitution effects from alternative electromagnetic cooking technologies. Forecasts reflect documented assumptions on hospitality construction timelines and certification processing durations. Material deviation in regulatory phase-in schedules or component supply continuity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Electrical Appliances Plastics Market
Appliances
UK Residential Vacuum Cleaner Market
Appliances
Residential Space Heater Market
Appliances
Intelligent Electric Rice Cooker Market
Appliances
Gas Ranges Market
Appliances
Europe Induction Hobs Market
Appliances
North America Microwave Oven Market
Appliances
Electric Rice Cooker Market
Appliances
Commercial Microwave Ovens Market
Appliances
Kuwait Microwave Ovens Market
Appliances
United Kingdom Tumble Dryers Market
Appliances
UAE Dishwasher Market
Appliances
GCC Microwave Oven Market
Appliances
Germany Consumer Appliances Market
Appliances
United States Microwave Oven Market
Appliances
Electric Ranges Market