
 India Flexible Plastic Packaging Market | 2026-2036
India Flexible Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
India Flexible Plastic Packaging Market Insights
A capital-intensity divergence between integrated film producers and standalone converters is rotating competitive advantage toward backward-linked players. Uflex Ltd. leverages captive resin compounding and metallization lines to sustain margin control across the value chain. Huhtamaki PPL Ltd. anchors its position through specialized aseptic and spouted pouch formats for dairy and beverage clients. Jindal Poly Films Ltd. dominates biaxially oriented polyester film supply, extending its reach into high-barrier laminates for pharmaceutical blister packs.
India flexible plastic packaging encompasses polymer-based films, laminates, and formed containers that conform to product geometry during filling, typically manufactured through blown film extrusion, cast film processes, or adhesive lamination of multilayer structures with thicknesses ranging from 20 microns to 250 microns depending on barrier requirements. Stand-up pouches with resealable fitments are displacing rigid containers in food & beverage applications as brands seek shelf differentiation and logistics efficiency. Polyethylene grades command volume leadership across bags and stretch films, though polypropylene is gaining in retort and microwaveable formats where thermal resistance commands premium positioning.
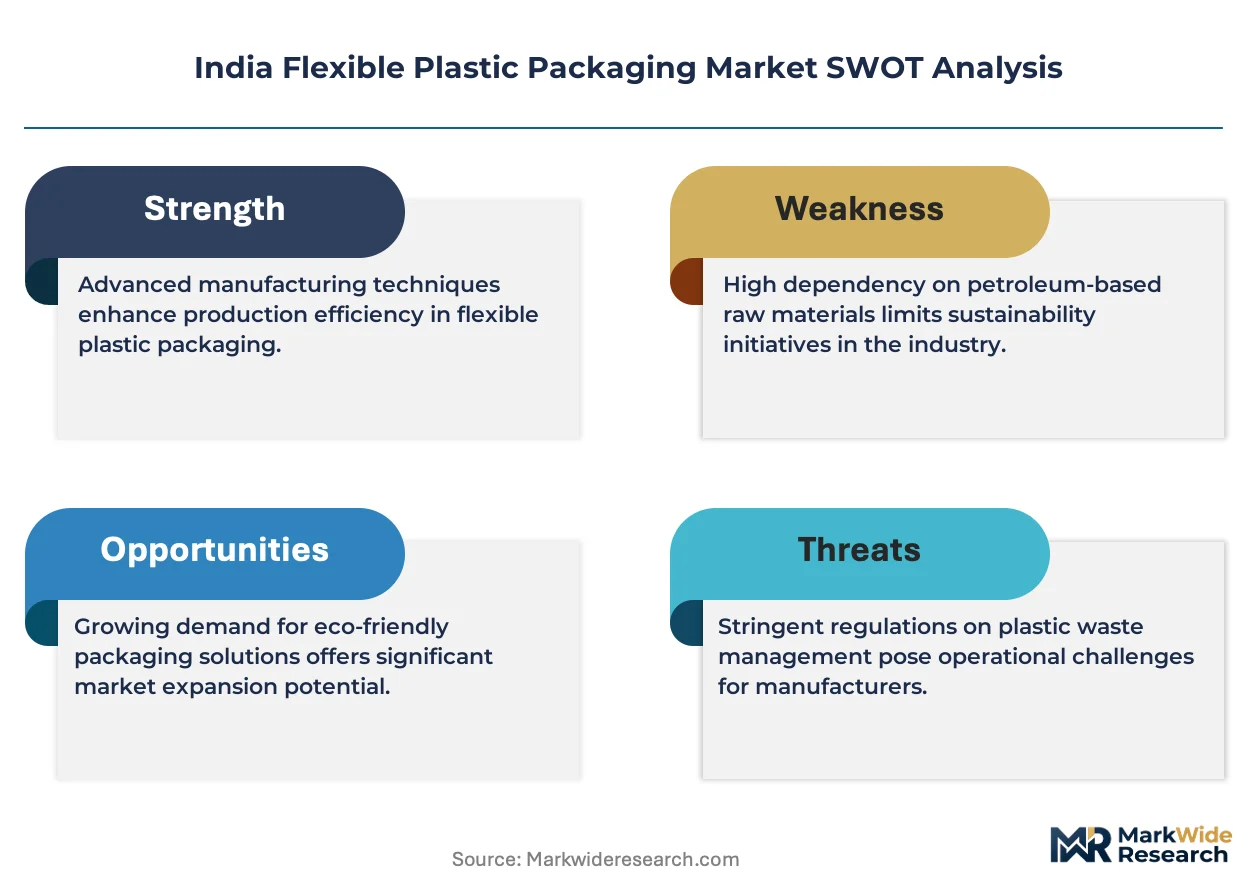
BIS certification for food-contact materials, Plastic Waste Management Rules enforced by the Central Pollution Control Board, and FSSAI migration limits collectively constrain formulation choices while accelerating mono-material redesign investments. The Extended Producer Responsibility framework now obliges brand owners to document collection and recycling pathways, shifting procurement criteria toward converter transparency. Stakeholders must monitor evolving EPR target thresholds and state-level plastic ban implementations to align capacity plans with compliance-ready material platforms.
Market Dynamics
India's Plastic Waste Management Rules and Extended Producer Responsibility mandates are forcing converters to abandon multilayer laminates in favor of recyclable mono-polymer structures, compressing margins while demanding capital redeployment across the value chain.
Growth Catalysts
- FSSAI Migration Limits:Stricter food-contact safety standards are accelerating compliant film investments by dairy and ready-to-eat meal processors seeking export eligibility.
- Polymer Resin Access:Maharashtra and Gujarat host concentrated polymer production and converting infrastructure that reduces logistics costs for FMCG contract packagers.
- Stand-up Pouch Formats:Food and beverage brands are adopting resealable fitment pouches to replace rigid containers, driven by shelf differentiation and e-commerce logistics efficiency.
Market Restraints
- Crude-Linked Resin Volatility:Polyethylene and polypropylene prices swing with naphtha and natural gas feedstock costs, squeezing converter margins on fixed-price FMCG contracts.
- Import Dependency for Specialty Additives:Barrier coatings and oxygen scavengers concentrate among European and Japanese suppliers, exposing converters to currency and shipping risks.
- Technical Limitations of Mono-Materials:Current polyethylene-only structures fail to match multilayer barrier performance for retort and aseptic applications, constraining regulatory-compliant format options.
Strategic Opportunities
- Chemical Recycling Infrastructure:Pyrolysis and depolymerization investments in Gujarat promise feedstock circularity that satisfies EPR documentation requirements for brand owners.
- Pharmaceutical Blister Packs:High-barrier laminates for temperature-sensitive drug delivery represent an underpenetrated segment with premium pricing power and regulatory entry barriers.
- PLI Scheme for Specialty Films:Government production-linked incentives for advanced polymer manufacturing are attracting capital toward domestic biaxially oriented film capacity.
Industry Challenges
- Mono-Material Redesign Expertise:Converters lack polymer scientists capable of reformulating multilayer barrier properties into single-resin structures without performance degradation.
- EPR Documentation Systems:Brand owners demand granular traceability of collection and recycling pathways that most small-scale converters cannot yet provide.
- Retooling Capex Burden:Shifting from solvent-based lamination to extrusion coating for recyclable structures requires press replacements exceeding typical mid-cap balance sheet capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Flexible Plastic Packaging Market |
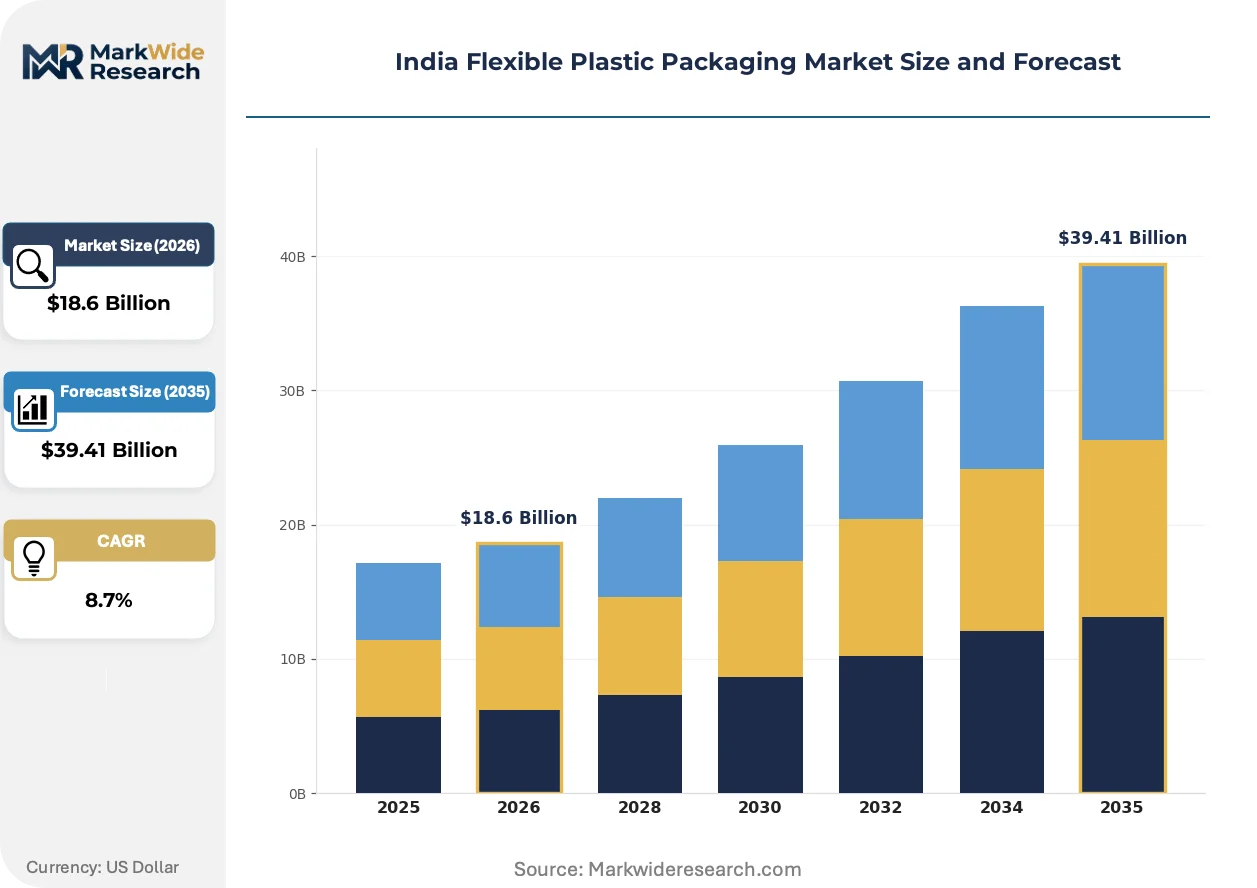
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $39.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Stretch Films, Shrink Films, Bags Application: Food & Beverage, Personal Care, Pharmaceuticals, Consumer Goods Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Others End User: Retail, Manufacturing, E-Commerce, Foodservice |
| Companies Covered | Uflex Ltd., Huhtamaki PPL Ltd., Essel Propack Ltd., Cosmo Films Ltd., Amcor Flexibles India, Jindal Poly Films Ltd., Polyplex Corporation Ltd., TCPL Packaging Ltd., Garware Polyester Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Flexible Plastic Packaging Market Trends and Innovations
Digital printing and metallization technologies are compressing minimum order quantities and accelerating SKU proliferation, while regulatory pressure on recyclability is rewiring material selection protocols across the converter base.
Digital flexographic and inkjet printing systems are miniaturizing the economic run length for customized pouch graphics. Regional snack brands and private-label retailers are adopting these presses to support rapid flavor rotations and seasonal campaigns. This technology is miniaturizing the barrier to entry for brand differentiation, fragmenting volume across smaller production batches that favor agile converters over scale-dependent competitors.
BIS certification requirements for food-contact materials are tightening testing protocols for migration limits and heavy metal content. The Central Pollution Control Board enforcement of these standards is disqualifying informal compounders from approved supplier lists. Dairy processors in Punjab and Haryana are responding by consolidating procurement toward certified film suppliers with documented quality management systems.
Direct-to-retailer procurement models are compressing the traditional distributor-converter-brand owner hierarchy. Large FMCG chains in Mumbai and Delhi are establishing specifications committees that bypass legacy packaging brokers and negotiate directly with film producers. This disintermediation is most visible in the organized retail sector, where private-label share expansion demands faster turnaround and transparent cost structures than conventional channel arrangements permit.
India Flexible Plastic Packaging Market Segmentation
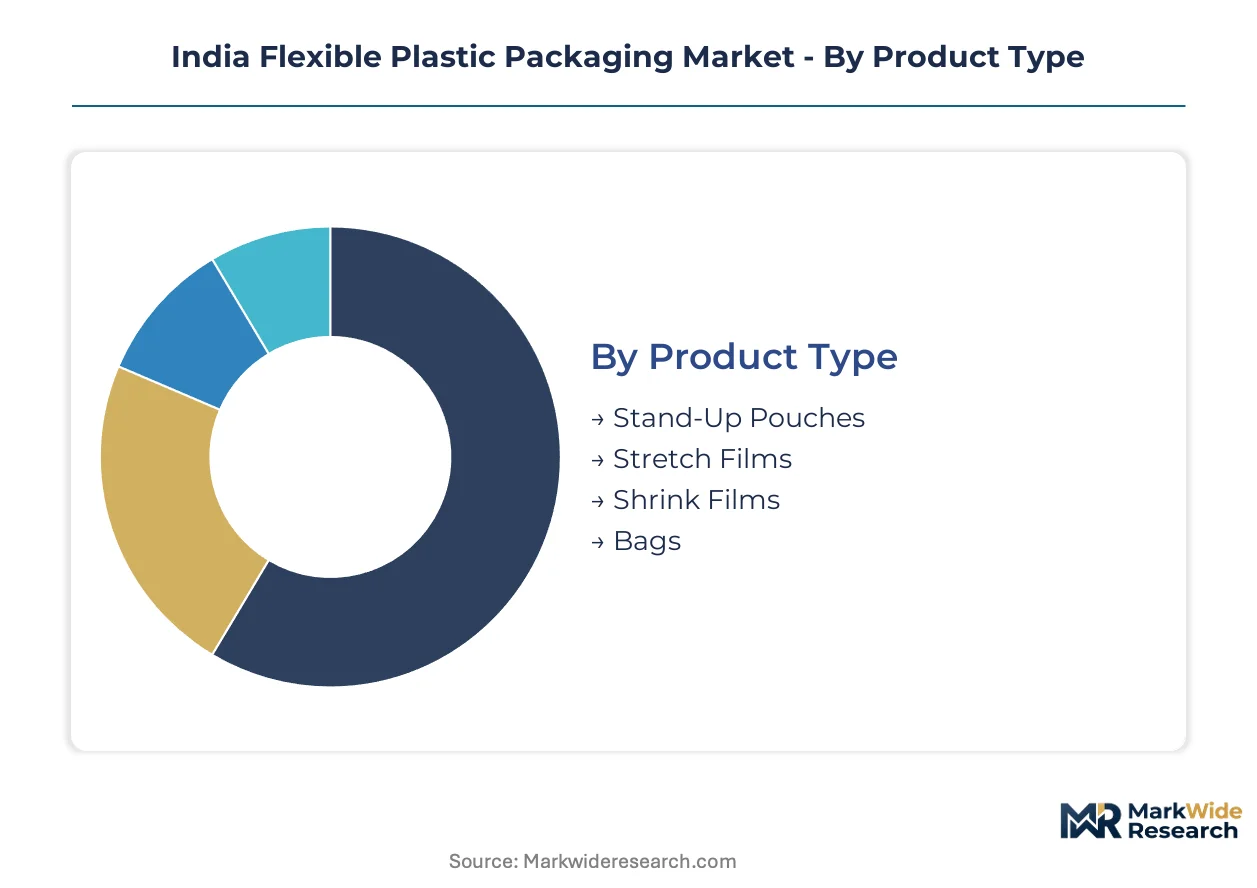
Segmentation in India's flexible plastic packaging market reveals how regulatory pressure and end-use specialization are fragmenting demand across material platforms and format types. Each category exposes distinct margin structures, compliance burdens, and geographic concentration patterns that determine converter strategy.
Product Type:
Domestic consumption dominates pouches and bags, while stretch and shrink films serve substantial export demand to Middle East and African markets.
- Stand-Up Pouches:Multilayer laminates with resealable fitments and spouts, typically 80-150 microns thick, incorporate EVOH or metallized layers for oxygen barrier. Dairy processors in Punjab and Haryana are consolidating procurement toward BIS-certified suppliers as FSSAI migration limits tighten. The format displaces rigid containers in ready-to-eat meals and extended shelf-life dairy.
- Stretch Films:Linear low-density polyethylene cast films, 12-25 microns, with cling additives for pallet unitization. Manufacturing clusters in Gujarat supply export markets across the Gulf region, though crude-linked resin volatility compresses margins on fixed-price contracts.
- Shrink Films:Polyethylene or polypropylene oriented films that contract 40-60% upon heat application for collation and display packaging.
- Bags:Single-ply or laminated polyethylene structures ranging from 20 microns for lightweight carry bags to 100+ microns for industrial liners.
Bags command the established base. The steepest expansion runs through stand-up pouches.
Application:
Cost tier stratification separates commodity food wrapping from premium pharmaceutical barrier laminates with tenfold price differentials.
- Food & Beverage:Retort pouches, aseptic cartons, and modified atmosphere packaging for dairy, snacks, and ready-to-eat meals. Maharashtra-based FMCG contract packagers drive volume concentration.
- Personal Care:Sachets, pillow pouches, and laminated tubes for shampoos and cosmetics. E-commerce logistics efficiency demands are accelerating format experimentation.
- Pharmaceuticals:High-barrier cold-form foil laminates and blister packs with WVTR specifications below 0.1 g/m²/day. CDSCO stability requirements and temperature-sensitive drug delivery needs create regulatory entry barriers that sustain premium pricing.
- Consumer Goods:Durable goods overwrap and promotional packaging with lower barrier specifications.
Food and beverage absorbs the volume base. Pharmaceuticals delivers the margin expansion.
Material:
Volume concentration favors polyethylene, though polypropylene gains share in thermal-resistant applications where regulatory-compliant mono-material redesign is accelerating.
- Polyethylene:LDPE, LLDPE, and HDPE grades dominate bags, stretch films, and general-purpose laminates. Gujarat polymer resin access reduces logistics costs for converters serving domestic FMCG clients.
- Polypropylene:Biaxially oriented and cast films for retort, microwaveable, and high-clarity applications. Central Pollution Control Board enforcement of Plastic Waste Management Rules is forcing transitions toward recyclable mono-polymer structures where polypropylene thermal resistance commands premium positioning.
- Polyvinyl Chloride:Shrinking share in food contact due to migration concerns and regulatory scrutiny.
- Others:Biodegradable additives, bio-based polymers, and niche barrier coatings.
Polyethylene anchors current capacity. Polypropylene captures the redesign investment flow.
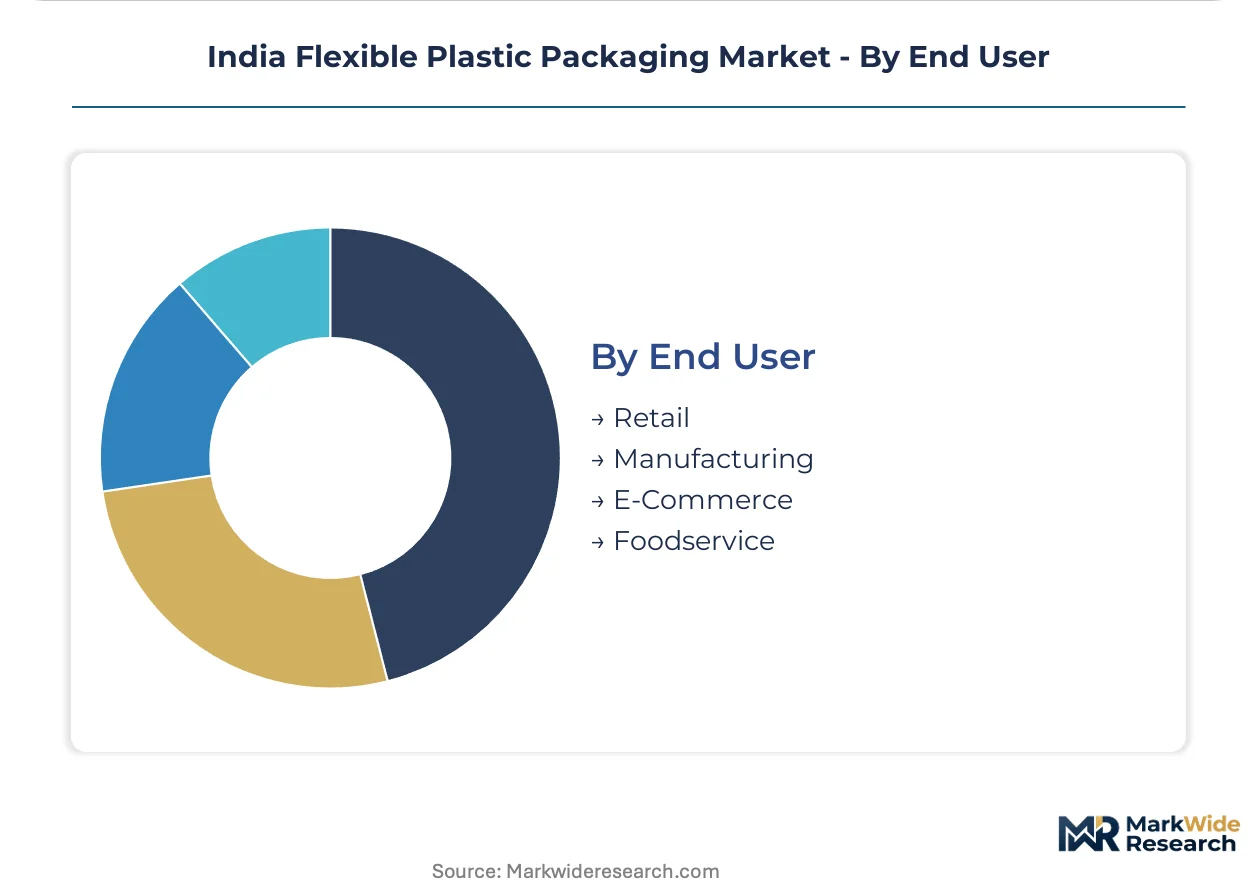
End User:
Customer type determines order fragmentation, with retail and e-commerce demanding SKU proliferation that strains converter flexibility.
- Retail:Large organized chains in Mumbai and Delhi are establishing direct procurement committees that disintermediate traditional packaging brokers. Private-label expansion demands faster turnaround than conventional channel arrangements permit.
- Manufacturing:Industrial processors of dairy, snacks, and pharmaceuticals with volume contracts and stringent quality management system requirements.
- E-Commerce:Third-party logistics providers and direct-to-consumer brands requiring damage-resistant, lightweight formats with return-friendly designs.
- Foodservice:Quick-service restaurants and institutional catering with high-throughput, cost-sensitive packaging needs.
Manufacturing retains the volume core. E-commerce is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Indian states. Maharashtra and Gujarat buyers absorb premium pricing for certified barrier films. Northern dairy processors in Punjab and Haryana squeeze converters on commodity pouch margins.
Maharashtra
FMCG contract packagers in Mumbai and Pune drive multilayer laminate demand for ready-to-eat meals and extended shelf-life dairy. FSSAI migration limit enforcement tightens supplier qualification, disqualifying informal compounders. Thane-Ambernath converting clusters concentrate metallization and pouch forming capacity serving organized retail chains.
Gujarat
Polymer resin production at Dahej and Hazira reduces logistics costs for polyethylene converters supplying domestic and export stretch film markets. Central Pollution Control Board Plastic Waste Management Rules enforcement accelerates chemical recycling investments. Ahmedabad-Vadodara corridor hosts pyrolysis pilot plants targeting EPR-compliant feedstock circularity.
Punjab and Haryana
Dairy cooperatives and milk processing units generate concentrated pouch demand with stringent cost controls. BIS certification requirements for food-contact materials filter procurement toward documented quality management systems. Ludhiana and Karnal industrial zones concentrate mid-cap converters serving Amul and Verka supply chains.
Tamil Nadu
Pharmaceutical manufacturers in Chennai and Hyderabad corridor source high-barrier blister packs and cold-form laminates for temperature-sensitive drug exports. CDSCO stability requirements sustain premium pricing for certified suppliers. Sri City and Oragadam industrial belts attract pharmaceutical packaging investments from integrated film producers.
Delhi-NCR
E-commerce logistics providers and direct-to-consumer brands demand damage-resistant, lightweight formats with rapid turnaround. Extended Producer Responsibility documentation requirements from brand owners strain small-scale converter compliance capacity. Faridabad and Noida packaging clusters pivot toward digital printing systems to serve SKU proliferation for private-label retailers.
India Flexible Plastic Packaging Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-speed margin structure. Backward-linked players with captive resin compounding and metallization lines sustain pricing power against standalone converters exposed to raw material volatility. Three archetypes dominate: integrated polymer-to-pouch producers, specialized barrier film specialists, and regional mid-cap converters serving single end-use segments. Competitive moves concentrate on mono-material redesign investments and direct-to-retailer procurement bypass of traditional distribution channels.
Among integrated domestic producers, Uflex Ltd., Jindal Poly Films Ltd., and Huhtamaki PPL Ltd. occupy positions spanning resin handling through finished pouch supply. Uflex exemplifies the backward-integrated archetype with captive compounding and metallization assets. Jindal Poly Films Ltd. anchors biaxially oriented polyester supply for pharmaceutical and food barrier applications. Huhtamaki PPL Ltd. represents the multinational-specialist model with format expertise in aseptic and spouted pouch segments. These three sit within distinct strategic tiers rather than direct overlap, reducing price-driven confrontation.
| Leading Market Players |
|---|
| Uflex Ltd. |
| Huhtamaki PPL Ltd. |
| Essel Propack Ltd. |
| Cosmo Films Ltd. |
| Amcor Flexibles India |
| Jindal Poly Films Ltd. |
| Polyplex Corporation Ltd. |
| TCPL Packaging Ltd. |
| Garware Polyester Ltd. |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Dahej and Hazira polymer complexes anchors cost floors for polyethylene converters serving Maharashtra and Gujarat FMCG clusters, compressing margin headroom for standalone players lacking backward integration into resin compounding. This scale concentration simultaneously elevates price-setting power for integrated film producers while forcing mid-cap converters toward commodity pouch segments with thinner spreads.
Pricing Analysis
After-sales service contracts for metallization and barrier coating maintenance drive lifetime value capture for integrated producers serving pharmaceutical and dairy clients. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels separates BIS-validated suppliers from informal compounders. Pricing pressure stems from crude-linked resin volatility squeezing fixed-price FMCG contract margins. Small-scale converters in Punjab and Haryana exhibit highest price sensitivity, while Tamil Nadu pharmaceutical manufacturers absorb premium spreads for CDSCO-compliant cold-form laminates.
Supply Chain Analysis
Inventory lead times for European and Japanese oxygen scavenger additives stretch converter working capital cycles, exposing mid-cap players to currency and shipping risk accumulation. Raw material sourcing draws from Saudi and Singapore naphtha-fed resin supply, with specialty barrier coatings anchored in German and Japanese chemical production. Single-source vulnerability concentrates among additive suppliers, while distribution runs through Mumbai and Ahmedabad polymer trading hubs toward Thane-Ambernath converting clusters and northern dairy belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Paper-based and fiber-molded packaging substitution threatens flexible plastic incumbents as Extended Producer Responsibility mandates harden and brand owners pivot toward demonstrably recyclable alternatives.
For Market Incumbents: Compound barrier performance advantages in pharmaceutical and retort applications where mono-material alternatives fail regulatory compliance, while accelerating captive chemical recycling investments in Gujarat to satisfy EPR documentation requirements from FMCG brand owners. Prioritize backward integration into biaxially oriented film capacity eligible for PLI scheme incentives. For New Entrants and Emerging Players: Anchor in Delhi-NCR e-commerce logistics demand for damage-resistant lightweight formats with rapid SKU turnaround, where digital printing miniaturization favors agile converters over scale-dependent competitors. Target private-label retailer procurement committees disintermediating traditional packaging brokers. Pursue direct-to-retailer specifications development as primary go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated polymer-to-pouch producers with demonstrated mono-material redesign capabilities and documented EPR compliance systems. Five-to-ten year viability hinges on feedstock circularity infrastructure rather than volume scale alone. Target acquisition archetype: Gujarat-based converters with pyrolysis pilot partnerships and BIS certification depth. Monitor chemical recycling yield rates as inflection indicator for EPR-compliant feedstock cost competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Redesign Investment | Enables EPR compliance for FSSAI-regulated dairy and ready-to-eat meal processors. |
| Chemical Recycling Infrastructure | Pyrolysis capacity in Gujarat satisfies Central Pollution Control Board circularity documentation. |
| Direct-to-Retailer Procurement | Bypasses Mumbai and Delhi packaging brokers for faster private-label turnaround. |
| Digital Printing System Adoption | Serves SKU proliferation for e-commerce logistics providers in Delhi-NCR corridor. |
| Pharmaceutical Barrier Certification | CDSCO compliance for Tamil Nadu cold-form laminate demand captures premium spreads. |
Research Methodology
A spread of perspectives from polymer plant managers, FMCG procurement leads, dairy processor technical directors, and Central Pollution Control Board enforcement officers converged on the working assumptions for capacity utilization and regulatory compliance timelines. Primary fieldwork combined with secondary validation from BIS certification databases, FSSAI migration limit notifications, customs resin import records, and PLI scheme disclosure filings. Bottom-up converter capacity surveys triangulated against top-down polymer consumption estimates across the analysis window.
Segmentation dimensions modeled encompass material platform, product format, end-use application, and state-level regulatory enforcement cluster. Value projections throughout the forecast period derived from resin price elasticity modeling, EPR compliance cost pass-through assumptions, and format substitution rates for stand-up pouches displacing rigid containers. Industry-specific inputs incorporated dairy processor consolidation patterns in Punjab and Haryana, plus pharmaceutical export growth from Tamil Nadu.
Material uncertainties — abrupt state-level plastic ban implementations, naphtha price spike duration, and chemical recycling yield commercialization delays — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding EPR target threshold progression and mono-material barrier performance parity achievement. Revision becomes warranted when pyrolysis feedstock cost competitiveness crosses thresholds undercutting virgin resin spreads.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Saudi Arabia Flexible Plastic Packaging Market
Flexible Packaging
Metalized Flexible Packaging Market
Flexible Packaging
Global Breathable Films Market
Flexible Packaging
Bakery Flexible Packaging Market
Flexible Packaging
Global Flexible Packaging Market
Flexible Packaging
Russia Flexible Plastic Packaging Market
Flexible Packaging
China Flexible Packaging Market
Flexible Packaging
Flexible Intermediate Bulk Container Market
Flexible Packaging
North America Flexible Plastic Packaging Market
Flexible Packaging
Mexico Flexible Packaging Market
Flexible Packaging
Brazil Flexible Plastic Packaging Market
Flexible Packaging
Japan Flexible Plastic Packaging Market
Flexible Packaging
Flexible Lid Stock Packaging Market
Flexible Packaging
Converted Flexible Packaging Market
Flexible Packaging
Kenya Flexible Packaging Market
Flexible Packaging
Flexible Containers Market