
 Global Breathable Films Market | 2026-2036
Global Breathable Films Market Size, Share, and Industry Trends Forecast 2026-2036
Global Breathable Films Market Foresight
Medical textiles and hygiene products is broadening as the dominant application cluster for breathable films, displacing traditional construction-focused volumes in several developed markets. Covestro leverages its polyurethane chemistry expertise to supply high-performance membrane grades for surgical drapes and wound care laminates. Berry Global sustains manufacturing scale across multiple continents, anchoring its position in baby care and adult incontinence backsheet supply chains. RKW Group competes through specialized extrusion capabilities that serve agricultural covering and protective apparel segments with tailored microporous structures.
Breathable films are thin, flexible barriers engineered with microporous or monolithic structures that permit water vapor transmission while blocking liquid water and particulate ingress, typically manufactured through cast extrusion, stretching, or phase-inversion processes to achieve controlled pore sizes between 0.1 and 10 micrometers. Their primary commercial purpose centers on moisture management in enclosed systems where condensation control, wearer comfort, or product integrity must coexist with environmental protection. Microporous polyethylene dominates volume production due to its cost-efficiency and compatibility with hygiene product lamination, while expanded polytetrafluoroethylene commands premium positioning in medical and industrial protective applications where biocompatibility and chemical resistance justify higher unit economics. Polyurethane films are gaining traction in textile lamination for performance apparel, though ethylene vinyl alcohol remains a niche player constrained by moisture sensitivity and processing complexity.
The FDA regulates breathable films incorporated into medical devices through biocompatibility testing requirements under ISO 10993, while the EPA oversees chemical constituent reporting for films containing per- and polyfluoroalkyl substances in the United States. REACH registration and restriction obligations within the European Union compel reformulation of certain additive packages, and China's SAMR enforces GB standards governing plasticizer migration limits in products contacting food or skin. Japan's METI maintains JIS standards for textile-functional film integration that influence export specifications for Asian manufacturers. Stakeholders must monitor evolving substance restrictions across these jurisdictions while evaluating captive extrusion investments versus merchant supply arrangements.
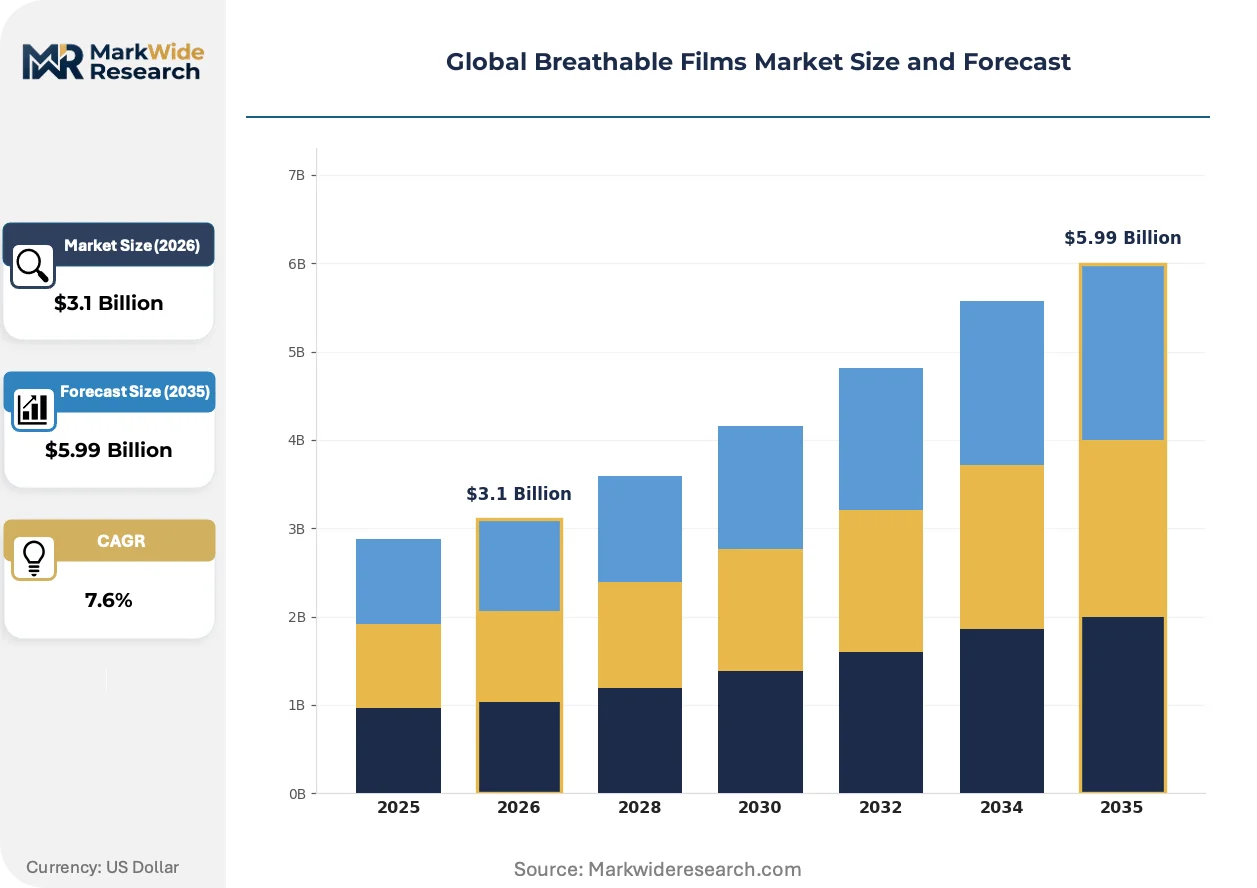
Market Dynamics
REACH compliance in the European Union and China's GB standards are forcing simultaneous reformulation of plasticizer packages across multiple supplier tiers, compressing margins for non-integrated compounders while rewarding vertically integrated polymer producers with captive additive synthesis.
Growth Catalysts
- Hygiene Product Premiumization:Diaper manufacturers in Germany and the United States are expanding procurement of breathable backsheet films for premium product lines, creating sustained volume anchors for microporous polyethylene suppliers.
- REACH Migration Limits:Tightening EU restrictions on plasticizer migration are accelerating substitution toward compliant polymer grades, advantaging producers with pre-certified material libraries.
- Medical Textile Expansion:Surgical drape and wound care laminate producers are specifying high-performance polyurethane membranes, displacing conventional nonwoven barriers in acute care settings.
Market Restraints
- Ethylene Feedstock Volatility:Polyethylene resin costs fluctuate with naphtha and natural gas liquid pricing, compressing margin visibility for extrusion-focused film converters without backward integration into monomer supply.
- PTFE Supply Concentration:Expanded polytetrafluoroethylene production clusters in the United States and Japan, creating geographic concentration risk for medical device manufacturers requiring biocompatible barriers.
- EVOH Moisture Sensitivity:Ethylene vinyl alcohol films suffer performance degradation in high-humidity environments, limiting deployment in tropical construction membrane applications regardless of oxygen barrier superiority.
Strategic Opportunities
- Indian Medical Device Localization:CDSCO regulatory harmonization with ISO 13485 is enabling domestic sterile barrier production, opening import substitution potential for breathable film laminators serving hospital chains in Maharashtra and Karnataka.
- Agricultural Covering Specifications:RKW Group's specialized microporous structures for greenhouse climate control are establishing technical reference points that competitors can target in Mediterranean and Middle Eastern protected cultivation markets.
- China Dual Carbon Alignment:MEE enforcement of carbon intensity benchmarks is creating preference for thinner-gauge films with equivalent vapor transmission, favoring downgauging technology investments.
Industry Challenges
- ISO 10993 Testing Timelines:FDA biocompatibility requirements for medical device films extend certification cycles to 18-24 months, delaying revenue recognition for new product formulations.
- Extrusion Equipment Lead Times:Cast film and biaxial stretching lines require 14-18 month delivery schedules from European and Japanese machinery suppliers, constraining capacity expansion timing.
- Lamination Adhesive Compatibility:Solvent-free polyurethane adhesives for hygiene product assembly exhibit variable bond strength with microporous structures, forcing iterative qualification protocols with diaper OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Breathable Films Market |
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.99 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Microporous Polyethylene, Expanded Polytetrafluoroethylene, Polyurethane, Coated Nonwoven, Ethylene Vinyl Alcohol, Others Application: Medical Textiles, Agriculture Coverings, Hygiene Products, Construction Membranes, Protective Apparel, Packaging Solutions Product Form: Rolls, Sheets, Laminates, Films, Coatings, Panels End User Industry: Textile Manufacturers, Farming Enterprises, Medical Equipment Makers, Building Contractors, Personal Care Brands, Food Processors |
| Companies Covered | Covestro, Kimberly-Clark, Arkema, Imerys, Schweitzer-Mauduit International, Berry Global, RKW Group, Mitsui Chemicals, Nitto Denko Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Breathable Films Market Shifts & Advancements
Phase-inversion manufacturing is consolidating process control advantages over conventional stretching methods, while regulatory substance restrictions and buyer procurement centralization are simultaneously reshaping competitive positioning across material grades.
Monolithic polyurethane film technology is consolidating its position in performance apparel lamination through enhanced moisture vapor transmission rates without micropore-dependent structures. Outdoor and workwear brands in Germany and Japan are specifying these grades for waterproof-breathable jacket constructions. The technology is consolidating premium price tiers previously segmented by PTFE membrane availability, compressing unit economics for ePTFE suppliers in textile applications.
China's GB standards for plasticizer migration in skin-contact products are tightening testing protocols beyond REACH Annex XVII baseline requirements. Domestic film producers must reformulate additive packages or source compliant masterbatches from certified compounders. Hygiene product exporters targeting Chinese domestic consumption are most affected, with several European suppliers accelerating SAMR registration to maintain access.
Buyer concentration among multinational diaper OEMs is compressing supplier qualification cycles and unbundling technical service from material supply contracts. Tier-one hygiene manufacturers in the United States and Germany now require dedicated application engineering support as a condition of volume allocation. This pattern is most visible in North American procurement, where Berry Global and specialized converters compete on response velocity rather than sole specification ownership.
Global Breathable Films Market Segmentation
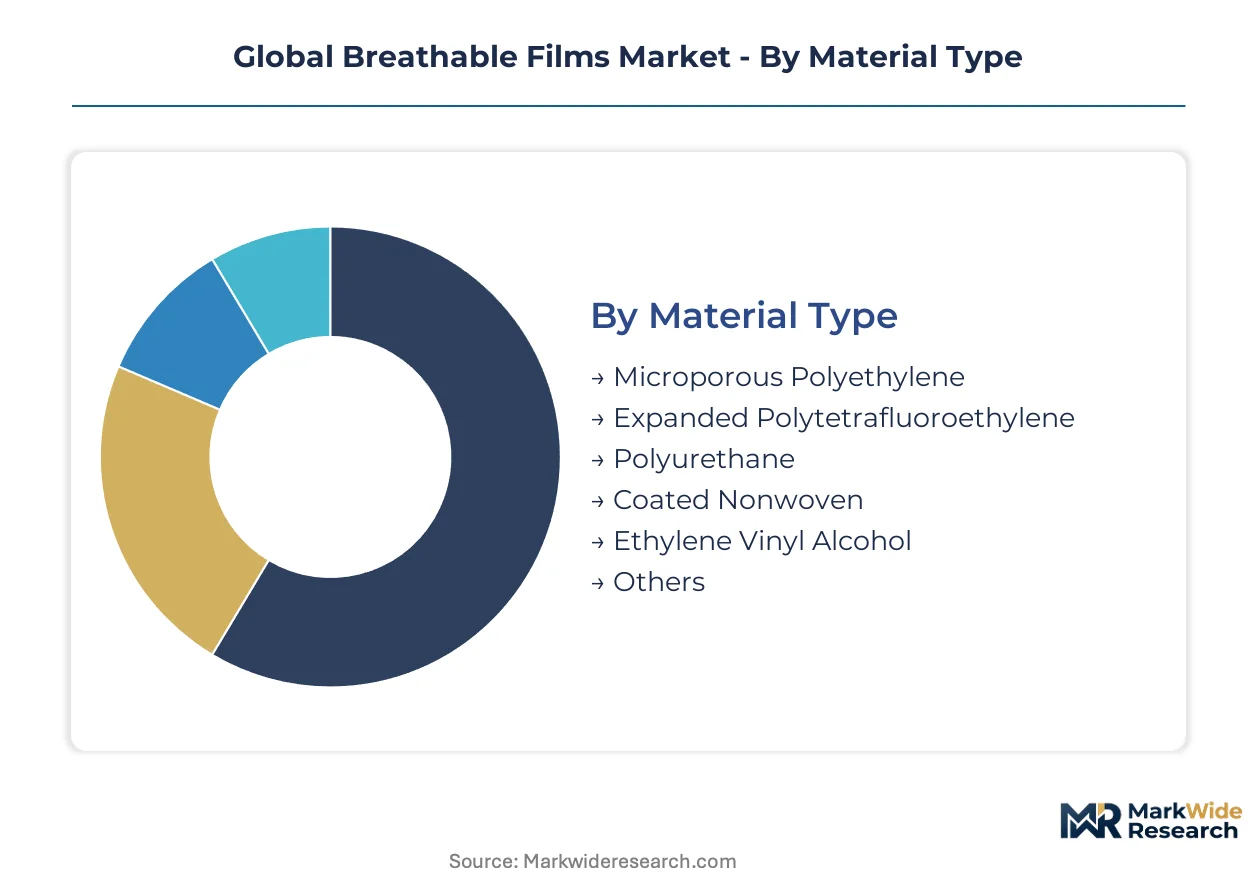
Material specifications and application requirements drive distinct procurement patterns across breathable film segments. Buyers prioritize vapor transmission rates, lamination compatibility, and regulatory compliance when selecting grades for specific end-uses.
Material Type:
Upgrade cycles favor polymers with certified additive packages as REACH and GB standards tighten migration limits.
- Microporous Polyethylene:Manufactured through controlled biaxial stretching of calcium carbonate-filled polyethylene to create interconnected micropores between 0.1 and 10 micrometers. Diaper manufacturers in Germany and the United States specify this grade for premium backsheet laminations due to cost-efficiency and consistent vapor transmission performance.
- Expanded Polytetrafluoroethylene:Produced by mechanical stretching of PTFE paste to form a node-and-fibril structure with exceptional chemical resistance and biocompatibility. Surgical drape producers specify ePTFE for sterile barrier applications where FDA ISO 10993 compliance and extended wear durability justify premium positioning.
- Polyurethane:Monolithic film structures achieve moisture vapor transmission through hydrophilic polymer chemistry rather than physical porosity.
- Coated Nonwoven:Breathable barriers formed by applying microporous coatings to spunbond or meltblown substrates.
- Ethylene Vinyl Alcohol:High oxygen barrier films limited by moisture sensitivity in tropical deployment.
- Others:Includes specialty polyamide and polyester grades for niche industrial applications.
Volume placements concentrate in microporous polyethylene; the faster expansion belongs to polyurethane.
Application:
End-use margins separate medical and hygiene applications from commodity construction and agricultural segments.
- Medical Textiles:Surgical drapes, wound care dressings, and sterile packaging require biocompatible membranes with validated viral barrier performance. German hospitals and Japanese acute care facilities specify polyurethane and ePTFE laminates for extended procedure durations.
- Hygiene Products:Baby diapers and adult incontinence products utilize breathable backsheets to reduce skin moisture accumulation and improve wearer comfort. Procter & Gamble and Essity operations in the United States and Germany anchor procurement volumes for microp polyethylene grades.
- Agriculture Coverings:Greenhouse climate control films balance vapor transmission with thermal retention.
- Construction Membranes:Building envelope barriers manage interstitial condensation in wall and roof assemblies.
- Protective Apparel:Industrial and healthcare garments specify breathable barriers for chemical splash protection.
- Packaging Solutions:Modified atmosphere packaging for fresh produce employs selective gas permeability films.
Revenue concentration sits with medical textiles; hygiene products deliver the steepest volume expansion trajectory.
Product Form:
Converter capabilities and OEM assembly requirements determine form factor selection across supply tiers.
- Rolls:Continuous web format enables high-speed lamination and automated diaper assembly lines. Hygiene product manufacturers in Germany and the United States specify master rolls exceeding two-meter widths to minimize splice frequency.
- Laminates:Pre-combined breathable film and nonwoven substrates reduce downstream processing steps for medical textile converters.
- Sheets:Cut-to-size formats for manual assembly operations and specialty equipment.
- Films:Unconverted single-layer supply for captive lamination operations.
- Coatings:Liquid-applied breathable barriers for textile finishing operations.
- Panels:Rigid composite structures for architectural and equipment applications.
Procurement weight falls on rolls; laminates are gaining share fastest among medical device suppliers.
End User Industry:
Customer technical sophistication and qualification protocols segment the buyer base across compliance tiers.
- Medical Equipment Makers:Sterile barrier manufacturers require ISO 13485-certified film suppliers with validated change control processes. German surgical pack producers and Japanese device manufacturers impose 18-24 month qualification timelines.
- Personal Care Brands:Diaper and feminine hygiene manufacturers prioritize scale security and formulation stability. Kimberly-Clark and Unicharm operations specify annual volume commitments with penalty clauses for supply interruption.
- Textile Manufacturers:Performance apparel and workwear producers specify breathable laminates for waterproof-breathable constructions.
- Farming Enterprises:Protected cultivation operators purchase climate control films through agricultural supply distributors.
- Building Contractors:Construction membrane procurement flows through building material wholesalers with regional stocking requirements.
- Food Processors:Modified atmosphere packaging users specify gas transmission rates for specific produce categories.
Contract value concentrates with medical equipment makers; personal care brands drive the highest shipment frequencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial parks in Leverkusen and Shanghai's chemical zones concentrate film extrusion capacity for hygiene and medical textile supply chains. Tax incentives for advanced materials manufacturing in Germany and bonded logistics arrangements in China's free-trade zones accelerate facility co-location near polymer feedstock sources.
United States
Diaper OEMs in Wisconsin and Ohio expand backsheet film procurement for premium product lines. FDA biocompatibility requirements under ISO 10993 extend qualification timelines for medical device film suppliers. Berry Global operates multiple extrusion facilities serving personal care brands with microporous polyethylene grades.
Germany
REACH Annex XVII restrictions on plasticizer migration compel reformulation of additive packages for skin-contact applications. Covestro leverages polyurethane chemistry expertise from its Leverkusen headquarters to supply surgical drape manufacturers. RKW Group maintains specialized extrusion lines in central Germany for agricultural covering films.
China
GB standards for plasticizer migration in hygiene products exceed REACH baseline requirements, forcing masterbatch sourcing changes. SAMR registration requirements block non-compliant European suppliers from domestic consumption channels. Yangtze River Delta film converters supply both export-oriented diaper OEMs and domestic medical textile producers.
Japan
METI-administered JIS standards for textile-functional film integration shape export specifications for Asian manufacturers. PMDA oversight of medical device materials extends certification cycles comparable to FDA timelines. Osaka-based laminate producers specify high-performance membranes for acute care surgical packs.
India
CDSCO harmonization with ISO 13485 enables domestic sterile barrier production for hospital chains in Maharashtra and Karnataka. PLI scheme incentives for medical device manufacturing attract film laminators to establish local converting operations. Domestic diaper brands in Gujarat accelerate procurement of breathable backsheet materials as local supply scales.
Global Breathable Films Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated polymer producers commanding medical-grade supply and merchant extruders serving commodity hygiene applications. The vendor base concentrates around three strategic archetypes: captive resin producers with additive synthesis capabilities, specialized converters with lamination expertise, and diversified materials conglomerates with cross-sector film portfolios. Capacity expansion and backward integration into monomer supply represent the dominant competitive moves, as feedstock cost visibility separates margin leaders from price-takers.
Within the integrated producer tier, Covestro exemplifies the polymer chemistry specialist archetype through its Leverkusen-centered operations, while Berry Global occupies a position as the scale-driven diversified supplier with multi-continent manufacturing footprints. RKW Group represents the specialized extrusion converter focused on tailored microporous structures for agricultural and protective apparel segments.
| Leading Market Players |
|---|
| Covestro |
| Kimberly-Clark |
| Arkema |
| Imerys |
| Schweitzer-Mauduit International |
| Berry Global |
| RKW Group |
| Mitsui Chemicals |
| Nitto Denko Corporation |
| Others |
Supply & Pricing Matrix
China's dual carbon intensity benchmarks gate qualified supply for premium-tier breathable film access, compressing margins for extrusion converters without MEE-compliant thinner-gauge technology while rewarding producers with certified downgauging capabilities and SAMR-registered additive packages.
Pricing Analysis
Lead-time-driven pricing stratification rewards expedited delivery with premium positioning while spot inventory commands discounts in hygiene-grade microporous polyethylene. Three-tier pricing structure across premium, standard, and economy levels separates ISO 10993-certified medical membranes from REACH-compliant hygiene grades and commodity construction films. Price differentiation hinges on certification tier and volume scale, with diaper OEMs extracting annual commitment discounts. Cost compression in standard-grade polyethylene is intensifying because ethylene feedstock volatility erodes margin visibility for non-integrated compounders. Personal care brands exhibit highest price sensitivity; surgical drape manufacturers prioritize biocompatibility validation over unit cost.
Supply Chain Analysis
Workforce availability constraints in Germany's Leverkusen chemical corridor and China's Yangtze River Delta industrial zones are tightening extrusion technician recruitment for cast film and biaxial stretching operations. Supply concentrates in Germany, China, and the United States, with Covestro and Berry Global anchoring polyurethane and polyethylene capacity respectively. Raw material dependencies draw from naphtha-derived ethylene, calcium carbonate fillers, and specialty polyurethane prepolymers. Single-source vulnerability clusters around Japanese and American ePTFE production for medical device barriers. Distribution runs through bonded logistics arrangements in China's free-trade zones and regional building material wholesalers serving construction membrane contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Breathable films are entering a technology-transition phase as monolithic polyurethane chemistry displaces microporous polyethylene in performance apparel and acute care applications.
For Market Incumbents: Cement backward integration into monomer supply to defend margin position against ethylene feedstock volatility, while accelerating SAMR registration to preempt European competitors from Chinese domestic hygiene channels. Prioritize captive additive synthesis capabilities to compress reformulation cycles as REACH Annex XVII and GB standards tighten plasticizer migration limits. For New Entrants and Emerging Players: Domestic hospital chains in Maharashtra and Karnataka represent the most penetrable buyer archetype, enabled by CDSCO harmonization with ISO 13485 and PLI scheme incentives for sterile barrier localization. Target agricultural covering specifications in Mediterranean protected cultivation markets where RKW Group's technical reference points have established demand pull. Lead with application engineering support bundled to film supply, mirroring North American diaper OEM procurement requirements. For Investors and Strategic Acquirers: CDSCO notification of domestic sterile barrier production guidelines is the leading indicator that Indian medical device localization is accelerating beyond import substitution into export competitiveness. Frame long-term viability around 5-10 year windows where certified additive libraries and pre-validated change control processes compound competitive moats. Target specialized extrusion converters with lamination expertise and existing ISO 13485 certification. Watch for MEE enforcement actions on carbon intensity benchmarks as the inflection signal for downgauging technology acquisition premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Supply | Covestro's polyurethane chemistry expertise anchors margin visibility against ethylene volatility in Leverkusen. |
| Regulatory Registration Acceleration | SAMR compliance for GB plasticizer standards blocks non-certified European suppliers from Chinese domestic channels. |
| Application Engineering Bundling | Tier-one diaper OEMs in Wisconsin and Ohio now mandate dedicated technical support as condition of volume allocation. |
| Downgauging Technology Investment | Thinner-gauge films with equivalent vapor transmission align with China's dual carbon intensity benchmarks. |
| Domestic Sterile Barrier Localization | CDSCO harmonization enables import substitution for hospital chains in Maharashtra and Karnataka. |
Research Methodology
Document review covered customs and trade data, SEC 10-K filings, and ECHA REACH registration databases, complemented by interviews with extrusion plant managers, hygiene product procurement leads, medical device regulatory affairs directors, and distribution channel partners across Germany, China, and the United States. Primary fieldwork with surgical drape manufacturers and diaper OEMs validated secondary assumptions on qualification timelines and volume commitment structures. Bottom-up capacity modeling triangulated against top-down demand segmentation across material grades and application clusters.
Segmented outputs across material type, application, product form, and end-user industry were generated through the analytical framework, with CAGRs derived from elasticity-adjusted demand curves and substitution rate assumptions for polyurethane versus microporous polyethylene. Industry-specific forecast inputs incorporated REACH Annex XVII reformulation timelines, CDSCO regulatory harmonization progress, and MEE carbon intensity benchmark enforcement patterns throughout the projection horizon.
Revisions become necessary when REACH substance restriction expansions, CDSCO notification delays, or ethylene feedstock price shocks materialize beyond modeled ranges. Forecasts reflect assumptions on regulatory enforcement consistency and polymer substitution elasticity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Indonesia Flexible Packaging Market
Flexible Packaging
Germany Flexible Plastic Packaging Market
Flexible Packaging
GCC Shrink Sleeves Market
Flexible Packaging
Canada Multilayer Flexible Packaging Market
Flexible Packaging
Asia-Pacific Flexible Plastic Packaging Market
Flexible Packaging
Japan Flexible Plastic Packaging Market
Flexible Packaging
Confectionery Flexible Packaging Market
Flexible Packaging
Thailand Flexible Packaging Market
Flexible Packaging
Global Flexible Plastic Packaging Market
Flexible Packaging
Thermoform Packaging Market
Flexible Packaging
Asia Pacific Single-Use Packaging Market
Flexible Packaging
Flexible Film Market
Flexible Packaging
Kenya Flexible Packaging Market
Flexible Packaging
Africa Flexible Packaging Market
Flexible Packaging
Egypt Flexible Plastic Packaging Market
Flexible Packaging
Flexible Containers Market