
 Flexible Containers Market | 2026-2036
Flexible Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible Containers Market Foresight
ISO 9001 and BRCGS certification cycles is bifurcating the supplier base into qualified tier-one converters and undifferentiated regional players. Amcor plc leverages its global film extrusion footprint to sustain multi-region supply contracts for food-grade laminates. Mondi anchors European demand through integrated kraft paper and flexible packaging operations. Sealed Air competes on automated packaging equipment tie-ins that lock in consumables demand.
Flexible containers are pliable, non-rigid enclosures—typically constructed from polyethylene, polypropylene, or multi-layer laminates ranging from 50 to 250 microns—that protect, transport, and dispense goods without structural sidewalls. Their primary purpose is to minimize material weight, maximize product-to-package ratios, and adapt to irregular fill volumes across liquid, powder, and solid formats. Polyethylene-based pouches occupy the largest volume share due to cost efficiency and heat-seal reliability, though laminates command the deepest margin pools where barrier performance against oxygen and moisture is critical. Stand-up pouch formats are displacing rigid alternatives in personal care and pet care segments because of shelf presence and e-commerce shipping efficiency.
FDA food contact regulations and EU REACH restrictions on per- and polyfluoroalkyl substances are tightening material specifications and accelerating fluorine-free barrier development. EPA guidelines on recycling stream contamination and state-level extended producer responsibility laws in California and New York are reshaping design-for-recyclability requirements. Stakeholders must monitor how rapidly evolving single-use packaging bans and chemical disclosure mandates force reformulation timelines without compromising shelf-life performance.
Market Dynamics
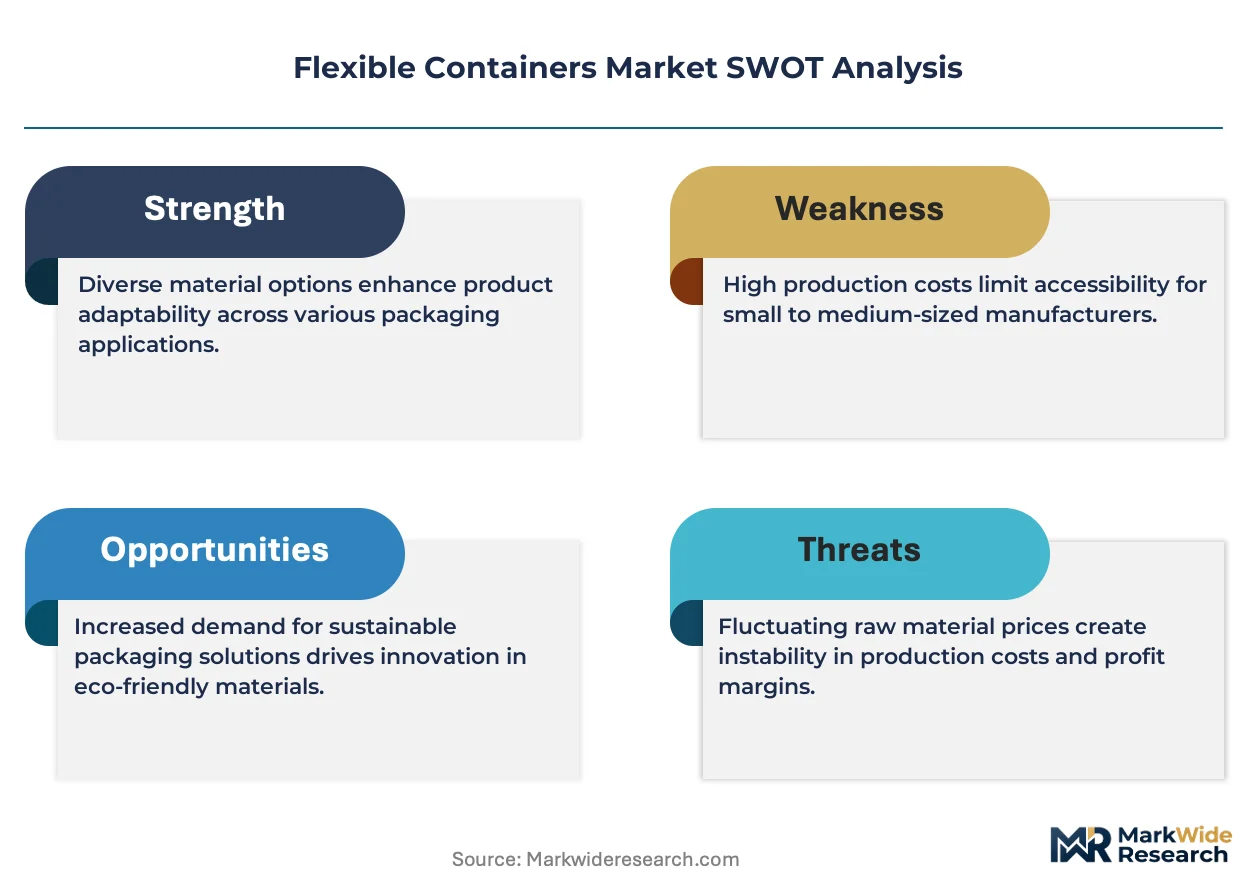
EU REACH restrictions on per- and polyfluoroalkyl substances are forcing material reformulation across the entire flexible packaging value chain, compressing development timelines while shelf-life requirements remain fixed.
Growth Catalysts
- EU Green Deal recyclability mandates:Germany's packaging converter cluster is investing in mono-material extrusion lines to meet 2030 circular economy targets, pulling demand for compatible substrates.
- Stand-up pouch adoption:Pet care brands in the United States are replacing rigid tubs with flexible formats to reduce shipping cube and damage rates in e-commerce fulfillment.
- Fluorine-free barrier coatings:Water-based and bio-based oxygen barrier technologies are reaching commercial scale, enabling compliance without performance trade-offs.
Market Restraints
- Ethylene feedstock volatility:Polyethylene resin prices swing with naphtha and natural gas liquid markets, squeezing converter margins on fixed-price annual contracts.
- Adhesive supply concentration:Solvent-free laminating adhesive production clusters with three European chemical suppliers, creating single-source risk for mid-tier converters.
- Mechanical recycling incompatibility:Multi-layer laminates containing EVOH or metallized films contaminate polyethylene recycling streams, triggering state-level extended producer responsibility penalties in California and New York.
Strategic Opportunities
- India food processing expansion:FSSAI-mandated food safety upgrades are driving first-time flexible packaging adoption among mid-sized spice and snack processors in Gujarat and Maharashtra.
- Digital printing convergence:Inkjet web presses combined with on-demand pouch forming enable micro-batch customization for regional craft brands without plate costs.
- Reusable distribution systems:Loop-style refill platforms in France and the United Kingdom are creating demand for durable flexible containers with standardized dispensing interfaces.
Industry Challenges
- BRCGS certification backlog:Third-party audit capacity constraints are delaying supplier qualification for food-grade laminate contracts, stretching procurement timelines to six months.
- Legacy equipment retrofit costs:Converters with solvent-based laminators face capital-intensive upgrades to water-based or solventless systems to meet EPA maximum achievable control technology standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible Containers Market |
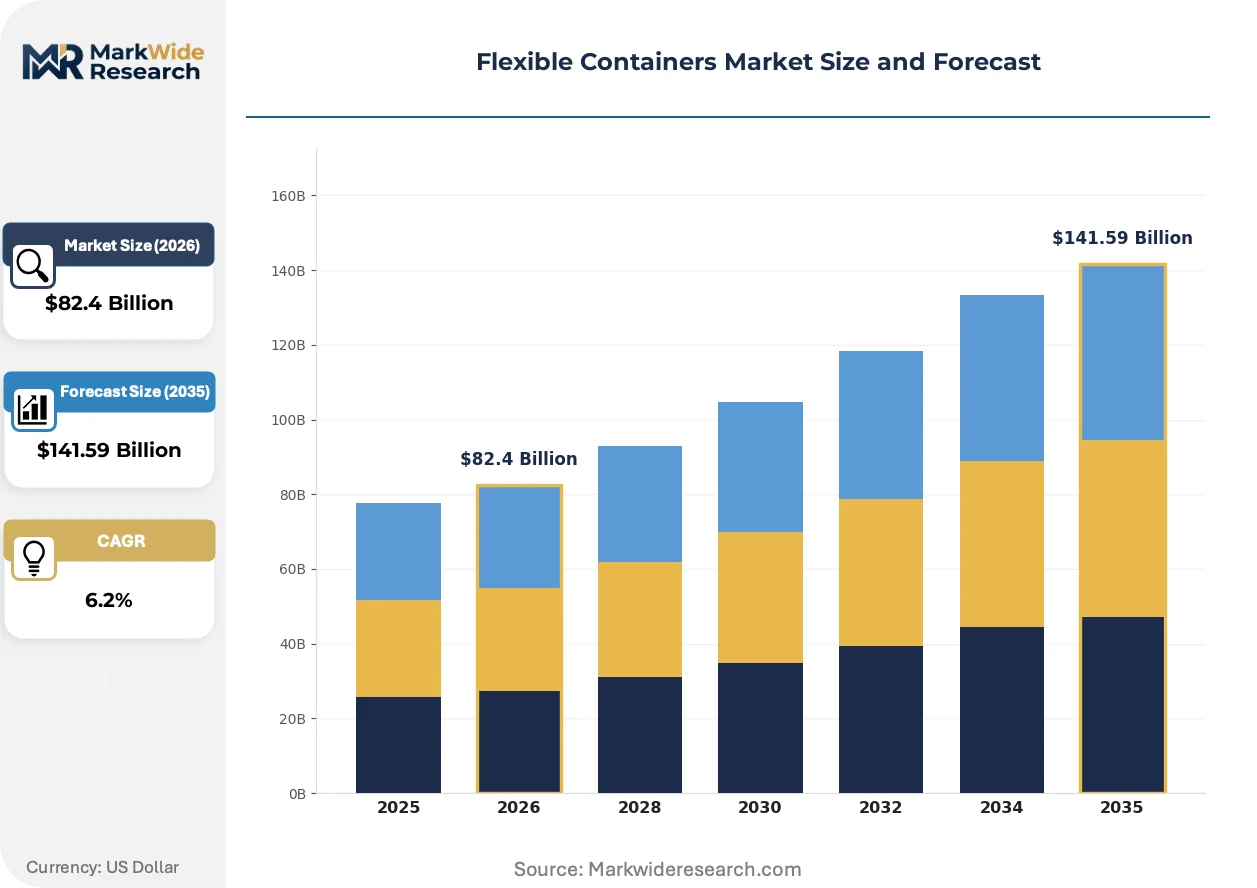
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $141.59 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene, Polypropylene, Laminates, Foil, Paperboard, Polyvinyl Chloride Container Type: Pouches, Bags, Sacks, Bladders, Wraps, Sheets End Use Industry: Food & Beverage, Personal Care, Pharmaceuticals, Chemicals, Agriculture, Pet Care Packaging Style: Stand-up Pouch, Gusseted Bag, Vacuum Bag, Retort Pouch, Roll Stock, Recloseable |
| Companies Covered | Amcor plc, Smurfit Westrock, Mondi, Sealed Air, Constantia Flexibles, Berry Global, Sonoco Products Company, Huhtamaki, TC Transcontinental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible Containers Market Shifts & Advancements
Material science breakthroughs and regulatory chemistry bans are converging to reshape barrier performance specifications, while digital manufacturing tools compress production economics for short-run formats.
Mono-material polyethylene pouches with plasma-enhanced barrier coatings are displacing conventional multi-layer laminates in shelf-stable snack applications. European retail private-label buyers are specifying these formats for 2025 packaging refreshes. The shift collapses converter SKU complexity while satisfying retailer recyclability scorecard requirements.
REACH restrictions on per- and polyfluoroalkyl substances entered full enforcement for food contact materials in 2023. Fluorinated grease barriers in microwave popcorn and fast-food packaging must reformulate within eighteen-month transition windows. German and Dutch brand owners are accelerating qualification of silicone and clay-based alternatives to avoid supply disruption.
Direct-to-brand procurement platforms are aggregating small-batch orders that bypass traditional distributor markups. Specialty coffee roasters in the Pacific Northwest and Nordic craft chocolate makers are sourcing printed pouches through digital-native converters with sub-thousand-unit minimums. The model concentrates margin with agile regional producers while fragmenting volume among national incumbents.
Flexible Containers Market Segmentation
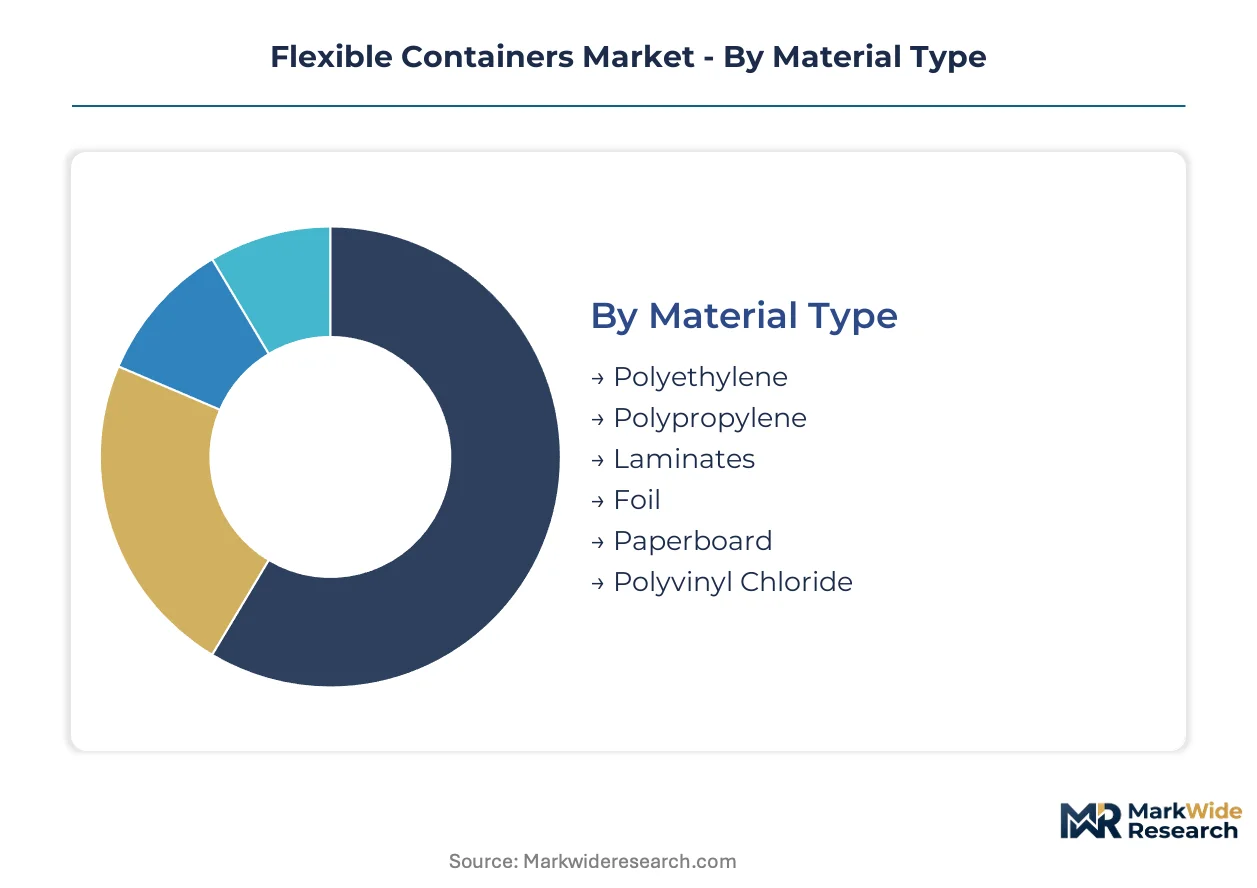
Flexible containers segment across material chemistry, physical format, and functional performance tiers. Each dimension channels distinct procurement patterns and margin structures that shape converter specialization and buyer-seller contracting dynamics.
Material Type:
Channel mix varies sharply by substrate chemistry. Polyethylene and polypropylene flow predominantly through high-volume distributor networks serving food processors, while laminates and foil route through qualified direct contracts with pharmaceutical and personal care brand owners.
- Polyethylene:Linear low-density and high-density grades dominate liquid and dry food packaging. Heat-seal reliability at 130-160°C enables high-speed form-fill-seal operations. Demand concentrates in German retail private-label supply chains where mono-material recyclability scorecards drive specification.
- Laminates:Multi-layer structures combining polyethylene, polyethylene terephthalate, and ethylene vinyl alcohol deliver oxygen transmission rates below 0.5 cc/m²/day. Pharmaceutical blister packs and retortable pet food pouches in the United States and Japan anchor premium pricing tiers.
- Polypropylene:Oriented films provide clarity and stiffness for snack food windows and label facestocks. Clarity requirements from Mexican and Brazilian food exporters sustain regional converter demand.
- Foil:Aluminum layers below 7 microns enable zero oxygen and moisture transmission for coffee, infant formula, and military rations. Defense procurement and specialty coffee roasters in Italy and Vietnam drive order flow.
- Paperboard:Fiber-based substrates with polymer barriers serve frozen food and quick-service restaurant packaging. Swedish and Finnish retail chains specify these for fiber-recyclable claims.
- Polyvinyl Chloride:Shrink films and medical solution bags persist in niche applications despite regulatory pressure. Indian pharmaceutical packaging maintains residual demand for IV fluid containers.
By volume, polyethylene leads. By growth pace, laminates are gaining share fastest as barrier requirements tighten.
Container Type:
Cost tier segmentation separates commodity formats from engineered solutions. Pouches and bags compete on unit economics at scale, while bladders and specialized wraps command engineering margins through performance specifications.
- Pouches:Three- and four-side-seal formats with spouts and fitments displace rigid bottles in condiments, beverages, and personal care. Doyen-style stand-up configurations from French and UK converters serve Loop-style refill platforms.
- Bags:Woven polypropylene and multi-wall paper constructions handle 25-50 kg agricultural and chemical payloads. Brazilian soybean exporters and Moroccan phosphate processors sustain regional manufacturing clusters.
- Sacks:Valve and open-mouth formats for cement, chemicals, and food ingredients. Turkish and Egyptian construction material distributors drive volume through Middle East and North Africa trade corridors.
- Bladders:Collapsible liquid containers for wine, edible oils, and industrial chemicals. Australian wine exporters and Chilean fruit juice processors specify aseptic bag-in-box systems.
- Wraps:Stretch and shrink films for unitization and pallet containment. Mexican automotive parts suppliers and Thai electronics exporters drive cast film demand.
- Sheets:Flat film and barrier webs for thermoforming and lamination. Italian and Spanish fresh produce packaging converters source coextruded sheets for modified atmosphere trays.
By installed capacity, bags dominate. By margin expansion, bladders are climbing the fastest.
End Use Industry:
Application-driven procurement separates regulated from unregulated demand pools. Food and pharmaceutical buyers enforce audit-heavy supplier qualification, while agriculture and chemicals tolerate broader supply bases.
- Food & Beverage:Shelf-stable, refrigerated, and frozen formats across snack, dairy, and ready-meal segments. US pet food e-commerce fulfillment and Indian spice FSSAI compliance upgrades pull concurrent demand waves.
- Pharmaceuticals:Blister lidding, sachets, and IV bags requiring extractables and leachables documentation. German and Swiss contract manufacturers enforce ISO 15378 and USP Class VI certification.
- Personal Care:Stand-up pouches for shampoo, lotion, and cosmetic samples. Korean and Indonesian beauty brands drive digital-printed short-run formats.
- Chemicals:UN-certified flexible intermediate bulk containers and drum liners. Belgian and Dutch industrial chemical distributors specify conductive films for static-sensitive payloads.
- Agriculture:Seed, fertilizer, and crop protection packaging with UV stabilization. Canadian prairie grain handlers and Ukrainian sunflower oil exporters sustain seasonal demand peaks.
- Pet Care:Retort pouches and multi-serve bags replacing metal cans. Premium brands in California and New York specify recyclable mono-material formats to preempt extended producer responsibility penalties.
By revenue concentration, food and beverage leads. By regulatory intensity, pharmaceuticals are expanding most quickly.
Packaging Style:
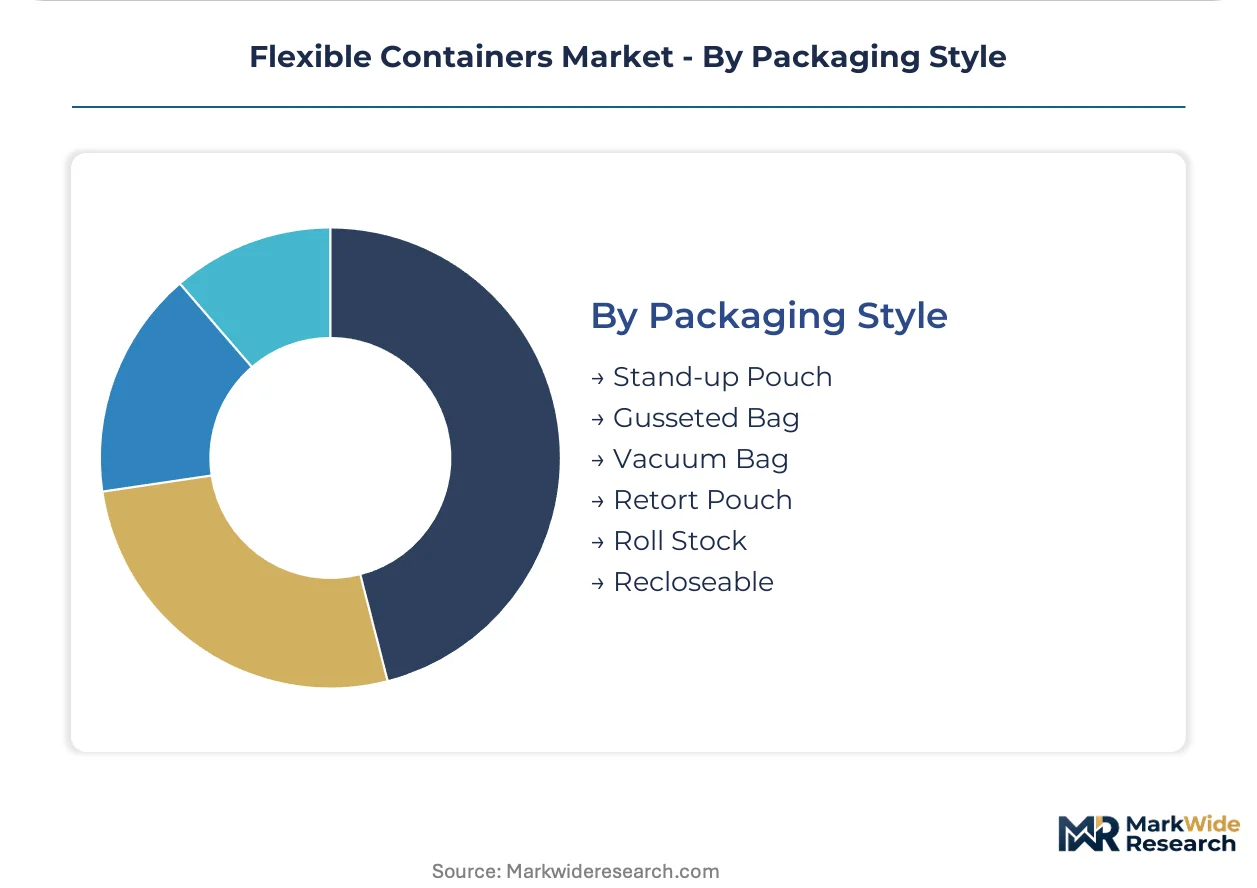
Customer type segmentation separates retail-facing formats from industrial and institutional configurations. Stand-up pouches and recloseable formats serve consumer brands, while roll stock and vacuum bags supply co-manufacturers and food service.
- Stand-up Pouch:Doyen bottom-gusset construction with tear notches and resealable zippers. Snack and pet care brands in the United States and Germany specify these for shelf differentiation and e-commerce cube efficiency.
- Retort Pouch:Four-layer laminates with aluminum oxide or silicon oxide barriers surviving 121°C sterilization. Japanese ready-meal processors and Thai seafood exporters anchor technical requirements.
- Gusseted Bag:Side- or bottom-gusseted formats for coffee, flour, and pet food. Italian espresso roasters and Colombian specialty coffee cooperatives drive premium kraft-paper laminate demand.
- Vacuum Bag:Multi-layer coextrusions for meat, cheese, and seafood preservation. Spanish and Portuguese cured meat processors specify high-barrier nylon-polyethylene structures.
- Roll Stock:Unformed film webs for downstream thermoforming and pouch making. Central European meat packers and North American cheese processors purchase through annual tolling contracts.
- Recloseable:Zipper, slider, and press-to-close mechanisms integrated during converting. Dutch and Danish dairy brands specify child-resistant closures for liquid yogurt formats.
By format proliferation, stand-up pouches lead. By technical complexity, retort pouches show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brand-owner sustainability procurement teams concentrate purchasing power in Germany, the United States, and India, where converting infrastructure clusters most densely around food processing and e-commerce fulfillment hubs.
Germany
Retail private-label buyers specify mono-material polyethylene formats for 2025 packaging refreshes, pulling demand through converter clusters in North Rhine-Westphalia. EU Green Deal recyclability mandates force qualification of plasma-enhanced barrier coatings by 2030. Düsseldorf-based converters anchor European laminate supply for shelf-stable snacks.
United States
Pet care e-commerce brands replace rigid tubs with stand-up pouches to reduce shipping damage rates in California and New York fulfillment centers. EPA guidelines on recycling stream contamination trigger state-level extended producer responsibility penalties. Midwest converting corridors around Chicago supply retort pouches for ready-meal processors.
India
FSSAI-mandated food safety upgrades drive first-time flexible packaging adoption among mid-sized spice processors in Gujarat and Maharashtra. Central government PLI scheme incentives support domestic film extrusion capacity expansion. Ahmedabad and Mumbai converter clusters specialize in printed laminates for export-oriented snack brands.
Japan
Ready-meal processors anchor technical requirements for four-layer retort laminates surviving 121°C sterilization. METI circular economy roadmaps accelerate mono-material qualification timelines. Chubu region converters around Nagoya supply seafood exporters with high-barrier pouch formats.
Brazil
Soybean exporters sustain woven polypropylene manufacturing clusters for 25-50 kg agricultural payloads. ANVISA pharmaceutical packaging regulations tighten extractables documentation for sachet formats. São Paulo state converters serve Mercosur trade corridor demand for valve sacks in construction materials.
Flexible Containers Market Competitive Landscape
Player mix skews toward integrated film extruders and specialized converters, creating a tiered structure where global laminators compete with regional digital-native producers. Consolidation pressure concentrates among European and North American players seeking backward integration into resin compounding. Two strategic archetypes dominate: multi-region supply contract holders leveraging scale, and agile regional specialists capturing micro-batch customization. Competitive moves center on automated packaging equipment tie-ins and fluorine-free barrier technology licensing.
Among integrated packaging groups, Amcor plc exemplifies the multi-region laminate supplier archetype through its global film extrusion footprint. Mondi occupies a position within the European kraft paper and flexible packaging integration tier. Sealed Air sits within the equipment-consumables bundling segment, representing automated system providers that lock in recurring materials demand.
| Leading Market Players |
|---|
| Amcor plc |
| Smurfit Westrock |
| Mondi |
| Sealed Air |
| Constantia Flexibles |
| Berry Global |
| Sonoco Products Company |
| Huhtamaki |
| TC Transcontinental |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day resin inventory cycles in German converter warehouses concentrate pricing power with integrated extruders holding captive polyethylene supply, while spot-buying mid-tier players absorb ethylene feedstock volatility through compressed margins.
Pricing Analysis
Annual fixed-price contracts indexed to ICIS ethylene and naphtha benchmarks dominate converter-brand owner agreements, with premium-mid-economy pricing differentiation separating BRCGS-certified tier-one laminators from undifferentiated regional bag producers. Price differentiation hinges on barrier performance tier and ISO 15378 pharmaceutical certification status. Cost compression in commodity polyethylene pouches is intensifying because fixed-price contracts expose converters to resin spikes. Private-label retail buyers exhibit highest price sensitivity; pharmaceutical contract manufacturers show least.
Supply Chain Analysis
Solvent-free laminating adhesive production clusters with three European chemical suppliers in Germany, Belgium and the Netherlands, creating single-source vulnerability for mid-tier converters sourcing PUR and PUD chemistries. Raw material flows draw from Saudi ethylene crackers, US Gulf Coast polyethylene exports, and Chinese BOPET film capacity. Tariff exposure on Chinese substrate imports is reshaping procurement geography. Distribution runs through high-volume distributor networks for commodity grades and qualified direct contracts for barrier laminates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flexible containers sit in early-cycle expansion as FSSAI-mandated food safety upgrades in India drive first-time packaging adoption among mid-sized processors previously using bulk formats.
For Market Incumbents: Shield market position by accelerating fluorine-free barrier coating R&D to preempt REACH enforcement gaps, and secure backward integration into mono-material extrusion capacity in North Rhine-Westphalia to capture EU Green Deal recyclability mandates before regional competitors qualify. For New Entrants and Emerging Players: BRCGS certification fast-tracks unlock food-grade laminate contracts stalled by six-month audit backlogs, opening white-space in Indian spice processing and Nordic craft chocolate micro-batches. Target digital-native converters with sub-thousand-unit minimums as the most penetrable entry vector. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across plasma-enhanced barrier coating equipment, favoring asset-light licensing models over capex-heavy manufacturing. Long-term viability through the next decade rests on acquiring regional digital-printing specialists with installed inkjet web capacity. Watch mono-material qualification timelines at German retail private-label buyers as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Barrier Technology Licensing | REACH compliance without reformulation delays captures German retail procurement. |
| Mono-Material Extrusion Capacity Expansion | EU Green Deal recyclability mandates pull demand through North Rhine-Westphalia clusters. |
| Digital Printing Web Press Integration | On-demand pouch forming enables micro-batch customization for Pacific Northwest coffee roasters. |
| Automated Packaging Equipment Tie-Ins | Consumables lock-in secures recurring laminate demand from e-commerce pet care brands. |
| India Converter Cluster Partnership | FSSAI compliance upgrades drive first-time flexible packaging adoption in Gujarat spice processing. |
Research Methodology
Desk research of trade association filings, customs export records, and regulatory enforcement databases preceded structured interviews with flexible packaging procurement managers, food safety compliance officers at FSSAI-regulated processors, converting plant engineers, and laminating adhesive technical directors. Primary fieldwork with converter operations heads and brand-owner sustainability teams combined with secondary validation against EU ECHA restriction timelines and EPA recycling contamination guidelines. Bottom-up capacity tallies and top-down demand modeling triangulated volume estimates.
Variance decomposition across material chemistry, physical format, and end-use industry dimensions structured the analytical framework throughout the forecast period. CAGRs derived from segment-level growth rate reconciliation against macroeconomic drivers. Modeled inputs incorporated ethylene feedstock price elasticity, BRCGS certification penetration curves, and digital printing adoption rates in craft food segments.
Decision-makers should treat outputs as directional under stable REACH enforcement and resin supply continuity assumptions; material deviation would warrant model refresh. Forecasts reflect documented base-case assumptions. Revision becomes warranted when EU mono-material recyclability timelines accelerate or China BOPET export duties cross threshold levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Global Flexible Packaging Market
Flexible Packaging
Bakery Flexible Packaging Market
Flexible Packaging
Hygiene Breathable Films Market
Flexible Packaging
Egypt Flexible Plastic Packaging Market
Flexible Packaging
Saudi Arabia Flexible Packaging Market
Flexible Packaging
Thermoform Packaging Market
Flexible Packaging
North America Flexible Packaging Market
Flexible Packaging
Kenya Flexible Packaging Market
Flexible Packaging
Latin America Flexible Packaging Market
Flexible Packaging
Litho Laminated Packaging Market
Flexible Packaging
North America Flexible Plastic Packaging Market
Flexible Packaging
Europe Flexible Packaging Market
Flexible Packaging
Flex Pack Coatings Market
Flexible Packaging
Stretch Packaging Market
Flexible Packaging
Africa Flexible Packaging Market
Flexible Packaging
France Flexible Plastic Packaging Market