
 Metalized Flexible Packaging Market | 2026-2036
Metalized Flexible Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Metalized Flexible Packaging Market Intelligence
ISO 9001 quality management certification is redrawing competitive entry barriers for metalized flexible packaging suppliers. Amcor plc leverages its integrated film-to-pouch manufacturing network across multiple continents. Huhtamaki Oyj sustains technology leadership in fiber-based barrier substrates that complement metalized film lines. Mondi Plc anchors European supply through its specialty kraft and extrusion coating assets.
Metalized flexible packaging consists of polymer substrates—typically polyester, BOPP, or nylon—vacuum-coated with aluminum to achieve oxygen and moisture barrier properties below 0.1 g/m²/day, serving primary functions in shelf-life extension and lightweight product protection. Stand-up pouches capture expanding margin pools as brand owners convert from rigid formats in food and beverage applications. Polyester metalized films dominate technical specifications where optical clarity and thermal stability matter most, while BOPP metalized variants compete aggressively on unit cost in mass-market snack packaging.
FDA food-contact notification requirements and EU REACH substance restrictions govern raw material selection and migration testing protocols for metalized layers in direct food applications. ECHA evaluations of aluminum nanoparticle classifications may force reformulation of vacuum deposition chemistries within European supply chains. Stakeholders must monitor evolving extended producer responsibility frameworks and decide between regional compliance investments versus format simplification strategies that reduce regulatory surface area.
Market Dynamics
Stand-up pouch conversion from rigid formats is compressing supply chains and forcing metalized film converters to integrate downstream into pouch fabrication to defend margin pools.
Growth Catalysts
- EU REACH substance restrictions:Migration testing protocols for aluminum nanoparticles are accelerating qualification of next-generation vacuum deposition chemistries among European flexible packaging suppliers.
- Processed food sector expansion:Indian and Chinese domestic brands are scaling regional metalized film capacity to serve shelf-stable snack and ready-meal packaging demand.
- ISO 9001 certification mandates:Quality management requirements are redrawing competitive entry barriers and consolidating supplier relationships among multinational food and beverage manufacturers.
Market Restraints
- Aluminum volatility:Primary aluminum price swings transmit directly into vacuum deposition input costs, squeezing converter margins on fixed-price annual contracts.
- Asian supply concentration:China and India together host over sixty percent of regional metalized BOPP capacity, creating geographic risk exposure for European and North American brand owners.
- Optical clarity limitations:Metalized polyethylene films cannot match polyester thermal stability above 120°C, restricting retort pouch applications.
Strategic Opportunities
- Brazilian regulatory alignment:ANVISA food-contact material harmonization with FDA standards is opening import pathways for North American metalized film suppliers.
- Fiber-based barrier convergence:Metalized film integration with molded fiber trays creates compostable hybrid formats for premium fresh produce segments.
- E-commerce direct fulfillment:Lightweight metalized pouches reduce dimensional weight shipping penalties versus rigid alternatives in Amazon and Alibaba fulfillment networks.
Industry Challenges
- Vacuum deposition technician scarcity:Specialized roll-to-roll metallization operators require 18-24 month training pipelines that regional vocational programs have not scaled.
- Extended producer responsibility compliance:EU packaging waste directives mandate recyclability redesign within tight timelines that outpace current mono-material metalized film development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metalized Flexible Packaging Market |
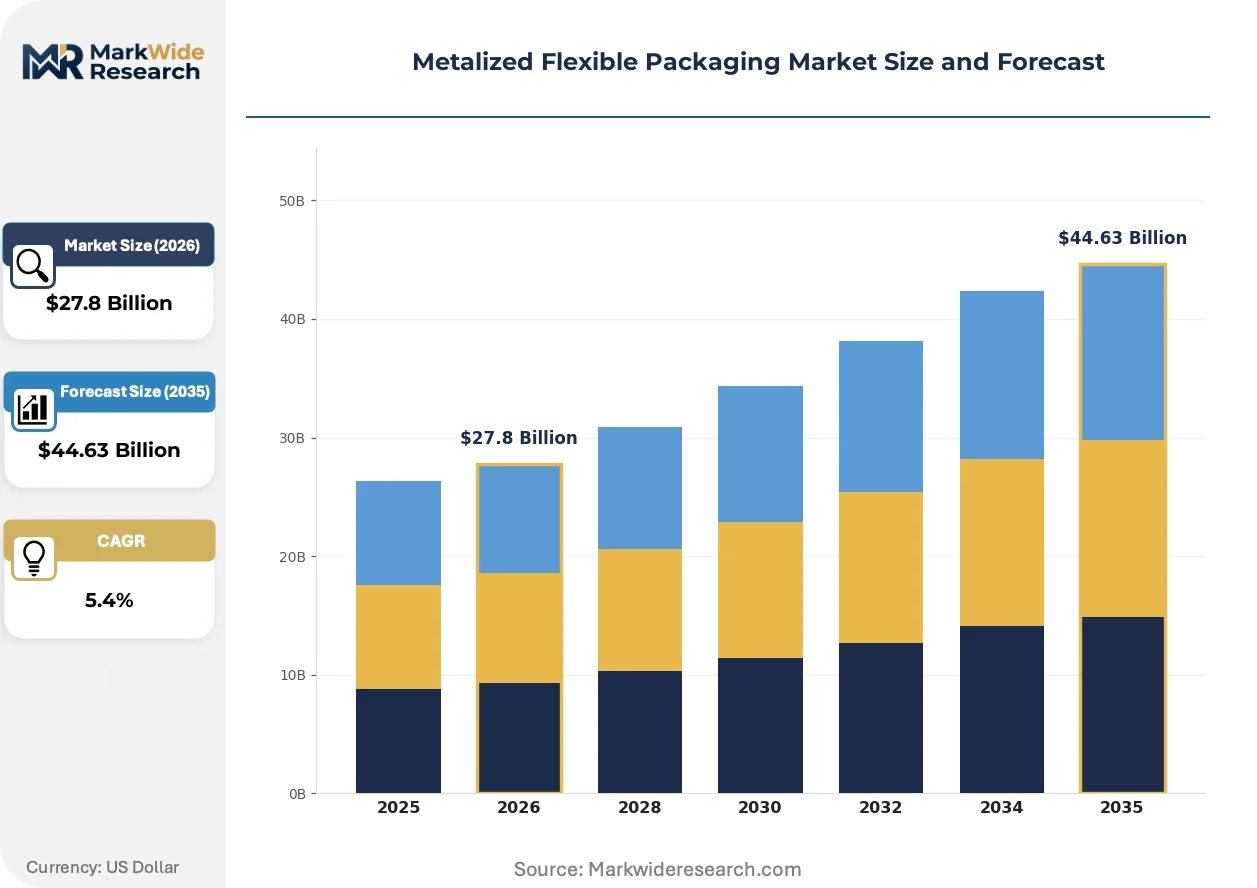
| Market Size in 2026 | $27.8 Billion |
| Market Size in 2035 | $44.63 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Bags, Films, Sachets Application: Food & Beverage, Healthcare, Personal Care, Electronics Material: Polyester, Nylon, Aluminum Foil, BOPP End User: Retail, Wholesale, E-Commerce, Direct Supply |
| Companies Covered | Huhtamaki Oyj, Polyplex Corporation Ltd., Amcor plc, Jindal Poly Films Limited, Uflex Limited, Mondi Plc, Transcontinental Inc., Constantia Flexibles, Sealed Air Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metalized Flexible Packaging Market Strategic Shifts & Innovations
Active barrier layer engineering and deposition chemistry advances are redefining performance thresholds while regulatory migration testing tightens formulation freedom.
Electron beam evaporation systems are achieving sub-10 nanometer aluminum layer uniformity for ultra-high barrier applications. Pharmaceutical blister pack manufacturers in Germany and Switzerland are adopting these systems to replace cold-form foil in moisture-sensitive drug formats. This precision deposition technology is miniaturizing barrier layer thickness while maintaining oxygen transmission rates below 0.05 cc/m²/day.
ECHA evaluations of aluminum nanoparticle classifications under REACH Annex VI are forcing reformulation of vacuum deposition chemistries across European supply chains. The industrial consequence is a 12-18 month qualification timeline extension for new metalized film grades entering direct food contact applications. Snack packaging converters in Italy and Spain are responding by accelerating mono-polyester metalized film development to simplify migration testing portfolios.
Brand owner specification consolidation is compressing approved supplier lists from twelve-plus vendors to three-to-four strategic partners per region. Food and beverage procurement teams in North America are unbundling film supply from pouch conversion services to capture transparency into true metallization costs. This concentration pattern is most visible in California and Texas, where plant-based protein startups are mandating single-source accountability for shelf-life performance claims.
Metalized Flexible Packaging Market Segmentation
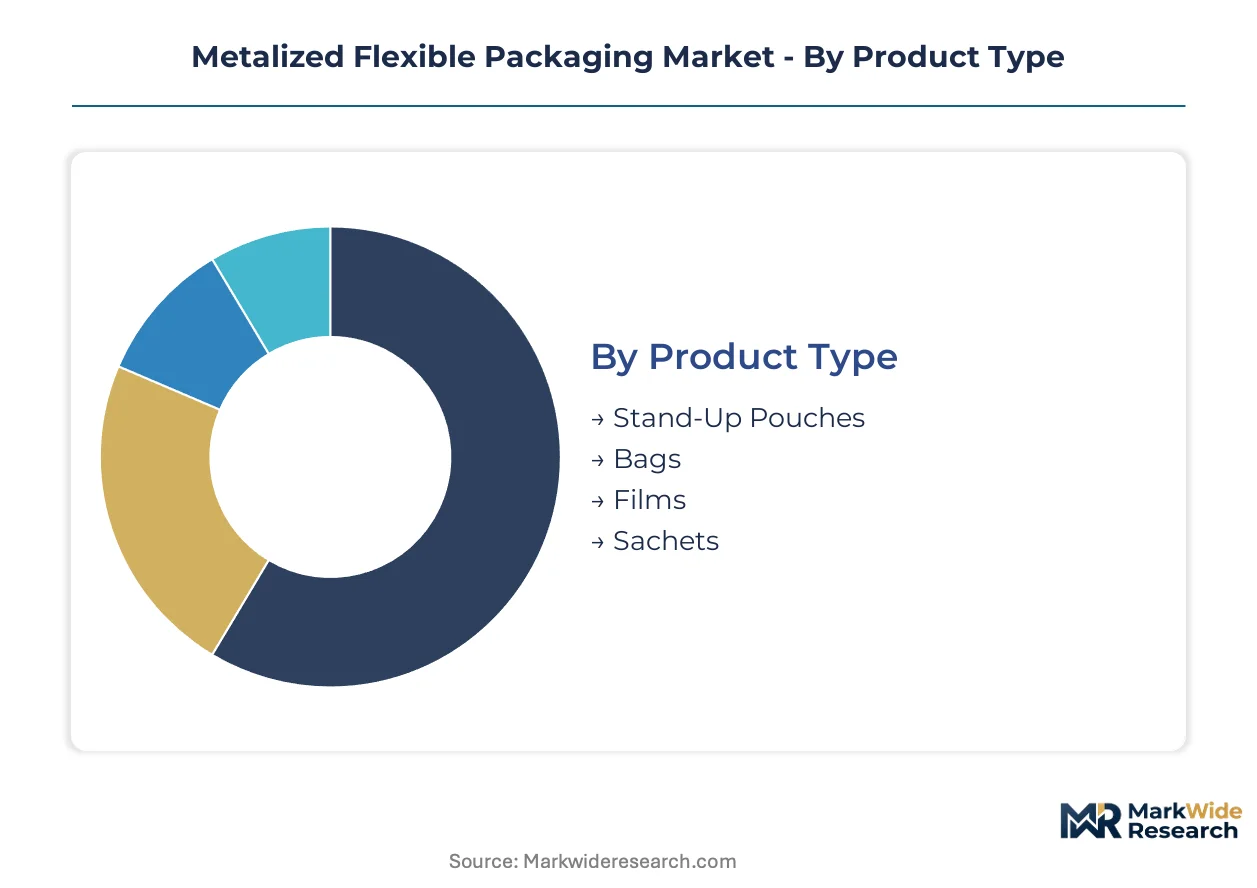
Metalized flexible packaging segmentation reveals how regulatory requirements and barrier specifications fragment supplier capabilities across formats. Understanding these divisions clarifies where vacuum deposition investments concentrate and which material platforms face qualification bottlenecks.
Product Type:
FDA food-contact notification requirements and EU REACH substance restrictions create divergent compliance burdens across format categories, reshaping converter specialization.
- Stand-Up Pouches:Laminated structures with metalized polyester or BOPP layers achieve oxygen transmission rates below 0.1 cc/m²/day while supporting resealable fitments. Demand concentrates in California and Texas plant-based protein segments where shelf-life performance claims require single-source accountability from brand owners.
- Films:Rollstock formats serve downstream pouch converters and lidding applications with precise thickness control from 6 to 23 microns. European snack packaging specialists in Italy and Spain are accelerating mono-polyester grades to simplify ECHA migration testing portfolios under evolving aluminum nanoparticle classifications.
- Bags:Pre-formed three-side-seal and gusseted configurations target bulk dry goods with lower barrier requirements than pharmaceutical or retort applications.
- Sachets:Single-serve portions for condiments and personal care samples prioritize unit cost over thermal stability, favoring BOPP metalized variants.
Stand-up pouches handle the majority of throughput; films are expanding most quickly on share as converters integrate downstream to capture margin pools.
Application:
End-use concentration determines metallization chemistry selection and migration testing intensity, with food contact imposing the strictest qualification protocols.
- Food & Beverage:Shelf-stable snacks, ready meals, and beverage concentrates drive volume. Indian and Chinese domestic brands are scaling regional metalized film capacity to serve processed food expansion.
- Healthcare:Pharmaceutical blister packs and medical device packaging demand sub-10 nanometer aluminum layer uniformity. German and Swiss manufacturers are adopting electron beam evaporation systems to replace cold-form foil in moisture-sensitive drug formats.
- Personal Care:Cosmetic sachets and sample packs prioritize optical clarity and printability over ultra-high barrier performance.
- Electronics:Static-dissipative and moisture-barrier formats protect semiconductors and components during global logistics.
Food and beverage commands the installed base; healthcare is gaining share fastest on precision deposition technology adoption.
Material:
Substrate selection trades thermal stability against unit cost, with regulatory scrutiny intensifying on aluminum layer migration characteristics.
- Polyester:PET films deliver optical clarity and dimensional stability above 120°C for retort and hot-fill applications. Premium fresh produce segments in Switzerland and Germany are integrating metalized polyester with molded fiber trays for compostable hybrid formats.
- BOPP:Biaxially oriented polypropylene dominates mass-market snack packaging through aggressive unit cost positioning. China and India together host over sixty percent of regional metalized BOPP capacity, creating geographic concentration exposure.
- Nylon:PA substrates provide puncture resistance and thermoformability for vacuum meat and cheese packaging.
- Aluminum Foil:Conventional foil laminates retain share in ultra-high barrier pharmaceutical and military specifications where vacuum deposition uniformity cannot match cold-form performance.
BOPP carries the volume base; polyester is climbing the fastest on premium format conversion and regulatory simplification strategies.
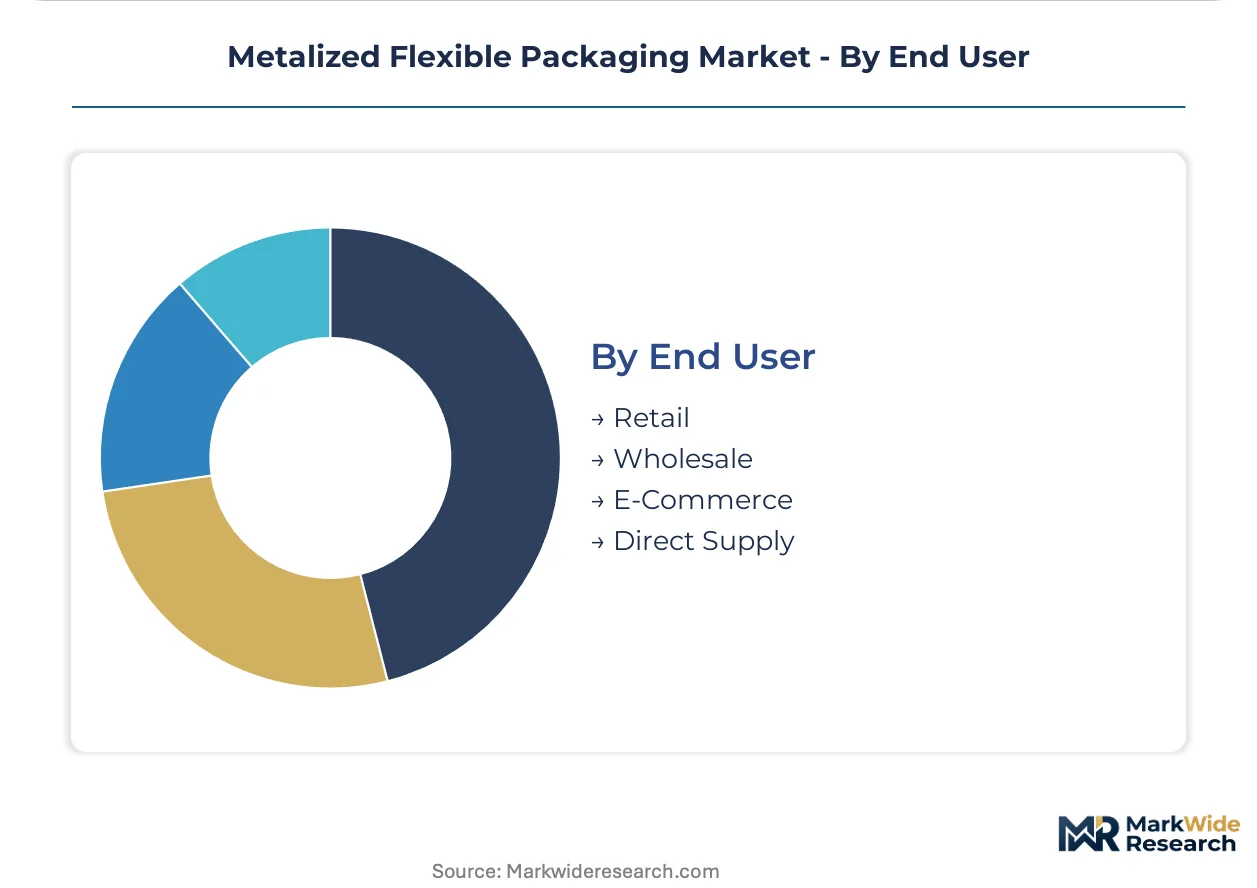
End User:
Channel configuration determines order fragmentation, lead time compression, and the value placed on inventory flexibility versus landed cost.
- Retail:Supermarket and hypermarket private label programs demand consistent color matching and shelf-ready presentation. ISO 9001 certification mandates are consolidating supplier relationships among multinational food and beverage manufacturers.
- E-Commerce:Amazon and Alibaba fulfillment networks favor lightweight metalized pouches that reduce dimensional weight shipping penalties versus rigid alternatives.
- Wholesale:Foodservice and institutional buyers prioritize pallet-level efficiency and extended shelf life for distribution center storage.
- Direct Supply:Brand owner captive packaging operations and co-manufacturing arrangements require technical service proximity and rapid prototyping capability.
Retail anchors procurement volume; e-commerce is the steepest expansion trajectory on fulfillment network optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government packaging waste directives and extended producer responsibility frameworks are redirecting capital toward regional metalized film capacity expansion. India and China dominate new metallization investments while European converters navigate REACH compliance timelines. Brazil and the United States offer alternative growth vectors through regulatory harmonization and processed food sector expansion.
China
Domestic flexible packaging converters in Jiangsu and Zhejiang provinces are scaling metalized BOPP capacity to serve regional processed food brands. The country's dual carbon goals are pressuring vacuum deposition facilities to upgrade energy efficiency or face operational constraints. Yangtze River Delta clusters host over sixty percent of Asia-Pacific metallization rollstock output.
India
FSSAI food-contact material standards are tightening aluminum migration testing protocols for snack packaging converters in Maharashtra and Gujarat. The PLI scheme for specialty chemicals is subsidizing domestic resin production that feeds downstream metallization lines. Mumbai-Pune industrial corridors anchor South Asian metalized film supply for ready-meal and beverage concentrate brands.
Germany
ECHA evaluations of aluminum nanoparticle classifications under REACH Annex VI are forcing 12-18 month qualification extensions for new metalized film grades. Bavarian pharmaceutical blister pack manufacturers are adopting electron beam evaporation systems to replace cold-form foil. Baden-Württemberg converter networks supply precision metallization for moisture-sensitive drug formats.
United States
FDA food-contact notification requirements govern raw material selection for California and Texas plant-based protein startups mandating single-source shelf-life accountability. Amazon fulfillment network optimization is accelerating lightweight metalized pouch adoption to reduce dimensional weight shipping penalties. Midwest flexible packaging converters are integrating downstream into pouch fabrication to defend margin pools.
Brazil
ANVISA food-contact material harmonization with FDA standards is opening import pathways for North American metalized film suppliers. São Paulo-based snack brands are converting from rigid formats to stand-up pouches with metalized barrier layers. Southeastern industrial zones concentrate Latin American flexible packaging demand for shelf-stable coffee and confectionery segments.
Metalized Flexible Packaging Market Key Industry Players
Listed leaders compete with private specialists across capital access and customer concentration dimensions. The vendor base organizes into three tiers: multinational integrated converters with captive film supply, regional metallization specialists serving downstream pouch fabricators, and private-label focused rollstock merchants. Strategic moves center on backward integration into resin compounding and geographic expansion through distribution partnerships rather than greenfield metallization assets.
Within the integrated converter tier, Amcor plc and Mondi Plc exemplify archetypes spanning film-to-pouch manufacturing networks across multiple continents. Huhtamaki Oyj occupies a position representing technology leadership in fiber-based barrier substrates that complement metalized film lines. These three entities anchor competitive positioning through ISO 9001 certification mandates that consolidate supplier relationships among multinational food and beverage manufacturers.
| Leading Market Players |
|---|
| Huhtamaki Oyj |
| Polyplex Corporation Ltd. |
| Amcor plc |
| Jindal Poly Films Limited |
| Uflex Limited |
| Mondi Plc |
| Transcontinental Inc. |
| Constantia Flexibles |
| Sealed Air Corporation |
| Others |
Cost & Logistics Intelligence
ISO 9001 certification gates both supplier qualification and price differentiation simultaneously, as multinational food and beverage manufacturers consolidate approved vendor lists from twelve-plus suppliers to three-to-four strategic partners per region. This quality management mandate compresses margin pools for uncertified converters while enabling certified suppliers to command premium positioning on shelf-life performance accountability.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with ISO 9001-accredited suppliers capturing favorable terms against uncertified competitors. Three-tier pricing structure separates FDA-grade migration-tested films from REACH-compliant European grades from economy BOPP variants. Pricing pressure stems from aluminum price volatility transmitting directly into vacuum deposition input costs on fixed-price annual contracts. Mass-market snack brands exhibit highest price sensitivity, while pharmaceutical blister pack manufacturers prioritize sub-10 nanometer uniformity over unit cost.
Supply Chain Analysis
Inventory cycles stretch 18-24 months for specialized roll-to-roll metallization operators, constraining converter flexibility against brand owner lead-time compression demands. China, India, and Germany anchor global metalized film capacity, with Jiangsu and Zhejiang provinces hosting over sixty percent of Asia-Pacific metallization rollstock output. Raw material dependencies center on primary aluminum ingot, polyester and BOPP resin, and vacuum deposition equipment. Single-source vulnerability concentrates in electron beam evaporation systems supplied by Bavarian and Swiss precision engineering clusters. Distribution runs through converter-integrated pouch fabrication networks and downstream flexible packaging specialists serving retail private-label programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Metalized flexible packaging is approaching a platform-economics inflection as e-commerce fulfillment networks standardize on lightweight pouch formats that interoperate across Amazon and Alibaba logistics systems. This ecosystem convergence rewards suppliers who consolidate film-to-pouch capabilities under single-source accountability frameworks.
For Market Incumbents: Compound technology leadership in fiber-based barrier substrates through integration with molded fiber trays for compostable hybrid formats. Defend margin pools by accelerating mono-polyester metalized film development to simplify ECHA migration testing portfolios against REACH Annex VI reformulation timelines. Prioritize backward integration into resin compounding to offset aluminum price volatility exposure on fixed-price contracts. For New Entrants and Emerging Players: Anchor in Brazilian stand-up pouch conversion as ANVISA harmonization with FDA standards opens import pathways for North American metallization suppliers. Target São Paulo-based snack brands converting from rigid formats with localized technical service proximity. Pursue co-manufacturing arrangements with plant-based protein startups in California and Texas demanding rapid prototyping capability for shelf-life performance claims. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electron beam evaporation precision deposition segments as pharmaceutical blister pack manufacturers replace cold-form foil. Long-term viability favors converters with captive film supply and downstream pouch fabrication integration. Monitor ECHA aluminum nanoparticle classification rulings as the signal for qualification timeline extensions that would compress European supplier margins and trigger consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive supply of polyester and BOPP feedstock insulates converters from commodity price swings. |
| Mono-Material Film Development | Mono-polyester grades simplify EU REACH migration testing portfolios for Italian and Spanish snack converters. |
| Electron Beam Evaporation Adoption | Sub-10 nanometer uniformity enables German and Swiss pharmaceutical manufacturers to displace cold-form foil. |
| E-Commerce Format Optimization | Lightweight metalized pouches reduce dimensional weight penalties in Amazon fulfillment networks. |
| Fiber-Barrier Hybrid Integration | Metalized polyester fusion with molded fiber trays creates compostable formats for Swiss and German premium produce segments. |
Research Approach
Cross-validation between primary interviews with vacuum deposition technicians, procurement leads at multinational food manufacturers, and flexible packaging converters anchors the qualitative findings. Secondary validation draws from FDA food-contact notifications, ECHA REACH Annex VI evaluations, EU packaging waste directive filings, and customs trade data on aluminum and polymer resin flows. Bottom-up capacity assessments at Jiangsu and Zhejiang metallization facilities triangulate against top-down demand estimates from processed food sector expansion patterns.
Sensitivity analysis across aluminum price volatility scenarios and REACH compliance timeline extensions shapes the analytical framework. Segmentation dimensions modeled include product type, application, material substrate, and end-user channel configuration across the projection horizon. CAGRs derive from installed base growth in stand-up pouch conversion, electron beam evaporation adoption rates in pharmaceutical packaging, and regional capacity buildout in India and China. Forecast inputs incorporate FSSAI migration testing protocol tightening and ANVISA regulatory harmonization trajectories.
Decision-makers should treat outputs as directional under base assumptions of sustained processed food sector expansion and stable REACH classification frameworks; material deviation in aluminum nanoparticle rulings or extended producer responsibility timelines would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Latin America Flexible Plastic Packaging Market
Flexible Packaging
Egypt Flexible Packaging Market
Flexible Packaging
Hygiene Breathable Films Market
Flexible Packaging
Middle East and Africa Flexible Plastic Packaging Market
Flexible Packaging
Nigeria Flexible Plastic Packaging Market
Flexible Packaging
Confectionery Flexible Packaging Market
Flexible Packaging
Canada Flexible Packaging Market
Flexible Packaging
Flexible Film Market
Flexible Packaging
Mexico Flexible Packaging Market
Flexible Packaging
Mexico Flexible Plastic Packaging Market
Flexible Packaging
Brazil Flexible Plastic Packaging Market
Flexible Packaging
GCC Flexible Packaging Market
Flexible Packaging
Thermoforming Packaging Market
Flexible Packaging
Kenya Flexible Packaging Market
Flexible Packaging
Flex Pack Coatings Market
Flexible Packaging
Morocco Flexible Plastic Packaging Market