
 Russia Flexible Plastic Packaging Market | 2026-2036
Russia Flexible Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Flexible Plastic Packaging Market Insights
Capital-intensity divergence between integrated polymer producers and downstream converters is redrawing competitive boundaries in Russia's flexible packaging sector. SIBUR leverages its captive polyethylene and polypropylene feedstock to control raw material costs across the value chain. KubRotoPak competes through specialized pouch and bag converting equipment calibrated for mid-volume regional food brands. Zavod Volga Polymer anchors its position in the Volga Federal District with proximity to agricultural processing hubs requiring bulk film supplies.
Russia flexible plastic packaging comprises polymer-based materials—typically polyethylene, polypropylene, or multilayer laminates between 20 and 250 microns—manufactured through blown film extrusion, cast film, or adhesive lamination processes to provide moisture barriers, seal integrity, and printability for consumer and industrial goods. Film and laminates dominate material throughput due to their ubiquity in food wrapping and industrial bundling applications, while pouches capture expanding margin pools as ready-meal and snack brands upgrade from rigid to flexible formats. Polyethylene sustains volume leadership across the material split, though biodegradable films are gaining trial traction among personal care exporters targeting EU retail compliance requirements.
Russia's Federal Service for Surveillance in Consumer Rights Protection and Human Wellbeing (Rospotrebnadzor) enforces sanitary-epidemiological standards for food-contact materials, while Eurasian Economic Union technical regulations mandate labeling and safety certification for packaging placed on the common market. The country's mandatory extended producer responsibility framework, administered by the Russian Environmental Operator, is forcing converters to redesign multilayer structures or fund separate collection infrastructure. Stakeholders must monitor whether EEU harmonization with EU packaging waste directives accelerates before domestic recycling capacity scales, as this timing gap will determine which material technologies receive capital allocation across the forecast horizon.
Market Dynamics
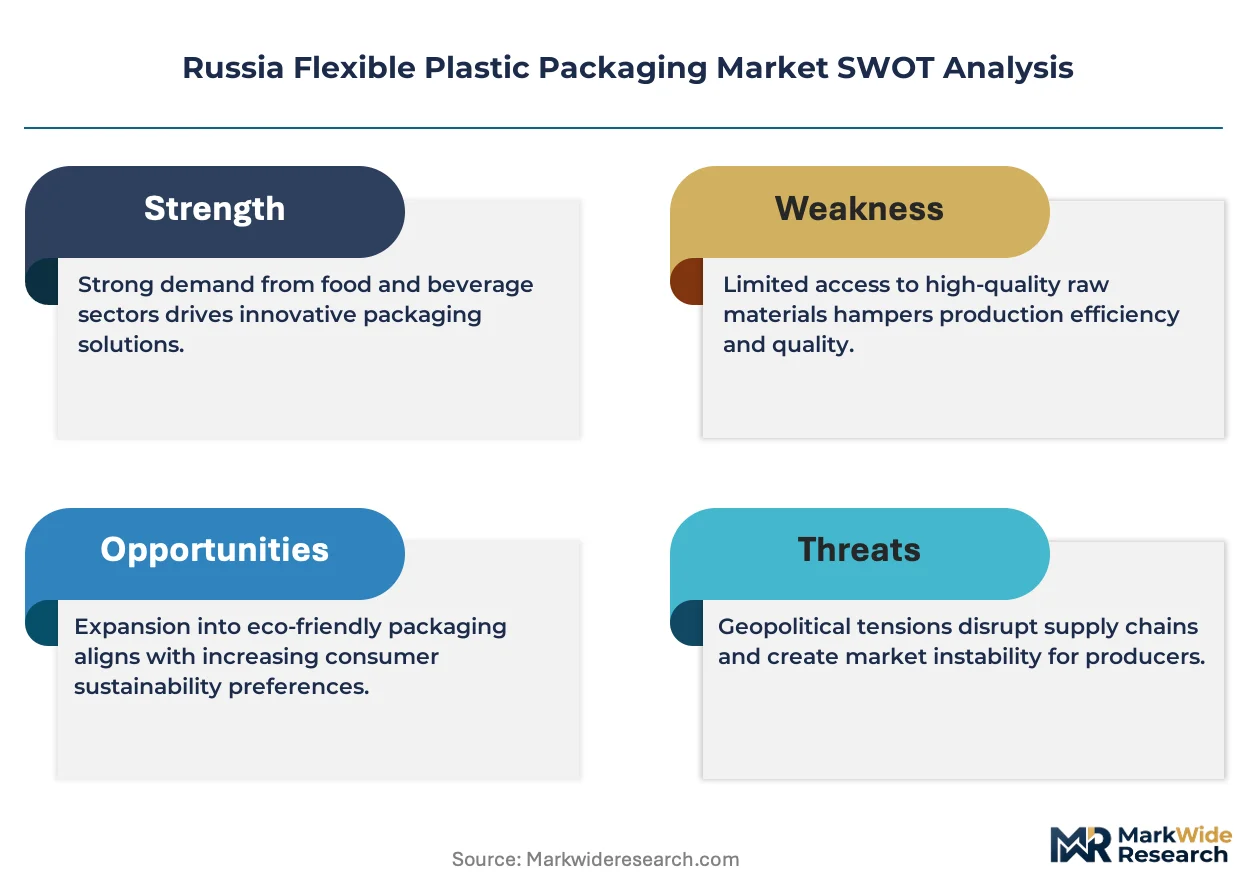
Russia's mandatory extended producer responsibility framework is forcing converters to redesign multilayer film structures or fund separate collection infrastructure, compressing margins for non-integrated players while rewarding captive feedstock holders.
Growth Catalysts
- EPR Compliance Deadlines:The Russian Environmental Operator's phased recycling targets are accelerating investment in mono-material alternatives among flexible packaging converters serving Moscow-based dairy processors.
- Barrier Film Upgrades:Meat and ready-meal brands in St. Petersburg are adopting ethylene vinyl alcohol coextrusions to replace metallized layers, simplifying end-of-life sorting without sacrificing oxygen transmission performance.
- Central District Logistics Density:FMCG producers clustering around the capital region's rail and highway nodes are consolidating procurement volumes, driving converter scale economies in film extrusion and pouch forming.
Market Restraints
- Polyolefin Import Dependency:Sanctions-related disruptions to high-pressure polyethylene supply from European petrochemical complexes have forced Russian converters toward SIBUR's domestic output, constraining formulation flexibility.
- Multilayer Recyclability Gap:Current mechanical recycling infrastructure cannot process adhesive-laminated structures containing polyamide or polyethylene terephthalate layers, limiting design options for premium shelf-life applications.
- Biodegradable Cost Premium:Polylactic acid and starch-based alternatives carry 40-60% raw material cost penalties versus conventional polyethylene, blocking adoption outside EU-exporting personal care segments.
Strategic Opportunities
- Volga Agricultural Processing:Bulk film demand from grain and oilseed processors in Samara and Saratov oblasts remains underserved by specialized barrier solutions, creating white space for regional converter expansion.
- Digital Print Convergence:Integration of flexographic presses with inline quality inspection systems is enabling short-run customization for mid-volume regional food brands previously locked out of premium pouch formats.
- EEU Harmonization Window:Pending alignment between Eurasian Economic Union technical regulations and EU packaging waste directives would unlock export certification pathways for compliant Russian converters.
Industry Challenges
- Polymer Chemist Scarcity:Formulation expertise for high-barrier coextrusions remains concentrated among Soviet-era trained specialists nearing retirement, constraining R&D throughput for next-generation structures.
- Retrofitting Capex Burden:Existing blown film lines require substantial modification to process post-industrial recycled content at required throughput rates, straining balance sheets of mid-tier converters.
- Sanitary-Epidemiological Certification Lag:Rospotrebnadzor approval timelines for new food-contact materials extend 18-24 months, delaying commercialization of innovative barrier coatings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Flexible Plastic Packaging Market |
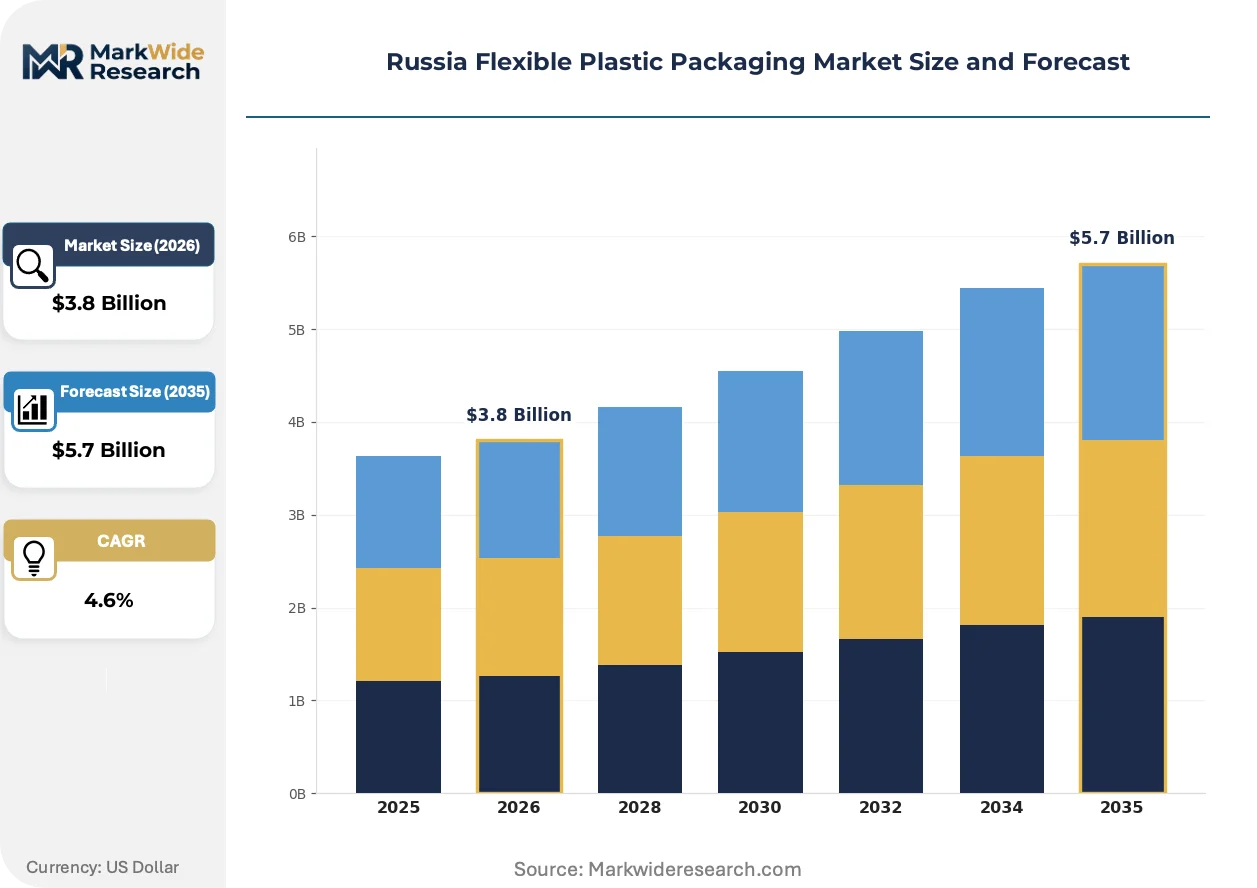
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Pouches, Film, Laminates Material: Polyethylene, Polypropylene, PVC, Biodegradable Films End User: Food, Beverage, Healthcare, Personal Care Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | SIBUR, KubRotoPak, Lambumiz, 2A – Upakovka, Zavod Volga Polymer, RDF Group, PKO-SURA, Protek Group, Mirpack Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Flexible Plastic Packaging Market Trends and Innovations
Active redesign of film layer architectures is compressing the technical advantage historically held by complex multilayer laminates, while regulatory pressure and buyer procurement evolution reshape competitive positioning across material categories.
Mono-material polyethylene structures incorporating metallocene-catalyzed sealant layers are decomposing the incumbent barrier hierarchy in frozen food and dairy applications. Major retail chains in the Central Federal District are specifying these formats for private-label ranges to preempt EPR sorting penalties. The shift is compressing demand for polyamide-containing laminates and redirecting converter capital toward sealant resin inventory.
Eurasian Economic Union technical regulations on food-contact material migration limits are tightening permissible thresholds for heavy metals and primary aromatic amines. This regulatory pressure is forcing ink and adhesive suppliers to reformulate solvent-based systems for waterborne or electron-beam curable alternatives. Dairy processors exporting to EEU member states are most affected, accelerating third-party laboratory certification investments.
Consolidated procurement by retail chains is displacing fragmented distributor networks as the dominant channel for flexible packaging sourcing. X5 Retail Group and Magnit are centralizing specifications and conducting direct converter audits, compressing margins for regional intermediaries. This concentration is most visible in Moscow and St. Petersburg, where logistics infrastructure supports just-in-time delivery requirements.
Russia Flexible Plastic Packaging Market Segmentation
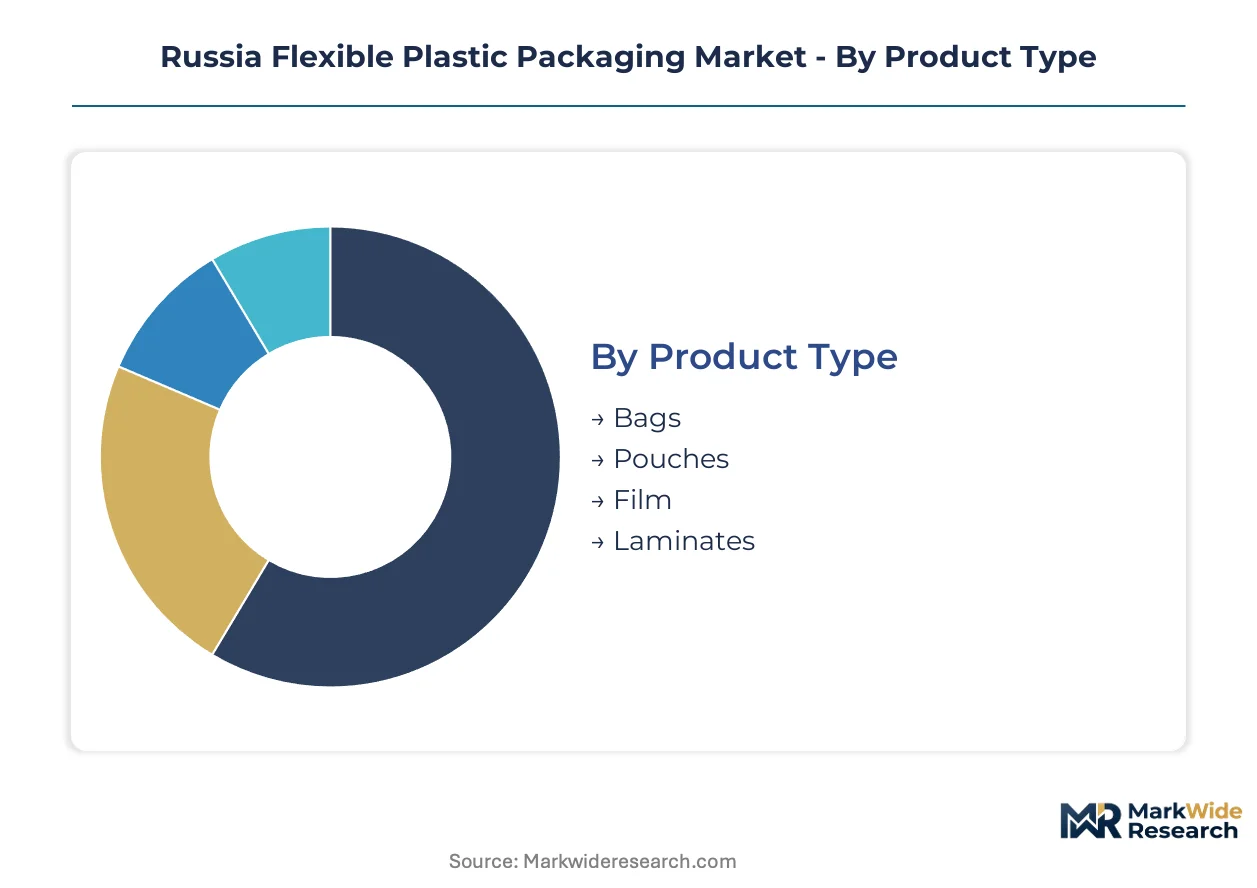
Flexible packaging converters in Russia must align product portfolios with diverging substitution pressures across material categories and end-use applications. The EPR framework and EEU technical regulations are fragmenting demand patterns, rewarding segments that simplify end-of-life sorting while penalizing complex multilayer structures.
Product Type:
Substitution pressure from rigid formats and alternative substrates varies sharply across product categories, with pouch formats facing the most intense competitive dynamics from paper-based and rigid plastic alternatives.
- Film:Blown and cast polyethylene films between 20-250 microns dominate throughput for food wrapping and industrial bundling. Moscow-based dairy processors are consolidating procurement volumes for mono-material polyethylene formats to preempt EPR sorting penalties.
- Laminates:Adhesive-laminated multilayer structures combining polyamide, polyethylene terephthalate, and aluminum layers deliver premium oxygen and moisture barriers for extended shelf-life meat and ready-meal applications. Current mechanical recycling infrastructure cannot process these structures, forcing converters toward redesign or separate collection funding.
- Pouches:Stand-up and flat pouch formats are gaining share in snack and ready-meal segments as brands upgrade from rigid containers.
- Bags:Side-seal and bottom-gusseted bags serve bulk agricultural and industrial applications with lower barrier requirements.
Film retains volume leadership; pouches hold the steepest expansion curve as ready-meal brands accelerate format conversion.
Material:
Cost tier stratification separates commodity polyolefins from specialty and biodegradable alternatives, with formulation flexibility constrained by sanctions-related import disruptions.
- Polyethylene:Low-density and linear low-density polyethylene sustain volume leadership across blown film extrusion applications. SIBUR's captive domestic supply anchors cost positions for Central Federal District converters serving retail chain private-label programs.
- Polypropylene:Biaxially oriented and cast polypropylene films deliver higher temperature resistance and clarity for retort and microwaveable applications. Demand concentrates among St. Petersburg processors exporting to EEU member states.
- PVC:Flexible PVC maintains niche positions in medical and pharmaceutical blister packaging despite regulatory pressure on plasticizer migration limits.
- Biodegradable Films:Polylactic acid and starch-based alternatives carry 40-60% raw material cost premiums versus conventional polyethylene, limiting adoption to personal care exporters targeting EU retail compliance requirements.
Polyethylene dominates absolute tonnage; biodegradable films are expanding most quickly from a minimal base.
End User:
Application-specific barrier requirements and certification intensity create diverging margin profiles across end-use segments.
- Food:Dairy, meat, and bakery applications drive the majority of flexible packaging demand, with multilayer barrier films specified for extended shelf-life products in Moscow and St. Petersburg retail chains.
- Beverage:Aseptic and hot-fill pouch formats are displacing rigid bottles in juice and dairy beverage segments.
- Healthcare:Sterile barrier systems for medical devices face Rospotrebnadzor approval timelines extending 18-24 months, delaying commercialization of innovative structures.
- Personal Care:Sachets and flexible tubes for cosmetics and hygiene products represent the primary outlet for biodegradable film trials among EU-exporting brands.
Food commands absolute volume; personal care offers the most accessible pathway for sustainable material premiums.
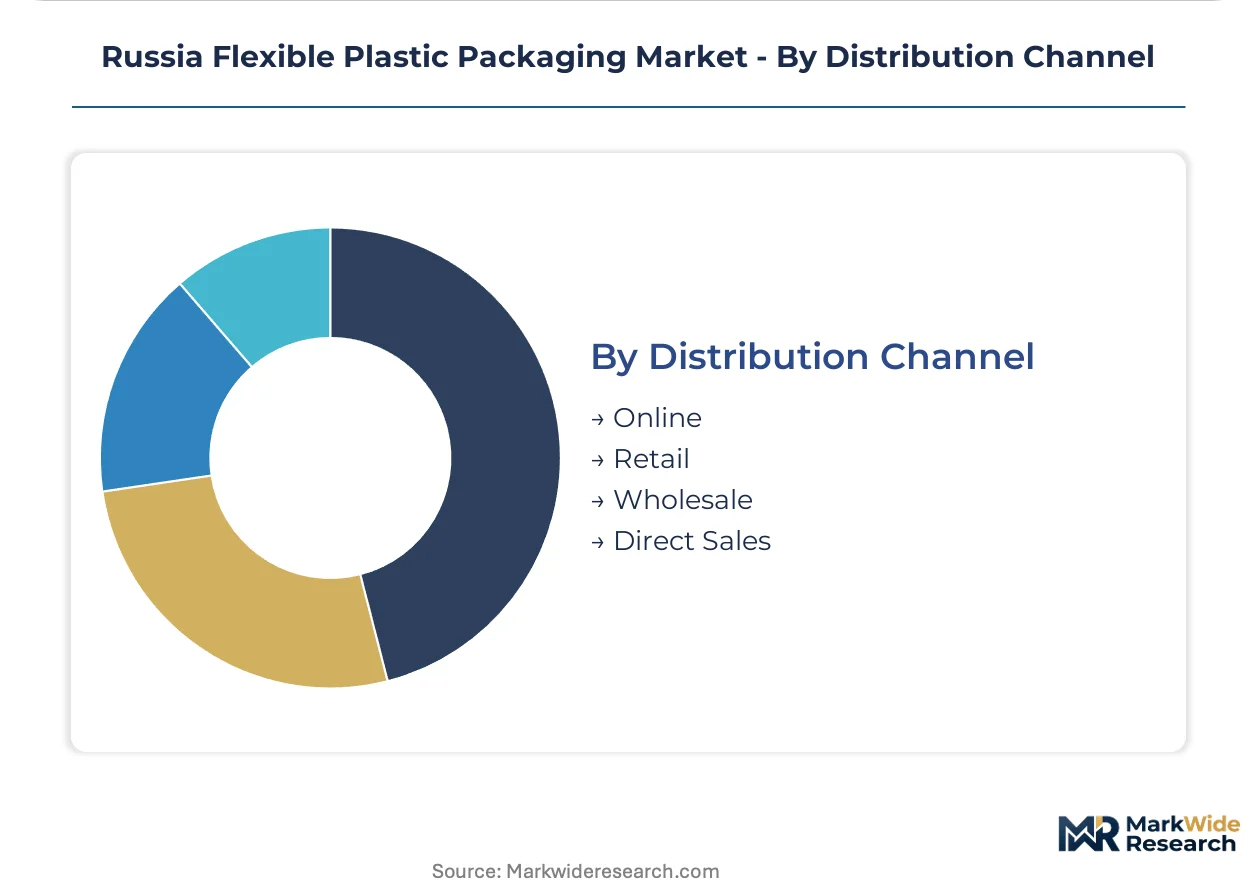
Distribution Channel:
Customer type concentration is restructuring channel economics, with retail chain consolidation displacing fragmented distributor networks.
- Retail:Direct procurement by X5 Retail Group and Magnit is centralizing specifications and converter audits, compressing margins for regional intermediaries in the Central Federal District.
- Direct Sales:Large FMCG producers in Moscow maintain dedicated converter relationships for just-in-time delivery of customized pouch formats.
- Wholesale:Regional distributors serve mid-volume food brands in the Volga Federal District with standardized film and bag inventories.
- Online:Digital platforms are emerging for specialty and short-run orders, though logistics infrastructure limits penetration outside capital region clusters.
Retail direct sales capture the largest revenue pool; online channels are gaining share fastest among small-batch regional brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the Central Federal District exceeds that of the Volga Federal District by a substantial margin, reflecting the concentration of retail chain procurement headquarters and premium logistics infrastructure around Moscow.
Central Federal District
Dairy and meat processors in Moscow and the surrounding oblasts are consolidating flexible packaging procurement volumes to secure scale discounts from converters. The Russian Environmental Operator's EPR recycling targets are accelerating converter investment in mono-material polyethylene formats. Major retail chains including X5 Retail Group and Magnit are conducting direct supplier audits in this cluster, bypassing traditional distributor networks.
Northwestern Federal District
St. Petersburg-based ready-meal and seafood brands are driving adoption of ethylene vinyl alcohol coextrusions to replace metallized barrier layers. Eurasian Economic Union technical regulations on food-contact material migration limits are forcing ink and adhesive reformulations among local converters. The city's port infrastructure supports just-in-time delivery schedules for exporters targeting EEU member states.
Volga Federal District
Grain and oilseed processors in Samara and Saratov oblasts generate substantial bulk film demand with lower barrier requirements than packaged food applications. Rospotrebnadzor sanitary-epidemiological standards apply uniformly but certification timelines vary by regional office capacity. Zavod Volga Polymer anchors regional supply from a position proximate to these agricultural processing hubs.
Southern Federal District
Rostov-on-Don serves as a distribution node for flexible packaging flowing into Black Sea port logistics and nearby food manufacturing. The district's horticulture and wine sectors are testing biodegradable film alternatives for export compliance with EU retail requirements. Converter presence remains thinner here than in Central or Northwestern districts, creating procurement cost penalties for mid-volume brands.
Ural Federal District
Industrial bundling applications in Yekaterinburg's machinery and metalworking sectors sustain demand for heavy-gauge polyethylene films with minimal print requirements. SIBUR's polymer production assets in the broader region provide feedstock cost advantages to locally integrated converters. The district's distance from Moscow-based retail procurement centers limits access to premium pouch and laminate specifications.
Russia Flexible Plastic Packaging Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Russia's flexible packaging sector. Integrated polymer producers with captive feedstock control raw material costs, while specialized converters compete through equipment calibration and regional proximity. The market structure separates into three strategic archetypes: upstream-integrated resin suppliers, mid-volume regional specialists, and niche barrier film innovators. Competitive dynamics center on backward integration into resin supply and geographic expansion toward underserved agricultural processing clusters.
Among upstream-integrated players, SIBUR exemplifies the cost-leadership archetype through its captive polyethylene and polypropylene production. KubRotoPak and Zavod Volga Polymer occupy positions as regional specialists, with the former calibrated for mid-volume pouch and bag converting and the latter anchored in Volga Federal District bulk film supply. These three companies represent the dominant competitive formations: integrated feedstock control, equipment-specialized regional service, and proximity-based agricultural supply.
| Leading Market Players |
|---|
| SIBUR |
| KubRotoPak |
| Lambumiz |
| 2A – Upakovka |
| Zavod Volga Polymer |
| RDF Group |
| PKO-SURA |
| Protek Group |
| Mirpack Company |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between SIBUR and Central Federal District converters lock in polyethylene supply visibility while insulating integrated players from spot market volatility that strains non-captive competitors.
Pricing Analysis
Configured-to-order pricing for multilayer barrier films commands substantial premiums over standard mono-material polyethylene formats. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Cost compression in standard film tiers is intensifying because retail chain procurement consolidation squeezes regional converter margins. Mid-volume food brands in the Volga Federal District exhibit highest price sensitivity, while Moscow-based dairy processors prioritizing EPR compliance demonstrate lowest sensitivity.
Supply Chain Analysis
Port congestion at Baltic Sea terminals and container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for specialty resin additives and converting equipment. Russia's flexible packaging supply chain draws from domestic polyethylene production anchored in Western Siberia, supplemented by polyamide and ethylene vinyl alcohol imports from Germany and South Korea. Single-source vulnerability concentrates in metallized film substrate supply. Distribution runs through direct converter relationships with retail chain headquarters, bypassing traditional wholesale networks in Moscow and St. Petersburg.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as X5 Retail Group and Magnit centralize procurement specifications, fragmenting converter margins and rewarding scale players with dedicated supply relationships.
For Market Incumbents: Consolidate backward integration into captive resin supply or regional logistics infrastructure to defend against SIBUR's feedstock cost advantage. Prioritize certification investment for EEU technical regulation compliance to maintain access to premium barrier film specifications. Channel control through direct retail chain relationships represents the critical defensive lever. For New Entrants and Emerging Players: Short-run digital print services for mid-volume regional food brands offer a service-layer gap where incumbents under-serve with legacy flexographic minimums. Target Volga Federal District agricultural processors requiring bulk film with lower barrier specifications. Pursue equipment-leasing partnerships to reduce capital barriers. For Investors and Strategic Acquirers: Regional mono-material specialists with established Rospotrebnadzor certification pathways represent the most attractive acquisition target archetype. Long-term viability hinges on EPR framework enforcement intensity and domestic recycling infrastructure buildout. Monitor Russian Environmental Operator recycling target announcements as the primary inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | SIBUR's captive polyethylene production anchors cost positions against import-dependent competitors. |
| Mono-Material Format Transition | Converters redesigning multilayer structures preempt EPR sorting penalties from Russian Environmental Operator. |
| Digital Print Capability Investment | Flexographic presses with inline inspection unlock short-run customization for regional food brands. |
| Regional Logistics Hub Expansion | Proximity to Volga agricultural processors reduces delivery costs for bulk film applications. |
| EEU Certification Pathway Development | Rospotrebnadzor approval timelines determine commercialization speed for innovative barrier coatings. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with polymer procurement managers, converter operations directors, retail chain category buyers, and Rospotrebnadzor certification specialists; and secondary validation against customs trade records, Eurasian Economic Union technical regulation filings, and SIBUR production disclosures. Bottom-up volume modeling triangulated against top-down value estimates derived from retail chain procurement data.
Across the analysis window, the forecasting framework modeled demand by product type, material grade, end-use application, and federal district distribution pattern. CAGRs were computed from annual growth rate progression analysis. Industry-specific inputs included EPR recycling target phase-in schedules and polyolefin capacity expansion timelines.
Material uncertainties — sanctions regime evolution, EEU-EU regulatory harmonization timing, and domestic mechanical recycling infrastructure scaling — sit outside the modeled envelope. Forecasts reflect documented assumptions about polymer chemist labor availability and converter capex cycles. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Hygiene Breathable Films Market
Flexible Packaging
Kenya Flexible Packaging Market
Flexible Packaging
GCC Flexible Packaging Market
Flexible Packaging
Flexible Containers Market
Flexible Packaging
Industrial Flexible Packaging Market
Flexible Packaging
Europe Flexible Packaging Market
Flexible Packaging
Global Breathable Films Market
Flexible Packaging
Converted Flexible Packaging Market
Flexible Packaging
Flexible Packaging Paper Market
Flexible Packaging
Bakery Flexible Packaging Market
Flexible Packaging
Asia-Pacific Flexible Plastic Packaging Market
Flexible Packaging
Thermoform Packaging Market
Flexible Packaging
Global Flexible Plastic Packaging Market
Flexible Packaging
Benelux Flexible Plastic Packaging Market
Flexible Packaging
Multilayer Flexible Packaging Market
Flexible Packaging
UK Flexible Plastic Packaging Market