
 Brazil Flexible Plastic Packaging Market | 2026-2036
Brazil Flexible Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Flexible Plastic Packaging Market Insights
The gap between premium multilayer barrier films and commodity polyethylene bags is repositioning how Brazilian converters allocate capital and technical resources. Amcor PLC leverages its global film technology portfolio to serve multinational food brands with extended-shelf-life packaging in the Southeast. Berry Global Inc anchors its position through scale manufacturing of printed rollstock for regional dairy and meat processors. Plaszom Zomer Industria De Plasticos Ltda specializes in customized flexible formats for mid-sized consumer goods companies competing on shorter runs.
Brazil flexible plastic packaging comprises polymer-based materials—typically polyethylene, polypropylene, or multilayer coextrusions between 20 and 150 microns—manufactured through blown or cast film extrusion, often laminated with aluminum oxide or ethylene vinyl alcohol for oxygen barrier performance. These materials primarily protect perishable goods from moisture, oxidation, and mechanical damage during distribution in tropical climates. Stand-up pouches and shrink films command disproportionate attention from brand owners seeking shelf differentiation and logistics efficiency in modern retail channels. Polyethylene remains the volume base for commodity applications, though nylon and EVOH-enhanced structures capture margin in pharmaceutical and premium food segments where barrier specifications are non-negotiable.
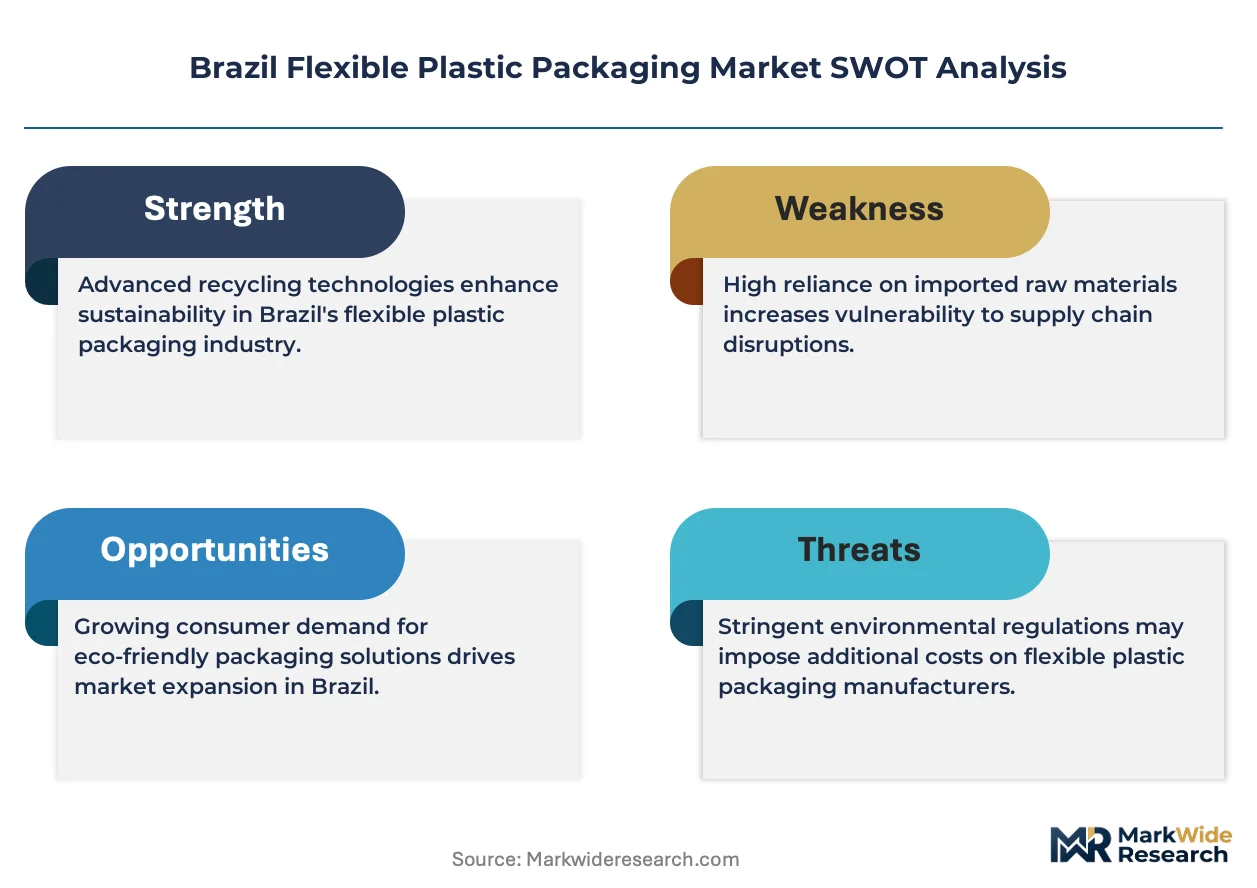
ANVISA governs food-contact compliance and migration limits for plastic packaging materials sold in Brazil, while the National Institute of Metrology, Quality and Technology (INMETRO) administers conformity assessment programs that affect import access and domestic producer certification. The Brazilian Association of Technical Standards (ABNT) publishes voluntary specifications that large retail chains increasingly mandate in procurement contracts. Stakeholders must track how proposed federal packaging waste legislation intersects with existing state-level extended producer responsibility programs in São Paulo and Rio de Janeiro to anticipate compliance cost allocation across the value chain.
Market Dynamics
ANVISA's migration-limit updates for food-contact materials are forcing converters to recertify resin grades, compressing margins for mid-sized processors while rewarding early adopters with certified supply chains.
Growth Catalysts
- High-barrier pouch demand:Packaged food producers in São Paulo's industrial corridor are expanding orders for multilayer structures with EVOH and aluminum oxide layers to extend shelf life in tropical distribution.
- Extended producer responsibility programs:State-level EPR mandates in São Paulo and Rio de Janeiro are creating compliance-driven demand for recyclable mono-material films and post-consumer recycled content.
- Modern retail channel expansion:Supermarket chains in the Southeast are specifying stand-up pouches and shrink films for private-label brands, pulling converter capacity toward printed rollstock with high graphic quality.
Market Restraints
- Resin import dependency:Brazil's polyethylene and polypropylene supply concentrates on Braskem's domestic production and imported grades, exposing converters to currency volatility and port congestion at Santos.
- ANVISA certification timelines:Food-contact material approvals require 12-18 month validation cycles, freezing formulation changes and delaying new product launches for regional meat and dairy processors.
- Rigid packaging substitution:Glass and metal cans retain share in premium beer and infant formula segments where oxygen barrier specifications exceed flexible film capabilities at scale.
Strategic Opportunities
- Northeast industrial corridor:Bahia and Pernambuco offer underpenetrated demand from fruit pulp exporters and emerging processed food clusters with limited local converter presence.
- Pharmaceutical blister films:ANVISA's alignment with ICH guidelines is opening demand for PVC-PVDC and cold-form aluminum laminates in generic drug packaging.
- ABNT voluntary standards:Large retail chains are mandating ABNT NBR compliance in procurement contracts, creating certification premiums for converters with in-house testing laboratories.
Industry Challenges
- Coextrusion technician scarcity:Blown film lines running seven-layer barrier structures require operators with polymer rheology training that technical institutes in Campinas and Curitiba struggle to supply.
- Legacy gravure press integration:Converters retrofitting solvent-free laminators onto existing print lines face downtime costs and color-matching inconsistencies that delay customer approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Flexible Plastic Packaging Market |
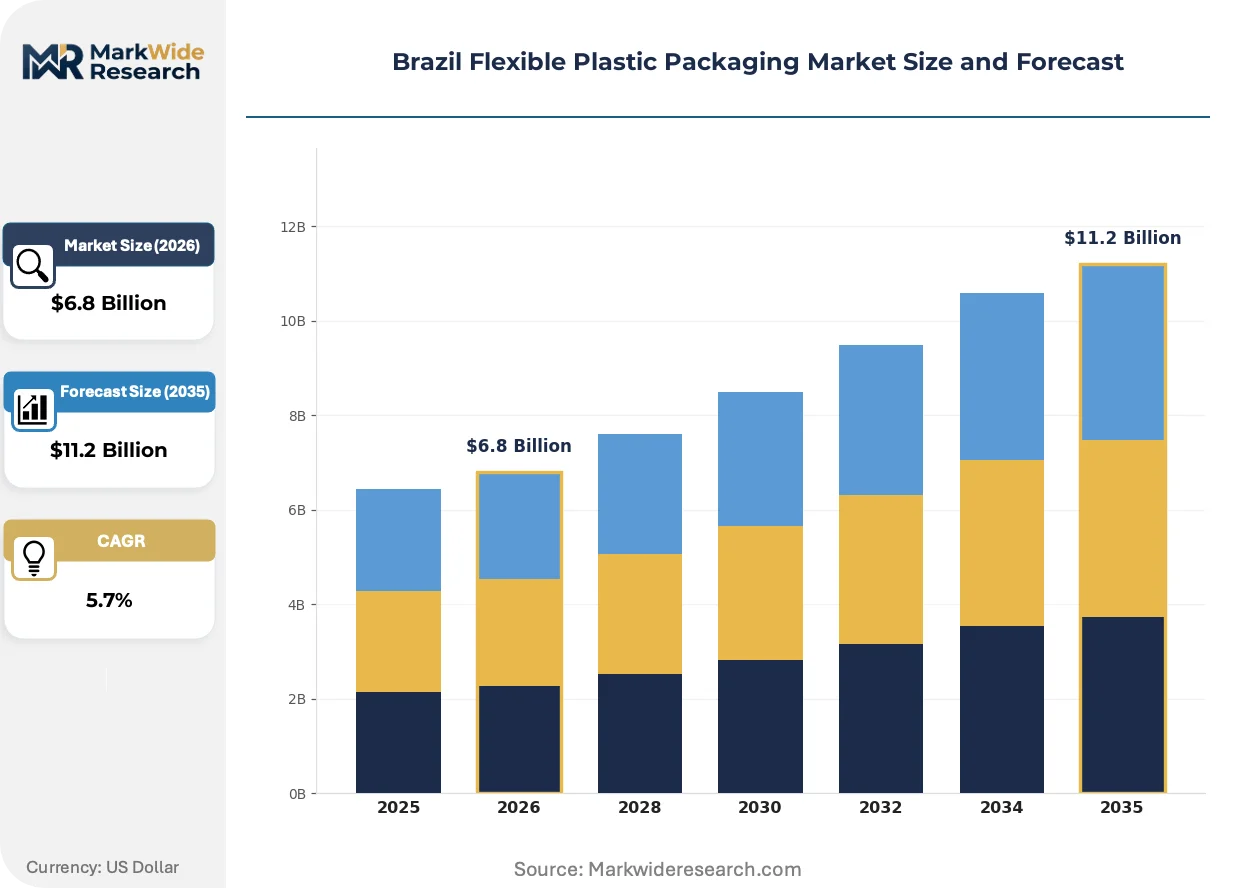
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Layflat Pouches, Shrink Films, Bags Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Nylon End User: Food & Beverage, Consumer Goods, Pharmaceuticals, Personal Care Technology: Extrusion, Lamination, Printing, Coating |
| Companies Covered | Sonoco Products Company, Amcor PLC, Huhtamaki Oyj, Plaszom Zomer Industria De Plasticos Ltda, Berry Global Inc, Videplast, Mondi PLC, Constantia Flexibles, Sealed Air, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Flexible Plastic Packaging Market Trends and Innovations
Digital printing and solvent-free adhesive technologies are compressing minimum order quantities and lead times, enabling shorter-run flexibility that reconfigures converter-customer relationships in the Southeast food belt.
Mono-material polyethylene films with enhanced barrier properties are converging with mechanical recycling infrastructure investments by major retailers, allowing converters to offer drop-in replacements for multilayer pouches without sacrificing heat-seal performance or printability.
ANVISA's updated Resolution RDC 326 on food-contact plastics tightens migration limits for heavy metals and primary aromatic amines, compelling converters to validate new antioxidant packages and document supply chain traceability from resin pellet to finished rollstock.
Brand owners in the Campinas-Curitiba corridor are consolidating supplier panels and demanding vendor-managed inventory programs, replacing spot purchasing with annual framework agreements that lock in volume commitments and technical service support.
Brazil Flexible Plastic Packaging Market Segmentation
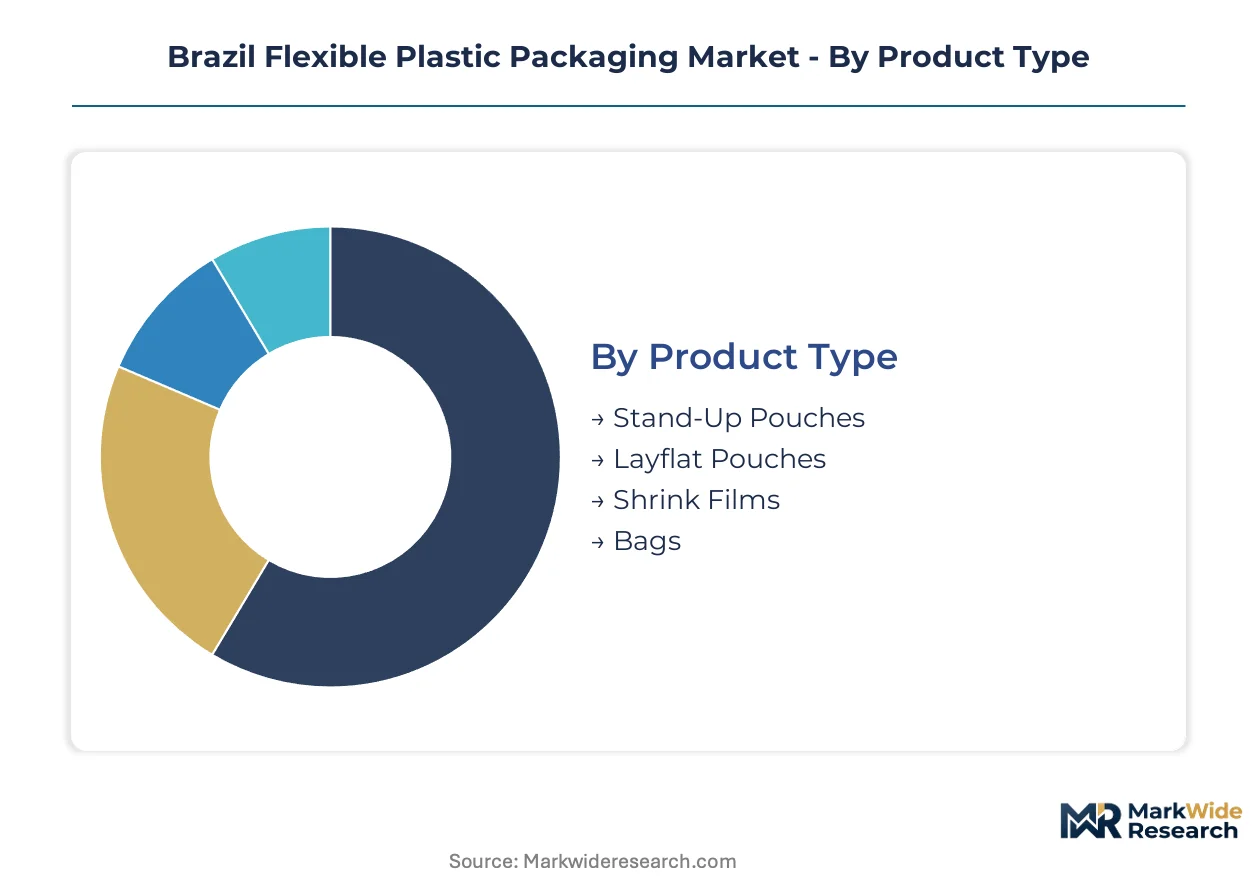
Converters in Brazil's flexible packaging sector face divergent margin profiles across product formats and end-use specifications. Understanding how technical requirements and buyer purchasing power segment demand reveals where capital deployment yields sustainable returns.
Product Type:
Packaged food producers differentiate purchasing by shelf-life extension needs and retail channel format requirements.
- Stand-Up Pouches:Multilayer structures combining PET, aluminum oxide, and polyethylene deliver 12-18 month shelf stability for ambient sauces and ready meals. São Paulo-based meat processors are expanding orders for high-barrier versions with resealable zippers to penetrate modern retail freezer sections.
- Shrink Films:Biaxially oriented polyethylene terephthalate or polyolefin formulations provide 40-70% shrinkage ratios for beverage multipacks and corrugated tray overwrap. Curitiba dairy cooperatives specify printed shrink bundles to replace corrugated secondary packaging in club store channels.
- Layflat Pouches:Three-side-seal polyethylene formats dominate commodity rice and dry bean packaging across Brazil's Northeast distribution networks.
- Bags:Gusseted polyethylene sacks with anti-slip embossing serve fertilizer and agricultural chemical bulk packaging in Mato Grosso grain belts.
Volume sits with bags serving agribusiness; growth tilts toward stand-up pouches capturing processed food premiumization.
Material:
Resin selection tracks barrier specification intensity and recyclability mandates under emerging extended producer responsibility frameworks.
- Polyethylene:Linear low-density and metallocene grades constitute the volume foundation for commodity films, though converters face pressure to certify post-consumer recycled content for São Paulo retail chain compliance.
- Nylon:Biaxially oriented polyamide 6 provides puncture resistance and oxygen barrier in vacuum-packed meat and cheese applications. Campinas processors specify nylon-EVOH coextrusions for export-grade beef shipments to Middle Eastern markets.
- Polypropylene:Cast and oriented PP films deliver clarity and stiffness for snack food lamination and label face stocks.
- Polyvinyl Chloride:Plasticized PVC remains entrenched in pharmaceutical blister packs despite environmental scrutiny, pending ANVISA alignment with international substitution timelines.
Polyethylene commands installed capacity; nylon-enhanced structures are climbing the fastest as barrier specifications tighten.
End User:
Buyer technical sophistication and validation requirements create distinct procurement patterns across sector verticals.
- Food & Beverage:Accounts for dominant flexible packaging consumption spanning ambient, chilled, and frozen distribution. ANVISA migration-limit compliance and tropical climate shelf-life demands drive specification intensity in processed meat, dairy, and beverage categories.
- Pharmaceuticals:Blister films, sachets, and strip packs require validated barrier performance and child-resistant functionality. Generic drug manufacturers in Rio de Janeiro industrial zones are expanding cold-form aluminum laminate orders as ANVISA adopts ICH stability guidelines.
- Consumer Goods:Detergent pods and home care refills specify water-soluble film and stand-up pouch formats with high-graphic print surfaces.
- Personal Care:Cosmetic sachets and flexible tubes demand compatibility with alcohol-based formulations and tropical storage conditions.
Food and beverage anchors volume commitments; pharmaceuticals show the steepest specification escalation as regulatory alignment accelerates.
Technology:
Capital intensity and operator skill requirements stratify converter capabilities and customer access tiers.
- Extrusion:Blown and cast film lines running 3-9 layers dominate polyethylene and polypropylene production. Braskem resin supply agreements and Santos port logistics determine cost competitiveness for commodity film exporters.
- Lamination:Solvent-free adhesive and extrusion lamination lines bond dissimilar films for barrier structures. Converters in the Southeast are retrofitting existing gravure presses with solvent-free systems to meet ABNT voluntary emission standards demanded by retail procurement panels.
- Printing:Flexographic and rotogravure presses deliver high-line-count graphics for brand differentiation. Digital printing installations are compressing minimum order quantities for mid-sized consumer goods companies.
- Coating:Aluminum oxide and silicon oxide vapor deposition adds oxygen barrier to transparent films for microwaveable and see-through packaging applications.
Extrusion holds installed base dominance; coating capacity is expanding most quickly as transparent barrier demand outpaces metallized film supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Campinas-Curitiba industrial corridor anchors Brazilian flexible packaging demand, with São Paulo state alone concentrating over half of national converter capacity and food processor procurement volumes.
São Paulo
Meat processors and dairy cooperatives in the Campinas metropolitan region are expanding orders for high-barrier pouches with EVOH layers. ANVISA's updated Resolution RDC 326 tightens migration limits for food-contact materials, forcing converters in the São Paulo industrial belt to recertify resin grades. The São Paulo state extended producer responsibility program mandates post-consumer recycled content thresholds for retail chain suppliers.
Minas Gerais
Dairy processors in the Triângulo Mineiro region specify printed rollstock for UHT milk and cheese packaging with 12-month shelf stability requirements. INMETRO conformity assessment programs govern import access for European barrier film technologies used by local converters. Belo Horizonte's emerging food tech cluster is pulling converter investment toward shorter-run digital printing capabilities.
Rio Grande do Sul
Poultry exporters in the Serra Gaúcha region demand vacuum-packed barrier structures compliant with Middle Eastern import specifications. The state-level environmental secretariat enforces packaging waste regulations that intersect with federal extended producer responsibility proposals. Porto Alegre's converter base specializes in shrink films for beverage multipacks distributed through southern Brazil's club store channels.
Paraná
Soybean oil and margarine processors in the Londrina-Maringá corridor specify high-clarity cast polypropylene films for retail differentiation. ABNT voluntary standards NBR 10520 and NBR 13834 are increasingly mandated in procurement contracts by Curitiba-based supermarket chains. The Curitiba metropolitan area hosts Brazil's densest concentration of seven-layer coextrusion capacity for barrier meat packaging.
Bahia
Fruit pulp exporters in the Recôncavo Baiano region generate underpenetrated demand for aseptic bag-in-box formats with 18-month ambient stability. The northeastern state's limited local converter presence creates logistics cost premiums for São Paulo-sourced materials. Salvador's port infrastructure improvements are attracting flexible packaging distributors seeking to serve emerging processed food clusters in Pernambuco.
Brazil Flexible Plastic Packaging Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technical capability and certification depth, with multinational film technology owners commanding annual framework agreements while regional converters compete on spot pricing for standard polyethylene formats. The vendor base stratifies into three tiers: global packaging conglomerates with integrated resin supply chains, mid-sized national specialists with customized format capabilities, and commodity converters serving agribusiness bulk packaging. Dominant competitive moves include retrofitting solvent-free lamination lines to meet ABNT emission standards and securing Braskem resin supply agreements to hedge currency volatility.
Among global packaging conglomerates, Amcor PLC and Berry Global Inc exemplify the premium-tier archetype through their integrated film technology portfolios and scale manufacturing positions. Plaszom Zomer Industria De Plasticos Ltda occupies a specialist position within the mid-tier segment, representing converters that compete on customized flexible formats and shorter production runs for regional consumer goods companies. These three entities anchor the competitive structure that smaller commodity converters must navigate through certification investments or niche geographic focus.
| Leading Market Players |
|---|
| Sonoco Products Company |
| Amcor PLC |
| Huhtamaki Oyj |
| Plaszom Zomer Industria De Plasticos Ltda |
| Berry Global Inc |
| Videplast |
| Mondi PLC |
| Constantia Flexibles |
| Sealed Air |
| Others |
Pricing and Supply Chain Analysis
Backward integration into Braskem resin supply agreements anchors converter pricing power in Brazil's flexible packaging sector, locking in feedstock cost predictability while currency hedging separates multinational film producers from spot-market-dependent regional competitors. This captive supply structure concentrates margin protection among scale players with annual volume commitments, leaving mid-sized processors exposed to polyethylene import volatility at Santos port.
Pricing Analysis
Yield-based pricing for high-barrier multilayer films anchors converter quotations, with EVOH-enhanced structures commanding premiums tied to shelf-life extension outcomes for meat and dairy processors. Three-tier pricing structure across premium certified grades, standard commercial films, and commodity polyethylene bags reflects ANVISA certification depth and volume scale. Cost compression in standard-grade rollstock is intensifying because converters retrofit solvent-free laminators to meet ABNT emission standards demanded by São Paulo retail chains. Agribusiness bulk bag buyers exhibit highest price sensitivity; pharmaceutical blister film purchasers show lowest.
Supply Chain Analysis
Freight cost differentials between Santos port discharge and Northeast distribution centers shape converter location decisions, with Bahia and Pernambuco logistics premiums reaching double-digit percentages versus São Paulo-sourced materials. Raw material supply draws from Braskem's domestic polyethylene and polypropylene production, supplemented by imported resin grades from the United States and Middle Eastern producers. Single-source vulnerability concentrates on Braskem's triethylene glycol and metallocene catalyst supply. Distribution runs through converter direct sales to food processors, with vendor-managed inventory programs replacing spot purchasing in the Southeast corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's flexible packaging sector sits in a solvent-free lamination transition phase, with digital printing compression of minimum order quantities displacing legacy gravure-dominant converter-customer relationships. Mono-material polyethylene barrier films are replacing multilayer non-recyclable structures under extended producer responsibility mandates.
For Market Incumbents: Acquire seven-layer coextrusion technician training programs from Campinas and Curitiba technical institutes to lock in barrier film operator pipelines before competitors. Defend against emerging digital-native converters by retrofitting existing gravure presses with solvent-free adhesive systems to meet ABNT NBR emission standards demanded by Curitiba supermarket procurement panels. Expand vendor-managed inventory agreements with Campinas meat processors to lock in annual volume commitments.
For New Entrants and Emerging Players: Begin with aseptic bag-in-box formats for fruit pulp exporters in Bahia's Recôncavo Baiano region, where limited local converter presence creates logistics cost premiums for São Paulo-sourced competitors. Target pharmaceutical blister film demand in Rio de Janeiro industrial zones as ANVISA aligns with ICH stability guidelines. Pursue digital printing installations to compress lead times for mid-sized consumer goods companies competing on shorter production runs.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to global packaging conglomerates seeking Southeast American barrier film capacity and ANVISA-certified supply chains. Long-term viability favors converters with in-house testing laboratories capable of documenting migration-limit compliance from resin pellet to finished rollstock. Watch for ANVISA's final Resolution RDC 326 implementation timeline as the signal for certification-driven consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Solvent-Free Lamination Retrofit | Enables ABNT NBR emission compliance required by São Paulo retail procurement panels. |
| Post-Consumer Recycled Content Certification | Satisfies São Paulo state extended producer responsibility recycled content thresholds. |
| Seven-Layer Coextrusion Capacity Addition | Captures EVOH barrier demand from Campinas meat processors expanding freezer section penetration. |
| Digital Printing Platform Installation | Compresses minimum order quantities for Belo Horizonte food tech cluster shorter-run requirements. |
| Northeast Distribution Hub Establishment | Reduces logistics premiums for Bahia fruit pulp exporters currently sourcing from São Paulo. |
Research Methodology
Trade association filings, ANVISA regulatory submissions, and Braskem resin supply disclosures formed the secondary backbone of this analysis, cross-referenced with customs records tracking polyethylene and polypropylene import flows through Santos port. Primary interviews with blown film line operators, gravure press technicians, and procurement managers at São Paulo meat and dairy processors validated formulation and specification trends. Top-down triangulation against food and beverage packaging consumption patterns and bottom-up aggregation of converter capacity installations anchored market sizing across the analysis window.
Bottom-up modeling tracked extrusion, lamination, printing, and coating technology capacity by layer count and barrier specification intensity, while top-down analysis calibrated against food processor procurement volumes in the Campinas-Curitiba corridor. Segmentation dimensions included product format, resin material, end-use vertical, and technology type, with CAGRs derived from trend extrapolation of high-barrier pouch adoption and mono-material film substitution rates. Forecast inputs incorporated ANVISA regulatory timeline assumptions and extended producer responsibility program implementation pace.
Underlying measurement precision varies by segment; stand-up pouch and pharmaceutical blister film categories carry tighter precision than commodity bag formats due to more concentrated supplier reporting. Forecasts reflect documented assumptions about resin price trajectories and regulatory implementation schedules. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Egypt Flexible Plastic Packaging Market
Flexible Packaging
Bakery Flexible Packaging Market
Flexible Packaging
Flexible Containers Market
Flexible Packaging
Morocco Flexible Plastic Packaging Market
Flexible Packaging
Flexible Packaging Paper Market
Flexible Packaging
Flexible Film Market
Flexible Packaging
Italy Flexible Plastic Packaging Market
Flexible Packaging
Asia-Pacific Flexible Plastic Packaging Market
Flexible Packaging
Nigeria Flexible Packaging Market
Flexible Packaging
China Flexible Packaging Market
Flexible Packaging
United States Flexible Plastic Packaging Market
Flexible Packaging
Flex Pack Coatings Market
Flexible Packaging
Latin America Flexible Packaging Market
Flexible Packaging
Flexible Bottle Market
Flexible Packaging
Confectionery Flexible Packaging Market
Flexible Packaging
Multilayer Flexible Packaging Market