
 Bakery Flexible Packaging Market | 2026-2036
Bakery Flexible Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Bakery Flexible Packaging Market Outlook
Single-source to multi-source procurement is restructuring supply relationships across the bakery flexible packaging value chain. Amcor plc leverages its global film manufacturing footprint to secure long-term contracts with pan-European bakery groups. Mondi anchors its position through integrated kraft paper and barrier film operations serving artisanal and commercial bakery segments. Huhtamaki competes via specialized molded fiber and flexible hybrid formats for premium pastry applications.
Bakery flexible packaging denotes laminated or monolayer films, pouches, bags, and wraps engineered with oxygen barrier properties between 0.1 and 10 cc/m²/day to preserve moisture, aroma, and structural integrity in bread, confectionery, and frozen dough products. Polyethylene and polypropylene films dominate material selection for cost-sensitive sliced bread and bun applications, while nylon-reinforced multilayer structures command margin pools in premium croissant and frozen patisserie formats where puncture resistance and extended shelf life justify higher unit economics. Pouches with zipper closures represent the fastest-growing product configuration as commercial bakeries and supermarket private labels shift from traditional tie-closure bread bags toward resealable formats that reduce staling-related waste.
The EU F-Gas Regulation and REACH compliance frameworks constrain fluorinated barrier chemistries, redirecting R&D investment toward bio-based coatings and mechanically recyclable mono-material structures. FDA food contact notification requirements govern U.S. import eligibility for European flexible packaging suppliers, creating divergent formulation pathways across Atlantic supply corridors. Stakeholders must monitor evolving extended producer responsibility schemes in France and Germany, where deposit-return discussions for flexible food packaging threaten to disrupt existing bakery supply chain economics.
Market Dynamics
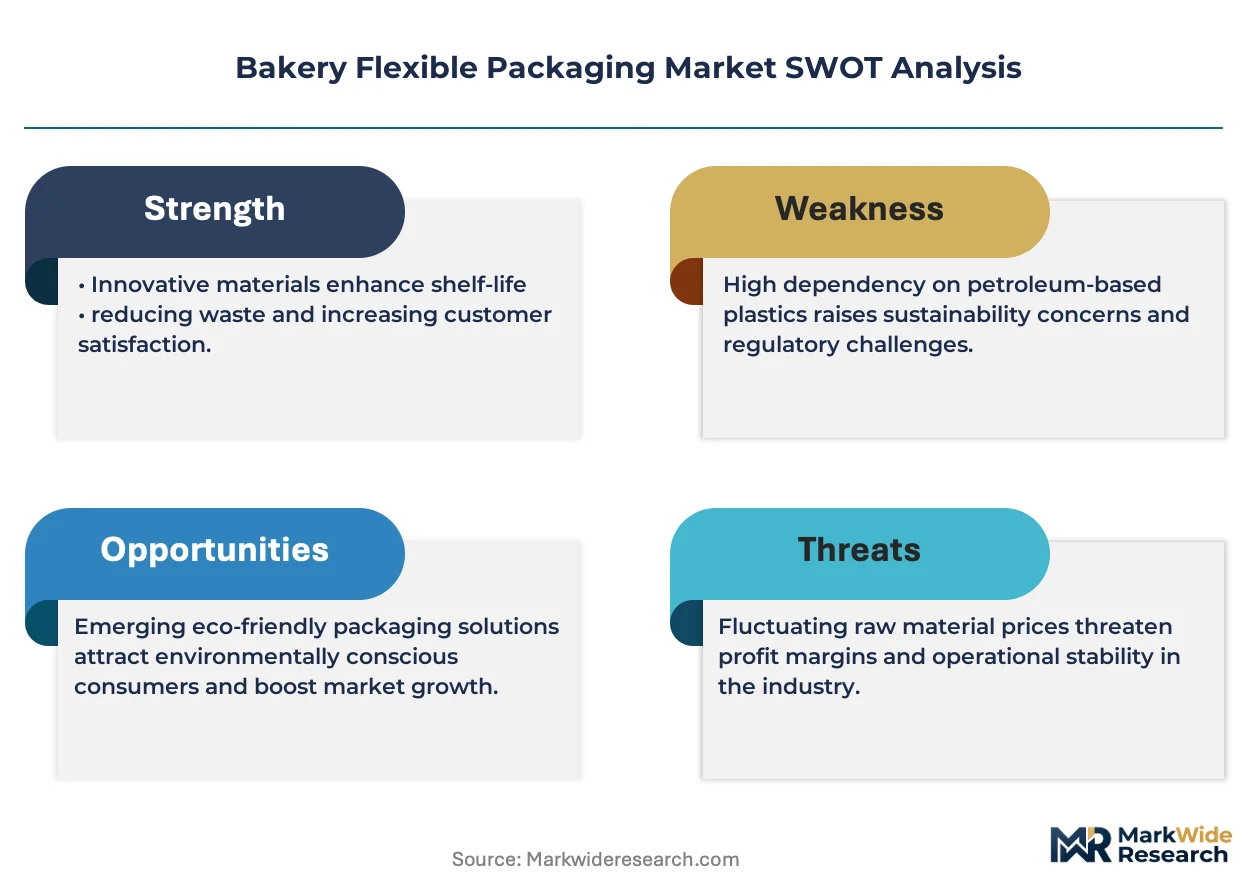
Resealable pouch adoption is compressing traditional tie-closure formats across commercial bakery lines, forcing film suppliers to retool lamination assets toward zipper-compatible structures and oxygen barrier specifications below 1 cc/m²/day.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Recyclability mandates are accelerating mono-material film R&D investments across German, French, and Italian converter operations.
- Artisanal bakery premiumization:Nylon-reinforced multilayer structures are penetrating frozen patisserie and croissant segments where puncture resistance commands price premiums.
- Extended shelf-life bread formats:Commercial bakeries are specifying high-barrier pouches for private-label distribution to reduce staling-related retail returns.
Market Restraints
- Ethylene and propylene feedstock volatility:PE and PP resin costs fluctuate with naphtha cracking margins, compressing converter margins on cost-sensitive sliced bread applications.
- Fluorinated barrier chemistry constraints:The EU F-Gas Regulation and REACH frameworks are phasing out perfluorinated coatings before bio-based alternatives achieve equivalent oxygen barrier performance.
- Rigid tray substitution in frozen dough:Crystallized PET and PP trays are displacing flexible formats in foodservice frozen pastry distribution due to stacking efficiency.
Strategic Opportunities
- Deposit-return scheme preparation:France and Germany are piloting extended producer responsibility models for flexible food packaging that reward mono-material design.
- Molded fiber-flexible hybrid formats:Premium pastry applications are converging fiber-based trays with high-barrier film lids to replace all-plastic clamshells.
- Bio-based coating convergence:Cellulose nanofibril and chitosan barrier layers are approaching mechanical recyclability parity with conventional multilayer films.
Industry Challenges
- Mono-material certification timelines:RecyClass and How2Recycle approvals require 12-18 month validation cycles that delay commercial launches.
- Laminate-to-mono-material asset reconfiguration:Converters must replace solvent-based adhesive lines with extrusion coating or thermal lamination equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bakery Flexible Packaging Market |
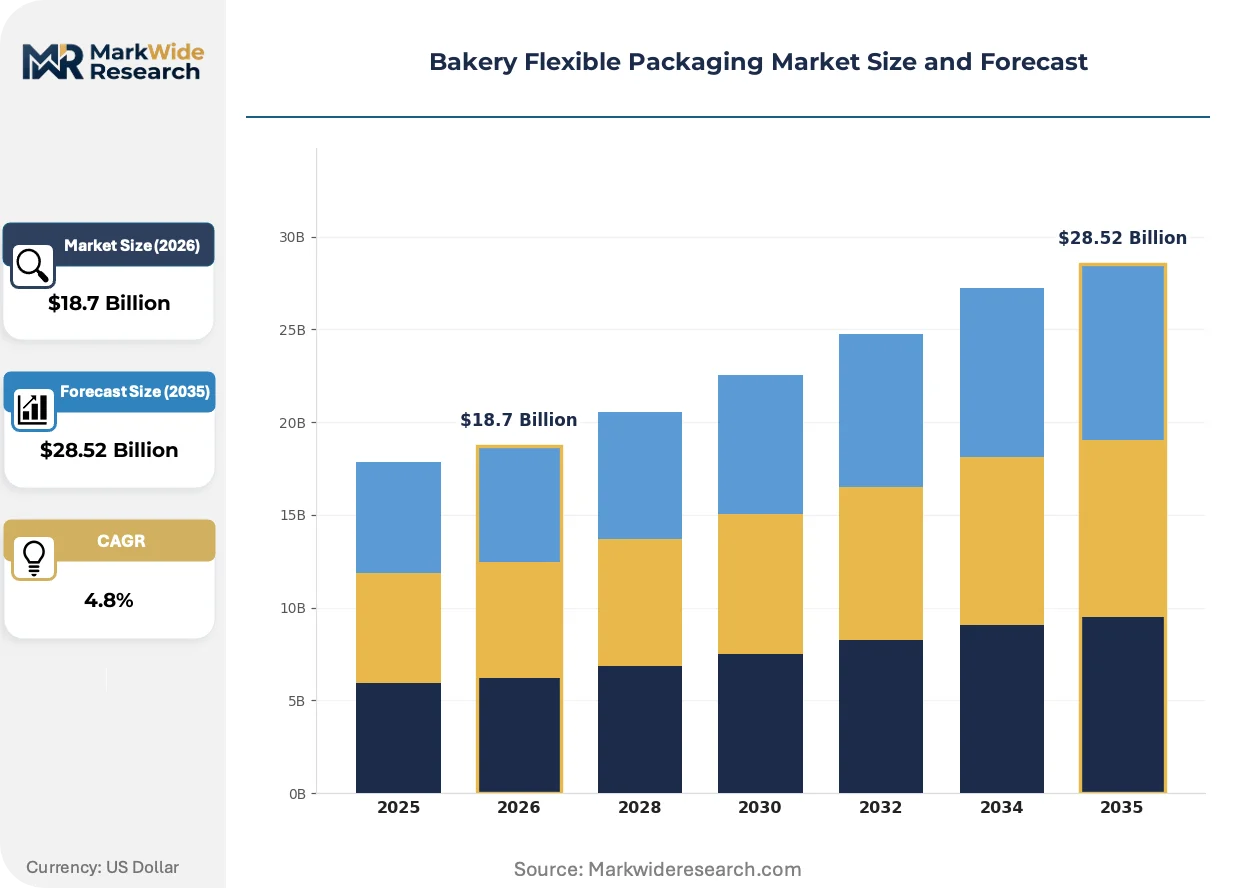
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Pouches, Wraps, Films Material: Polyethylene, Polypropylene, Nylon, Paper Closure Type: Zipper, Tie, Adhesive, Heat Seal End User: Artisanal Bakeries, Commercial Bakeries, Supermarkets, Food Service |
| Companies Covered | Amcor plc, Mondi, Huhtamaki, Smurfit Westrock, Sealed Air, Transcontinental Inc., Constantia Flexibles, International Paper, TOPPAN Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bakery Flexible Packaging Market Strategic Shifts
Barrier technology convergence and regulatory chemistry restrictions are compressing formulation diversity while resealable format engineering opens new specification tiers across frozen and ambient bakery segments.
Mono-material polyethylene structures with plasma-enhanced barrier deposition are unifying recyclability compliance with oxygen transmission performance previously requiring nylon or EVOH layers. German and Austrian commercial bakeries are specifying these films for private-label bread lines ahead of 2025 sorting infrastructure upgrades. This unification is compressing multilayer coextrusion demand among mid-tier converters lacking plasma coating capacity.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in barrier film manufacturing, redirecting capital toward water-based coating and vacuum metallization lines. Converters serving export markets must maintain dual formulation tracks to satisfy FDA food contact notification requirements for U.S.-bound shipments. Frozen patisserie and extended-shelf-life croissant formats face the tightest compliance windows due to their reliance on high-performance barrier specifications.
Supermarket private labels are consolidating flexible packaging procurement under single-source technical service agreements that bundle film specification, graphic design, and inventory management. This displaces fragmented spot purchasing through distributor intermediaries. The shift is most visible in German and Dutch retail bakery supply chains where centralized buying desks now mandate resealable pouch formats with unified EAN coding and shelf-ready secondary packaging.
Bakery Flexible Packaging Market Segmentation
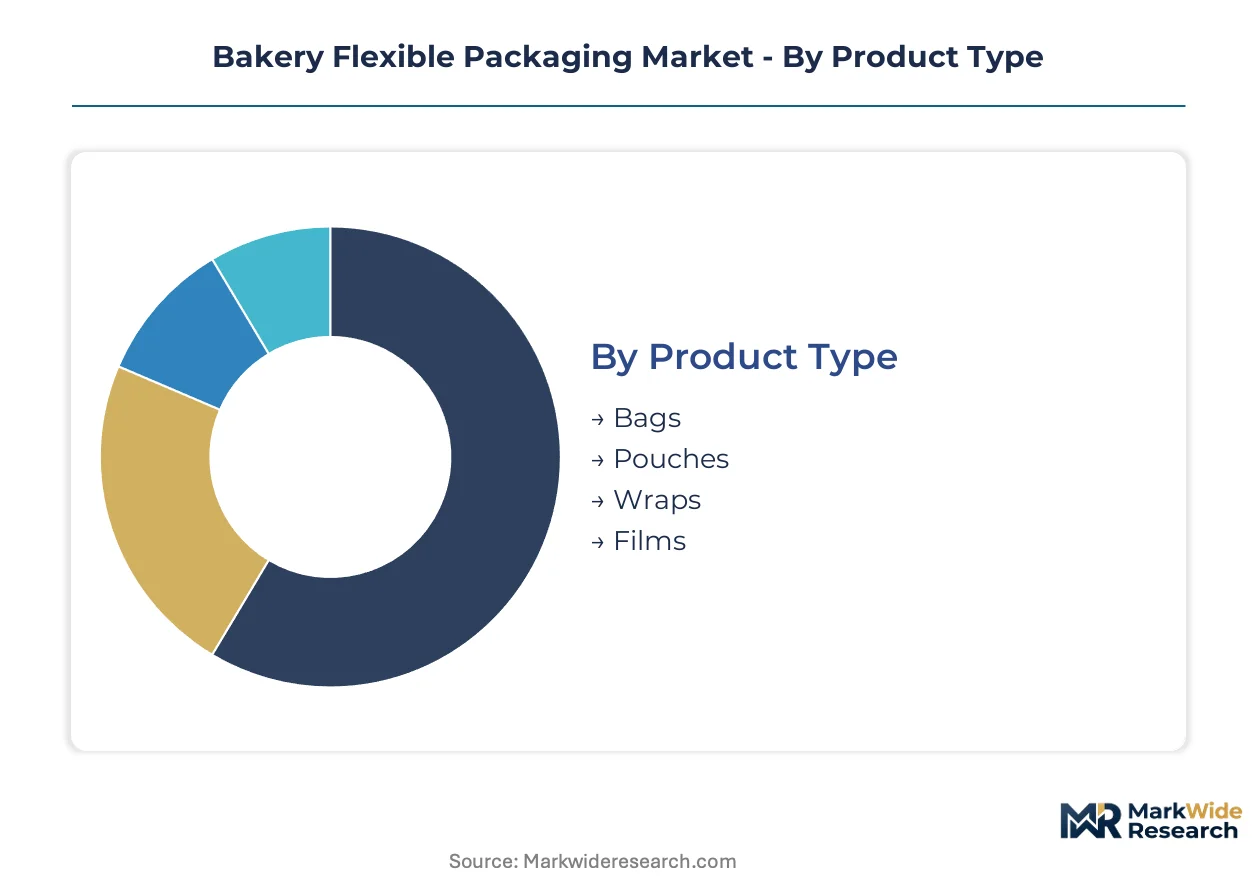
Flexible packaging specification tiers in bakery applications map directly to shelf-life requirements, distribution distance, and retail format economics. Each segmentation axis reveals distinct procurement patterns and margin structures that suppliers must navigate.
Product Type:
Film lamination complexity and barrier specification intensity define the technical differentiation across formats.
- Pouches:Multilayer structures with oxygen transmission rates below 1 cc/m²/day incorporate zipper-compatible seals for resealable bread and pastry lines. German commercial bakeries and Dutch supermarket private labels specify these for extended shelf-life private-label distribution where staling reduction justifies unit cost premiums.
- Films:Monolayer polyethylene and polypropylene substrates dominate high-volume sliced bread applications through form-fill-seal operations. Cost-sensitive procurement in French and Italian industrial bakeries concentrates here, though mono-material recyclability mandates are forcing specification upgrades.
- Bags:Side-gusseted polyethylene formats with tie closures retain share in artisanal bakery distribution where resealability adds limited value. Austrian and Swiss traditional bakeries maintain this specification for daily-fresh bread with 2-3 day consumption windows.
- Wraps:Thin-gauge films with modified atmosphere compatibility serve frozen dough and par-baked export formats. Puncture resistance specifications lag pouches, limiting penetration in premium pastry segments.
Mature deployment sits with Bags. Newer deployment is concentrated in Pouches.
Material:
Feedstock cost exposure and regulatory chemistry constraints reshape material selection priorities across converter operations.
- Polyethylene:Linear low-density grades with plasma-enhanced barrier deposition are displacing nylon-reinforced structures in German bread packaging ahead of recyclability infrastructure upgrades. Mono-material certification pathways favor this chemistry for deposit-return scheme eligibility.
- Polypropylene:Cast and oriented films deliver moisture barrier performance for bun and roll applications with lower oxygen sensitivity. Italian and Spanish industrial bakeries specify biaxially oriented PP for crinkle-cut bread bag aesthetics and machinability.
- Nylon:Polyamide layers in multilayer coextrusion provide puncture resistance for frozen croissant and patisserie distribution. EU F-Gas Regulation constraints on fluorinated alternatives sustain nylon demand despite mechanical recyclability limitations.
- Paper:Kraft-based substrates with bio-based barrier coatings penetrate premium artisanal segments where tactile differentiation supports price positioning. French bakery chains specify paper-flexible hybrids for macaron and viennoiserie gift formats.
Volume concentration remains with Polyethylene. Specification intensity peaks with Nylon.
Closure Type:
Consumer convenience engineering and line-speed compatibility drive format selection across bakery packaging lines.
- Zipper:Press-to-close profiles integrated during pouch forming enable resealability without clip accessories. German and Dutch retail consolidation under technical service agreements mandates zipper specification for private-label bread across multiple SKUs.
- Heat Seal:Hermetic closure integrity supports modified atmosphere packaging for extended shelf-life applications. French industrial bakeries specify peelable heat seals for consumer convenience in croissant and brioche distribution.
- Tie:Twist-wire and plastic clip closures persist in cost-optimized sliced bread formats where line speed exceeds 200 units per minute. Equipment amortization timelines delay zipper retrofitting at older Central European bakery facilities.
- Adhesive:Resealable tape systems occupy niche positions in bakery wrap applications with intermediate opening frequency requirements. Limited penetration reflects adhesive migration concerns under EU food contact frameworks.
Equipment investment is heaviest in Zipper. Lowest capital burden sits with Tie.
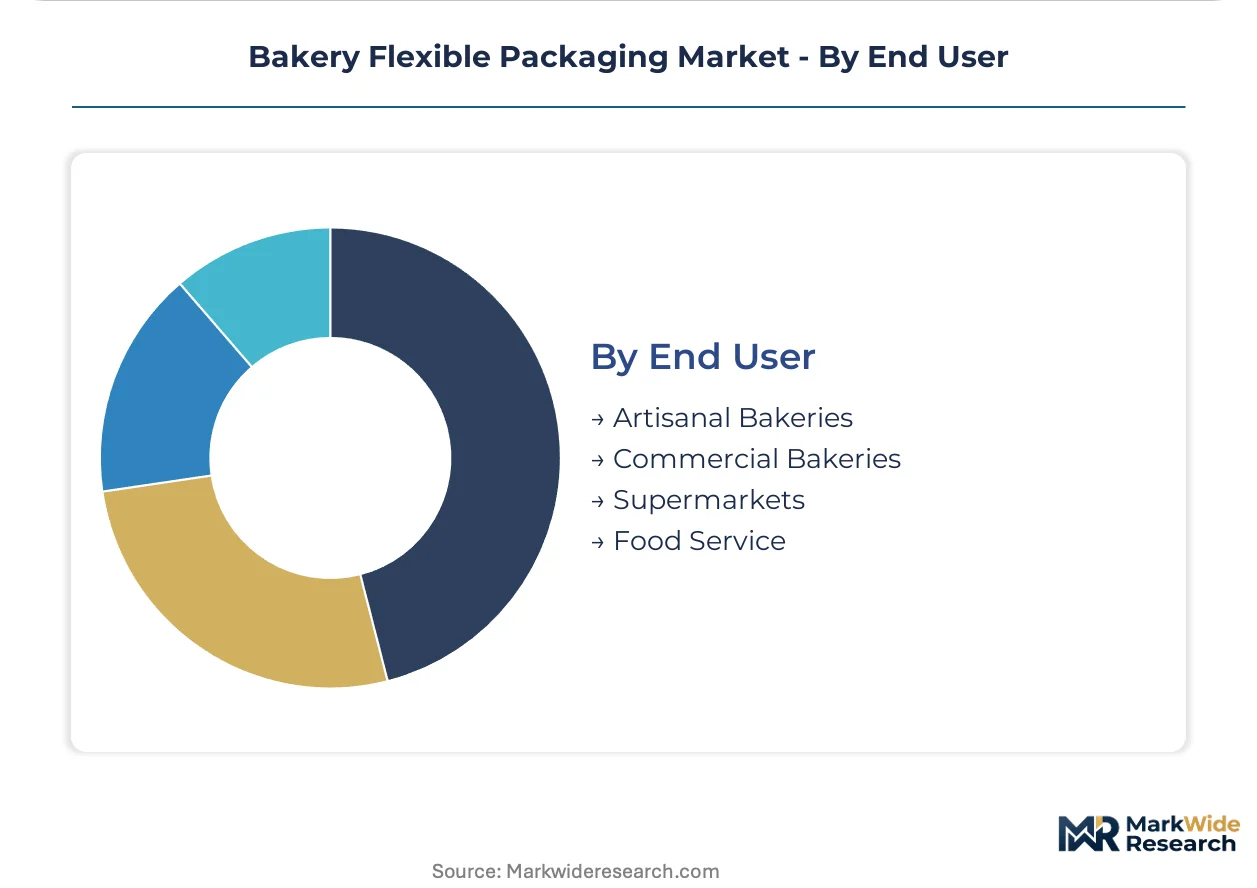
End User:
Procurement scale and specification authority determine supplier relationship structures across the demand base.
- Supermarkets:Centralized buying desks in German and Dutch retail chains consolidate flexible packaging procurement under single-source technical service agreements bundling film specification, graphic design, and inventory management. Resealable pouch formats with unified EAN coding are now mandatory.
- Commercial Bakeries:Pan-European industrial bakery groups leverage volume concentration to secure long-term film supply contracts with barrier specification customization. Extended shelf-life bread lines for private-label distribution drive high-barrier pouch adoption.
- Artisanal Bakeries:Fragmented procurement through distributor intermediaries persists despite gradual consolidation. Paper-based and kraft-flexible hybrid formats dominate where tactile differentiation supports premium positioning in French and Austrian markets.
- Food Service:Frozen dough and par-baked pastry distribution to hotels and catering operations favors rigid tray substitution for stacking efficiency. Flexible format retention concentrates in individually wrapped portion control applications.
Contract sophistication peaks with Supermarkets. Fragmentation persists in Artisanal Bakeries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyethylene resin production clusters in the US Gulf Coast and Middle East feedstock corridors anchor flexible packaging supply geography, while converter operations concentrate near industrial bakery demand centers in Western Europe and East Asia.
Germany
Industrial bakery output in Lower Saxony and North Rhine-Westphalia sustains premium flexible packaging procurement at scale. The EU Packaging and Packaging Waste Regulation tightens recyclability mandates for mono-material structures. Converter operations in the Rhine-Ruhr cluster retool lamination assets toward zipper-compatible pouch formats for extended shelf-life bread distribution.
United States
Commercial bakery consolidation across the Midwest and Southeast drives specification standardization for high-barrier films. FDA food contact notification requirements govern import eligibility for European suppliers, creating divergent formulation pathways. The Chicago-Joliet-Naperville corridor hosts concentrated flexible packaging converter capacity serving pan-regional bread and pastry distribution networks.
France
Artisanal bakery premiumization in Île-de-France and Auvergne-Rhône-Alpes sustains demand for paper-flexible hybrid formats. Extended producer responsibility schemes pilot deposit-return models for flexible food packaging that reward mono-material design. Lyon-based converter operations specialize in tactile-differentiated kraft substrates for macaron and viennoiserie gift applications.
China
Industrial bakery expansion in the Yangtze River Delta and Pearl River Delta compresses lead times for flexible packaging procurement. National standards under SAMR govern food contact materials, while dual carbon goals redirect investment toward bio-based coating technologies. Shanghai converter clusters supply both domestic bakery chains and export-oriented frozen dough processors.
Japan
Premium pastry distribution in the Kanto and Kansai regions demands puncture-resistant multilayer structures for frozen patisserie. METI guidelines on plastic resource circulation accelerate mono-material R&D investment. Osaka-based converter operations serve convenience store bakery supply chains with high-barrier specifications for extended shelf-life croissant formats.
Bakery Flexible Packaging Market Competitive Environment
Capacity expansion dominates the current landscape as converters reconfigure solvent-based adhesive lines toward extrusion coating and thermal lamination equipment. The vendor base stratifies across integrated multinational film manufacturers, regional converter specialists, and paper-based hybrid format developers. Three archetypes define competitive positioning: global film producers with captive resin access, European converters with integrated kraft paper operations, and Asian specialists in high-speed pouch forming. M&A activity and strategic partnerships concentrate around zipper technology licensing and mono-material certification capabilities.
Among integrated multinational suppliers, Amcor plc exemplifies the global film manufacturing archetype through its pan-regional production footprint. Mondi occupies a position within the European paper-flexible hybrid tier, leveraging integrated kraft paper and barrier film operations. Huhtamaki anchors the molded fiber-flexible convergence segment, representing specialized format development for premium pastry applications.
| Leading Market Players |
|---|
| Amcor plc |
| Mondi |
| Huhtamaki |
| Smurfit Westrock |
| Sealed Air |
| Transcontinental Inc. |
| Constantia Flexibles |
| International Paper |
| TOPPAN Holdings Inc. |
| Others |
Value Chain & Pricing Dynamics
Supermarket private-label consolidation under technical service agreements is forcing film converters to bundle specification, design, and inventory services, compressing spot-market pricing and rewarding scale-backed suppliers with captive resin access and plasma coating capacity.
Pricing Analysis
Technical service bundling separates integrated multinational suppliers from regional converters lacking in-house graphic design and inventory management capabilities. Three-tier pricing structure across premium, standard, and economy levels tracks barrier specification intensity, with nylon-reinforced multilayer structures commanding premiums over monolayer polyethylene. Pricing pressure stems from ethylene and propylene feedstock volatility transmitted through naphtha cracking margins. Commercial bakeries exhibit highest price sensitivity due to volume procurement and private-label margin constraints, while artisanal segments accept premiums for tactile-differentiated kraft-flexible hybrids.
Supply Chain Analysis
Freight cost differentials favor converter operations proximate to industrial bakery demand centers in Germany, France, and the Netherlands over resin import-dependent peripheral markets. Feedstock draws from US Gulf Coast and Middle East polyethylene production corridors, with converter margins tethered to naphtha cracking economics. Raw material dependencies center on linear low-density polyethylene grades, cast polypropylene films, and polyamide resins for multilayer structures. Single-source vulnerability concentrates in plasma-enhanced barrier deposition equipment. Distribution runs through pan-European logistics networks serving centralized supermarket buying desks and commercial bakery groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Packaging and Packaging Waste Regulation recyclability mandates are accelerating converter consolidation, as mono-material certification timelines and asset reconfiguration costs force exit of mid-tier solvent-based adhesive operators lacking extrusion coating capacity.
For Market Incumbents: Anchor market position through backward integration into kraft paper operations or captive resin supply agreements that insulate margin structures from feedstock volatility. Prioritize zipper-compatible pouch capacity expansion in Rhine-Ruhr and Lower Saxony clusters to capture supermarket private-label consolidation. Defend against molded fiber substitution in frozen patisserie by accelerating plasma-enhanced mono-material qualification ahead of deposit-return scheme implementation. For New Entrants and Emerging Players: EU F-Gas Regulation in Europe opens a window for bio-based barrier coating specialists to capture share in premium pastry applications where fluorinated chemistry phase-out creates specification gaps. Target artisanal bakery segments in France and Austria with paper-flexible hybrid formats that bypass incumbent polyethylene scale advantages. Pursue technical service agreement partnerships with regional supermarket chains seeking secondary supplier diversification beyond single-source procurement. For Investors and Strategic Acquirers: The window for entry favors converters with mono-material certification capabilities and zipper technology licensing positions. Long-term viability hinges on exposure to deposit-return scheme eligibility and plasma coating asset bases. Acquisition target archetype: mid-tier German or Austrian converters with established artisanal bakery relationships and underutilized extrusion coating lines. Watch for inflection in French and German EPR pilot program expansion as signal for accelerated mono-material specification mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Certification Investment | RecyClass and How2Recycle approvals unlock deposit-return scheme eligibility in France and Germany. |
| Plasma Barrier Coating Capacity Addition | Rhine-Ruhr converter clusters capture supermarket private-label resealable pouch specifications. |
| Kraft Paper Integration | Mondi-style hybrid operations serve artisanal premiumization in Île-de-France and Auvergne-Rhône-Alpes. |
| Zipper Technology Licensing | Press-to-close profile partnerships accelerate line-speed compatibility for extended shelf-life bread formats. |
| Bio-Based Coating R&D Partnership | Cellulose nanofibril and chitosan development addresses EU F-Gas Regulation fluorinated chemistry constraints. |
Study Parameters
Trade association publications from Flexible Packaging Europe, regulatory filings under EU Packaging and Packaging Waste Regulation, and converter capacity databases formed the secondary backbone. Primary interviews with procurement directors at German and Dutch supermarket chains, technical directors at Rhine-Ruhr film converters, and sustainability officers at pan-European bakery groups validated specification trend assumptions. Bottom-up volume estimates from product-type and material segmentation were triangulated against top-down macroeconomic indicators across the analysis window.
Historical trendline analysis of industrial bakery output, flexible packaging procurement volumes, and resin price indices established baseline growth patterns. The analytical framework modeled segmentation across product type, material chemistry, closure configuration, and end-user procurement structure throughout the forecast period. CAGRs were derived from regression analysis of segment-level drivers including resealable pouch adoption rates, mono-material infrastructure readiness, and regulatory compliance timelines. Forecast inputs incorporated EU F-Gas Regulation phase-down schedules and deposit-return scheme pilot expansion trajectories.
The model assumes a particular technology adoption path; alternative pathways for bio-based barrier coatings achieving oxygen transmission parity with nylon-reinforced structures would alter the outlook for multilayer film demand. Forecasts reflect underlying assumptions about regulatory enforcement intensity and sorting infrastructure investment timing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
APAC Flexible Packaging Market
Flexible Packaging
Flexible Food Packaging Market
Flexible Packaging
Flexible Packaging Paper Market
Flexible Packaging
Kenya Flexible Packaging Market
Flexible Packaging
Nigeria Flexible Packaging Market
Flexible Packaging
Africa Flexible Packaging Market
Flexible Packaging
Mexico Flexible Plastic Packaging Market
Flexible Packaging
United States Flexible Plastic Packaging Market
Flexible Packaging
Converted Flexible Packaging Market
Flexible Packaging
Europe Flexible Packaging Market
Flexible Packaging
Argentina Flexible Plastic Packaging Market
Flexible Packaging
Indonesia Flexible Plastic Packaging Market
Flexible Packaging
Flexible Bottle Market
Flexible Packaging
Russia Flexible Plastic Packaging Market
Flexible Packaging
Morocco Flexible Packaging Market
Flexible Packaging
UK Flexible Plastic Packaging Market