
 48V Mild Hybrid Battery Pack Systems Market | 2026-2036
48V Mild Hybrid Battery Pack Systems Market Size, Share, and Industry Trends Forecast 2026-2036
48V Mild Hybrid Battery Pack Systems Market Insights
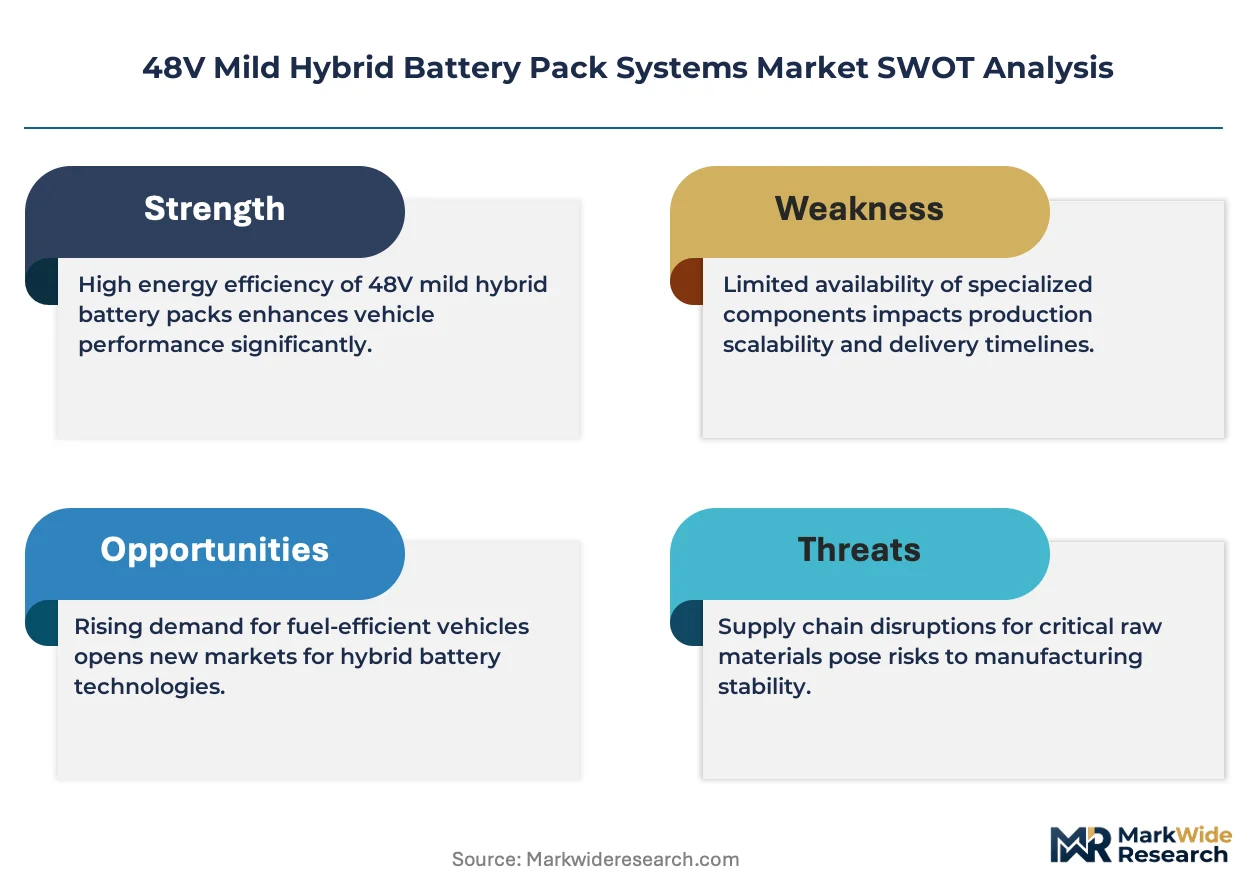
Modular battery pack configurations are expanding buyer choice as automakers unbundle thermal management from cell modules to mix-and-match subsystems across vehicle platforms. Robert Bosch leverages its power electronics integration to anchor premium tier-1 supply contracts. Continental AG sustains R&D intensity in cell balancing architectures. Samsung SDI competes on cylindrical cell formats optimized for 48V duty cycles.
A 48V mild hybrid battery pack system integrates lithium-ion or nickel-metal hydride cells with battery management, thermal control, and power electronics into a sub-60V architecture that enables torque assist, regenerative braking, and electrical load handling without full hybrid cost. Cell chemistry selection directly determines cycle life and cold-crank performance under partial-state-of-charge operation. Lithium-ion configurations lead volume shipments due to energy density advantages in passenger vehicle applications. Power electronics segments capture concentrated margin pools as inverter-integration complexity rises. Solid-state chemistries represent the fastest-growing technology category though from a narrow commercial base.
EPA tailpipe standards, EU CO2 fleet regulations, and China's MEE dual carbon framework collectively mandate emissions reductions that 48V systems cost-effectively address. NHTSA fuel economy rules and ECE R100 safety standards further shape product certification requirements and market access conditions. Stakeholders must monitor cell chemistry cost curves against regulatory stringency trajectories to time capacity commitments.
Market Dynamics
EU CO2 fleet standards and China's dual carbon goals are compressing OEM decision timelines, forcing 48V mild hybrid architectures from optional efficiency add-ons to mandatory compliance infrastructure across passenger vehicle platforms.
Growth Catalysts
- EU CO2 fleet regulations:Binding 2035 fleet-average targets mandate electrification pathways that 48V systems cost-effectively bridge for internal combustion platforms.
- China's MEE dual carbon framework:Provincial implementation timelines accelerate domestic OEM procurement of mild hybrid battery packs to avoid production penalties.
- Cell chemistry energy density gains:Lithium-ion configurations achieve sufficient duty-cycle performance to displace nickel-metal hydride in volume passenger applications.
Market Restraints
- Cell raw material volatility:Lithium carbonate and nickel price swings compress pack margins and destabilize long-term supply contracts.
- Thermal management subsystem concentration:Specialized coolant circuit suppliers cluster in Germany and South Korea, creating geographic chokepoints.
- High-voltage safety certification friction:ECE R100 testing protocols extend product validation timelines by 8-14 months for new entrants.
Strategic Opportunities
- India's FAME-II subsidy extension:Central government incentives for mild hybrid commercial vehicles open fleet procurement channels previously closed to 48V architectures.
- Solid-state chemistry convergence:Emerging sulfide-electrolyte formats promise cycle life improvements that could redefine pack warranty economics.
- Direct OEM battery management integration:Automakers are in-sourcing BMS firmware development, creating tier-1 supplier openings for bare cell and thermal module provision.
Industry Challenges
- Power electronics firmware talent scarcity:Inverter-control algorithm development faces acute competition from battery electric and full-hybrid programs.
- Legacy 12V electrical architecture integration:DC-DC converter placement and load balancing complexity multiplies validation cycles for platform engineers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 48V Mild Hybrid Battery Pack Systems Market |
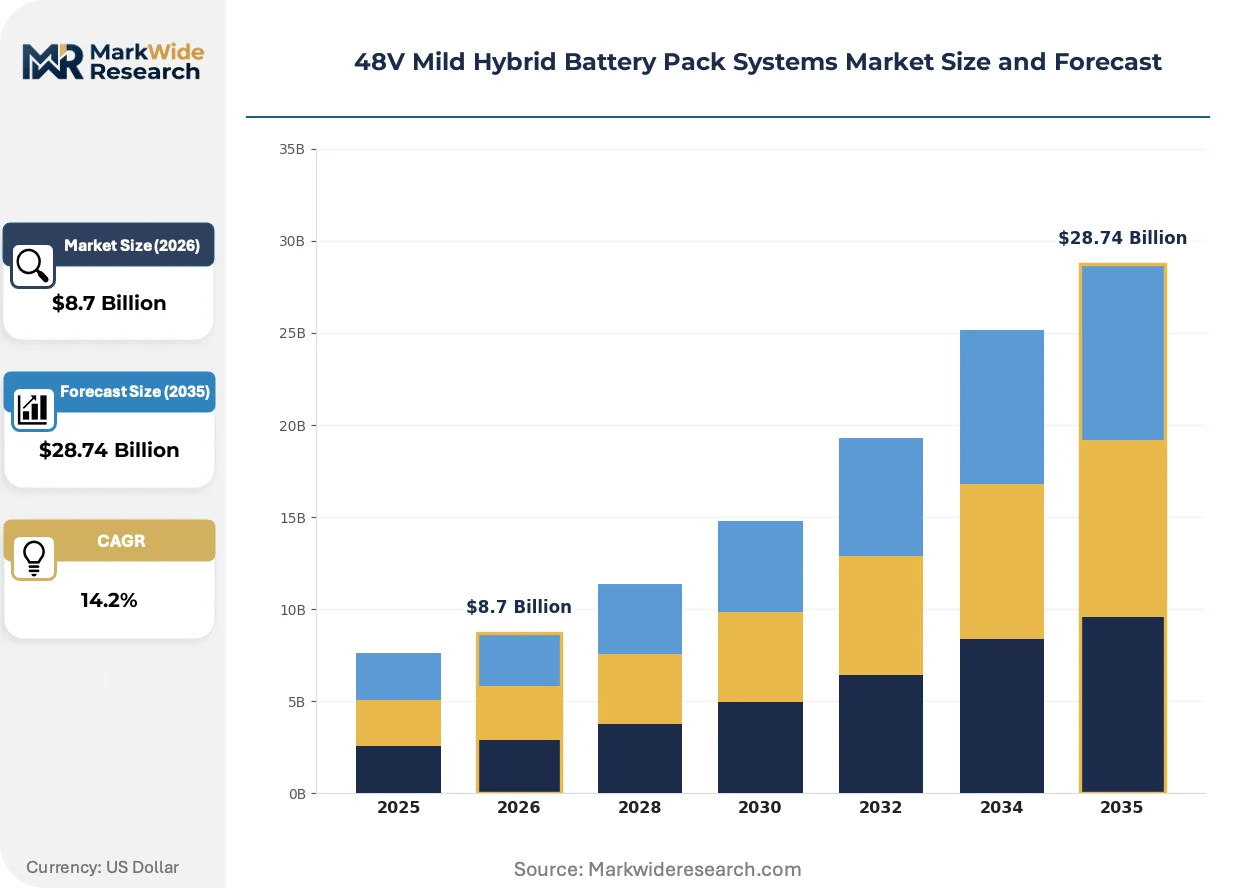
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion, Nickel-Metal Hydride, Lead-Acid, Solid-State Technology: Battery Management System, Cell Balancing, Thermal Management, Power Electronics Application: Passenger Vehicles, Commercial Vehicles, Electric Bicycles, Off-Road Equipment End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Robert Bosch, Continental AG, ZF Friedrichshafen AG, Valeo, LG Energy Solution, Samsung SDI, Panasonic Holdings, BYD Company, Hitachi Astemo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
48V Mild Hybrid Battery Pack Systems Market Trends and Innovations
Cell-to-pack architectures are collapsing traditional module boundaries, while solid-state electrolyte research accelerates and OEMs restructure procurement relationships around subsystem unbundling.
Silicon-anode lithium-ion formulations are electrifying energy density trajectories in 48V duty-cycle applications. Tier-1 suppliers are qualifying these chemistries for 2027 platform introductions. The technology is electrifying competitive positioning by enabling smaller pack footprints without sacrificing cold-crank performance.
EPA tailpipe standards under the current administration are tightening fleet-average calculations in ways that elevate 48V mild hybrid credits. Automotive engineering teams are recalibrating powertrain portfolios to maximize these credits. North American passenger vehicle platforms are responding with accelerated 48V system integration timelines.
Fleet procurement offices are consolidating battery pack sourcing decisions at the group level rather than delegating to individual brand engineering teams. This buyer concentration is compressing supplier negotiation cycles and favoring tier-1s with multi-platform certification portfolios. Germany and Japan exhibit the most pronounced procurement centralization.
48V Mild Hybrid Battery Pack Systems Market Segmentation
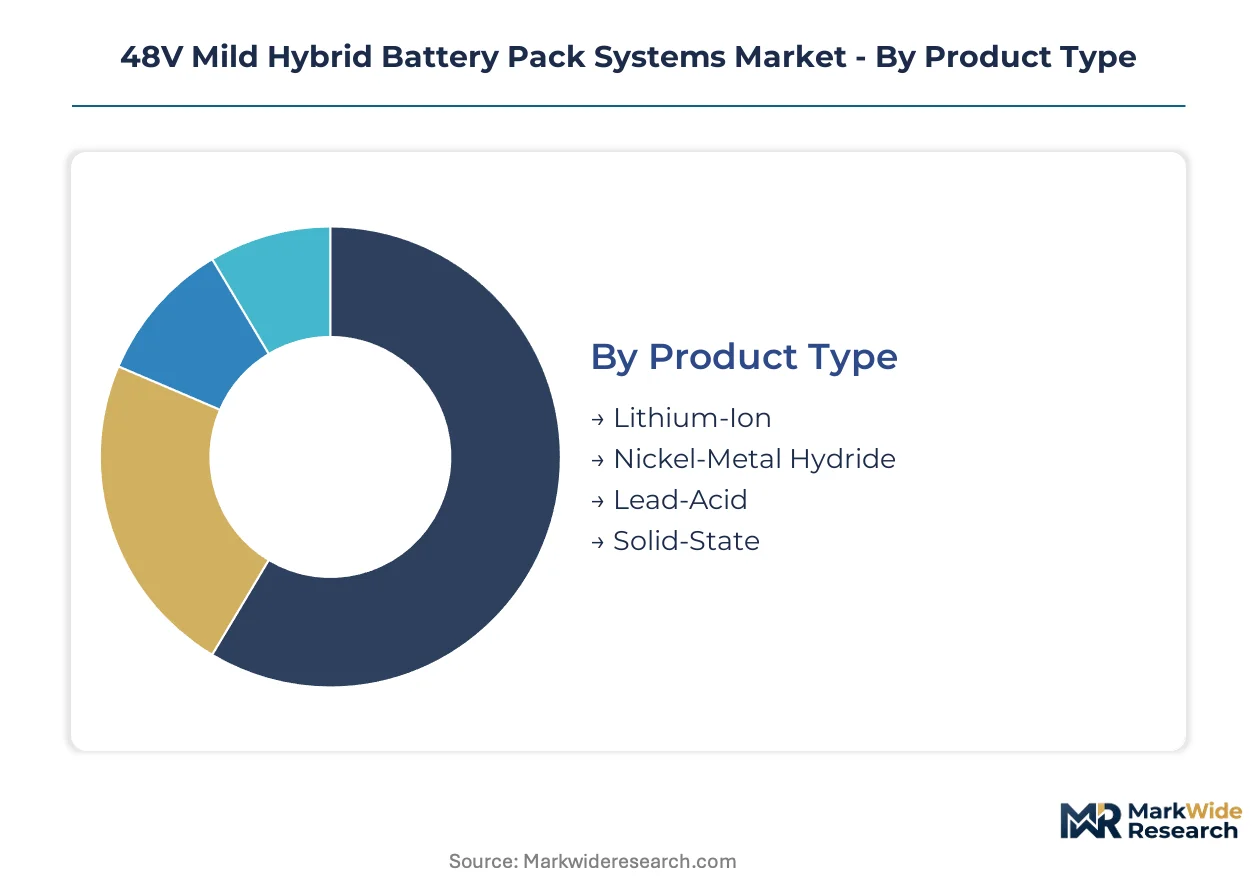
48V mild hybrid battery pack systems fragment across chemistry choices, subsystem technologies, vehicle applications, and procurement channels. Each segmentation axis carries distinct margin structures, certification requirements, and competitive dynamics that shape supplier positioning strategies.
Product Type:
Lithium-ion and nickel-metal hydride chemistries dominate embedded powertrain integration, while lead-acid persists in standalone retrofit configurations and solid-state formats target next-generation platform designs.
- Lithium-Ion:NMC and LFP cathode formulations deliver the energy density thresholds required for passenger vehicle torque-assist duty cycles. Demand clusters in Germany and South Korea where OEMs face binding EU CO2 fleet standards and domestic emissions regulations. Cell suppliers compete on cold-crank performance under partial-state-of-charge operation.
- Nickel-Metal Hydride:Mature chemistry retains cost advantages in commercial vehicle applications with less stringent packaging constraints. Toyota and Honda legacy hybrid programs in Japan sustain procurement volumes despite lithium-ion displacement pressure.
- Lead-Acid:Absorbent glass mat variants serve aftermarket retrofit channels and emerging market price-sensitive segments.
- Solid-State:Sulfide-electrolyte prototypes from Samsung SDI and QuantumScape target 2027-2028 platform introductions with cycle life warranties exceeding lithium-ion benchmarks.
Volume placements concentrate in lithium-ion; the faster expansion belongs to solid-state.
Technology:
Subsystem unbundling is redistributing value capture across battery management, thermal control, and power electronics as OEMs in-source firmware development.
- Battery Management System:State-of-charge algorithms and cell monitoring circuits determine pack safety certification under ECE R100. Continental AG and Robert Bosch anchor tier-1 supply for BMS hardware while automakers capture firmware margins.
- Power Electronics:Inverter-integration complexity concentrates margin pools as DC-DC converter placement multiplies validation cycles for platform engineers. Silicon carbide semiconductor adoption is climbing the fastest in this subsystem category.
- Thermal Management:Liquid coolant circuits and active heating elements protect cell longevity across temperature extremes. German and South Korean suppliers cluster around automotive production hubs.
- Cell Balancing:Active and passive balancing architectures manage voltage drift across series-connected cells. R&D intensity focuses on reducing energy dissipation during charge equalization.
Procurement concentrates in battery management systems; power electronics shows the steepest margin expansion trajectory.
Application:
Passenger vehicle platforms generate scale economies that subsidize technology development for niche commercial and off-road segments.
- Passenger Vehicles:C-segment and D-segment sedans integrate 48V systems as standard equipment to meet EU CO2 fleet standards and China's MEE dual carbon framework. European and Chinese OEM procurement timelines compress supplier certification windows.
- Commercial Vehicles:Light-duty trucks and delivery vans adopt mild hybrid architectures under India's FAME-II subsidy extension for fleet electrification pathways.
- Electric Bicycles:European urban mobility regulations drive 48V adoption in speed-pedelec categories requiring type approval.
- Off-Road Equipment:Construction and agricultural machinery applications remain nascent with limited regulatory pressure relative to on-road segments.
Passenger vehicles dominate unit placements; commercial vehicles are gaining share fastest as fleet procurement centralizes.
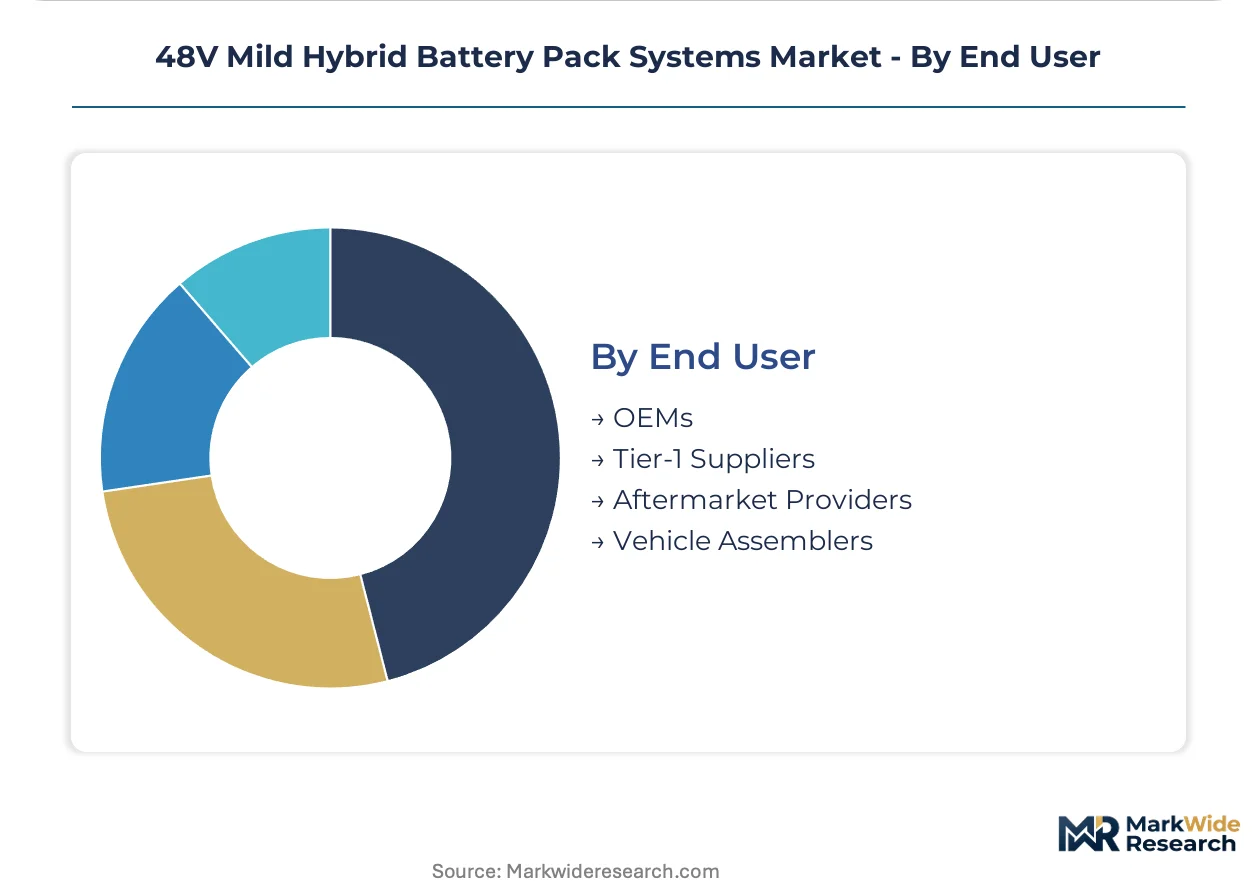
End User:
Procurement authority is migrating upstream from brand engineering teams to group-level battery sourcing offices, restructuring supplier relationship dynamics.
- OEMs:Volkswagen Group, Stellantis, and Hyundai Motor consolidate 48V pack sourcing decisions at holding company level. Multi-platform certification portfolios determine tier-1 supplier selection.
- Tier-1 Suppliers:Robert Bosch, Continental AG, and Denso integrate cells with thermal management and power electronics for direct OEM delivery. Margin pressure intensifies as automakers unbundle subsystems.
- Aftermarket Providers:Independent distributors serve vehicle retrofit channels and replacement demand in markets with aging fleet populations.
- Vehicle Assemblers:Contract manufacturers in emerging markets source complete 48V systems for localized production platforms.
Procurement volume concentrates with OEMs; tier-1 suppliers face the most acute margin compression as integration scope narrows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and China concentrate 48V system production capacity while the United States and Japan generate disproportionate technology development investment. Domestic automotive assembly clusters in South Korea and India are emerging as procurement growth poles.
Germany
Volkswagen Group and BMW procurement offices in Munich and Wolfsburg consolidate multi-brand 48V sourcing decisions under holding-company battery strategies. EU CO2 fleet standards mandate 2035 compliance pathways that 48V architectures bridge for remaining internal combustion platforms. Stuttgart and Ingolstadt production clusters anchor Robert Bosch and Continental AG supply relationships.
China
Geely, BYD, and SAIC Motor integrate 48V systems across C-segment and D-segment platforms to meet provincial MEE dual carbon implementation timelines. The dual carbon framework accelerates domestic OEM procurement to avoid production penalties in Shanghai and Guangdong. Yangtze River Delta battery pack assembly concentrates LG Energy Solution and CATL cell supply relationships.
United States
Ford and General Motors engineering teams recalibrate powertrain portfolios to maximize 48V mild hybrid credits under tightening EPA tailpipe standards. NHTSA fuel economy rules shape product certification requirements for Detroit platform introductions. Michigan and Ohio production clusters source power electronics from tier-1 suppliers with multi-platform certification portfolios.
Japan
Toyota and Honda sustain nickel-metal hydride procurement volumes for legacy hybrid programs while lithium-ion displacement pressure intensifies. METI industrial policy supports solid-state electrolyte research targeting 2027-2028 platform introductions. Nagoya and Tokyo engineering centers concentrate cell balancing architecture R&D for next-generation 48V duty cycles.
South Korea
Hyundai Motor and Kia consolidate 48V pack sourcing at holding-company level, compressing supplier negotiation cycles for domestic production platforms. Domestic emissions regulations parallel EU stringency trajectories. Seoul and Ulsan automotive clusters anchor Samsung SDI cylindrical cell format supply to tier-1 integrators.
48V Mild Hybrid Battery Pack Systems Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across three distinct supplier tiers. Tier-1 integrators capture system-level contracts by combining cells with thermal management and power electronics. Cell manufacturers compete on chemistry format and energy density trajectories. Technology licensors extract value from battery management firmware and inverter-control algorithms. Capacity expansion and strategic partnerships constitute the dominant competitive moves as OEMs unbundle subsystem procurement.
Within the diversified conglomerate tier, Robert Bosch and Continental AG exemplify full-system integration capabilities spanning power electronics, thermal management, and battery management hardware. Samsung SDI occupies a position among cell-specialist suppliers competing on cylindrical format optimization for 48V duty cycles. These three entities represent distinct archetypes: the German diversified industrial, the European automotive tier-1, and the Korean battery cell fabricator.
| Leading Market Players |
|---|
| Robert Bosch |
| Continental AG |
| ZF Friedrichshafen AG |
| Valeo |
| LG Energy Solution |
| Samsung SDI |
| Panasonic Holdings |
| BYD Company |
| Hitachi Astemo |
| Others |
Pricing and Supply Chain Analysis
OEM procurement office consolidation at Volkswagen Group, Stellantis, and Hyundai Motor compresses supplier negotiation cycles and forces tier-1 integrators to absorb margin compression or cede contracts to competitors with multi-platform certification portfolios.
Pricing Analysis
Cost-down pressure on tier-1 integrators accelerates because automakers unbundle thermal management and power electronics from cell modules to mix-and-match subsystems. Three-tier pricing structure across premium, standard, and economy levels separates certified suppliers with ECE R100 validation from uncertified entrants and aftermarket retrofit providers. Price differentiation traces to certification grade under EU CO2 fleet standards and volume scale commitments from holding-company procurement offices. Fleet procurement offices exhibit highest price sensitivity; premium passenger vehicle platforms retain pricing power for silicon-anode lithium-ion configurations.
Supply Chain Analysis
ECE R100 safety certification creates an eight-to-fourteen-month validation gate that filters new entrants and concentrates supply relationships among incumbent tier-1s with existing regulatory dossiers. Cell production clusters in China, South Korea, and Germany anchor global supply, with cylindrical formats from Samsung SDI and prismatic cells from CATL feeding tier-1 integrators. Raw material dependencies rest on lithium carbonate, nickel sulfate, and silicon anode precursors. Single-source vulnerability around German and South Korean thermal management subsystem suppliers elevates geographic concentration risk. Distribution runs through direct OEM contracts rather than spot-market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around suppliers with multi-platform certification portfolios as ECE R100 validation timelines and cell chemistry R&D intensity force weaker players toward exit or acquisition.
For Market Incumbents: Deploy backward integration into silicon anode precursor supply to secure cost positions against lithium-ion chemistry commoditization. Lock in multi-year thermal management subsystem contracts with German and South Korean suppliers before geographic chokepoints harden. Anchor premium tier-1 positioning through power electronics firmware talent acquisition from battery electric and full-hybrid programs. For New Entrants and Emerging Players: India's FAME-II subsidy extension for mild hybrid commercial vehicles opens a window for fleet procurement channel entry with lower certification friction than passenger vehicle platforms. Target aftermarket retrofit channels in European markets with aging fleet populations requiring 48V system replacements. Pursue bare cell and thermal module provision as automakers in-source battery management system firmware development. For Investors and Strategic Acquirers: The window for entry favors tier-1 integrators with dormant ECE R100 certifications and underutilized power electronics capacity across the analysis window. Solid-state chemistry convergence signals inflection timing; sulfide-electrolyte prototype qualification by Samsung SDI and QuantumScape indicates when lithium-ion displacement pressure will accelerate. Monitor provincial MEE dual carbon implementation timelines in China for demand trajectory confirmation.| Strategic Initiative | Industry Significance |
|---|---|
| Cell Chemistry Vertical Integration | Captures margin pools in silicon anode and solid-state electrolyte development. |
| Multi-Platform Certification Investment | Unlocks holding-company procurement contracts at Volkswagen Group and Stellantis. |
| Thermal Management Subsystem Unbundling | Enables mix-and-match procurement for OEM platform engineers. |
| Firmware Talent Acquisition | Addresses acute scarcity in inverter-control algorithm development. |
| Emerging Market Fleet Partnership | Secures FAME-II subsidy capture in India's commercial vehicle segment. |
Research Methodology
Multi-period observation of vehicle production databases, OEM procurement timelines, and cell chemistry cost curves anchored the trend analysis, supplemented by interviews with tier-1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and thermal management subsystem specialists. Secondary validation drew from IHS Markit registration data, EPA tailpipe standard filings, EU CO2 fleet compliance disclosures, and SEC 10-K filings from diversified industrial conglomerates. Bottom-up segment sizing triangulated against top-down market aggregation.
The input-output matrix mapped vehicle class, propulsion architecture, content per vehicle, and regional production cluster against cell chemistry adoption trajectories over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation. Forecast inputs included EU CO2 fleet standard stringency trajectories, China's MEE dual carbon provincial implementation timelines, and silicon anode energy density improvement curves.
The model assumes a particular technology adoption path; alternative pathways for solid-state electrolyte commercialization would alter the outlook. Forecasts reflect assumptions about ECE R100 certification timeline stability and lithium carbonate price volatility. A model refresh is warranted upon material change in EU CO2 fleet standard enforcement or solid-state chemistry prototype qualification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Solar Powered Electric Vehicle Market
Electric Vehicles
France Automotive High Performance Electric Vehicles Market
Electric Vehicles
Global Industrial Electric Vehicle Market
Electric Vehicles
Railway Lithium Battery Market
Electric Vehicles
North America Electric Vehicle (EV) Fluids Market
Electric Vehicles
China Electric Car Market
Electric Vehicles
Electric Vehicle Electric Heating Film Market
Electric Vehicles
EV Thermal System Market
Electric Vehicles
Indian E-Bike Rental Market
Electric Vehicles
India Electric Rickshaw Market
Electric Vehicles
Oman Electric Vehicle (EV) Market
Electric Vehicles
Middle East Electric Vehicle Market
Electric Vehicles
North America Automotive Battery Thermal Management System Market
Electric Vehicles
Mexico Electric Bus Market
Electric Vehicles
Australia Electric Vehicle Market
Electric Vehicles
E-Bike Battery Market