
 Europe Electric Bus Market | 2026-2036
Europe Electric Bus Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electric Bus Market Intelligence
Municipal transit authorities is reorganizing procurement priorities away from peripheral rural operators toward dense metropolitan networks. Solaris Bus & Coach leverages its Polish manufacturing base to dominate Central European tender awards. Volvo Buses anchors Nordic electrification through depot-charging integration with municipal utilities. BYD Auto competes on battery cost structures, sustaining price pressure across mid-volume contracts.
Europe electric bus denotes a battery-electric or fuel-cell-electric passenger vehicle exceeding ten meters in length, typically employing lithium-ion packs with 250-450 kWh capacity and regenerative braking systems, purpose-built for scheduled urban and interurban mass transit. Single-deck configurations occupy the dominant share of current deliveries, while articulated variants capture expanding share in high-ridership corridors where platform length restrictions ease. Fast charging infrastructure concentrates margin pools with grid-integration specialists, whereas depot charging sustains volume leadership through lower capital intensity and overnight scheduling flexibility.
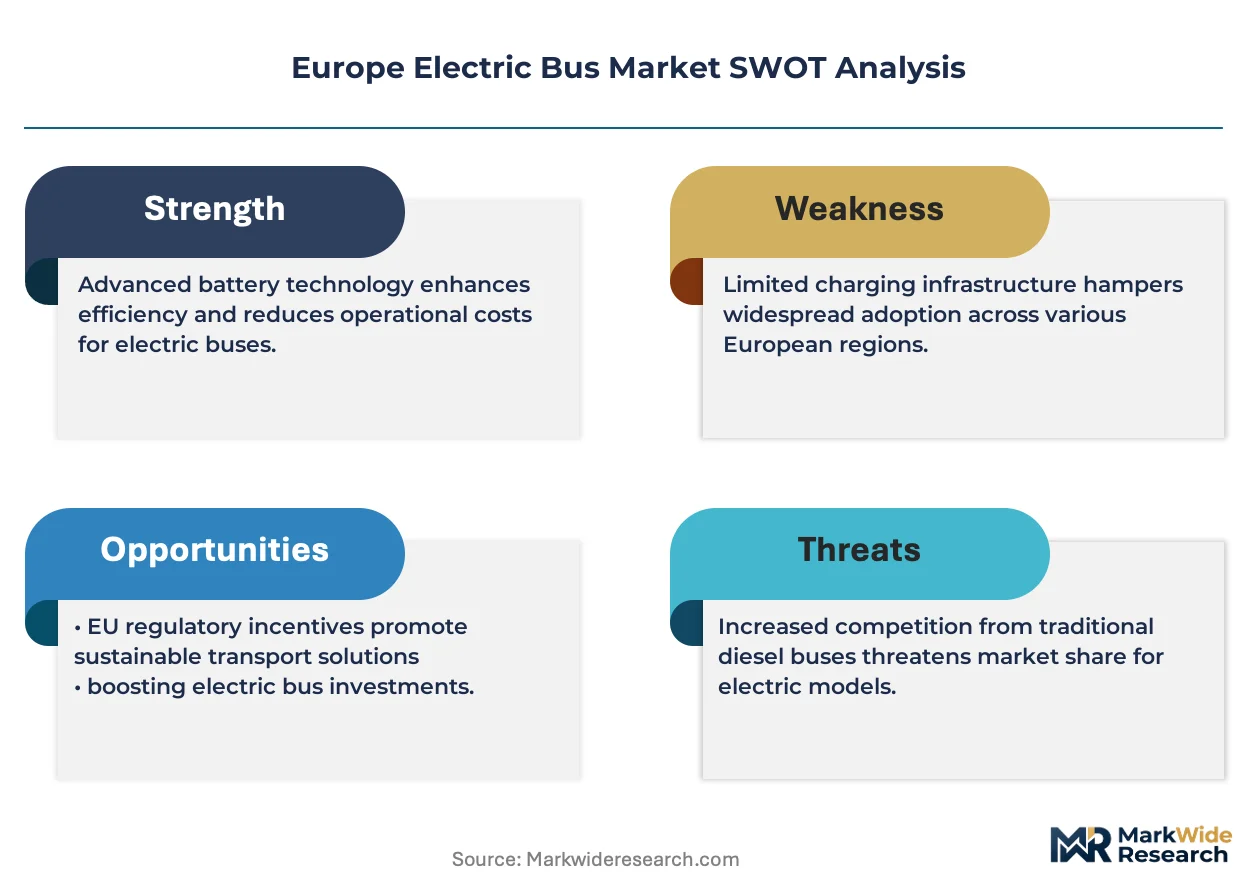
The EU Green Deal, F-Gas Regulation, and CE marking framework collectively mandate zero-emission fleet thresholds and battery safety certification, binding manufacturers to standardized electromagnetic compatibility and fire-suppression protocols. EMA and national type-approval bodies enforce these standards through market-access preconditions that filter out non-compliant suppliers. Stakeholders must monitor how the EU AI Act's forthcoming autonomous-vehicle provisions reshape software validation requirements and liability allocation across OEM-tier supplier contracts.
Market Dynamics
Fleet electrification across the Rhine-Ruhr corridor and Nordic capitals is compressing tender cycles, forcing municipal transit authorities to restructure procurement around battery lifecycle guarantees rather than upfront vehicle cost.
Growth Catalysts
- EU Green Deal binding thresholds:Mandatory zero-emission fleet quotas for urban transit operators accelerate replacement schedules and lock in multi-year electrification budgets.
- Lithium-ion pack cost curves:Declining cell prices enable 450 kWh configurations at parity with mid-life diesel refurbishment cycles.
- Depot-charging infrastructure:Grid-integration partnerships with municipal utilities in Germany and the Netherlands secure overnight capacity at fixed tariffs.
Market Restraints
- Cathode material concentration:European cell manufacturers depend on processed lithium hydroxide from limited refining capacity in Portugal and Finland.
- Grid connection queues:Distribution network operators in France and Italy impose 18-24 month lead times for megawatt-scale depot upgrades.
- F-Gas Regulation compliance costs:Thermal management system redesigns to eliminate potent greenhouse gas refrigerants add certification overhead for HVAC suppliers.
Strategic Opportunities
- Polish manufacturing expansion:Central European production bases serve tender awards across the Visegrád corridor with shortened delivery windows.
- Vehicle-to-grid integration:Bidirectional charging protocols transform parked bus fleets into grid-balancing assets for national transmission operators.
- EU AI Act autonomous provisions:Software validation frameworks for driver-assistance systems create first-mover advantages in Level-4 depot automation.
Industry Challenges
- Battery engineering talent scarcity:Thermal runaway containment and cell balancing expertise concentrates among a handful of Tier-1 system integrators.
- Type-approval timeline compression:EMA and KBA certification pathways for new pack architectures extend 8-14 months beyond diesel equivalents.
- Legacy depot retrofit complexity:Urban depots built for 1980s fleets require structural reinforcement to support 40-tonne battery-electric axle loads.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electric Bus Market |
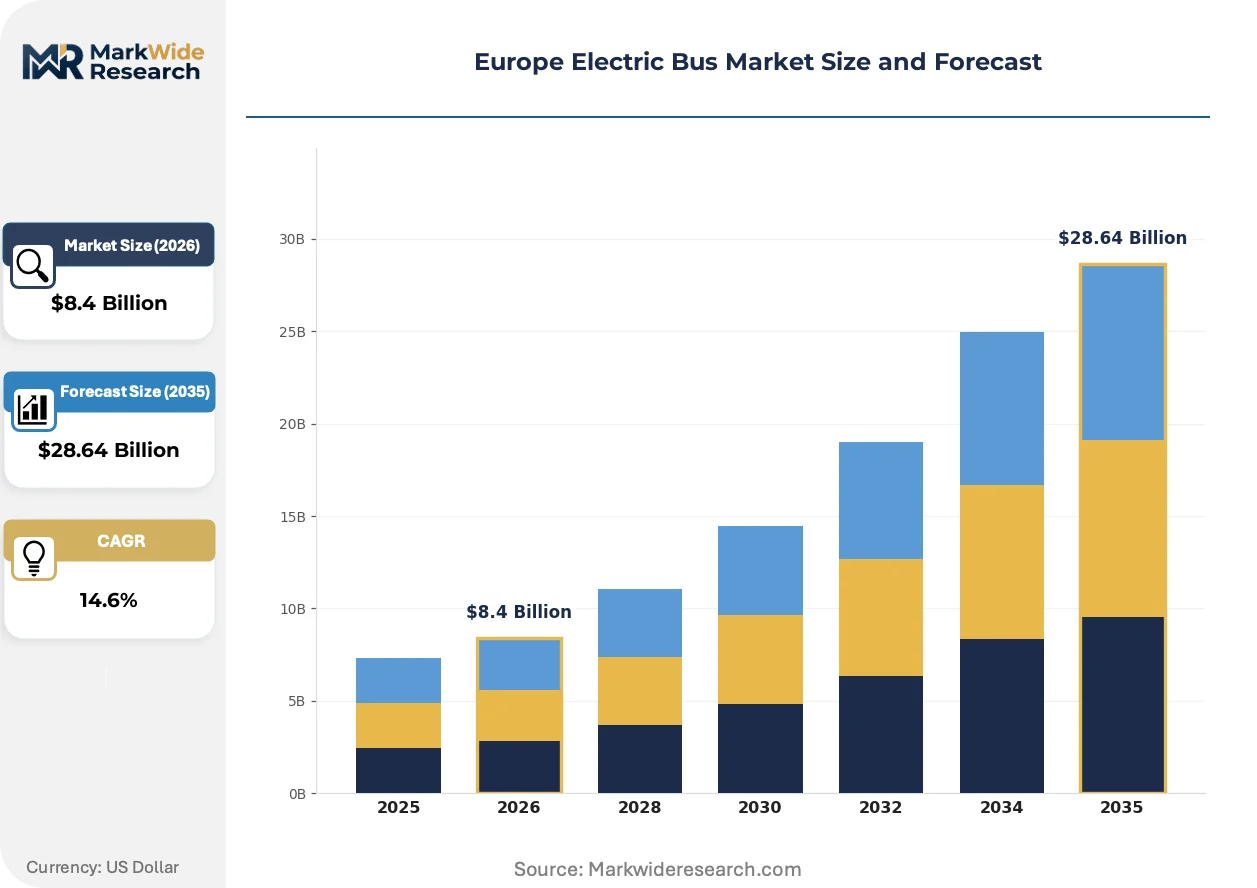
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $28.64 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Bus Type: Single-deck, Double-deck, Articulated, Mini Charging Infrastructure: Depot Charging, Fast Charging, Wireless Charging, Opportunity Charging Battery Technology: Lithium-ion, Solid State, Flow Battery, Nickel Manganese Cobalt End User: Public Transport, School Transport, Corporate Transport, Shuttle Service |
| Companies Covered | Solaris Bus & Coach, Volvo Buses, Yutong, Scania, BYD Auto, Mercedes-Benz, Iveco Bus, VDL Bus & Coach, MAN Truck & Bus, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electric Bus Market Strategic Shifts & Innovations
Silicon-carbide power electronics and solid-state thermal management are redefining drivetrain efficiency benchmarks, while procurement departments rewrite contract templates around energy-as-a-service structures.
Silicon-carbide inverters are supplanting conventional IGBT modules in 800-volt architectures. Solaris Bus & Coach and Volvo Buses have adopted these systems for 2024 platform refreshes. The technology is supplanting legacy power conversion across Central European tender specifications, compressing drivetrain supplier margins for silicon-based incumbent technologies.
The EU AI Act's forthcoming autonomous-vehicle provisions impose software validation requirements on OEM-tier supplier contracts. Liability allocation shifts from vehicle operators to algorithm developers for depot automation functions. French and German transit authorities are demanding pre-certified AI stacks in new tender documents, filtering out suppliers without in-house validation labs.
Tender structures now separate vehicle purchase from energy supply and maintenance obligations. Municipal operators in the Netherlands and Denmark favor 12-year total-cost contracts with guaranteed uptime clauses. This unbundling favors vertically integrated manufacturers with captive battery servicing networks over pure-play vehicle assemblers.
Europe Electric Bus Market Segmentation
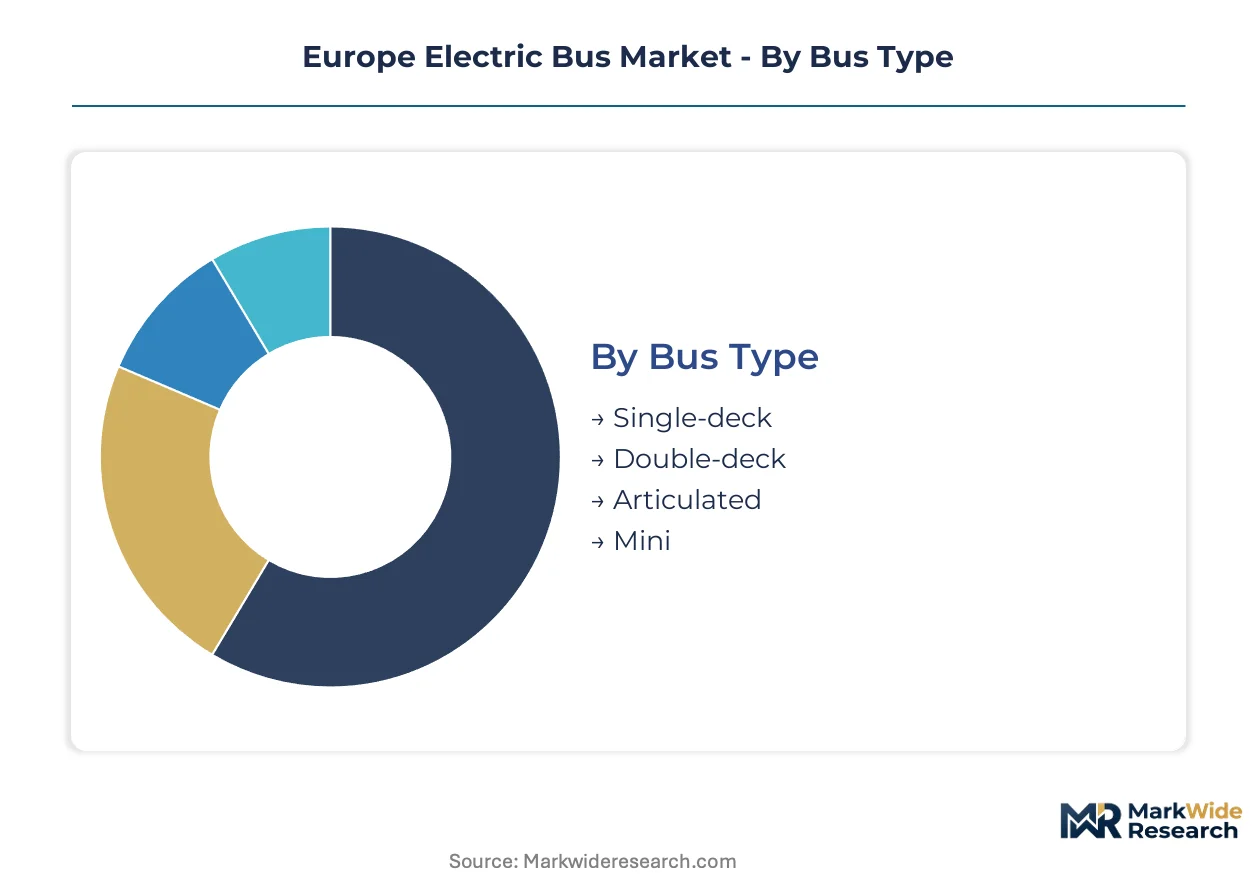
Segmentation reveals where procurement budgets concentrate and which technologies face displacement pressure. Transit authorities structure tenders around operational duty cycles, battery duty limits, and depot retrofit economics rather than vehicle purchase price alone.
Bus Type:
Single-deck configurations face immediate substitution pressure from articulated variants in high-ridership corridors, while double-deck electrification lags due to battery packaging constraints.
- Single-deck:Standard 12-meter configurations dominate current fleet replacements across Germany and France. Rhine-Ruhr corridor operators specify 450 kWh packs with depot-charging compatibility as baseline tender requirements.
- Articulated:18-meter bi-articulated variants capture expanding share where platform length restrictions ease. Nordic capitals prioritize these for BRT corridors with 300+ passenger capacity per vehicle.
- Double-deck:Battery height constraints limit roof-mounted pack options. London Transport for London trials restricted to specific route profiles with sub-15 km duty cycles.
- Mini:Sub-9-meter configurations serve last-mile feeder routes and rural demand-responsive transport. Polish municipal operators specify these for Visegrád corridor peripheral networks.
Single-deck retains volume leadership; articulated holds the steepest expansion curve.
Charging Infrastructure:
Cost tier differentiation separates capital-intensive fast-charging installations from lower-barrier depot retrofits.
- Depot Charging:Overnight plug-in systems sustain volume leadership through lower capital intensity and scheduling flexibility. Grid-integration partnerships with municipal utilities in the Netherlands secure fixed overnight tariffs.
- Fast Charging:Pantograph and plug-in systems at route terminals enable continuous operation. France and Italy impose 18-24 month grid connection queues that compress tender cycles.
- Opportunity Charging:En-route top-up at terminals and intermediate stops extends daily range without full depot dependency. Danish operators favor 12-year total-cost contracts bundling infrastructure with vehicle supply.
- Wireless Charging:Inductive pad systems at bus stops eliminate connector wear. Pilot deployments concentrate in Swedish and German test corridors with embedded road infrastructure.
Depot charging dominates installed base; opportunity charging gains share fastest in high-frequency networks.
Battery Technology:
Application requirements drive divergence between proven lithium-ion deployments and emerging solid-state pilot programs.
- Lithium-ion:NMC and LFP chemistries with 250-450 kWh capacity constitute current tender baselines. Cell balancing and thermal runaway containment expertise concentrates among Tier-1 system integrators.
- Solid State:Ceramic electrolyte architectures promise energy density improvements. EMA certification pathways for new pack architectures extend 8-14 months beyond lithium-ion equivalents.
- Nickel Manganese Cobalt:High-nickel cathode formulations optimize energy density for double-deck and articulated platforms. European manufacturers depend on processed lithium hydroxide from limited refining capacity in Portugal and Finland.
- Flow Battery:Vanadium redox systems offer unlimited cycle life for stationary depot buffering. Volume deployment constrained by electrolyte tank volume and weight penalties.
Lithium-ion retains procurement dominance; solid-state climbs the fastest in premium platform specifications.
End User:
Customer type segmentation separates municipal procurement mandates from commercial fleet economics.
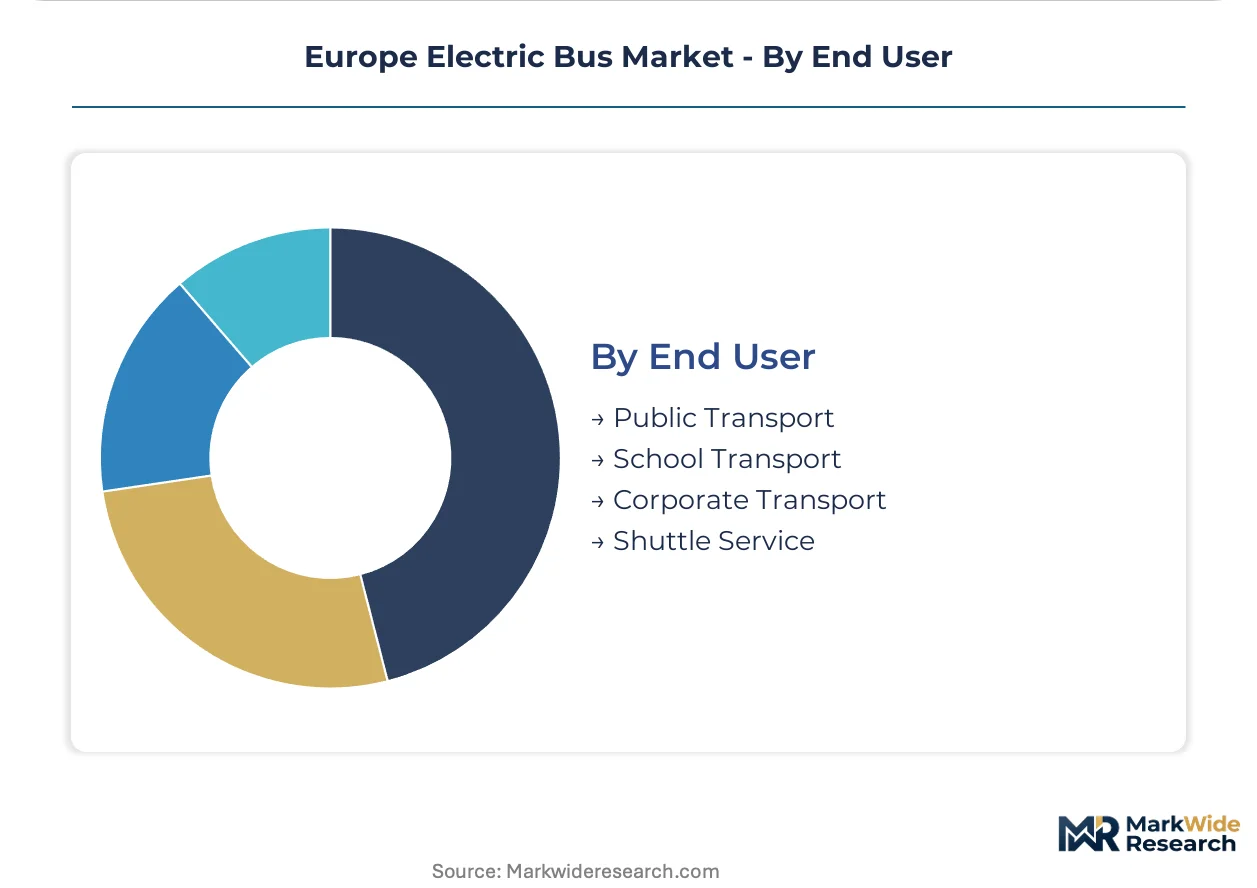
- Public Transport:Municipal transit authorities across Germany and France operate under EU Green Deal binding emission thresholds. Fleet replacement schedules lock in multi-year electrification budgets independent of fuel price volatility.
- School Transport:Dedicated student services in suburban and rural networks favor mini-bus configurations. Procurement concentrates in state-level education transport contracts with standardized safety specifications.
- Corporate Transport:Campus and industrial site shuttles prioritize depot-charging simplicity over route flexibility. Dutch and Danish corporate campuses specify 12-year total-cost contracts with guaranteed uptime clauses.
- Shuttle Service:Airport and intermodal connection services demand premium interior specifications. Paris Charles de Gaulle and Amsterdam Schiphol specify pre-certified AI stacks for depot automation functions.
Public transport commands procurement volume; corporate transport expands most quickly in campus electrification programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polish manufacturers export battery-electric chassis across the Visegrád corridor while Nordic operators import depot-charging integration packages from Dutch grid specialists.
Germany
Rhine-Ruhr metropolitan networks drive procurement volume through state-level fleet mandates. KBA enforces type-approval timelines that extend certification cycles for new pack architectures. North Rhine-Westphalia transit authorities specify 450 kWh configurations with guaranteed battery lifecycle clauses.
France
Paris region operators prioritize bi-articulated variants for high-capacity BRT corridors. ANSM and national regulators impose 18-24 month grid connection queues for megawatt-scale depot upgrades. Île-de-France Mobilités bundles infrastructure investment with vehicle procurement in 12-year service contracts.
Netherlands
Randstad urban networks favor total-cost-of-ownership structures separating vehicle purchase from energy supply. Grid-integration partnerships with municipal utilities secure fixed overnight charging tariffs. Rotterdam and Amsterdam specify pre-certified AI stacks for depot automation in new tender documents.
Poland
Visegrád corridor demand concentrates procurement awards toward Central European manufacturing bases. Solaris leverages Polish production facilities to compress delivery windows for municipal operators. Warsaw and Kraków transit authorities specify standardized safety configurations for peripheral rural networks.
Sweden
Nordic capitals prioritize silicon-carbide power electronics in 800-volt platform specifications. CE marking frameworks mandate electromagnetic compatibility certification for depot-charging infrastructure. Stockholm and Gothenburg operators trial wireless inductive pad systems at embedded road infrastructure test corridors.
Europe Electric Bus Market Key Industry Players
Listed leaders compete with private specialists across battery cost structures and charging integration capabilities. The vendor base clusters around three strategic tiers: vertically integrated manufacturers with captive cell supply, regional assemblers leveraging proximity to municipal procurement offices, and technology licensors providing drivetrain packages to third-party body builders. Consolidation pressure concentrates among mid-volume specialists facing margin compression from 450 kWh pack parity with diesel refurbishment cycles. Dominant competitive moves include backward integration into cell balancing expertise and strategic partnerships with municipal utilities for grid-connection priority.
Within the regional incumbent tier, Solaris Bus & Coach and Volvo Buses exemplify divergent geographic anchoring strategies. Solaris occupies a position representing Central European production proximity to Visegrád corridor tenders. Volvo exemplifies Nordic integration with depot-charging utility partnerships. BYD Auto sits within the cost-structure archetype, representing battery economics pressure across mid-volume contract segments.
| Leading Market Players |
|---|
| Solaris Bus & Coach |
| Volvo Buses |
| Yutong |
| Scania |
| BYD Auto |
| Mercedes-Benz |
| Iveco Bus |
| VDL Bus & Coach |
| MAN Truck & Bus |
| Others |
Cost & Logistics Intelligence
CE marking and EU Green Deal compliance frameworks gate market access while simultaneously stratifying price tiers across battery-electric and fuel-cell platforms. Municipal procurement offices in Germany and France use certification preconditions to filter suppliers, concentrating pricing power among Tier-1 system integrators with in-house validation labs.
Pricing Analysis
Silicon-carbide inverter configurations command 15-20% premiums over legacy IGBT platforms in 800-volt architectures. Three-tier pricing structure across premium silicon-carbide, standard lithium-ion, and economy refurbished-diesel-comparable segments reflects battery capacity and thermal management sophistication. Cost compression in mid-volume contracts intensifies as BYD Auto sustains price pressure through captive cell economics. Polish municipal operators exhibit highest price sensitivity; Dutch Randstad authorities prioritize total-cost structures over upfront vehicle cost.
Supply Chain Analysis
Grid connection queues stretching 18-24 months in France and Italy have extended effective lead times for depot-charging infrastructure beyond vehicle delivery windows. European cell manufacturers draw from processed lithium hydroxide refining concentrated in Portugal and Finland, with cathode active material dependencies anchored in China and South Korea. Single-source vulnerability concentrates in thermal runaway containment expertise among a handful of Tier-1 system integrators. Distribution runs through municipal utility partnerships for overnight charging capacity allocation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe electric bus market is recovering from procurement cycle compression triggered by EU Green Deal mandate acceleration. Fleet replacement schedules now operate independently of fuel price volatility, locking in multi-year electrification budgets.
For Market Incumbents: Secure captive battery lifecycle servicing networks to defend against energy-as-a-service unbundling. Deepen backward integration into cell balancing and thermal management expertise to offset engineering talent scarcity. Lock grid-connection priority agreements with municipal utilities before queue extensions in France and Italy worsen.
For New Entrants and Emerging Players: Lead with vehicle-to-grid integration capabilities as a differentiated bidirectional charging proposition for national transmission operators. Target Polish Visegrád corridor peripheral networks where Solaris delivery advantages are weakest. Pursue 12-year total-cost contract structures with guaranteed uptime clauses to bypass upfront capital barriers.
For Investors and Strategic Acquirers: The EU AI Act's autonomous-vehicle provisions reshape the acquisition landscape toward software validation capabilities and pre-certified AI stack developers. Long-term viability centers on manufacturers with vertical integration into depot automation and grid-balancing assets. Watch EMA certification timeline compression for solid-state battery architectures as the inflection signal for next-generation platform consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium hydroxide refining capacity from Portuguese and Finnish sources for pack production. |
| Depot Charging Infrastructure Partnership | Locks fixed overnight tariffs with municipal utilities in the Netherlands and Germany. |
| Software-Defined Vehicle Investment | Positions for EU AI Act pre-certification requirements in French and German tender documents. |
| Geographic Manufacturing Footprint | Compresses delivery windows for Visegrád corridor awards through Polish production bases. |
| Platform Standardization | Enables 450 kWh pack parity with diesel refurbishment cycles across Rhine-Ruhr specifications. |
Research Approach
A standing panel of municipal transit procurement directors, Tier-1 battery system integrators, grid-integration specialists at distribution network operators, and EMA type-approval consultants provided ongoing calibration across primary fieldwork. Secondary validation drew from KBA certification databases, EU Green Deal implementation progress reports, ANSM grid connection queue disclosures, and municipal tender documentation from Rhine-Ruhr and Randstad authorities. Bottom-up fleet replacement schedules triangulated against top-down EU emission threshold mandates.
Consistency checks validated volume and value outputs against vehicle registration databases and production disclosures from IHS Markit and ACEA. The analytical framework modeled segmentation across bus type, charging infrastructure, battery technology, and end user, with propulsion architecture and regional regulatory cluster as cross-cutting dimensions. CAGRs derived from fitted adoption curves reflecting binding fleet quotas and cell cost trajectory assumptions. Forecast inputs incorporated depot retrofit lead times and solid-state certification pathway extensions.
Forecasts assume regulatory continuity in EU Green Deal thresholds, F-Gas refrigerant phase-down schedules, and CE marking electromagnetic compatibility protocols; material policy shifts would require re-modeling. Battery material supply disruptions or grid connection queue extensions beyond current baselines represent specific revision triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Fuel-Cell Electric Vehicle Insulation Market
Electric Vehicles
Hoverboard Scooter Market
Electric Vehicles
Global Automotive High-Performance Electric Vehicles Market
Electric Vehicles
Electric Vehicle Electric Heating Film Market
Electric Vehicles
Electric Vehicle Regenerative Braking System Market
Electric Vehicles
North America E-Bike Market
Electric Vehicles
AC BEV On-Board Charger Market
Electric Vehicles
Automotive Battery Thermal Management System Market
Electric Vehicles
Indian E-Bike Rental Market
Electric Vehicles
Europe Electric Truck Market
Electric Vehicles
BEV Electric Drive Unit Market
Electric Vehicles
US Electric Vehicle Market
Electric Vehicles
United States Electric Car Market
Electric Vehicles
Solar Electric Car Market
Electric Vehicles
Extended Range Electric Vehicle (EREV) Market
Electric Vehicles
India Electric Bus Market