
 48V Mild Hybrid Electric Vehicle (MHEV) Market | 2026-2036
48V Mild Hybrid Electric Vehicle (MHEV) Market Size, Share, and Industry Trends Forecast 2026-2036
48V Mild Hybrid Electric Vehicle (MHEV) Market Insights
Fleet procurement is restructuring around electrified light commercial vehicles as logistics operators consolidate purchasing power across multi-brand tenders. Volkswagen Group leverages its modular 48V toolkit across Audi, Skoda, and VW badges to sustain volume economics in European fleet channels. Stellantis anchors its competitive position through integrated motor generator supply tied to Ram and Fiat Professional van programs. Hyundai Motor Company differentiates via dedicated 48V variants of its commercial platform sold through direct fleet negotiation.
A 48V mild hybrid electric vehicle employs a belt-driven or crankshaft-mounted integrated starter-generator producing up to 15 kW of electric assist, paired with a lithium-ion battery pack operating at roughly 48 volts nominal. The architecture enables torque-fill during acceleration, coasting with engine-off operation, and recuperation of braking energy without the cost and mass penalties of full high-voltage hybrid systems. Passenger car deployments dominate current volumes, though margin pools concentrate in SUV applications where 48V systems support cylinder deactivation and active suspension loads. Integrated motor generator technology leads growth trajectory as automakers abandon discrete belt-alternator-starter layouts in favor of axle-mounted or transmission-embedded designs yielding higher recuperation efficiency.
EPA tailpipe standards and the EU F-Gas Regulation shape 48V system design by mandating CO2 reductions and restricting refrigerant choices that affect ancillary electrical loads. NHTSA fuel economy rules in the United States push domestic manufacturers toward 48V adoption as a compliance bridge technology. Fleet operators and OEM procurement teams must monitor how REACH chemical restrictions on battery materials and evolving EPA test-cycle boundaries alter system cost structures and supplier qualification requirements.
Market Dynamics
Integrated motor generator architectures are displacing belt-alternator-starter layouts as automakers chase higher recuperation efficiency and packaging flexibility in powertrain design.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on high-global-warming-potential refrigerants force ancillary load electrification, expanding 48V system addressable content per vehicle.
- Light commercial vehicle fleets:Logistics operators across Germany, France, and the Netherlands consolidate multi-brand tenders favoring electrified vans with 48V torque-fill capability.
- Axle-mounted motor generators:Transmission-embedded designs enable engine-off coasting at highway speeds, delivering CO2 reductions without full hybrid cost structures.
Market Restraints
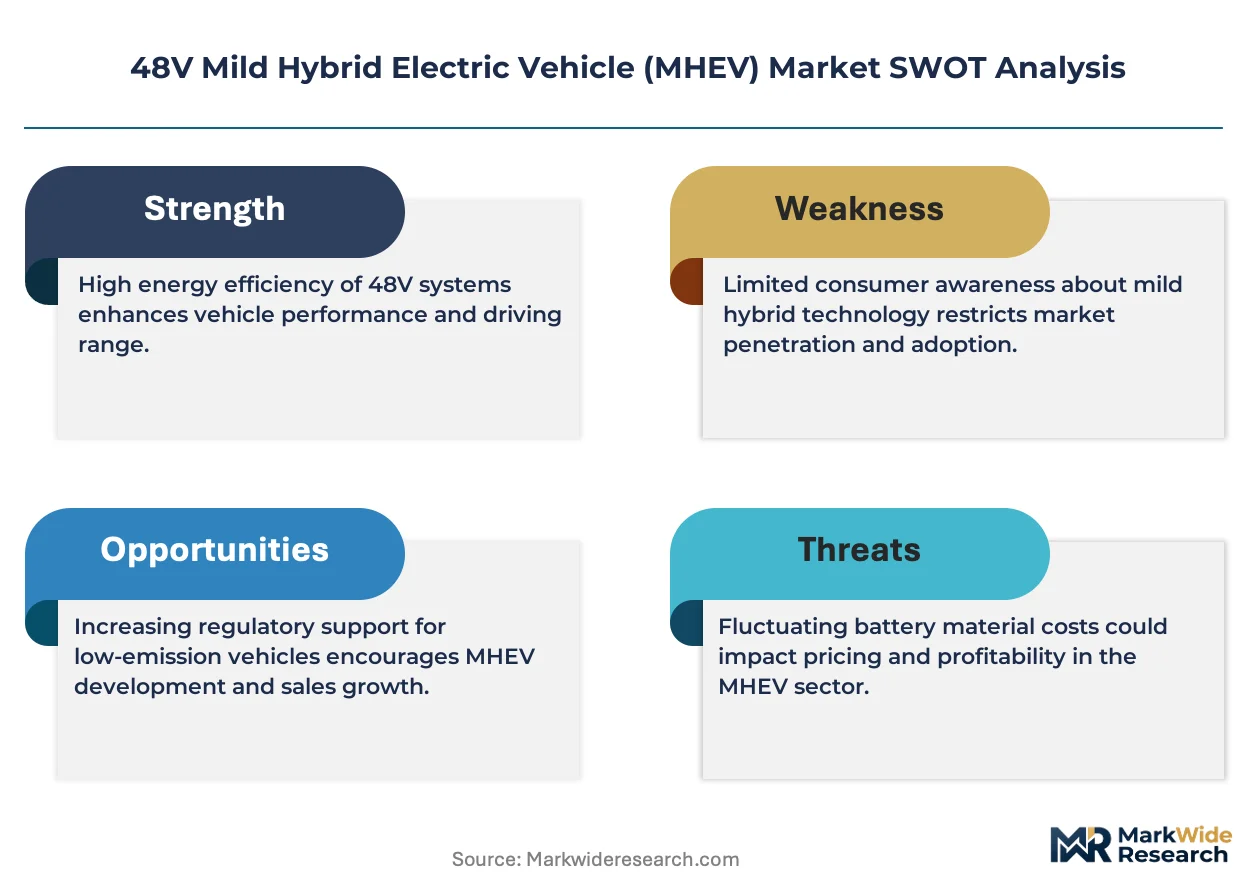
- Lithium-ion cell supply concentration:Battery material processing capacity clusters in China, exposing European and North American OEMs to geopolitical supply disruptions and qualification delays.
- REACH chemical restrictions:ECHA oversight of nickel, cobalt, and manganese compounds in battery packs forces supplier requalification and alternative chemistry development.
- High-voltage hybrid substitution:PHEV architectures with 400V systems offer deeper electrification for similar incremental cost in premium SUV segments, capping 48V upside.
Strategic Opportunities
- India commercial vehicle segment:BIS certification pathways and CEA grid integration standards create a regulatory runway for 48V adoption in diesel-intensive logistics corridors.
- Active suspension electrification:Convergence of 48V power nets with electromechanical damper systems opens content expansion in luxury SUV and performance car segments.
- Direct fleet negotiation channels:Bypassing traditional dealer networks allows OEMs to bundle 48V hardware with telematics and predictive maintenance contracts.
Industry Challenges
- Power electronics integration:Combining DC-DC converters, motor inverters, and battery management systems into single thermal packages strains cooling architecture design cycles.
- ISO 26262 functional safety certification:ASIL-D requirements for torque-intervention systems extend validation timelines and engineering headcount demands.
- Legacy 12V electrical load migration:Dual-voltage architectures require harness redesign and component requalification across model-year changeovers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 48V Mild Hybrid Electric Vehicle (MHEV) Market |
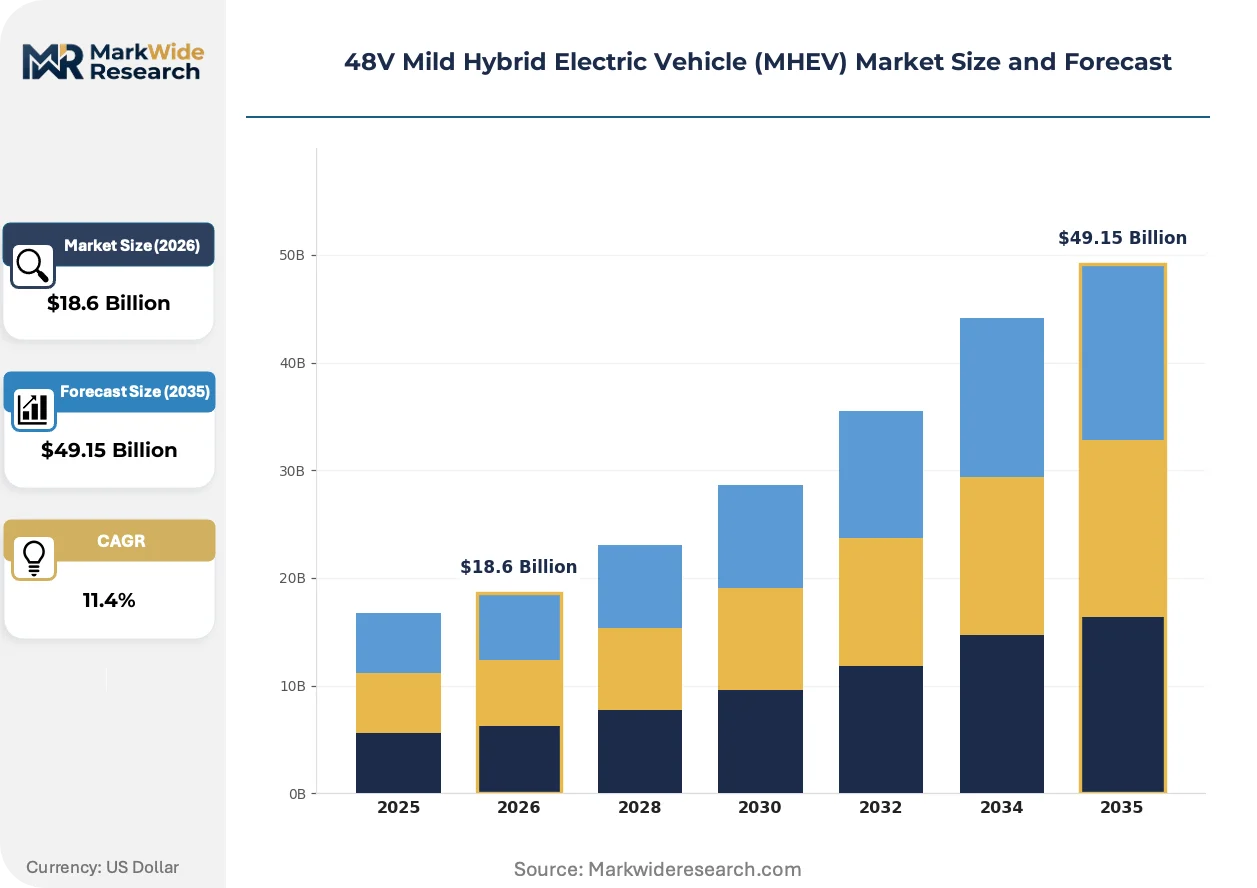
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $49.15 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger Car, Light Commercial Vehicle, Heavy Commercial Vehicle, SUV Technology: Regenerative Braking, Start-Stop System, Electric Power Steering, Integrated Motor Generator End User: OEMs, Aftermarket Providers, Fleet Operators, Leasing Companies Sales Channel: Direct Sales, E-commerce, Dealerships, Distributors |
| Companies Covered | Mercedes-Benz, Stellantis, Toyota Motor Corporation, Ford Motor Company, Hyundai Motor Company, Volkswagen Group, Honda Motor Co., Ltd, Audi AG, BMW AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
48V Mild Hybrid Electric Vehicle (MHEV) Market Trends and Innovations
Powertrain electrification is fragmenting across voltage tiers as automakers optimize cost-per-CO2-gram across passenger car, SUV, and light commercial portfolios.
Crankshaft-mounted integrated starter-generators are expanding into transmission-embedded and axle-mounted configurations. European OEMs adopt these layouts for rear-drive hybrid variants to preserve cargo space in vans. The shift is expanding into front-wheel-drive platforms previously reserved for belt-driven systems, compressing supplier margins on legacy alternator-starter hardware.
EPA tailpipe standards under the Clean Air Act are tightening test-cycle boundaries for CO2 measurement. Domestic manufacturers respond by calibrating 48V systems for real-world driving conditions rather than laboratory cycles. Light truck segments face the steepest compliance gradients, accelerating belt-to-crankshaft migration timelines.
Fleet procurement patterns are consolidating around total-cost-of-ownership metrics that weight fuel savings against residual value risk. Large logistics operators in Germany and the Netherlands now specify 48V hardware as mandatory in multi-year lease tenders. This specification pressure transmits backward through OEM fleet sales channels, displacing optional-equipment ordering flexibility.
48V Mild Hybrid Electric Vehicle (MHEV) Market Segmentation
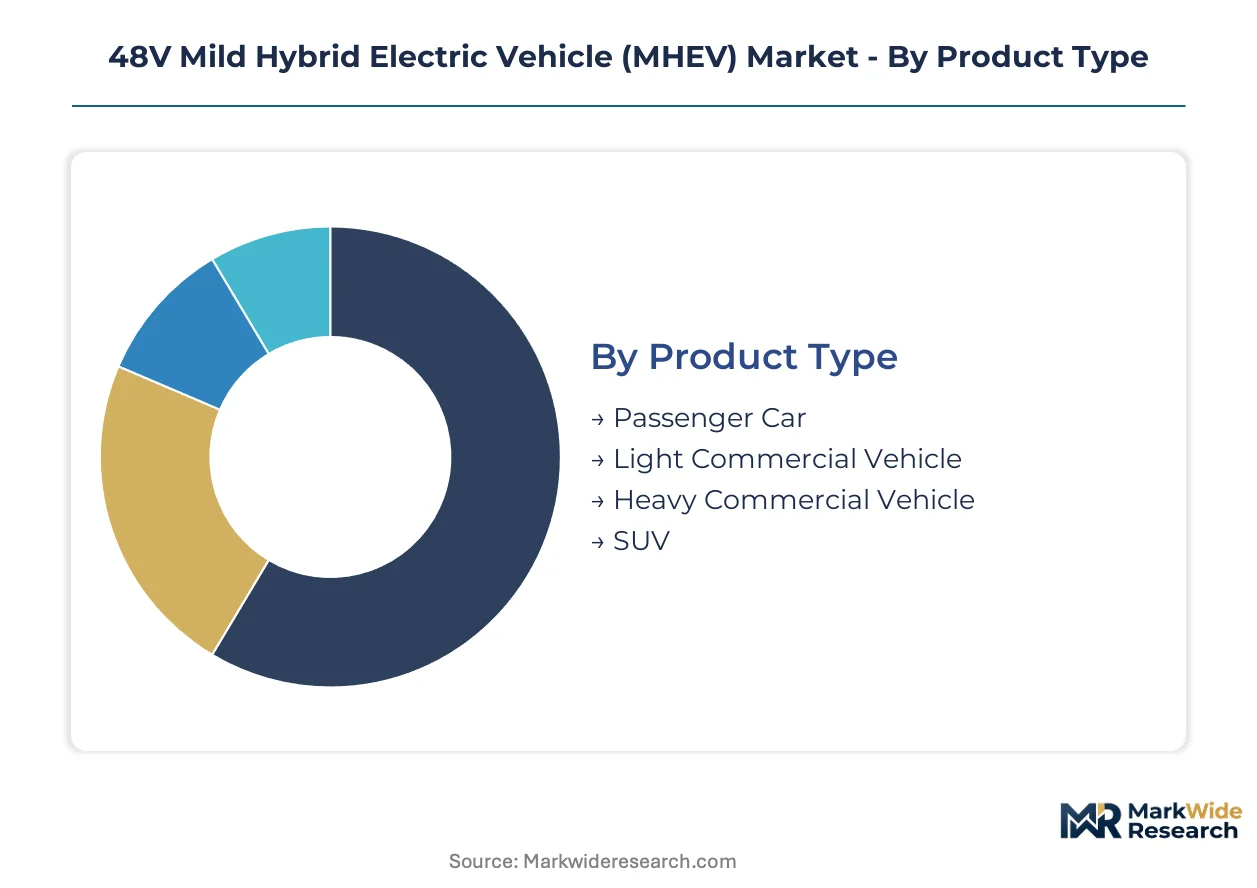
Segmentation in the 48V MHEV market reveals how voltage architecture, vehicle duty cycle, and procurement channel determine system specification and margin structure. Each dimension carries distinct engineering requirements and regulatory exposure that shape supplier qualification and OEM platform strategy.
Product Type:
Standardization dominates at the platform level while customization concentrates in powertrain calibration and battery sizing across vehicle duty profiles.
- Passenger Car:Belt-driven integrated starter-generator architectures prevail in C-segment and D-segment sedans, with European OEMs calibrating systems for WLTP cycle optimization. German fleet channels specify 48V hardware as baseline equipment in corporate lease programs, compressing optional-equipment margins.
- SUV:Crankshaft-mounted motor generators support cylinder deactivation and active suspension loads in premium segments. US light truck regulations under NHTSA fuel economy rules accelerate belt-to-crankshaft migration timelines for compliance.
- Light Commercial Vehicle:Transmission-embedded designs enable engine-off coasting without cargo space compromise. Dutch and German logistics operators mandate 48V torque-fill in multi-year tenders.
- Heavy Commercial Vehicle:Axle-mounted configurations address stop-start intensity in urban delivery cycles. BIS certification pathways in India create regulatory runway for diesel-intensive corridors.
Leading the category by volume: Passenger Car. Climbing the fastest: Light Commercial Vehicle.
Technology:
Cost tier stratification separates legacy belt-alternator-starter layouts from integrated motor generator architectures commanding premium positioning.
- Integrated Motor Generator:Transmission-embedded and axle-mounted designs yield recuperation efficiency above belt-driven alternatives. European engineering investment clusters in Germany for rear-drive hybrid van applications.
- Regenerative Braking:48V lithium-ion packs capture deceleration energy without high-voltage insulation penalties. China concentrates heaviest production capacity for power electronics integration.
- Start-Stop System:Belt-alternator-starter configurations face margin compression as OEMs abandon discrete layouts. EPA test-cycle boundary tightening under the Clean Air Act accelerates displacement.
- Electric Power Steering:Ancillary load electrification expands addressable content per vehicle under EU F-Gas Regulation refrigerant restrictions. REACH chemical oversight on battery materials forces supplier requalification.
Dominant by installation base: Start-Stop System. Steepest expansion trajectory: Integrated Motor Generator.
End User:
Customer type determines specification authority, with direct fleet negotiation displacing traditional dealer-channel ordering flexibility.
- Fleet Operators:Consolidated multi-brand tenders in France, Germany, and the Netherlands specify 48V hardware as mandatory. Total-cost-of-ownership metrics weight fuel savings against residual value risk in lease structures.
- OEMs:Volkswagen Group leverages modular 48V toolkits across Audi, Skoda, and VW badges. Stellantis anchors supply through integrated motor generator programs for Ram and Fiat Professional vans.
- Leasing Companies:Residual value forecasting incorporates electrification content into depreciation models. Specification pressure transmits backward through OEM fleet sales channels.
- Aftermarket Providers:Retrofit opportunity concentrates in 12V-to-48V harness redesign for legacy electrical load migration. ISO 26262 ASIL-D requirements extend validation timelines for torque-intervention systems.
Highest procurement volume: OEMs. Gaining share fastest: Fleet Operators.
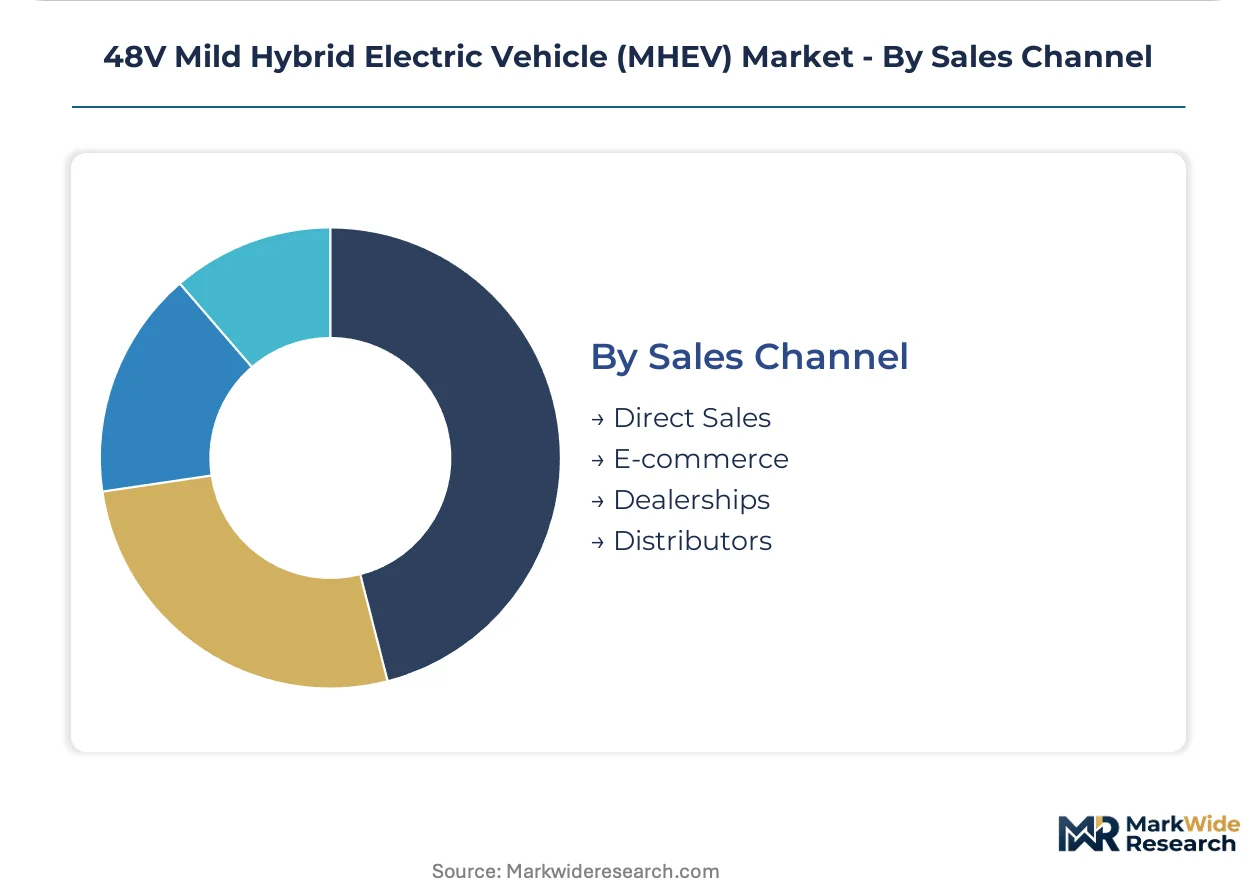
Sales Channel:
Channel structure reflects power concentration in fleet procurement versus fragmentation in retail consumer markets.
- Direct Sales:Hyundai Motor Company negotiates dedicated 48V commercial variants through bypassed dealer networks. Telematics and predictive maintenance bundling expands contract value.
- Dealerships:Traditional retail channels face margin pressure as fleet specification removes optional-equipment flexibility. European volume economics depend on consolidated tender participation.
- Distributors:Regional parts networks support aftermarket battery replacement and power electronics service. REACH compliance documentation burdens inventory management systems.
- E-commerce:Digital channels remain nascent for complete 48V system procurement, concentrated in component-level battery and converter sales.
Channel leader by transaction value: Direct Sales. Expanding most quickly: E-commerce.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet procurement consolidation and engineering investment clusters concentrate 48V MHEV demand in Germany, China, and the United States, with regulatory pressure spreading adoption into secondary logistics corridors.
China
Domestic logistics operators and passenger OEMs drive integrated motor generator demand for cost-efficient CO2 compliance. MIIT dual carbon goals accelerate 48V adoption in light commercial platforms. Yangtze River Delta engineering centers concentrate heaviest power electronics integration investment.
Germany
Volkswagen Group and BMW anchor European 48V volume through modular toolkit deployment across fleet channels. EU Green Deal CO2 limits under KBA enforcement tighten van emission ceilings. Stuttgart and Munich engineering clusters lead crankshaft-mounted motor generator architecture development.
United States
Light truck segment compliance pressure under NHTSA fuel economy rules accelerates belt-to-crankshaft migration timelines. EPA Clean Air Act test-cycle boundary tightening forces real-world driving calibration investment. Detroit-based OEM procurement teams specify 48V hardware for fleet lease structures.
India
Diesel-intensive logistics corridors in Maharashtra and Gujarat create addressable demand for 48V torque-fill in commercial stop-start cycles. BIS certification pathways and CEA grid integration standards establish regulatory runway. Tamil Nadu manufacturing clusters attract component localization for battery pack assembly.
Netherlands
Consolidated multi-brand fleet tenders from Rotterdam and Amsterdam logistics operators mandate 48V hardware as baseline equipment. EU F-Gas Regulation refrigerant restrictions expand ancillary electrical load addressable content. Eindhoven region suppliers specialize in DC-DC converter integration for van applications.
48V Mild Hybrid Electric Vehicle (MHEV) Market Competitive Landscape
German and Japanese producers anchor one tier; South Korean and American specialists hold differentiated positions in fleet-direct channels. The market structures around consolidated OEM captive supply with tiered component supply concentration. Three archetypes dominate: integrated motor generator system integrators, modular toolkit platform providers, and fleet-negotiation specialists. Competitive moves center on backward integration into battery cell qualification and transmission-embedded design licensing.
Within the modular toolkit tier, Volkswagen Group exemplifies platform-scale deployment across multi-brand portfolios. Among fleet-direct specialists, Hyundai Motor Company occupies a position emphasizing commercial variant negotiation bypassing traditional dealer networks. Stellantis represents the integrated motor generator supply anchor for light commercial van programs. These three entities illustrate how competitive positioning stratifies across engineering investment intensity and procurement channel control.
| Leading Market Players |
|---|
| Mercedes-Benz |
| Stellantis |
| Toyota Motor Corporation |
| Ford Motor Company |
| Hyundai Motor Company |
| Volkswagen Group |
| Honda Motor Co., Ltd |
| Audi AG |
| BMW AG |
| Others |
Pricing and Supply Chain Analysis
Lithium carbonate price indices in China cascade through 48V battery pack cost structures, compressing margins on belt-driven starter systems while elevating integrated motor generator architectures to premium positioning. Tier 1 suppliers in Germany and South Korea absorb volatility through long-term offtake contracts with cathode material processors, insulating OEM fleet pricing from spot-market swings.
Pricing Analysis
Volume pools concentrate in belt-alternator-start configurations while margin capture shifts toward transmission-embedded motor generators. Three-tier pricing structure across premium crankshaft-mounted, standard belt-driven, and economy start-stop systems reflects recuperation efficiency differentials. Cost compression in legacy 12V migration hardware intensifies as REACH compliance adds qualification overhead. Fleet operators in the Netherlands exhibit highest price sensitivity due to total-cost-of-ownership tender structures, while luxury SUV buyers absorb premium positioning for active suspension electrification.
Supply Chain Analysis
Engineering talent scarcity in Stuttgart and Munich engineering clusters constrains crankshaft-mounted motor generator ramp rates, while Yangtze River Delta power electronics facilities face similar workforce bottlenecks. Lithium-ion cell production draws from China, South Korea, and Japan; power semiconductor fabrication rests on Taiwan and Germany; rare earth magnet processing centers on China. Single-source vulnerability in permanent magnet supply threatens transmission-embedded design timelines. Distribution runs through OEM captive supply networks with tiered component qualification gates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Integrated motor generators are displacing belt-alternator-starter layouts as the dominant 48V architecture, compressing the window for legacy supplier repositioning.
For Market Incumbents: Cement platform-scale deployment through backward integration into battery cell qualification, locking in volume commitments from Volkswagen Group and Stellantis fleet channels. Prioritize ASIL-D certification investment to defend against high-voltage hybrid substitution in premium SUV segments. Capacity addition in Tamil Nadu manufacturing clusters hedges against REACH-driven European supply disruption. For New Entrants and Emerging Players: Launch via direct fleet negotiation channels in Indian commercial vehicle corridors, bypassing established OEM dealer networks. White-space concentrates in BIS-certified axle-mounted configurations for diesel-intensive logistics routes. Target aftermarket 12V-to-48V harness retrofit demand as legacy electrical load migration accelerates through model-year changeovers. For Investors and Strategic Acquirers: The window for entry favors power electronics integration specialists with ISO 26262 validation capabilities and existing MIIT relationships in China. Long-term viability hinges on transmission-embedded design licensing revenue streams rather than discrete component supply. Watch for EPA test-cycle boundary tightening as the inflection signal accelerating belt-to-crankshaft migration timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Motor Generator Platform Licensing | Transmission-embedded designs yield higher recuperation efficiency for Stellantis and Hyundai fleet programs. |
| Battery Supply Agreement with Cathode Processors | Long-term offtake contracts insulate German OEMs from lithium carbonate volatility in Yangtze River Delta. |
| ASIL-D Functional Safety Certification | ISO 26262 validation opens torque-intervention system supply to BMW and Audi hybrid variants. |
| Direct Fleet Negotiation Channel Establishment | Bypassing dealer networks enables telematics bundling with Dutch logistics operators. |
| Tamil Nadu Manufacturing Localization | BIS certification pathways and CEA grid standards support Indian commercial vehicle electrification corridors. |
Research Methodology
Document review covered OEM technical specifications, EU F-Gas Regulation implementation guidance, and EPA Clean Air Act test-cycle documentation, complemented by interviews with Tier 1 supplier procurement directors, OEM platform engineers, fleet operations managers at German logistics operators, and power electronics integration specialists. Secondary validation drew from KBA type-approval databases, MIIT dual carbon policy filings, vehicle production registration data, and BIS certification records. Bottom-up build-ups of 48V system installations triangulated against top-down OEM revenue attribution across the analysis window.
Segmentation outputs modeled vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions throughout the forecast period. CAGRs derived from logistic curve adoption modeling calibrated to fleet tender specification timelines and regulatory compliance deadlines. Industry-specific inputs incorporated REACH chemical restriction phase-in schedules and NHTSA fuel economy rule stringency trajectories.
Raw material price volatility, geopolitical disruption in semiconductor fabrication, and accelerated high-voltage hybrid cost parity are the dominant revision risks warranting forecast reassessment. Material deviation in lithium carbonate indices, Taiwan strait logistics chokepoints, or PHEV pricing convergence warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
China Solar E-Bike Market
Electric Vehicles
Mexico Automotive High Performance Electric Vehicle Market
Electric Vehicles
48V Mild Hybrid Battery Pack Systems Market
Electric Vehicles
Electric Bike Kit Market
Electric Vehicles
North America E-Bike Market
Electric Vehicles
Asia-Pacific Electric Vehicle (EV) Fluids Market
Electric Vehicles
Asia-Pacific Solar E-Bike Market
Electric Vehicles
Global EV Relay Market
Electric Vehicles
China NEV Taxi Market
Electric Vehicles
Electric Vehicle Battery Cases Market
Electric Vehicles
Train Battery Market
Electric Vehicles
Electric Vehicle (EV) Battery Housing Market
Electric Vehicles
Global Golf Cart and Neighborhood Electric Vehicle (NEV) Market
Electric Vehicles
India Electric Vehicle Market
Electric Vehicles
Worldwide EV Range Extender Market
Electric Vehicles
Europe Electric Bus Market