
 Europe Fuel Cell Electric Vehicle Market | 2026-2036
Europe Fuel Cell Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Fuel Cell Electric Vehicle Market Foresight
Fleet operators is unwinding the historical dominance of private consumers in European fuel cell vehicle procurement. Daimler Truck AG leverages its heavy-duty platform specialization to anchor commercial contracts across German logistics corridors. Toyota Motor Corporation sustains passenger-car credibility through its Mirai technology lineage. Hyundai Motor Company competes aggressively on total-cost-of-ownership metrics for bus and truck deployments.
Europe fuel cell electric vehicles convert hydrogen via proton-exchange membrane stacks into electricity for traction motors, typically operating at 60-80 kW net output for passenger configurations and 200+ kW for heavy-duty platforms, with water vapor as the sole tailpipe emission. The vehicle type dimension shows bus and truck categories pulling ahead of sedan volume as municipal transit authorities and freight operators prioritize route-predictable hydrogen refueling. Within fuel source segmentation, hydrogen commands structural attention while biogas retains niche positioning in Nordic circular-economy pilots. Distribution channel dynamics favor direct sales and fleet sales over retail dealerships where infrastructure coupling determines contract viability.
The EU Green Deal frames binding decarbonization timelines while ECHA oversees hydrogen purity standards affecting stack durability warranties. Germany's national hydrogen strategy channels public capital into refueling networks, and the F-Gas Regulation shapes coolant chemistry choices in thermal management systems. Stakeholders must weigh electrolyzer capacity buildouts against vehicle deployment schedules to avoid infrastructure-demand mismatches that strand capital.
Market Dynamics
Fleet procurement contracts in Germany's freight corridors are compressing passenger-vehicle dominance as hydrogen refueling infrastructure concentrates along predictable logistics routes. This structural pivot toward commercial operators reconfigures manufacturing priorities and stack sizing across European OEM portfolios.
Growth Catalysts
- EU Green Deal binding targets:The framework mandates transport sector decarbonization timelines that force municipal transit authorities to accelerate zero-emission fleet replacements, directly channeling public procurement budgets toward fuel cell bus platforms.
- Electrolyzer capacity buildouts:Germany's national hydrogen strategy deploys state capital into refueling networks along the Rhine-Ruhr industrial belt, creating infrastructure certainty that de-risks fleet operator investment decisions.
- Proton-exchange membrane efficiency gains:Stack power density improvements enable 200+ kW outputs for heavy-duty platforms without proportional hydrogen storage volume increases, expanding route viability for long-haul freight configurations.
Market Restraints
- Platinum group metal cost volatility:Membrane electrode assembly fabrication depends on iridium and platinum catalysts whose price swings compress stack manufacturing margins and extend payback periods for fleet operators.
- Electrolyzer supply concentration:Alkaline and PEM electrolyzer manufacturing concentrates in Chinese and German supplier bases, creating delivery bottlenecks that strand vehicle deployment schedules ahead of hydrogen production capacity.
- F-Gas Regulation coolant constraints:Thermal management system chemistry choices face phase-down timelines under EU fluorinated gas rules, forcing redesign cycles that delay platform certification.
Strategic Opportunities
- Netherlands port hydrogen hubs:Rotterdam and Amsterdam industrial clusters offer concentrated demand anchors for heavy-duty fuel cell deployment, with dedicated truck corridors connecting maritime freight to inland distribution centers.
- Biogas-to-hydrogen pilot convergence:Nordic circular-economy frameworks enable biomethane reformation pathways that differentiate fleet offerings in Sweden and Denmark through carbon-intensity accounting advantages.
- Power-to-X regulatory tailwinds:The Renewable Energy Directive II certification schemes for green hydrogen create offtake guarantees that improve project finance terms for electrolyzer-vehicle coupled investments.
Industry Challenges
- High-pressure tank certification timelines:Type IV carbon-fiber hydrogen storage vessels face extended homologation cycles under ECE R134 and EU safety protocols, delaying vehicle platform launches by 12-18 months.
- Stack durability warranty calibration:Fleet operators demand 8,000+ hour operational guarantees that exceed current membrane degradation modeling, forcing OEMs to absorb residual performance risk or price premiums that erode total-cost-of-ownership competitiveness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Fuel Cell Electric Vehicle Market |
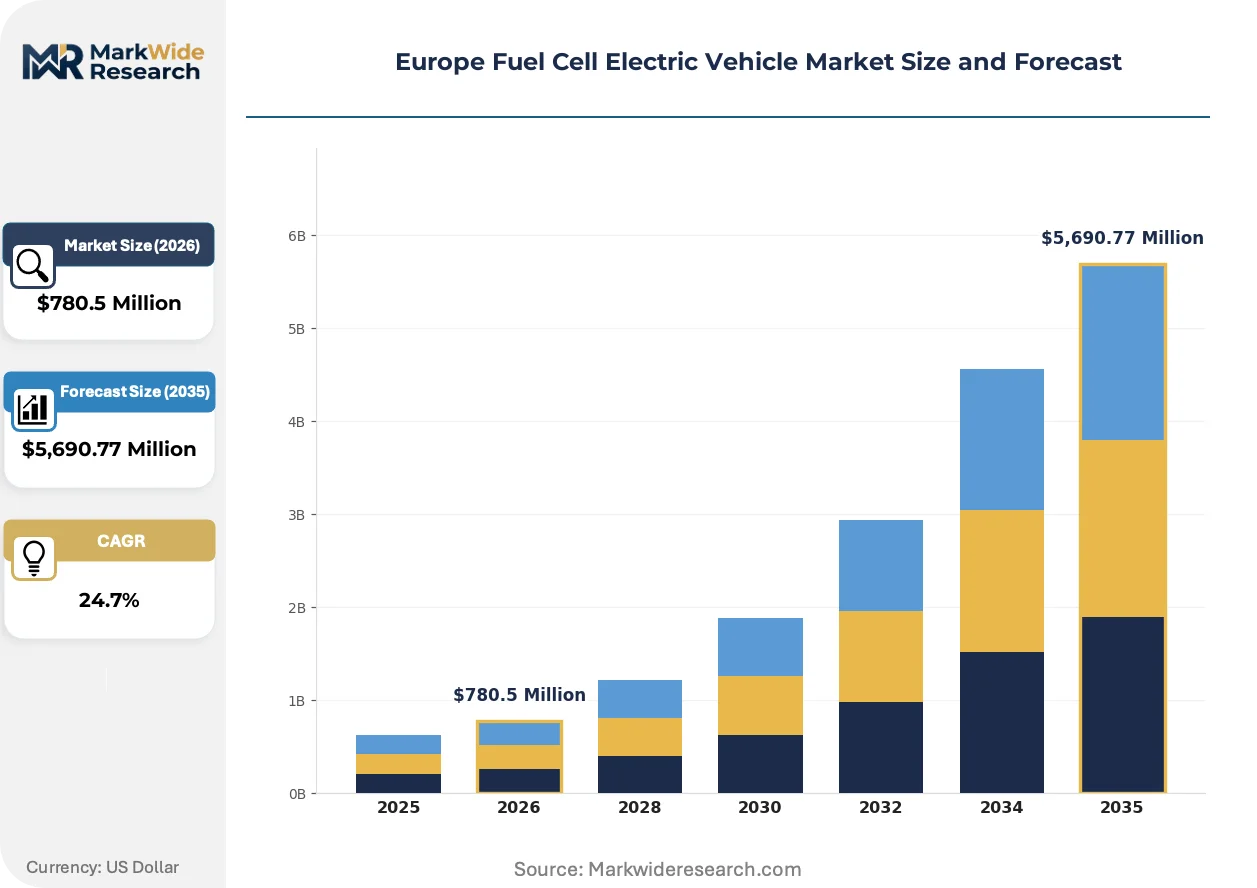
| Market Size in 2026 | $780.5 Million |
| Market Size in 2035 | $5,690.77 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Bus, Truck Fuel Source: Hydrogen, Natural Gas, Biogas, Methanol Distribution Channel: Direct Sales, Dealerships, Online, Fleet Sales End User: Private Consumers, Public Transport, Logistics, Government |
| Companies Covered | Hyundai Motor Company, Toyota Motor Corporation, BMW Group, Honda Motor Co., Ltd., Mercedes-Benz Group, Renault, Daimler Truck AG, Volvo Group, Hopium, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Fuel Cell Electric Vehicle Market Shifts & Advancements
Technology roadmaps in European fuel cell platforms are diverging between passenger efficiency optimization and heavy-duty power scaling, with regulatory pressure forcing simultaneous advancement across incompatible design priorities.
Proton-exchange membrane stack architecture is bifurcating into two distinct development tracks. Passenger configurations prioritize 60-80 kW net output with minimized platinum loading for cost containment. Heavy-duty platforms pursue 200-300 kW systems with reinforced membrane durability for continuous high-load operation. This technical divergence is compressing supplier economies of scale as membrane electrode assembly lines require dedicated tooling for each power class.
The EU F-Gas Regulation is reshaping thermal management system design across German and French manufacturing bases. The phasedown of hydrofluorocarbon coolants forces refrigerant chemistry transitions toward CO2 or hydrocarbon alternatives that demand higher operating pressures and redesigned heat exchanger geometries. Bus and truck categories face the steepest engineering cycles given their larger cabin and battery thermal loads.
Fleet procurement contracts are displacing retail dealership channels for commercial vehicle categories. Municipal transit authorities in the Netherlands and Germany negotiate direct manufacturer relationships that bundle vehicles with hydrogen supply agreements and maintenance service levels. This channel compression eliminates margin layers but requires OEMs to build in-house energy trading capabilities that traditional automotive sales organizations lack.
Europe Fuel Cell Electric Vehicle Market Segmentation
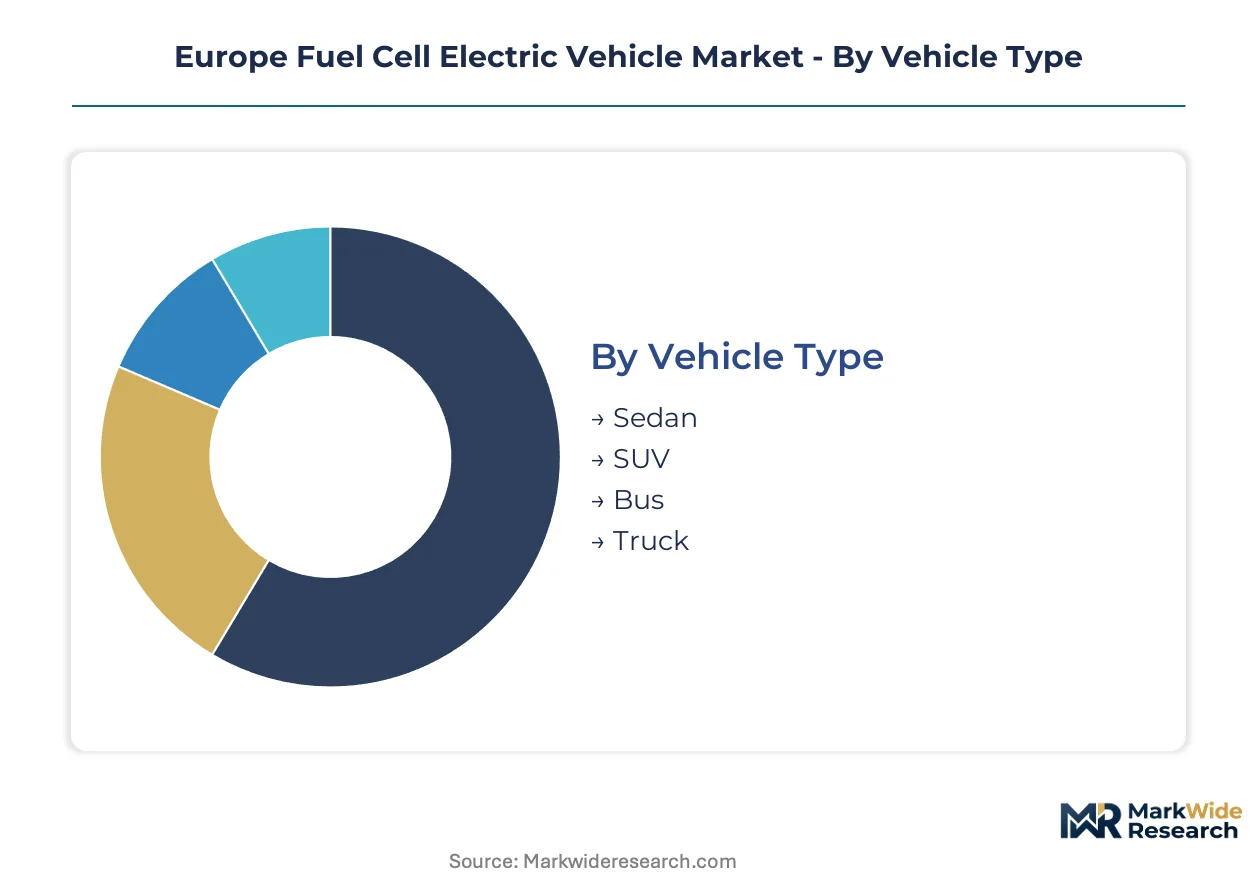
Fleet procurement channels in Europe's fuel cell vehicle market concentrate demand along predictable logistics corridors, reshaping how segments flow through distribution networks. Understanding these channel-segment couplings reveals where infrastructure investment unlocks contract viability.
Vehicle Type:
Direct sales and fleet sales channels dominate commercial categories, while dealerships retain residual passenger volume where hydrogen refueling density remains sparse.
- Bus:Municipal transit authorities in Germany and the Netherlands negotiate bundled procurement contracts that pair vehicles with hydrogen supply agreements. Rotterdam and Amsterdam transit operators anchor demand through dedicated depot refueling infrastructure.
- Truck:Heavy-duty platforms scaling 200-300 kW outputs serve Rhine-Ruhr freight corridors where route predictability enables infrastructure amortization. Daimler Truck AG leverages platform specialization to secure logistics fleet contracts.
- Sedan:Toyota's Mirai technology lineage sustains limited private-consumer demand through retail dealership channels.
- SUV:Hyundai competes on total-cost-of-ownership metrics for fleet configurations requiring passenger capacity.
Bus dominates installed base across municipal fleets. Truck is where expansion concentrates as freight operators prioritize route-predictable hydrogen economics.
Fuel Source:
Cost tiers separate infrastructure-ready hydrogen from niche alternatives where circular-economy accounting creates differentiation.
- Hydrogen:Proton-exchange membrane stacks convert compressed gas at 350-700 bar into electricity for traction motors. Germany's national hydrogen strategy channels public capital into refueling networks, creating infrastructure certainty that de-risks fleet investment.
- Biogas:Nordic circular-economy frameworks in Sweden and Denmark enable biomethane reformation pathways with carbon-intensity accounting advantages for public procurement scoring.
- Natural Gas:Methane reformation retains transitional positioning where electrolyzer capacity lags vehicle deployment schedules.
- Methanol:Liquid carrier pathways face ECHA purity standard compliance costs that compress commercial viability.
Hydrogen dominates installed base. Biogas is where expansion concentrates through Nordic carbon-accounting differentiation.
Distribution Channel:
Customer type determines channel viability, with fleet operators bypassing traditional retail margin layers.
- Fleet Sales:Municipal transit authorities and logistics operators negotiate direct manufacturer relationships bundling vehicles with maintenance service levels. This channel eliminates dealership margins but demands OEM in-house energy trading capabilities.
- Direct Sales:Heavy-duty truck procurement runs through manufacturer-direct contracts where infrastructure coupling determines contract structure along German freight corridors.
- Dealerships:Residual passenger-vehicle volume flows through traditional retail where hydrogen station density supports private ownership.
- Online:Digital configuration tools serve early-adopter consumers with limited commercial traction.
Fleet sales dominates installed base. Direct sales is where expansion concentrates as commercial procurement scales.
End User:
Application requirements segment procurement priorities across route predictability and duty-cycle intensity.
- Public Transport:Municipal bus fleets in Germany and the Netherlands scale hydrogen procurement through depot-based refueling with predictable daily mileage. EU Green Deal binding targets force accelerated zero-emission fleet replacements.
- Logistics:Freight operators along Rhine-Ruhr industrial corridors prioritize total-cost-of-ownership metrics where 8,000+ hour stack durability warranties determine platform selection.
- Government:Federal procurement programs anchor demand through standardized vehicle specifications and maintenance service levels.
- Private Consumers:Residual demand concentrates where retail hydrogen infrastructure supports passenger-car ownership patterns.
Public transport dominates installed base. Logistics is where expansion concentrates as freight electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet procurement contracts concentrate demand along Germany's Rhine-Ruhr freight corridors and Dutch port hydrogen hubs, with municipal transit authorities anchoring volume in depot-based bus deployments.
Germany
Municipal bus fleets in Berlin and Hamburg scale hydrogen procurement through depot refueling infrastructure. The national hydrogen strategy channels public capital into refueling networks along the Rhine-Ruhr industrial belt. Daimler Truck AG secures logistics fleet contracts across North Rhine-Westphalia's freight corridors.
Netherlands
Rotterdam and Amsterdam transit operators anchor demand through dedicated hydrogen depot infrastructure. The EU Green Deal binding targets force accelerated zero-emission fleet replacements for municipal authorities. Port hydrogen hubs at Rotterdam connect maritime freight to inland distribution centers via dedicated truck corridors.
France
Heavy-duty platforms serve logistics routes between Paris and Lyon where hydrogen refueling economics favor predictable mileage patterns. The F-Gas Regulation shapes thermal management system redesign cycles for French manufacturing bases. Auvergne-Rhône-Alpes industrial clusters host biogas-to-hydrogen pilot programs.
Sweden
Nordic circular-economy frameworks enable biomethane reformation pathways with carbon-intensity accounting advantages. National procurement scoring prioritizes low-carbon intensity hydrogen for public transit tenders. Gothenburg and Stockholm municipal fleets deploy biogas-sourced fuel cell buses.
United Kingdom
Logistics operators evaluate total-cost-of-ownership metrics for freight corridors connecting London to Midlands distribution centers. ECHA hydrogen purity standards affect stack durability warranties for UK-deployed platforms. Aberdeen and London host concentrated bus fleet trials with depot-based refueling.
Europe Fuel Cell Electric Vehicle Market Competitive Landscape
Player mix skews toward diversified automotive conglomerates with heavy-duty platform specialization. The vendor base concentrates around manufacturers with proton-exchange membrane stack integration capabilities. Two strategic archetypes dominate: commercial-vehicle specialists leveraging freight corridor relationships, and passenger-car incumbents sustaining technology credibility. Competitive moves center on fleet procurement contract capture and electrolyzer-vehicle coupling partnerships.
Within the commercial-vehicle tier, Daimler Truck AG and Volvo Group exemplify heavy-duty platform specialization. Hyundai Motor Company and Toyota Motor Corporation occupy positions across both passenger and commercial segments. These manufacturers anchor procurement relationships with municipal transit authorities and logistics operators through bundled vehicle-service agreements.
| Leading Market Players |
|---|
| Hyundai Motor Company |
| Toyota Motor Corporation |
| BMW Group |
| Honda Motor Co., Ltd. |
| Mercedes-Benz Group |
| Renault |
| Daimler Truck AG |
| Volvo Group |
| Hopium |
| Others |
Supply & Pricing Matrix
ECHA hydrogen purity standards gate both membrane electrode assembly qualification and warranty pricing tiers simultaneously. Fleet operators face cost-plus contracts indexed to platinum group metal spot markets, compressing margin predictability for OEMs while biogas-sourced hydrogen commands carbon-intensity premiums in Nordic procurement scoring.
Pricing Analysis
Cost-plus contracts with platinum group metal indexation dominate fleet procurement agreements across German logistics corridors. Pricing stratifies across heavy-duty premium configurations, mid-range bus platforms, and residual passenger economy tiers based on stack durability warranties and after-sales service bundling. Cost compression in passenger segments is intensifying because membrane electrode assembly suppliers compete on platinum loading minimization. Municipal transit authorities exhibit lowest price sensitivity due to EU Green Deal-mandated procurement timelines, while private consumers face highest sensitivity where hydrogen station density remains sparse.
Supply Chain Analysis
Port congestion along Rotterdam-Antwerp container corridors elevates inbound logistics costs for membrane electrode assembly imports from South Korean and Japanese supplier bases. Stack manufacturing draws from iridium catalysts sourced primarily from South Africa, platinum from Russia and Zimbabwe, and carbon-fiber tanks from Germany and Japan. Single-source vulnerability concentrates in PEM electrolyzer fabrication where Chinese and German suppliers control alkaline and proton-exchange membrane production capacity. Distribution runs through direct manufacturer-fleet relationships that bypass traditional automotive dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates opportunity as fleet procurement displaces private-consumer channels, generating specialized niches for electrolyzer-coupled vehicle-service bundling and regional hydrogen hub anchoring.
For Market Incumbents: Secure long-term offtake agreements with Rotterdam and Amsterdam port hydrogen hubs before electrolyzer capacity constraints strand vehicle deployment schedules. Daimler Truck AG and Volvo Group should deepen backward integration into membrane electrode assembly fabrication to insulate margins from platinum price volatility. Certification investment in ECHA hydrogen purity compliance creates switching costs against emerging stack suppliers. For New Entrants and Emerging Players: Anchor in Nordic biogas-to-hydrogen pilot corridors where carbon-intensity accounting advantages differentiate procurement bids in Sweden and Denmark. The Netherlands municipal bus replacement cycle offers most penetrable fleet volume through depot-based refueling infrastructure bundling. Go-to-market positioning should emphasize total-cost-of-ownership analytics against diesel parity for logistics operators. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed electrolyzer manufacturers seeking downstream vehicle coupling to secure offtake visibility. Long-term viability across the analysis window hinges on electrolyzer-vehicle deployment synchronization rather than technology differentiation alone. Monitor Germany's national hydrogen strategy refueling network buildout timelines as the critical inflection signal for capital deployment pacing.| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyzer-Vehicle Coupling Partnership | Rotterdam port hydrogen hubs anchor demand certainty for fleet procurement contracts. |
| Membrane Electrode Assembly Backward Integration | In-house platinum loading optimization insulates margins from spot market volatility. |
| Biogas-to-Hydrogen Certification Program | Nordic circular-economy frameworks enable carbon-intensity premium capture in public tenders. |
| Depot Refueling Infrastructure Joint Venture | Amsterdam transit authorities bundle vehicle procurement with dedicated hydrogen supply agreements. |
| Heavy-Duty Platform Standardization | Rhine-Ruhr freight corridor route predictability enables 200-300 kW stack economies of scale. |
Research Methodology
Cross-validation between OEM platform engineering disclosures and municipal transit authority procurement records anchors the qualitative findings. Primary interviews with fleet procurement managers, hydrogen infrastructure developers, membrane electrode assembly technical directors, and ECHA regulatory compliance officers combined with secondary validation from EU Green Deal implementation reports, national hydrogen strategy filings, and electrolyzer manufacturing capacity databases. Bottom-up vehicle deployment tracking and top-down infrastructure investment flows triangulate market sizing.
Sensitivity analysis around electrolyzer capacity buildout schedules and platinum group metal price scenarios shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include vehicle type, fuel source, distribution channel, and end-user application, with regional regulatory cluster differentiation across Germany, Netherlands, France, Sweden, and United Kingdom. CAGRs derive from infrastructure-vehicle deployment synchronization modeling and fleet replacement cycle analysis, incorporating stack durability warranty calibration and F-Gas Regulation thermal management compliance timelines as industry-specific inputs.
Decision-makers should treat outputs as directional under base assumptions of electrolyzer capacity scaling and hydrogen refueling network deployment; material deviation in either would warrant model refresh. Specific risk factors include platinum price volatility compressing manufacturing margins, ECHA purity standard revisions affecting stack warranties, and electrolyzer supply bottlenecks stranding vehicle deployment. Practitioners should keep alternative scenarios live as EU Green Deal transport sector target enforcement evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Europe Hybrid Electric Vehicle Battery Market
Electric Vehicles
Global Vehicle to Grid Technology Market
Electric Vehicles
Commercial Electric Vehicle Resistive Braking System Market
Electric Vehicles
Asia Pacific Hybrid Electric Vehicle Battery Market
Electric Vehicles
EV Coolants Market
Electric Vehicles
North America Automotive Battery Thermal Management System Market
Electric Vehicles
Electric Vehicle Relay Market
Electric Vehicles
Europe Electric Vehicle (EV) Fluids Market
Electric Vehicles
Germany Solar E-Bike Market
Electric Vehicles
Global Solar Powered Car Market
Electric Vehicles
Japan E-Bike Market
Electric Vehicles
High-Performance Electric Sports Cars Market
Electric Vehicles
Asia-Pacific Electric Vehicle (EV) Fluids Market
Electric Vehicles
India E-Bike Market
Electric Vehicles
United Kingdom Electric Vehicle (EV) Market
Electric Vehicles
Electric Loader Rickshaw Market