
 Electric Vehicle Battery Cases Market | 2026-2036
Electric Vehicle Battery Cases Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Battery Cases Market Insights
Aftermarket refurbishment of damaged battery enclosures is rewriting margin distribution across the value chain. ThyssenKrupp AG leverages its steel processing heritage to supply high-strength stamped housings for European OEM platforms. Magna International Inc. anchors North American supply through integrated aluminum extrusion and assembly capabilities. SGL Carbon specializes in carbon-fiber composite trays that cut mass for premium electric sports cars.
Electric vehicle battery cases are structural containers, typically fabricated from aluminum alloys or multi-material sandwiches, that protect lithium-ion cells from mechanical intrusion, thermal runaway propagation, and environmental ingress while integrating cooling channels and electrical isolation barriers. Aluminum cases dominate volume production due to their strength-to-weight ratio and compatibility with extrusion and stamping lines, though composite trays from SGL Carbon and TRB Lightweight are capturing share in performance segments where mass reduction justifies premium pricing. Stamping and extrusion processes lead in throughput economics for OEM-scale programs, while machining and injection molding serve lower-volume module housings and aftermarket replacement channels.
The EU Battery Regulation and China's GB/T standards mandate crashworthiness and fire-containment testing that OEMs cannot satisfy without certified case suppliers, tightening qualification timelines for new entrants. NHTSA in the United States enforces FMVSS 305 electrical safety requirements that propagate into housing design specifications for vehicles sold in that market. Stakeholders must monitor how evolving thermal-runaway propagation rules in multiple jurisdictions reshape material selection and joint-design requirements before committing to long-term tooling investments.
Market Dynamics
OEM platform consolidation around 800-volt architectures is compressing battery case qualification timelines while simultaneously raising thermal management performance thresholds that legacy stamping suppliers struggle to meet.
Growth Catalysts
- EU Battery Regulation:Mandatory carbon footprint declarations and recycled content mandates are forcing OEMs to redesign enclosures for end-of-life disassembly, creating certified supplier demand.
- Aluminum extrusion:High-pressure cooling channel integration enables single-piece side walls that eliminate weld joints, cutting thermal interface resistance by half versus stamped assemblies.
- South Korea's battery cluster:Concentrated cell production around Ulsan and Gwangju generates localized case demand that favors domestic stamping and machining suppliers.
Market Restraints
- Primary aluminum price volatility:London Metal Exchange pricing swings directly compress housing margins, forcing suppliers to index contracts or absorb input cost shocks.
- Die-casting equipment concentration:Large-tonnage aluminum die-casting capacity clusters in China and Germany, creating geographic supply risk for OEMs seeking dual-source strategies.
- Composite fire-barrier integration:Mica sheet and aerogel layering adds processing steps that aluminum extruders cannot easily absorb without dedicated clean-room investments.
Strategic Opportunities
- Second-life battery repurposing:End-of-life EV packs require refurbished or replacement housings for stationary storage applications, opening aftermarket channels outside OEM supply agreements.
- Cell-to-pack architectures:Eliminating module housings shifts structural burden to the main case, expanding aluminum casting and composite sandwich opportunities for housing specialists.
- India's PLI scheme for ACC batteries:Domestic cell manufacturing incentives are attracting housing suppliers to establish stamping and welding operations near Gujarat and Tamil Nadu cell plants.
Industry Challenges
- Multi-physics simulation talent:Coupled thermal-structural-crash modeling requires engineers fluent in LS-DYNA and Star-CCM+ that traditional metal-forming shops rarely employ.
- GB/T 31485.3 certification timelines:China's thermal-runaway propagation testing protocol demands 6-12 months of validation cycles that delay program launches for unqualified suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Battery Cases Market |
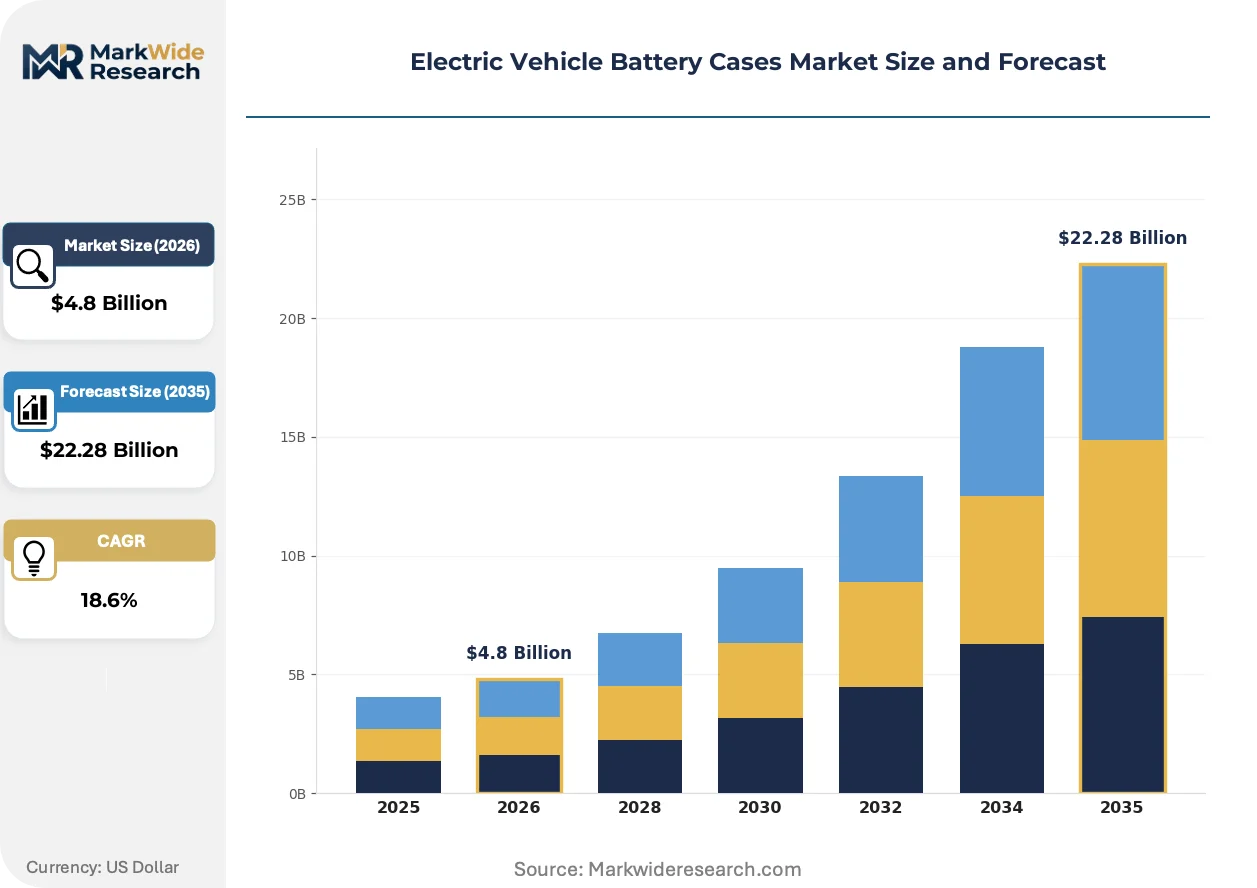
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Aluminum, Steel, Composite, Plastic Product Type: Case, Housing, Module, Enclosure Manufacturing Process: Injection Molding, Stamping, Machining, Extrusion End User: OEMs, Aftermarket Providers, Fleet Operators, Distributors |
| Companies Covered | ThyssenKrupp AG, Magna International Inc., GF Linamar LLC, SGL Carbon, Novelis Inc., Minth Group, TRB Lightweight, Hitachi Metals, Ltd., Norsk Hydro ASA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Battery Cases Market Trends and Innovations
Digital thread integration across design-to-manufacturing workflows is compressing case development cycles while enabling real-time quality verification that traditional inspection protocols cannot match.
Aluminum laser-weld monitoring systems is digitizing joint quality assurance by embedding photodiode arrays directly into welding heads, capturing melt-pool dynamics at 10-kilohertz sampling rates. European premium OEMs now mandate this in-line verification for all structural welds. The technology is digitizing supplier qualification by replacing destructive testing with statistically validated process signatures.
REACH restrictions on hexavalent chromium surface treatments are forcing conversion to trivalent passivation and zirconium-based coatings for aluminum corrosion protection. Housing suppliers serving European export markets must requalify surface finishing lines before 2026 enforcement deadlines. Die-casters in Germany and Austria are absorbing capex for closed-loop trivalent plating systems to maintain OEM supply status.
Fleet operators and battery-leasing companies are unbundling case refurbishment from cell replacement, creating independent service provider demand for housing inspection, repair, and recertification. This disintermediation separates structural warranty responsibility from cell performance guarantees. North American commercial vehicle fleets are pioneering this split-contract model for medium-duty electric trucks.
Electric Vehicle Battery Cases Market Segmentation
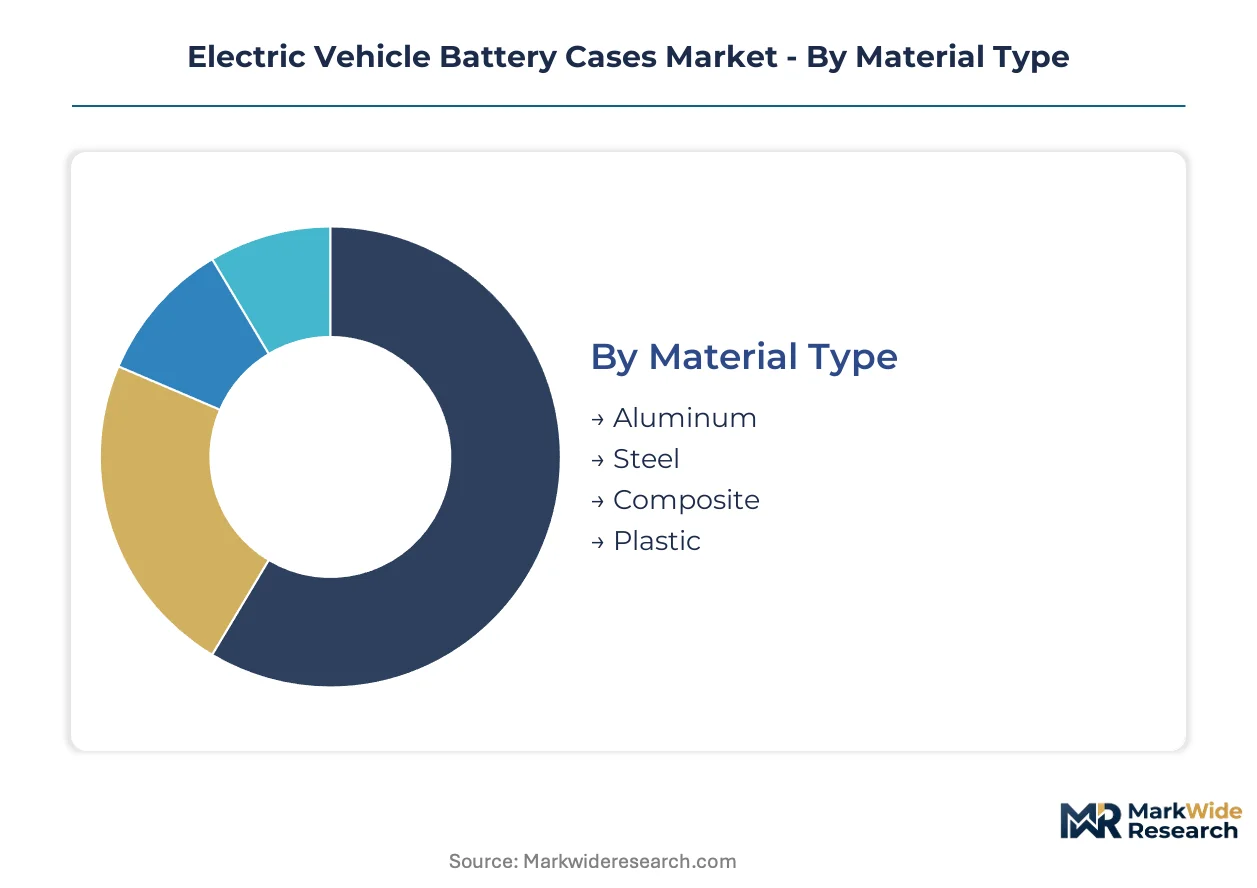
Material selection, manufacturing process, and customer channel each impose distinct certification requirements and margin structures on battery case suppliers. Segmentation reveals where capital intensity concentrates and which technology transitions threaten incumbent positioning.
Material Type:
Cost tier determines thermal conductivity, crash absorption, and recyclability trade-offs across the supplier base.
- Aluminum:Extruded 6xxx-series alloys deliver strength-to-weight ratios above 180 MPa yield strength while accommodating integrated cooling channels. German OEM platforms and South Korean cell manufacturers specify aluminum for 800-volt architectures where thermal management density is non-negotiable.
- Steel:High-strength stamped grades from ThyssenKrupp's Duisburg operations provide intrusion resistance at 40% lower material cost than aluminum, dominating commercial vehicle applications where mass penalties are tolerable.
- Composite:Carbon-fiber sandwich constructions from SGL Carbon cut housing mass by 35% versus aluminum, serving premium sports car programs where battery placement demands extreme weight reduction.
- Plastic:Glass-filled polyamide module housings isolate individual cell groups in lower-voltage architectures, produced via injection molding near cell assembly plants in China and Mexico.
Aluminum holds installed capacity across European and Asian stamping lines. Composite is rotating up the share rankings as cell-to-pack architectures expand structural load requirements.
Product Type:
Application scope defines the boundary between structural crashworthiness and modular replaceability in OEM system design.
- Case:The primary structural container carrying vehicle crash loads and thermal runaway containment, typically fabricated from extruded aluminum side rails joined to stamped or cast end plates. China's GB/T 31485.3 certification mandates 5-minute fire resistance that drives case wall thickness and mica barrier integration.
- Housing:Encloses complete battery packs with integrated cooling manifolds and electrical isolation barriers, requiring multi-physics validation across thermal, structural, and electromagnetic domains. European OEMs specify housing-level modularity to enable platform sharing across vehicle segments.
- Module:Intermediate containers grouping 10-20 cells, rapidly losing share as cell-to-pack architectures eliminate modular intermediates. Remains relevant in commercial vehicle retrofit applications where incremental capacity expansion is required.
- Enclosure:Secondary protective shells for stationary storage repurposing of end-of-life automotive packs, typically simplified steel fabrications without automotive crash certification. Aftermarket refurbishment specialists in North America are building enclosure assembly capacity adjacent to battery recycling facilities.
Case and housing command qualification timelines exceeding 18 months. Module is rotating up the share rankings only in retrofit and second-life channels outside OEM supply agreements.
Manufacturing Process:
Volume scale and geometric complexity dictate equipment selection and geographic supplier clustering.
- Injection Molding:Glass-filled polymer module housings and electrical isolators, constrained to lower-temperature applications below cell thermal runaway thresholds. Tooling amortizes across millions of units for high-volume cell module programs.
- Stamping:High-speed steel and aluminum forming for tray bottoms, side walls, and structural reinforcements, dominating throughput economics at OEM production scales. German and South Korean press shops hold concentrated capacity for 800-ton-plus progressive die lines.
- Machining:CNC finishing of cast or extruded aluminum for cooling channel precision and interface tolerances, serving low-volume premium programs and aftermarket replacement channels where tooling investment is prohibitive.
- Extrusion:Hollow aluminum profiles with integrated cooling passages, eliminating welded joints and cutting thermal interface resistance. Magna's aluminum extrusion operations in Ontario and Austria supply European and North American OEM platforms with single-piece side rail constructions.
Stamping holds installed capacity across automotive supply corridors. Extrusion is gaining share fastest as thermal management integration requirements intensify.
End User:
Customer type separates long-term qualification relationships from transactional procurement with divergent warranty and service expectations.
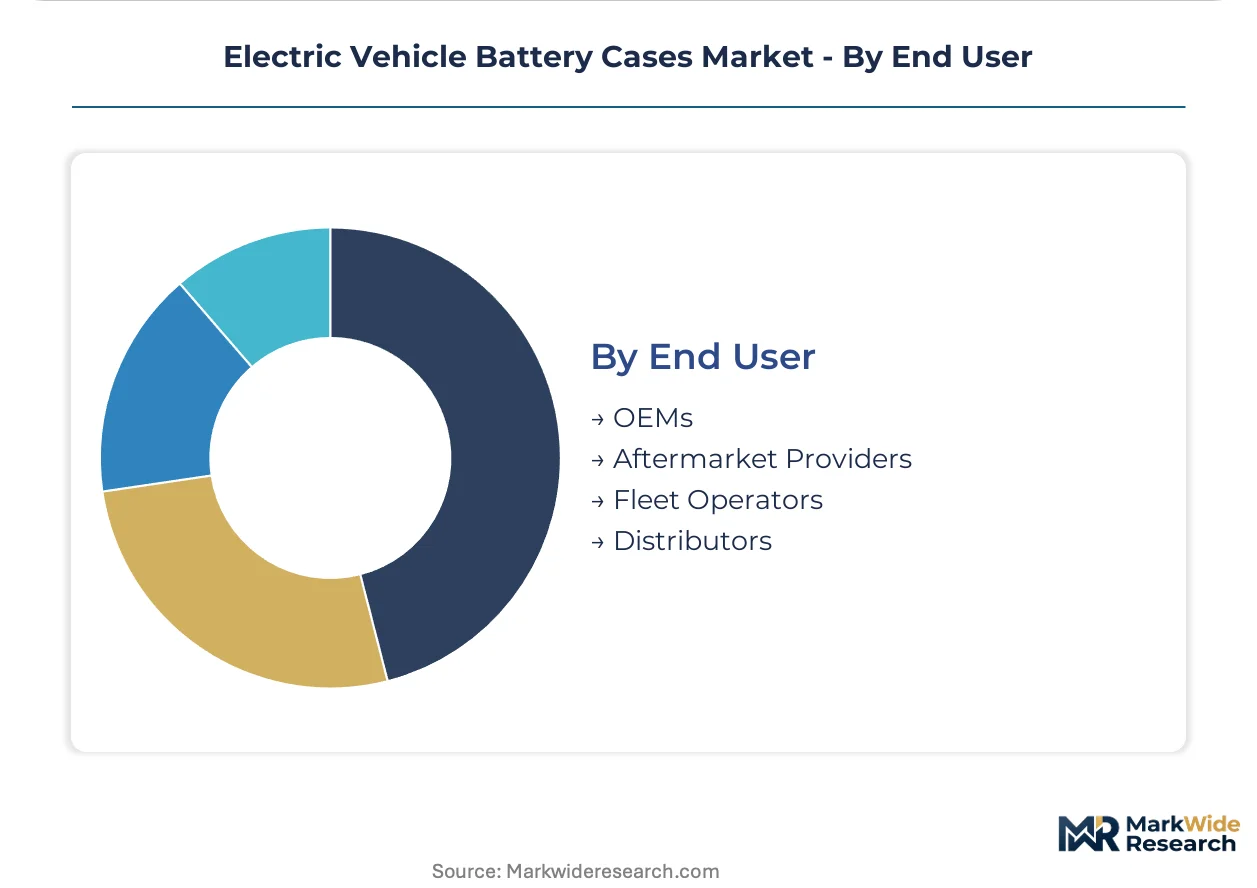
- OEMs:Platform-scale procurement with 7-10 year supply agreements, mandating IATF 16949 certification, crash simulation capabilities, and geographic proximity to vehicle assembly. Volkswagen's Zwickau electric platform and Hyundai's Ulsan complex anchor regional supplier ecosystems.
- Aftermarket Providers:Independent refurbishment and replacement housing demand, unbundled from cell supply and requiring rapid turnaround rather than design collaboration. North American commercial fleets are pioneering split-contract models separating structural warranty from cell performance guarantees.
- Fleet Operators:Battery-leasing companies and logistics operators procuring replacement cases for damage repair and second-life repurposing, prioritizing cost minimization over lightweighting.
- Distributors:Wholesale channels for repair parts and collision replacement, carrying inventory risk and demanding standardized geometries compatible with multiple OEM platforms.
OEMs hold installed capacity across qualified supplier networks. Aftermarket providers are climbing the fastest as fleet electrification expands damage repair and refurbishment demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large-tonnage aluminum die-casting capacity clusters disproportionately in China and Germany, creating geographic supply risk for OEMs pursuing dual-source strategies. Stamping and extrusion lines concentrate near vehicle assembly hubs in South Korea and the United States, while composite fabrication remains anchored in European aerospace corridors.
China
GB/T 31485.3 thermal-runaway propagation testing mandates 5-minute fire resistance standards that compress qualification timelines for unqualified suppliers. MIIT enforcement of GB standards for EV battery safety tightens structural integrity requirements for export-bound enclosures. The Yangtze River Delta hosts concentrated cell-to-pack manufacturing around CATL and BYD facilities, driving localized aluminum housing demand.
Germany
Volkswagen's Zwickau electric platform and BMW's Leipzig assembly anchor procurement of crash-tested aluminum housings from qualified tier suppliers. KBA oversight of EU Battery Regulation implementation forces OEMs to redesign enclosures for end-of-life disassembly and recycled content compliance. The automotive engineering corridor spanning Bavaria and Baden-Württemberg holds Europe's densest concentration of certified aluminum extrusion and stamping capacity.
South Korea
LG Energy Solution and SK On cell production around Ulsan and Gwangju generates localized case demand favoring domestic stamping and machining suppliers. MFDS-aligned safety protocols propagate into housing design specifications for vehicles exported under bilateral trade agreements. The Busan-Ulsan industrial cluster supports integrated aluminum processing from billet casting through finished housing assembly.
United States
NHTSA enforcement of FMVSS 305 electrical safety requirements propagates into housing design specifications for vehicles sold in the domestic market. IRA domestic content incentives are attracting housing suppliers to establish stamping operations near Michigan and Tennessee vehicle assembly plants. Magna's aluminum extrusion operations in Ontario supply cross-border OEM platforms with single-piece side rail constructions.
India
PLI scheme incentives for ACC battery manufacturing are attracting housing suppliers to establish stamping and welding operations near Gujarat and Tamil Nadu cell plants. BIS certification timelines for imported aluminum grades delay qualification of overseas suppliers against domestic fabricators. The Delhi-Mumbai Industrial Corridor hosts emerging tool-and-die capacity serving both automotive OEMs and battery system integrators.
Electric Vehicle Battery Cases Market Competitive Landscape
Steel heritage conglomerates and aluminum extrusion specialists split the market between cost-driven commercial vehicle applications and lightweight passenger car platforms. Supplier qualification timelines exceeding 18 months for OEM-scale programs create defensive moats around incumbent fabricators. Three archetypes dominate: integrated automotive tier suppliers with platform-scale extrusion capacity, metals conglomerates leveraging upstream aluminum or steel processing assets, and composite specialists capturing premium performance segments. Capacity expansion and geographic proximity to cell manufacturing clusters represent the dominant competitive moves as OEMs consolidate platform architectures.
Among Germany-based metals conglomerates, ThyssenKrupp AG occupies a position exemplifying steel heritage conversion into high-strength stamped housings for European OEM platforms. Magna International Inc. anchors the integrated tier-supplier archetype with cross-border aluminum extrusion and assembly capabilities spanning Ontario and Austria. SGL Carbon sits within the composite specialist tier, representing carbon-fiber sandwich constructions that cut housing mass for premium electric sports car programs where battery placement demands extreme weight reduction.
| Leading Market Players |
|---|
| ThyssenKrupp AG |
| Magna International Inc. |
| GF Linamar LLC |
| SGL Carbon |
| Novelis Inc. |
| Minth Group |
| TRB Lightweight |
| Hitachi Metals, Ltd. |
| Norsk Hydro ASA |
| Others |
Pricing and Supply Chain Analysis
Large-tonnage aluminum die-casting capacity clustering in China and Germany concentrates upstream bargaining power with billet suppliers and equipment operators, leaving downstream margin pools with OEM-qualified fabricators who carry 18-month certification timelines and crash-test validation assets.
Pricing Analysis
Aftermarket refurbishment revenue and second-life enclosure sales now drive lifetime value beyond initial OEM supply contracts. Three-tier pricing structure across premium certified, standard qualified, and economy unbranded levels separates crash-tested aluminum housings from commercial vehicle steel trays and repurposed stationary storage shells. Cost compression in standard-grade aluminum extrusions is intensifying because London Metal Exchange price volatility forces suppliers to absorb margin shocks or renegotiate indexed contracts. Fleet operators and battery-leasing companies show highest price sensitivity, while premium OEM platforms prioritize thermal management performance over unit cost.
Supply Chain Analysis
Primary aluminum feedstock draws from Chinese smelters, Russian bauxite refiners, and Australian alumina processors, with secondary scrap recovery expanding in European and North American loops. Critical dependencies include 6xxx-series alloy billet, high-pressure die-casting equipment above 4,000 tons, and mica sheet fire barriers sourced from Indian and Brazilian mines. Single-source vulnerability concentrates in large-tonnage die-casting cell supply, where Chinese and German equipment builders hold effective duopoly. Distribution runs through qualified tier-1 supplier networks with IATF 16949 certification, bypassing open market channels for OEM-scale programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across material technologies, manufacturing processes, and end-user channels creates multiple niche entry points as cell-to-pack architectures and second-life repurposing unbundle traditional OEM supply relationships.
For Market Incumbents: Entrench qualification moats by deepening captive aluminum extrusion capacity in South Korea and Germany, and accelerate GB/T 31485.3 certification assets before Chinese thermal-runaway propagation rules tighten. Composite specialists and steel stampers pose substitution threats in commercial vehicle and premium sports car segments. Control over cooling channel integration IP and laser-weld monitoring technology represents the critical defensive lever. For New Entrants and Emerging Players: Build out refurbishment and recertification capabilities adjacent to North American battery recycling clusters, where fleet operators are unbundling structural warranty from cell performance guarantees. India's PLI scheme for ACC batteries offers the most penetrable geography, with domestic stamping demand outpacing qualified supplier presence near Gujarat and Tamil Nadu cell plants. Pursue rapid-turnaround service contracts rather than platform-scale OEM qualification. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed aluminum extrusion specialists in Ontario and Austria that lack cell-to-pack thermal management capabilities but hold OEM relationships. Long-term viability hinges on 800-volt architecture penetration and composite sandwich adoption rates. Watch for inflection in laser-weld monitoring mandates from European premium OEMs as a signal of process control premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Cell-to-Pack Thermal Management Integration | Single-piece aluminum side rails with embedded cooling channels eliminate weld joints and cut thermal resistance for 800-volt platforms. |
| GB/T 31485.3 Certification Investment | Chinese thermal-runaway propagation testing mandates 5-minute fire resistance standards that compress qualification timelines for unqualified suppliers. |
| Second-Life Refurbishment Capacity Buildout | Stationary storage repurposing of end-of-life automotive packs creates aftermarket enclosure demand outside OEM supply agreements. |
| REACH-Compliant Surface Finishing Conversion | Trivalent passivation and zirconium-based coating requalification maintains European export market access before 2026 enforcement deadlines. |
| Laser-Weld Monitoring Technology Deployment | Photodiode arrays capturing melt-pool dynamics at 10-kilohertz sampling rates replace destructive testing with statistically validated process signatures. |
Research Methodology
Cross-validation between OEM platform engineering disclosures and supplier certification databases anchors the qualitative findings in this study. Primary interviews with Tier 1 supplier procurement managers, OEM battery system architects, aftermarket refurbishment specialists, and aluminum extrusion plant directors combined with secondary validation from MIIT GB standard filings, KBA type-approval records, NHTSA FMVSS 305 enforcement data, and vehicle production databases. Bottom-up capacity modeling and top-down OEM procurement estimates were reconciled through iterative triangulation.
Calibration against historical platform launch cycles and certification timeline data informed the analytical framework across the projection horizon. Segmentation dimensions modeled include material type, manufacturing process, product architecture, and regional regulatory cluster, with vehicle class and propulsion voltage tier as automotive-specific layers. CAGRs were derived from installed capacity buildouts, OEM platform consolidation roadmaps, and thermal management performance thresholds. Forecast inputs incorporated aluminum price trajectory assumptions and cell-to-pack architecture penetration rates.
Stress conditions across London Metal Exchange volatility bands, GB/T certification timeline delays, and composite fire-barrier supply constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about OEM platform consolidation and thermal runaway propagation rule evolution. Cross-checking against IHS Markit vehicle production forecasts and CRU aluminum market balances is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
France Electric Vehicle Market
Electric Vehicles
Europe Electric Car Market
Electric Vehicles
Electric Vehicle NVH Material Market
Electric Vehicles
Premium Electric Motorcycle Market
Electric Vehicles
US Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Luxury Electric Vehicle Market
Electric Vehicles
Right Hand Drive Electric Vehicle Market
Electric Vehicles
Used EV Market
Electric Vehicles
Battery-Only Electric Bus Market
Electric Vehicles
Global Smart Electric Drive Market
Electric Vehicles
Electric Tricycle Market
Electric Vehicles
Electric Axle Drive Systems Market
Electric Vehicles
Asia Pacific Electric Three-Wheelers Market
Electric Vehicles
Global Electric Vehicles Market
Electric Vehicles
Global Industrial Electric Vehicle Market
Electric Vehicles
South America Automotive High Performance Electric Vehicles Market