
 BEV On-Board Charger Market | 2026-2036
BEV On-Board Charger Market Size, Share, and Industry Trends Forecast 2026-2036
BEV On-Board Charger Market Insights
Power electronics engineering talent is bifurcating between legacy automotive hubs and emerging EV manufacturing clusters, constraining charger design velocity for tier-two suppliers. BorgWarner leverages its inverter and power module expertise to anchor integrated drivetrain-charger systems. Delta Energy Systems competes through high-frequency switching architectures that reduce magnetics mass. STMicroelectronics dominates silicon carbide substrate supply, a chokepoint for next-generation charger efficiency.
A BEV on-board charger converts alternating current from the grid into direct current for battery pack storage, typically operating at power levels from 3.3 kW to 22 kW with peak efficiencies exceeding 95 percent using silicon carbide MOSFETs and active power factor correction circuits. Bidirectional chargers represent the fastest-growing product type as vehicle-to-grid protocols mature, while AC chargers sustain the largest installed base across home charging stations where overnight dwell time offsets lower power density. Installation type segmentation reveals fleet depots as the densest margin pool due to centralized procurement and 24-hour utilization rates.
China's MIIT enforces GB/T charging compatibility and efficiency benchmarks that gate domestic market access, while Europe's F-Gas Regulation and CE marking framework constrain refrigerant choices in liquid-cooled charger designs. The EU AI Act introduces conformity assessment complexity for smart charging algorithms that optimize grid load balancing. Stakeholders must monitor how harmonization between China's GB/T standards and Europe's CCS2 protocol evolves, as divergence would fragment charger platform economics and force redundant certification investments.
Market Dynamics
The transition from silicon IGBTs to silicon carbide MOSFETs is compressing charger form factors while elevating thermal management requirements, forcing suppliers to re-architect power stages around substrate availability and liquid-cooled integration.
Growth Catalysts
- GB/T Standard Harmonization:China's MIIT mandates unified charging protocols that streamline domestic certification and accelerate platform consolidation for local automakers.
- Fleet Electrification Mandates:Corporate sustainability targets and municipal procurement rules in Germany and California are concentrating demand for high-power bidirectional chargers in depot installations.
- Silicon Carbide Substrate Scaling:Wafer diameter expansion from six-inch to eight-inch production lines is reducing power semiconductor costs and enabling 22 kW onboard charger penetration into mid-market vehicle segments.
Market Restraints
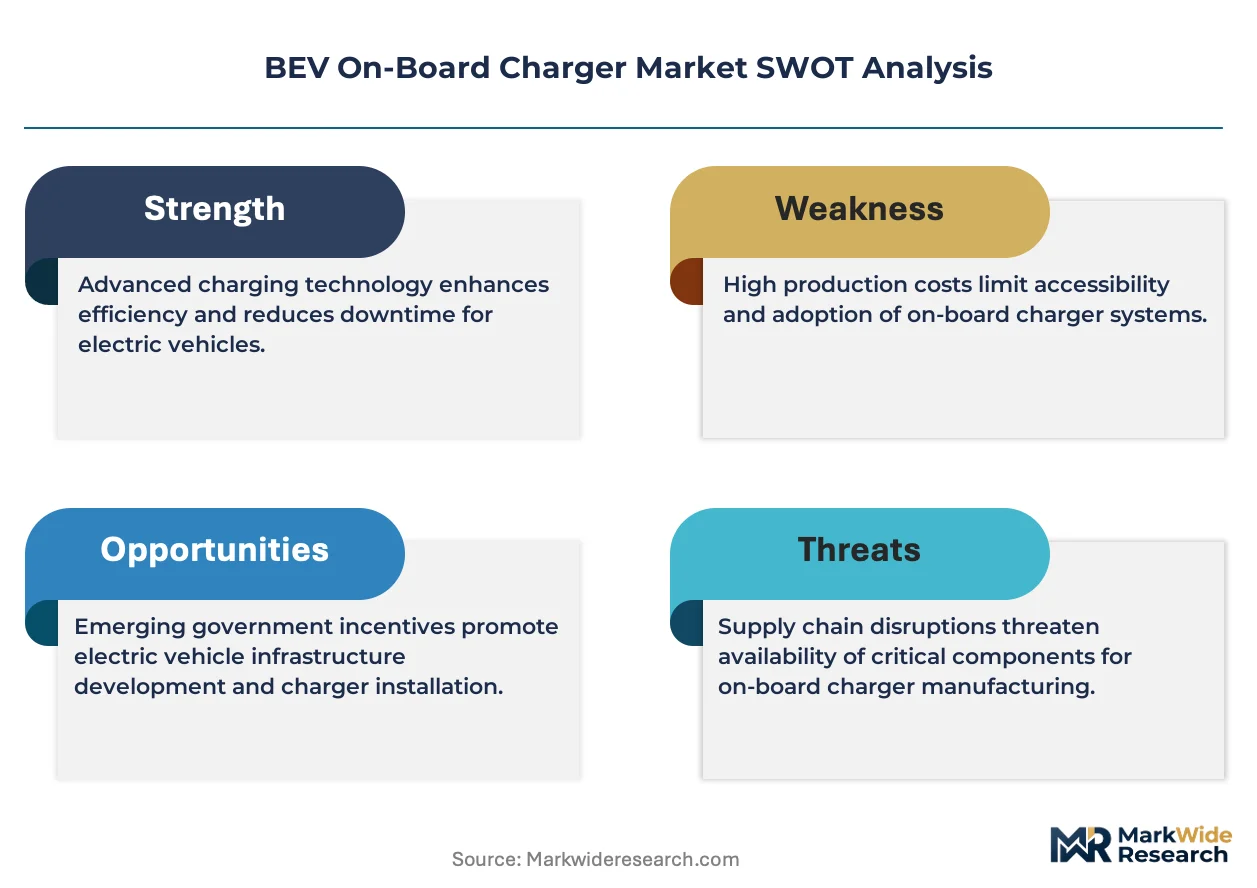
- Substrate Supply Concentration:STMicroelectronics, Wolfspeed, and Infineon control 80 percent of automotive-grade silicon carbide substrate supply, creating allocation risk for tier-two charger suppliers.
- F-Gas Compliance Costs:Europe's F-Gas Regulation restricts refrigerant choices in liquid-cooled designs, forcing thermal engineering redesigns and qualification retesting.
- IGBT Stranded Assets:Existing silicon-based charger production lines face accelerated obsolescence as automakers specify SiC-only architectures for 800V platforms.
Strategic Opportunities
- V2G Protocol Maturation:IEEE 1547 and ISO 15118-20 standardization is opening grid services revenue streams for bidirectional charger deployments in California and Texas.
- India PLI Scheme:Production-linked incentives for advanced automotive electronics are attracting charger assembly investments targeting domestic EV manufacturers and export markets.
- Wireless Charging Integration:Inductive pad architectures are converging with onboard power electronics, creating white space for resonant coil and inverter co-design specialists.
Industry Challenges
- Power Electronics Talent Scarcity:Magnetics design and wide-bandgap semiconductor application expertise concentrates in legacy automotive hubs and emerging EV clusters, constraining tier-two supplier velocity.
- Multi-Protocol Certification Burden:Simultaneous GB/T, CCS2, and CHAdeMO qualification timelines extend product launch cycles and fragment engineering resources.
- Thermal-Mechanical Integration Complexity:Liquid-cooled charger modules must coexist with battery pack thermal loops, requiring systems-level optimization that exceeds traditional tier-one electrical competencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | BEV On-Board Charger Market |
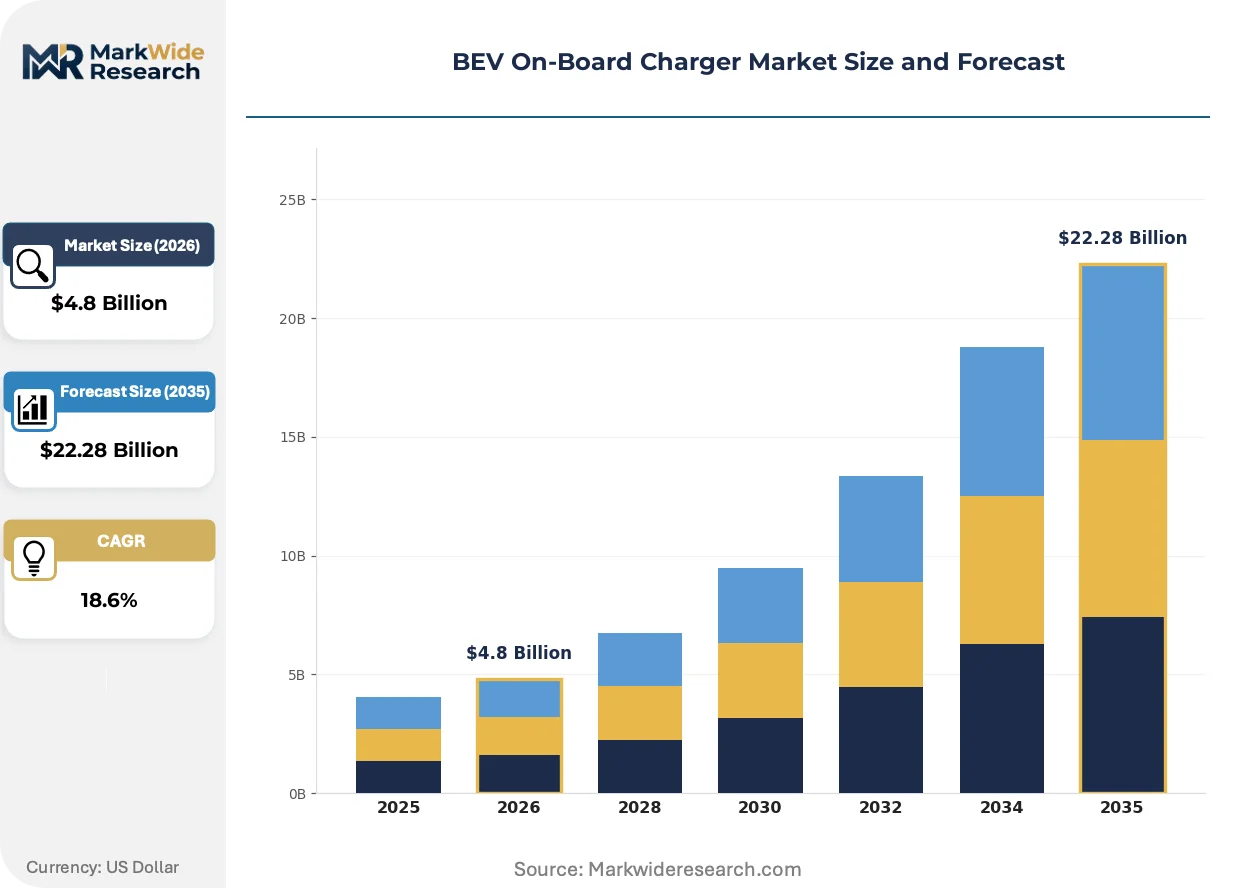
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Chargers, DC Chargers, Bidirectional Chargers, Fast Chargers, Portable Chargers Charging Technology: Inductive Charging, Conductive Charging, Resonant Inductive, Wireless Power Transfer, Plug-in Charging End User: Battery Electric Vehicles, Plug-in Hybrid Vehicles, Commercial Fleets, Electric Buses, Delivery Vehicles Installation Type: Home Charging Stations, Workplace Charging, Public Charging Points, Private Garages, Fleet Depots |
| Companies Covered | BorgWarner, Delta Energy Systems, Eaton, STMicroelectronics, Valeo, BRUSA Elektronik, Toyota Industries Corporation, Bel Fuse, innolectric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
BEV On-Board Charger Market Trends and Innovations
Power semiconductor material transitions and bidirectional energy flow architectures are redefining charger performance benchmarks and supplier value capture mechanisms.
Silicon carbide MOSFETs enable switching frequencies above 100 kHz, shrinking magnetics mass and enabling compact onboard packaging. Premium sedan and SUV platforms from German and Korean automakers are adopting SiC-based 11 kW and 22 kW chargers as standard equipment. This technology is supplanting silicon IGBT designs across the 6.6 kW and above power classes, compressing incumbent semiconductor supplier margins and reallocating value toward substrate and packaging specialists.
Europe's F-Gas Regulation and accompanying CE marking framework are constraining refrigerant selection in liquid-cooled charger designs, pushing manufacturers toward CO2-based thermal systems. The regulation elevates engineering qualification costs but creates competitive moats for suppliers with in-house thermal simulation capabilities. High-power fleet depot installations in Germany and the Netherlands face the strictest compliance timelines, accelerating local sourcing of refrigerant-compliant components.
Fleet operators are consolidating procurement decisions at the corporate sustainability office level, displacing fragmented site-by-site purchasing. Centralized tenders specify total-cost-of-ownership metrics including energy efficiency and vehicle-to-building capability, favoring integrated charger-inverter suppliers. This concentration is most visible in California and Texas, where utility demand response programs amplify the value of bidirectional charging infrastructure.
BEV On-Board Charger Market Segmentation
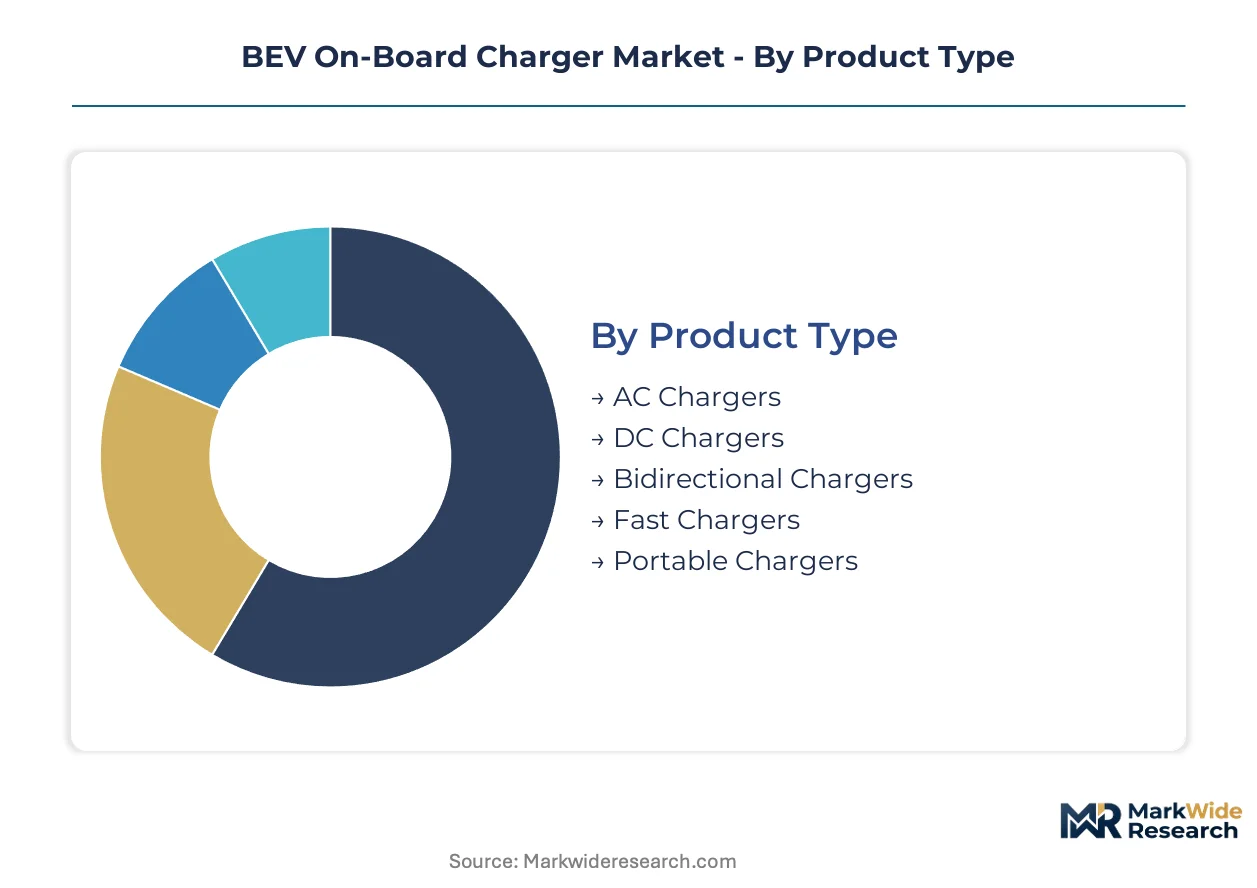
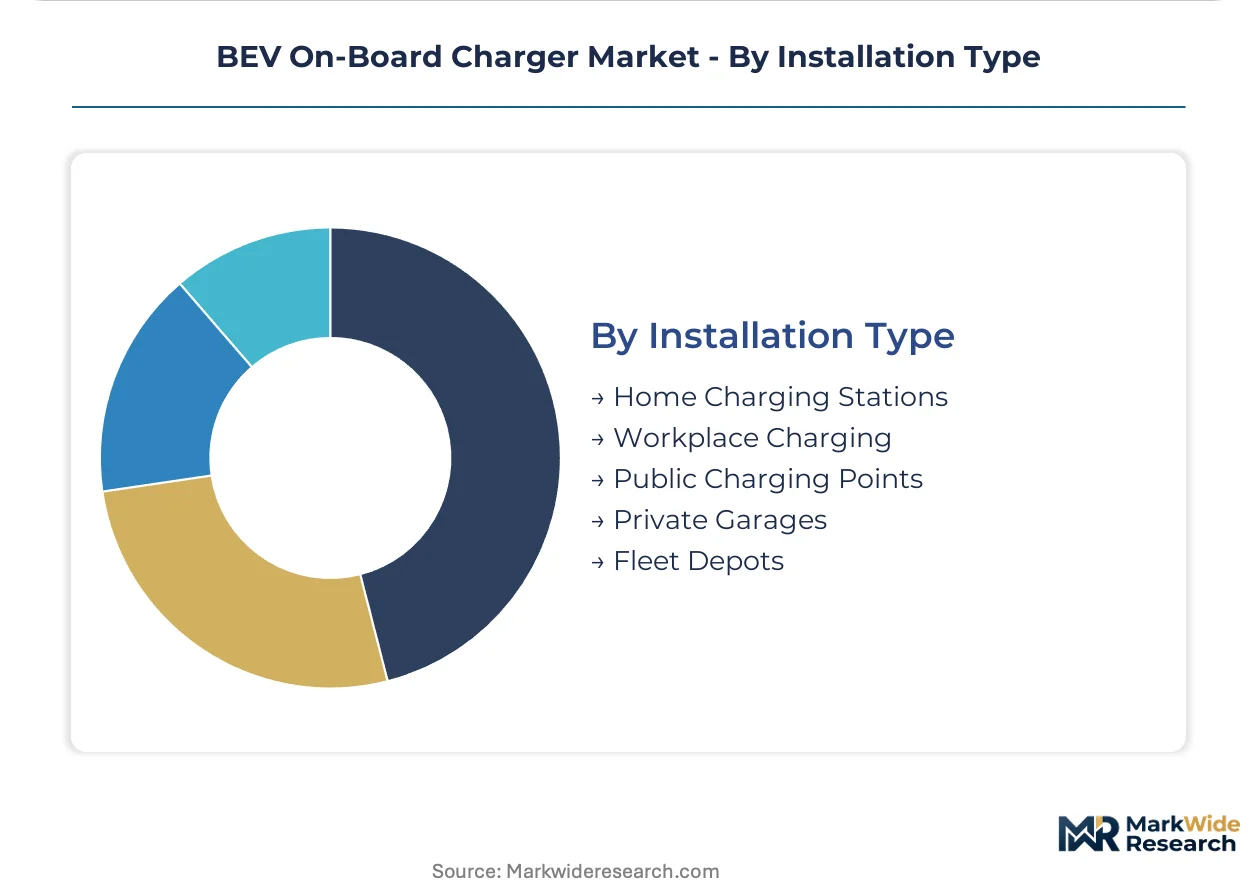
Segmentation in the BEV on-board charger market reveals how power electronics architecture, charging protocol compatibility, and installation infrastructure create distinct margin pools. Each dimension carries different regulatory exposure, from China's GB/T mandates for product types to Europe's F-Gas Regulation for thermal design in installation categories.
Product Type:
Domestic market penetration concentrates on AC and bidirectional architectures in China and Europe, while export-led growth in portable and fast charger segments targets emerging EV markets in Southeast Asia and Latin America.
- AC Chargers:These units convert grid alternating current to direct current at 3.3 kW to 22 kW power levels using silicon carbide MOSFETs and active power factor correction. Demand clusters in German and Chinese residential installations where overnight dwell time offsets lower power density. AC chargers command the established base.
- Bidirectional Chargers:Vehicle-to-grid capable architectures enable energy flow from battery packs back to the grid or buildings under IEEE 1547 and ISO 15118-20 protocols. California and Texas fleet operators are consolidating procurement around this capability to capture utility demand response revenue. The steepest expansion runs through bidirectional chargers.
- DC Chargers:Direct current units bypass onboard conversion for high-speed external charging but require robust onboard rectification interfaces.
- Fast Chargers:High-power architectures demand advanced thermal management and substrate availability from STMicroelectronics and Wolfspeed supply channels.
- Portable Chargers:Compact emergency units target secondary vehicle markets and rental fleet flexibility requirements in India and Brazil.
Power class specifications are diverging between 400V silicon IGBT legacy platforms and 800V silicon carbide architectures.
Charging Technology:
Cost tier stratification separates premium resonant inductive systems from standardized conductive charging, with wireless architectures commanding three to five times the bill-of-materials cost of plug-in equivalents.
- Conductive Charging:Physical connector-based systems dominate through GB/T, CCS2, and CHAdeMO protocol implementations. German automakers specify conductive architectures for 11 kW and 22 kW onboard integration in premium sedan platforms. Conductive charging commands the established base.
- Inductive Charging:Pad-based wireless systems eliminate connector wear and enable automated fleet charging in depot environments. The Netherlands and Norway are deploying inductive infrastructure for electric bus corridors where connector maintenance costs exceed hardware premiums. The steepest expansion runs through inductive charging.
- Resonant Inductive:Tuned coil architectures reduce alignment sensitivity for consumer parking applications.
- Wireless Power Transfer:Dynamic charging embedded in roadways targets commercial corridor electrification trials in Sweden and Germany.
- Plug-in Charging:Remains the cost-optimized default for residential and workplace installations across all major markets.
Magnetics design complexity escalates with switching frequency demands above 100 kHz.
End User:
Volume concentration follows fleet electrification mandates, with commercial procurement displacing individual consumer purchasing in high-utilization segments.
- Commercial Fleets:Centralized procurement at corporate sustainability offices specifies total-cost-of-ownership metrics including bidirectional capability and energy efficiency. California and Germany enforce the strictest fleet emissions mandates, concentrating high-power charger demand in depot configurations. Commercial fleets command the established base.
- Delivery Vehicles:Last-mile electrification in urban zones drives 22 kW onboard charger specification for rapid turnaround between shifts. Amazon and DHL fleet specifications are standardizing around silicon carbide-based architectures to minimize charging downtime. The steepest expansion runs through delivery vehicles.
- Battery Electric Vehicles:Passenger car platforms anchor mid-market 6.6 kW to 11 kW charger deployment.
- Plug-in Hybrid Vehicles:Smaller battery packs sustain 3.3 kW to 6.6 kW charger economics with lower thermal management requirements.
- Electric Buses:High-capacity depot charging demands liquid-cooled 22 kW onboard systems with F-Gas-compliant refrigerant loops.
Utilization rate differentiates margin structures between 24-hour fleet operations and intermittent residential charging.
Installation Type:
Margin concentration pools in fleet depots due to centralized procurement scale, while home charging stations fragment across individual consumer decisions with lower per-unit profitability.
- Fleet Depots:Centralized installations achieve 24-hour utilization rates and bulk procurement power unavailable to residential segments. Germany and the Netherlands face the strictest F-Gas Regulation compliance timelines for liquid-cooled charger modules in depot environments. Fleet depots command the established base.
- Home Charging Stations:Residential installations sustain the largest installed base volume across China, Germany, and the United States. Overnight dwell time offsets lower power density requirements, enabling cost-optimized AC charger specification in mid-market vehicle segments. The steepest expansion runs through home charging stations.
- Workplace Charging:Employer-subsidized installations concentrate in California and Texas corporate campuses.
- Public Charging Points:Utility-operated infrastructure prioritizes interoperability over onboard charger specification influence.
- Private Garages:Premium residential installations in Korean and German urban centers specify 22 kW bidirectional capability for vehicle-to-home applications.
Thermal-mechanical integration complexity escalates as liquid-cooled modules must coexist with battery pack thermal loops.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys onboard chargers predominantly in fleet depot configurations with bidirectional capability, while Germany and the United States concentrate residential AC installations where overnight dwell time shapes power class specifications differently.
China
Fleet electrification mandates from MIIT accelerate 22 kW bidirectional charger deployment in commercial depots across the Yangtze River Delta. GB/T standard harmonization streamlines domestic certification while gating market access for foreign suppliers. Shenzhen and Shanghai manufacturing clusters anchor silicon carbide substrate packaging operations for integrated drivetrain-charger systems.
Germany
Premium sedan and SUV platforms from Stuttgart and Munich automakers specify SiC-based 11 kW and 22 kW chargers as standard equipment. The F-Gas Regulation restricts refrigerant choices in liquid-cooled designs, forcing thermal engineering redesigns for CE marking compliance. Bavaria's industrial corridor concentrates power electronics talent for magnetics design and wide-bandgap semiconductor applications.
United States
California and Texas fleet operators consolidate procurement around vehicle-to-grid capability to capture utility demand response revenue under IEEE 1547 protocols. The Inflation Reduction Act production tax credits incentivize domestic charger assembly investments. Detroit automotive engineering hubs compete with Austin and Silicon Valley emerging EV clusters for power electronics talent.
South Korea
Seoul Capital Area premium vehicle manufacturers specify 800V silicon carbide architectures for export-oriented battery electric sedans. METI-aligned efficiency benchmarks push suppliers toward high-frequency switching designs. Busan-Ulsan industrial complexes host thermal-mechanical integration specialists for liquid-cooled charger modules.
India
Production-linked incentive schemes from the central government attract charger assembly investments targeting domestic EV manufacturers and Southeast Asian export markets. BIS certification requirements for automotive electronics create qualification timelines that favor established component suppliers. Tamil Nadu and Gujarat manufacturing zones concentrate final assembly operations for portable and mid-power AC charger segments.
BEV On-Board Charger Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidated substrate supply creating allocation chokepoints for tier-two charger suppliers. The upper tier combines power semiconductor fabrication with thermal system integration, while mid-tier competitors rely on external sourcing for silicon carbide MOSFETs. Two strategic archetypes dominate: integrated drivetrain-charger system suppliers and high-frequency switching architecture specialists. Competitive moves center on backward integration into substrate supply and geographic expansion into India PLI scheme jurisdictions.
Among diversified automotive component manufacturers, BorgWarner occupies a position exemplifying integrated drivetrain-charger system supply, while STMicroelectronics anchors the substrate specialist tier controlling automotive-grade silicon carbide wafer allocation. Delta Energy Systems represents the high-frequency switching architecture archetype competing through magnetics mass reduction.
| Leading Market Players |
|---|
| BorgWarner |
| Delta Energy Systems |
| Eaton |
| STMicroelectronics |
| Valeo |
| BRUSA Elektronik |
| Toyota Industries Corporation |
| Bel Fuse |
| innolectric |
| Others |
Pricing and Supply Chain Analysis
Eight-inch silicon carbide wafer capacity utilization rates at STMicroelectronics and Wolfspeed facilities determine cost floors for 22 kW onboard charger modules, concentrating pricing power among substrate specialists while compressing margins for tier-two suppliers dependent on spot procurement.
Pricing Analysis
Long-term offtake agreements dominate procurement between German automakers and integrated drivetrain suppliers, locking in silicon carbide MOSFET volumes across multi-year vehicle platform cycles. Three-tier pricing structure across premium SiC-based 22 kW systems, standard 11 kW mid-market units, and economy 6.6 kW silicon IGBT legacy designs reflects certification grade differentiation under GB/T and CE marking frameworks. Cost compression in the economy tier intensifies as 800V platform mandates accelerate IGBT production line obsolescence. Fleet operators in California and Germany exhibit lowest price sensitivity due to total-cost-of-ownership procurement metrics, while individual residential buyers in India and Brazil drive hard bargaining on portable charger segments.
Supply Chain Analysis
Just-in-time inventory strategies prevail among Korean and German automakers for silicon carbide substrates, while Chinese depot operators maintain strategic stockpiles of GB/T-compliant power modules to buffer against MIIT certification delays. Manufacturing concentrates in China, Germany, and South Korea, with substrate fabrication anchored in STMicroelectronics' Italian and Singapore facilities and Wolfspeed's North American operations. Supply chains draw from six-inch wafer legacy capacity and emerging eight-inch lines, magnetics copper windings, and F-Gas-compliant refrigerant thermal systems. Single-source vulnerability runs through STMicroelectronics, Wolfspeed, and Infineon controlling automotive-grade silicon carbide substrate allocation. Distribution runs through Tier 1 integrated drivetrain suppliers and direct OEM platform engineering relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The BEV onboard charger market is navigating a cyclical recovery driven by fleet electrification mandate waves in Germany, California, and China, with procurement volumes expanding as corporate sustainability targets harden into enforceable compliance deadlines.
For Market Incumbents: Secure captive silicon carbide substrate supply through backward integration or long-term offtake agreements with STMicroelectronics and Wolfspeed to defend against allocation chokepoints. Expand in-house thermal simulation capabilities to capture F-Gas Regulation compliance premiums in European depot installations. Prioritize certification investment for GB/T-CCS2 protocol harmonization to avoid redundant engineering qualification costs.
For New Entrants and Emerging Players: Anchor in India's PLI scheme jurisdictions to access production-linked incentives for advanced automotive electronics assembly targeting domestic EV manufacturers and Southeast Asian export markets. Target portable charger and mid-power AC segments where BIS certification timelines favor established component partnerships over integrated system competition. Pursue co-design relationships with resonant coil specialists for wireless charging integration opportunities in Dutch and Norwegian bus corridor deployments.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors substrate and packaging specialists over commodity power electronics assemblers, with value capture migrating upstream toward silicon carbide wafer and thermal management capabilities. Long-term viability over the next decade rests on backward integration depth and protocol certification breadth. Monitor IEEE 1547 and ISO 15118-20 standardization velocity as the inflection signal for vehicle-to-grid revenue model maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Substrate Backward Integration | Captive eight-inch wafer supply secures allocation priority from STMicroelectronics and Wolfspeed for 800V platform ramps. |
| GB/T-CCS2 Dual Protocol Certification | Harmonized qualification streamlines market access across China's MIIT mandates and European CE marking frameworks. |
| F-Gas-Compliant Thermal System Development | CO2-based refrigerant loops unlock German and Dutch fleet depot procurement concentrated under strictest compliance timelines. |
| Vehicle-to-Grid Software Platform Investment | IEEE 1547 protocol readiness captures California and Texas utility demand response revenue streams from bidirectional chargers. |
| India PLI Scheme Manufacturing Footprint | Production-linked incentives attract assembly investments targeting domestic EV manufacturers and Southeast Asian export markets. |
Research Methodology
Cross-validation between OEM platform engineering disclosures and Tier 1 supplier procurement data anchors the qualitative findings on silicon carbide adoption trajectories and power class specifications. Primary interviews with automotive power electronics directors, thermal system engineers, fleet sustainability officers, and semiconductor substrate procurement leads combined with secondary validation from vehicle production databases, IHS Markit registration data, MIIT GB/T certification filings, and SEC supplier filings. Bottom-up charger unit forecasts triangulate against top-down BEV production projections across the analysis window.
Sensitivity analysis on silicon carbide substrate pricing, F-Gas Regulation compliance cost trajectories, and fleet electrification mandate enforcement timelines frames the forecast confidence intervals. Segmentation dimensions modeled span product type, charging technology, end user category, installation infrastructure, and regional regulatory cluster throughout the forecast period. CAGRs derive from power class penetration curves, vehicle platform electrification roadmaps, and charging protocol standardization velocity. Forecast inputs include OEM platform engineering specifications, utility demand response program expansion, and substrate wafer capacity buildout announcements.
Material uncertainties — silicon carbide substrate allocation disputes, GB/T-CCS2 protocol divergence, and F-Gas Regulation enforcement variance — sit outside the modeled envelope. Forecasts reflect assumptions on technology transition rates and regulatory harmonization pathways. Revision becomes warranted when substrate supply concentration or protocol fragmentation crosses thresholds that alter platform engineering economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Europe Electric Bus Market
Electric Vehicles
Wireless Electric Vehicle Charging Market
Electric Vehicles
North America Electric Truck Market
Electric Vehicles
Germany Solar E-Bike Market
Electric Vehicles
E-Axle Market
Electric Vehicles
Hoverboard Scooter Market
Electric Vehicles
Electric Vehicle Ambient Lighting Market
Electric Vehicles
Electric Vehicle Extruded Aluminum Battery Trays Market
Electric Vehicles
United Kingdom Hybrid Electric Vehicle Battery Market
Electric Vehicles
UK Electric Vehicle Market
Electric Vehicles
Electric Vehicle Helmet Market
Electric Vehicles
Electric Vehicle (EV) Range Extender Market
Electric Vehicles
E-Bike Market
Electric Vehicles
Electric Vehicle Lithium-Ion Battery Market
Electric Vehicles
Europe Electric Vehicle Market
Electric Vehicles
Commercial Vehicle Traction Battery Systems Market