
 India Dental Insurance Market | 2026-2036
India Dental Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
India Dental Insurance Market Foresight
Asset-light digital distribution models are reshaping competitive entry barriers in India dental insurance. Bajaj Allianz General Insurance leverages its extensive agent network to sustain rural penetration while competing on premium affordability. Tata AIG General Insurance anchors its position through corporate tie-ups, whereas Star Health and Allied Insurance specializes in preventive-care bundled policies that differentiate its portfolio. ICICI Lombard Health Insurance controls a significant share of online direct-to-customer channels, extending its reach without heavy branch infrastructure.
India dental insurance constitutes a specialized health coverage product designed to indemnify policyholders against diagnostic, preventive, restorative, and prosthodontic treatment costs, typically subject to waiting periods, sub-limits, and co-payment clauses. The product serves both individual risk-mitigation needs and employer-sponsored employee benefit schemes, with claims adjudication hinging on procedure-wise fee schedules negotiated with network dental clinics. Individual and family policy types dominate current premium volumes, though employer-sponsored segments exhibit the steepest growth trajectory as workforce wellness budgets expand. Comprehensive coverage levels command higher margins than basic preventive plans, while annual payment modes reduce insurer acquisition costs relative to monthly premium collection cycles.
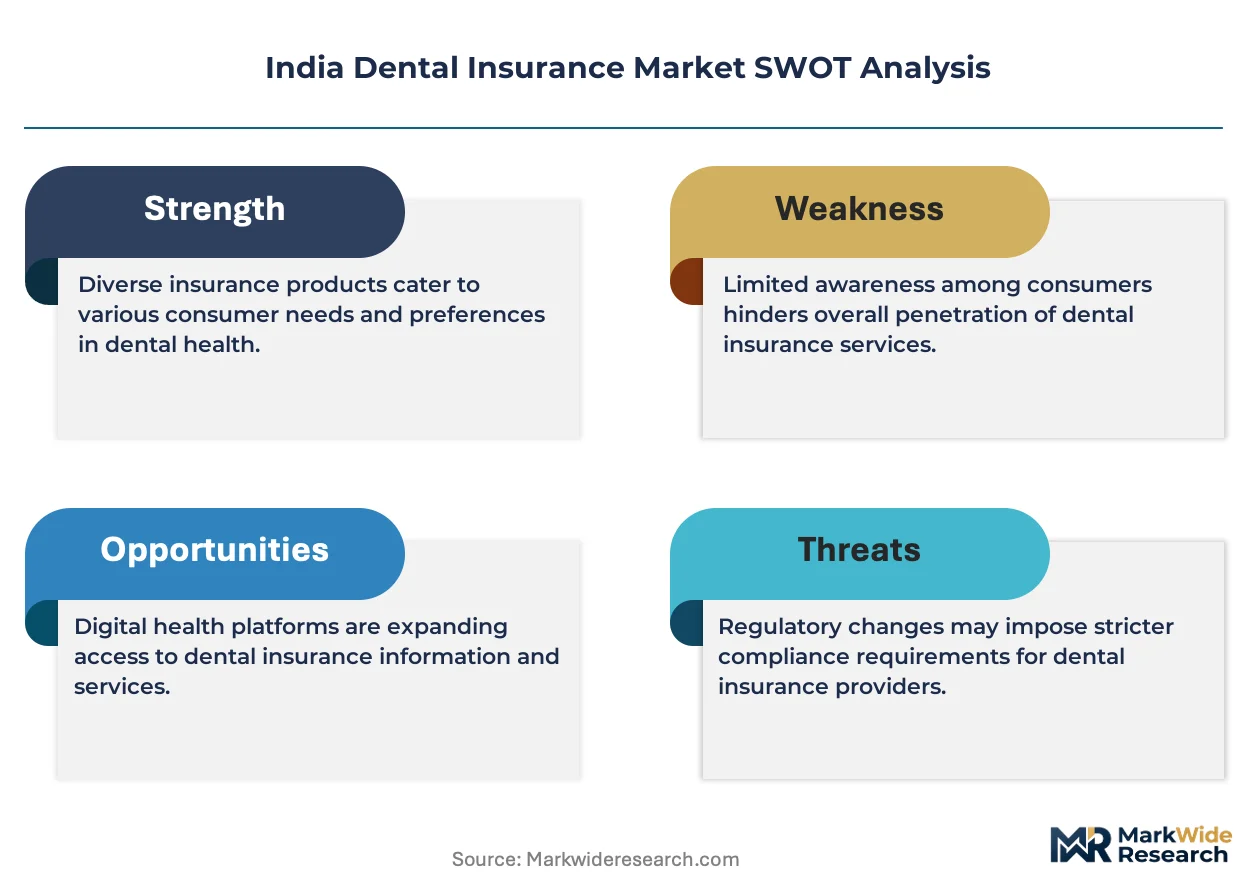
IRDAI governs product filing, solvency, and consumer protection standards for all dental insurance offerings in India, while the Insurance Ombudsman mechanism addresses grievance escalation. BIS certification requirements for medical devices indirectly influence insurer-provider network agreements on implant and prosthodontic reimbursement rates. Stakeholders must monitor IRDAI's evolving sandbox regulations for bite-sized dental micro-policies, as these could unlock mass-market penetration among informal-sector workers lacking employer coverage.
Market Dynamics
IRDAI's sandbox framework for micro-insurance products is dismantling legacy distribution economics, enabling bite-sized dental coverage to reach informal-sector workers through mobile-first channels previously inaccessible to traditional underwriters.
Growth Catalysts
- Employer wellness mandates:Mid-sized enterprises across Maharashtra and Karnataka are bundling dental riders into group health policies to reduce absenteeism from untreated oral conditions.
- PLI scheme spillover:Production-linked incentives for medical device manufacturing are compressing implant and prosthodontic costs, expanding reimbursable procedure coverage at lower premium points.
- Digital KYC protocols:Aadhaar-linked instant verification is collapsing policy issuance timelines from days to minutes for individual purchasers.
Market Restraints
- Provider network fragmentation:Tier-2 and Tier-3 cities lack sufficient empaneled dental clinics, forcing insurers to reimburse out-of-network providers at uncontrolled fee-for-service rates.
- Adverse selection concentration:Individual policyholders with pre-existing periodontal conditions dominate voluntary enrollment, skewing claims ratios before mandatory waiting periods expire.
- Co-payment resistance:Mandatory patient cost-sharing clauses trigger mid-term lapses among price-sensitive subscribers in Gujarat and Rajasthan markets.
Strategic Opportunities
- Gujarat dental tourism corridor:Ahmedabad and Surat clinics attract overseas patients for implant procedures, creating cross-border premium collection potential for insurers with international provider networks.
- Preventive-care gamification:Mobile apps rewarding twice-annual checkups with premium discounts are penetrating younger demographics in Bengaluru and Hyderabad.
- IRDAI sandbox micro-policies:Bite-sized coverage for single procedures is unlocking first-time insurance penetration among gig economy workers lacking employer benefits.
Industry Challenges
- Claims adjudication automation:Procedure-code standardization gaps between insurer platforms and clinic management software create manual verification backlogs exceeding 45 days.
- Network clinic credentialing:BIS certification requirements for sterilization equipment delay empaneled provider expansion in Tamil Nadu and Kerala.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Dental Insurance Market |
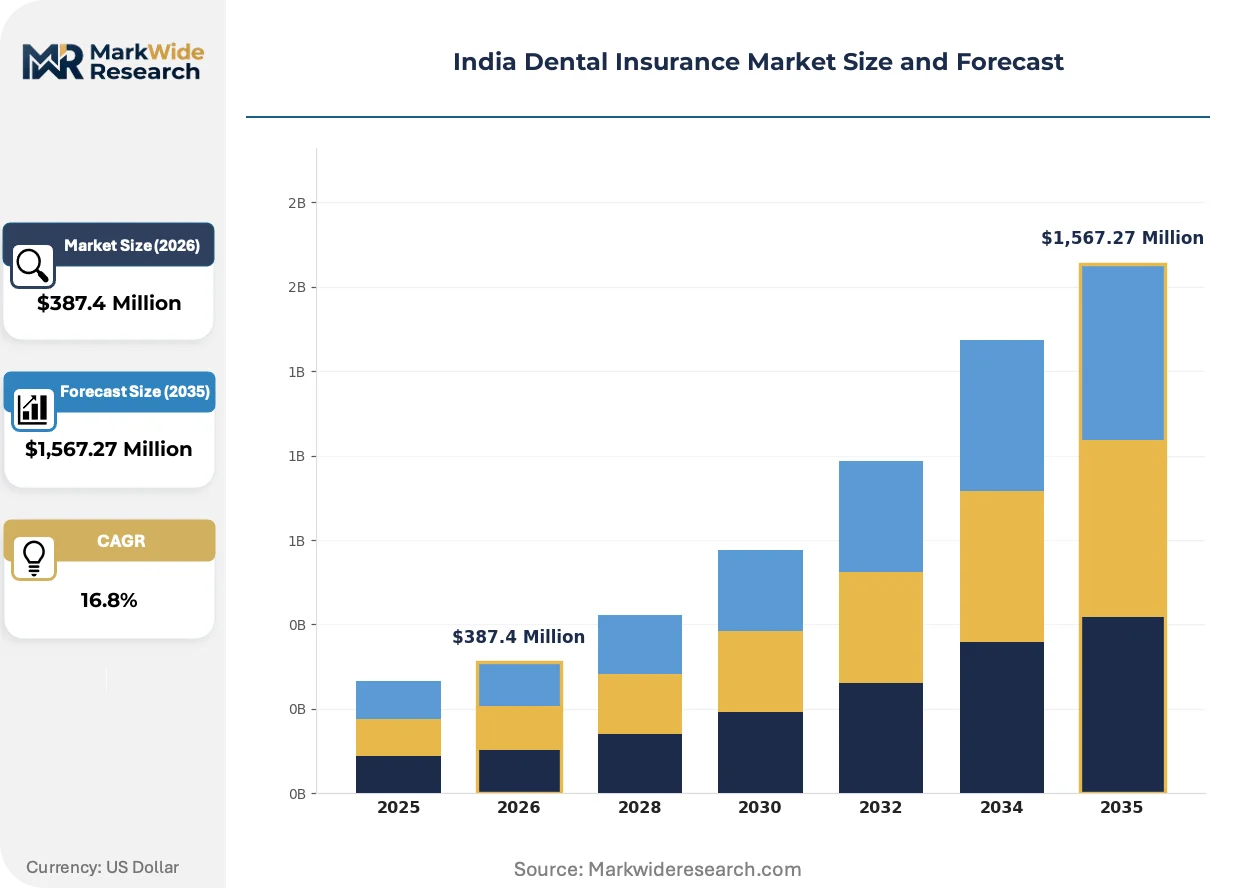
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $1,567.27 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Individual, Family, Group, Employer-Sponsored Coverage Level: Basic, Comprehensive, Major Services, Preventive Payment Mode: Monthly, Quarterly, Annual, One-Time Customer Segment: Adults, Seniors, Children, Corporate |
| Companies Covered | Future Generali India Insurance, Bajaj Allianz General Insurance, Aditya Birla Health Insurance, Tata AIG General Insurance, Star Health and Allied Insurance, Cholamandalam MS General Insurance, GoDigit Health Insurance, Niva Bupa Health Insurance, ICICI Lombard Health Insurance, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Dental Insurance Market Shifts & Advancements
Tele-dentistry platforms are collapsing the distance between diagnostic need and insurance authorization, restructuring how preventive care gets financed and delivered across India's metropolitan clusters.
AI-powered oral scanning applications are virtualizing the initial diagnostic layer, allowing policyholders to submit cavity and gum-condition assessments through smartphone cameras before clinic visits. Tier-1 corporate policyholders are piloting these tools to pre-authorize preventive claims. This compression of the diagnostic chain is virtualizing traditional fee-for-service reimbursement models into episode-based prepayment structures.
IRDAI's 2024 master circular on wellness-oriented policy design is mandating preventive-care coverage minimums for all new dental product filings. Insurers must now allocate specified portions of premium income toward annual checkup reimbursements. Standalone dental specialists are responding faster than general health insurers, redesigning actuarial models around utilization rather than catastrophe coverage.
Direct-to-consumer platforms are disintermediating agent networks for individual policy sales, with policyholders in Delhi and Mumbai completing full purchase journeys without human intermediaries. Aggregator websites now command significant share of new premium generation, forcing incumbents to rebuild commission structures around retention rather than acquisition. This channel migration is most pronounced among subscribers under 35 seeking family floater coverage.
India Dental Insurance Market Segmentation
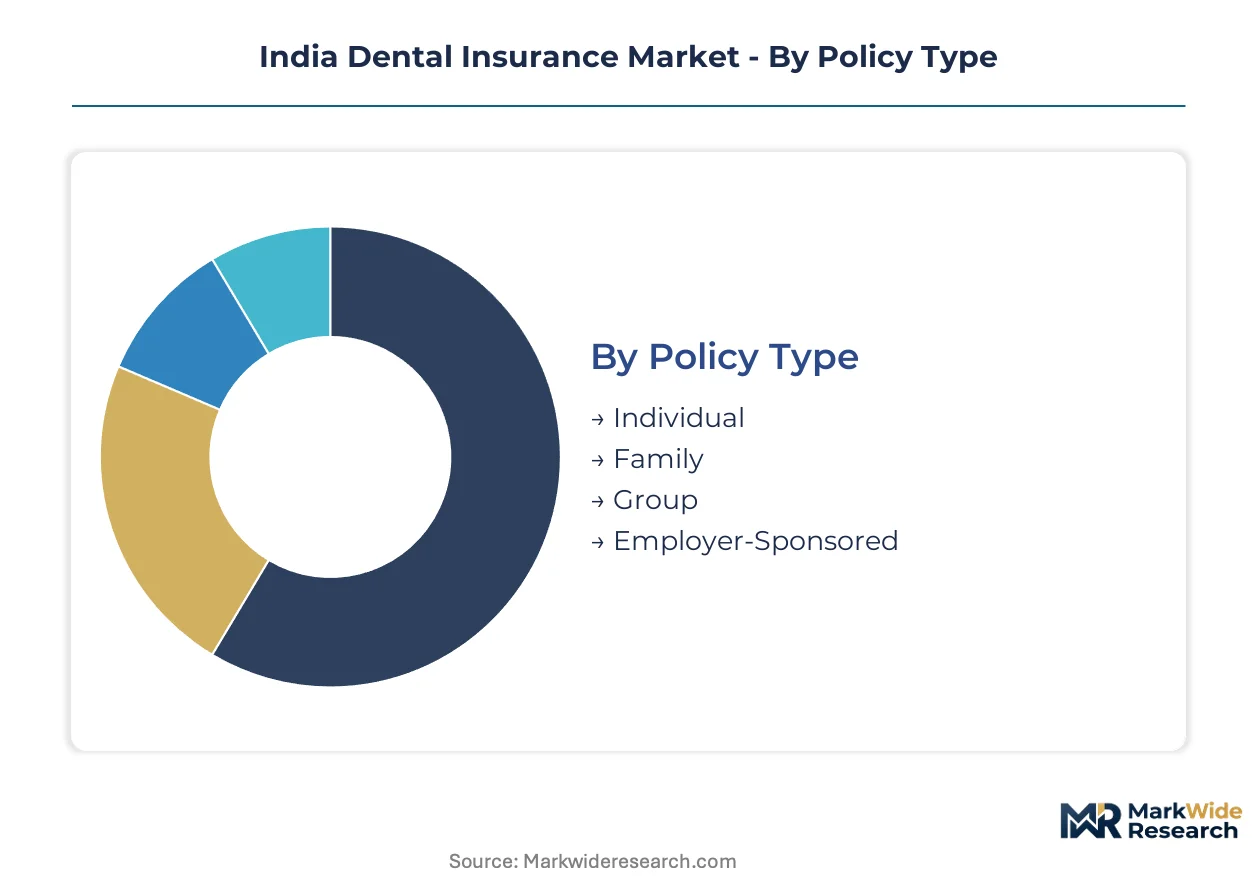
Dental insurance segmentation in India reflects divergent risk appetites and purchasing power across subscriber profiles. Policy type and coverage level configurations determine underwriting economics, while payment mode flexibility shapes retention rates in price-sensitive markets.
Policy Type:
Policy renewal cycles vary dramatically across subscriber acquisition channels, with direct-to-consumer individual plans exhibiting the shortest decision windows and employer-sponsored schemes locking in multi-year commitments.
- Individual:Single-subscriber policies carry the highest acquisition cost per premium rupee due to marketing spend and medical underwriting overhead. Demand concentrates among self-employed professionals in Mumbai and Delhi seeking tax-advantaged health coverage, though adverse selection from delayed dental treatment seekers elevates claims ratios.
- Family:Multi-member floater structures spread risk across age cohorts while reducing per-capita administrative burden. Maharashtra and Karnataka households drive uptake, motivated by pediatric orthodontic coverage needs and senior prosthodontic provisions under unified premiums.
- Group:Community-based enrollment through resident welfare associations and professional guilds achieves modest scale in tier-1 cities. These segments leverage collective bargaining for standardized coverage tiers.
- Employer-Sponsored:Corporate wellness mandates are expanding fastest among mid-sized enterprises in Bengaluru and Hyderabad, with HR departments bundling dental riders into group health master policies to reduce workforce absenteeism from untreated oral conditions.
Individual policies dominate installed base. Employer-Sponsored is where expansion concentrates.
Coverage Level:
Premium-to-claim ratios stratify sharply across benefit tiers, with preventive plans generating surplus margins that subsidize major services exposure.
- Basic:Limited benefit schedules covering extractions and emergency pain management attract price-sensitive subscribers in Gujarat and Rajasthan. These plans suffer elevated lapse rates when co-payment clauses trigger unexpected out-of-pocket expenses.
- Comprehensive:Full-spectrum coverage spanning diagnostic, restorative, and prosthodontic procedures commands the highest margins and lowest churn. Bengaluru and Hyderabad professionals favor this tier for family floater configurations.
- Major Services:Catastrophic-focused coverage for implants, crowns, and oral surgery addresses aging demographic needs. Demand clusters among seniors in Chennai and Kochi seeking protection against high-ticket procedures.
- Preventive:Checkup and cleaning reimbursement structures align with IRDAI wellness mandates, with younger demographics in Delhi and Mumbai responding to gamified premium discount incentives.
Comprehensive coverage commands premium positioning. Preventive plans are climbing the fastest as regulatory minimums reshape product filings.
Payment Mode:
Collection frequency directly determines insurer working capital efficiency and customer lifetime value calculations.
- Monthly:High-frequency micro-payments reduce subscriber entry barriers but inflate administrative overhead through repeated collection cycles. Digital wallet integration is penetrating among gig economy workers in tier-1 cities.
- Quarterly:Intermediate cadence balancing cash flow predictability with subscriber convenience. Limited uptake relative to monthly and annual alternatives.
- Annual:Single upfront payment locks in retention and eliminates recurring collection costs. Corporate policyholders and affluent individual subscribers in Mumbai and Delhi prefer this mode for tax planning alignment.
- One-Time:Single-procedure micro-policies enabled by IRDAI sandbox regulations target informal-sector workers lacking employer coverage, with mobile-first distribution collapsing issuance timelines.
Annual payment dominates corporate accounts. One-Time micro-policies are gaining share fastest through sandbox-enabled distribution.
Customer Segment:
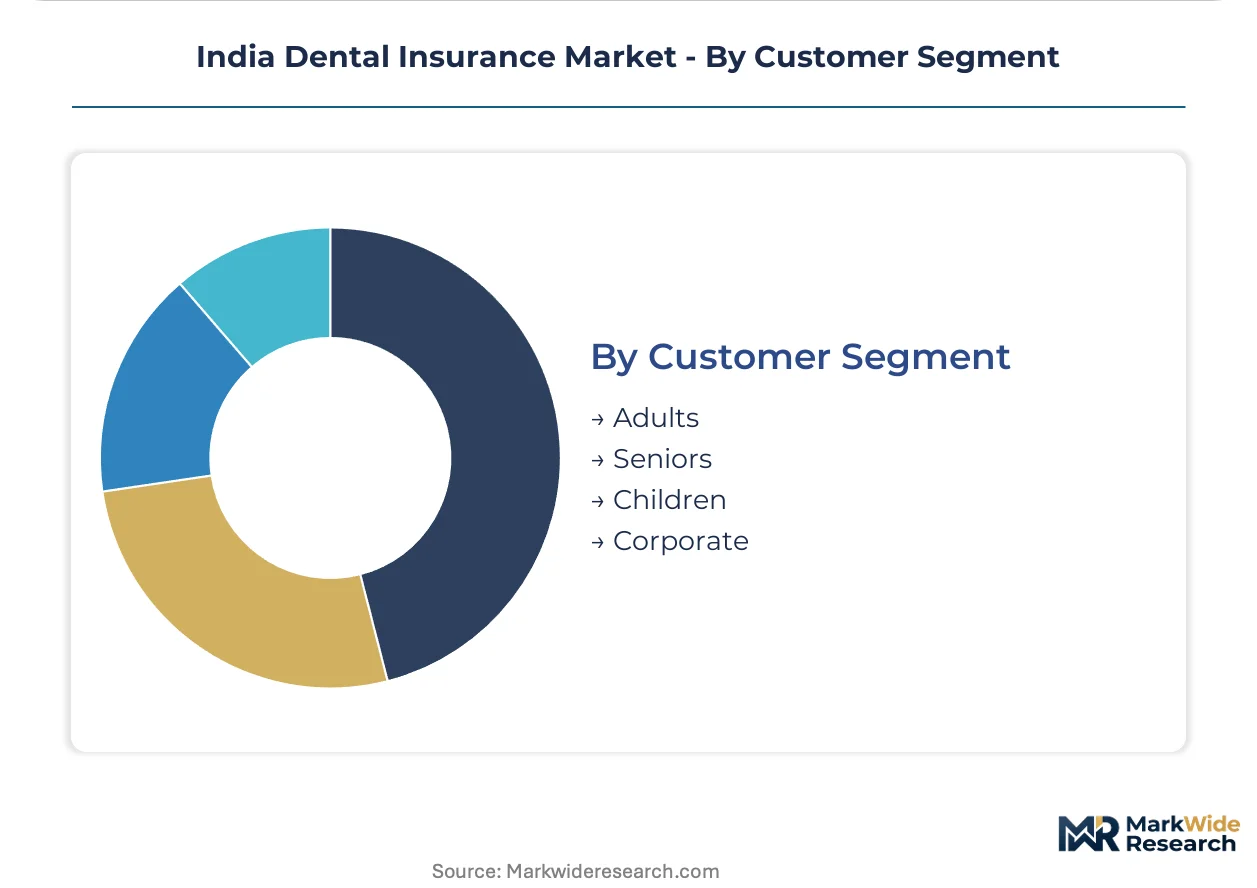
Age-correlated morbidity patterns and employment status fundamentally reshape product design and channel strategy.
- Adults:Working-age subscribers aged 25-55 constitute the core premium volume, with preventive-care utilization rates lowest in this cohort. Bengaluru IT professionals drive family floater adoption.
- Seniors:Post-retirement subscribers exhibit the highest per-capita claims intensity for prosthodontic and periodontal treatments. Chennai and Kochi concentrations reflect South India's aging demographic profile.
- Children:Pediatric orthodontic and preventive coverage anchors family policy purchases, with parents in Delhi and Mumbai prioritizing early intervention benefits.
- Corporate:Employer-sponsored wellness schemes are expanding most quickly among mid-sized enterprises in Maharashtra and Karnataka seeking to differentiate talent acquisition.
Adults constitute the largest addressable pool. Corporate segments are expanding most quickly as workforce wellness budgets mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra commands premium pricing power through Mumbai's corporate density, while Rajasthan's price-sensitive markets compress margins for basic preventive plans. This asymmetry shapes insurer channel strategies across state boundaries.
Maharashtra
Mumbai and Pune drive employer-sponsored adoption among financial services and IT enterprises seeking wellness differentiation. IRDAI's sandbox framework enables faster product approvals for bite-sized dental riders targeting gig workers in the Mumbai Metropolitan Region. The Mumbai-Pune corridor concentrates the highest density of empaneled network clinics.
Karnataka
Bengaluru's technology workforce fuels family floater demand for comprehensive coverage including pediatric orthodontics. State-level IT policy incentives indirectly expand corporate wellness budgets through employment cost deductions. Whitefield and Electronic City clusters anchor employer-sponsored penetration among mid-sized enterprises.
Gujarat
Ahmedabad and Surat dental clinics attract medical tourism flows for implant procedures, creating cross-border premium collection opportunities. BIS certification requirements for sterilization equipment delay network expansion in tier-2 cities. The Ahmedabad corridor specializes in high-value prosthodontic services for overseas patients.
Tamil Nadu
Chennai's aging demographic concentrates demand for major services coverage addressing periodontal and prosthodontic needs. State health mission programs for senior care indirectly elevate oral health awareness. The Chennai-Coimbatore axis hosts the highest per-capita claims intensity for catastrophic dental procedures.
Delhi-NCR
Direct-to-consumer digital channels achieve deepest penetration among under-35 subscribers seeking instant policy issuance. Aadhaar-linked KYC protocols collapse verification timelines for individual purchasers in Gurugram and Noida. The National Capital Region anchors online premium generation without agent intermediation.
India Dental Insurance Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in niche risk pools. The market structures around three player tiers: diversified general insurers with health divisions, standalone health specialists with dental focus, and digital-native entrants leveraging sandbox distribution. Consolidation pressure concentrates among mid-scale regional underwriters lacking corporate tie-up scale. Dominant competitive moves include corporate wellness mandate capture and mobile-first micro-policy deployment.
Among diversified general insurers, Bajaj Allianz General Insurance and Tata AIG General Insurance occupy positions reflecting extensive agent networks and corporate relationship depth. ICICI Lombard Health Insurance anchors the direct-to-consumer digital channel tier. Star Health and Allied Insurance exemplifies the standalone health specialist archetype with preventive-care bundling differentiation. These three represent distinct strategic postures without implying specific market share claims.
| Leading Market Players |
|---|
| Future Generali India Insurance |
| Bajaj Allianz General Insurance |
| Aditya Birla Health Insurance |
| Tata AIG General Insurance |
| Star Health and Allied Insurance |
| Cholamandalam MS General Insurance |
| GoDigit Health Insurance |
| Niva Bupa Health Insurance |
| ICICI Lombard Health Insurance |
| Others |
Supply & Pricing Matrix
The Mumbai-Pune freight corridor's logistics cost dynamics compress margin buffers for insurers serving tier-2 clinics while amplifying price differentiation between metropolitan empaneled networks and out-of-network reimbursement tiers. This spatial cost structure concentrates underwriting profitability along the western corridor while forcing rural distributors to absorb higher per-policy servicing expenses.
Pricing Analysis
Employer-sponsored buyers anchor subscription-tiered pricing structures across comprehensive, preventive, and major services levels. Premium differentiation hinges on IRDAI wellness-mandate compliance grades and network clinic density, with co-payment clauses intensifying cost compression in Gujarat and Rajasthan markets. Price sensitivity peaks among gig economy subscribers seeking sandbox-enabled micro-policies, while corporate wellness budgets exhibit lowest elasticity.
Supply Chain Analysis
Third-party administrators and dental clinic aggregators hold concentrated claim adjudication capacity across Maharashtra, Karnataka, and Delhi-NCR. Insurer operations draw from Aadhaar-linked KYC infrastructure, tele-dentistry diagnostic platforms, and BIS-certified sterilization equipment supply. Single-source vulnerability sits with centralized provider network management systems. Distribution runs through direct-to-consumer digital channels and corporate HR benefit portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India dental insurance is crossing a platform-economics inflection where interoperability between insurer core systems and clinic management software determines network expansion velocity. The IRDAI sandbox framework's API standardization mandates are accelerating this ecosystem convergence.
For Market Incumbents: Pre-empt digital-native entrants by captive integration of tele-dentistry diagnostic layers and AI-powered claims automation. Star Health and Allied Insurance's preventive-care bundling demonstrates how vertical control over wellness touchpoints defends against sandbox-enabled micro-policy disintermediation. Priority investment in BIS certification pre-qualification for tier-2 clinic networks blocks competitor empaneled expansion.
For New Entrants and Emerging Players: Tier-3 cities in Tamil Nadu and Kerala lacking empaneled network density represent the most penetrable entry point for mobile-first micro-policy distribution. Ahmedabad-Surat dental tourism corridors offer cross-border premium collection white space for insurers with international provider tie-ups. Go-to-market execution should anchor on WhatsApp-integrated policy issuance with Aadhaar-automated KYC.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors standalone health specialists with embedded dental focus over diversified general insurers lacking actuarial depth in oral health utilization patterns. Long-term viability rests on preventive-care gamification IP and provider network density in underpenetrated states. Monitor IRDAI sandbox product approval velocity as inflection signal for micro-policy market formation.
| Strategic Initiative | Industry Significance |
|---|---|
| Tele-Dentistry Platform Integration | Compresses diagnostic-to-authorization timelines for Star Health and Allied Insurance's corporate clients. |
| Sandbox Micro-Policy Launch | Unlocks gig economy penetration through ICICI Lombard Health Insurance's mobile-first distribution infrastructure. |
| Provider Network Expansion | Bajaj Allianz General Insurance extends rural reach via BIS-certified clinic credentialing in tier-2 Maharashtra markets. |
| Preventive-Care Gamification | Tata AIG General Insurance's corporate tie-ups leverage wellness app engagement to reduce claims intensity. |
| Cross-Border Premium Collection | Ahmedabad-Surat corridor enables international patient reimbursement through Niva Bupa Health Insurance's network agreements. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with dental clinic network managers, insurance product development executives, IRDAI regulatory affairs specialists, and corporate HR benefits administrators. Secondary validation drew from IRDAI product filing databases, BIS certification registries, hospital procurement records, and PLI scheme medical device manufacturing disclosures. Bottom-up premium volume estimates triangulated against top-down addressable population projections.
Calibration anchored on historical policy issuance trajectories across the analysis window, with segmentation modeling spanning policy type, coverage level, payment mode, and customer segment dimensions. CAGRs derived from procedure-cost inflation differentials, employer wellness budget expansion rates, and digital channel penetration curves. Tele-dentistry adoption velocity and sandbox product approval pipelines fed scenario-weighted projections.
Stress conditions across IRDAI regulatory stance shifts, implant cost compression rates, and tier-2 network clinic expansion speeds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on Aadhaar integration stability and corporate wellness mandate enforcement. Quarterly review of sandbox product approval volumes and tele-dentistry claim authorization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
United States Bancassurance Market
Insurance
Reinsurance Market
Insurance
Asia-Pacific Critical Illness Insurance Market
Insurance
Workers Compensation Insurance Market
Insurance
Fire Insurance Market
Insurance
Global Boats and Yacht Insurance Market
Insurance
Europe Bancassurance Market
Insurance
General Insurance Market
Insurance
Canada Home Insurance Market
Insurance
Canada House Insurance Market
Insurance
Compulsory Third Party (CTP) Insurance Market
Insurance
United Kingdom Car Insurance Market
Insurance
Europe Travel Insurance Market
Insurance
Bancassurance Market
Insurance
Austria Property and Casualty Insurance Market
Insurance
Germany Property and Casualty Insurance Market