
 General Insurance Market | 2026-2036
General Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
General Insurance Market Insights
Usage-based premium modules is decoupling coverage from annual contracts. Allianz leverages telematics data to price motor policies dynamically. Berkshire Hathaway sustains its dominance in commercial property through captive reinsurance structures. Progressive Corporation differentiates via algorithmic risk scoring that compresses quote-to-bind timelines.
General insurance encompasses non-life coverage contracts that indemnify policyholders against property damage, liability exposure, and financial loss through risk-pooled premium mechanisms governed by statutory solvency ratios and claims-reserve adequacy rules. Motor insurance commands the largest premium pool among product types, though liability coverage generates superior margins from complex commercial accounts. Online platforms represent the fastest-growing distribution channel as direct-to-consumer interfaces displace agent-mediated placement for standardized risks.
FDA oversight of clinical-trial liability shapes product development for life-science underwriters in the United States, while EIOPA's Solvency II framework governs capital adequacy across European carriers. The SEC's climate disclosure rules and the EU Green Deal's sustainability reporting standards are forcing insurers to embed transition-risk scenarios into underwriting models. Stakeholders must monitor how regulatory divergence between Washington and Brussels fragments policy wording and capital allocation.
Market Dynamics
Telematics-enabled usage-based pricing is fragmenting the traditional annual-contract model, forcing carriers to rebuild actuarial frameworks around real-time risk telemetry rather than historical loss ratios.
Growth Catalysts
- Cyber Mandates:The EU's Digital Operational Resilience Act compels financial institutions to carry operational risk coverage, creating mandatory demand pools for cyber liability products.
- Logistics Expansion:E-commerce fulfillment networks in Germany and the United States are scaling commercial property coverage to protect automated warehousing assets against business interruption.
- Telematics Integration:Connected vehicle data streams enable dynamic motor pricing that aligns premiums with actual driving behavior rather than demographic proxies.
Market Restraints
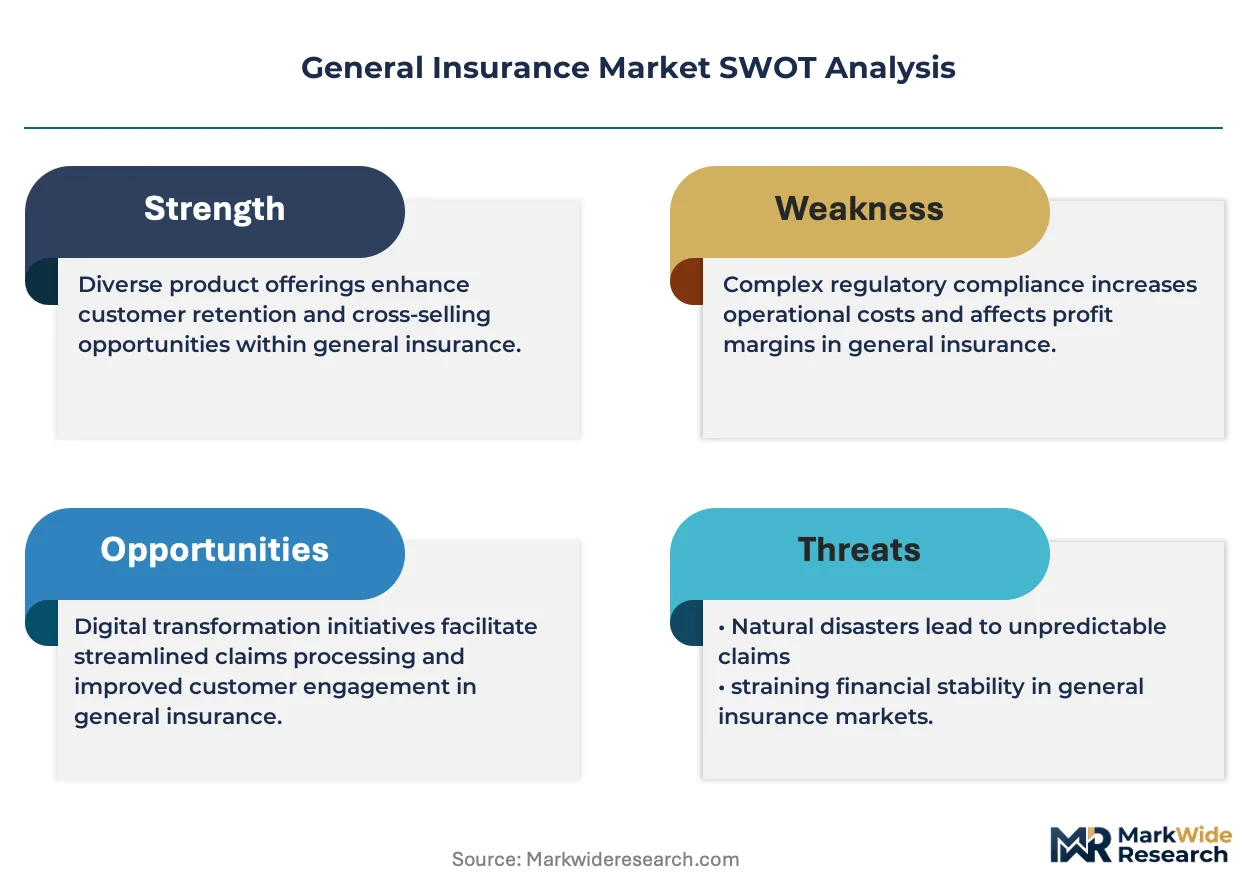
- Catastrophe Model Uncertainty:Climate volatility is eroding confidence in historical loss data, forcing carriers to hold elevated capital reserves against property portfolios.
- Reinsurance Capacity Concentration:Bermuda and London market capacity constraints are tightening retrocession layers, compressing primary carrier underwriting leverage.
- Legacy System Architecture:Policy administration platforms built on decades-old code bases impose integration friction with modern data ingestion pipelines.
Strategic Opportunities
- Parametric Products:Index-triggered coverage for agricultural and renewable energy assets bypasses traditional claims adjustment, accelerating payout velocity.
- Embedded Distribution:Point-of-sale insurance integration at automotive dealerships and real estate closings captures risks at origination moments.
- Climate Risk Analytics:Satellite imagery combined with geospatial modeling enables granular property underwriting in previously unmeasured coastal zones.
Industry Challenges
- Actuarial Talent Scarcity:Demand for data scientists with insurance domain expertise exceeds supply, inflating compensation costs for predictive modeling teams.
- Multi-Jurisdictional Compliance:Divergent state-level rate filing requirements in the United States fragment product standardization, elevating legal and operational overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | General Insurance Market |
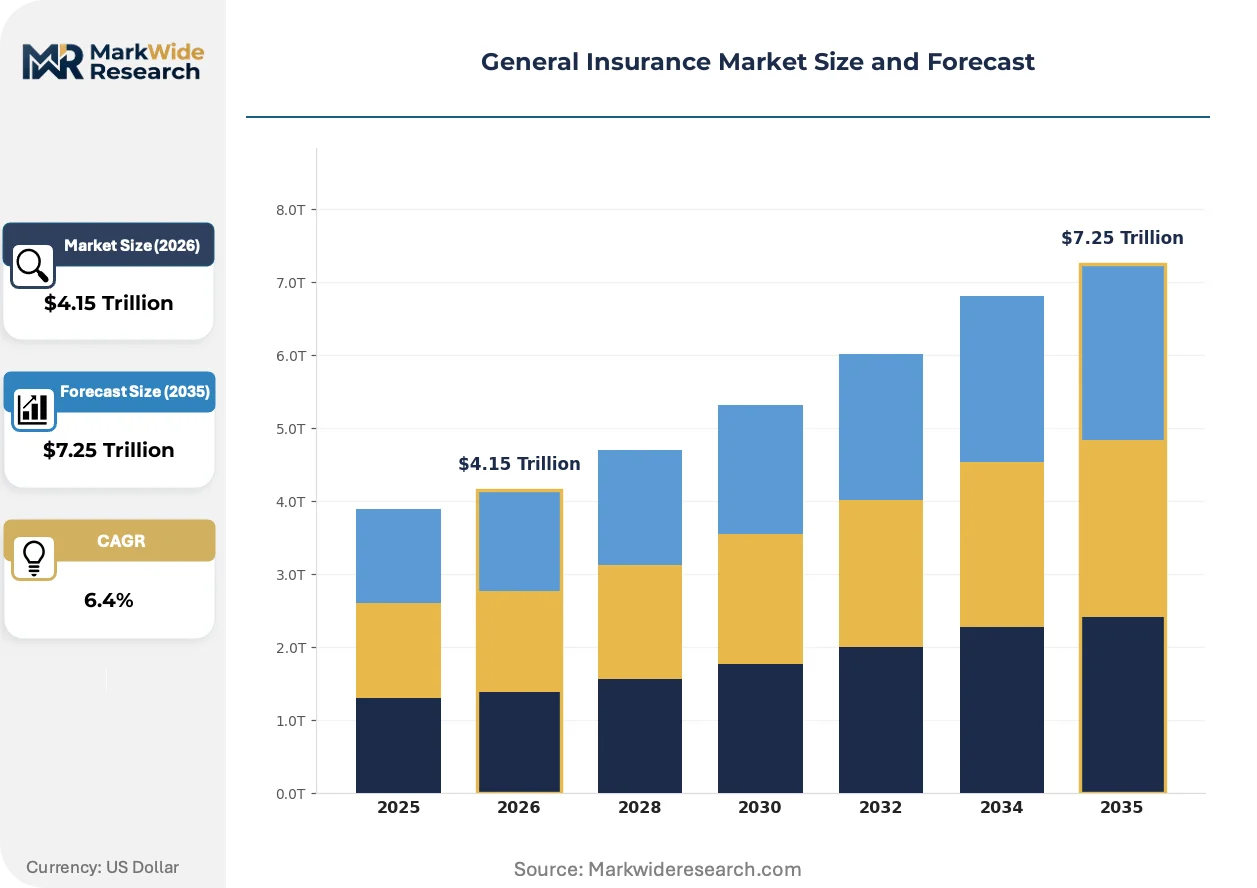
| Market Size in 2026 | $4.15 Trillion |
| Market Size in 2035 | $7.25 Trillion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Motor Insurance, Property Insurance, Travel Insurance, Liability Insurance, Marine Insurance, Credit Insurance Customer Category: Individual Policyholders, Small Businesses, Corporate Clients, Nonprofit Organizations, Freelancers Distribution Channel: Direct Sales, Bancassurance, Online Platforms, Insurance Brokers, Agents, Corporate Sales Risk Class: Low Risk, Medium Risk, High Risk, Emerging Risks, Catastrophic Risks |
| Companies Covered | Allianz, Berkshire Hathaway, State Farm, Progressive Corporation, Liberty Mutual, Allstate, Travelers, Chubb, Axa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
General Insurance Market Trends and Innovations
Distributed ledger infrastructure and algorithmic underwriting engines are compressing the value chain between risk identification and capital deployment. Three developments warrant particular attention.
Blockchain-based smart contracts are decentralizing claims settlement by executing payouts automatically when oracle-fed data confirms triggering events. Agricultural cooperatives in Australia and catastrophe bond sponsors in Bermuda have piloted parametric structures that bypass traditional loss adjustment. The technology is decentralizing trust mechanisms that previously required intermediary validation, shrinking administrative expense ratios.
The SEC's climate disclosure rules are mandating scenario analysis for insured portfolios with material transition risk exposure. Property-casualty carriers must now model stranded asset probabilities within commercial real estate and energy sector accounts. US-domiciled underwriters are restructuring coverage limits and pricing tiers to reflect regulatory capital charges on carbon-intensive holdings.
Direct-to-consumer platforms are displacing agent-mediated placement for standardized personal lines risks. Price-comparison engines and mobile-first quote interfaces capture motor and homeowners policyholders who previously relied on independent broker advice. This channel migration is most pronounced among digitally native demographic cohorts in metropolitan markets.
General Insurance Market Segmentation
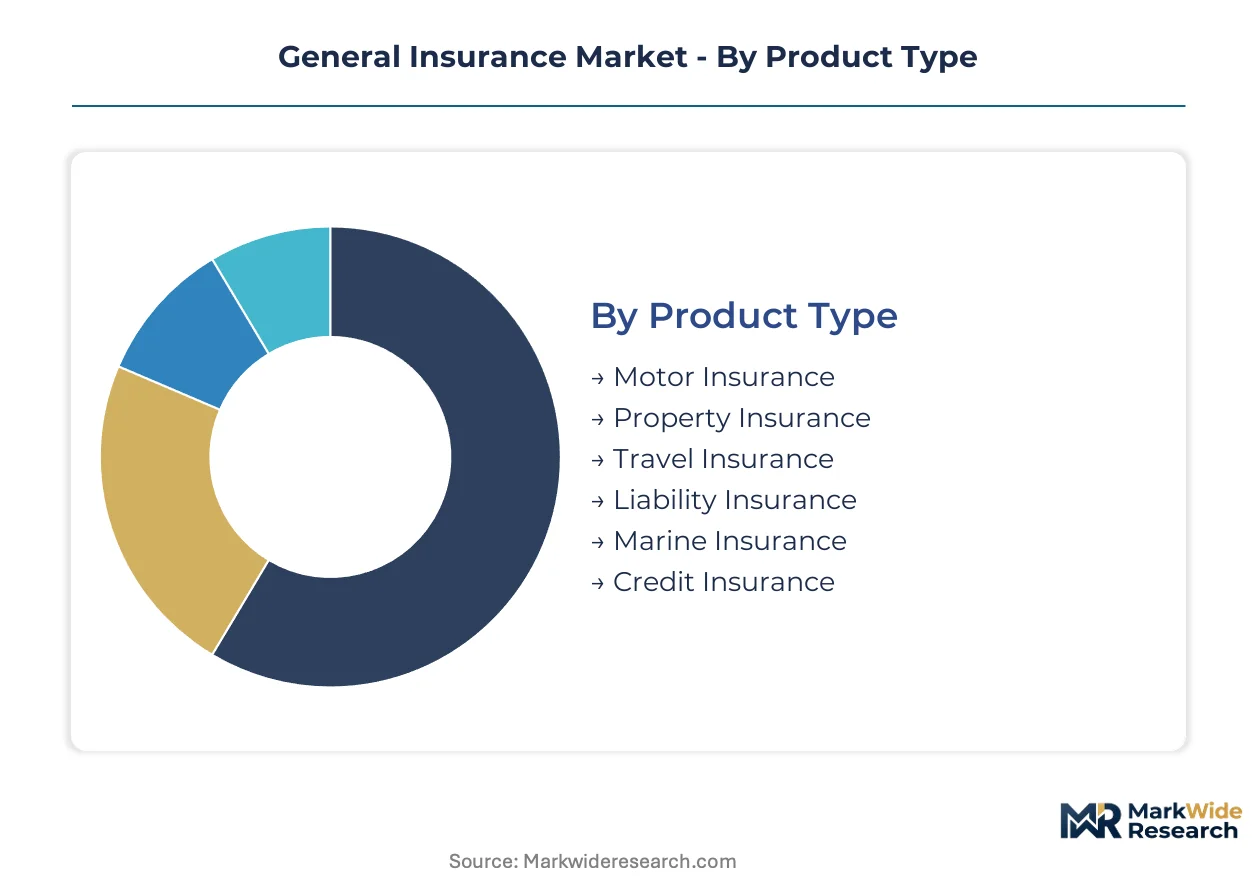
General insurance carriers segment risk pools to align capital reserves with loss volatility and match distribution economics to buyer sophistication. Product architecture, customer scale, channel efficiency, and risk classification collectively determine underwriting margins and solvency requirements across portfolio construction.
Product Type:
Technology integration varies sharply across coverage lines, with data-rich segments enabling dynamic pricing while traditional lines rely on static annual contracts.
- Motor Insurance:Telematics-enabled usage-based contracts now capture real-time driving behavior through onboard diagnostics and smartphone sensors. Fleet operators in Germany and ride-hailing platforms in India are accelerating adoption of pay-per-mile structures that displace demographic rating factors.
- Property Insurance:Commercial accounts dominate premium volume, with automated warehousing and renewable energy assets driving demand for business interruption riders. Climate volatility has forced carriers to rebuild catastrophe models around forward-looking scenario analysis rather than historical loss data.
- Travel Insurance:Embedded distribution at airline booking engines and online travel agencies captures impulse purchases through single-trip micro-policies.
- Liability Insurance:Professional and product liability lines serve law firms, medical practices, and manufacturers facing litigation exposure in the United States.
- Marine Insurance:Hull and cargo coverage protects container fleets and commodity traders against port congestion and geopolitical route disruption.
- Credit Insurance:Trade credit policies shield exporters against buyer default, with European export credit agencies providing sovereign backstops.
Mature deployment sits with Motor Insurance. Newer deployment is concentrated in Property Insurance as climate analytics reshape underwriting.
Customer Category:
Scale of exposure and procurement sophistication create distinct service models, from standardized self-service to captive risk management programs.
- Corporate Clients:Multinational enterprises negotiate master policies covering global property portfolios and directors' liability through dedicated risk managers. Captive insurance structures in Bermuda and Vermont allow large manufacturers to retain predictable risks while capping catastrophic exposure.
- Small Businesses:Commercial package policies bundle general liability, property, and business interruption into simplified offerings sold through agent networks and digital marketplaces. Restaurants, contractors, and professional services firms in the United States represent the core addressable base.
- Individual Policyholders:Personal auto and homeowners coverage dominates direct-to-consumer acquisition through price-comparison engines.
- Nonprofit Organizations:Specialized liability coverage addresses volunteer accidents and governance exposures unique to charitable operations.
- Freelancers:Gig economy platforms in the United Kingdom and Netherlands embed professional indemnity and equipment coverage into service fees.
Corporate Clients command the deepest actuarial engagement. Freelancers represent the fastest-growing customer acquisition target as platform employment expands.
Distribution Channel:
Channel economics reflect the trade-off between acquisition cost and advice intensity, with digital interfaces gaining share in standardized risks.
- Online Platforms:Direct-to-consumer quote engines and mobile apps compress quote-to-bind timelines to minutes for motor and homeowners policies. Price transparency engines in the United Kingdom and Germany have displaced substantial agent-mediated volume among digitally native demographics.
- Insurance Brokers:Independent intermediaries retain dominance in complex commercial placements requiring coverage design and claims advocacy. Marsh, Aon, and Willis Towers Watson structures serve Fortune 500 accounts with multinational exposure.
- Direct Sales:Captive agent forces and call centers serve affinity groups and legacy policyholder bases.
- Bancassurance:Retail banking networks distribute simple life and non-life products through branch staff in France and Italy.
- Agents:Independent producers maintain local relationships with small commercial accounts and high-net-worth personal lines.
- Corporate Sales:Dedicated teams negotiate multinational programs with risk managers and captive managers.
Broker networks retain the highest-margin commercial relationships. Online Platforms are climbing the fastest as mobile-first interfaces capture standardized personal lines.
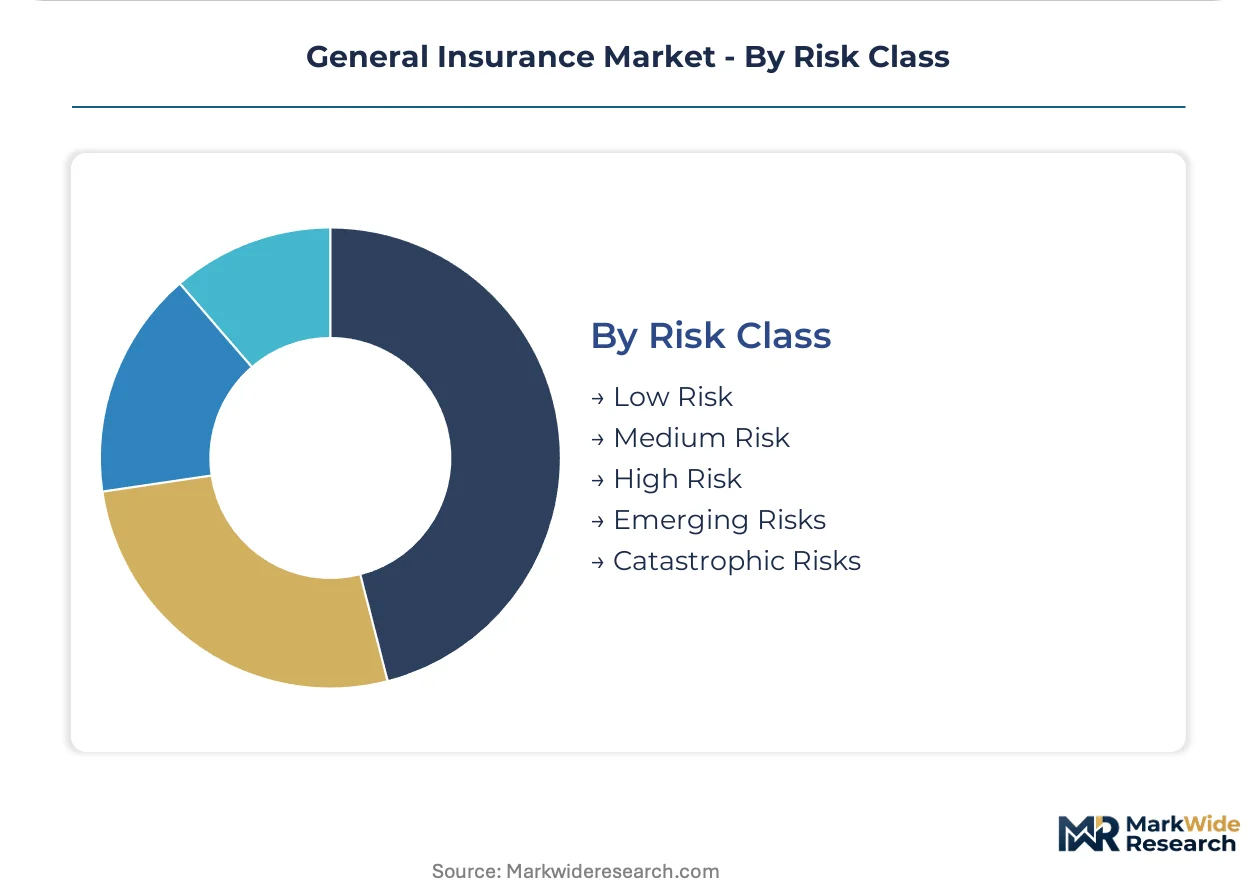
Risk Class:
Capital allocation and pricing precision depend on loss predictability, with emerging and catastrophic risks demanding alternative capital structures.
- Catastrophic Risks:Natural peril exposure in coastal zones and seismic corridors requires reinsurance treaties and catastrophe bond issuance to spread peak losses. Florida windstorm and California earthquake pools illustrate the concentration challenges facing primary carriers.
- Emerging Risks:Cyber liability, climate transition exposure, and pandemic business interruption lack historical loss data, forcing scenario-based pricing and limited coverage terms. The EU's Digital Operational Resilience Act is creating mandatory demand for operational risk coverage in financial services.
- High Risk:Hazardous manufacturing, aviation, and energy extraction command elevated premiums and stringent safety engineering requirements.
- Medium Risk:Standard commercial and personal lines with established actuarial foundations dominate premium volume.
- Low Risk:Mass-market personal lines with predictable frequency and severity profiles enable automated underwriting and minimal loss adjustment expense.
Medium Risk categories anchor current premium pools. Emerging Risks are expanding most quickly as regulatory mandates and technological disruption create new liability exposures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium generation concentrates in developed economies with mature regulatory frameworks, while emerging markets expand coverage penetration through digital distribution platforms.
United States
Commercial property and cyber liability lines drive premium expansion as Fortune 500 accounts restructure risk retention programs. The SEC's climate disclosure rules mandate scenario analysis for property-casualty portfolios with material transition exposure. New York and Chicago host the densest concentrations of captive insurance managers serving multinational manufacturing clients.
China
Motor insurance volume leads Asia-Pacific premium pools as vehicle ownership penetrates tier-two cities. SAMR's consumer protection directives reshape policy wording transparency for direct-to-consumer platforms. Shanghai and Beijing anchor the largest bancassurance distribution networks linking state banks with domestic carriers.
Germany
Industrial property and engineering coverage dominate commercial lines as manufacturing exporters manage supply chain interruption exposure. EIOPA's Solvency II framework governs capital adequacy and risk-based supervision across European-domiciled carriers. Munich and Frankfurt cluster the continent's largest reinsurance treaty negotiation centers.
United Kingdom
Lloyd's syndicates and London market brokers retain dominance in complex international risks including marine and aviation coverage. The FCA's consumer duty regulations tighten product governance standards for retail general insurance distribution. The City of London remains the primary hub for catastrophe bond issuance and alternative capital structuring.
India
Motor third-party liability and health rider attachments expand as regulatory minimum coverage thresholds rise for commercial vehicle operators. IRDAI's sandbox framework permits pilot deployments of telematics-enabled usage-based motor products. Mumbai and Bangalore concentrate insurtech development teams building mobile-first distribution interfaces for mass-market penetration.
General Insurance Market Competitive Landscape
Top-tier vendors anchor diversified multi-line portfolios, while regional specialists and digital-native entrants fragment sub-segment competition. Berkshire Hathaway and Allianz exemplify scale-driven archetypes with captive reinsurance capabilities and global commercial property dominance. Progressive Corporation represents algorithmic pricing leadership compressing quote-to-bind timelines. Competitive moves concentrate on embedded distribution partnerships and climate risk analytics acquisition.
Among European-headquartered conglomerates, Allianz and Axa occupy positions spanning life and non-life operations with emphasis on commercial property and liability lines. State Farm, Allstate, and Progressive Corporation exemplify distinct US market archetypes: the mutual structure, the agency-driven model, and the direct-to-consumer algorithmic platform respectively. Chubb and Travelers anchor the high-net-worth and specialty commercial segments through tailored coverage architectures. Liberty Mutual maintains multi-channel presence balancing independent agent networks with direct digital acquisition.
| Leading Market Players |
|---|
| Allianz |
| Berkshire Hathaway |
| State Farm |
| Progressive Corporation |
| Liberty Mutual |
| Allstate |
| Travelers |
| Chubb |
| Axa |
| Others |
Pricing and Supply Chain Analysis
Fortune 500 risk managers in the United States negotiate master policies through captive structures in Bermuda and Vermont, anchoring pricing power in long-term contractual frameworks rather than spot-market premiums. This buyer concentration forces primary carriers to absorb catastrophe model uncertainty into multi-year rate commitments while competing for treaty renewal cycles.
Pricing Analysis
Margin tightening in commercial property lines reflects elevated capital reserves against climate volatility and compressed retrocession capacity from Bermuda markets. Three-tier pricing structure across premium, standard, and economy levels segments corporate accounts by loss history and safety engineering investment, with price differentiation hinging on ISO 31000 risk management certification and captive participation depth. Cost-down pressure on personal motor lines accelerates because telematics-enabled usage-based products displace demographic rating factors. Small businesses exhibit highest price sensitivity through price-comparison engines, while multinational captives prioritize coverage breadth over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Bermuda and London market reinsurers who anchor capacity for peak catastrophe layers. Capital formation draws from the United States, Bermuda, and Switzerland as primary sources of alternative capital through catastrophe bond issuance and collateralized reinsurance structures. Raw material dependencies center on actuarial talent pools, satellite imagery data feeds, and regulatory compliance infrastructure. Tariff exposure on cross-border reinsurance treaties fragments policy wording between Washington and Brussels. Distribution runs through broker networks for complex commercial placements and direct-to-consumer platforms for standardized personal lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carriers are racing to integrate climate risk analytics and telematics data pipelines as vertical-integration levers that compress quote-to-bind timelines and reduce dependency on third-party modeling vendors.
For Market Incumbents: Deepen captive reinsurance capabilities in Bermuda and Vermont to retain predictable risks while capping peak exposures. Invest in proprietary satellite imagery partnerships to bypass third-party catastrophe model vendors. The SEC's climate disclosure rules threaten capital charges on carbon-intensive portfolios, making in-house transition-risk scenario analysis essential for pricing tier restructuring.
For New Entrants and Emerging Players: Insurtech platforms targeting gig economy freelancers in the United Kingdom and Netherlands represent the most penetrable white-space segment. Embedded distribution partnerships with automotive dealerships and real estate closings capture risks at origination moments with minimal customer acquisition cost. A mobile-first usage-based motor product piloted under India's IRDAI sandbox framework offers regulatory cover for algorithmic pricing experimentation.
For Investors and Strategic Acquirers: The window for entry favors climate risk analytics specialists with geospatial modeling capabilities and parametric product architectures. Long-term viability hinges on underwriting margin expansion through automated claims settlement rather than premium growth alone. Watch for inflection when EIOPA's Solvency II review embeds transition-risk capital charges, forcing distressed divestitures from carbon-heavy commercial property portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Product Development | Index-triggered agricultural coverage accelerates payout velocity through oracle-fed smart contracts. |
| Telematics Integration | Real-time driving data streams enable dynamic motor pricing that displaces demographic proxies. |
| Climate Risk Analytics Acquisition | Satellite imagery combined with geospatial modeling unlocks granular coastal zone underwriting. |
| Embedded Distribution Partnerships | Point-of-sale integration at automotive dealerships captures motor risks at origination moments. |
| Captive Reinsurance Structuring | Bermuda and Vermont domiciles allow manufacturers to retain predictable risks while capping catastrophic exposure. |
Research Methodology
Document review covered SEC climate disclosure filings, EIOPA Solvency II supervisory reports, and IRDAI sandbox framework documentation, complemented by interviews with chief underwriting officers, captive insurance managers, and insurtech platform engineers. Secondary validation drew from Lloyd's market data, catastrophe bond issuance databases, and trade credit agency filings. Bottom-up premium pool estimates triangulated against top-down regulatory capital adequacy benchmarks across the analysis window.
Segment-level projections across product type, customer category, distribution channel, and risk class dimensions fed into consolidated market sizing. CAGRs were derived from regression analysis of premium volume trends against regulatory mandate implementation timelines and telematics adoption curves. Forward-looking scenario weights incorporated EIOPA stress test parameters and SEC climate disclosure phase-in schedules without year-specific anchoring.
Caveats apply where Solvency II review outcomes or SEC climate rule litigation could materially shift capital charge assumptions and treaty pricing. Forecasts reflect documented regulatory trajectories and technology adoption patterns rather than macroeconomic cycle timing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Singapore Business Income Insurance Market
Insurance
Europe Electronic Gadgets Insurance Market
Insurance
Germany Travel Insurance Market
Insurance
Europe Bancassurance Market
Insurance
Germany Property and Casualty Insurance Market
Insurance
UK Commercial Insurance Market
Insurance
Insurance Aggregators Market
Insurance
B2B2C Insurance Market
Insurance
Logistics Insurance Market
Insurance
Aerospace Insurance Market
Insurance
Europe Liability Insurance Market
Insurance
Usage-Based Insurance for Automotive Market
Insurance
Auto Extended Warranty Market
Insurance
Cybersecurity Insurance Market
Insurance
Specialty Insurance Market
Insurance
Green Insurance Market