
 Bancassurance Market | 2026-2036
Bancassurance Market Size, Share, and Industry Trends Forecast 2026-2036
Bancassurance Market Intelligence
Bank distribution of insurance products is tilting toward digital-physical hybrid models as lenders seek non-interest revenue streams. Crédit Agricole SA leverages its cooperative banking network to sustain dominance in European life policy distribution through branch-based advisory. HSBC Holdings Plc anchors its bancassurance footprint across Asia-Pacific markets through exclusive partnerships with regional insurers. ING Groep NV differentiates via online platform integration, competing with traditional branch-heavy incumbents for younger customer segments.
Bancassurance denotes the distribution of insurance products through banking channels, where financial institutions act as intermediaries selling life, health, and general coverage to their existing depositor and borrower bases. The model relies on data-sharing protocols between bank core banking systems and insurer policy administration platforms, enabling risk-based product customization and embedded underwriting at point of sale. Life insurance commands the largest premium pool within product type segmentation, reflecting long-term savings substitution in markets with limited pension infrastructure. Branch network distribution retains structural importance in emerging economies where customer trust concentrates with physical banking presence, while online platforms capture accelerating share among digitally native retail segments in developed markets.
EIOPA guidelines across Europe mandate product governance and suitability assessments that reshape how banks structure insurance commissions and disclosure frameworks. India's RBI and IRDAI jointly regulate bancassurance tie-ups through caps on insurer partners per bank and strict fee transparency requirements that determine market access viability. Stakeholders must monitor evolving conduct standards and digital integration requirements as regulators intensify scrutiny over mis-selling risks and data interoperability between banking and insurance platforms.
Market Dynamics
Bank-insurer data interoperability mandates are forcing wholesale restructuring of legacy policy administration architectures, with EIOPA's product governance standards and India's IRDAI fee transparency rules driving compliance spend toward API-first infrastructure.
Growth Catalysts
- EIOPA Product Governance:Europe's conduct standards mandate suitability assessments that deepen advisory relationships and extend policy tenures through branch networks.
- Embedded Underwriting APIs:Real-time risk scoring at point-of-sale compresses issuance cycles and expands coverage penetration among mass-market depositors.
- India:RBI-IRDAI joint guidelines cap insurer partners per bank, concentrating distribution muscle behind scaled bancassurance tie-ups with PSU lenders.
Market Restraints
- Legacy Core Banking Integration:Decades-old policy administration platforms require multimillion-dollar middleware overhauls to achieve real-time data exchange with insurer systems.
- Commission Compression:EIOPA and national conduct authorities cap fee structures, squeezing non-interest revenue yields for distributing banks.
- Data Localization Mandates:India's RBI and comparable central banks in emerging markets impose server-residency requirements that fragment cloud architecture strategies.
Strategic Opportunities
- Microinsurance via Mobile Banking:Unbanked-to-banked transitions in sub-Saharan Africa and Southeast Asia create first-mover terrain for pay-as-you-go health and crop coverage.
- AI-Driven Personalization:Transaction-pattern analysis enables dynamic premium adjustments and cross-sell targeting at underwriting stage.
- EU Green Taxonomy Alignment:EIOPA guidelines on sustainable product disclosure create premium positioning for climate-linked savings-linked policies.
Industry Challenges
- API Standardization Fragmentation:Absence of unified data-exchange protocols between bank core systems and insurer platforms forces bilateral integration projects.
- Mis-Selling Surveillance:Conduct authorities in Europe and India deploy mystery-shopping and complaint-pattern analytics that elevate compliance staffing requirements.
- Actuarial-Data Science Talent Gap:Hybrid skill sets combining traditional risk modeling with machine-learning deployment remain scarce across both banking and insurance operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bancassurance Market |
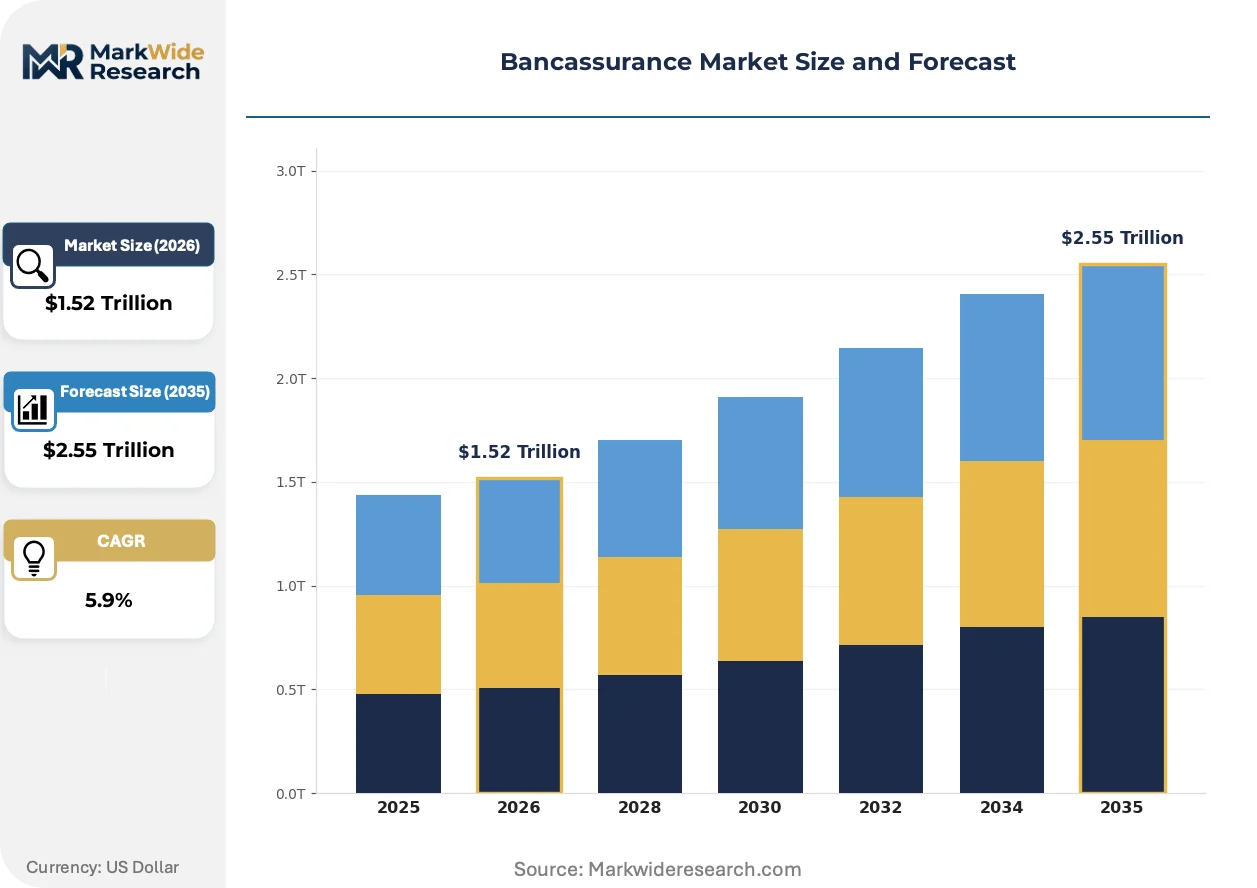
| Market Size in 2026 | $1.52 Trillion |
| Market Size in 2035 | $2.55 Trillion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Channel Type: Direct Sales, Online Platforms, Branch Network, Partnerships Product Type: Life Insurance, Health Insurance, General Insurance, Investment Plans Customer Type: Retail Customers, High-Net-Worth Individuals, SMEs, Corporates Distribution Model: Exclusive Agency, Independent Agency, Broker, Online Broker |
| Companies Covered | Crédit Agricole SA, ABN AMRO Group NV, Citigroup Inc., Wells Fargo and Co., Barclays Bank Plc, HSBC Holdings Plc, ING Groep NV, American Express Co., Banco Santander SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bancassurance Market Strategic Shifts & Innovations
Digital-physical hybrid distribution architectures are displacing pure branch or pure online models, with API ecosystems and regulatory sandbox frameworks enabling real-time product customization at the point of banking interaction.
Embedded insurance APIs are collapsing the traditional separation between account origination and policy issuance. These interfaces pull transaction history and credit bureau data to generate instant risk quotes during loan or deposit onboarding. European cooperative banks and Indian PSU lenders are deploying these stacks fastest, compressing the end-to-end sales cycle from days to minutes and eliminating paper-based proposal forms.
EIOPA's 2023 product governance guidelines mandate suitability assessments and commission transparency disclosures that reshape how banks structure insurance remuneration. The rules force separation of advisory and execution functions in branch settings, elevating training costs but reducing conduct-fine exposure. Life and long-term savings products face the steepest compliance burden, with distributors in Germany, France, and Italy reconfiguring incentive schemes to meet the new standards.
Younger retail segments are bypassing branch-based advisory entirely, purchasing term life and health riders through mobile banking apps with minimal human interaction. This channel shift concentrates among urban, digitally native depositors in developed markets, while rural and older demographics retain physical advisory preferences. Banks are responding with tiered service models: self-serve digital for simple products, scheduled video consultations for complex coverage, preserving branch capacity for relationship-heavy segments.
Bancassurance Market Segmentation
Bancassurance segmentation reveals how distribution infrastructure and customer sophistication determine revenue capture. Channel type and product mix dictate integration complexity with banking core systems, while customer tier shapes advisory intensity and commission structures.
Channel Type:
Mature markets favor digital-physical hybrids, while emerging economies retain branch dominance due to trust concentration with physical banking presence.
- Direct Sales:Bank-employed advisors execute face-to-face policy origination within branch premises, leveraging depositor trust relationships built through lending and deposit activity. Indian PSU banks deploy this model most intensively under RBI-IRDAI guidelines that cap insurer partnerships per lender.
- Online Platforms:Self-serve interfaces embedded within mobile banking apps enable instant quote generation and paperless policy issuance for digitally native retail segments. HSBC Holdings Plc anchors its Asia-Pacific footprint through platform integration with regional insurer APIs.
- Branch Network:Physical advisory remains structurally important in markets with limited digital penetration, particularly for complex life and investment-linked products requiring suitability assessments.
- Partnerships:Strategic alliances between banks and insurers create exclusive distribution arrangements that concentrate premium flow through defined territorial or product scopes.
Branch Network handles the majority of throughput; Online Platforms is the fastest mover on share.
Product Type:
Cost tier stratification separates premium advisory products from self-serve commodity coverage.
- Life Insurance:Long-term savings and protection policies dominate premium pools, substituting for pension infrastructure in markets with limited social security frameworks. EIOPA product governance mandates reshape commission disclosure and suitability frameworks across European cooperative banking networks.
- Health Insurance:Riders attached to retail loan products and standalone medical coverage expand penetration among mass-market depositors seeking catastrophic protection. Embedded underwriting APIs compress issuance cycles from days to minutes at point-of-sale.
- General Insurance:Property, motor, and liability coverage distributed through banking channels leverages transaction data for risk scoring and premium personalization.
- Investment Plans:Unit-linked and savings-linked policies face steepest compliance burden under conduct authority rules separating advisory from execution functions.
Life Insurance commands the deepest revenue pool; Health Insurance is expanding most quickly via embedded distribution.
Customer Type:
Application complexity scales with relationship depth and asset sophistication.
- Retail Customers:Mass-market depositors access standardized term life and health riders through digital channels with minimal advisory intervention. Younger urban segments in developed markets bypass branch consultation entirely.
- High-Net-Worth Individuals:Complex estate planning and wealth preservation structures demand scheduled video consultations or dedicated private banking advisory preserving human relationship capacity.
- SMEs:Business protection and key-person coverage distributed through commercial banking relationships leverages credit bureau data and transaction patterns for risk assessment.
- Corporates:Group life and health arrangements negotiated at enterprise level require bespoke policy administration integration with payroll and benefits platforms.
Retail Customers generate the highest policy volume; High-Net-Worth Individuals yield the steepest margin per contract.
Distribution Model:
Volume concentration favors exclusive arrangements, while margin accrues to independent intermediaries with multi-insurer access.
- Exclusive Agency:Single-insurer representation through bank channels concentrates distribution muscle behind scaled bancassurance tie-ups, particularly in India where RBI-IRDAI guidelines limit partner counts per lender.
- Independent Agency:Multi-insurer access enables product comparison and competitive quoting, though commission transparency rules under EIOPA and national conduct authorities compress fee yields.
- Broker:Intermediary-led placement of complex commercial coverage operates at arm's length from core banking relationships, serving corporate and HNW segments.
- Online Broker:Digital aggregation platforms compare insurer quotes within banking app ecosystems, capturing digitally native segments with minimal human touch.
Exclusive Agency dominates premium throughput; Online Broker is gaining share fastest among younger customer cohorts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's RBI-IRDAI joint guidelines on insurer partner caps per bank are concentrating distribution muscle behind scaled bancassurance tie-ups with PSU lenders. EU conduct standards under EIOPA mandate product governance and suitability assessments that reshape commission disclosure frameworks. These regulatory architectures determine market access viability and compliance spend trajectories across key jurisdictions.
India
PSU banks and private insurers are deepening distribution tie-ups under RBI and IRDAI guidelines that cap insurer partners per lender at three. Mumbai and Delhi-NCR house the densest concentrations of bank headquarters and insurer regional offices negotiating exclusive arrangements. Branch network penetration in rural Maharashtra and Gujarat accelerates policy uptake among unbanked-to-banked transitions.
France
Crédit Agricole SA leverages its cooperative banking network to sustain dominance in European life policy distribution through branch-based advisory. EIOPA product governance standards mandate suitability assessments that elevate training costs but reduce conduct-fine exposure. Paris and Lyon cluster the headquarters of major banking-insurer partnerships reconfiguring incentive schemes under new transparency rules.
United Kingdom
HSBC Holdings Plc anchors its bancassurance footprint across Asia-Pacific markets through exclusive partnerships with regional insurers, with London serving as coordination hub. The Financial Conduct Authority's conduct standards parallel EIOPA disclosure requirements on commission transparency. The City of London and Edinburgh concentrate insurance-linked banking operations targeting HNW advisory segments.
Netherlands
ING Groep NV differentiates via online platform integration, competing with traditional branch-heavy incumbents for younger customer segments seeking self-serve policy origination. Dutch regulators enforce EU product governance standards with additional national suitability requirements. Amsterdam houses the digital infrastructure teams developing API-first underwriting stacks for real-time risk scoring.
United States
Wells Fargo and Citigroup distribute insurance products through retail banking networks, with the OCC and state insurance commissioners governing bank-insurer data-sharing protocols. Embedded underwriting APIs compress issuance cycles for term life and health riders at point-of-sale. New York and Charlotte cluster the technology centers integrating insurer policy administration platforms with core banking systems.
Bancassurance Market Key Industry Players
On the supply side, the industry is tiered between cooperative banking networks with captive insurance distribution, global universal banks with multi-market exclusive partnerships, and digital-first challengers integrating API-first underwriting stacks. Three strategic archetypes dominate: branch-heavy incumbents leveraging depositor trust relationships, platform-integrated specialists capturing digitally native segments, and cooperative structures sustaining mutual ownership models. Competitive moves concentrate on API infrastructure investment and exclusive partnership consolidation under regulatory caps on insurer partners per bank.
Within the cooperative banking tier, Crédit Agricole SA exemplifies branch-network dominance through its French agricultural banking federation structure. Among global universal banks, HSBC Holdings Plc and ING Groep NV occupy contrasting positions—HSBC anchoring multi-market exclusive arrangements across Asia-Pacific, ING pursuing digital platform differentiation against traditional advisory models. These three entities represent the structural spectrum from physical advisory dependence to self-serve API integration.
| Leading Market Players |
|---|
| Crédit Agricole SA |
| ABN AMRO Group NV |
| Citigroup Inc. |
| Wells Fargo and Co. |
| Barclays Bank Plc |
| HSBC Holdings Plc |
| ING Groep NV |
| American Express Co. |
| Banco Santander SA |
| Others |
Cost & Logistics Intelligence
Overcapacity in European policy administration infrastructure is compressing vendor margins and forcing banks toward API-first procurement models that prioritize interoperability spend over traditional licensing fees.
Pricing Analysis
Volume-discount tiering structures dominate bancassurance technology procurement, with premium-mid-economy pricing differentiation separating full-stack advisory platforms from self-serve digital modules. Price differentiation hinges on EIOPA compliance certification levels and embedded underwriting sophistication, with banks in France and Germany paying premiums for suitability-assessment automation. Cost compression in standard-tier middleware is intensifying because Indian PSU lenders are consolidating vendor relationships under RBI-IRDAI partner caps. Retail banking segments exhibit highest price sensitivity, while private banking units prioritize relationship-management features over per-seat costs.
Supply Chain Analysis
Export-control regimes limiting cross-border data flows are fragmenting cloud architecture strategies and forcing regional data-center buildouts. Technology sourcing concentrates in India, Ireland, and Singapore, where vendor ecosystems cluster around banking software development. Raw material dependencies span core banking licenses, policy administration platforms, and real-time risk-scoring engines. Single-source vulnerability runs through legacy mainframe-dependent insurers whose modernization timelines lag regulatory mandates. Distribution runs through bilateral API integration projects rather than standardized middleware marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bancassurance functions as a service-attach opportunity where recurring commission streams and policy administration fees expand faster than one-time technology licensing revenue.
For Market Incumbents: Insulate core deposit relationships from fintech disintermediation by deepening exclusive insurer partnerships within regulatory caps. Prioritize backward integration into proprietary underwriting APIs to reduce third-party platform dependency. EIOPA conduct-fine exposure and commission transparency rules threaten non-interest revenue yields without advisory-function separation investments. For New Entrants and Emerging Players: Sub-Saharan African mobile banking penetration offers first-mover terrain for pay-as-you-go microinsurance distribution. Target rural Indian markets where PSU branch networks remain the sole financial access point. Pursue white-label API partnerships with regional banks lacking in-house digital infrastructure capabilities. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cooperative banking networks with captive insurance distribution and multi-decade depositor relationships. Long-term viability favors scaled bancassurance tie-ups with regulatory-protected partner exclusivity. Monitor IRDAI and EIOPA enforcement patterns as inflection indicators for compliance-spend acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Infrastructure Migration | Real-time data exchange with insurer platforms collapses policy issuance cycles from days to minutes. |
| Exclusive Partnership Consolidation | RBI-IRDAI caps on insurer partners per bank concentrate premium flow behind scaled tie-ups. |
| EIOPA Compliance Automation | Suitability-assessment algorithms reduce conduct-fine exposure across European cooperative networks. |
| Mobile Microinsurance Launch | Pay-as-you-go health and crop coverage captures unbanked-to-banked transitions in emerging markets. |
| AI-Driven Personalization Investment | Transaction-pattern analysis enables dynamic premium adjustments at point-of-sale underwriting. |
Research Approach
A spread of perspectives from bank distribution heads, insurer partnership directors, regulatory compliance officers, and core banking technology vendors converged on the working assumptions shaping this analysis. Primary fieldwork drew from structured interviews with bancassurance executives at European cooperative networks and Indian PSU lenders, validated against secondary sources including EIOPA guideline documents, RBI-IRDAI circulars, and insurer annual partnership disclosures. Bottom-up policy volume estimates triangulated against top-down premium pool assessments across channel and product segmentations.
Demand-supply-balance framing anchored the forecast architecture across the analysis window, modeling channel type, product mix, customer tier, and distribution model as core segmentation dimensions. CAGRs derived from trajectory convergence between historical premium growth patterns and regulatory-mandated technology investment cycles. Forecast inputs incorporated API penetration rates and branch-network density metrics as industry-specific demand drivers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by digital-first challengers with embedded finance capabilities would shift outcomes. Material shifts in EIOPA enforcement intensity or RBI-IRDAI partner-cap adjustments would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Global AI in Auto-Insurance Market
Insurance
Djibouti Insurance Market
Insurance
Umbrella Insurance Market
Insurance
Cyber Liability Insurance Market
Insurance
Agriculture Insurance Market
Insurance
Directors and Officers (Dando) Insurance Market
Insurance
India Health Insurance Market
Insurance
China Property and Casualty Insurance Market
Insurance
Jewelry Insurance Market
Insurance
Green Insurance Market
Insurance
India Life and Non-Life Insurance Market
Insurance
Self Funded Insurance Market
Insurance
North America Liability Insurance Market
Insurance
Telecommunication Insurance Market
Insurance
Trade Credit Insurance Market
Insurance
Global Healthcare Claims Management Market