
 Germany Property and Casualty Insurance Market | 2026-2036
Germany Property and Casualty Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Property and Casualty Insurance Market Foresight
Insurance broker networks are rewriting distribution economics in Germany's property and casualty sector. Allianz SE leverages its captive agent infrastructure to sustain pricing power in motor and homeowners lines. HUK-Coburg Versicherungsgruppe anchors mass-market penetration through direct-to-consumer operations. Munich Re competes at the reinsurance layer, extending risk capacity to primary carriers across German commercial portfolios.
Germany property and casualty insurance encompasses risk transfer contracts covering asset damage, third-party liability, and business interruption losses, underwritten with technical reserves calculated via actuarial mortality tables and catastrophe modeling. These instruments indemnify policyholders against fortuitous losses while stabilizing corporate balance sheets. Personal lines motor insurance dominates premium volume but faces margin compression from claims inflation, whereas commercial property and specialty insurance capture widening rate adequacy. Liability insurance grows fastest among freelancers and small businesses exposed to professional indemnity risks.
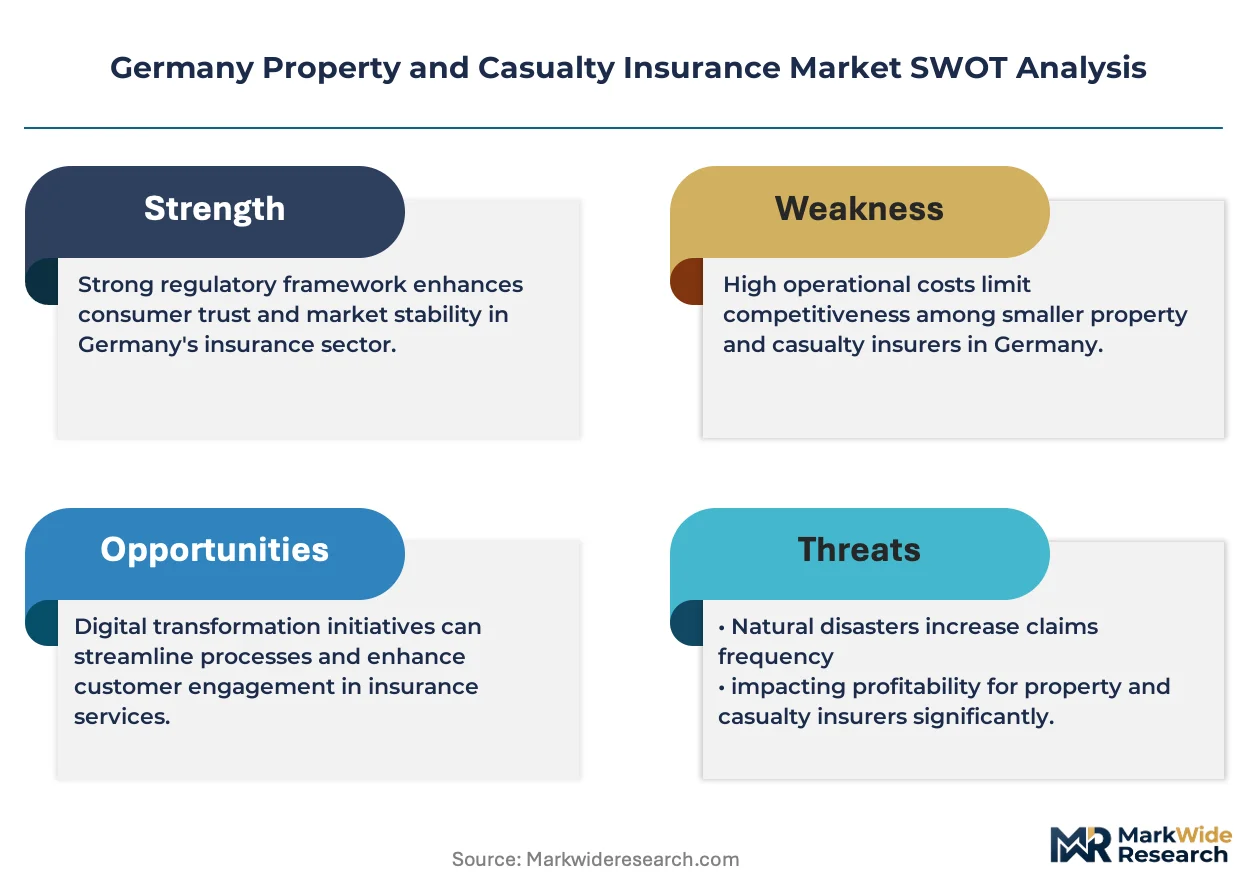
BaFin enforces Solvency II capital requirements while the German Insurance Supervision Act shapes product filing and consumer disclosure standards. These frameworks elevate compliance costs but also screen out undercapitalized entrants, concentrating market access among established carriers. Climate risk disclosure mandates from the EU Green Deal are forcing portfolio repricing in catastrophe-exposed lines. Stakeholders must monitor whether regulatory tightening in nat-cat reserves triggers selective withdrawal from high-risk regions or accelerates alternative capital inflows.
Market Dynamics
BaFin's Solvency II implementation is forcing German carriers to restructure capital reserves while climate disclosure mandates from the EU Green Deal accelerate portfolio repricing in catastrophe-exposed lines.
Growth Catalysts
- Logistics infrastructure expansion:German freight operators are scaling commercial property coverage for automated warehouses and cold-chain facilities along the Rhine-Alpine corridor.
- EU Green Deal nat-cat mandates:Climate risk disclosure requirements are expanding demand for parametric flood and storm policies among industrial policyholders in North Rhine-Westphalia.
- Telematics penetration:Usage-based motor insurance is capturing younger risk pools through smartphone-integrated driving behavior scoring.
Market Restraints
- Reinsurance cost volatility:Global retrocession capacity tightening is elevating cession costs for German primary carriers writing commercial property treaties.
- Interest rate compression:Persistently low yields on government bonds are constraining investment income that historically subsidized technical margins.
- Legacy IT architecture:Core policy administration systems at established Versicherungsvereine require multimillion-euro modernization to support real-time data integration.
Strategic Opportunities
- Cyber liability white space:Mid-sized Mittelstand manufacturers remain underinsured against ransomware and business interruption, creating room for standalone cyber policies.
- Embedded distribution partnerships:Automotive OEMs and real estate platforms are integrating motor and homeowners coverage at point of sale.
- ESG-linked captive structures:Large German industrials are establishing in-house insurers to directly manage climate transition risks and carbon credit verification.
Industry Challenges
- Actuarial talent scarcity:German universities produce insufficient graduates with catastrophe modeling and climate risk analytics expertise to meet carrier demand.
- Interoperability friction:Blockchain-based smart contract pilots face integration barriers with BaFin-mandated legacy reporting formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Property and Casualty Insurance Market |
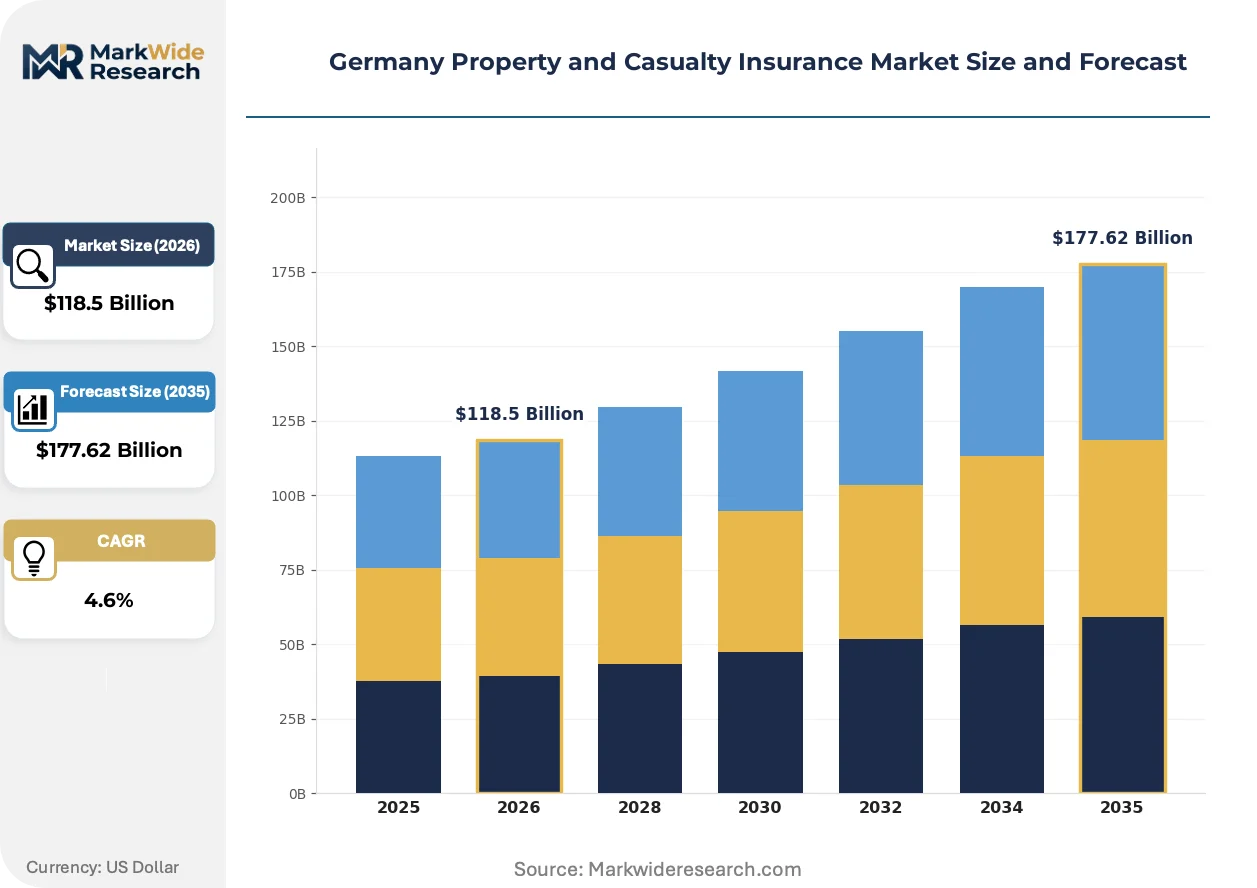
| Market Size in 2026 | $118.5 Billion |
| Market Size in 2035 | $177.62 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Motor Insurance, Homeowners Insurance, Liability Insurance, Commercial Property, Workers Compensation, Travel Insurance Distribution Channel: Direct Sales, Insurance Brokers, Bancassurance, Online Platforms, Agent Networks, Telemarketing Customer Type: Individual Policyholders, Small Businesses, Corporations, Public Sector Entities, Nonprofit Organizations, Freelancers Underwriting Segment: Personal Lines, Commercial Lines, Specialty Insurance, Reinsurance, Agricultural Coverage, Marine Insurance |
| Companies Covered | AXA Konzern AG, R+V Versicherung AG, Allianz SE, Zurich Insurance, HUK-Coburg Versicherungsgruppe, Munich Re, Generali Deutschland, Hannover Re, Talanx Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Property and Casualty Insurance Market Shifts & Advancements
Digital underwriting infrastructure and climate risk quantification are compressing traditional pricing cycles while redrawing competitive boundaries between direct writers and broker-mediated channels.
Artificial intelligence-driven claims triage is collapsing loss adjustment expense ratios for German motor and property carriers. Mid-sized regional insurers in Bavaria and Baden-Württemberg are deploying computer vision for automated damage assessment. This compression is enabling price competition that erodes traditional agent commission structures.
The EU Green Deal's climate risk disclosure framework is mandating scenario analysis for insurance balance sheets. German carriers must now stress-test nat-cat reserves against 1.5-degree warming pathways. Commercial property underwriters are responding by withdrawing capacity from flood-exposed Rhine Valley municipalities.
Corporate risk managers are consolidating vendor relationships and demanding integrated property-cyber-business interruption programs. Manufacturing buyers in automotive and chemicals verticals are replacing fragmented single-line placements with multi-peril master policies. This concentration is most visible among DAX-listed industrials headquartered in Frankfurt and Munich.
Germany Property and Casualty Insurance Market Segmentation
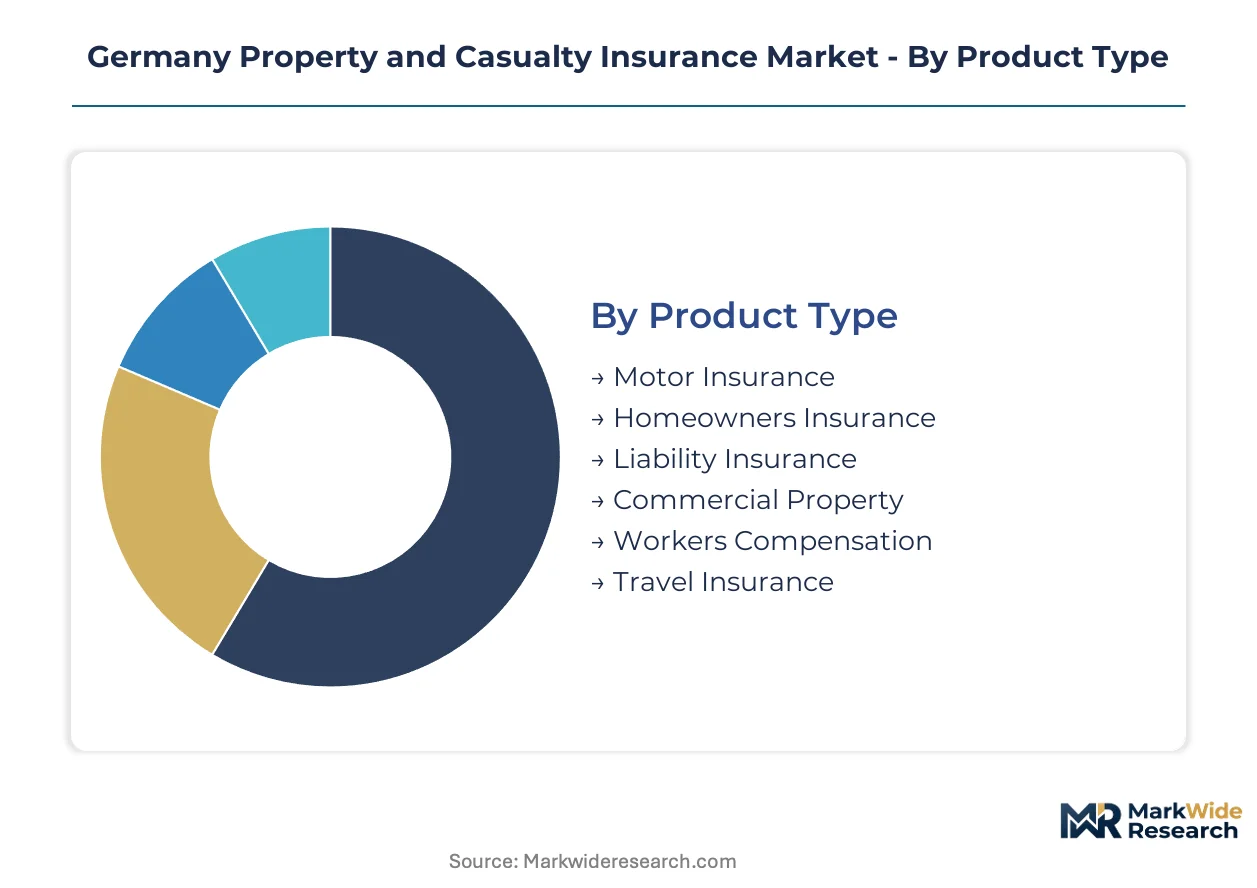
German property and casualty insurers segment their portfolios across product lines, distribution channels, customer profiles, and underwriting approaches. Each dimension reveals distinct margin structures and capital intensity requirements under Solv II. Product mix determines reserve adequacy calculations, while distribution choice shapes acquisition cost ratios and customer lifetime value.
Product Type:
Cost tier differentiation separates mass-market personal lines from capital-intensive commercial portfolios requiring sophisticated catastrophe modeling.
- Motor Insurance:Third-party liability and comprehensive vehicle coverage generate the largest premium volume across German states. Claims inflation from advanced driver assistance system repairs compresses technical margins for Bavarian and Baden-Württemberg carriers. Telematics integration is capturing younger risk pools through smartphone-based driving behavior scoring.
- Homeowners Insurance:Residential property coverage combines building and contents protection against fire, storm, and water damage. Demand concentrates in owner-occupied housing stock across North Rhine-Westphalia's urban corridors. Climate risk disclosure mandates from the EU Green Deal are forcing repricing in flood-exposed Rhine Valley municipalities.
- Liability Insurance:Personal and professional indemnity coverage indemnifies policyholders against third-party claims.
- Commercial Property:Industrial asset protection for manufacturing facilities, warehouses, and infrastructure assets.
- Workers Compensation:Statutory employer liability coverage for occupational injury and disease claims.
- Travel Insurance:Trip cancellation, medical emergency, and baggage protection for leisure and business travelers.
Motor Insurance holds installed capacity. Liability Insurance is rotating up the share rankings.
Distribution Channel:
Customer acquisition economics vary sharply across direct, intermediated, and embedded distribution architectures.
- Direct Sales:Carrier-owned channels bypass intermediary commissions through telephone and mail-based customer acquisition. HUK-Coburg Versicherungsgruppe anchors mass-market penetration through this model. Cost advantages enable price competition that erodes traditional agent commission structures.
- Insurance Brokers:Independent intermediaries advise commercial buyers and high-net-worth individuals on complex multi-line placements. Broker networks are rewriting distribution economics in Germany's property and casualty sector. Corporate risk managers are consolidating vendor relationships and demanding integrated property-cyber-business interruption programs.
- Bancassurance:Bank branch distribution of standard personal lines products to depositors and mortgage customers.
- Online Platforms:Digital comparison engines and direct-to-consumer portals for standardized product categories.
- Agent Networks:Tied representative structures exclusive to single carrier product portfolios.
- Telemarketing:Outbound sales operations targeting renewal periods and cross-sell opportunities.
Insurance Brokers hold installed capacity. Online Platforms are rotating up the share rankings.
Customer Type:
Account size and risk complexity determine service intensity, pricing sophistication, and retention economics.
- Individual Policyholders:Retail consumers purchasing motor, homeowners, and personal liability coverage through standardized products. Demand concentrates among dual-income households in suburban Munich and Frankfurt metropolitan zones. Telematics penetration is capturing younger risk pools through smartphone-integrated driving behavior scoring.
- Small Businesses:Mittelstand manufacturers and service enterprises requiring bundled property, liability, and business interruption protection. Mid-sized Mittelstand manufacturers remain underinsured against ransomware and business interruption, creating room for standalone cyber policies.
- Corporations:Large industrial and commercial enterprises with complex multi-national risk profiles.
- Public Sector Entities:Municipal governments and state agencies procuring property and liability coverage.
- Nonprofit Organizations:Charitable and social service entities with specialized directors and officers liability needs.
- Freelancers:Self-employed professionals purchasing professional indemnity and portable business equipment coverage.
Individual Policyholders hold installed capacity. Small Businesses are rotating up the share rankings.
Underwriting Segment:
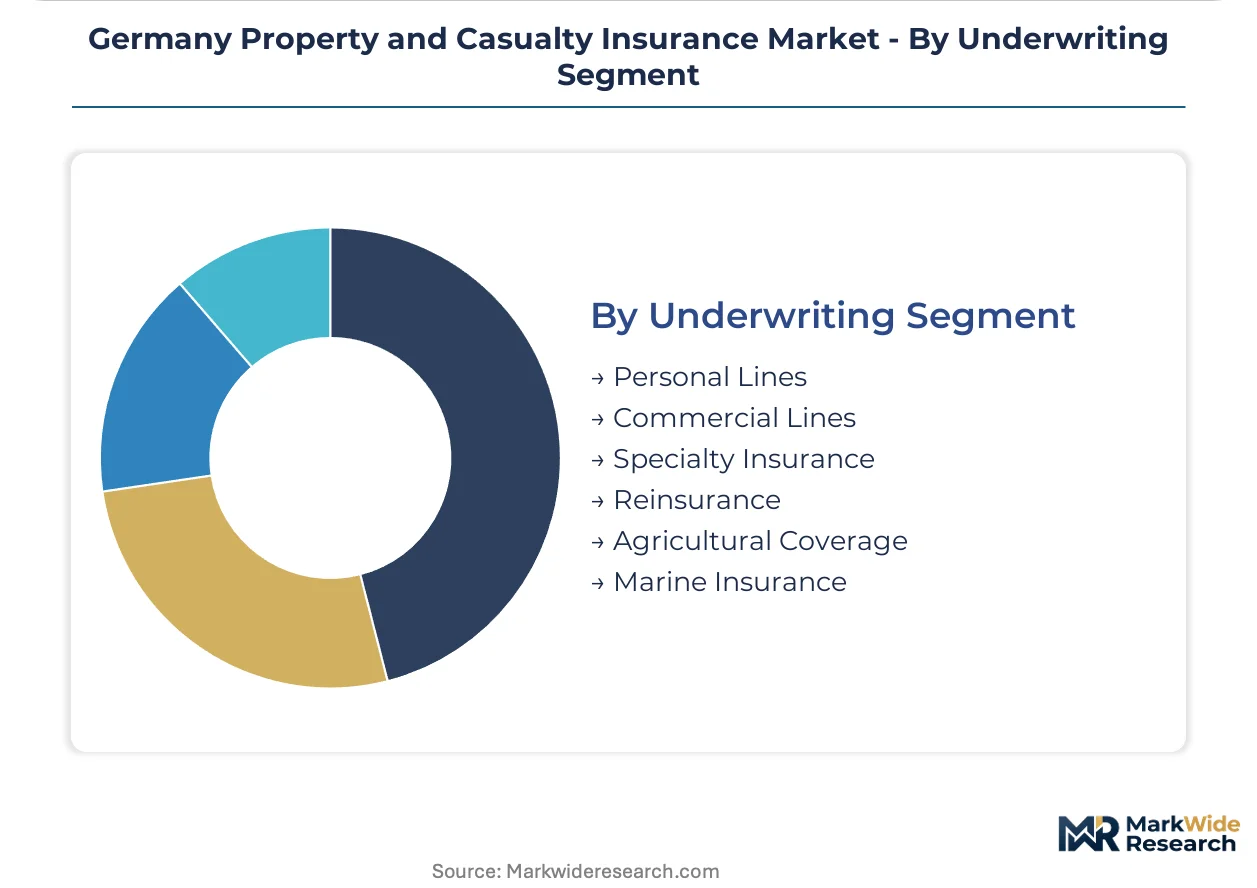
Portfolio construction separates retail personal lines from commercial and specialty books with distinct capital requirements.
- Personal Lines:Standardized retail products for individual and household risk transfer. Motor and liability products dominate premium generation across Bavaria, North Rhine-Westphalia, and Baden-Württemberg. Claims inflation from advanced driver assistance system repairs compresses technical margins for regional carriers.
- Commercial Lines:Mid-market and large corporate property, liability, and business interruption coverage. Commercial property coverage demand is rising among German logistics operators scaling automated warehouses and cold-chain facilities along the Rhine-Alpine corridor.
- Specialty Insurance:Non-standard risks requiring bespoke underwriting and alternative risk transfer structures.
- Reinsurance:Risk capacity provision to primary carriers through treaty and facultative arrangements.
- Agricultural Coverage:Crop, livestock, and farm property protection against weather and disease perils.
- Marine Insurance:Hull, cargo, and liability coverage for inland waterway and ocean-going vessels.
Personal Lines hold installed capacity. Commercial Lines are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria commands pricing premiums in commercial motor coverage that undercut North Rhine-Westphalia's competitive rates by double-digit margins. This asymmetry reflects divergent risk pools, regulatory enforcement intensity, and industrial composition across German states.
Bavaria
Automotive manufacturing clusters around Munich and Ingolstadt sustain concentrated demand for fleet motor and commercial liability coverage. BaFin's Solvency II capital requirements bind regional carriers to stricter reserve adequacy standards than neighboring states. Allianz SE leverages its captive agent infrastructure to dominate premium generation across Bavaria's suburban corridors.
North Rhine-Westphalia
Logistics operators along the Rhine-Alpine corridor are scaling commercial property coverage for automated warehouses and cold-chain facilities. EU Green Deal climate risk disclosure mandates force repricing of flood-exposed policies in Cologne-Düsseldorf metropolitan zones. Industrial policyholders face parametric storm coverage expansion as primary carriers withdraw capacity from high-risk municipalities.
Baden-Württemberg
Mid-sized Mittelstand manufacturers generate rotating demand for cyber liability and professional indemnity protection. Regional insurers deploy computer vision for automated damage assessment, collapsing loss adjustment expense ratios. Stuttgart's machinery and automotive supplier density creates specialized underwriting expertise unavailable in northern states.
Hesse
Frankfurt's DAX-listed industrial headquarters consolidate vendor relationships and demand integrated property-cyber-business interruption programs. Reinsurance capacity from Munich Re and Hannover Re flows through Frankfurt-based broker networks to primary carriers. Financial services concentration elevates directors and officers liability coverage penetration above national averages.
Hamburg
Marine cargo and inland waterway hull coverage clusters around the Port of Hamburg's shipping infrastructure. Hanseatic underwriting traditions sustain specialty insurance expertise in maritime liability and logistics interruption. Northern port exposure to North Sea storm surges drives parametric nat-cat product innovation absent in landlocked southern states.
Germany Property and Casualty Insurance Market Competitive Landscape
Integrated financial conglomerates and mutual insurance associations split the market between scale-driven pricing power and membership-based retention economics. The sector exhibits tiered consolidation: three national carriers capture disproportionate personal lines share while regional Versicherungsvereine retain commercial loyalty through localized underwriting relationships. Dominant competitive moves include embedded distribution partnerships with automotive OEMs and real estate platforms, plus multimillion-euro legacy IT modernization to support real-time data integration.
Among diversified financial services groups, Allianz SE and Munich Re occupy positions that exemplify divergent strategic archetypes: the former anchors mass-market penetration through captive agent infrastructure, while the latter competes at the reinsurance layer extending risk capacity to primary carriers. HUK-Coburg Versicherungsgruppe represents the mutual association model, anchoring direct-to-consumer operations that bypass intermediary commissions and enable price competition eroding traditional agent structures. These three entities collectively illustrate the spectrum from integrated conglomerate to specialized reinsurer to member-owned cooperative that defines German property and casualty competitive dynamics.
| Leading Market Players |
|---|
| AXA Konzern AG |
| R+V Versicherung AG |
| Allianz SE |
| Zurich Insurance |
| HUK-Coburg Versicherungsgruppe |
| Munich Re |
| Generali Deutschland |
| Hannover Re |
| Talanx Group |
| Others |
Supply & Pricing Matrix
Munich's reinsurance and primary carrier concentration shapes pricing power across German property and casualty lines, with capacity availability in Bavaria directly influencing rate adequacy for commercial portfolios nationwide. BaFin's Solvency II capital requirements tighten reserve standards for carriers headquartered in this cluster, compressing technical margins and forcing selective withdrawal from catastrophe-exposed regions.
Pricing Analysis
The customization-premium spread separates configured-to-order commercial multi-peril programs from standardized personal lines products. Three-tier pricing structure across premium, standard, and economy levels dominates motor and homeowners coverage, with telematics-integrated policies commanding rate advantages over traditional rating. Cost compression in mass-market motor lines is intensifying because claims inflation from advanced driver assistance system repairs outpaces rate filings. Individual policyholders purchasing through direct channels exhibit highest price sensitivity, while DAX-listed industrials procuring integrated property-cyber-business interruption programs prioritize coverage breadth over premium minimization.
Supply Chain Analysis
Tariff exposure between Germany and key retrocession markets elevates cession costs for commercial property treaties written by domestic primary carriers. Risk capacity draws from Munich, London, and Bermuda, with alternative capital inflows from ILS markets increasingly supplementing traditional reinsurance. Natural catastrophe modeling software, actuarial talent pools, and regulatory compliance infrastructure constitute critical input dependencies. Single-source vulnerability concentrates in legacy IT architecture providers serving established Versicherungsvereine. Distribution runs through Frankfurt-based broker networks for commercial placements, while direct-to-consumer operations bypass intermediary layers entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German property and casualty insurance is cycling through a hard market phase, with reinsurance cost volatility and climate risk repricing driving rate adequacy recovery across commercial lines.
For Market Incumbents: Harden technical margins by accelerating legacy IT modernization to support real-time data integration, addressing the interoperability friction blocking blockchain-based smart contract deployment. Consolidate commercial broker relationships before embedded distribution partnerships with automotive OEMs and real estate platforms displace traditional placement channels. Prioritize catastrophe modeling capability investment to defend pricing power in nat-cat lines facing EU Green Deal disclosure mandates. For New Entrants and Emerging Players: Cyber liability white space among Mittelstand manufacturers in Baden-Württemberg offers the most penetrable entry point, with ransomware and business interruption coverage gaps creating standalone policy demand. Target freelancers and small businesses exposed to professional indemnity risks through digital-first distribution architectures that bypass established agent commission structures. Lead with parametric flood and storm products for industrial policyholders in North Rhine-Westphalia where primary carriers are withdrawing capacity. For Investors and Strategic Acquirers: Carve-out targets emerge from mutual insurance associations seeking to monetize captive member bases while shedding capital-intensive commercial lines. Long-term viability hinges on regulatory technology adaptation capacity and climate risk analytics infrastructure. Monitor BaFin enforcement intensity as the inflection signal: selective withdrawal from high-risk regions accelerates alternative capital inflows and creates acquisition opportunities for well-capitalized platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Legacy IT Modernization | Multimillion-euro core policy administration upgrades enable real-time data integration demanded by BaFin reporting formats. |
| Embedded Distribution Partnership | Automotive OEM and real estate platform integrations capture motor and homeowners coverage at point of sale. |
| Cyber Liability Product Launch | Standalone ransomware and business interruption policies address underinsurance among Mittelstand manufacturers. |
| Parametric Nat-Cat Expansion | Index-based flood and storm coverage fills capacity withdrawal from EU Green Deal stress-tested municipalities. |
| ESG-Linked Captive Structure | In-house insurers allow DAX industrials to directly manage climate transition risks and carbon credit verification. |
Research Methodology
A standing panel of chief underwriting officers, reinsurance treaty negotiators, BaFin supervisory specialists, and corporate risk managers provided ongoing calibration across the study period. Primary interview insights combined with secondary validation from BaFin solvency reports, GDV market statistics, EU Green Deal regulatory filings, and carrier annual disclosures. Bottom-up policy count modeling and top-down premium aggregation triangulated market size estimates.
Scenario-bracketing framed low, base, and high cases around reinsurance capacity availability and climate loss frequency assumptions across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, customer profile, and underwriting segment, with additional granularity on state-level regulatory enforcement intensity. CAGRs derived from trend extrapolation of historical premium growth adjusted for Solvency II capital requirement phase-ins and EU Green Deal implementation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by well-capitalized alternative capital providers or technology-enabled direct writers would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Identity Theft Insurance Market
Insurance
Marine Cargo Insurance Market
Insurance
Mobile Phone Insurance Market
Insurance
Extended Warranty Agreement Market
Insurance
Road Assistance Insurance Market
Insurance
Asia-Pacific Liability Insurance Market
Insurance
Germany Health and Medical Insurance Market
Insurance
Trade Credit Insurance Market
Insurance
Europe EV Insurance Market
Insurance
Boiler Insurance Market
Insurance
Saudi Arabia Health Insurance Market
Insurance
Netherlands Property and Casualty Insurance Market
Insurance
Single Trip Travel Insurance Market
Insurance
US Extended Warranty Market
Insurance
Art Insurance Market
Insurance
GCC Health Insurance Market