
 Canada House Insurance Market | 2026-2036
Canada House Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Canada House Insurance Market Insights
OSFI's capital adequacy guidelines for property and casualty insurers is rebalancing reserve requirements and risk-weighting methodologies across the sector. Intact Financial Corporation leverages its national broker network and direct-to-consumer platform to sustain underwriting scale. Desjardins Insurance anchors its position through cooperative ownership structure and Quebec-focused product specialization. Aviva Canada competes via digital claims infrastructure and segmented pricing for catastrophe-exposed regions.
Canada house insurance constitutes property and casualty coverage protecting residential structures and contents against named perils including fire, wind, water, and theft, with policies specifying deductibles, coverage limits, and replacement valuation methods. The product serves homeowners, renters, and property investors by transferring financial risk of physical asset loss to underwritten pools. Homeowners policies dominate premium volume while landlord coverage expands fastest amid rental housing shortages in Toronto and Calgary. Distribution through broker networks retains the largest share of premium flow, though direct and online channels are capturing digitally native customer segments. Extended replacement coverage commands margin premiums as construction cost inflation elevates rebuild valuations beyond standard policy limits.
Health Canada and PMRA coordinate disaster response frameworks that influence coverage exclusions for environmental hazards, while OSFI governs insurer solvency and capital buffers. Provincial regulators including Alberta's Treasury Board and Finance and British Columbia's Financial Services Authority supervise market conduct, rate filings, and consumer protection standards. The federal National Flood Insurance Program under development will reshape coverage obligations between private underwriters and public backstops. Stakeholders must monitor how climate scenario testing and granular peril modeling will redraw insurability boundaries for high-risk postal codes.
Market Dynamics
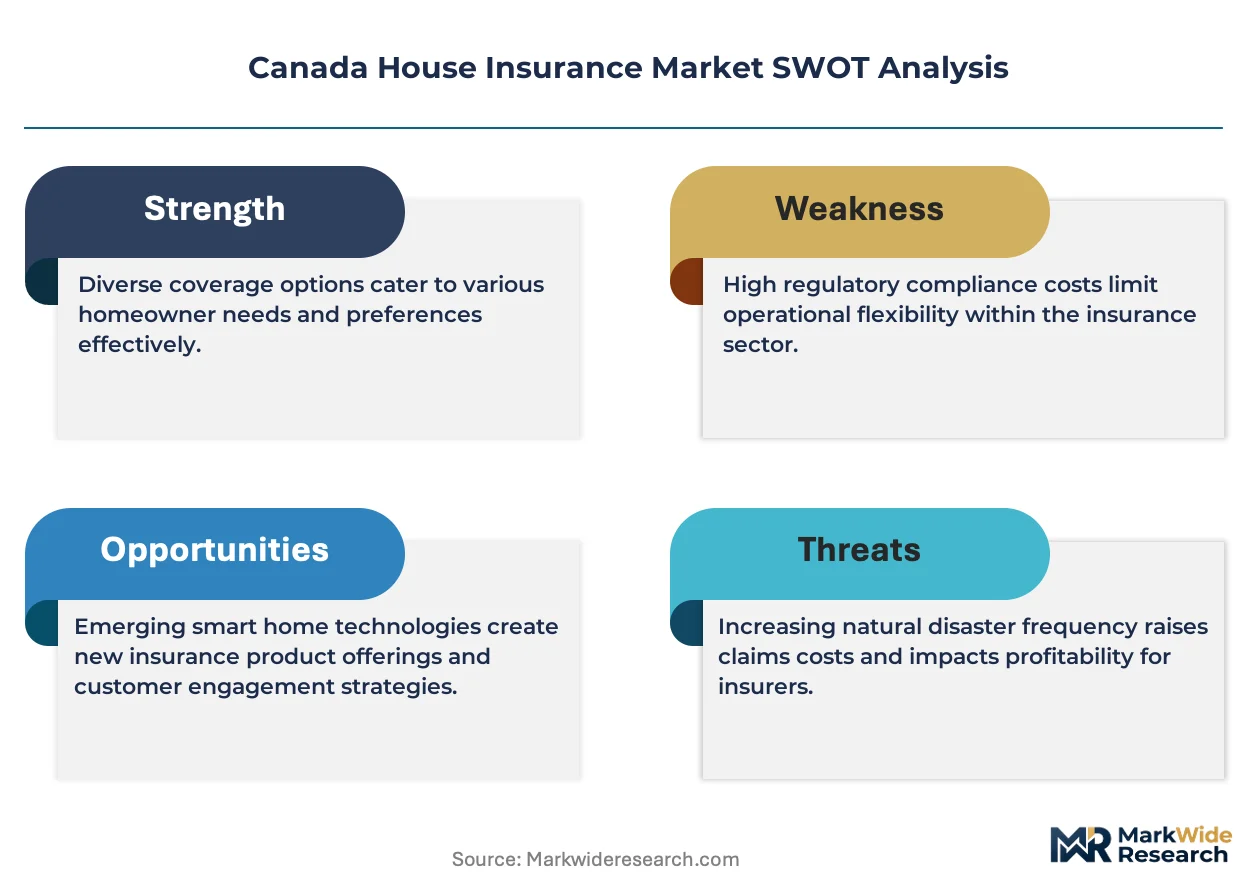
OSFI's climate stress-testing mandates are compressing capital allocation timelines for property and casualty insurers, forcing rapid repricing of catastrophe-exposed portfolios before the National Flood Insurance Program launches.
Growth Catalysts
- First-time buyer expansion:Ontario and British Columbia municipalities are accelerating permit approvals for dense infill housing, creating concentrated demand for comprehensive replacement policies among new homeowners.
- Federal flood framework:The National Flood Insurance Program under development is clarifying coverage boundaries between private underwriters and public backstops, reducing regulatory uncertainty for product development.
- Wildfire model refinement:Catastrophe modeling vendors are deploying granular peril scoring for Alberta postal codes, enabling risk-based pricing that was previously unavailable in standard rating territories.
Market Restraints
- Construction cost volatility:Lumber and concrete input prices have destabilized replacement cost estimators, forcing insurers to either absorb margin compression or trigger policyholder disputes over valuation disputes.
- Reinsurance capacity concentration:Bermuda and London market capacity providers are tightening attachment points for Canadian property treaties, elevating net retention burdens for domestic primary carriers.
- Regulatory filing friction:Alberta's Treasury Board and Finance maintains rate approval timelines that lag real-time peril accumulation, creating capital deployment mismatches during rapid climate adjustment cycles.
Strategic Opportunities
- Landlord coverage white space:Toronto and Calgary rental housing shortages are intensifying institutional investor participation in multi-unit residential, creating demand for specialized rental property products with tenant default riders.
- Parametric product convergence:Satellite-based precipitation monitoring and IoT water sensors are enabling index-triggered flood endorsements that bypass traditional loss adjustment overhead.
- Digital direct distribution:Broker channel capture is fragmenting as digitally native cohorts in Vancouver and Montreal migrate to app-based policy binding with instant claims imaging.
Industry Challenges
- Actuarial talent scarcity:Climate risk modeling specialization is concentrating among a narrow cohort of credentialed professionals, extending product development timelines for regional insurers without captive modeling units.
- Legacy core system integration:Real-time peril data feeds from meteorological services are crashing against policy administration platforms built on batch-processing architectures, requiring expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada House Insurance Market |
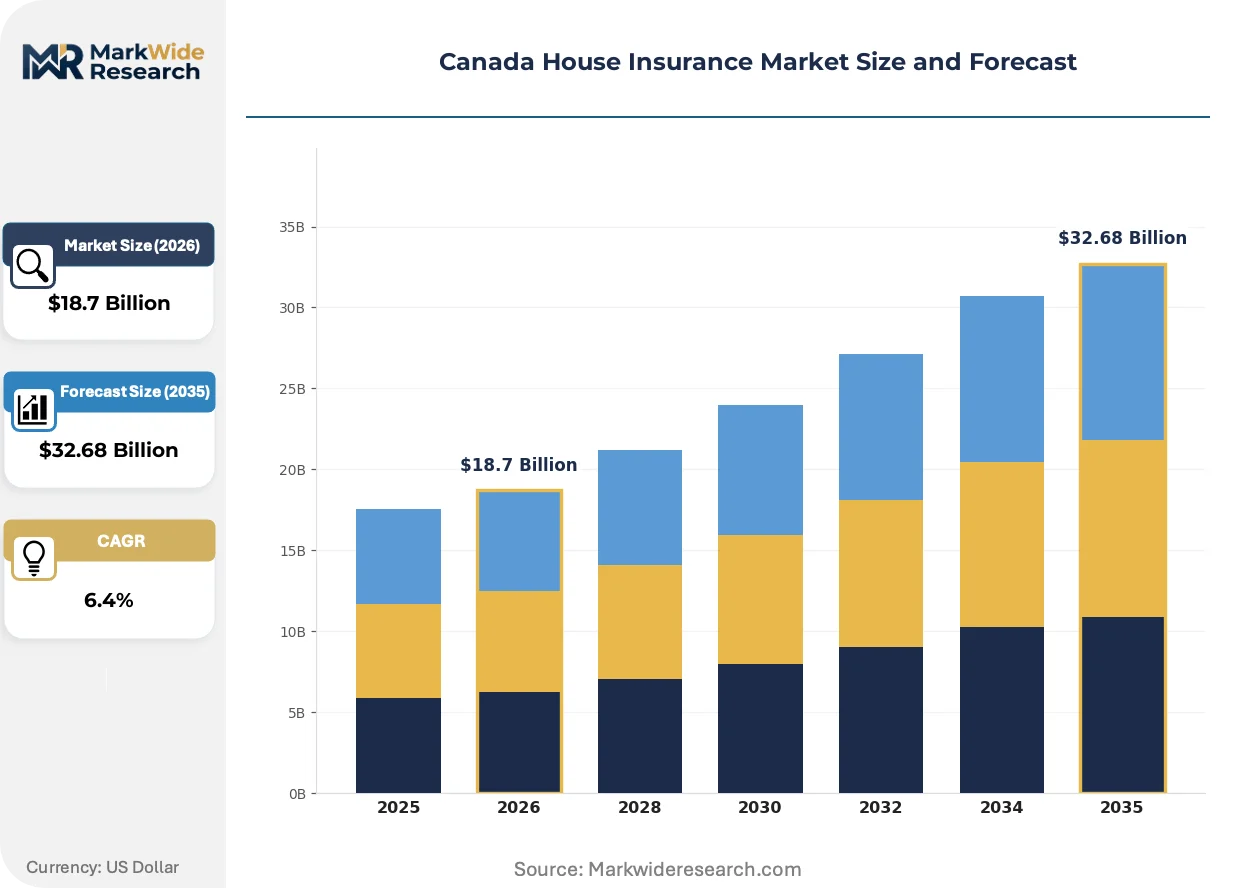
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Homeowners, Renters, Landlord, Vacation, Mobile Home Coverage Level: Total Replacement, Actual Cash Value, Extended Replacement, Basic Coverage Distribution Channel: Direct, Broker, Online, Comparison Sites Customer Demographic: Young Families, Retirees, Singles, New Home Buyers |
| Companies Covered | Intact Financial Corporation, Desjardins Insurance, Aviva Canada, The Co-operators Group, TD Insurance, Wawanesa, Allstate Insurance Company of Canada, Economical Mutual, CAA Insurance, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada House Insurance Market Trends and Innovations
Telematics and remote sensing are collapsing the information asymmetry between insurers and policyholders, enabling dynamic pricing that responds to individual property conditions rather than postal code aggregates.
IoT-connected water leak detectors are electrifying loss prevention strategies for high-value residential portfolios. Intact and Desjardins are subsidizing sensor installation for policyholders in flood-prone Ontario watersheds. This technology is compressing water damage frequency rates and shifting underwriting focus from post-loss indemnification to pre-loss intervention.
Health Canada and PMRA are coordinating disaster response frameworks that expand coverage exclusions for mold and contamination following flood events. This regulatory tightening is pushing insurers to develop standalone environmental hazard endorsements. Quebec and British Columbia regulators are demanding enhanced disclosure of these exclusions at point of sale, altering broker training requirements.
Buyer behavior is fragmenting across channel preferences as younger cohorts abandon annual renewal cycles for on-demand coverage adjustments. Digital-native platforms are disintermediating traditional broker relationships in urban centers. This channel rotation is most visible in Vancouver condominium markets, where unit turnover rates drive frequent policy cancellation and rebinding activity.
Canada House Insurance Market Segmentation
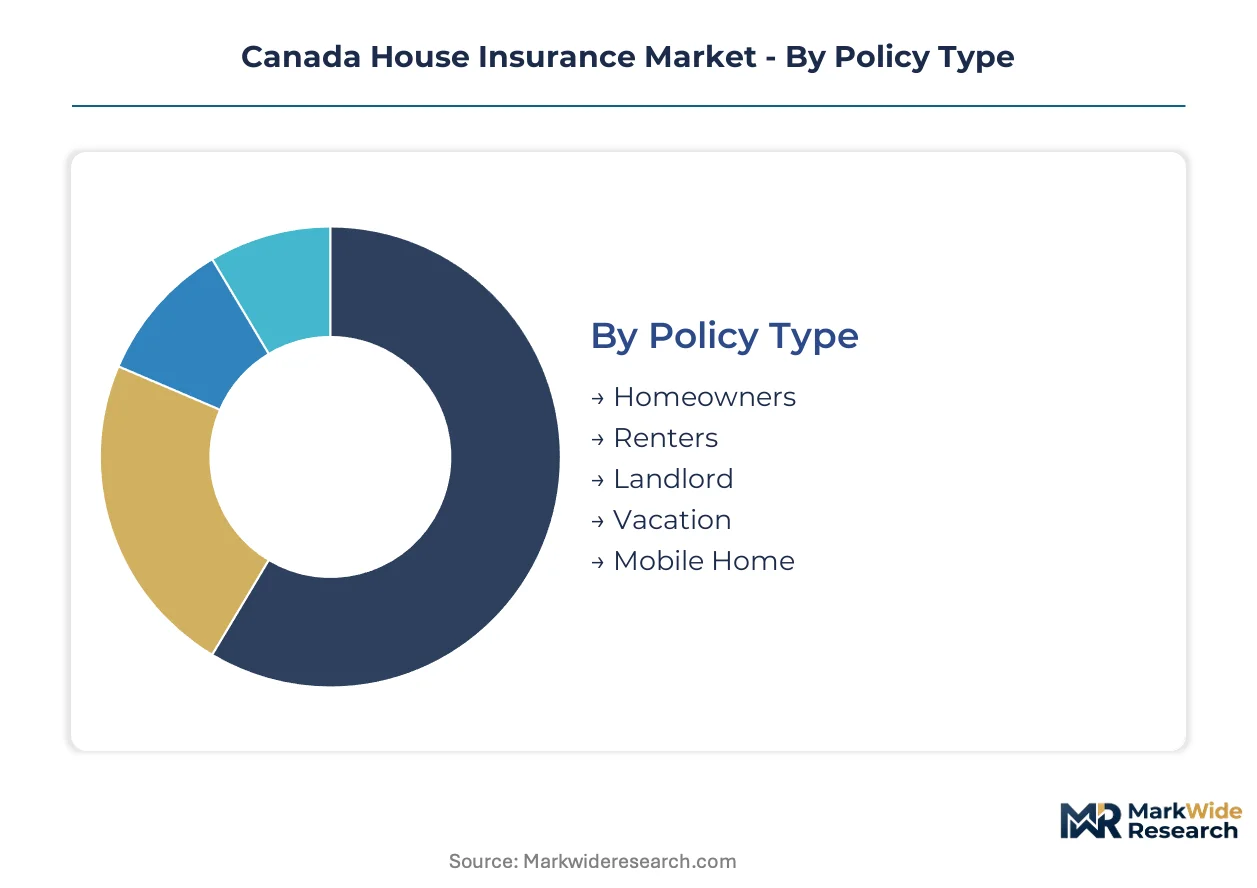
Segmentation in the Canada house insurance market reveals divergent risk appetites and purchasing behaviors across policy structures, valuation methods, and channel preferences. Understanding these divisions enables carriers to align product design with specific buyer economics and regulatory exposures.
Policy Type:
Buyer risk profiles and asset ownership patterns fundamentally differentiate demand across policy categories.
- Homeowners:Comprehensive dwelling and contents protection for owner-occupied single-family and condominium units. Demand concentrates in Ontario's Greater Toronto Area and Vancouver's detached housing markets, where mortgage lenders mandate full replacement coverage as loan condition.
- Landlord:Specialized coverage for rental property owners protecting structure, liability, and rental income interruption. Toronto and Calgary institutional investors are driving uptake amid multi-unit residential shortages, with tenant default riders emerging as critical differentiator.
- Renters:Contents-only policies protecting personal property and liability for leaseholders. Young professionals in Montreal and Vancouver are expanding this segment as rental tenure lengthens.
- Vacation:Seasonal dwelling coverage for secondary residences with adjusted occupancy risk weighting. Ontario cottage country and British Columbia ski properties generate concentrated demand.
- Mobile Home:Modified structural coverage accounting for transportable foundation risks and depreciation curves. Alberta and rural Quebec manufacturing communities sustain this niche.
Homeowners leads volumes today; landlord coverage is gaining share fastest.
Coverage Level:
Valuation methodology selection reflects construction cost volatility exposure and mortgage lender requirements.
- Total Replacement:Full rebuild cost coverage without depreciation deduction, typically capped at policy limit plus inflation guard. OSFI's climate stress-testing is hardening demand in Alberta wildfire zones and Ontario floodplains where rebuild costs exceed original purchase prices.
- Extended Replacement:Coverage exceeding stated dwelling limit by fixed percentage to address construction cost spikes. Vancouver and Toronto policyholders are selecting this option as lumber and concrete input volatility destabilizes standard estimators.
- Actual Cash Value:Depreciated settlement based on age and condition of damaged property. Retirees in Atlantic Canada are accepting this trade-off for premium reduction on older dwellings.
- Basic Coverage:Named-peril policies covering fire, lightning, and limited perils only. First-time buyers in Quebec are selecting this entry-level option before upgrading to comprehensive terms.
Total replacement dominates premium flow; extended replacement is climbing the fastest as inflation persists.
Distribution Channel:
Purchasing behavior fragments sharply across age cohorts and policy complexity requirements.
- Broker:Independent and captive intermediaries providing comparative placement and claims advocacy. Complex landlord and high-value homeowner policies in Ontario and British Columbia sustain broker channel dominance.
- Direct:Carrier-owned sales forces and call centers handling straightforward renewals and standard homeowner policies. Intact and Desjardins are investing in direct infrastructure to capture efficiency gains.
- Online:Carrier websites and proprietary apps enabling instant quoting and policy binding. Vancouver and Montreal millennials are migrating to this channel for condominium coverage.
- Comparison Sites:Aggregator platforms displaying multi-carrier pricing for standardized products. Young families in Alberta are using these tools for initial market exploration before broker consultation.
Broker networks retain largest share; online binding is expanding most quickly among urban millennials.
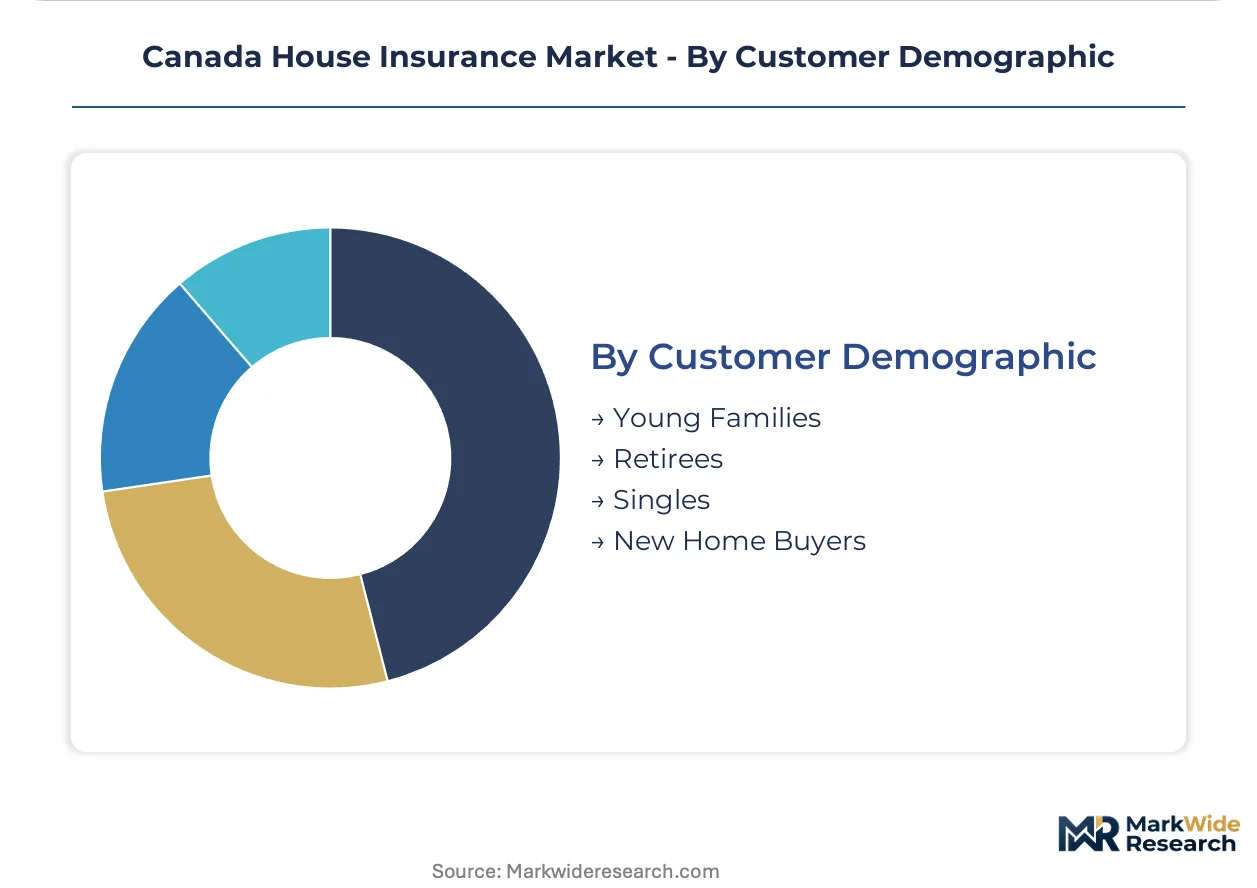
Customer Demographic:
Life stage and asset accumulation patterns determine coverage breadth and price sensitivity.
- New Home Buyers:First-time purchasers requiring lender-mandated comprehensive coverage with minimal deductibles. Ontario and British Columbia municipalities are accelerating permit approvals for dense infill housing, concentrating demand among this cohort.
- Young Families:Growing households upgrading from renters to homeowners and expanding liability limits. Calgary and Toronto suburbs are seeing this demographic drive replacement cost estimator revisions.
- Retirees:Empty-nest homeowners optimizing coverage for paid-off properties and fixed incomes. Quebec and Atlantic Canada regions show preference for actual cash value settlements.
- Singles:Unattached individuals selecting renters or condominium policies with minimal contents coverage. Downtown Vancouver and Montreal rental markets sustain this segment.
New home buyers anchor volume growth; young families show steepest expansion trajectory as household formation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Actuarial talent clusters in Toronto and Montreal anchor the industry's geographic distribution, with risk modeling expertise concentrating where major carriers maintain headquarters and catastrophe research facilities.
Ontario
First-time buyers in the Greater Toronto Area drive comprehensive replacement policy uptake as municipal infill permits accelerate. OSFI's capital adequacy guidelines govern solvency requirements for carriers headquartered in Toronto. The Kitchener-Waterloo corridor hosts insurtech ventures developing digital distribution platforms.
Quebec
Cooperative ownership structures sustain localized product specialization serving Montreal's condominium density. Desjardins anchors market presence through member-based governance. Quebec City's regulatory environment shapes consumer protection standards for French-language policy disclosure.
British Columbia
Vancouver's rental housing shortages intensify landlord coverage demand among institutional investors. The British Columbia Financial Services Authority supervises rate filings for wildfire-exposed portfolios. Kelowna and Victoria secondary markets generate vacation property coverage concentration.
Alberta
Calgary's multi-unit residential expansion drives rental income protection products for property investors. The Treasury Board and Finance maintains rate approval timelines affecting capital deployment cycles. Edmonton and Fort McMurray postal codes concentrate wildfire model refinement activity.
Atlantic Canada
Retirees in Halifax and St. John's optimize actual cash value settlements for paid-off coastal properties. Health Canada coordinates disaster response frameworks influencing flood coverage exclusions. Charlottetown's smaller risk pools limit carrier participation in comprehensive product offerings.
Canada House Insurance Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distribution channel and geographic coverage dimensions. The market exhibits tiered consolidation with national broker networks, cooperative structures, and direct-to-consumer platforms occupying distinct competitive positions. Three archetypes dominate: integrated financial services groups leveraging cross-selling infrastructure, mutual and cooperative entities emphasizing member governance, and technology-forward carriers prioritizing digital claims automation. M&A activity concentrates on broker network consolidation and insurtech capability acquisition.
Within the integrated financial services tier, Intact Financial Corporation and TD Insurance exemplify scale-driven national coverage through diversified product portfolios. Desjardins Insurance anchors the cooperative archetype with Quebec-focused governance structures. Aviva Canada occupies a position representing international carrier adaptation to Canadian catastrophe modeling requirements.
| Leading Market Players |
|---|
| Intact Financial Corporation |
| Desjardins Insurance |
| Aviva Canada |
| The Co-operators Group |
| TD Insurance |
| Wawanesa |
| Allstate Insurance Company of Canada |
| Economical Mutual |
| CAA Insurance |
| Others |
Pricing and Supply Chain Analysis
Broker-network-rolled distribution specialists anchor pricing discipline through commission structures that tether carrier profitability to intermediary retention rates, while reinsurance capacity concentration in Bermuda and London forces Canadian primary carriers to absorb elevated net retention burdens that compress underwriting margins.
Pricing Analysis
The bundled-vs-unbundled service split separates comprehensive replacement policies with inflation guard riders from stripped-down named-peril coverage. Three-tier pricing structure across premium, standard, and economy levels stratifies by deductible level, extended replacement endorsement inclusion, and claims service tier. Pricing pressure stems from construction cost volatility as lumber and concrete input spikes destabilize replacement cost estimators. First-time buyers in Ontario and British Columbia show highest price sensitivity, while institutional landlords in Toronto accept premium positioning for tenant default protection.
Supply Chain Analysis
Warehouse-distribution layer concentration in Toronto and Montreal anchors broker network logistics, with regional underwriting hubs feeding provincial adjuster deployment. Domestic actuarial talent clusters in these cities draw from university programs and carrier headquarters proximity. Supply chain risk centers on single-source vulnerability for catastrophe modeling software from international vendors. Distribution runs through independent broker networks retaining largest premium flow share, though direct carrier platforms are fragmenting channel capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Canadian house insurance rests on parametric product adoption that collapses loss adjustment expense ratios and shifts value capture from indemnification to prevention.
For Market Incumbents: Anticipate digital-native entrant pressure in Vancouver and Montreal condominium segments by accelerating broker platform digitization and embedding IoT sensor subsidies into high-value homeowner policies. Vertical integration into proprietary catastrophe modeling capabilities reduces dependency on international vendor pricing power. Defend position through exclusive tenant default rider development for Toronto institutional landlord accounts. For New Entrants and Emerging Players: Digital comparison site partnerships offer lowest-friction customer acquisition for standardized renter policies in Alberta and Quebec. White space concentrates in parametric flood endorsements for Ontario watershed properties where traditional loss adjustment overhead erodes carrier economics. Target Atlantic Canada retiree segments with actual cash value products priced below comprehensive replacement alternatives. For Investors and Strategic Acquirers: Valuations sit cheapest among regional mutual carriers lacking captive modeling units and dependent on third-party vendor relationships. Long-term viability hinges on climate scenario testing infrastructure that redraws insurability boundaries for high-risk postal codes. Acquisition target archetype: mid-cap Ontario or British Columbia regional with underdigitized broker network and concentrated catastrophe exposure. Watch OSFI capital adequacy guideline revisions as inflection signal for forced consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| IoT Sensor Subsidy Program | Intact and Desjardins deployments in Ontario floodplains compress water damage frequency and shift underwriting to pre-loss intervention. |
| Parametric Product Launch | Satellite precipitation monitoring enables index-triggered flood endorsements that bypass traditional loss adjustment overhead. |
| Broker Network Digitization | Direct-to-consumer platform investment captures digitally native cohorts abandoning annual renewal cycles in Vancouver condominium markets. |
| Climate Modeling Capability Acquisition | In-house peril scoring reduces reinsurance treaty dependency as Bermuda and London markets tighten attachment points. |
| Tenant Default Rider Expansion | Specialized rental income protection addresses Toronto and Calgary multi-unit residential shortages among institutional investors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with property and casualty underwriting executives, independent broker principals, provincial regulator officials, and catastrophe modeling specialists with secondary validation through OSFI solvency filings, provincial rate approval databases, and carrier annual reports. Bottom-up policy segmentation data triangulated against top-down premium flow estimates from broker network disclosures.
Historical reference periods anchored the forecast window to observed climate loss development patterns and regulatory filing cycles across the analysis window. Segmentation dimensions modeled include policy type, coverage valuation methodology, distribution channel, and customer demographic life stage. CAGRs derived from trend extrapolation of permit approval velocity, household formation rates, and climate exposure accumulation. Key inputs encompassed construction cost inflation trajectories and reinsurance capacity availability assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to National Flood Insurance Program implementation timing and wildfire model refinement adoption rates across Alberta postal codes. Outputs reflect documented assumptions regarding climate scenario severity and regulatory capital requirement stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
AI in Insurance Market
Insurance
Specialty Insurance Market
Insurance
Cargo Insurance Market
Insurance
Commercial Insurance Market
Insurance
Business Travel Accident Insurance Market
Insurance
China Property and Casualty Insurance Market
Insurance
Social Media Analytics-Based Insurance Market
Insurance
Global Vehicle Insurance Market
Insurance
EV Insurance Market
Insurance
Cybersecurity Insurance Market
Insurance
Australia Parametric Insurance Market
Insurance
Saudi Arabia Health & Medical Insurance Market
Insurance
Bancassurance Market
Insurance
US Extended Warranty Market
Insurance
Intellectual Property Liability Insurance Market
Insurance
Reinsurance Carriers Market