
 Fire Insurance Market | 2026-2036
Fire Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Fire Insurance Market Intelligence
Advanced risk modeling software is rebalancing underwriting economics across the fire insurance value chain. State Farm leverages proprietary catastrophe modeling to sustain pricing power in wildfire-exposed states. Chubb anchors high-net-worth residential portfolios through specialized loss-prevention engineering services. Berkshire Hathaway competes via scale advantages in reinsurance-backed primary coverage.
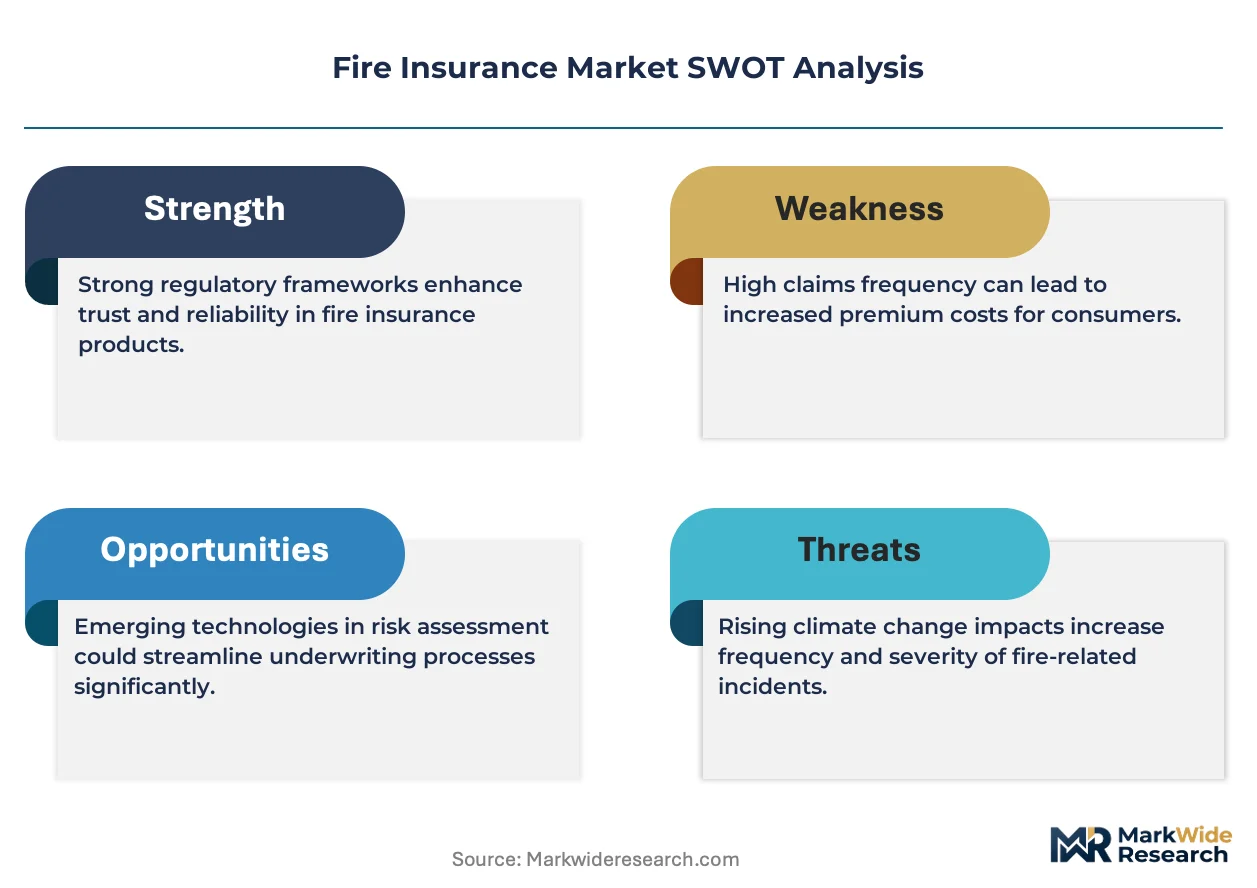
Fire insurance constitutes property coverage indemnifying policyholders against direct physical loss or damage from combustion, lightning, or smoke, with policies typically specifying deductibles, coverage limits, and coinsurance clauses tied to replacement cost valuations. Commercial and industrial segments dominate premium volume as manufacturing facilities, warehousing complexes, and energy infrastructure carry concentrated asset values requiring tailored all-risk coverage. Residential demand clusters in standard-tier products, while high-net-worth customized policies capture disproportionate margin pools through bundled valuation services and risk mitigation consulting.
State insurance regulators in the U.S. enforce solvency standards and rate-approval processes that directly constrain pricing flexibility and market entry. The National Association of Insurance Commissioners coordinates catastrophe reserve requirements, while ISO develops standardized policy forms and loss costs that shape product design across admitted carriers. Stakeholders must monitor evolving climate disclosure mandates from securities regulators and their downstream effects on capital allocation to fire-exposed underwriting lines.
Market Dynamics
Wildfire risk recalibration is compressing capacity in high-exposure states and forcing carriers to retreat from unprofitable geographies, while the U.S. Inflation Reduction Act's climate resilience provisions redirect capital toward hardened construction standards and mitigation-linked underwriting.
Growth Catalysts
- Catastrophe modeling software:Advanced simulation platforms enable granular risk pricing that sustains carrier participation in wildfire corridors. Commercial real estate developers in California and Australia now procure coverage contingent on third-party fire-risk scores.
- IRAs climate resilience provisions:Federal tax incentives for fire-resistant building materials expand the addressable market for construction-phase coverage. Property developers embed insurance procurement into project financing structures.
- Mediterranean Europe exposure growth:Portugal, Spain, and Greece are recording consecutive years of record fire losses that force traditional carriers to cede premium volume to specialty underwriters with engineering capabilities.
Market Restraints
- Reinsurance capacity concentration:Bermuda and London market reinsurers dominate catastrophe retrocession, creating pricing power asymmetry that squeezes primary carrier margins during hard market cycles.
- State rate-approval friction:California Department of Insurance and similar state regulators constrain premium adequacy through prior-approval statutes that lag loss cost inflation by 18-24 months.
- Parametric substitute emergence:Satellite-triggered wildfire policies from alternative capital providers displace traditional indemnity coverage for agricultural and forestry assets.
Strategic Opportunities
- High-net-worth residential engineering:Bundled loss-prevention consulting and guaranteed replacement cost valuation capture margin pools unavailable in commoditized standard-tier products.
- Industrial facility hardening mandates:Energy infrastructure operators in Texas and Louisiana face NFPA 1300 wildfire mitigation standards that create demand for compliance-linked coverage structures.
- Climate disclosure convergence:SEC and EU CSRD reporting requirements force institutional asset managers to document fire exposure, expanding demand for portfolio-level risk transfer instruments.
Industry Challenges
- Actuarial talent scarcity:Fire-specific catastrophe modelers command premium compensation that strains mid-tier carrier staffing budgets.
- Legacy policy administration integration:Established carriers struggle to embed real-time sensor data from IoT fire detection systems into decades-old core systems.
- Cross-state licensing complexity:Surplus lines authorization requirements vary across 50 state jurisdictions, slowing product rollout for national program administrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire Insurance Market |
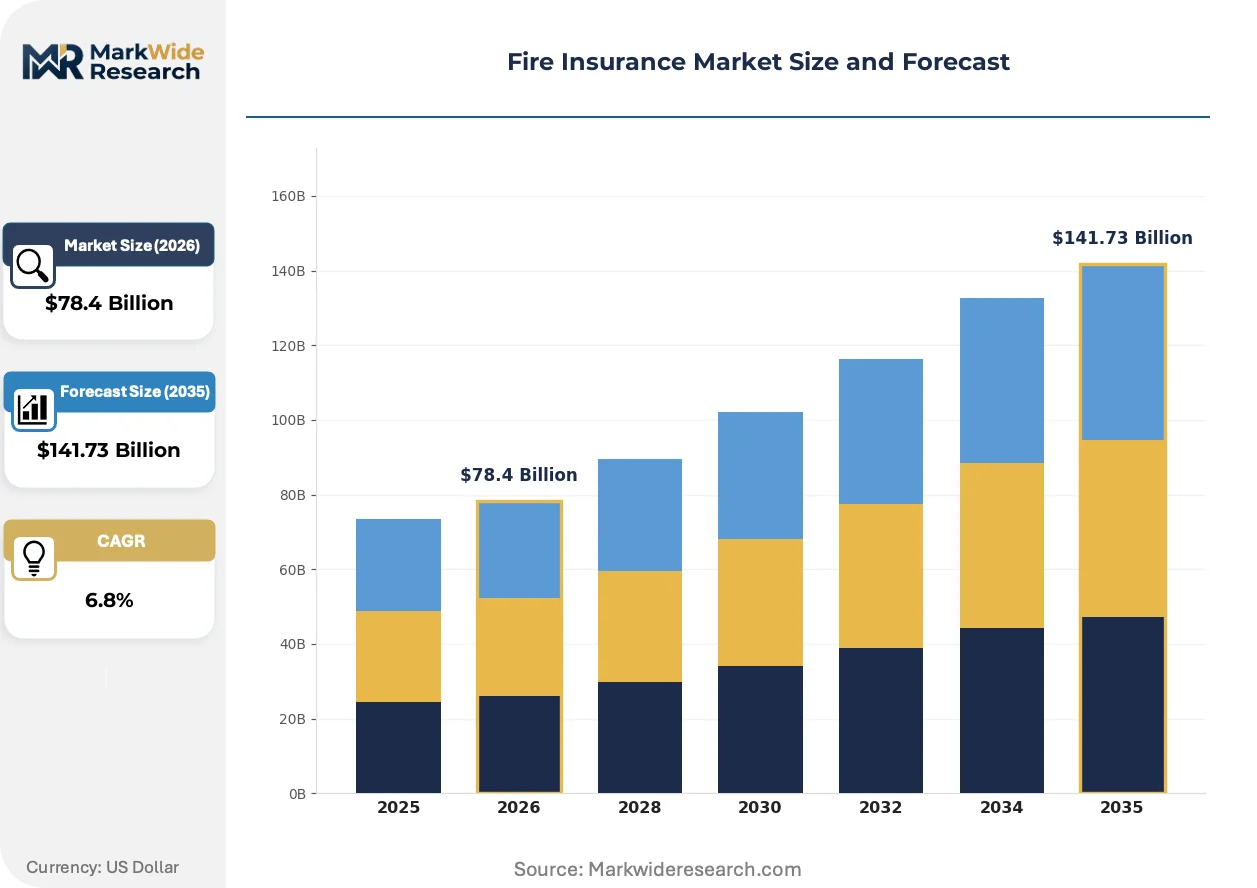
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Residential, Commercial, Industrial, Agricultural Coverage Type: Named Perils, All-Risk, Basic Coverage, Extended Coverage Policyholder Type: Individuals, Businesses, Non-Profits, Government Entities Premium Tier: Standard, High-Net-Worth, Economical, Customized |
| Companies Covered | Liberty Mutual, Farmers Insurance Group, State Farm, Zurich, Chubb, Berkshire Hathaway, American International Group, USAA, Progressive Insurance Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire Insurance Market Strategic Shifts & Innovations
Sensor-enabled risk monitoring and algorithmic underwriting are compressing the traditional inspection-to-bind timeline while regulatory disclosure mandates reshape how institutional buyers evaluate fire exposure across property portfolios.
Remote sensing platforms integrating satellite thermal imaging with ground-based weather station networks are consolidating underwriting workflows for wildfire-exposed commercial properties. Large industrial facility operators in California and Australia now require continuous monitoring as a condition of coverage placement. This technology stack is consolidating actuarial functions that previously required separate peril-specific models into unified wildfire probability engines.
The EU Corporate Sustainability Reporting Directive and SEC climate disclosure rules are mandating granular fire risk quantification for institutional real estate portfolios. Asset managers must now document physical climate exposure in audited financial statements. Commercial mortgage-backed securities issuers in the United States and European Union are responding by embedding insurance procurement covenants that exceed standard lender requirements.
Buyers are fragmenting coverage placement across multiple surplus lines carriers rather than consolidating with single admitted market underwriters. Large commercial real estate developers in high-risk zones now layer coverage across five to seven carriers to secure adequate limits. This pattern is most visible in California's Central Valley and Colorado's Front Range, where single-carrier capacity constraints force sophisticated procurement strategies.
Fire Insurance Market Segmentation
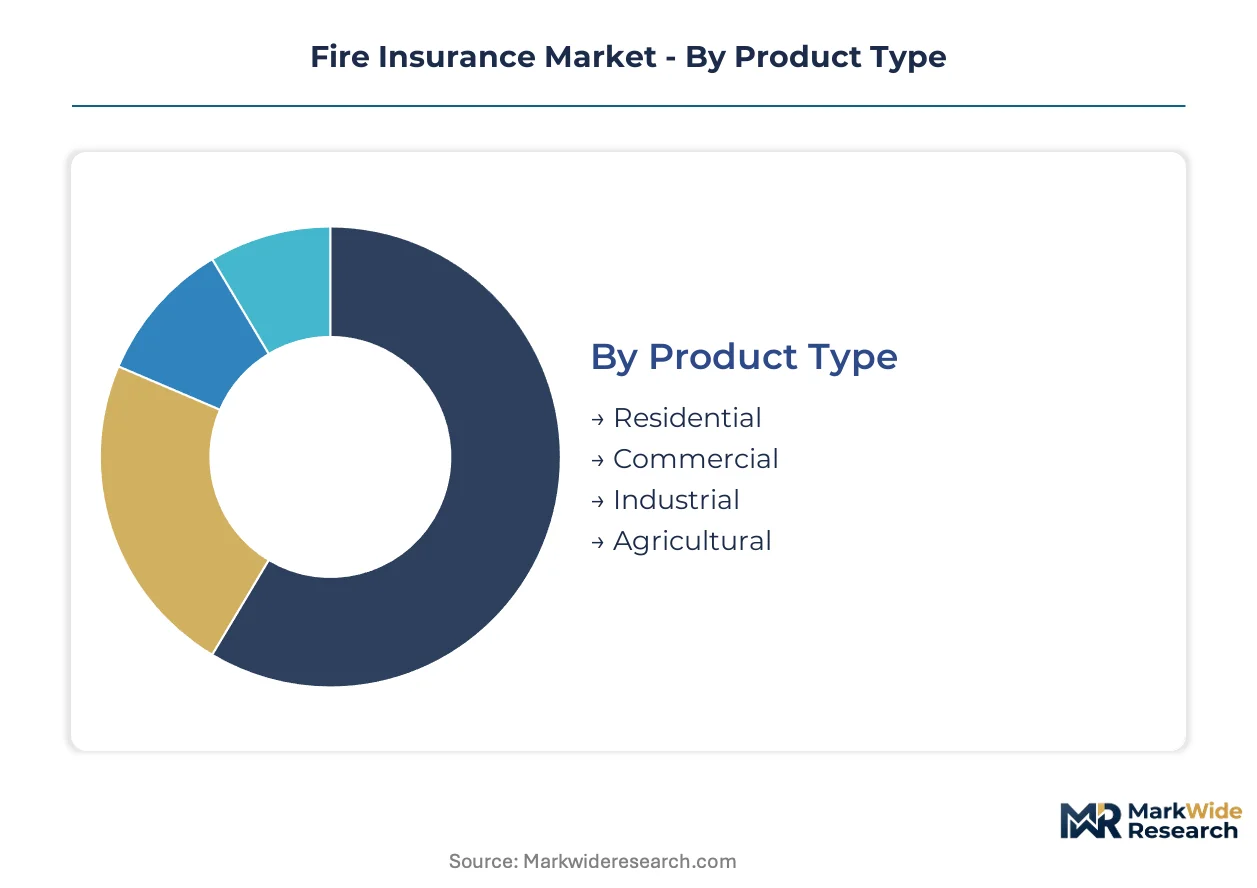
Fire insurance segmentation reflects divergent capital requirements across asset classes and policyholder sophistication. Underwriters calibrate pricing engines separately for standardized residential portfolios versus engineered commercial risks requiring loss-prevention consulting.
Product Type:
Capital intensity escalates dramatically from residential dwellings to industrial complexes with specialized hazard mitigation systems.
- Residential:Standardized dwelling coverage dominates premium volume through mass-market distribution. Demand clusters in California wildland-urban interface zones where NFPA 1144 defensible space mandates reshape underwriting criteria.
- Commercial:Multi-tenant office and retail properties require tailored business interruption riders and contingent time element coverage. Real estate investment trusts in Australia and Mediterranean Europe now procure coverage contingent on third-party fire-risk engineering assessments.
- Industrial:Manufacturing facilities with high-hazard processes command the steepest capital reserves.
- Agricultural:Crop and livestock operations in fire-prone regions face parametric displacement from satellite-triggered alternatives.
Most installed capacity flows through Commercial. Expansion is steepest in Industrial as energy infrastructure hardening mandates proliferate.
Coverage Type:
Margin profiles separate sharply between commoditized named perils and engineering-intensive all-risk structures.
- All-Risk:Comprehensive coverage indemnifies against all causes of loss except explicitly excluded perils. Large commercial real estate developers in Texas and Louisiana layer all-risk towers across multiple surplus lines carriers to secure adequate limits for petrochemical-adjacent properties.
- Named Perils:Policies specify enumerated fire, lightning, and smoke triggers without ambiguity. Standard-tier residential markets in Portugal and Greece rely predominantly on named perils as carrier capacity retreats from catastrophic exposure zones.
- Basic Coverage:Stripped-down protection for price-sensitive segments.
- Extended Coverage:Endorsements add riot, civil commotion, and explosion protection.
Pricing power concentrates in All-Risk. Named Perils is gaining share fastest as primary carriers seek clarity in loss attribution.
Policyholder Type:
Risk selection discipline varies enormously between individual consumers and institutional buyers with dedicated risk management functions.
- Businesses:Corporate risk managers negotiate manuscript policy forms with loss-adjustment protocols and claims-handling stipulations. Multinational manufacturers with operations spanning California, Australia, and Spain demand portfolio-level coverage structures with consistent deductibles across jurisdictions.
- Individuals:Homeowners purchase through agent networks and direct-to-consumer platforms with limited customization. First-time buyers in Colorado's Front Range face mandatory wildfire risk disclosures that delay binding.
- Non-Profits:Museums and cultural institutions require fine arts riders.
- Government Entities:Municipal infrastructure carries sovereign immunity complications.
Submission volume peaks with Businesses. Individuals is expanding most quickly as climate disclosure mandates reach retail mortgage markets.
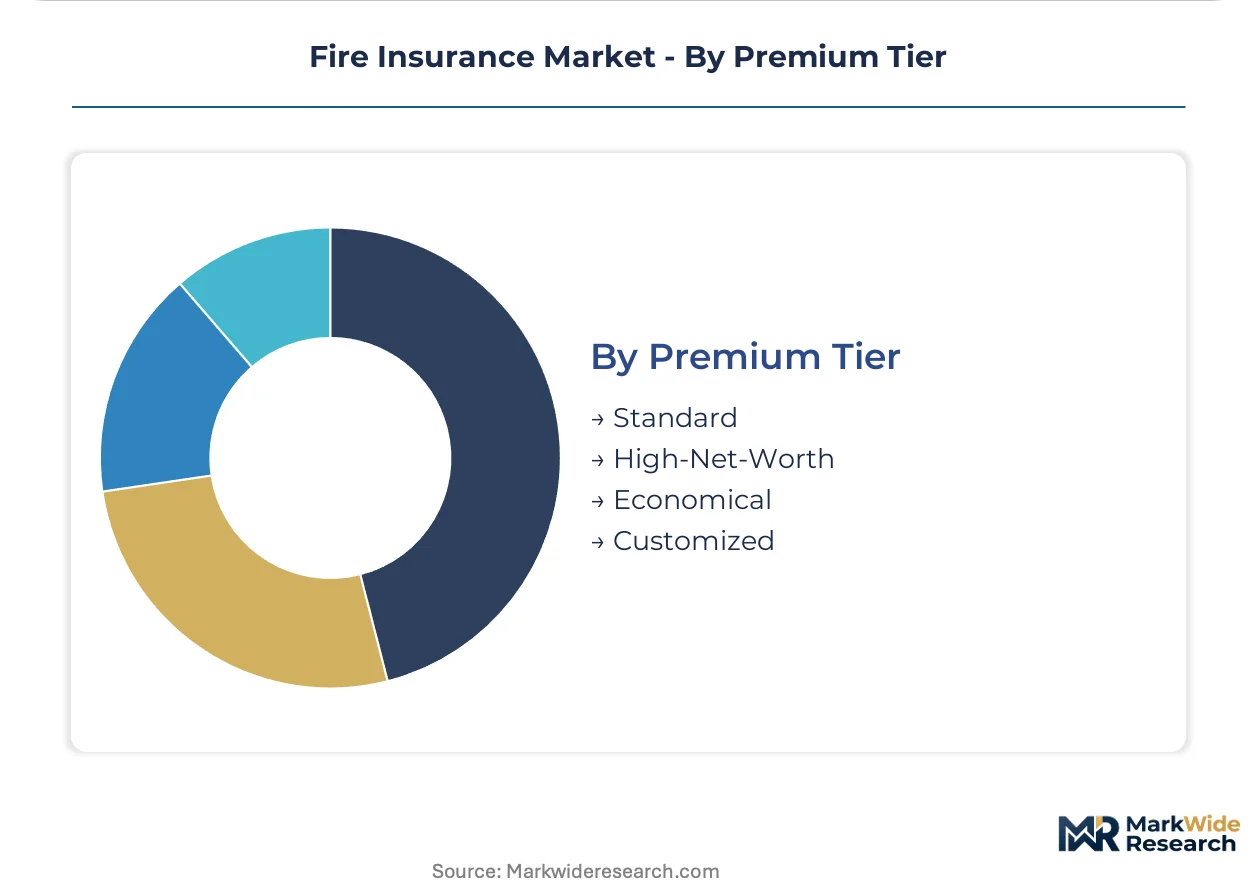
Premium Tier:
Customer lifetime value stratifies across four distinct service intensity levels.
- High-Net-Worth:Customized policies bundle guaranteed replacement cost valuation, loss-prevention engineering, and concierge claims service. Family offices in California and New York procure coverage through specialty brokers with direct carrier relationships bypassing standard distribution.
- Customized:Mid-market commercial accounts negotiate manuscript endorsements for unique exposures. Regional supermarket chains with extensive refrigerated warehousing in Texas require specialized smoke damage protocols.
- Standard:ISO forms dominate admitted market distribution.
- Economical:Minimal coverage satisfies lender requirements.
Revenue per policyholder peaks in High-Net-Worth. Customized is climbing the fastest as middle-market commercial buyers professionalize procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's wildland-urban interface zones command disproportionate underwriting attention as catastrophic fire losses force capacity recalibration across primary carriers and reinsurance markets.
United States
Commercial real estate developers in Texas and Louisiana embed NFPA 1300 compliance into project financing structures. The Inflation Reduction Act channels federal tax incentives toward fire-resistant construction materials. Petrochemical corridor facilities in Houston anchor demand for layered all-risk towers across multiple surplus lines carriers.
Australia
Remote sensing platforms integrating satellite thermal imaging consolidate underwriting workflows for industrial facility operators. The country's prudential regulator enforces catastrophe reserve requirements that shape capital allocation. Manufacturing clusters in Victoria and New South Wales mandate continuous fire monitoring as a condition of coverage placement.
Spain
Consecutive years of record fire losses in Mediterranean coastal provinces force traditional carriers to cede premium volume to specialty underwriters. EU CSRD disclosure mandates require granular fire risk quantification for institutional real estate portfolios. Barcelona and Madrid commercial property markets now layer coverage across five to seven carriers to secure adequate limits.
Portugal
Agricultural and forestry asset owners face displacement from traditional indemnity coverage by satellite-triggered parametric alternatives. The national insurance supervisor coordinates solvency standards that constrain pricing flexibility. Alentejo region wine producers increasingly procure coverage contingent on third-party fire-risk engineering assessments.
Greece
Island tourism infrastructure operators confront shrinking admitted market capacity as wildfire exposure intensifies across the Aegean archipelago. Standard-tier residential markets rely predominantly on named perils products as carrier retreat accelerates. Athens metropolitan area high-net-worth residential policies capture disproportionate margin pools through bundled valuation services.
Fire Insurance Market Key Industry Players
Portfolio diversification dominates the current landscape as carriers rebalance geographic exposure away from catastrophic loss corridors. The market structure concentrates among tier-one national writers with proprietary catastrophe modeling capabilities and specialty underwriters with engineering service integration. Three archetypes define competitive positioning: scale-driven reinsurance-backed primaries, high-net-worth engineering specialists, and surplus lines program administrators. M&A activity targets technology-enabled underwriting platforms, while strategic partnerships with sensor providers reshape risk selection protocols.
Among U.S.-based national writers, State Farm and Berkshire Hathaway occupy positions anchored by scale advantages in reinsurance-backed primary coverage. Chubb exemplifies the engineering-intensive archetype through specialized loss-prevention services targeting high-net-worth residential portfolios. Zurich represents the multinational program administrator model with capacity to layer coverage across multiple jurisdictions for commercial real estate developers.
| Leading Market Players |
|---|
| Liberty Mutual |
| Farmers Insurance Group |
| State Farm |
| Zurich |
| Chubb |
| Berkshire Hathaway |
| American International Group |
| USAA |
| Progressive Insurance Group |
| Others |
Cost & Logistics Intelligence
Reinsurance capacity from Bermuda and London market retrocession providers flows through primary carrier pricing tiers, with cost pass-through compressing margins in standard-tier residential products while specialty engineering-backed coverage retains pricing power.
Pricing Analysis
Input-cost pass-through from catastrophe retrocession markets drives pricing stratification across premium, standard, and economy tiers. Premium differentiation hinges on engineering service bundling and guaranteed replacement cost valuation versus commoditized ISO forms. Pricing pressure stems from state rate-approval statutes in California and similar jurisdictions that lag loss cost inflation. Standard-tier residential buyers exhibit highest price sensitivity, while high-net-worth policyholders prioritize loss-prevention consulting over premium minimization.
Supply Chain Analysis
Catastrophe modeling software supply rests on specialized vendors in the United States, United Kingdom, and Bermuda. Raw material dependencies include satellite thermal imaging data, ground-based sensor networks, and actuarial talent pools. Single-source vulnerability concentrates in proprietary simulation platforms that dominate wildfire probability engines. Distribution runs through program administrators layering coverage across multiple surplus lines carriers for commercial real estate developers in high-exposure zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fire insurance functions as a geographic-arbitrage play where carriers with Bermuda reinsurance backing capture margin in California wildfire corridors that admitted market competitors cannot access due to state rate-approval constraints.
For Market Incumbents: Hedge geographic concentration by reallocating capacity from California wildland-urban interface zones to Texas and Louisiana industrial corridors where NFPA 1300 compliance-linked coverage structures command premium pricing. State rate-approval friction in high-exposure states threatens margin sustainability; backward integration into proprietary catastrophe modeling capabilities defends pricing power against reinsurance-backed competitors. For New Entrants and Emerging Players: Enter via parametric wildfire products for agricultural and forestry assets in Portugal and Spain where traditional indemnity coverage is retreating. Mediterranean Europe's record fire losses have ceded premium volume to specialty underwriters with engineering capabilities. Satellite-triggered policy deployment through agribroker networks offers the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for technology-enabled underwriting platforms because legacy policy administration systems cannot embed real-time IoT fire detection data, creating acquisition demand for modern core systems. The five-to-ten-year viability window favors targets with sensor-provider partnerships and surplus lines program administrator licenses across multiple state jurisdictions. Watch for inflection when SEC climate disclosure mandates expand to retail mortgage markets.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Catastrophe Modeling Investment | State Farm leverages internal simulation platforms to sustain pricing power in wildfire-exposed states. |
| Loss-Prevention Engineering Service Expansion | Chubb anchors high-net-worth residential portfolios through specialized risk mitigation consulting. |
| Surplus Lines Program Administrator Acquisition | Zurich layers coverage across multiple jurisdictions for commercial real estate developers. |
| Sensor-Provider Strategic Partnership | Remote sensing platforms consolidate underwriting workflows for California industrial facility operators. |
| Parametric Product Line Launch | Satellite-triggered wildfire policies displace traditional indemnity coverage for agricultural assets. |
Research Approach
Direct dialogue with underwriting executives, catastrophe modelers, state insurance regulators, and commercial real estate risk managers grounded qualitative findings in operational reality. Secondary validation drew from NAIC catastrophe reserve filings, SEC climate disclosure rulemakings, ISO standardized policy form updates, and EIOPA insurance supervision reports. Bottom-up premium volume estimates triangulated against top-down market size benchmarks.
Segmented outputs across product type, coverage structure, policyholder sophistication, and premium tier informed the analytical framework over the projection horizon. CAGRs derived from loss cost trend analysis, capacity deployment patterns, and regulatory rate-approval cycle dynamics. Wildfire probability engine adoption curves and parametric displacement rates served as industry-specific forecast inputs.
The model holds under stable climate loss trends and current state regulatory frameworks; deviation in federal climate resilience funding levels or reinsurance market hardening would shift capacity allocation assumptions. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
France Car Insurance Market
Insurance
Medical Professional Liability Insurance Market
Insurance
Japan Liability Insurance Market
Insurance
Germany Travel Insurance Market
Insurance
Europe Embedded Insurance Market
Insurance
Middle East Business Income Insurance Market
Insurance
Credit Insurance Market
Insurance
Global Sports Insurance Market
Insurance
India Parametric Insurance Market
Insurance
United States Insurance Brokerage Market
Insurance
Financial Protection Market
Insurance
Saudi Arabia Health Insurance Market
Insurance
Asia-Pacific Critical Illness Insurance Market
Insurance
Group Health Insurance Market
Insurance
General Insurance Market
Insurance
Peru Insurance Market