
 Compulsory Third Party (CTP) Insurance Market | 2026-2036
Compulsory Third Party (CTP) Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Compulsory Third Party (CTP) Insurance Market Analysis
Commercial vehicle fleet coverage is hardening as logistics operators face elevated liability exposure across interstate corridors. State Farm anchors its position through captive agency distribution in high-volume U.S. states. Progressive differentiates via telematics-integrated pricing models that reward low-risk commercial drivers. Chubb specializes in high-limit excess layers for corporate fleet accounts with complex multi-jurisdictional operations.
Compulsory Third Party (CTP) insurance constitutes a statutorily mandated liability contract covering bodily injury to third parties arising from motor vehicle accidents, with premium calculations tied to actuarial risk pools and claims history databases. Its primary commercial purpose is to guarantee compensation availability for accident victims regardless of at-fault driver solvency. Standard CTP policies occupy the mature core of the market with thin margins and high regulatory scrutiny, while Enhanced CTP variants with income-replacement riders capture expanding margin pools. Passenger Vehicles dominate premium volume but face saturation, whereas Commercial Vehicles and Buses generate faster growth through fleet consolidation and rising medical cost inflation.
The U.S. National Association of Insurance Commissioners coordinates state-level reserve adequacy standards that directly shape pricing floors and market entry conditions. Australia's state-based CTP regulators and China's SAMR jointly enforce mandatory coverage verification through digital registration linkages that prevent uninsured vehicle operation. Stakeholders must monitor how real-time claims data sharing between insurers and transport authorities redefines risk segmentation and portfolio construction.
Market Dynamics
Telematics-enabled usage-based pricing is compressing traditional risk-pooling models as insurers gain real-time visibility into driver behavior, forcing legacy actuarial frameworks to recalibrate around continuous data streams rather than historical claims aggregates.
Growth Catalysts
- Commercial fleet electrification mandates:The US NHTSA and EU Green Deal emission targets are expanding insured vehicle pools as operators replace diesel fleets with electric commercial vehicles requiring recalibrated liability coverage.
- China's SAMR digital registration enforcement:Mandatory coverage verification through real-time registration linkages eliminates uninsured vehicle operation and locks in premium collection at point of vehicle licensing.
- Medical cost inflation indexing:Australia's state-based CTP regulators are automatically adjusting benefit caps to healthcare inflation, preserving real claim values and preventing premium erosion from nominal fixed limits.
Market Restraints
- Actuarial data asymmetry:Insurers face adverse selection as high-risk commercial operators migrate to minimum-coverage state pools while low-risk fleets self-insure through captive arrangements.
- Reinsurance capacity concentration:Catastrophic bodily injury claims in single-vehicle mass-casualty events exhaust primary layers, forcing dependence on London and Bermuda markets for excess-of-loss treaty renewals.
- Legacy IT integration costs:Core policy administration systems built on 1990s mainframe architectures require multimillion-dollar replacement to interface with telematics APIs and real-time pricing engines.
Strategic Opportunities
- India's uninsured motorist gap:Mandatory third-party coverage enforcement remains patchy outside tier-1 cities, creating white-space penetration potential as the country's IRDAI tightens registration-linked compliance.
- Gig economy driver classification:Food delivery and ride-hail platforms operate in coverage gray zones between personal and commercial use, opening product innovation space for hybrid CTP endorsements.
- Parametric injury benefit triggers:Blockchain-verified accident data from connected vehicles enables instant payout protocols, reducing claims administration overhead and litigation reserves.
Industry Challenges
- Predictive modeling talent scarcity:CTP insurers compete with fintech and health insurance sectors for data scientists capable of building telematics-driven pricing algorithms from raw sensor feeds.
- Cross-border fleet jurisdiction complexity:Corporate accounts operating across multiple state or national regulatory regimes require legal teams to reconcile conflicting mandatory benefit structures and claims procedures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compulsory Third Party (CTP) Insurance Market |
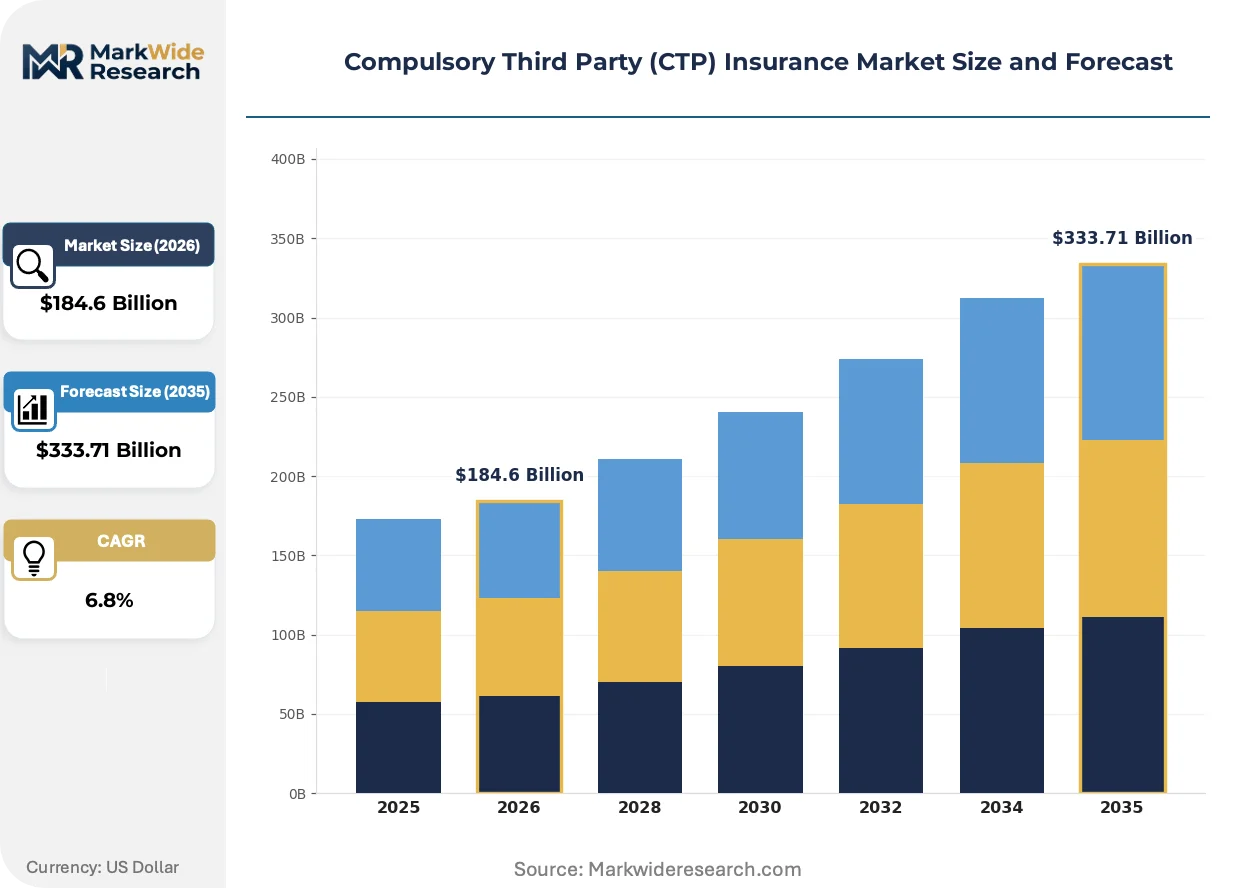
| Market Size in 2026 | $184.6 Billion |
| Market Size in 2035 | $333.71 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Standard CTP, Enhanced CTP, Lifetime Care, Basic CTP Vehicle Type: Passenger Vehicles, Commercial Vehicles, Motorcycles, Buses Distribution Channel: Online, Brokers, Direct Sales, Agents Claim Process: Standard Claims, Fast Track Claims, Complex Claims, Minor Claims |
| Companies Covered | Allstate, Travelers, State Farm, Chubb, USAA, Progressive, Liberty Mutual, Nationwide, Berkshire Hathaway, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compulsory Third Party (CTP) Insurance Market Emerging Trajectories
Real-time data ingestion from vehicle sensors and mobile devices is dismantling the traditional annual policy renewal cycle, replacing static premium bands with dynamic pricing that fluctuates with actual exposure.
Telematics-integrated CTP underwriting is rewriting how insurers segment risk pools. Continuous monitoring of acceleration, braking, and mileage patterns allows granular driver scoring that separates safe commercial operators from high-exposure accounts. Major fleet managers in Australia and Germany are piloting these programs, accepting privacy trade-offs for premium reductions of fifteen to twenty-five percent. The structural compression of cross-subsidization between risk tiers is forcing mid-market insurers to specialize or exit standard coverage lines entirely.
The EU AI Act's risk classification framework for automated decision-making directly constrains how insurers deploy algorithmic pricing models in member states. Systems affecting fundamental rights—including access to essential insurance—must meet transparency and human-oversight standards. CTP providers operating across Germany, France, and Italy are restructuring their actuarial workflows to document model logic and maintain appeal pathways, increasing compliance overhead but reducing litigation exposure from discriminatory pricing challenges.
Fleet procurement departments are consolidating insurance purchasing through captive brokers and direct insurer relationships, bypassing traditional independent agency channels that dominated personal lines distribution. Large logistics operators in the United States and Brazil now negotiate multi-year master policies covering thousands of vehicles across state boundaries, extracting volume discounts and customized claims handling protocols. This concentration of buying power squeezes commission structures and favors insurers with dedicated national account service infrastructure over regional carriers.
Compulsory Third Party (CTP) Insurance Market Segmentation
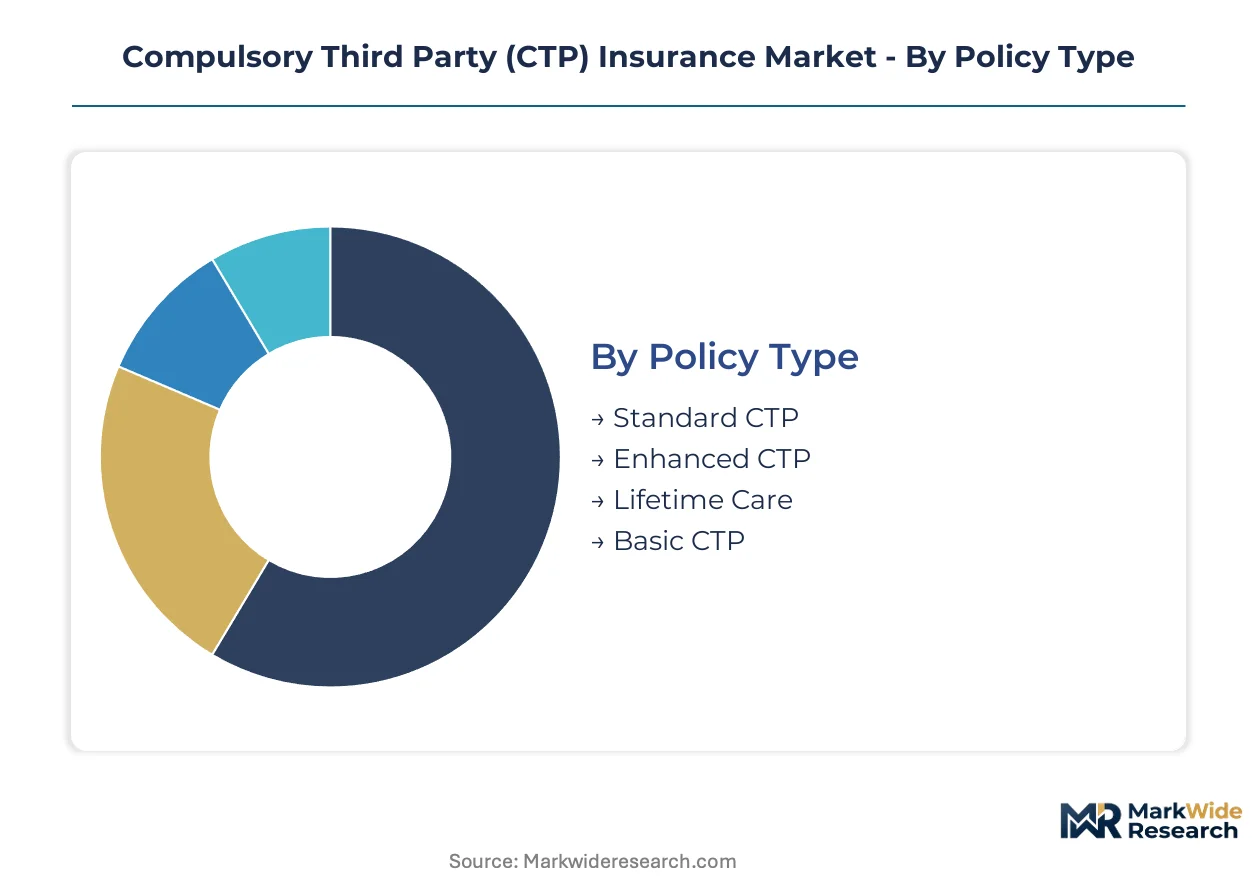
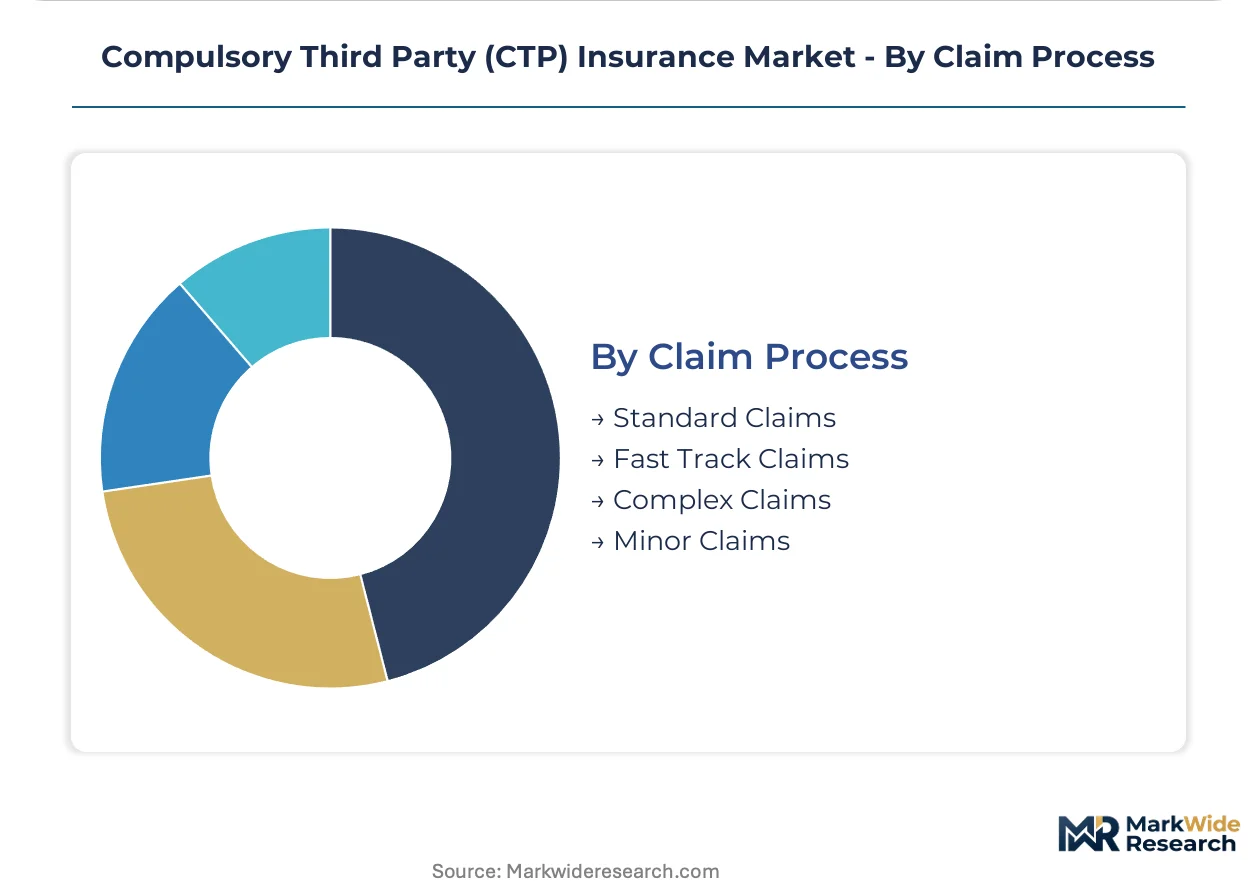
CTP insurance segmentation reflects divergent regulatory treatment across vehicle classes and claim severity tiers. Insurers calibrate capital reserves and pricing models differently for each segment based on mandated benefit floors and claims administration complexity.
Policy Type:
Regulatory certification intensity varies sharply across policy tiers, with lifetime care products requiring actuarial sign-off from multiple state-appointed medical assessors.
- Standard CTP:Statutorily mandated minimum coverage satisfying baseline bodily injury liability requirements. Australia's state-based regulators and Germany's KBA enforce uniform benefit structures that compress underwriting margins and prioritize claims-paying capacity over product differentiation.
- Enhanced CTP:Optional income-replacement riders and extended rehabilitation benefits attach to core statutory coverage. Fleet operators in Brazil and corporate accounts across China's tier-1 cities drive uptake as medical cost inflation erodes real value of fixed statutory benefits.
- Lifetime Care:Catastrophic injury provision covering indefinite medical and attendant care for severe spinal or brain trauma. Australia's lifetime care schemes in New South Wales and Victoria require dedicated premium pools segregated from standard claim reserves.
- Basic CTP:Stripped-down coverage meeting only absolute legal minimums, common in emerging markets with weak enforcement infrastructure.
Leading the category by volume: Standard CTP. Growing fastest: Enhanced CTP.
Vehicle Type:
Risk-weighted premium differentials widen as commercial vehicle kilometers traveled generate disproportionate claim frequency relative to personal automobile exposure.
- Passenger Vehicles:Saturated core segment with mature penetration rates exceeding ninety percent in mandatory jurisdictions. Australia's state-based schemes and Germany's KBA-linked registration systems enforce coverage verification at point of title transfer.
- Commercial Vehicles:Fleet consolidation and interstate logistics expansion concentrate demand among large operators seeking multi-jurisdictional master policies. Brazil's ANTT freight regulations and US NHTSA commercial safety mandates tighten liability frameworks for heavy goods vehicles.
- Motorcycles:Elevated injury severity per accident drives higher statutory premiums in most jurisdictions. Thailand's road safety bureau and Italy's Ministry of Transport impose specific two-wheeler coverage minimums above standard automobile requirements.
- Buses:Mass-casualty exposure from single-vehicle incidents necessitates excess-of-loss reinsurance treaties. China's SAMR mandates real-time coverage verification for commercial passenger transport operators through digital registration linkages.
Dominating premium volume: Passenger Vehicles. Expanding most quickly: Commercial Vehicles.
Distribution Channel:
Channel economics shift as fleet procurement departments bypass traditional intermediaries for direct insurer negotiations.
- Online:Digital policy issuance and claims notification platforms reduce acquisition costs. India's IRDAI mandates API integration between insurer systems and regional transport authority databases for real-time coverage verification.
- Brokers:Retain relevance for complex multi-jurisdictional fleet placements requiring specialized placement expertise. Large logistics operators in the United States and Brazil leverage broker relationships for customized claims handling protocols.
- Direct Sales:Insurer-owned channels capture personal lines volume through price comparison integration. Australia's state-based CTP schemes increasingly direct consumers to official portals for policy selection.
- Agents:Captive distribution networks dominate in high-volume US states where State Farm and similar carriers maintain exclusive representation agreements.
Capturing greatest transaction volume: Online. Sustaining highest margin per policy: Brokers.
Claim Process:
Administrative cost structures diverge based on medical complexity assessment requirements and legal representation patterns.
- Standard Claims:Moderate injury severity requiring independent medical examination and statutory benefit calculation. Australia's state-based CTP regulators mandate standardized impairment assessment protocols to reduce litigation variance.
- Fast Track Claims:Low-severity protocols bypassing full adversarial assessment for claims below monetary thresholds. Germany's KBA-aligned insurers and UK Motor Insurers' Bureau pilot automated settlement for whiplash-dominated minor injury categories.
- Complex Claims:Multi-trauma or disputed liability matters requiring specialized claims units and legal panel coordination. Lifetime care projections and future economic loss calculations demand actuarial and medical expert testimony.
- Minor Claims:First-party notification and rapid settlement without formal dispute resolution. China's SAMR encourages digital claims submission through mobile platforms linked to traffic accident documentation systems.
Processing greatest claim volume: Standard Claims. Steepest expansion trajectory: Fast Track Claims.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's state-based CTP schemes operate as natural laboratories for coverage innovation, with New South Wales and Victoria hosting lifetime care pilots that concentrate actuarial expertise in Sydney and Melbourne insurance clusters.
United States
Commercial fleet electrification drives coverage recalibration as logistics operators replace diesel vehicles with electric trucks requiring modified liability frameworks. The NHTSA coordinates state-level reserve adequacy standards that shape pricing floors across interstate corridors. Texas and California anchor national premium volume through high-volume captive agency networks concentrated in Dallas-Fort Worth and Los Angeles metro areas.
Germany
The KBA enforces uniform benefit structures through digital registration linkages that eliminate uninsured vehicle operation nationwide. Telematics-integrated pricing models gain traction among commercial fleet operators seeking premium reductions through continuous driver monitoring. Munich and Frankfurt host the primary insurance underwriting clusters serving multi-jurisdictional corporate accounts across the EU.
China
SAMR mandates real-time coverage verification through digital registration systems that lock in premium collection at vehicle licensing points. Tier-1 cities including Shanghai and Beijing drive Enhanced CTP uptake as medical cost inflation erodes real value of fixed statutory benefits. The Yangtze River Delta concentrates commercial fleet underwriting expertise serving logistics operators along interstate corridors.
Brazil
Freight regulations from ANTT tighten liability frameworks for heavy goods vehicles operating across state boundaries. Fleet consolidation accelerates demand for multi-year master policies covering thousands of vehicles through direct insurer negotiations. São Paulo anchors national premium volume while Rio Grande do Sul emerges as a hub for commercial vehicle telematics pilot programs.
India
IRDAI tightens registration-linked compliance mechanisms to close uninsured motorist gaps outside tier-1 cities. Patchy enforcement in secondary markets creates white-space penetration potential for digital policy issuance platforms. Maharashtra and Karnataka concentrate insurtech development clusters building API integration between insurer systems and regional transport authority databases.
Compulsory Third Party (CTP) Insurance Market Vendor Landscape
Top-tier vendors anchor the national account segment, while regional specialists occupy fragmented personal lines distribution. The market exhibits tiered concentration with scale-driven carriers commanding fleet procurement departments through direct relationships. Three archetypes dominate: captive agency networks, telematics-integrated direct writers, and high-limit excess layer specialists. Competitive moves center on M&A for digital capabilities and strategic partnerships with fleet telematics providers.
Within the captive agency archetype, State Farm exemplifies distribution concentration through exclusive representation agreements in high-volume states. Progressive represents the telematics-integrated pricing model that rewards low-risk commercial drivers with dynamic premium adjustments. Chubb occupies a position among high-limit excess layer specialists serving corporate fleet accounts with complex multi-jurisdictional operations.
| Leading Market Players |
|---|
| Allstate |
| Travelers |
| State Farm |
| Chubb |
| USAA |
| Progressive |
| Liberty Mutual |
| Nationwide |
| Berkshire Hathaway |
| Others |
Supply Flow & Price Mechanics
Medical cost inflation indices cascade through CTP insurance pricing tiers, compressing margins on standard statutory coverage while amplifying premium differentials for enhanced income-replacement riders that corporate fleet buyers in Australia and China increasingly demand.
Pricing Analysis
Short lead-time pricing premiums dominate the CTP market as fleet procurement departments negotiate multi-year master policies with customized claims handling protocols, extracting discounts unavailable to smaller operators purchasing through annual renewal cycles. Three-tier pricing structure across premium, standard, and economy levels separates enhanced lifetime care products from basic statutory minimums, with certification intensity from state-appointed medical assessors driving the premium tier. Cost compression in standard coverage is intensifying because thin regulatory-mandated margins limit pricing flexibility, while captive self-insurance arrangements among low-risk commercial fleets erode the risk pool. Mid-market logistics operators exhibit highest price sensitivity, whereas multinational corporate accounts with complex multi-jurisdictional operations prioritize claims service quality over premium minimization.
Supply Chain Analysis
Logistics and freight cost differentials across interstate corridors shape reinsurance placement economics, with catastrophic bodily injury claims requiring excess-of-loss treaty renewals through London and Bermuda markets. Capital concentration rests on Australia, Germany, and the United States as primary underwriting hubs, while claims administration labor pools concentrate in India and the Philippines for back-office processing. Dependencies on actuarial talent, medical assessment networks, and legacy IT infrastructure create structural vulnerability. Single-source vulnerability in reinsurance capacity forces primary insurers into concentrated treaty negotiations. Distribution runs through captive agency networks in high-volume US states, direct digital portals in Australia's state-based schemes, and specialized brokers for complex fleet placements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CTP insurance market sits in a technology-transition phase as telematics-enabled usage-based pricing displaces traditional annual renewal cycles and historical claims-based actuarial frameworks.
For Market Incumbents: Extend telematics data integration capabilities to defend against fintech entrants capturing low-risk commercial driver segments through real-time pricing algorithms. Deepen API infrastructure investments that interface with state transport authority registration databases, mirroring China's SAMR digital enforcement model. Lock in multi-year master policy relationships with consolidating fleet operators before regional carriers specialize or exit standard coverage lines entirely.
For New Entrants and Emerging Players: Begin with India's uninsured motorist gap outside tier-1 cities, where patchy IRDAI enforcement creates white-space for digital policy issuance platforms with API-linked registration verification. Target gig economy driver classification gray zones between personal and commercial use, developing hybrid CTP endorsements for food delivery and ride-hail platforms. Pursue parametric injury benefit triggers using blockchain-verified connected vehicle data as a differentiated go-to-market angle.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier insurers with captive agency networks in high-volume US states where legacy IT replacement costs have strained balance sheets. Long-term viability hinges on telematics integration depth and national account service infrastructure rather than regional market share concentration. Watch for inflection signals in real-time claims data sharing mandates between insurers and transport authorities, which will reshape risk segmentation economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Progressive's sensor-driven pricing models reward low-risk commercial drivers with dynamic premium adjustments. |
| Digital Registration Linkage | China's SAMR mandates real-time coverage verification that eliminates uninsured vehicle operation nationwide. |
| Excess Layer Specialization | Chubb's high-limit capacity serves corporate fleets with complex multi-jurisdictional liability exposures. |
| Lifetime Care Segregation | Australia's New South Wales and Victoria schemes require dedicated premium pools for catastrophic injury provision. |
| Parametric Claims Automation | Blockchain-verified accident data from connected vehicles enables instant payout protocols reducing litigation reserves. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combining primary interviews with insurance underwriting executives, fleet procurement managers, state regulator actuaries, and claims administration specialists with secondary validation from NAIC reserve adequacy standards, IRDAI compliance circulars, and SAMR digital enforcement protocols. Bottom-up policy volume estimates triangulated against top-down premium pool calculations derived from vehicle registration databases and mandatory coverage verification systems.
Granularity-level modeling segmented the CTP market by policy type, vehicle class, distribution channel, and claim severity tier, with regional regulatory clusters treated as distinct forecasting units. CAGRs were derived from trajectory analysis across the projection horizon, incorporating medical cost inflation indexing, fleet electrification penetration curves, and telematics adoption rates as industry-specific forecast inputs.
Underlying measurement precision varies by segment; passenger vehicle coverage in mature mandatory jurisdictions carries tighter precision than emerging market penetration estimates. Forecasts reflect assumptions about enforcement tightening timelines and technology adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Asia-Pacific AI in Insurance Market
Insurance
Global Livestock Insurance Market
Insurance
Marine Cargo Insurance Market
Insurance
India Electronic Gadget Insurance Market
Insurance
France Car Insurance Market
Insurance
Financial Protection Market
Insurance
Drone Insurance Market
Insurance
South Africa Property and Casualty Insurance Market
Insurance
Australia Parametric Insurance Market
Insurance
Reinsurance Carriers Market
Insurance
Digital Innovation in Insurance Market
Insurance
Microinsurance Market
Insurance
Property and Casualty Insurance Market
Insurance
Solar Panel Warranty Insurance Market
Insurance
Germany Property and Casualty Insurance Market
Insurance
Europe Bancassurance Market