
 United States Bancassurance Market | 2026-2036
United States Bancassurance Market Size, Share, and Industry Trends Forecast 2026-2036
United States Bancassurance Market Intelligence
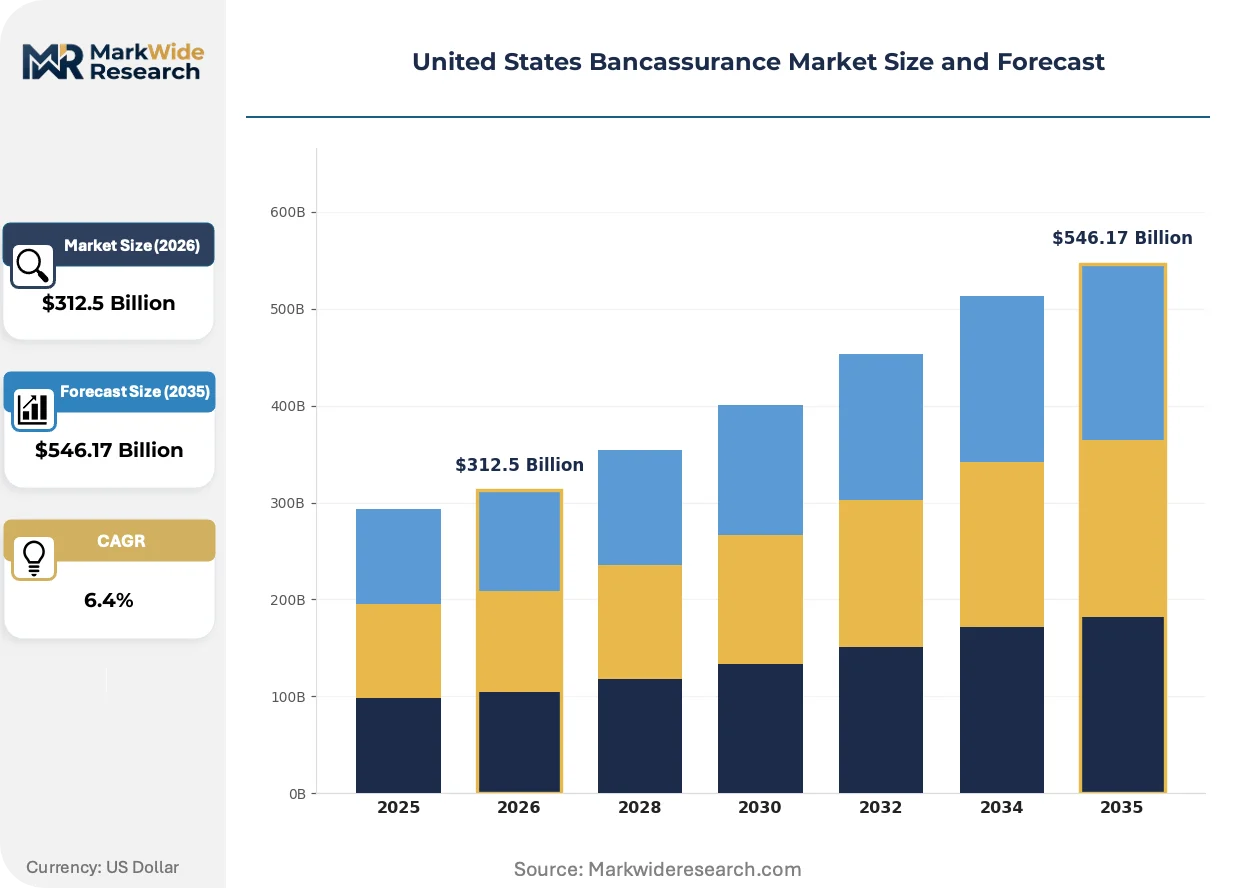
The SEC's Regulation Best Interest is pivoting how banks structure insurance sales compensation and disclosure protocols across branch networks. Wells Fargo and Co. leverages its extensive retail footprint to embed life insurance referrals within mortgage and wealth management conversations. Metlife Inc. anchors the product supply side through proprietary term and universal life offerings distributed via exclusive bank partnerships. Citigroup Inc. competes on digital integration, routing insurance quotes through its mobile banking interface to capture younger demographics.
Bancassurance denotes the distribution of insurance products through banking channels, combining deposit-taking infrastructure with underwriting access via contractual agency or joint venture arrangements. The model relies on customer data analytics, branch staff licensing, and regulatory compliance architecture to convert transactional banking relationships into recurring premium flows. Life insurance dominates product mix due to longer policy durations and higher commission structures that align with bank revenue targets. Retail banking remains the primary distribution channel, though mobile banking is accelerating fastest as smartphone-native consumers bypass physical branches for term life and simplified issue products.
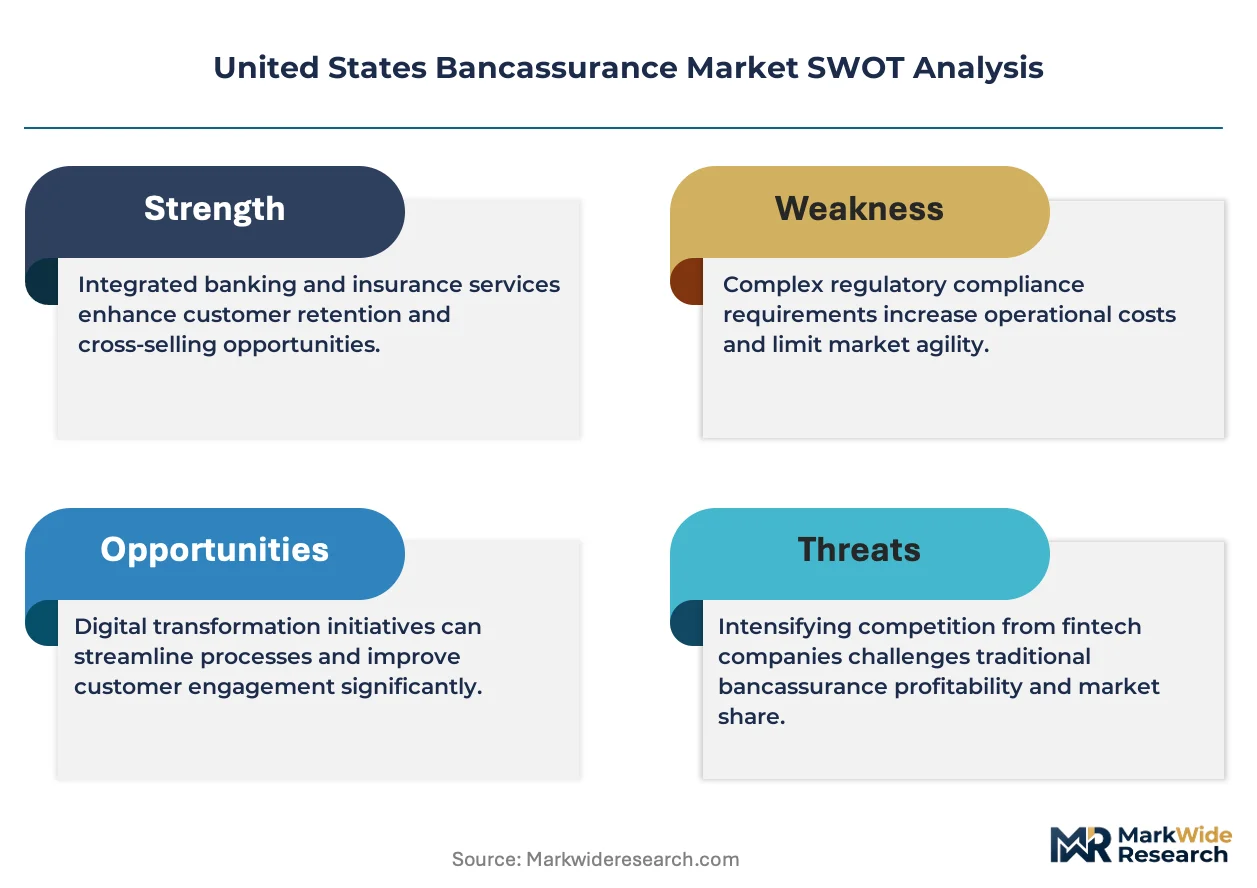
The SEC, state insurance commissioners, and FINRA collectively govern bancassurance conduct standards, licensing requirements, and suitability obligations across the United States. These frameworks elevate compliance costs but also create barriers that favor incumbent banks with established legal infrastructure over fintech entrants. Stakeholders must monitor evolving fiduciary interpretations and state-level insurance licensing reciprocity as determinants of scalable distribution economics.
Market Dynamics
SEC Regulation Best Interest is compressing commission structures across bank branch networks while accelerating fee-based advisory models that reshape how insurance products reach mass-affluent households.
Growth Catalysts
- Demographic tailwinds in Sun Belt states:Texas and Florida exhibit aging population clusters with above-average bank branch density, creating favorable unit economics for life insurance distribution through existing deposit relationships.
- Mobile banking penetration:Smartphone-native consumers bypass physical branches for simplified issue term products, expanding addressable reach beyond traditional geographic constraints.
- Fiduciary standard harmonization:The SEC's Regulation Best Interest elevates disclosure protocols that build consumer trust in bank-sold insurance relative to independent agent channels.
Market Restraints
- Compliance cost escalation:FINRA licensing requirements and state-level insurance commissioner examinations impose fixed costs that burden smaller regional bank networks disproportionately.
- Interest rate sensitivity:Universal life product profitability compresses when fixed-income yields fail to support illustrated crediting rates, constraining bank willingness to promote cash-value products.
- Agency channel competition:Independent producers retain advisory relationships in complex estate planning scenarios where bank staff licensing limits prevent sophisticated policy structuring.
Strategic Opportunities
- Embedded insurance APIs:Real-time underwriting integration with core banking platforms enables instant term life quotes during mortgage origination workflows.
- Retirement income gap solutions:Mass-affluent households aged 55-70 seek guaranteed lifetime income riders that banks can attach to existing annuity relationships.
- Data monetization partnerships:Transactional spending patterns and deposit flow analytics enable predictive life event targeting for insurance cross-sell.
Industry Challenges
- Branch staff licensing bottlenecks:State insurance producer examinations create 90-120 day onboarding delays that throttle product rollout velocity across regional networks.
- Legacy core system integration:Policy administration data feeds from carrier systems into bank CRM platforms require expensive middleware development for seamless customer experience.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Bancassurance Market |
| Market Size in 2026 | $312.5 Billion |
| Market Size in 2035 | $546.17 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Life Insurance, Health Insurance, Property Insurance, Casualty Insurance Distribution Channel: Retail Banking, Online Banking, Financial Advisors, Mobile Banking Customer Type: Individual Clients, Small Businesses, Corporates, Non-profits Service Type: Advisory Services, Sales Support, Claims Processing, Marketing Services |
| Companies Covered | Metlife Inc., Barclays Bank Plc, Wells Fargo and Co., ING Groep NV, Lloyds Banking Group Plc, Citigroup Inc., HSBC Holdings Plc, CNA Financial Corp., American Express Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Bancassurance Market Strategic Shifts & Innovations
Digital distribution infrastructure is displacing branch-centric sales models while regulatory technology investments automate suitability documentation and compliance surveillance across bank networks.
Application programming interface architecture is electrifying policy issuance by embedding real-time underwriting decisions within mobile banking workflows. Millennials and Gen Z account holders initiate term life quotes without human intervention, compressing the traditional 14-day sales cycle into minutes. This velocity is electrifying customer acquisition economics for banks that previously abandoned insurance cross-sell due to friction costs.
The SEC's Regulation Best Interest standard mandates enhanced documentation of customer-specific reasons for insurance recommendations. Banks must now maintain searchable digital records of risk tolerance assessments and product comparisons. Wealth management divisions within national banks absorb the heaviest compliance burden, redirecting technology budgets toward surveillance software that flags potentially unsuitable sales patterns.
Self-directed insurance research is fragmenting the traditional branch referral model. Mass-affluent consumers arrive at banking appointments with carrier comparisons sourced through aggregator platforms, diminishing the informational advantage historically held by licensed branch staff. This behavioral shift concentrates in metropolitan markets with high digital literacy, where banks compete by integrating third-party rating data directly into their proprietary interfaces.
United States Bancassurance Market Segmentation
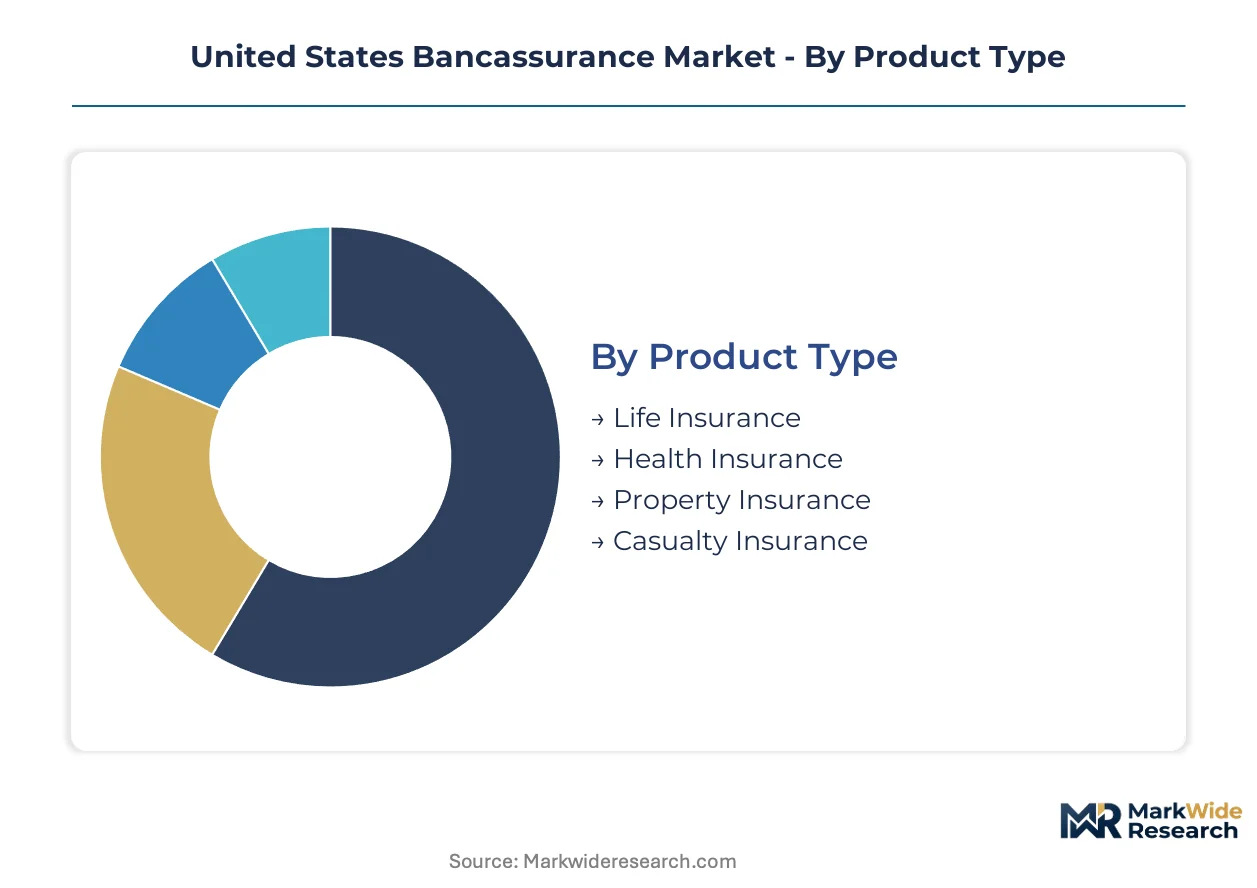
Bancassurance segmentation reveals how product design, channel economics, and customer archetypes intersect to determine profitability. Banks must align underwriting partnerships with specific client life stages and transaction behaviors to convert deposit relationships into premium flows.
Product Type:
Product selection hinges on policy duration and commission structure alignment with bank revenue targets.
- Life Insurance:Term, universal, and whole life policies dominate bancassurance portfolios due to multi-year premium commitments and higher embedded commissions. Demand concentrates among mass-affluent households in Texas and Florida, where aging demographics and bank branch density create favorable distribution economics.
- Health Insurance:Supplemental Medicare Advantage and dental coverage products attach to existing banking relationships for retirees. Regulatory complexity under state insurance commissioner oversight limits bank staff participation, pushing distribution toward licensed financial advisors rather than branch tellers.
- Property Insurance:Homeowners and renters coverage products integrate with mortgage origination workflows, enabling real-time quote generation during loan closing.
- Casualty Insurance:Auto and umbrella liability policies leverage credit scoring data for risk-based pricing, though direct writer competition compresses margins.
Life Insurance leads on scale; Health Insurance leads on momentum.
Distribution Channel:
Channel strategy determines customer acquisition cost and regulatory compliance burden.
- Retail Banking:Physical branch networks remain the primary conversion point for complex cash-value life products requiring face-to-face explanation. Wells Fargo and regional banks deploy licensed platform staff to embed insurance referrals within deposit account openings and mortgage discussions.
- Mobile Banking:Smartphone-native consumers initiate simplified issue term life quotes through integrated app interfaces, bypassing traditional 14-day sales cycles. Citigroup and digital-first competitors capture younger demographics through real-time underwriting APIs embedded in mobile workflows.
- Online Banking:Web-based portals support self-directed research and policy comparison, though conversion rates lag mobile for impulse purchases.
- Financial Advisors:Licensed advisors within wealth management divisions handle sophisticated estate planning scenarios where bank staff licensing limits prevent complex policy structuring.
Retail Banking retains volume dominance; Mobile Banking climbs the fastest.
Customer Type:
Customer archetype dictates product complexity and relationship depth requirements.
- Individual Clients:Mass-affluent households aged 55-70 drive demand for retirement income solutions and guaranteed lifetime income riders. Transactional deposit data enables predictive life event targeting for insurance cross-sell.
- Small Businesses:Owner-operators seek key person coverage and buy-sell agreement funding through existing commercial banking relationships.
- Corporates:Mid-market employers access group life and voluntary benefits through treasury management partnerships, though scale requirements favor national carriers.
- Non-profits:Religious and charitable organizations pursue executive benefit plans and charitable gift annuities, representing a niche segment with specialized fiduciary requirements.
Individual Clients anchor premium volume; Small Businesses gain share fastest.
Service Type:
Service configuration determines ongoing revenue recognition and customer retention economics.
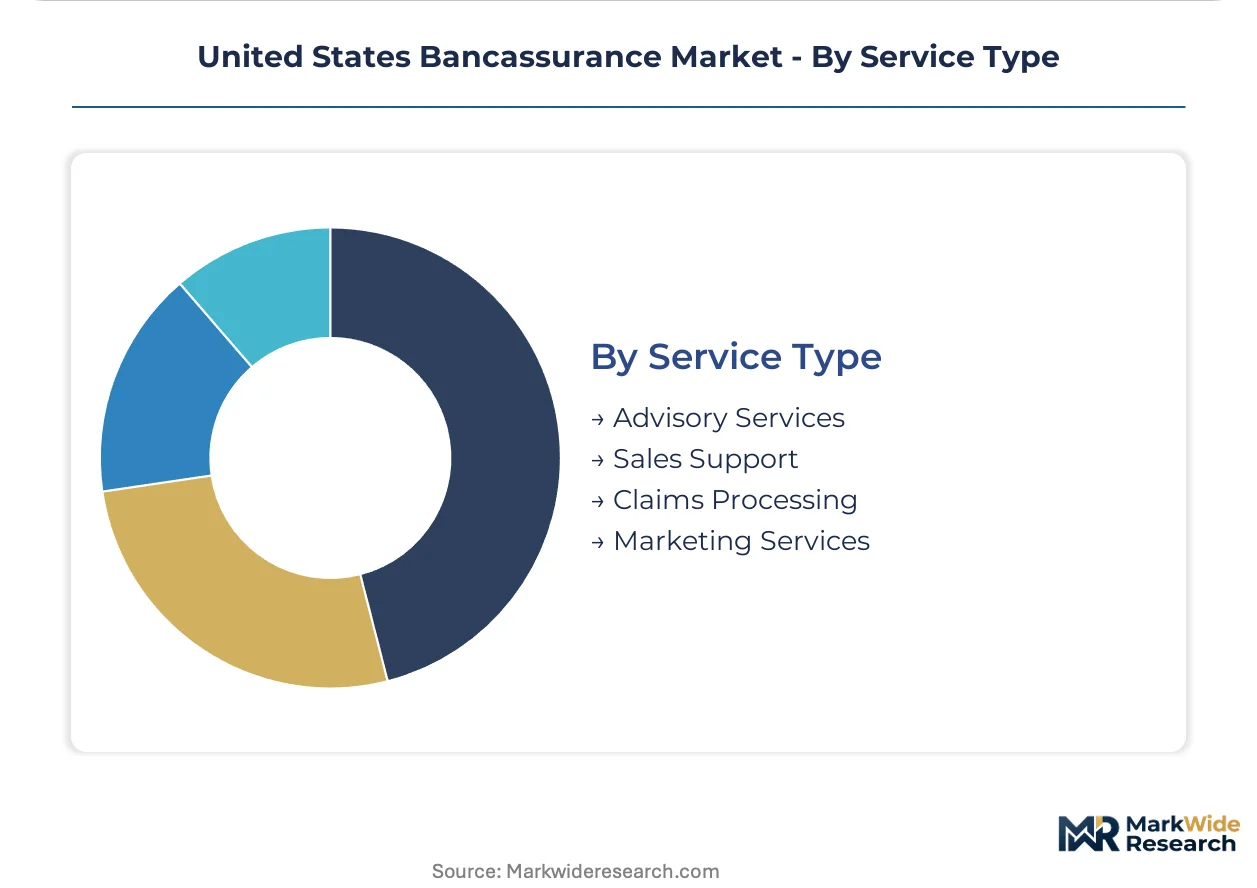
- Advisory Services:Fee-based financial planning integrates insurance recommendations within comprehensive wealth management relationships. SEC Regulation Best Interest elevates documentation requirements for suitability assessments.
- Sales Support:Branch staff training and licensing infrastructure enables product rollout across regional networks, though 90-120 day onboarding delays throttle velocity.
- Claims Processing:Carrier-administered claims handling preserves bank reputation while outsourcing operational complexity.
- Marketing Services:Co-branded campaigns and data analytics partnerships leverage transactional spending patterns for predictive targeting.
Advisory Services commands premium pricing; Sales Support scales most broadly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bancassurance first achieved scale in the United States during the 1990s when Glass-Steagall restrictions eroded and banks acquired insurance agency networks. State-level regulatory variation shaped early geographic concentration. Today's distribution economics favor regions combining aging demographics with dense branch infrastructure.
Texas
Mass-affluent households in Dallas-Fort Worth and Houston drive demand for retirement income products and universal life policies. The Texas Department of Insurance maintains producer licensing reciprocity with most states, reducing onboarding friction for regional bank networks expanding insurance staff. San Antonio anchors a cluster of military-focused financial institutions cross-selling simplified issue products to veteran depositors.
Florida
Retiree migration from the Northeast concentrates premium demand in Tampa Bay and Southwest Florida corridors. The state's Office of Insurance Regulation enforces stringent continuing education requirements that elevate staff qualification costs for community banks. Miami-Dade presents distinct unit economics, with Spanish-language product distribution capturing Caribbean and Latin American household wealth.
California
Technology sector wealth creation in Silicon Valley and San Francisco generates demand for sophisticated estate planning solutions beyond typical bank staff licensing limits. The California Department of Insurance scrutinizes bank-sold annuity suitability under heightened fiduciary interpretations. Los Angeles County maintains branch density sufficient for face-to-face sales of complex cash-value products.
New York
Metropolitan New York's concentration of financial advisors within bank wealth management divisions handles policy structuring that branch staff cannot execute. The New York State Department of Financial Services imposes advertising review requirements that delay product rollout timelines. Upstate regional banks compete through exclusive carrier partnerships rather than proprietary product development.
Illinois
Chicago's commercial banking relationships generate small business key person coverage and buy-sell agreement funding demand. The Illinois Department of Insurance participates in national producer database harmonization, streamlining multi-state licensing for bank employees. Downstate community banks leverage agricultural lending relationships to distribute crop insurance alongside traditional life products.
United States Bancassurance Market Key Industry Players
Capital-heavy national banks with extensive branch footprints compete with asset-light digital platforms for insurance distribution partnerships. The market structure concentrates around three archetypes: full-service money centers integrating insurance within wealth management divisions, regional banks relying on exclusive carrier relationships, and digital-first competitors routing quotes through mobile interfaces. Consolidation pressure intensifies as compliance costs from SEC Regulation Best Interest and state licensing requirements burden smaller networks. Strategic moves center on API-based underwriting integration and fee-based advisory model conversion away from traditional commission structures.
Among the full-service money center archetype, Wells Fargo and Co. and Citigroup Inc. occupy positions defined by retail footprint scale and digital integration capability respectively. Metlife Inc. anchors the product supply side as a carrier archetype distributing proprietary term and universal life through exclusive bank partnerships. These three entities exemplify how bancassurance competition separates distribution infrastructure owners from underwriting specialists, with hybrid models emerging at the intersection.
| Leading Market Players |
|---|
| Metlife Inc. |
| Barclays Bank Plc |
| Wells Fargo and Co. |
| ING Groep NV |
| Lloyds Banking Group Plc |
| Citigroup Inc. |
| HSBC Holdings Plc |
| CNA Financial Corp. |
| American Express Co. |
| Others |
Cost & Logistics Intelligence
Mass-affluent households aged 55-70 concentrate premium demand for guaranteed lifetime income riders and universal life policies, anchoring a commission-based pricing model that rewards multi-year policy commitments and face-to-face advisory depth. This buyer concentration reinforces tiered compensation structures across bank branch networks, where licensed platform staff capture higher payouts for complex cash-value products than simplified issue term offerings.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates bespoke estate planning solutions from mass-market term life and no-frills simplified issue products. Price differentiation hinges on policy customization depth and advisor certification tier, with FINRA-licensed wealth management advisors commanding premium placement fees unavailable to branch tellers. Pricing pressure stems from SEC Regulation Best Interest compressing traditional commission loads, accelerating fee-based advisory conversion. Small regional banks exhibit acute price sensitivity due to fixed compliance cost burdens, while national money centers absorb margin compression through scale economies.
Supply Chain Analysis
Underwriting capacity rests on exclusive carrier partnerships with MetLife and proprietary product developers, while technology infrastructure draws from API specialists and legacy core system integrators. Raw material dependencies include actuarial data services, compliance surveillance software, and mobile banking platform architecture. Single-source vulnerability concentrates in carrier-administered policy administration systems that require expensive middleware for bank CRM integration. Distribution runs through hybrid branch-digital channels, with retail banking retaining volume dominance and mobile banking climbing fastest among smartphone-native demographics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States bancassurance market represents a late-cycle quality story as mass-affluent retirement planning demand shifts toward fiduciary-grade advisory specifications and guaranteed income product complexity. This premiumization trajectory favors institutions with established compliance infrastructure and licensed advisor depth over commission-dependent branch models.
For Market Incumbents: Cement exclusive carrier relationships with proprietary product development rights to lock in distribution economics before SEC Regulation Best Interest fully compresses commission structures. Deepen vertical integration into fee-based advisory services within wealth management divisions, converting transactional insurance cross-sell into recurring planning relationships that withstand fiduciary scrutiny. For New Entrants and Emerging Players: Launch via embedded insurance APIs integrated into mortgage origination and deposit account opening workflows, bypassing the 90-120 day staff licensing bottlenecks that throttle traditional branch rollout. Target Sun Belt regional banks in Texas and Florida lacking in-house actuarial capabilities, offering white-label underwriting partnerships that accelerate product velocity without fixed compliance infrastructure investment. For Investors and Strategic Acquirers: Regional bank consolidators are the most active acquirer in this space, seeking deposit-rich institutions with underpenetrated insurance cross-sell ratios and established FINRA licensing frameworks. Watch for inflection where fee-based advisory revenue exceeds 50% of total bancassurance income, signaling successful model conversion ahead of regulatory compression.| Strategic Initiative | Industry Significance |
|---|---|
| API-Based Underwriting Integration | Real-time term life quotes embedded in mobile banking workflows compress 14-day sales cycles to minutes. |
| Fee-Based Advisory Conversion | Wealth management divisions absorb SEC Regulation Best Interest compliance burden through recurring planning revenue. |
| Exclusive Carrier Partnership | Proprietary product access locks in margin economics unavailable to open-architecture competitors. |
| Multi-State Licensing Harmonization | Texas and Florida reciprocity agreements reduce 90-120 day producer onboarding delays across regional networks. |
| Data Monetization Partnership | Transactional spending analytics enable predictive life event targeting for insurance cross-sell campaigns. |
Research Approach
Coverage spans Texas, Florida, California, New York, and Illinois, with primary inputs from each state combining interviews with bank wealth management executives, state insurance commissioner staff, FINRA compliance officers, and carrier distribution leads. Secondary validation draws from SEC filings, state insurance department examination reports, NAIC regulatory databases, and bank call report data. Bottom-up policy volume estimates triangulate against top-down premium flow projections across the analysis window.
Rate-of-change decomposition separates volume growth from pricing mix shift across product type, distribution channel, customer archetype, and service configuration dimensions. CAGRs derive from segmented regression modeling incorporating demographic migration patterns, branch density economics, and regulatory cost trajectory assumptions. Forecast inputs include mobile banking penetration curves, fiduciary standard implementation timelines, and carrier partnership exclusivity terms.
Several conditions sit outside the modeled scope, including potential federal preemption of state insurance licensing requirements, disruptive fintech charter approvals, and macroeconomic interest rate shocks affecting universal life crediting rates. Forecasts reflect assumptions about steady regulatory implementation without enforcement acceleration or delay. A small set of named triggers warrants ongoing watch: SEC examination priority shifts, state reciprocity agreement withdrawals, and carrier capacity constraints in guaranteed income product lines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Bancassurance Market
Insurance
UAE Property and Casualty Insurance Market
Insurance
Canada Property and Casualty Insurance Market
Insurance
Financial Guarantee Market
Insurance
Microinsurance Market
Insurance
Netherlands Property and Casualty Insurance Market
Insurance
Agricultural Insurance Market
Insurance
Global Vehicle Insurance Market
Insurance
Canada Health and Medical Insurance Market
Insurance
Reinsurance Market
Insurance
Europe Extended Warranty Market
Insurance
Canada Home Insurance Market
Insurance
Insurance Big Data Analytics Market
Insurance
Japan Parametric Insurance Market
Insurance
India Electronic Gadget Insurance Market
Insurance
US Electronic Gadgets Insurance Market