
 Workers Compensation Insurance Market | 2026-2036
Workers Compensation Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Workers Compensation Insurance Market Insights
Skilled trade labor availability is bifurcating the workers compensation insurance landscape, separating carriers that can underwrite specialized industrial risks from those retreating to general commercial lines. Travelers leverages its century-old expertise in construction and energy risks to sustain premium growth in hard-to-place occupational classes. The Hartford competes through integrated loss control services that reduce policyholder experience modification factors. Chubb Limited anchors its high-segment position with multinational capacity serving Fortune 500 self-insured retention programs.
Workers compensation insurance constitutes a statutory social insurance mechanism mandating employer-funded coverage for occupational injuries, illnesses, and fatalities, with premium calculations tied to classification codes, payroll exposure, and experience rating modifiers that adjust base rates by individual loss history. The product exists to transfer employer liability for workplace harm while providing no-fault medical and wage replacement benefits to injured workers. Standard policy types dominate premium volume across small and mid-sized employers, though large deductible structures capture disproportionate margin pools from national accounts seeking balance-sheet control over predictable loss layers. Disability benefits coverage generates the most contested claims activity, while rehabilitation services represent the fastest-growing cost component as medical inflation shifts toward functional restoration and return-to-work protocols.
State insurance departments, the National Council on Compensation Insurance, and OSHA collectively shape market conduct through rate filing approvals, statistical plan reporting requirements, and workplace safety enforcement that directly influences loss cost trends. NCCI experience rating plans and interstate rating procedures standardize premium determinants across forty jurisdictions, while residual market mechanisms provide coverage of last resort where voluntary market capacity withdraws. Stakeholders must monitor state legislative activity around presumption expansions for occupational diseases and the integration of telemedicine into statutory medical benefit schedules.
Market Dynamics
Artificial intelligence is compressing claims processing timelines and recalibrating loss cost reserves across the workers compensation insurance sector, forcing carriers to rebuild operational infrastructure around predictive analytics platforms.
Growth Catalysts
- OSHA workplace safety mandates:Construction sector employers are expanding coverage purchases as federal enforcement tightens. Premium volume concentrates in high-hazard occupational classes.
- State-level competitive rating evolution:Monopolistic funds in multiple US jurisdictions are transitioning toward open-market mechanisms. This regulatory shift unlocks private carrier participation.
- Telemedicine integration:Medical benefit schedules are incorporating remote diagnostic protocols. Rehabilitation services are accelerating return-to-work timelines.
Market Restraints
- Medical inflation concentration:Functional restoration and long-term disability costs are outpacing wage replacement components. Loss adjustment expenses absorb disproportionate reserve allocations.
- Residual market burden:Assigned risk pools in high-rate jurisdictions require cross-subsidization from voluntary market carriers. Withdrawal restrictions trap capacity in unprofitable segments.
- Experience rating volatility:NCCI interstate rating procedures amplify premium swings for mid-sized employers. Cash flow unpredictability depresses retention rates.
Strategic Opportunities
- Self-insured retention programs:Fortune 500 employers are seeking captive structures and large deductible arrangements. Multinational capacity providers can capture margin pools from national accounts.
- Presumption expansion tailwinds:State legislative activity around occupational disease coverage is creating new statutory benefit obligations. Carriers with predictive underwriting capabilities can price emerging exposures.
- AI-driven loss control convergence:Computer vision and wearable sensor technologies are integrating with traditional safety consulting. Real-time hazard detection reduces experience modification factors.
Industry Challenges
- Actuarial talent scarcity:Specialized underwriters capable of pricing complex industrial risks are exiting the workforce. Knowledge transfer gaps threaten retention of construction and energy expertise.
- Legacy system integration friction:Predictive analytics platforms require data architecture overhaul. Core policy administration systems resist API connectivity with external IoT data streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Workers Compensation Insurance Market |
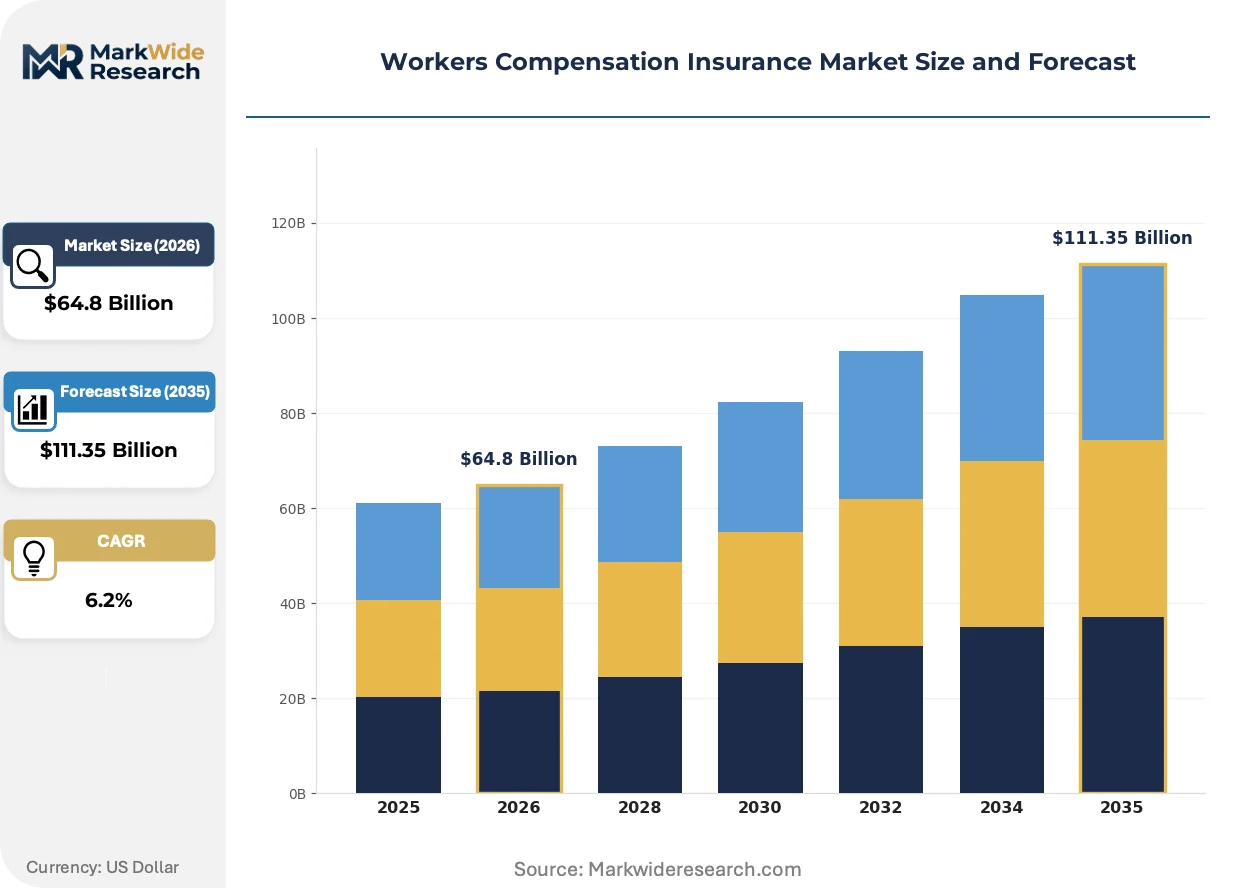
| Market Size in 2026 | $64.8 Billion |
| Market Size in 2035 | $111.35 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Standard, Large Deductible, Self-Insured, Voluntary Compensation Coverage Type: Medical Benefits, Disability Benefits, Rehabilitation Services, Death Benefits Distribution Channel: Direct Sales, Insurance Brokers, Online Platforms, Agents End User Industry: Manufacturing, Construction, Transportation, Hospitality |
| Companies Covered | Travelers, The Hartford, Zurich Insurance Group, AmTrust Financial Services, Chubb Limited, Berkshire Hathaway Group, Liberty Mutual Insurance Companies, American Financial Group, Old Republic Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Workers Compensation Insurance Market Trends and Innovations
Digital infrastructure is displacing paper-based claims workflows across the workers compensation insurance value chain, with automation penetrating underwriting, loss adjustment, and medical cost containment simultaneously.
Telematics and wearable sensor technology is miniaturizing occupational risk monitoring. Construction and logistics employers are piloting biometric devices for real-time fatigue detection. This hardware compression is enabling continuous exposure data collection that recalibrates classification codes.
The US Department of Labor is expanding silica exposure enforcement under revised OSHA permissible exposure limits. Industrial sandblasting and countertop fabrication operations face heightened inspection frequency. Carriers are responding with exclusionary endorsements and specialized loss control mandates.
Employer purchasing committees are consolidating brokerage relationships and demanding unbundled service components. Risk managers are separating claims administration from carrier selection. This procurement compression is most visible in manufacturing verticals across the Midwest and Southeast.
Workers Compensation Insurance Market Segmentation
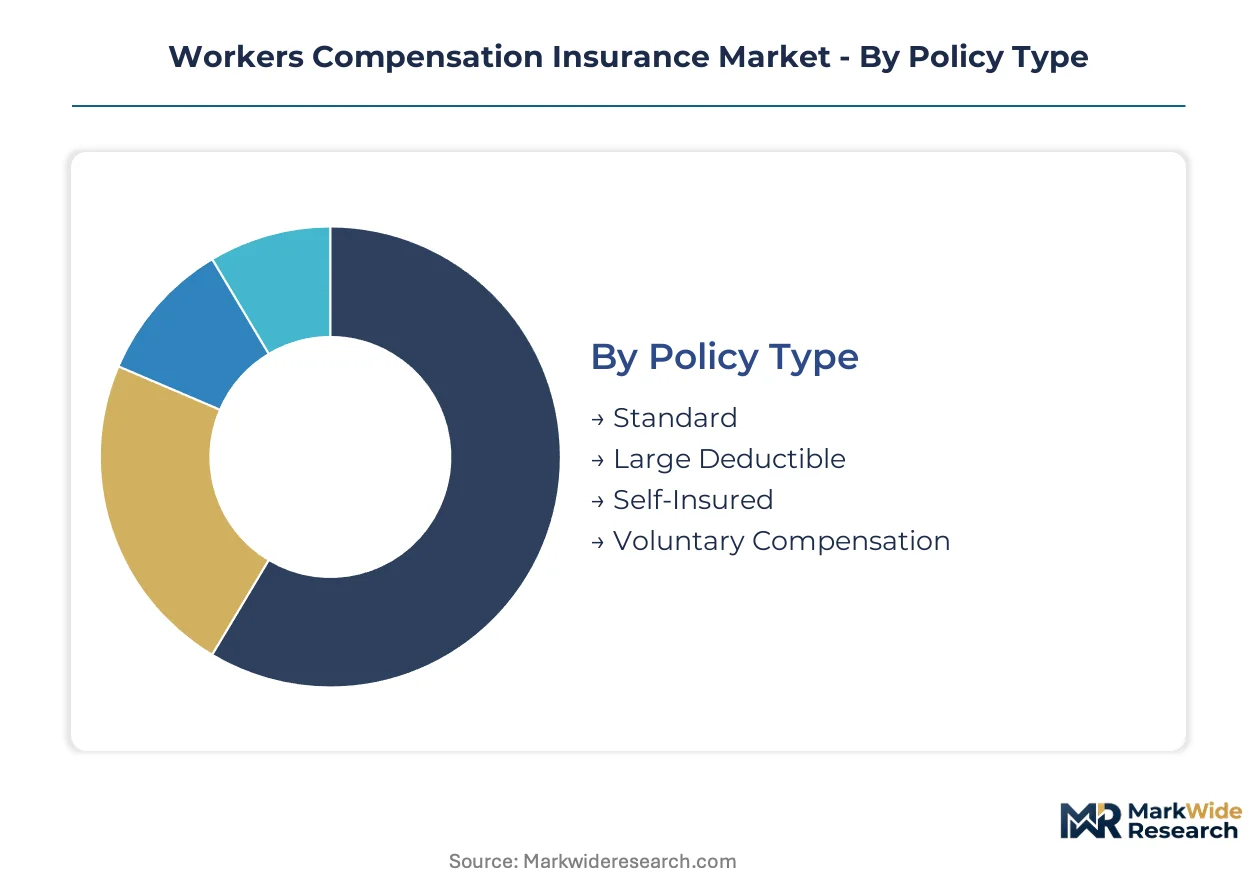
Workers compensation insurance segmentation reveals how premium pools concentrate across policy structures and where underwriting expertise creates defendable moats. Carriers calibrate capital allocation by matching policy complexity to their actuarial capabilities and loss control infrastructure.
Policy Type:
Substitution pressure runs highest among basic policy forms as digital distribution erodes traditional underwriting value, while complex structures retain pricing power through captive expertise requirements.
- Standard:Fixed-premium policies with guaranteed cost terms dominate small and mid-sized employer purchases. Manufacturing employers across the Midwest generate the densest quote volume as NCCI classification codes standardize rate filings across state jurisdictions.
- Large Deductible:Retention-based structures shift predictable loss layers to policyholder balance sheets. National accounts in construction and energy verticals concentrate here, seeking premium relief through self-funded primary layers while capping catastrophic exposure.
- Self-Insured:Employers with sufficient capitalization assume direct liability through state-approved self-insurance permits. Regulatory approval requirements and excess market procurement needs limit adoption to Fortune 500 entities with dedicated risk management departments.
- Voluntary Compensation:Elective coverage extensions protect non-mandated workers such as domestic employees or casual laborers. Agricultural employers in seasonal hiring states generate intermittent demand for this supplemental protection.
Standard policies retain volume leadership; large deductible structures hold the steepest expansion curve among national accounts seeking balance-sheet control.
Coverage Type:
Cost tier stratification separates medical components from indemnity exposures, with rehabilitation services commanding premium pricing as return-to-work outcomes determine reserve adequacy.
- Medical Benefits:Statutory schedules govern physician reimbursement and hospital charges for occupational injury treatment. State fee schedules in California and New York create the widest geographic dispersion in cost per claim.
- Disability Benefits:Wage replacement payments during temporary or permanent incapacity generate the most litigated claim disputes. Construction sector employers face the highest severity concentration due to traumatic injury frequency.
- Rehabilitation Services:Functional restoration and vocational retraining accelerate return-to-work timelines. Telemedicine protocols are compressing physical therapy delivery costs while expanding rural access.
- Death Benefits:Survivor payments and funeral expense allowances cap exposure for fatal workplace incidents. High-hazard classifications in mining and logging drive statutory maximum benefit utilization.
Medical benefits retain volume leadership; rehabilitation services are climbing the fastest as medical inflation shifts toward functional restoration protocols.
Distribution Channel:
Customer type fragmentation separates transactional purchasers seeking rate comparison from complex risks requiring advisory placement and claims advocacy.
- Direct Sales:Carrier-employed underwriters quote standard policies for low-complexity risks. Technology and professional services employers with clean loss histories gravitate toward streamlined digital quoting platforms.
- Insurance Brokers:Independent intermediaries negotiate terms across multiple carrier markets. Mid-sized manufacturing employers rely on brokerage relationships for experience rating dispute resolution and coverage gap analysis.
- Online Platforms:Digital aggregators provide instant quoting for small accounts with straightforward classification codes. Micro-employers in retail and food service generate the highest quote-to-bind velocity through these channels.
- Agents:Captive and independent agents deliver localized service for geographically concentrated policyholder bases. Rural construction contractors depend on agency relationships for OSHA compliance guidance bundled with coverage placement.
Insurance brokers retain volume leadership; online platforms are gaining share fastest among sub-50-employee accounts seeking frictionless procurement.
End User Industry:
Application severity separates high-hazard verticals requiring specialized underwriting from clerical risks competing on price alone.
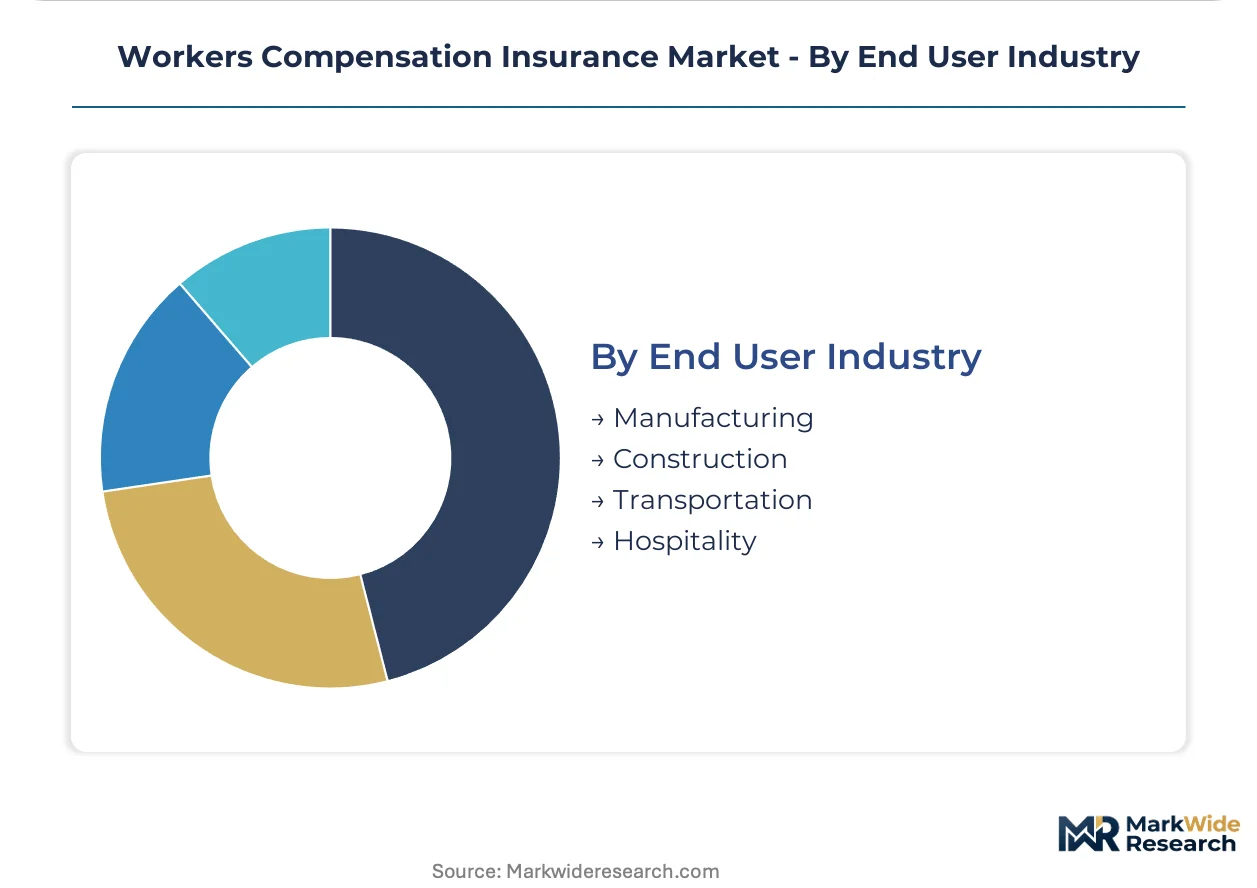
- Manufacturing:Machinery operation and repetitive motion exposures generate frequency-driven claim patterns. Automotive and electronics assembly plants in Michigan and Ohio constitute the largest premium pools.
- Construction:Falls, struck-by incidents, and silica exposure drive severity concentration. Federal OSHA enforcement expansion under revised permissible exposure limits is accelerating coverage purchases among specialty trade contractors.
- Transportation:Long-haul trucking and last-mile delivery combine vehicle collision risk with musculoskeletal strain. Driver classification disputes between employees and independent contractors create coverage ambiguity in gig economy logistics.
- Hospitality:Slip-and-fall incidents and kitchen burns dominate lower-severity claim profiles. Seasonal employment patterns and high turnover complicate payroll reporting accuracy for premium calculation.
Manufacturing retains volume leadership; construction holds the steepest expansion curve as federal safety mandates tighten enforcement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in workers compensation insurance concentrates disproportionately in the United States, where state-level rate filings and competitive rating transitions generate premium elasticity unavailable in monopolistic fund jurisdictions. European markets operate under tighter regulatory constraints that compress carrier margins.
United States
Construction sector employers in Texas and Florida are expanding coverage purchases as OSHA silica enforcement tightens under revised permissible exposure limits. State insurance departments in California and New York maintain the most complex rate filing approval processes. Premium volume clusters in the Midwest manufacturing belt, where automotive assembly plants in Michigan and Ohio generate dense quote activity.
Canada
Provincial workers compensation boards in Ontario and British Columbia retain monopolistic structures that limit private carrier participation. The country's national insurance regulator oversees residual market mechanisms where voluntary capacity withdraws. Industrial employers in Alberta's energy sector face rising assessments as oil sands operations report elevated occupational injury frequency.
Germany
Employers liability insurance associations (Berufsgenossenschaften) dominate statutory coverage through sector-specific mutual structures. The German Social Code mandates unified premium rates that suppress price competition. Manufacturing concentration in Bavaria and Baden-Württemberg sustains dense policyholder pools for metalworking and machinery risks.
United Kingdom
Employers liability coverage operates through competitive insurance markets rather than state monopoly. The Health and Safety Executive enforces workplace safety standards that directly influence loss cost trends. London-based carriers and Lloyd's syndicates provide multinational capacity serving Fortune 500 self-insured retention programs.
Australia
State-based workers compensation schemes in New South Wales and Victoria are transitioning toward privatized claims management. Safe Work Australia coordinates national policy consistency across jurisdictional boundaries. Mining operations in Western Australia generate high-severity exposure concentrations that attract specialized underwriting expertise.
Workers Compensation Insurance Market Competitive Landscape
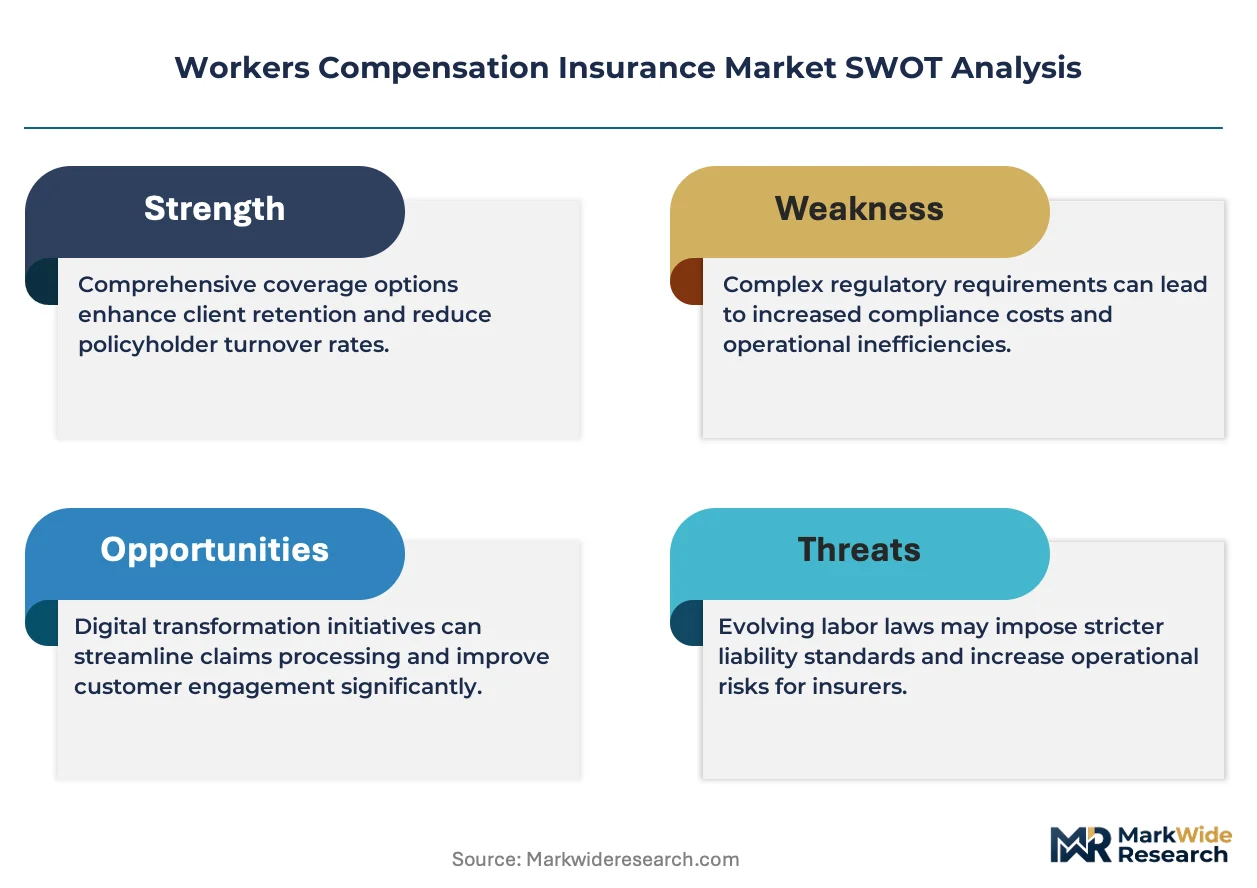
Technology leadership and cost leadership are held by different player archetypes across the workers compensation insurance sector. Predictive analytics capabilities concentrate among national carriers with dedicated data science infrastructure, while regional mutuals compete on local loss control relationships and experience rating stability. Three archetypes dominate: integrated carriers bundling claims administration with underwriting, monoline specialists focusing exclusively on workers compensation, and diversified financial services conglomerates leveraging capital scale. Competitive dynamics center on M&A activity targeting specialized underwriting talent and strategic partnerships embedding telematics into traditional safety consulting.
Among the integrated carrier tier, Travelers and The Hartford exemplify archetypes combining century-old construction expertise with modern loss control infrastructure. Chubb Limited occupies a position serving multinational capacity needs for Fortune 500 self-insured retention programs. These three entities represent distinct competitive positioning vectors: construction specialization, mid-market manufacturing penetration, and high-segment multinational service.
| Leading Market Players |
|---|
| Travelers |
| The Hartford |
| Zurich Insurance Group |
| AmTrust Financial Services |
| Chubb Limited |
| Berkshire Hathaway Group |
| Liberty Mutual Insurance Companies |
| American Financial Group |
| Old Republic Group |
| Others |
Pricing and Supply Chain Analysis
Forty-five to sixty-day policy issuance lead times in standard workers compensation markets compress to fifteen days in digitally streamlined jurisdictions, concentrating pricing power with carriers possessing real-time underwriting infrastructure while forcing traditional distributors toward advisory service differentiation.
Pricing Analysis
The customization-premium spread separates guaranteed-cost standard policies from large-deductible configured structures, with the latter commanding fifteen to thirty percent pricing premiums for balance-sheet control. Price differentiation hinges on experience modification factor precision and NCCI classification code granularity. Cost compression in standard tier policies is intensifying because digital aggregators compress quote-to-bind friction. Small retail and food service employers exhibit highest price sensitivity, while Fortune 500 national accounts prioritize claims advocacy over rate comparison.
Supply Chain Analysis
Strategic-stockpile preferences dominate residual market mechanisms where state assigned risk pools require cross-subsidization buffers, while just-in-time capacity deployment characterizes competitive rating jurisdictions. Capital concentration rests on the United States, United Kingdom, and Bermuda as primary underwriting hubs. Reinsurance capacity, actuarial talent, and predictive analytics platforms constitute critical input dependencies. Single-source vulnerability concentrates in NCCI statistical data monopolies. Distribution runs through independent brokerage networks for mid-market complexity, direct digital channels for micro-employers, and captive agents for geographically concentrated rural risks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Workers compensation insurance operates through a cyclical recovery phase as OSHA enforcement expansion drives construction sector coverage purchases following pandemic-period premium softness.
For Market Incumbents: Consolidate specialized underwriting expertise in construction and energy risks before actuarial talent scarcity deepens. Acquire predictive analytics capabilities to defend against AI-native entrants compressing loss adjustment timelines. Prioritize NCCI experience rating dispute resolution infrastructure as mid-sized employers face cash flow unpredictability from interstate rating volatility. For New Entrants and Emerging Players: State self-insurance permit fast-tracks unlock Fortune 500 captive management white space where multinational capacity providers remain underrepresented. Target residual market mechanisms in high-rate jurisdictions where withdrawal restrictions trap incumbent capacity. Lead with telemedicine-integrated claims administration as a differentiated service bundle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified financial services conglomerates seeking workers compensation monoline divestitures. Long-term viability centers on carriers possessing both predictive data infrastructure and specialized industrial underwriting heritage. Monitor state legislative activity around occupational disease presumption expansion as inflection indicator for emerging exposure pricing capability.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Analytics Platform Deployment | AI-driven claims processing reduces loss adjustment expenses for Travelers and The Hartford. |
| Telemedicine Integration Partnership | Remote diagnostic protocols accelerate return-to-work timelines for rehabilitation services. |
| Self-Insurance Permit Acquisition | Fortune 500 captive structures capture margin pools from national accounts seeking balance-sheet control. |
| Specialized Underwriting Talent Recruitment | Construction and energy expertise retention counters knowledge transfer gaps threatening sector coverage. |
| OSHA Compliance Bundling Service | Federal silica enforcement expansion drives coverage purchases among specialty trade contractors. |
Research Methodology
Initial hypotheses were tested against primary input from carrier underwriting executives, state insurance department regulators, brokerage principals, and risk management officers at Fortune 500 employers and refined through secondary validation against NCCI statistical plan filings, OSHA enforcement databases, state legislative tracking systems, and SEC 10-K insurance segment disclosures. Bottom-up premium volume estimates triangulated with top-down market sizing from regulatory rate filing aggregates.
Variance decomposition across policy type, coverage component, distribution channel, and end-user industry dimensions structured the analytical framework over the projection horizon. CAGRs derived from regression analysis against payroll exposure growth, medical inflation trajectories, and regulatory rating system transitions. Forecast inputs incorporated NCCI interstate rating procedure modifications and state presumption expansion legislative tracking.
Underlying assumptions cover OSHA enforcement intensity persistence, medical cost containment effectiveness, and competitive rating transition pace, with deviation risk concentrated in residual market burden shifts and actuarial talent supply constraints. Revision becomes warranted when state legislative presumption activity crosses threshold frequencies or AI claims automation adoption accelerates beyond modeled penetration curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Africa Microinsurance Market
Insurance
Extended Warranty Agreement Market
Insurance
North America Family Floater Health Insurance Market
Insurance
Earthquake Insurance Market
Insurance
Global Cargo Transportation Insurance Market
Insurance
Entertainment Insurance Market
Insurance
Title Insurance Market
Insurance
General Insurance Market
Insurance
Europe Liability Insurance Market
Insurance
US Property and Casualty (P&C) Insurance Market
Insurance
South Africa Property and Casualty Insurance Market
Insurance
US Insurance Third-Party Administrator Market
Insurance
Umbrella Insurance Market
Insurance
Marine Freight Insurance Market
Insurance
Middle East Business Income Insurance Market
Insurance
China Parametric Insurance Market