
 Austria Property and Casualty Insurance Market | 2026-2036
Austria Property and Casualty Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Austria Property and Casualty Insurance Market Outlook
A capital-intensity divergence between legacy incumbents and digital challengers is reorganizing competitive dynamics across Austria's property and casualty sector. Allianz Elementar Versicherungs-AG leverages its integrated bancassurance network to sustain pricing power in motor and home lines. Vienna Insurance Group anchors market presence through its dense branch infrastructure across Upper Austria and Styria. UNIQA Osterreich Versicherungen AG differentiates via specialized SME liability products targeting Vienna's service economy.
Property and casualty insurance constitutes risk transfer contracts indemnifying policyholders against financial loss from property damage, liability claims, or personal injury, with premiums calibrated through actuarial modeling of frequency and severity distributions. These instruments primarily protect commercial and residential asset bases while ensuring contractual liability coverage for operational and personal exposures. Motor insurance commands the largest premium pool among product types, driven by mandatory third-party liability requirements and rising comprehensive coverage for electric vehicle fleets. Home insurance maintains stable penetration across Austria's owner-occupied housing stock, while liability insurance captures expanding demand from professional services firms and construction contractors facing heightened litigation exposure.
Austria's Financial Market Authority enforces Solvency II-aligned capital adequacy standards that shape product pricing and reserve requirements for domestic underwriters. The European Insurance and Occupational Pensions Authority coordinates supervisory convergence across EU member states, affecting cross-border reinsurance arrangements and group solvency calculations. Stakeholders must monitor evolving climate risk disclosure mandates from the European Central Bank's stress testing framework and assess how physical risk models will recalibrate regional premium adequacy for flood and storm coverage in alpine and Danube basin exposures.
Market Dynamics
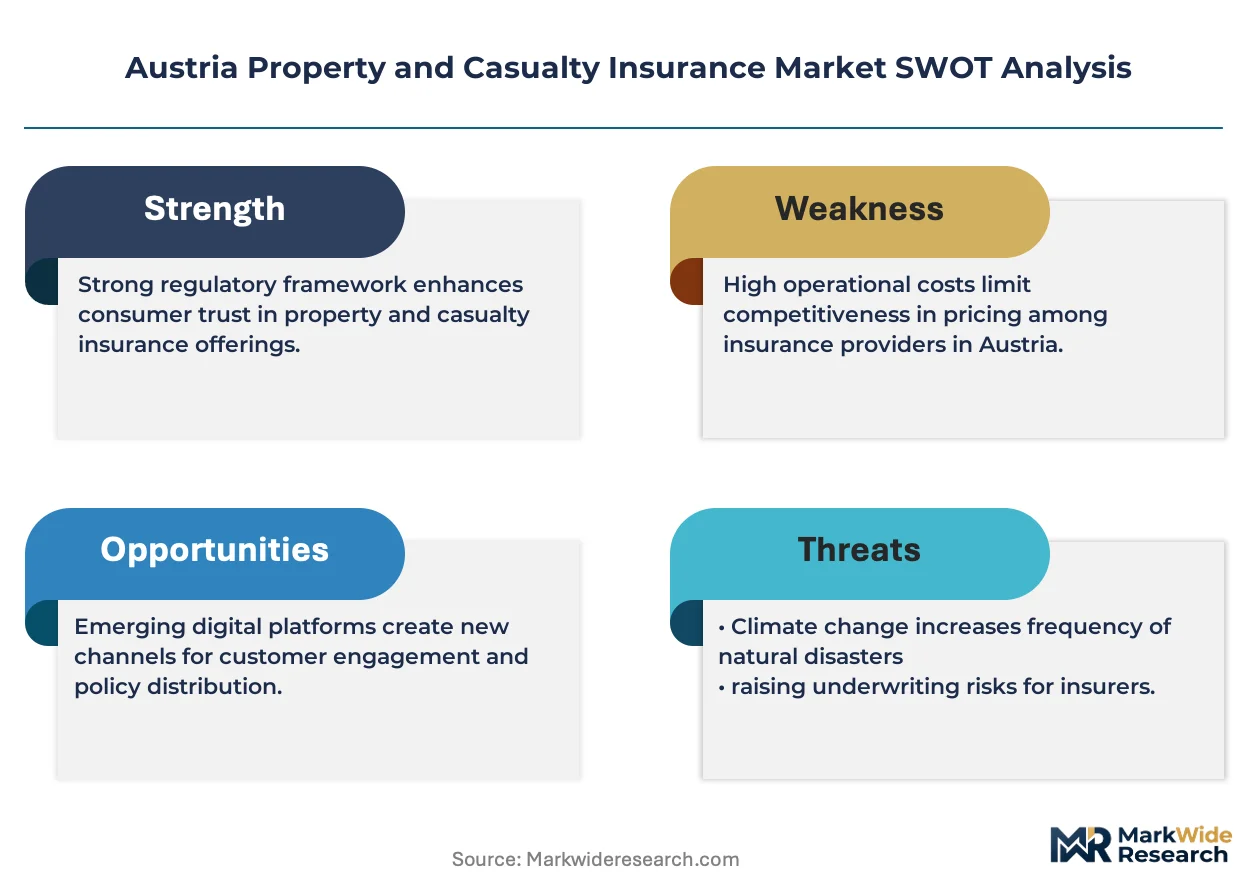
Climate risk recalibration is compressing traditional actuarial models as alpine flood zones expand and Danube basin storm frequency intensifies, forcing underwriters to rebuild pricing frameworks from physical exposure data rather than historical loss patterns.
Growth Catalysts
- Electric vehicle fleet mandates:Austria's phased combustion engine restrictions are accelerating comprehensive motor coverage demand for battery-electric commercial fleets and private vehicles.
- EU Green Deal disclosure requirements:Corporate sustainability reporting obligations are expanding directors' and officers' liability coverage needs among Vienna-listed enterprises.
- Alpine tourism infrastructure expansion:Ski resort operators in Tyrol and Vorarlberg are procuring enhanced property coverage for avalanche and infrastructure failure risks.
Market Restraints
- Reinsurance capacity tightening:Global catastrophe bond spreads are elevating retrocession costs for Austrian primary carriers writing natural peril coverage.
- Long-duration climate model uncertainty:Actuarial reserves for 30-year property policies face adequacy questions as regional precipitation patterns destabilize.
- Low-yield investment income:Solvency II-mandated sovereign bond portfolios are compressing risk-free rate assumptions underlying product pricing.
Strategic Opportunities
- Embedded insurance distribution:Automotive OEMs and real estate platforms are integrating point-of-sale coverage for vehicle and home purchasers.
- Cyber liability underpenetration:Styrian manufacturing SMEs remain uninsured against operational technology ransomware exposures.
- Parametric flood products:Satellite-triggered indemnity structures are bypassing traditional loss adjustment for Danube catchment agricultural risks.
Industry Challenges
- Climate data science talent scarcity:Catastrophe modelers with alpine geospatial expertise command premium compensation that mid-tier carriers struggle to match.
- Legacy core system integration:Mainframe policy administration platforms from the 1990s resist API connectivity with telematics data streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Austria Property and Casualty Insurance Market |
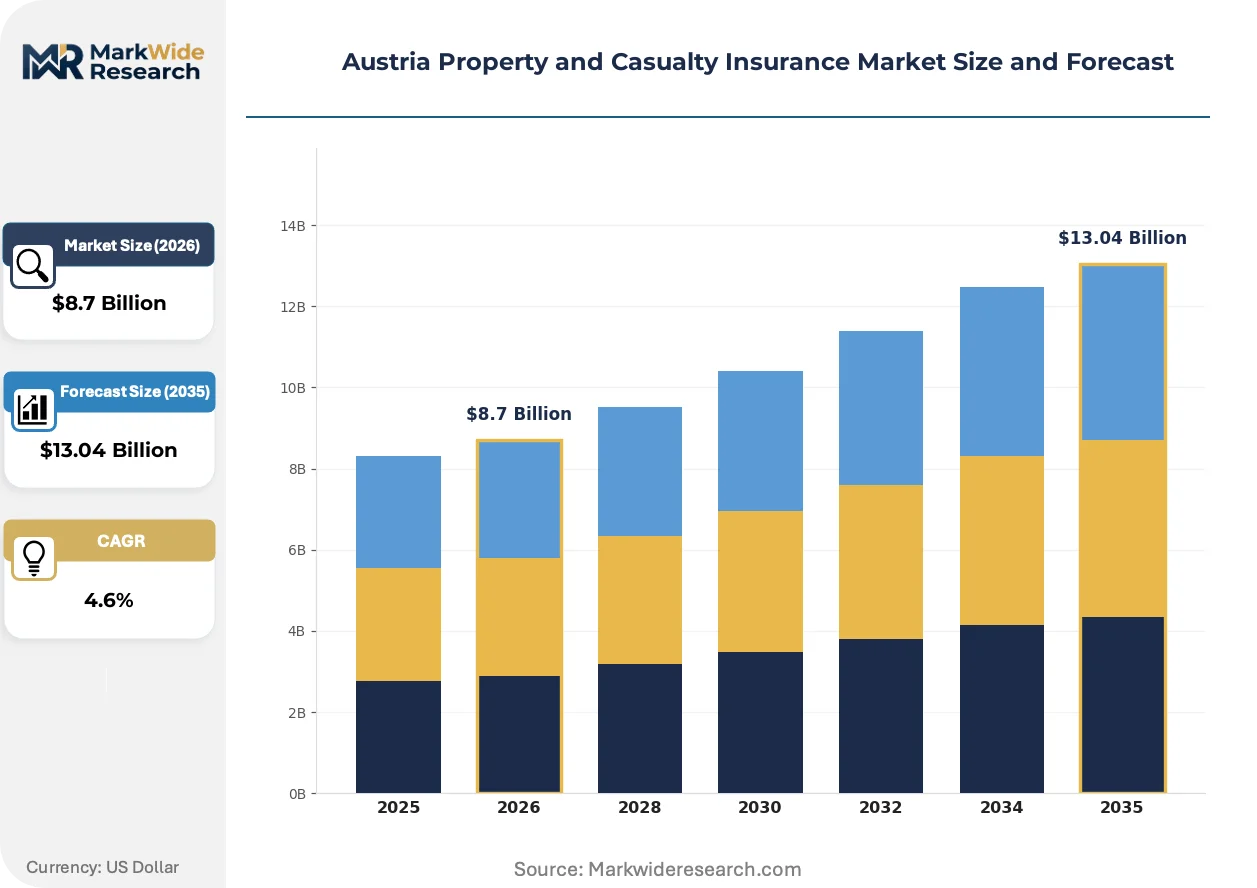
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Home Insurance, Motor Insurance, Liability Insurance, Travel Insurance Coverage Type: Comprehensive, Third-Party, Collision, Uninsured Motorist Customer Segment: Individuals, Small Businesses, Corporations, Non-Profit Organizations Distribution Channel: Direct Sales, Brokers, Agents, Online Platforms |
| Companies Covered | Allianz Elementar Versicherungs-AG, Donau Versicherung AG, UNIQA Osterreich Versicherungen AG, Oberösterreichische Versicherung AG, Zurich Versicherungs-AG, Generali Versicherung AG, Grazer Wechselseitige Versicherung AG, Helvetia Versicherungen AG, Vienna Insurance Group (Wiener Städtische), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Austria Property and Casualty Insurance Market Strategic Shifts
Telematics and sensor infrastructure are collapsing the information asymmetry between underwriters and policyholders, enabling real-time risk pricing that rewards loss prevention behavior rather than pooling static demographic categories.
Usage-based motor insurance is decomposing the traditional annual premium model into granular per-kilometer and per-event pricing structures. Fleet managers in Upper Austria are adopting connected vehicle dongles that transmit braking patterns and route risk profiles. This granular data architecture is compressing cross-subsidies between high-risk and low-risk drivers into individualized rate cells.
Austria's Financial Market Authority is implementing ECB-aligned climate stress testing protocols that mandate scenario analysis for 1-in-200-year flood events. Domestic insurers must model portfolio concentration across exposed postal codes. Residential property writers in Salzburg and Lower Austria are restricting new business in designated hazard zones.
Commercial buyers are unbundling risk placement across multiple specialized underwriters rather than consolidating with single carriers. Large Vienna real estate developers now separately procure property, terrorism, and environmental impairment coverage. This fragmentation pattern is most pronounced among construction contractors facing project-specific bond and liability requirements.
Austria Property and Casualty Insurance Market Segmentation
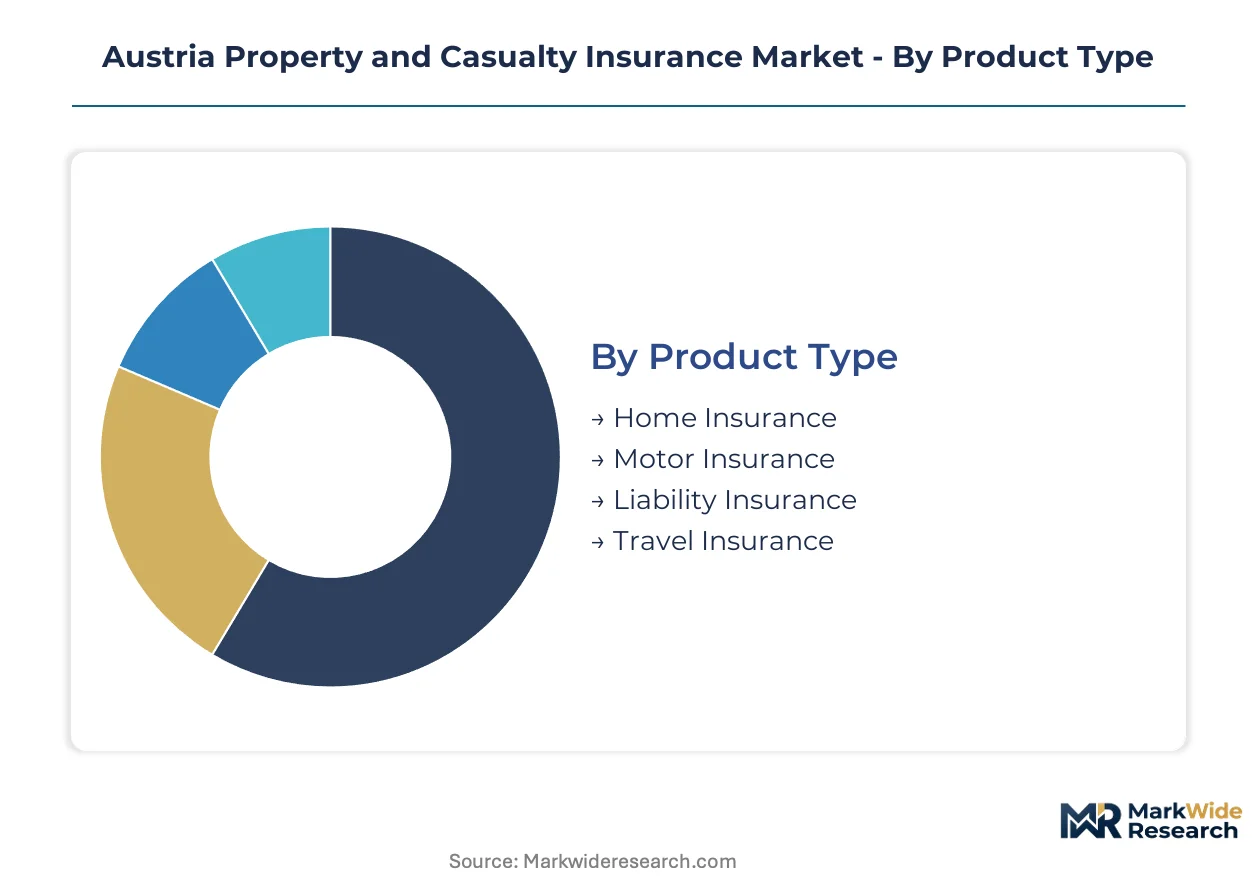
Austria's property and casualty market fragments across four structural dimensions that reshape how carriers allocate capital, price risk, and deploy distribution infrastructure. Each segmentation axis reveals divergent margin profiles and growth trajectories that inform product development priorities.
Product Type:
Motor and home lines flow through bancassurance partnerships and tied agent networks, while liability and travel products concentrate in broker-mediated commercial placements and direct digital channels.
- Motor Insurance:Mandatory third-party liability coverage anchors premium volumes across Austria's vehicle fleet. Tyrolean and Vorarlberg commercial fleet operators are expanding comprehensive coverage for battery-electric vehicles as combustion phase-out deadlines approach.
- Home Insurance:Fire and elemental peril contracts protect Austria's owner-occupied housing stock. Salzburg and Lower Austria underwriters are restricting new policy issuance in alpine flood zones where climate models show destabilizing precipitation patterns.
- Liability Insurance:Professional and product liability coverage addresses litigation exposure for Vienna service firms and construction contractors. SME procurement through independent brokers dominates this line.
- Travel Insurance:Trip cancellation and medical evacuation coverage serves leisure and business travelers. Direct online platforms capture the majority of individual policy sales.
Motor insurance dominates installed base. Liability insurance is where expansion concentrates.
Coverage Type:
Cost tier differentiation separates mandatory minimum coverage from premium-tier risk transfer products, with collision and comprehensive commanding higher per-policy margins than statutory minimums.
- Comprehensive:All-risk property and motor coverage indemnifies policyholders against own-damage losses regardless of fault. Upper Austria fleet managers are adopting telematics-linked comprehensive policies with real-time premium adjustments.
- Third-Party:Statutory liability coverage satisfies Austria's mandatory motor insurance requirements. This segment generates volume but compresses margins through regulatory price caps.
- Collision:Own-damage motor coverage limited to impact events. Vienna urban drivers with high parking density show elevated attachment rates for this mid-tier product.
- Uninsured Motorist:Protection against losses caused by unidentified or uninsured third parties. Styrian agricultural vehicle operators value this coverage given rural road accident patterns.
Third-party coverage dominates installed base. Comprehensive is climbing the fastest as vehicle values rise.
Customer Segment:
Volume concentration sits with individual policyholders, while margin expansion follows commercial accounts demanding tailored risk engineering and loss prevention services.
- Individuals:Personal lines coverage for motor, home, and liability risks. Vienna and Salzburg households with above-median property values drive premium adequacy in this segment.
- Small Businesses:SME liability and property packages tailored to service economy operators. Styrian manufacturing SMEs remain underpenetrated for cyber liability coverage.
- Corporations:Large commercial accounts with complex, multi-line risk placements. Vienna real estate developers now unbundle property, terrorism, and environmental coverage across specialized underwriters.
- Non-Profit Organizations:Directors' and officers' liability and event cancellation coverage. EU Green Deal disclosure requirements are expanding D&O procurement among Vienna-listed social enterprises.
Individuals dominate installed base. Small businesses represent the steepest expansion trajectory as regulatory complexity deepens.
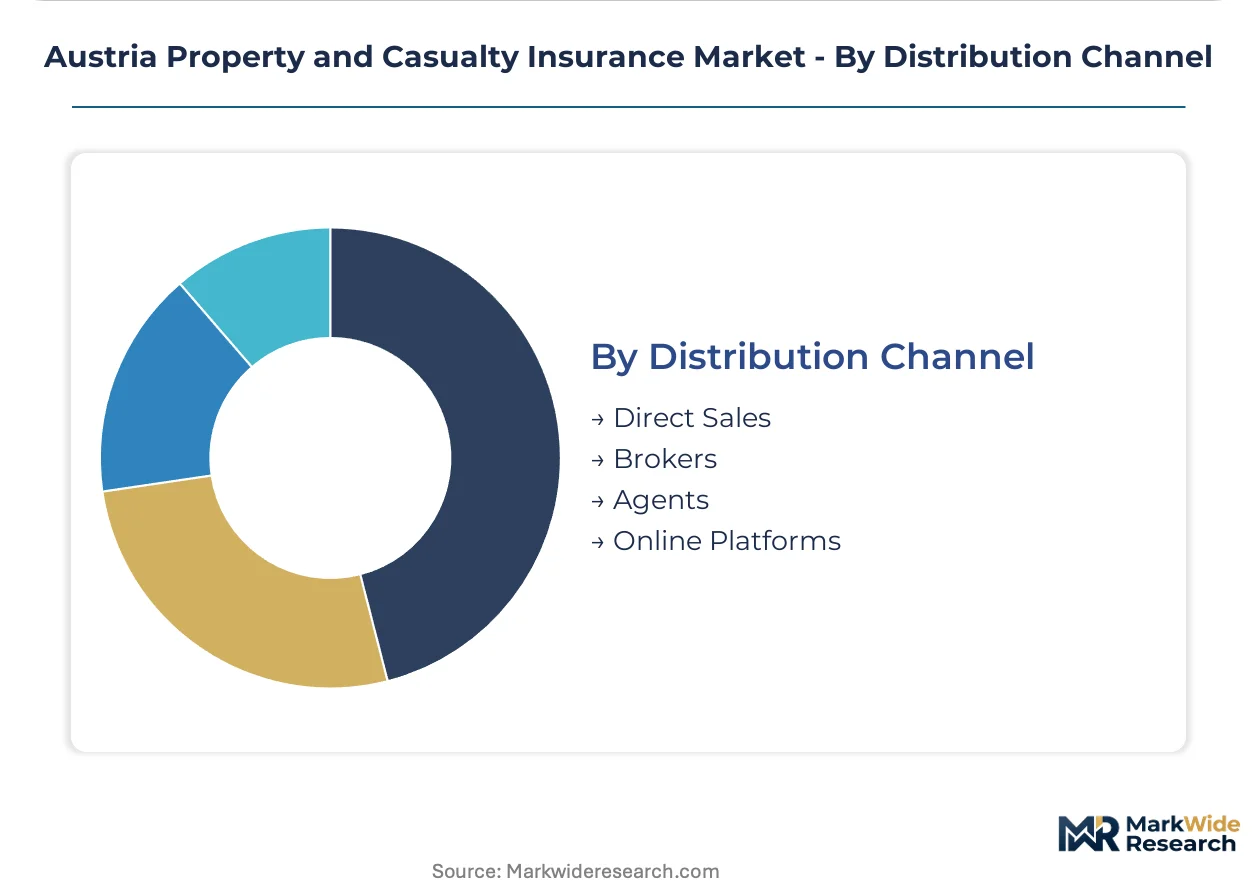
Distribution Channel:
Customer type and product complexity dictate channel selection, with high-touch advice migrating to brokers and standardized coverage shifting to automated platforms.
- Direct Sales:Carrier-owned channels including branch networks and call centers. Vienna Insurance Group leverages its dense Upper Austria and Styria branch infrastructure for direct motor and home policy placement.
- Brokers:Independent intermediaries serving commercial accounts with complex risk profiles. Large construction contractors rely on broker access to specialized surety and project liability markets.
- Agents:Tied representatives with exclusive carrier appointments. Allianz Elementar's bancassurance partnerships distribute motor and home products through banking channels.
- Online Platforms:Digital direct-to-consumer and embedded distribution. Automotive OEMs are integrating point-of-sale motor coverage for vehicle purchasers through API-connected platforms.
Agents and direct sales dominate installed base. Online platforms are gaining share fastest as embedded insurance partnerships proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Austria's property and casualty insurance consumption concentrates in urban centers and alpine tourism corridors, diverging from rural agricultural zones where penetration remains thinner and product mix skews toward statutory minimums.
Vienna
Corporate liability and directors' and officers' coverage dominates premium flows as EU Green Deal disclosure mandates expand procurement among listed enterprises. The national Financial Market Authority enforces Solvency II-aligned capital standards that elevate pricing for complex commercial placements. Vienna's dense service economy sustains broker-mediated SME liability demand.
Upper Austria
Manufacturing fleet operators drive telematics-linked comprehensive motor coverage as battery-electric commercial vehicle adoption accelerates. Regional supervisory standards from Linz-based regulatory offices coordinate with federal solvency requirements. Industrial zones around Linz and Steyr anchor connected-vehicle insurance experimentation.
Salzburg
Property underwriters restrict new home policy issuance in designated alpine flood zones where climate models signal destabilizing precipitation. The national climate stress testing framework mandates 1-in-200-year flood scenario analysis for residential portfolios. Ski resort operators in surrounding districts procure enhanced avalanche and infrastructure failure coverage.
Tyrol and Vorarlberg
Tourism infrastructure expansion fuels specialized property coverage demand for avalanche, landslide, and cable transport failure risks. Alpine tourism development permits now require proof of catastrophic peril insurance. Innsbruck and Bregenz serve as underwriting hubs for mountain resort risk engineering services.
Styria
Manufacturing SMEs remain underpenetrated for cyber liability and operational technology ransomware coverage despite expanding digitalization. Regional chambers of commerce promote insurance literacy programs for industrial risk transfer. Graz anchors broker networks serving construction contractors with project-specific bond requirements.
Austria Property and Casualty Insurance Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in Austria's property and casualty insurance structure. The upper tier comprises multi-line carriers with bancassurance networks and dense branch infrastructure sustaining pricing power in motor and home lines. Below them, regional mutuals and specialized liability underwriters capture niche commercial segments. Three archetypes dominate: integrated conglomerates with banking partnerships, alpine-focused regional mutuals, and international carriers with reinsurance-backed capacity. Competitive moves concentrate on embedded insurance distribution partnerships and climate risk model differentiation.
Within the integrated tier, Allianz Elementar Versicherungs-AG and Vienna Insurance Group occupy positions defined by distribution depth and geographic coverage density. UNIQA Osterreich Versicherungen AG exemplifies the specialist archetype targeting SME liability placements. Zurich Versicherungs-AG and Generali Versicherung AG represent internationally capitalized carriers with cross-border reinsurance access. These five names anchor the competitive structure without exhausting the participant base.
| Leading Market Players |
|---|
| Allianz Elementar Versicherungs-AG |
| Donau Versicherung AG |
| UNIQA Osterreich Versicherungen AG |
| Oberösterreichische Versicherung AG |
| Zurich Versicherungs-AG |
| Generali Versicherung AG |
| Grazer Wechselseitige Versicherung AG |
| Helvetia Versicherungen AG |
| Vienna Insurance Group (Wiener Städtische) |
| Others |
Value Chain & Pricing Dynamics
Solvency II capital adequacy standards gate both carrier qualification and premium differentiation in Austria's property and casualty sector, compressing risk-free rate assumptions for low-yield sovereign bond portfolios while elevating pricing for climate-exposed property lines. This regulatory architecture simultaneously filters marginal underwriters from the market and stratifies consumer offerings across capital-backed tiers.
Pricing Analysis
Annual renewable contracts dominate personal lines, while multi-year corporate placements with inflation-adjusted premiums anchor commercial accounts. Three-tier pricing structure across premium, standard, and economy levels separates telematics-linked comprehensive motor coverage from statutory minimum third-party liability. Cost compression in economy tiers intensifies because bancassurance networks bundle home and motor products at thin margins. Small businesses demonstrate highest price sensitivity, whereas Vienna-listed corporations prioritize coverage breadth over premium minimization.
Supply Chain Analysis
Port congestion at Hamburg and Rotterdam elevates reinsurance treaty documentation transit times for Austrian primary carriers sourcing capacity from London and Zurich markets. Risk capital concentrates in Bermuda, London, and Switzerland for catastrophe excess-of-loss protection. Treaty renewals hinge on loss experience from alpine flood zones and Danube basin storm corridors. Distribution runs through broker-mediated placements for commercial accounts and tied-agent networks for personal lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded insurance APIs are transforming Austria's property and casualty sector into a platform-coordinated ecosystem, collapsing distribution friction between automotive OEMs, real estate platforms, and underwriters through standardized data exchange protocols.
For Market Incumbents: Compound pricing power in motor and home lines by deepening bancassurance exclusivity with Raiffeisen and Erste Bank networks. Accelerate legacy core system API connectivity to capture telematics data streams from connected vehicle fleets, neutralizing digital challenger threat from embedded distribution platforms.
For New Entrants and Emerging Players: EU Green Deal disclosure fast-tracks create immediate white-space opportunity in directors' and officers' liability for Vienna-listed mid-caps. Target Styrian manufacturing SMEs with cyber liability products addressing operational technology ransomware exposure, leveraging regional chamber of commerce insurance literacy programs as channel entry point.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across climate-exposed property lines as alpine flood zone restrictions tighten new business capacity. Acquire specialized alpine risk engineering boutiques with proprietary geospatial modeling capabilities. Monitor ECB climate stress test disclosure patterns as signal for portfolio revaluation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Enables real-time premium adjustments for Upper Austria fleet operators adopting connected vehicle dongles. |
| Climate Risk Model Differentiation | Secures pricing power in Salzburg flood zones where historical loss patterns destabilize. |
| Embedded Insurance Partnership | Captures point-of-sale motor coverage through automotive OEM API connectivity. |
| Cyber Liability Product Launch | Addresses underpenetration among Styrian manufacturing SMEs facing ransomware exposure. |
| Alpine Risk Engineering Acquisition | Builds proprietary catastrophe modeling capability for Tyrol and Vorarlberg tourism infrastructure. |
Study Parameters
Cross-validation between primary interviews with underwriters, brokers, and regulatory affairs specialists and secondary sources including FMA supervisory disclosures, EIOPA convergence reports, and ECB climate stress test documentation anchors the qualitative findings. Bottom-up premium volume estimates from carrier filings triangulate against top-down macroeconomic consumption models.
Sensitivity analysis across the projection horizon tests forecast robustness against Solvency II capital requirement revisions and electric vehicle fleet penetration scenarios. Segmentation dimensions include product type, coverage tier, customer scale, and distribution channel, with CAGRs derived from actuarial frequency-severity modeling and premium adequacy trends.
Underlying assumptions cover stable regulatory capital frameworks and gradual climate model recalibration, with deviation risk concentrated in abrupt reinsurance capacity withdrawal or accelerated alpine precipitation pattern shifts. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Road Assistance Insurance Market
Insurance
Asia-Pacific Extended Warranty Market
Insurance
Marine Freight Insurance Market
Insurance
North America Family Floater Health Insurance Market
Insurance
Asia-Pacific Liability Insurance Market
Insurance
Earthquake Insurance Market
Insurance
Spain Group Health Insurance Market
Insurance
Japan Bancassurance Market
Insurance
Global Home Insurance Market
Insurance
Agricultural Insurance Market
Insurance
Asia-Pacific AI in Insurance Market
Insurance
Germany Car Insurance Market
Insurance
Insurance Brokerage Market
Insurance
Asia-Pacific Group Health Insurance Market
Insurance
Middle East and Africa Travel Insurance Market
Insurance
United Kingdom Health and Medical Insurance Market