
 Global Boats and Yacht Insurance Market | 2026-2036
Global Boats and Yacht Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Global Boats and Yacht Insurance Market Analysis
Multi-policy bundling is consolidating buyer choice across hull, liability, and environmental coverage into single-package offerings. Chubb Group Holdings Inc leverages its high-net-worth personal lines infrastructure to dominate the superyacht segment. Allianz SE anchors European market presence through specialized marine underwriting capabilities. Markel American Insurance Company differentiates via niche expertise in performance sailing vessels and custom-built craft.
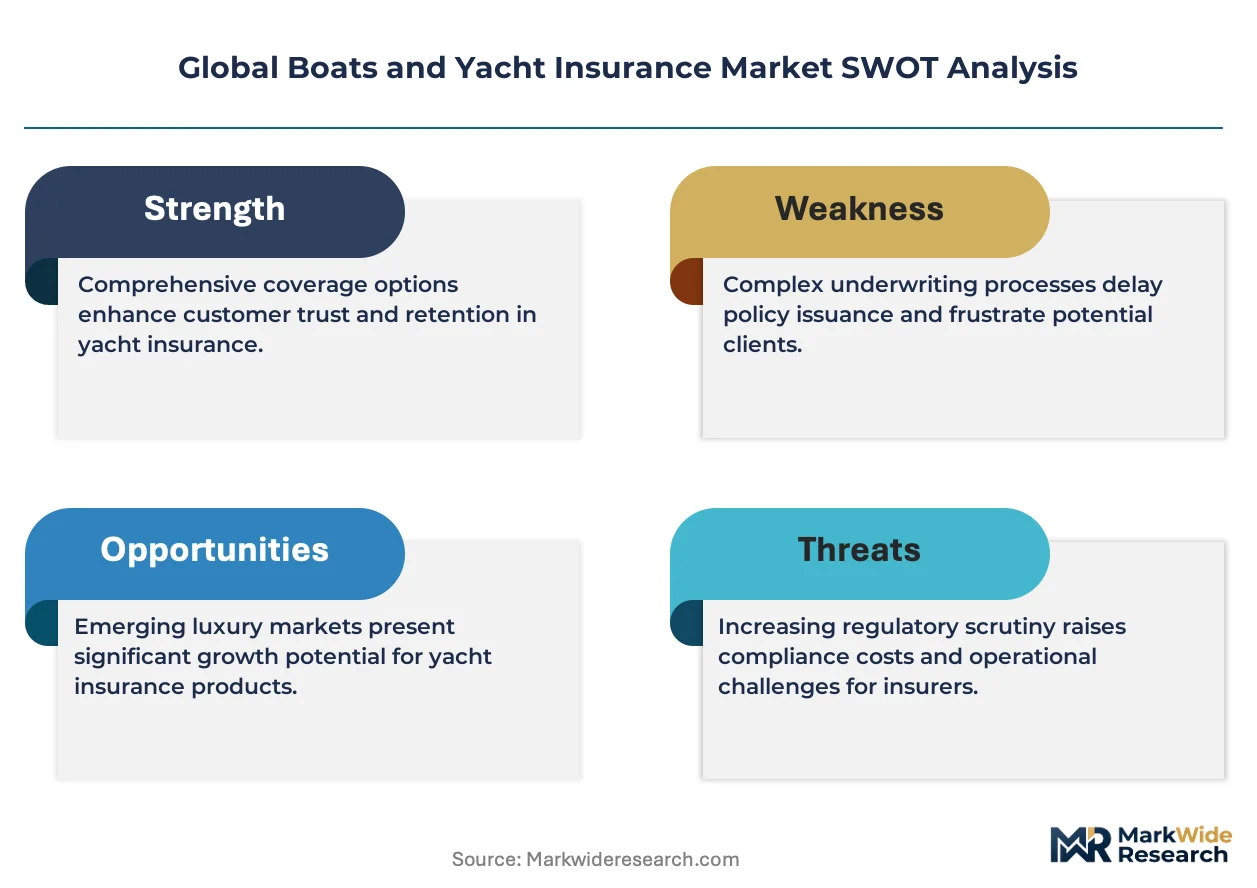
Boats and yacht insurance constitutes a specialized property-and-casualty product line covering physical damage, third-party liability, and environmental remediation for watercraft ranging from personal watercraft under six meters to superyachts exceeding thirty meters in length, with underwriting grounded in naval architecture surveys, navigational zone ratings, and seasonal lay-up provisions. The vessel type dimension reveals motor yachts generating the largest premium pools due to higher hull values and complex machinery coverage requirements, while catamarans represent the fastest-growing sub-segment driven by charter fleet expansion and multihull cruising popularity. Policy type structures show comprehensive coverage commanding dominant share, though third-party liability exhibits fastest growth as regulatory minimums escalate in environmentally sensitive cruising grounds.
FDA marine safety guidelines, EPA Clean Water Act discharge standards, and EU F-Gas Regulation refrigerant protocols collectively shape coverage mandates and exclusion language across international waters. Lloyd's of London operates under UK Financial Conduct Authority and Prudential Regulation Authority oversight, while US carriers navigate state-level insurance commissioner filing requirements alongside federal Coast Guard documentation rules. Stakeholders must monitor evolving climate risk modeling methodologies and parametric trigger innovations as hurricane severity trends force fundamental repricing of catastrophic exposure in traditional indemnity structures.
Market Dynamics
Parametric insurance triggers are compressing claims settlement cycles from months to days, forcing traditional indemnity carriers to restructure catastrophic exposure pricing models around real-time weather data feeds and automated payout mechanisms.
Growth Catalysts
- EU F-Gas Regulation:Refrigerant protocol mandates for marine HVAC systems are expanding environmental liability coverage minimums across Mediterranean charter fleets, creating mandatory upgrade pathways for existing policies.
- High-net-worth portfolio expansion:Ultra-affluent owners in Monaco, Palma de Mallorca, and Fort Lauderdale are consolidating hull, crew, and cyber coverage into single-carrier relationships, reducing price sensitivity.
- Hybrid propulsion systems:Battery-electric auxiliary drives in 40-60 meter motor yachts are generating specialized machinery breakdown coverage demand with bespoke thermal runaway provisions.
Market Restraints
- Hurricane modeling volatility:North Atlantic tropical cyclone severity uncertainty is compressing reinsurance capacity for Florida and Gulf Coast hull writers, forcing primary carriers to retain more peak exposure.
- Naval architect supply concentration:Surveyor certification for superyacht valuations depends on a tight pool of Lloyd's Register and Bureau Veritas-accredited specialists concentrated in Southampton and Fort Lauderdale.
- Legacy IT infrastructure:Established marine underwriters operate on policy administration systems built for static annual renewals, creating friction against real-time telematics integration.
Strategic Opportunities
- Indonesia archipelago expansion:The Raja Ampat and Komodo cruising grounds lack developed marine insurance distribution, presenting first-mover advantage for parametric hurricane and piracy products.
- EU Green Deal maritime directives:Carbon intensity indexing for vessels over 5,000 GT is creating compliance-linked coverage products with premium discounts for verified emission reductions.
- Telematics-channel convergence:Satellite-connected engine monitoring and geofencing data streams enable usage-based premium structures for seasonal owner-operators in the Great Lakes and Pacific Northwest.
Industry Challenges
- Climate risk actuarial talent scarcity:Catastrophe modelers with combined naval architecture and stochastic weather simulation expertise command premium compensation, constraining carrier expansion.
- Multi-jurisdiction claims coordination:Salvage operations involving flag states, coastal state environmental courts, and P&I club mutual agreements create settlement timeline unpredictability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Boats and Yacht Insurance Market |
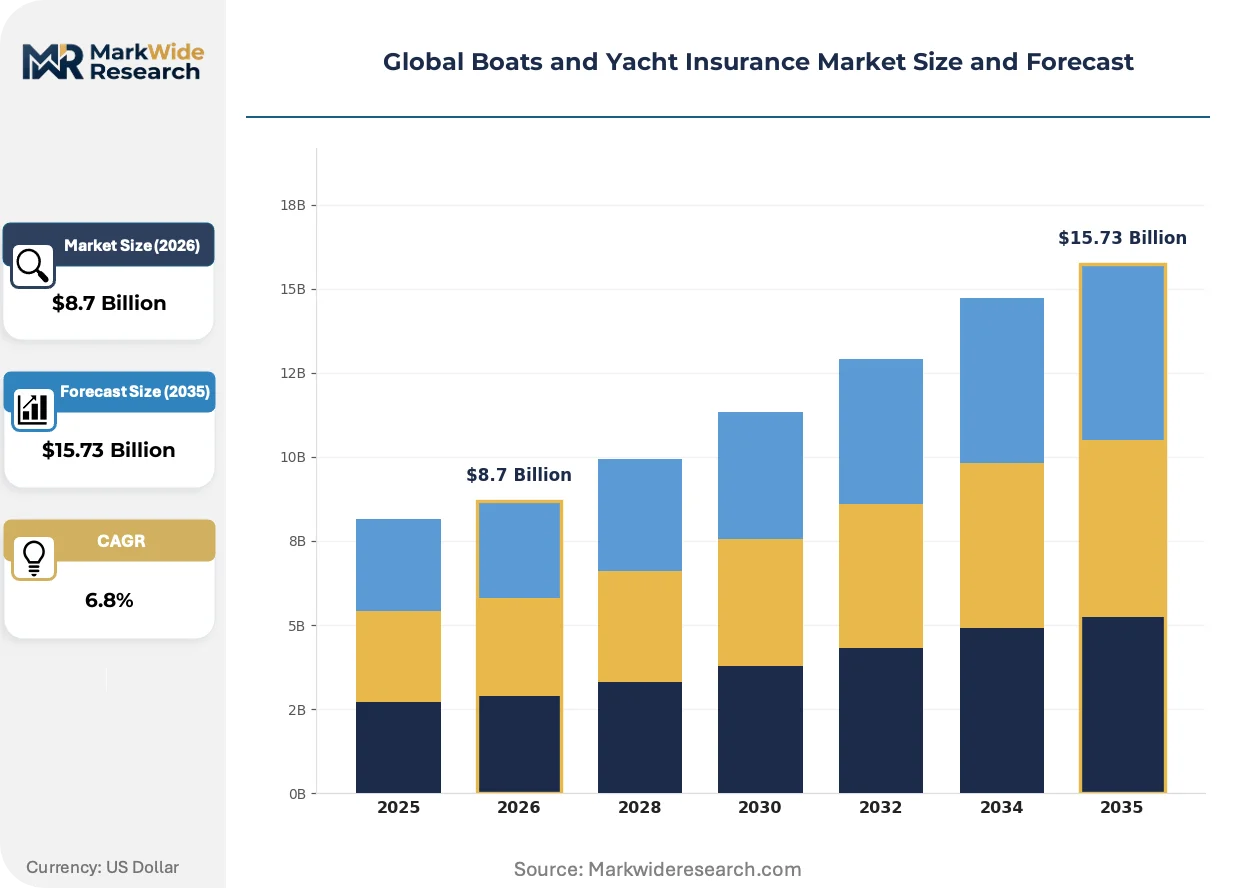
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Comprehensive, Third Party Liability, Collision, Medical Coverage Vessel Type: Sailboats, Motor Yachts, Catamarans, Personal Watercraft Coverage Options: Property Damage, Theft, Liability, Environmental Damage Client Type: Individual Owners, Commercial Operators, Charter Companies, Dealers |
| Companies Covered | Chubb Group Holdings Inc, American International Group Inc., Allianz SE, AXA S.A, QBE Insurance Group Ltd, Zurich Insurance Group Ltd, Markel American Insurance Company, The Hanover Insurance Group, Lloyd's of London, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Boats and Yacht Insurance Market Emerging Trajectories
Digital twin hull monitoring and blockchain-verified maintenance records are compressing information asymmetry between owners and underwriters, enabling dynamic premium adjustment models that respond to real-time vessel condition rather than static survey schedules.
Autonomous collision avoidance systems integrating lidar and machine-vision processing are absorbing traditional navigator error liability into product defect coverage frameworks. Superyacht builders in Northern Germany and Dutch custom yards are specifying these systems as standard fitment. The shift is compressing demand for standalone crew negligence riders while expanding product recall exposure for sensor manufacturers.
The EPA Clean Water Act vessel discharge standards are mandating ballast water treatment system coverage endorsements for all US-documented craft over 79 feet. Shipyards in Seattle and Newport News are retrofitting older hulls to maintain charter eligibility. The regulatory drag is most acute for Great Lakes cruising fleets, where seasonal lock passages create concentrated compliance inspection windows.
Fractional ownership platforms are fragmenting single-vessel risk across 8-12 co-owners, each requiring named insured status and usage-schedule verification. Charter management companies in the British Virgin Islands and Seychelles are absorbing administrative burden through embedded insurance procurement. The behavioral shift is most visible among tech-sector buyers aged 35-50, who treat yacht access as an asset-light subscription rather than capital deployment.
Global Boats and Yacht Insurance Market Segmentation
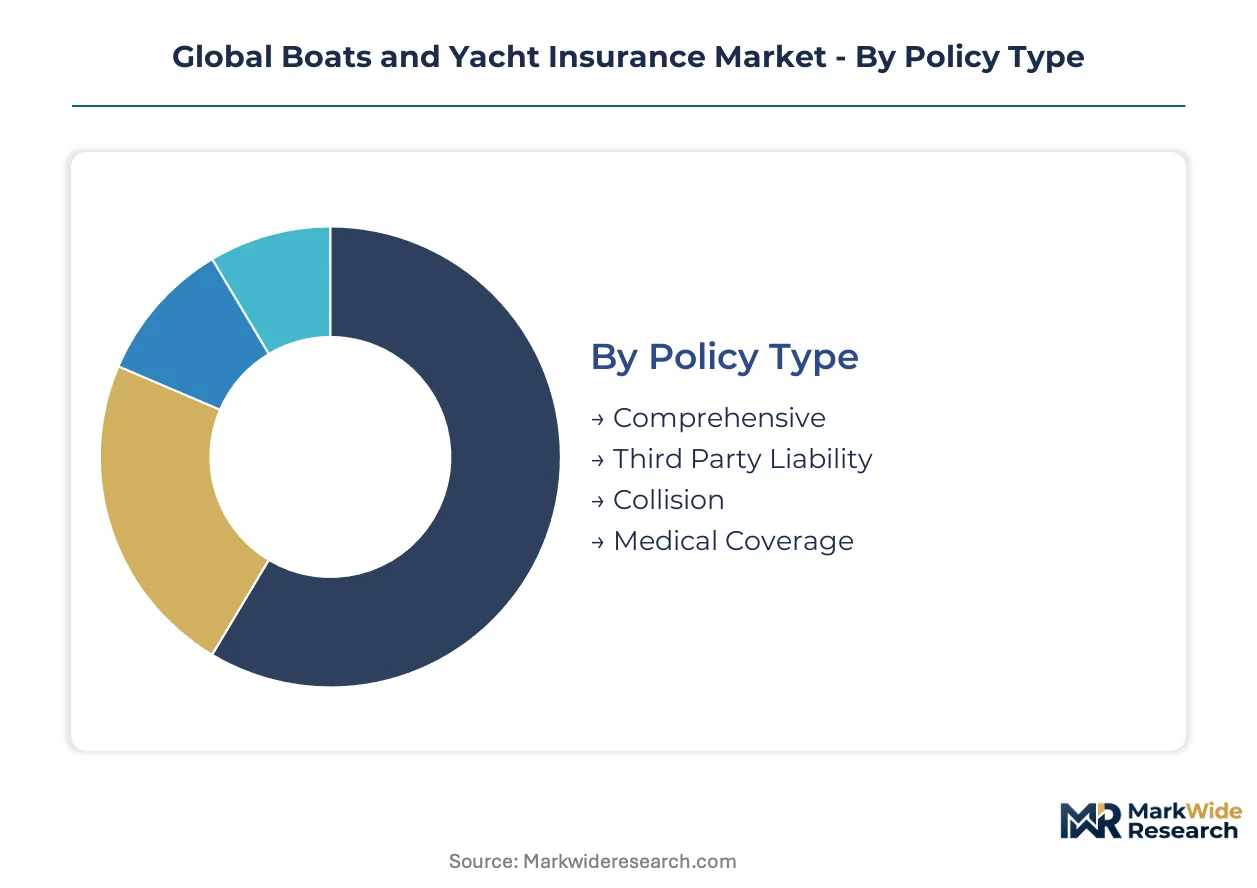
Segmentation in boats and yacht insurance determines underwriting complexity, pricing granularity, and carrier specialization strategies. Each dimension reflects distinct risk profiles, regulatory exposures, and client service requirements that shape product architecture across the value chain.
Policy Type:
Premium allocation follows the depth of indemnity protection and claims settlement scope.
- Comprehensive:Bundles hull damage, machinery breakdown, environmental liability, and crew coverage into unified policy structures. Demand concentrates among superyacht owners in Monaco and Fort Lauderdale seeking single-carrier relationships with streamlined renewal cycles.
- Third Party Liability:Covers bodily injury and property damage to third parties without hull protection for the insured vessel. Mediterranean charter fleets facing EU F-Gas Regulation mandates are expanding minimum coverage thresholds to satisfy environmental court jurisdictions.
- Collision:Isolates physical damage from contact with other vessels or fixed objects. Coastal Florida owner-operators prioritize this rider given congested marina density and hurricane salvage congestion.
- Medical Coverage:Addresses crew and passenger injury treatment costs. Indonesian archipelago cruisers in Raja Ampat and Komodo grounds require this endorsement due to remote evacuation distances.
Volume sits with Comprehensive; growth tilts toward Third Party Liability.
Vessel Type:
Naval architecture complexity and machinery density drive actuarial modeling differentiation.
- Motor Yachts:Encompass displacement and planing hulls with diesel, hybrid, or battery-electric propulsion. Northern German and Dutch custom yards specify autonomous collision avoidance systems as standard, shifting liability frameworks toward product defect coverage.
- Catamarans:Multihull designs with dual-engine redundancy and expansive deck space. Charter fleet expansion in the British Virgin Islands and Seychelles is accelerating demand for usage-based premium structures.
- Sailboats:Monohull craft relying on wind propulsion with auxiliary engine backup. Performance sailing vessels require specialized surveyor certification from Lloyd's Register-accredited specialists.
- Personal Watercraft:Jet-powered vessels under six meters including jet skis and wave runners. Great Lakes seasonal operators leverage telematics-enabled geofencing for lay-up period discounts.
Motor Yachts command the largest premium pools; Catamarans show the steepest expansion trajectory.
Coverage Options:
Regulatory mandates and cruising ground risk profiles determine endorsement selection hierarchies.
- Property Damage:Protects hull, machinery, and equipment against physical loss. US-documented craft over 79 feet require ballast water treatment system endorsements per EPA Clean Water Act standards.
- Theft:Covers vessel and equipment disappearance risks. Piracy exposure in Southeast Asian waters drives demand for parametric trigger products with automated settlement.
- Liability:Encompasses third-party bodily injury, property damage, and legal defense costs. EU Green Deal maritime directives are linking carbon intensity indexing to premium discount eligibility.
- Environmental Damage:Addresses fuel spill remediation and refrigerant leak cleanup. F-Gas Regulation compliance in Mediterranean HVAC systems is expanding mandatory upgrade pathways.
Property Damage anchors premium volume; Environmental Damage is climbing the fastest.
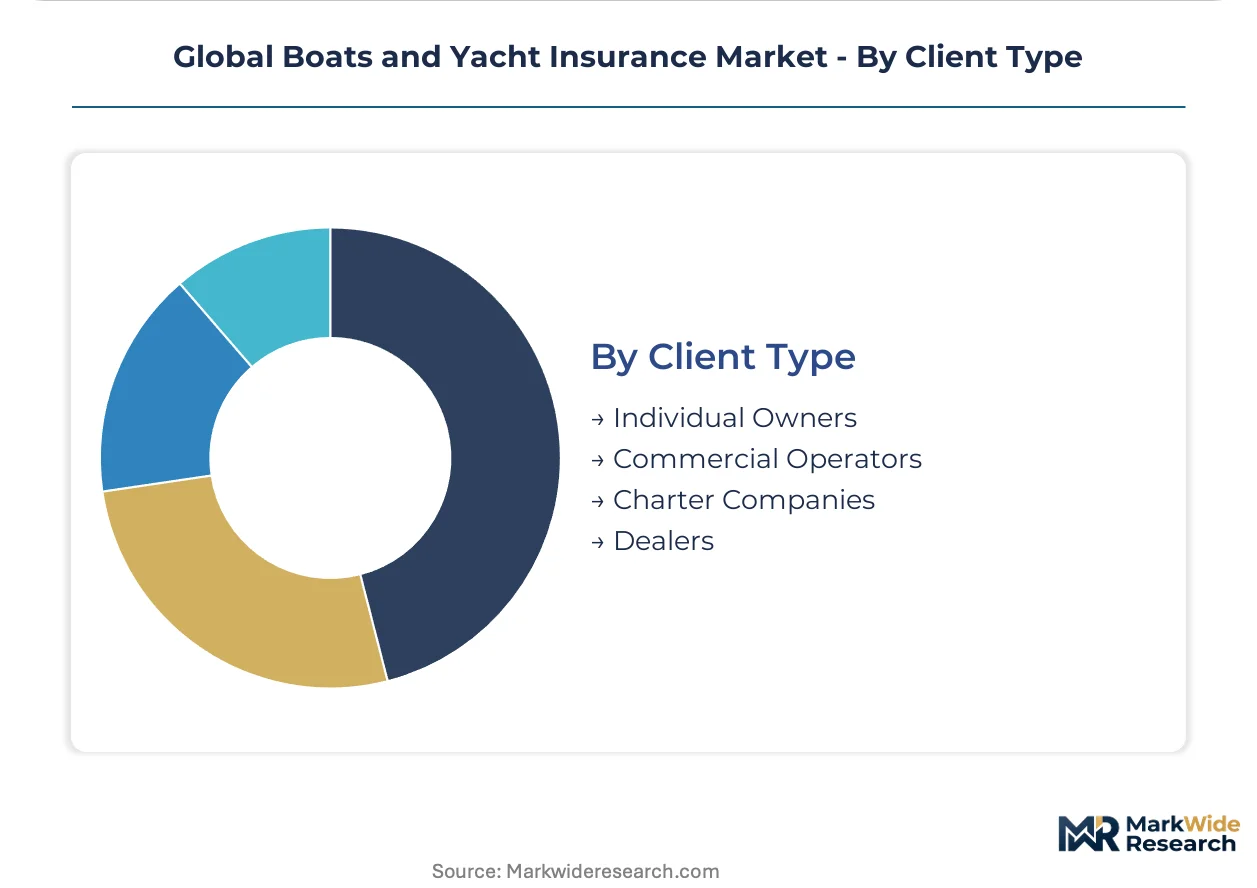
Client Type:
Ownership structure complexity and administrative burden tolerance shape distribution channel preferences.
- Individual Owners:High-net-worth principals consolidating hull, crew, and cyber coverage. Ultra-affluent buyers in Palma de Mallorca exhibit reduced price sensitivity through single-carrier relationships.
- Charter Companies:Fleet operators managing multiple vessels with rotating guest manifests. Embedded insurance procurement absorbs fractional ownership platform administrative burdens across 8-12 co-owner structures.
- Commercial Operators:Businesses deploying vessels for fishing, transport, or survey work. Seasonal lock passages in Great Lakes cruising create concentrated compliance inspection windows.
- Dealers:Retail and brokerage entities holding inventory risk during sales cycles. Shipyards in Seattle and Newport News retrofit older hulls to maintain charter eligibility and insurance access.
Individual Owners dominate premium contribution; Charter Companies are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Superyacht construction concentrates in Northern Germany and the Netherlands, while premium consumption clusters in Mediterranean tax-advantaged jurisdictions and Florida hurricane corridors. This production-consumption divide shapes underwriting capacity allocation and regulatory compliance burdens across carrier portfolios.
United States
Coastal Florida drives catastrophic exposure pricing with hurricane modeling volatility compressing reinsurance capacity for Gulf Coast hull writers. EPA Clean Water Act vessel discharge standards mandate ballast water treatment endorsements for US-documented craft exceeding 79 feet. Fort Lauderdale anchors the superyacht servicing cluster where high-net-worth owners consolidate hull, crew, and cyber coverage.
Germany
Northern German custom yards specify autonomous collision avoidance systems as standard fitment, shifting liability frameworks toward product defect coverage. KBA vehicle-type approval processes intersect with Lloyd's Register certification requirements for machinery breakdown policies. Hamburg and Bremen concentrate naval architect talent pools accredited for superyacht valuations.
United Kingdom
Lloyd's of London operates under FCA and PRA oversight while maintaining marine underwriting dominance through syndicated capacity structures. UK Financial Conduct Authority filing requirements govern policy wording for international cruising grounds. Southampton hosts the concentrated surveyor certification pipeline for Lloyd's Register-accredited specialists.
France
EU F-Gas Regulation refrigerant protocols for marine HVAC systems expand environmental liability coverage minimums across Mediterranean charter fleets. ANSM and CNIL oversight frameworks apply where vessels carry medical equipment or process passenger data. The Côte d'Azur cruising corridor generates demand for third-party liability expansion as environmental court jurisdictions tighten.
Indonesia
The Raja Ampat and Komodo cruising grounds lack developed marine insurance distribution, presenting first-mover positioning for parametric hurricane and piracy products. Remote evacuation distances drive medical coverage endorsement requirements for archipelago operators. Jakarta-based charter management companies absorb administrative burdens for fractional ownership platforms spanning 8-12 co-owners.
Global Boats and Yacht Insurance Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market segments. Conglomerates leverage balance sheet scale to absorb catastrophic hurricane exposure in Florida and Gulf Coast portfolios. Specialists capture margin through bespoke underwriting for performance sailing vessels and custom-built craft with complex machinery coverage requirements. The dominant competitive moves center on geographic expansion into underpenetrated cruising grounds and parametric product innovation compressing claims settlement cycles.
Within the diversified carrier tier, Chubb Group Holdings Inc and Allianz SE exemplify scale-driven positioning through high-net-worth personal lines infrastructure and specialized marine underwriting capabilities respectively. Markel American Insurance Company occupies the specialist archetype with niche expertise in performance sailing vessels. These three entities represent the competitive spectrum from integrated conglomerate operations to focused craft-specific underwriting.
| Leading Market Players |
|---|
| Chubb Group Holdings Inc |
| American International Group Inc. |
| Allianz SE |
| AXA S.A |
| QBE Insurance Group Ltd |
| Zurich Insurance Group Ltd |
| Markel American Insurance Company |
| The Hanover Insurance Group |
| Lloyd's of London |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation refrigerant protocol mandates for marine HVAC systems are forcing Mediterranean charter fleets to upgrade coverage minimums, compelling underwriters to restructure premium schedules around environmental compliance tiers and certified installer networks.
Pricing Analysis
Cost-down pressure on standard hull policies accelerates because Florida hurricane modeling volatility compresses reinsurance capacity, forcing primary carriers to retain more peak exposure. Three-tier pricing structure across premium, standard, and economy levels separates Lloyd's syndicate placements from admitted carrier filings and surplus lines surplus. Price differentiation hinges on surveyor certification tier and navigational zone restrictions. Ultra-affluent owners in Monaco exhibit minimal price sensitivity, while Great Lakes seasonal operators negotiate aggressively on lay-up period discounts.
Supply Chain Analysis
Domestic-content mandates for US-documented craft exceeding 79 feet under EPA Clean Water Act standards are reshaping sourcing toward Seattle and Newport News shipyards for ballast water treatment retrofits. Underwriting capacity concentrates in the United Kingdom, Germany, and the United States. Raw material dependencies include naval architect surveyor certification, satellite telematics hardware, and specialized marine HVAC refrigerant systems. Single-source vulnerability sits with the concentrated Lloyd's Register-accredited surveyor pool in Southampton and Fort Lauderdale. Distribution runs through Fort Lauderdale servicing clusters, Monaco brokerage houses, and Jakarta charter management platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EU F-Gas Regulation environmental liability mandates create a barrier-to-entry moat for carriers with established Mediterranean charter fleet relationships and certified installer networks.
For Market Incumbents: Anticipate parametric insurance startups compressing claims settlement cycles from months to days, threatening traditional indemnity pricing power. Defensive moves center on acquiring real-time weather data feed capabilities and embedding telematics-channel convergence into policy administration systems. Channel control through exclusive surveyor certification pipelines in Fort Lauderdale and Southampton reinforces underwriting information asymmetry. For New Entrants and Emerging Players: Embedded insurance procurement platforms for fractional ownership structures offer the most penetrable entry vector. White-space targets include Indonesia's Raja Ampat and Komodo cruising grounds lacking developed marine insurance distribution, and cyber coverage bundling for high-net-worth owner-operators. Direct-to-consumer digital quoting engines bypass established broker relationships in the British Virgin Islands and Seychelles charter management segments. For Investors and Strategic Acquirers: The window for entry favors specialist underwriters with niche expertise in performance sailing vessels and custom-built craft. Long-term viability rests on parametric trigger innovation capability and climate risk actuarial talent acquisition. The signal to watch is hurricane severity trend data forcing fundamental repricing of catastrophic exposure in traditional indemnity structures.| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Product Launch | Automated payout mechanisms compress claims settlement cycles from months to days for hurricane-exposed Florida hulls. |
| Telematics Platform Integration | Satellite-connected engine monitoring enables usage-based premium structures for Great Lakes seasonal operators. |
| Environmental Compliance Certification | F-Gas Regulation HVAC upgrade pathways secure mandatory coverage minimums across Mediterranean charter fleets. |
| Acquisition of Specialist Surveyor Networks | Lloyd's Register-accredited certification pipelines in Southampton and Fort Lauderdale control valuation information asymmetry. |
| Geographic Expansion into Indonesia | Raja Ampat and Komodo cruising grounds lack developed marine insurance distribution for first-mover parametric products. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with marine underwriters, yacht brokerage principals, naval architect surveyors, and charter fleet operators. Lloyd's of London market returns, UK Financial Conduct Authority filings, and US state insurance commissioner rate filings provided carrier-level granularity. Bottom-up vessel count and premium per hull estimates triangulated against top-down market value reconstructions across the analysis window.
Data-stream reconciliation across policy type, vessel type, coverage options, and client type segmentation dimensions shaped the analytical framework. CAGRs were derived from trend extrapolation of hull value growth, fleet expansion rates, and regulatory mandate expansion timelines. Stochastic hurricane severity modeling and hybrid propulsion machinery breakdown frequency data informed scenario-weighted projections throughout the forecast period.
Inputs from Lloyd's market underwriters and Mediterranean charter fleet managers were available through the study window; gaps in Indonesian archipelago cruising ground loss data introduce uncertainty bands around parametric product pricing assumptions. Forecasts reflect documented assumptions regarding EU Green Deal maritime directive implementation pace and North Atlantic tropical cyclone severity trends. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Drone Insurance Market
Insurance
Saudi Arabia Travel Insurance Market
Insurance
Social Media Analytics-Based Insurance Market
Insurance
United Kingdom Health and Medical Insurance Market
Insurance
Umbrella Insurance Market
Insurance
Usage-Based Insurance for Automotive Market
Insurance
Group Health Insurance Market
Insurance
Mobile Phone Insurance Market
Insurance
Property and Casualty Insurance Market
Insurance
US Electronic Gadgets Insurance Market
Insurance
Commercial Cyber Insurance Market
Insurance
India Health Insurance Market
Insurance
Europe Mobile Phone Insurance Market
Insurance
France Liability Insurance Market
Insurance
US Long-Term Care Private Insurance Market
Insurance
Digital Monetary Insurance Market