
 Dental Insurance Market | 2026-2036
Dental Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Insurance Market Intelligence
Modular plan design is recalibrating buyer choice in dental insurance as carriers unbundle preventive, basic, and major coverage into mix-and-match tiers. Delta Dental leverages its massive provider network control to anchor state-level market presence. UnitedHealth Group sustains competitive pressure through integrated medical-dental benefit administration. Humana Inc. specializes in Medicare Advantage dental riders that extend its senior demographic reach.
Dental insurance is a risk-pooling financial product covering diagnostic, preventive, restorative, and prosthodontic services through pre-negotiated fee schedules or capitation contracts with licensed practitioners. Its primary commercial purpose is reducing out-of-pocket cost barriers to routine oral care while managing catastrophic dental expense exposure for individuals and employer groups. PPO plans dominate enrollment volume due to broader provider choice flexibility, while HMO structures concentrate margin pools through closed-network capitation. Preventive coverage represents the most mature tier with near-universal inclusion, whereas comprehensive plans integrating orthodontia and implants capture the fastest-growing premium segment.
The Affordable Care Act, state insurance commissioners, and ERISA fiduciary standards collectively shape product design, network adequacy requirements, and employer plan administration across the United States. OSHA bloodborne pathogen protocols and state-level dental board regulations further influence provider network credentialing and claims processing standards. Stakeholders must monitor Medicaid expansion ballot initiatives and Medicare dental benefit legislative proposals that could restructure the addressable market for commercial carriers.
Market Dynamics
The Affordable Care Act pediatric dental essential health benefit mandate is compressing plan design flexibility while employer-sponsored group plans expand coverage to part-time workers, creating simultaneous standardization and access pressures across the commercial dental insurance landscape.
Growth Catalysts
- Medicaid Expansion Ballot Initiatives:State-level voter-approved Medicaid expansions in holdout states are enlarging the subsidized dental coverage pool and creating new managed care contract opportunities for commercial carriers.
- Tele-diagnostics Integration:Remote oral health screening platforms are extending preventive care reach into rural and underserved urban census tracts, reducing geographic access barriers that previously suppressed enrollment.
- Employer Part-Time Eligibility Expansion:Large retail and hospitality employers are extending group dental benefits to variable-hour workforces, capturing previously uninsured hourly worker segments.
Market Restraints
- Provider Network Concentration:Delta Dental's state-level network dominance in 15 states creates credentialing bottlenecks and limits competitive plan differentiation for smaller carriers.
- Fee Schedule Compression:Capitation contract rates in closed-network HMO structures have stagnated below inflation-adjusted dental procedure cost growth, squeezing practitioner participation incentives.
- Orthodontia Cost Volatility:Clear aligner therapy and implant-supported prosthodontics carry high per-case variability that complicates actuarial pricing for comprehensive plan tiers.
Strategic Opportunities
- Medicare Dental Benefit Legislative Proposals:Congressional consideration of adding routine dental services to Medicare Part B would create a 65-million-member addressable market for standalone and supplemental dental products.
- Direct-to-Consumer Subscription Models:Monthly membership plans bypassing employer sponsorship are capturing gig-economy workers and early-career professionals outside traditional group channels.
- AI-Assisted Claims Adjudication:Machine learning radiograph analysis is accelerating prior authorization workflows and reducing fraudulent billing exposure in major restorative claims.
Industry Challenges
- Actuarial Talent Scarcity:Specialized dental actuaries with hybrid clinical-benefit expertise command premium compensation and limit carrier expansion velocity.
- Legacy Administration System Migration:Decades-old claims platforms require multimillion-dollar replacement cycles to support real-time eligibility verification and mobile member portals.
- Network Adequacy Compliance:State insurance commissioner travel-time standards for specialist access demand continuous provider recruitment in thin-market counties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Insurance Market |
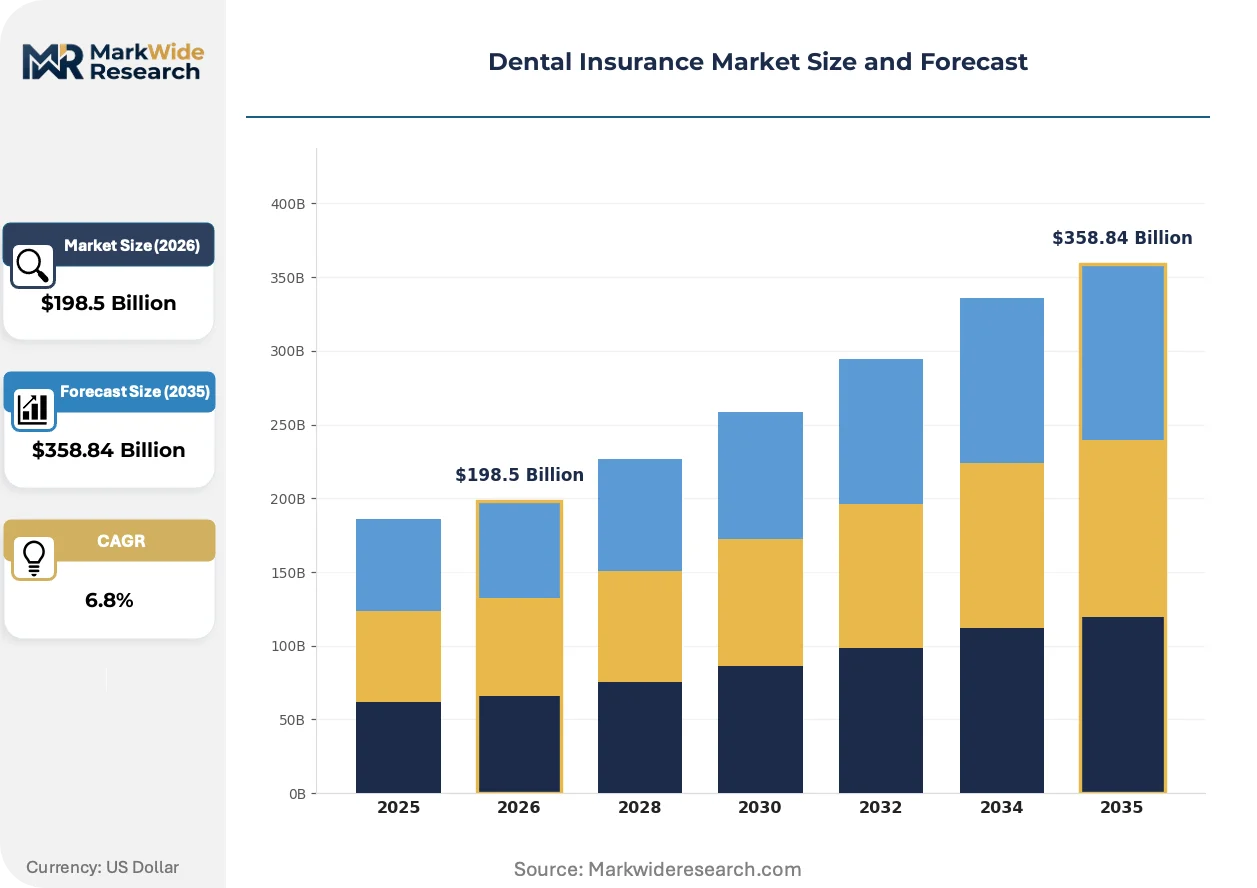
| Market Size in 2026 | $198.5 Billion |
| Market Size in 2035 | $358.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Plan Type: HMO, PPO, Indemnity, Discount Payment Model: Fee-for-Service, Capitation, Shared Responsibility, Preferred Provider Provider Network: Private Practice, Group Practice, Dental Spa, Hospital Coverage Level: Basic, Major, Preventive, Comprehensive |
| Companies Covered | MetLife Inc., Guardian Life Insurance Company of America, Delta Dental, Anthem Blue Cross Blue Shield, Sun Life Financial Inc., UnitedHealth Group, Humana Inc., DentaQuest, Cigna Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Insurance Market Strategic Shifts & Innovations
Digital health infrastructure and regulatory pressure are converging to reshape how dental benefits are priced, distributed, and consumed across employer, individual, and public payer segments.
Teledentistry platforms are decentralizing preventive care delivery by enabling asynchronous oral health consultations through smartphone imaging. Rural health clinics and federally qualified health centers are deploying these tools to triage patients before in-person visits. The technology is decentralizing geographic barriers that previously concentrated specialist access in metropolitan corridors.
OSHA bloodborne pathogen protocol updates are tightening credentialing documentation requirements for network dentists. Carrier compliance departments must verify annual training certifications across thousands of participating practitioners. Solo and small-group practices in Texas and Florida face the steepest administrative burden from these credentialing intensifications.
Subscription-based dental membership plans are displacing traditional insurance for uninsured middle-income households seeking predictable cost structures. Direct primary care dental practices in Colorado and Washington are piloting these models, bypassing carrier intermediaries entirely. Employer groups with 50-100 employees in the Mountain West show the highest willingness to substitute these arrangements for conventional PPO coverage.
Dental Insurance Market Segmentation
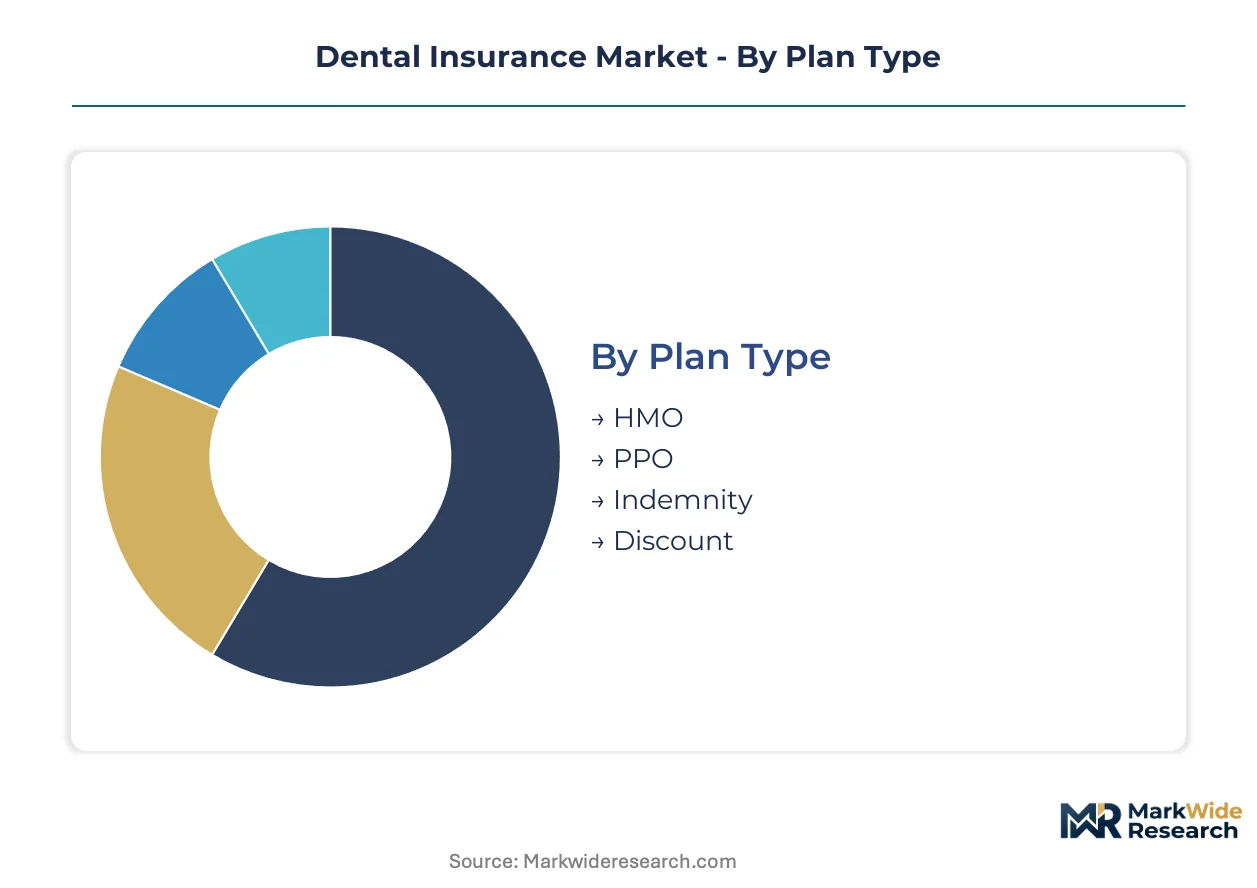
Dental insurance segmentation reveals how carriers calibrate risk pools, provider contracts, and member cost-sharing across distinct commercial configurations. Each dimension—plan design, reimbursement mechanics, delivery setting, and benefit depth—carries unique regulatory filing requirements and network adequacy obligations that shape market entry economics.
Plan Type:
OSHA network adequacy standards and state insurance commissioner mandates apply differentially across plan structures, with closed-network designs facing stricter credentialing documentation burdens than open-access alternatives.
- PPO:Preferred provider organizations negotiate discounted fee schedules with broad dentist networks while preserving member choice flexibility. Employer groups in Texas and Florida concentrate enrollment here, driven by workforce demands for out-of-network optionality.
- HMO:Health maintenance organizations lock members into capitated primary care dentists with specialist referrals required. Closed-network structures dominate Medicaid managed care contracts in California and New York, where state fiscal pressures favor predictable per-member-per-month costs.
- Indemnity:Traditional fee-for-service reimbursement without network restrictions carries higher premiums and member cost-sharing. Small professional employer groups in Illinois and Pennsylvania retain this structure for executive-tier benefits.
- Discount:Non-insurance membership programs provide negotiated rate access without risk pooling or claims adjudication. Uninsured households in Arizona and Colorado access these through direct-to-consumer marketing channels.
PPO sits at the top of the volume ranking, with Discount climbing the fastest.
Payment Model:
Reimbursement mechanics determine carrier cash flow timing, provider administrative burden, and fraud exposure profiles across the commercial dental landscape.
- Fee-for-Service:Itemized procedure codes trigger per-claim payment with embedded utilization review. Private practices in Ohio and Michigan prefer this model for revenue predictability.
- Capitation:Fixed monthly payments per enrolled member transfer utilization risk to participating dentists. Group practices in Florida and Texas accept capitation for Medicaid and Medicare Advantage dental riders.
- Preferred Provider:Tiered network participation rewards members with lower cost-sharing for in-network utilization. Large employers in Washington and Oregon structure benefits around this incentive alignment.
- Shared Responsibility:Blended models combine base capitation with supplemental fee-for-service for complex procedures. Dental spas in California and New York pilot these arrangements for cosmetic and implant services.
Fee-for-Service retains the largest premium volume, though Capitation is gaining share fastest in public payer segments.
Provider Network:
Delivery setting segmentation maps to distinct malpractice coverage requirements, HIPAA privacy protocol implementations, and OSHA bloodborne pathogen compliance documentation standards.
- Private Practice:Solo and small-group dental offices constitute the historical backbone of carrier networks. Rural counties in Georgia and Tennessee depend on these practitioners for network adequacy compliance.
- Group Practice:Multi-location dental organizations aggregate purchasing power and standardize clinical protocols. DSO-affiliated practices in Texas and Florida concentrate pediatric dental essential health benefit capacity.
- Dental Spa:Cosmetic-focused facilities bundle aesthetic dentistry with wellness amenities. Affluent suburban markets in California and Colorado generate out-of-network demand for these settings.
- Hospital:Academic medical centers and community hospitals house dental residency programs and emergency oral surgery capacity. Medicaid expansion states including Kentucky and West Virginia rely on hospital-based dentists for safety-net access.
Private Practice maintains the deepest network penetration, with Group Practice expanding most quickly through DSO consolidation.
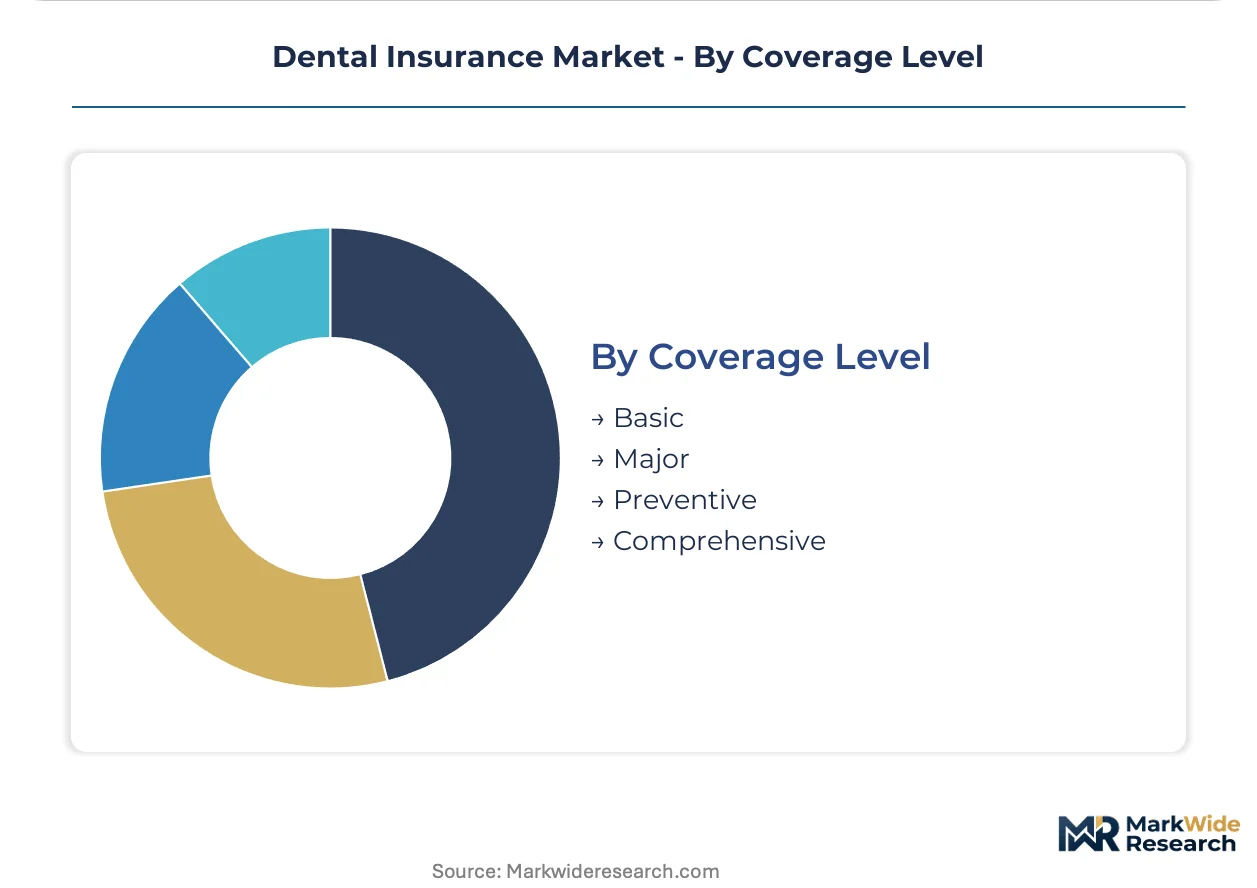
Coverage Level:
Benefit depth tiers align with actuarial pricing complexity, with comprehensive and major coverage requiring more sophisticated risk pooling than preventive-only designs.
- Preventive:Diagnostic and prophylactic services with minimal member cost-sharing dominate employer-sponsored enrollment. Near-universal inclusion in group plans reflects ACA pediatric dental mandate spillover effects.
- Comprehensive:Integrated preventive, basic, and major coverage with orthodontia and implant riders captures premium growth in Medicare Advantage and affluent individual markets.
- Basic:Restorative fillings and simple extractions occupy the middle tier with moderate coinsurance requirements. Mid-size employers in Pennsylvania and Ohio standardize on this cost-containment level.
- Major:Crowns, bridges, dentures, and oral surgery carry highest member cost-sharing and annual maximum limitations. Retiree populations in Arizona and Florida drive supplemental policy demand here.
Preventive commands the widest enrollment base, while Comprehensive posts the steepest expansion trajectory in senior demographic segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The dental insurance industry traces its commercial lineage to the United States, where employer-sponsored group coverage first scaled during the post-war benefits expansion of the 1950s and 1960s. This foundational model subsequently diffused to Canada and select European markets, though structural variation in healthcare financing produced divergent adoption patterns. Today, national regulatory frameworks and employer benefit customs shape distinct market architectures across concentrated geographies.
United States
Employer-sponsored group plans dominate commercial enrollment, with large retail and hospitality chains extending coverage to variable-hour workforces. The Affordable Care Act pediatric dental essential health benefit mandate compresses plan design flexibility while creating standardized coverage floors. Texas and Florida concentrate PPO enrollment volume due to workforce preferences for out-of-network optionality.
Germany
Statutory health insurance funds (Gesetzliche Krankenversicherung) provide baseline dental coverage, with supplemental private policies capturing premium growth among affluent households. The country's national pharmaceutical regulator oversees benefit design harmonization across sickness funds. Bavaria and Baden-Württemberg host the densest networks of private dental practices accepting supplemental coverage.
Japan
Employment-based health insurance societies (Kenkō Hoken Kumiai) incorporate dental benefits within unified medical coverage structures. METI guidelines influence administrative standardization across insurer IT platforms. The Kanto region surrounding Tokyo concentrates corporate headquarters and associated group dental contract administration.
United Kingdom
NHS dental services provide subsidized access, with private insurance capturing demand for cosmetic and specialist procedures outside public queues. The Care Quality Commission regulates provider standards across both sectors. London and the Southeast generate disproportionate private policy uptake among professional services employees.
Canada
Provincial health plans exclude routine dental care, leaving employer-sponsored benefits and individual policies as primary coverage mechanisms. Health Canada guidelines influence supplemental insurance product filing requirements. Ontario and Quebec concentrate group enrollment through financial services and technology sector employers.
Dental Insurance Market Key Industry Players
Premium-margin players sit above commodity-margin players across network control and administrative sophistication. The market structures around three tiers: national carriers with integrated medical-dental platforms, specialized dental insurers with state-level network dominance, and regional administrators serving Medicaid managed care contracts. Consolidation pressure intensifies as scale advantages in provider credentialing and claims automation widen performance dispersion. Two competitive moves dominate: acquisition of dental service organizations to secure captive provider capacity, and deployment of AI-assisted adjudication to compress administrative expense ratios.
Among specialized dental insurers, Delta Dental and DentaQuest exemplify distinct archetypes. Delta Dental occupies a position defined by state-level network control and nonprofit mutual structures. DentaQuest represents the Medicaid-centric administrator model, anchoring public payer contract concentration. UnitedHealth Group and Cigna Group sit within the integrated medical-dental tier, leveraging cross-selling infrastructure and unified member portals. These four entities collectively illustrate the strategic segmentation governing competitive positioning.
| Leading Market Players |
|---|
| MetLife Inc. |
| Guardian Life Insurance Company of America |
| Delta Dental |
| Anthem Blue Cross Blue Shield |
| Sun Life Financial Inc. |
| UnitedHealth Group |
| Humana Inc. |
| DentaQuest |
| Cigna Group |
| Others |
Cost & Logistics Intelligence
Large employer groups in Texas and Florida anchor pricing power through PPO plan demand, forcing carriers to structure premiums around out-of-network optionality rather than cost containment alone. This buyer concentration compresses margin pools for smaller carriers unable to match Delta Dental's network scale.
Pricing Analysis
Three-tier pricing structure across comprehensive, basic, and preventive coverage levels dominates employer-sponsored enrollment, with orthodontia and implant riders commanding premium positioning. Price differentiation hinges on network breadth and annual maximum benefit thresholds. Pricing pressure stems from fee schedule compression in Medicaid managed care contracts. Small-group employers in the Mountain West exhibit highest price sensitivity, while Medicare Advantage dental riders face least elasticity due to demographic necessity.
Supply Chain Analysis
Provider network capacity rests on solo and small-group dental practices concentrated in Georgia, Tennessee, and rural Texas counties. Credentialing documentation and OSHA bloodborne pathogen compliance requirements feed administrative cost structures. Single-source vulnerability concentrates in Delta Dental's state-level network dominance across fifteen states. Distribution runs through employer-sponsored group channels, direct-to-consumer platforms, and Medicaid managed care administrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
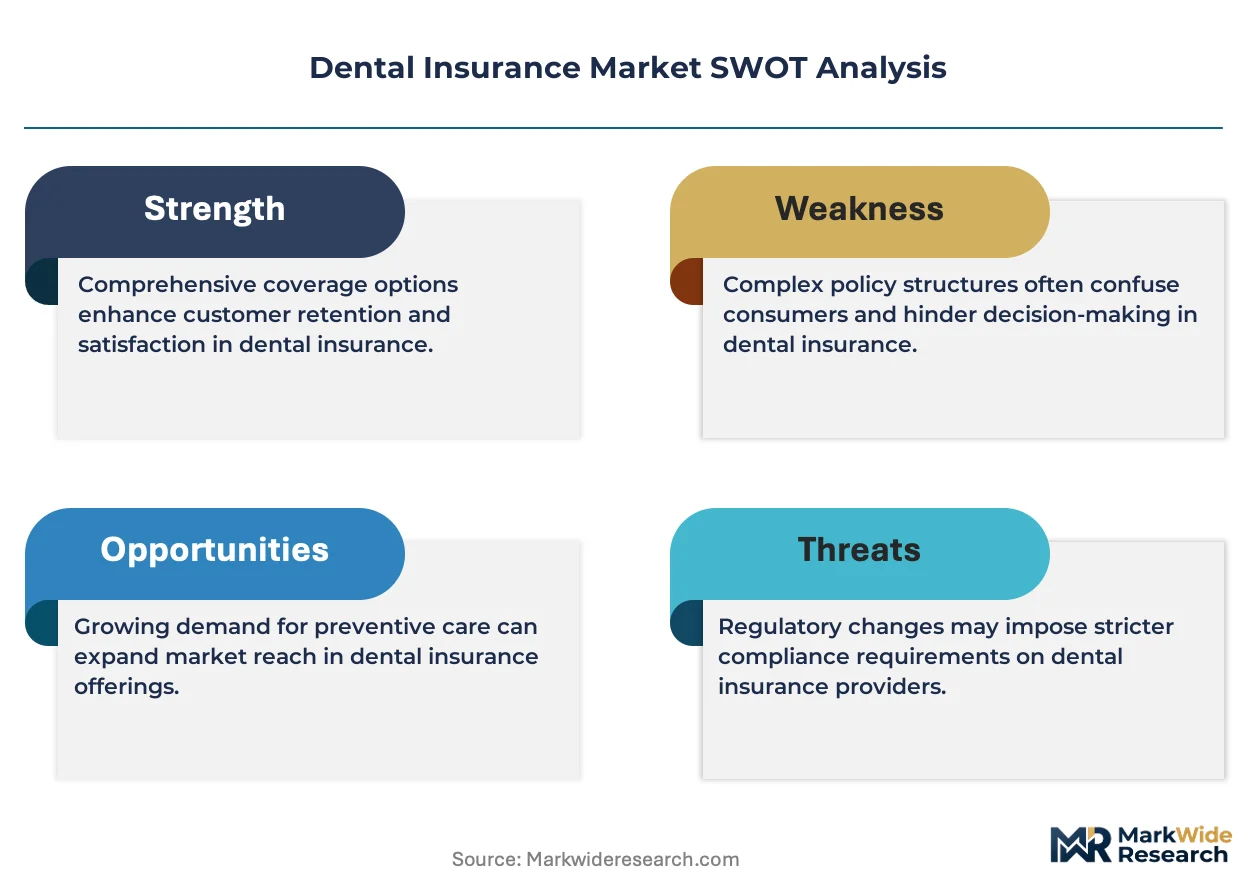
The dental insurance market functions as a regulatory compounder, with the Affordable Care Act pediatric dental essential health benefit mandate permanently expanding the addressable enrollment base and standardizing coverage floors.
For Market Incumbents: Acquire dental service organizations to secure captive provider capacity and bypass credentialing bottlenecks. Consolidate administrative platforms to compress expense ratios against AI-assisted adjudication threats. Build backward integration into telediagnostics infrastructure to capture preventive care delivery. For New Entrants and Emerging Players: Enter via direct-to-consumer subscription models targeting gig-economy workers and early-career professionals outside employer channels. White-space concentration sits in Medicare Advantage dental riders for the 65-million-member senior demographic. Deploy narrow-network HMO structures with capitation contracts to undercut PPO pricing. For Investors and Strategic Acquirers: Integrated medical-dental carriers are the most active acquirer in this space, consolidating specialized dental insurers for cross-selling infrastructure. Long-term viability favors carriers with state-level network control and Medicaid managed care contract concentration. Watch Medicare dental benefit legislative proposals as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Claims Adjudication | Machine learning radiograph analysis accelerates prior authorization workflows and reduces fraudulent billing exposure. |
| DSO Acquisition | Captive provider capacity secures network adequacy compliance and reduces recruitment costs in thin-market counties. |
| Teledentistry Platform Integration | Remote oral health screening extends preventive care reach into rural and underserved urban census tracts. |
| Medicare Advantage Dental Rider Expansion | Senior demographic reach captures premium growth in the fastest-expanding coverage tier. |
| Direct-to-Consumer Subscription Launch | Monthly membership plans bypass employer sponsorship and capture uninsured middle-income households. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined through structured interviews with dental carrier actuaries, provider network directors, state insurance commissioners, and employer benefits managers. Secondary validation draws from CMS Medicare data, state Medicaid managed care contract filings, NAIC regulatory submissions, and employer-sponsored benefits survey databases. Bottom-up enrollment modeling triangulates against top-down premium pool estimates.
Granularity-level modeling disaggregates projections by plan type, payment model, provider network configuration, and coverage depth tier across the analysis window. CAGRs derive from historical enrollment velocity, premium rate filing trends, and demographic shift assumptions. Forecast inputs incorporate Medicaid expansion ballot initiative outcomes and Medicare dental benefit legislative probability assessments.
Inputs from carrier rate filings and state regulatory databases were available through the study window; gaps in real-time enrollment disclosures introduce uncertainty bands around quarterly trajectory assumptions. Forecasts reflect documented assumptions regarding network adequacy compliance costs and actuarial talent scarcity constraints. A small set of named triggers—Medicare dental benefit legislation, Medicaid expansion ballot results, and AI adjudication regulatory guidance—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Auto Compulsory Insurance Market
Insurance
Asia-Pacific AI in Insurance Market
Insurance
US Homeowner's Insurance Market
Insurance
Earthquake Insurance Market
Insurance
Europe Online Insurance Market
Insurance
Agricultural Insurance Market
Insurance
France Car Insurance Market
Insurance
Cybersecurity Insurance Market
Insurance
Vietnam Private Health Insurance Market
Insurance
Green Insurance Market
Insurance
Singapore Property and Casualty Insurance Market
Insurance
Microinsurance Market
Insurance
Agriculture Reinsurance Market
Insurance
Japan Liability Insurance Market
Insurance
Single Trip Travel Insurance Market
Insurance
India Travel Insurance Market