
 India Connector Market | 2026-2036
India Connector Market Size, Share, and Industry Trends Forecast 2026-2036
India Connector Market Insights
India's PLI scheme for telecom and networking products is expanding the addressable base for domestic connector procurement. TE Connectivity India leverages its global R&D footprint to localize high-speed backhaul solutions for Indian tower operators. Amphenol Interconnect India anchors its position through deep relationships with defense PSU contractors requiring MIL-spec circular connectors. Molex India specializes in board-to-board interconnects serving Bengaluru-based OEMs in consumer electronics and server assembly.
Connectors are electromechanical devices engineered to join electrical circuits, typically specified by contact pitch, current rating, insertion force, and environmental sealing against dust or moisture ingress. Their primary purpose is to enable reliable signal and power transmission while permitting field assembly, maintenance, and modular equipment design. Fiber optic and USB product types command premium positioning as data center builds accelerate across Hyderabad and Noida, while D-Sub interfaces occupy mature industrial automation channels with stable but slower expansion. Surface mount technology leads volume production for consumer electronics, though wire-to-board configurations sustain stronger margins in aerospace and instrumentation applications where vibration resistance justifies higher engineering overhead.
BIS certification requirements and TRAI mandates on telecom equipment quality shape product qualification timelines and testing expenditures for connector suppliers seeking public network contracts. CDSCO oversight extends to medical device interconnects, adding a compliance layer for manufacturers targeting diagnostic equipment makers in Mumbai and Delhi. The CEA's electrical safety standards further govern power connector specifications for industrial and renewable energy installations. Stakeholders must weigh domestic certification investments against the revenue pull from India's expanding electronics manufacturing base and infrastructure digitization programs.
Market Dynamics
India's connector market is being restructured by the government's Production Linked Incentive scheme, which is redirecting procurement from import-dependent supply chains toward domestic manufacturing clusters in Tamil Nadu and Karnataka.
Growth Catalysts
- PLI Scheme Expansion:The government's production-linked incentive framework for telecom and networking products is mandating local value addition, compelling OEMs to source connectors from certified domestic suppliers rather than offshore channels.
- 5G Backhaul Buildout:Telecom service providers are deploying massive fiber optic infrastructure across Maharashtra and Gujarat, creating sustained demand for high-density optical connectors and weatherproof outdoor assemblies.
- BIS Certification Mandates:Tightened Bureau of Indian Standards reliability norms for telecommunications infrastructure are disqualifying uncertified imports and elevating qualified domestic manufacturers into preferred vendor status.
Market Restraints
- Raw Material Concentration:Specialty copper alloys and high-performance thermoplastics for connector housings remain concentrated in East Asian supply bases, exposing Indian assemblers to currency volatility and shipping disruptions.
- Capital Equipment Intensity:Precision stamping and automated insertion machinery for micro-miniature connectors require substantial upfront investment, constraining capacity expansion among mid-tier domestic players.
- Technical Substitution Risk:Wireless charging and contactless power transfer technologies are displacing physical power connectors in consumer electronics applications, compressing addressable volume in high-volume segments.
Strategic Opportunities
- Defense Localization Mandates:Offset requirements and indigenization targets for defense PSUs are creating dedicated demand channels for MIL-spec circular connectors with multi-year procurement visibility.
- Medical Device Interconnects:CDSCO oversight of diagnostic equipment is expanding the compliance-addressable market for sterilizable, high-reliability connectors serving Mumbai and Delhi healthcare manufacturers.
- Renewable Energy Integration:CEA electrical safety standards for solar and wind installations are standardizing power connector specifications, opening specification windows for suppliers with certified industrial product lines.
Industry Challenges
- Precision Manufacturing Talent Scarcity:Tooling design and micro-molding process engineering expertise remains concentrated in legacy industrial regions, forcing Bengaluru and Chennai operators to recruit from distant talent pools or invest in extended training programs.
- Multi-Regulatory Certification Burden:BIS telecom norms, CDSCO medical device requirements, and CEA electrical safety standards operate on non-harmonized testing protocols, extending product qualification timelines and multiplying laboratory expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Connector Market |
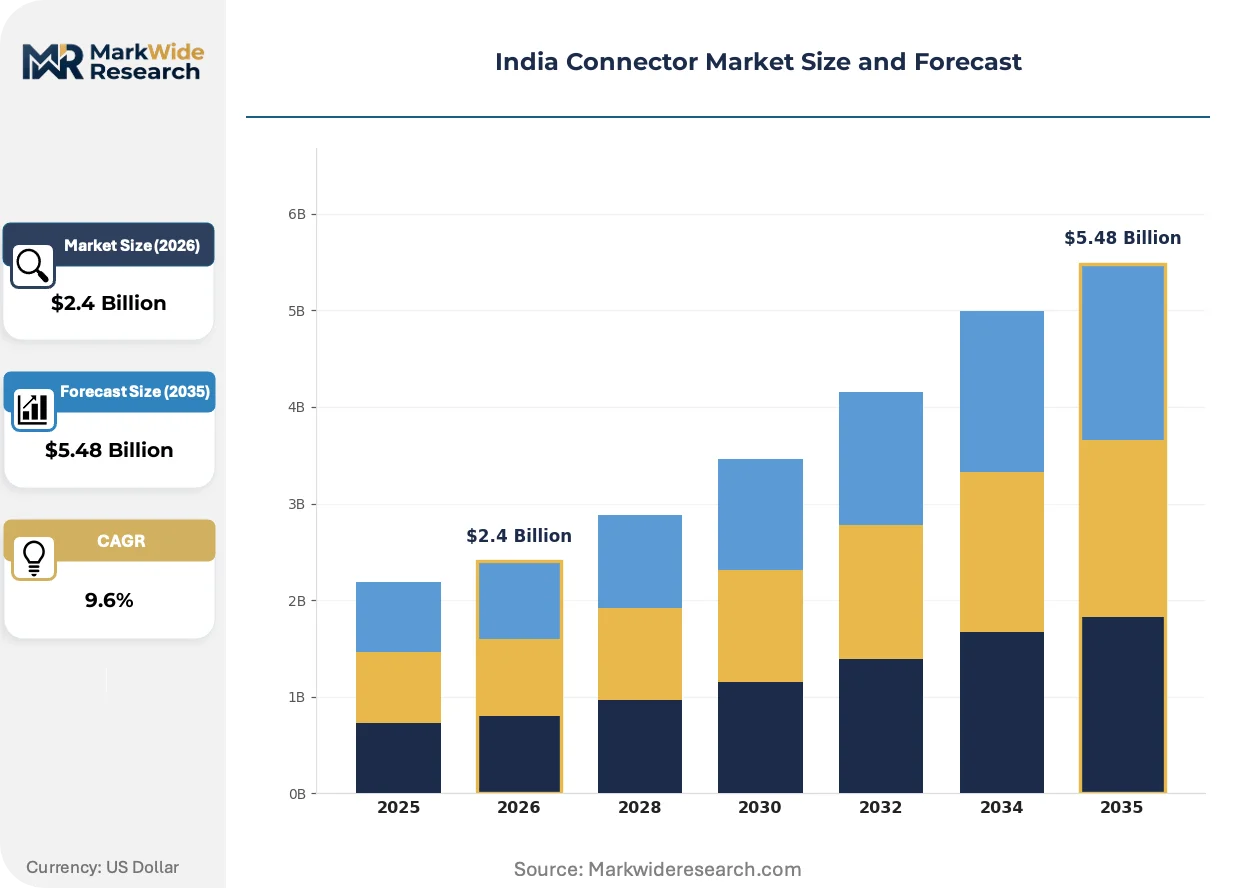
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.48 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coaxial, Ethernet, Fiber Optic, USB, HDMI, D-Sub Technology: Surface Mount, Through Hole, Board-to-Board, Wire-to-Board, Circular, Modular Application: Telecommunication, Consumer Electronics, Data Centers, Aerospace, Defense, Instrumentation End User: Telecom Service Providers, OEMs, System Integrators, IT Companies, Manufacturing Units |
| Companies Covered | TE Connectivity India Pvt. Ltd., Amphenol Interconnect India Pvt. Ltd., Molex India Pvt. Ltd., HARTING India Pvt. Ltd., Hitech India, Jetronics India, Allied Electronics, Wago Ltd, Pricol Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Connector Market Trends and Innovations
Active developments across materials science, regulatory frameworks, and procurement architectures are compressing product lifecycles and reconfiguring competitive positioning in India's connector market.
High-speed backhaul connectors are integrating silicon photonics transceivers directly into the connector housing, eliminating separate optical transponder assemblies. Tower operators in Hyderabad and Noida are specifying these integrated assemblies for 5G fronthaul links. This convergence is integrating optical and electrical functions into single-receptacle designs, reducing installation labor and failure points in outdoor cell sites.
TRAI mandates on telecom equipment quality are requiring documented traceability and accelerated aging testing for all connectors deployed in public networks. The Bureau of Indian Standards has aligned its reliability testing protocols with these mandates, extending qualification timelines but creating barriers against uncertified competitors. Southern manufacturing corridors around Chennai are responding by building captive testing laboratories to compress certification cycles.
Electronics system integrators are consolidating vendor relationships around full-interconnect solution providers rather than discrete component sourcing. Bengaluru-based OEMs in server assembly and consumer electronics are awarding multi-year framework contracts to suppliers with integrated board-to-board, wire-to-board, and cable assembly capabilities. This preference shift is most visible in Karnataka's electronics manufacturing clusters, where procurement teams prioritize single-source accountability over component-level cost optimization.
India Connector Market Segmentation
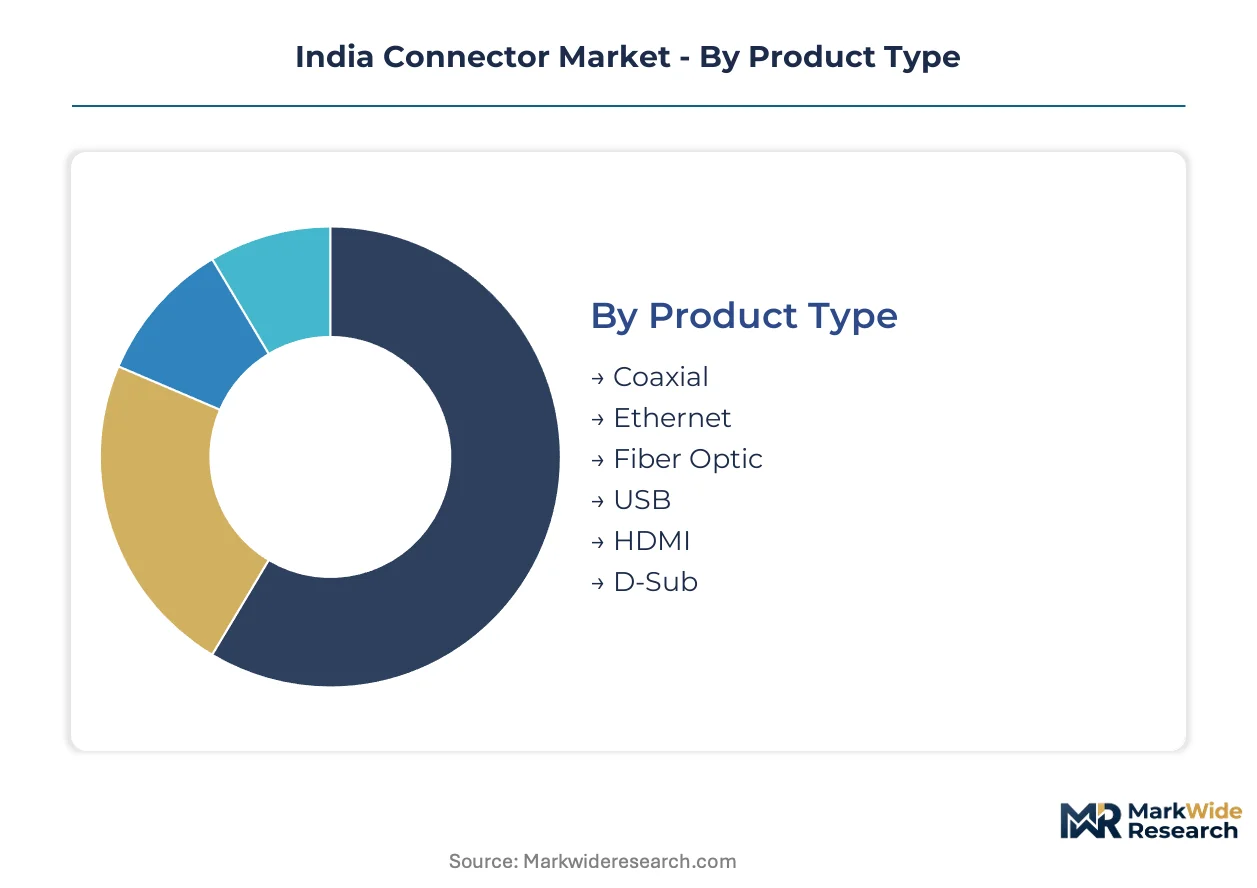
Connector procurement in India diverges sharply across end-use environments, with telecom infrastructure demanding weatherproof optical assemblies while consumer electronics prioritize miniaturized surface-mount formats. Understanding these segment boundaries clarifies where certification investments yield vendor preference and where scale economies dominate supplier selection.
Product Type:
Buyers prioritize signal integrity specifications and environmental sealing ratings when selecting connector families for deployment.
- Fiber Optic:These assemblies transmit data via glass or plastic fiber cores with minimal signal loss over distance. Demand concentrates in Maharashtra and Gujarat where Reliance Jio and Bharti Airtel are densifying 5G fronthaul networks, with TRAI quality mandates requiring documented traceability for every deployed unit.
- USB:Universal Serial Bus connectors standardize peripheral connectivity across consumer and industrial devices. Bengaluru-based OEMs in server assembly are specifying USB-C with power delivery for next-generation rack equipment, driven by convergence toward single-cable data and power architectures.
- Coaxial:Cylindrical connectors with concentric conductor geometry maintain impedance matching for RF applications.
- Ethernet:RJ45 and industrial Ethernet formats dominate wired networking infrastructure.
- HDMI:High-definition multimedia interfaces carry uncompressed video and audio in consumer displays.
- D-Sub:D-shaped metal shield connectors persist in legacy industrial automation and instrumentation channels.
Fiber optic leads on scale; USB leads on momentum.
Technology:
Manufacturing process selection hinges on assembly automation compatibility and field-service accessibility requirements.
- Surface Mount:These connectors solder directly to PCB pads without through-hole drilling, enabling high-density automated assembly. Consumer electronics manufacturers in Tamil Nadu's Sriperumbudur cluster specify micro-miniature surface-mount headers for smartphone motherboards, constrained by precision stamping equipment availability.
- Wire-to-Board:Configurations join discrete conductors to PCB terminations with crimp or insulation-displacement contacts. Aerospace and instrumentation applications in Hyderabad favor these for vibration resistance, with BIS certification extending qualification timelines but protecting qualified suppliers from import competition.
- Through Hole:Leads pass through PCB holes for mechanical stability in high-stress environments.
- Board-to-Board:Stacking connectors link parallel PCBs in compact electronic assemblies.
- Circular:Cylindrical mating interfaces seal against moisture and dust ingress.
- Modular:Configurable contact arrangements adapt to varying pin-count requirements.
Surface mount dominates volume; wire-to-board commands margin premiums.
Application:
End-use environment dictates reliability grade, with outdoor telecom and military applications requiring extended temperature and sealing validation.
- Telecommunication:Connectors for cellular infrastructure must survive temperature cycling, UV exposure, and humidity. Tower operators across Maharashtra specify IP67-rated optical connectors for 5G backhaul, with BIS reliability norms disqualifying uncertified imports from public network contracts.
- Defense:MIL-spec circular connectors with bayonet or threaded coupling serve weapons platforms and communications gear. Offset requirements and indigenization targets for defense PSUs create multi-year procurement visibility for qualified domestic manufacturers.
- Consumer Electronics:High-volume, cost-optimized interconnects for smartphones, laptops, and wearables.
- Data Centers:High-speed backhaul and power distribution connectors for server and storage infrastructure.
- Aerospace:Lightweight, high-reliability assemblies for avionics and satellite systems.
- Instrumentation:Precision connectors for test and measurement equipment.
Telecommunication anchors procurement volume; defense offers steadiest contract visibility.
End User:
Purchasing authority varies between centralized procurement teams at telecom operators and distributed engineering selection at OEMs.
- Telecom Service Providers:Reliance Jio, Bharti Airtel, and Vodafone Idea operate centralized sourcing for network infrastructure. Their 5G deployment schedules across Gujarat and Maharashtra are creating sustained demand for fiber optic and power connectors with multi-year framework agreements.
- System Integrators:Electronics assembly houses in Bengaluru and Chennai consolidate vendor relationships around full-interconnect solution providers rather than discrete component sourcing, awarding multi-year contracts to suppliers with integrated capabilities.
- OEMs:Original equipment manufacturers specify connectors during product design.
- IT Companies:Enterprise hardware purchasers for data center and networking equipment.
- Manufacturing Units:Industrial automation and process control equipment builders.
Telecom service providers drive largest individual contracts; system integrators are consolidating supplier relationships fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Connector manufacturing in India traces its industrial lineage to the 1980s electronics policy era, when state-led investments established Tamil Nadu and Karnataka as precision component hubs. These southern corridors remain the geographic anchor for domestic production.
Maharashtra
Telecom infrastructure deployment drives connector consumption across Mumbai and Pune metropolitan zones. TRAI mandates on equipment quality require BIS certification for all public network components. Tower operators in Maharashtra specify IP67-rated optical assemblies for 5G fronthaul links.
Gujarat
Reliance Jio's fiber densification programs create sustained procurement volume for weatherproof outdoor connectors. The state's electronics manufacturing policy offers capital subsidies for precision stamping equipment. Gandhinagar-based system integrators consolidate vendor relationships around full-interconnect solution providers.
Karnataka
Bengaluru's server assembly and consumer electronics OEMs anchor demand for micro-miniature board-to-board interconnects. CDSCO oversight extends to medical device interconnects for diagnostic equipment manufacturers. Electronics City and Whitefield clusters host captive testing laboratories to compress BIS certification cycles.
Tamil Nadu
Sriperumbudur's smartphone manufacturing ecosystem consumes high-volume surface-mount headers for motherboard assembly. The PLI scheme for telecom products mandates local value addition, redirecting procurement toward certified domestic suppliers. Chennai-based operators recruit precision tooling talent from distant industrial regions.
Telangana
Data center construction across Hyderabad accelerates demand for high-speed backhaul connectors with integrated silicon photonics. CEA electrical safety standards govern power connector specifications for renewable energy installations. The city's electronics manufacturing cluster attracts framework contracts from multi-year procurement programs.
India Connector Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification grade and application complexity, with MIL-spec and medical-grade suppliers commanding pricing power over standard industrial formats. The vendor base organizes into three strategic archetypes: global majors with localized R&D footprints, defense-focused specialists with PSU relationships, and domestic scale players serving consumer electronics. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as mid-tier operators seek testing laboratory investments and technology licensing arrangements.
Among global majors with Indian subsidiaries, TE Connectivity India Pvt. Ltd., Amphenol Interconnect India Pvt. Ltd., and Molex India Pvt. Ltd. occupy positions across the premium-tier spectrum. These entities exemplify the archetype of multinational fabricators leveraging global R&D infrastructure to localize high-reliability solutions. Their presence anchors the competitive structure, with each representing distinct specialization vectors within the broader connector ecosystem.
| Leading Market Players |
|---|
| TE Connectivity India Pvt. Ltd. |
| Amphenol Interconnect India Pvt. Ltd. |
| Molex India Pvt. Ltd. |
| HARTING India Pvt. Ltd. |
| Hitech India |
| Jetronics India |
| Allied Electronics |
| Wago Ltd |
| Pricol Limited |
| Others |
Pricing and Supply Chain Analysis
Silicon photonics integration into connector housings is compressing assembly labor costs while concentrating procurement power among tower operators in Hyderabad and Noida who specify these integrated assemblies. This technology shift simultaneously elevates engineering overhead requirements and disqualifies smaller domestic assemblers from premium-tier contracts, reshaping margin distribution across the supplier base.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates MIL-spec circular connectors for defense PSUs from industrial-grade formats and high-volume consumer electronics headers. Price differentiation rests on BIS certification grade and volume scale, with qualified suppliers capturing 40-60% premiums over uncertified imports. Cost compression in consumer electronics surface-mount segments is intensifying because wireless charging substitution erodes physical connector volumes. Telecom service providers exhibit lowest price sensitivity due to multi-year framework agreements and reliability mandates, while smartphone OEMs in Tamil Nadu's Sriperumbudur cluster drive hardest bargain negotiations.
Supply Chain Analysis
BIS certification gating and TRAI quality mandates extend qualification timelines, protecting qualified domestic manufacturers from import competition but constraining supplier base expansion. Specialty copper alloys and high-performance thermoplastics draw from concentrated East Asian supply bases in China, Japan, and South Korea, exposing Indian assemblers to currency volatility and shipping disruptions. Single-source vulnerability persists for precision stamping equipment and automated insertion machinery. Distribution runs through direct procurement channels at telecom operators and consolidated vendor relationships at Bengaluru-based system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
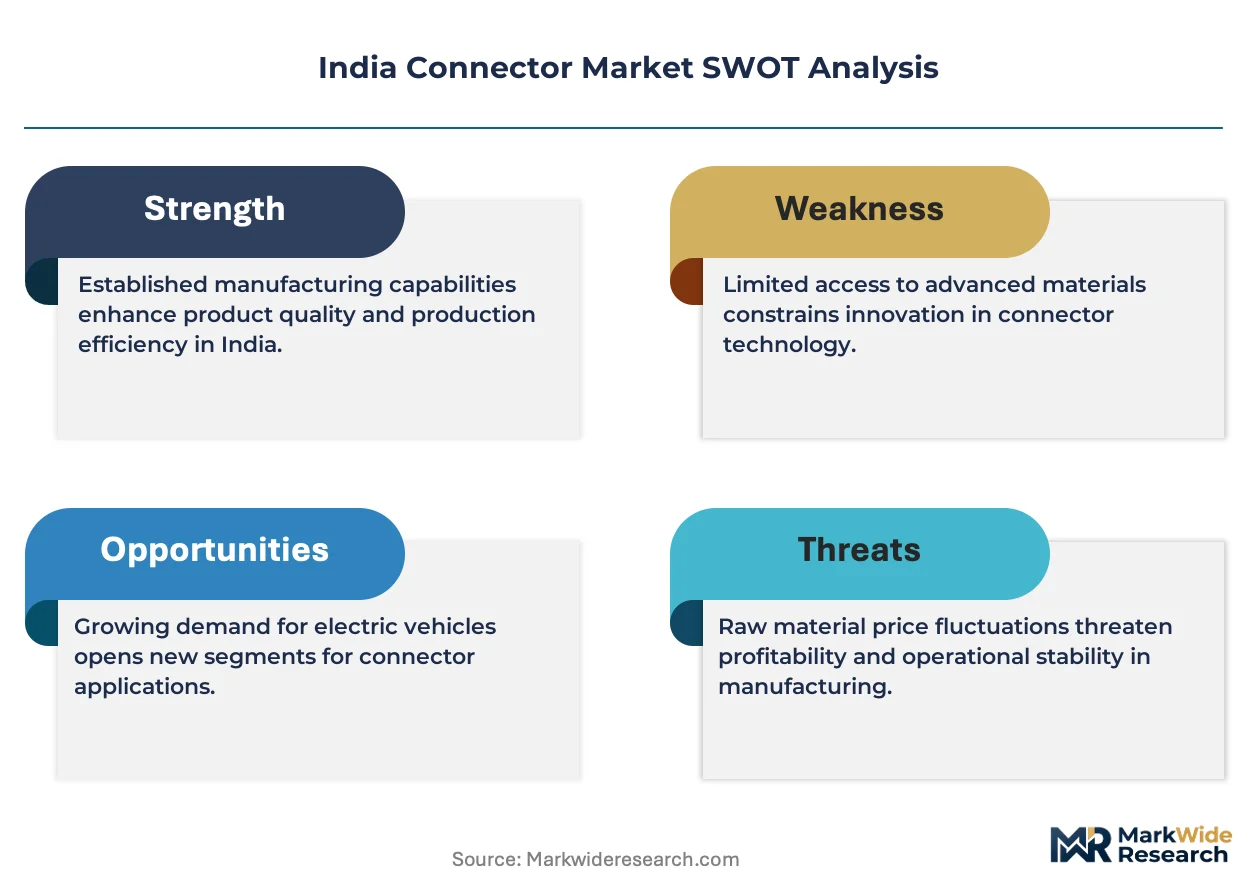
The India connector market functions as a regulatory compounder where BIS certification mandates and PLI scheme localization requirements continuously expand the addressable base for qualified domestic suppliers. TRAI equipment quality mandates represent the most significant demand catalyst, creating sustained procurement visibility for certified manufacturers.
For Market Incumbents: Anticipate wireless charging substitution in consumer electronics by deepening MIL-spec and medical-grade connector portfolios where certification barriers protect pricing power. Invest in captive testing laboratories across southern manufacturing corridors to compress BIS certification cycles and defend against emerging domestic scale players. Prioritize framework contract renewals with Reliance Jio and Bharti Airtel before 5G backhaul deployment peaks.
For New Entrants and Emerging Players: Defense PSU contractors with indigenization mandates represent the most penetrable buyer archetype, offering multi-year procurement visibility offsetting upfront certification investments. Target renewable energy power connector specifications under CEA electrical safety standards, where standardization creates specification windows for new qualified entrants. Pursue technology licensing arrangements with East Asian precision equipment manufacturers to circumvent capital intensity constraints.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier domestic assemblers lacking captive testing infrastructure but holding BIS certifications and established PSU relationships. Long-term viability over a 5-10 year window hinges on PLI scheme extension and defense localization mandate durability. Monitor TRAI enforcement intensity on telecom equipment traceability as the primary inflection signal for premium-tier supplier pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Testing Laboratory Investment | Compresses BIS certification cycles for telecom and medical device connectors in Chennai and Bengaluru clusters. |
| Defense PSU Framework Contract | Secures multi-year procurement visibility for MIL-spec circular connectors under indigenization mandates. |
| Silicon Photonics Licensing Agreement | Enables domestic production of integrated optical-electrical assemblies for 5G fronthaul specifications. |
| Precision Stamping Capacity Expansion | Addresses equipment bottlenecks constraining micro-miniature connector output for consumer electronics OEMs. |
| Renewable Energy Certification Program | Qualifies industrial power connectors under CEA standards for solar and wind installation procurement. |
Research Methodology
Multiple input streams — primary interviews with connector procurement managers at telecom operators, regulatory affairs leads at BIS and CDSCO, and plant engineers at precision stamping facilities — were reconciled against secondary validation from TRAI equipment quality circulars, BIS certification databases, and PLI scheme administrative records. Bottom-up and top-down triangulation cross-referenced vendor shipment data with tower deployment schedules across Maharashtra and Gujarat.
Historical volume trajectories were cross-referenced against panel input from electronics system integrators in Bengaluru and defense PSU procurement officers to anchor projections across the modeling period. Segmentation dimensions modeled include product type, manufacturing technology, application environment, and end-user purchasing authority. CAGRs were derived from trend extrapolation adjusted for regulatory milestone impacts and substitution technology penetration curves. Industry-specific forecast inputs incorporated 5G backhaul deployment density and defense offset fulfillment schedules.
Underlying measurement precision varies by segment; fiber optic and MIL-spec connector categories carry tighter precision than high-volume consumer electronics formats due to documented procurement visibility. Forecasts reflect assumptions regarding PLI scheme continuity, BIS enforcement intensity, and East Asian raw material supply stability. A model refresh is warranted upon material change in TRAI equipment quality mandate scope or defense indigenization target acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
Hazardous Location Connectors Market
Connectors
Global Cables and Connector Market
Connectors
Magnetic Connector Market
Connectors
Underwater Mate Connectors Market
Connectors
Connector Kits Market
Connectors
Connector Adapter Kits Market
Connectors
Heavy-Duty Connector Market
Connectors
Global Fiber Optic Connectors Market
Connectors
5G Connector Market
Connectors
Japan Connector Market
Connectors
DIN Connectors Market
Connectors
Filtered Connectors Market
Connectors
Circular Connectors Market
Connectors
PCI-E Connectors Market
Connectors
High-Reliability Connectors Market
Connectors
Press Fit Connector Market