
 Press Fit Connector Market | 2026-2036
Press Fit Connector Market Size, Share, and Industry Trends Forecast 2026-2036
Press Fit Connector Market Outlook
China's Jiangsu province is tilting toward press fit connector capacity expansion for electric vehicle powertrain modules. TE Connectivity leverages vertical integration across copper alloy sourcing and precision stamping to sustain cost discipline in high-volume automotive contracts. Amphenol Corporation anchors North American supply through captive plating facilities serving telecommunications infrastructure builds. Fujitsu Limited dominates Japanese domestic demand for high-density backplane connectors in server and storage systems.
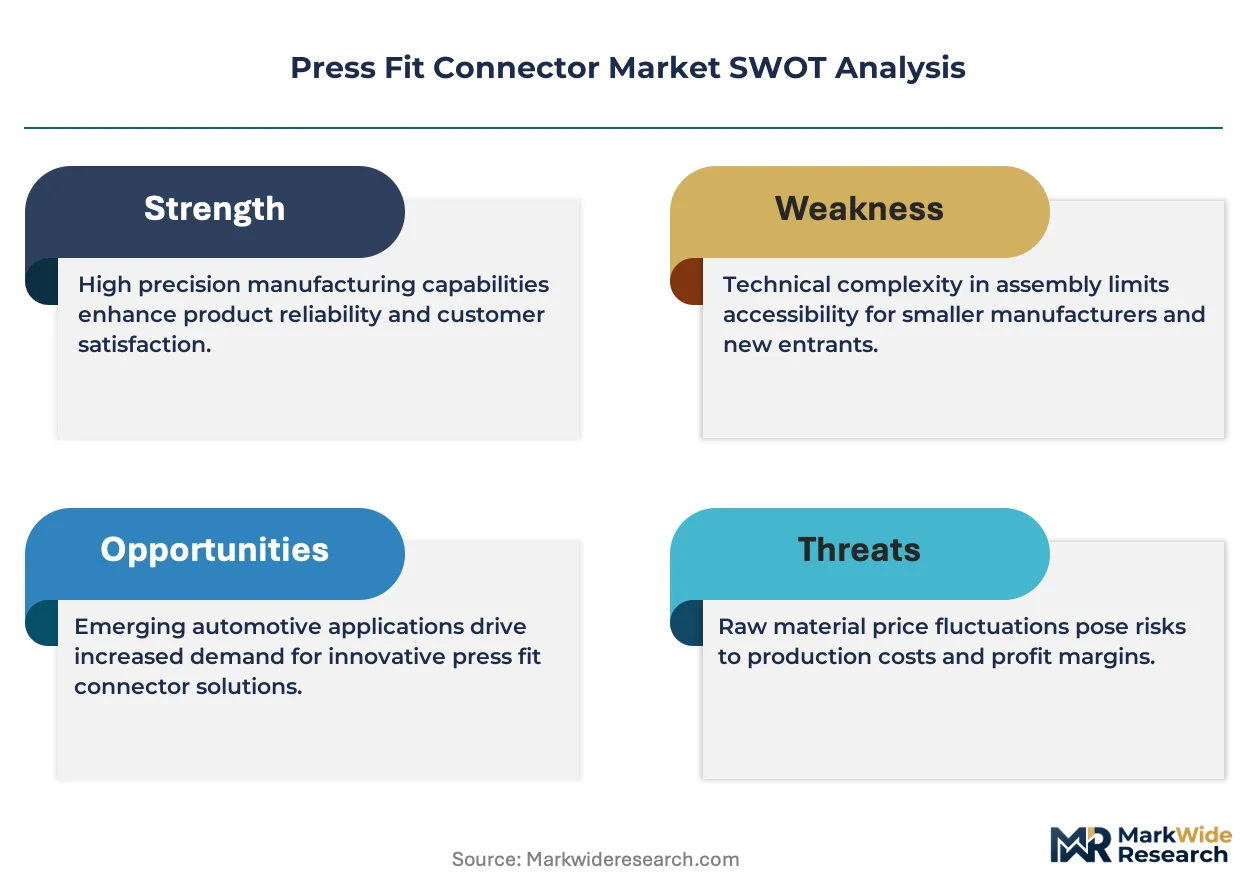
A press fit connector employs a compliant pin terminal engineered for insertion into plated through-holes without solder, achieving electrical continuity through mechanical interference fit with typical insertion forces of 30-120 newtons per pin depending on compliant section geometry. The primary industrial purpose centers on eliminating thermal solder processes while improving reworkability and vibration resistance in high-reliability assemblies. Signal connectors lead unit volume across consumer electronics and telecommunications applications where density and cost sensitivity shape procurement decisions. High-density connectors represent the fastest-expanding category as data center backplanes migrate toward 112 Gbps PAM4 signaling architectures demanding tighter pitch arrays. Copper material grades command premium positioning due to conductivity requirements in power connector segments serving electric vehicle battery management systems.
The US EPA oversees hazardous substance restrictions affecting plating chemistries in connector manufacturing, while REACH compliance in Europe mandates substance disclosure across supply chains for electronics components sold into EU member states. China's GB standards and MIIT certification requirements govern electromagnetic compatibility testing for press fit assemblies deployed in domestic telecommunications infrastructure. Stakeholders must monitor evolving RoHS exemption timelines and regional content thresholds as these determine qualification pathways and factory location decisions across the forecast horizon.
Market Dynamics
Automotive electrification programs are compressing qualification timelines for high-current press fit interconnects, forcing suppliers to accelerate plating chemistry validation and compliant pin geometry iteration cycles.
Growth Catalysts
- EU REACH substance disclosure mandates:RoHS exemption timelines for lead-free alternatives are redirecting procurement toward compliant press fit architectures in German automotive powertrains.
- Copper alloy conductivity thresholds:Battery management systems in electric vehicles specify oxygen-free copper grades that favor mechanical interference fits over soldered joints for thermal cycling resilience.
- Jiangsu province capacity expansion:Chinese electric vehicle module assembly lines are absorbing dedicated press fit connector output for domestic powertrain integration.
Market Restraints
- Plated through-hole pitch limitations:Sub-0.8mm pitch arrays encounter insertion force variance that degrades signal integrity in 112 Gbps backplane applications.
- High-purity copper concentrate supply:Chilean and Peruvian mining output volatility transmits directly to connector material cost structures.
- Compliant pin rework complexity:Extraction damage to PCB barrels limits field repairability and elevates total cost of ownership in telecommunications infrastructure.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Domestic semiconductor packaging incentives are opening qualification pathways for press fit assembly equipment suppliers.
- Optical-electrical hybrid backplanes:Convergence of silicon photonics with copper signaling creates demand for mixed-technology press fit zones in hyperscale data centers.
- Direct OEM contracting models:Automotive tier-1 suppliers are bypassing distribution to negotiate volume commitments for electric vehicle platform-specific connector families.
Industry Challenges
- Precision stamping die maintenance:Sub-micron tolerance requirements for compliant pin sections demand specialized tool-and-die expertise concentrated in German and Japanese supplier bases.
- MIIT electromagnetic compatibility certification:Chinese domestic telecommunications deployments require extended test cycles that compress product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Press Fit Connector Market |
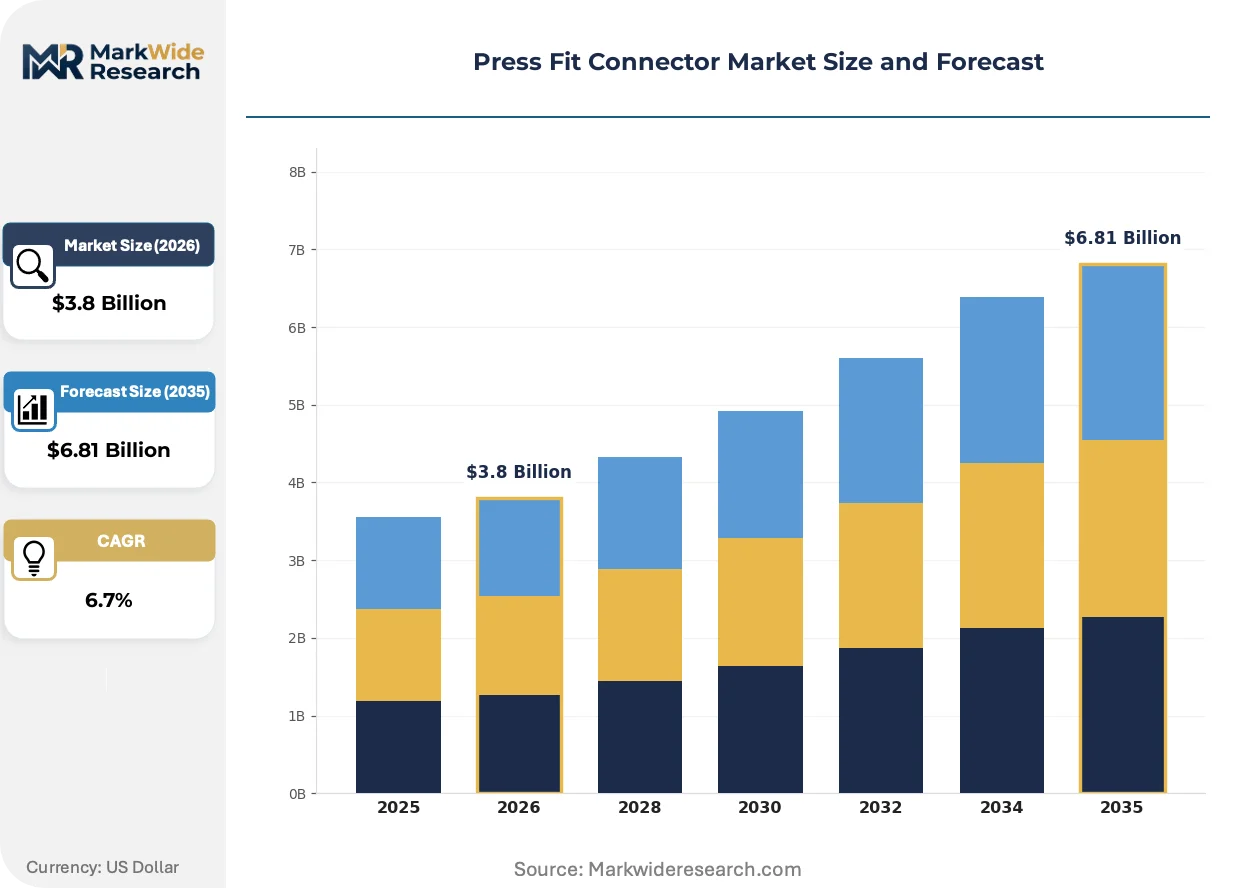
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Connector Type: Power Connectors, Signal Connectors, High-Density Connectors, Modular Connectors Application: Consumer Electronics, Automotive, Industrial Equipment, Telecommunications Material: Copper, Aluminum, Plastic, Steel Installation Method: Through-Hole, Surface Mount, Panel Mount, Custom Solutions |
| Companies Covered | TE Connectivity, Amphenol Corporation, Samtec, Fujitsu Limited, HARTING Technology Group, Japan Aviation Electronics Industry, Radiall, J.S.T. Manufacturing, Interplex Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Press Fit Connector Market Strategic Shifts
Press fit connector evolution centers on three vectors: contact physics refinement, regulatory chemistry substitution, and procurement relationship restructuring.
Compliant pin geometries incorporating dual-beam eye-of-the-needle designs are collapsing the insertion force variance window that previously separated automotive power applications from telecommunications signal density requirements. Data center backplane manufacturers in South Korea and Taiwan are adopting these architectures for 112 Gbps PAM4 signaling lanes. The structural consequence compresses SKU proliferation across end-use segments.
REACH authorization requirements for hexavalent chromium plating alternatives are forcing chemistry transitions toward trivalent chromium and thin-layer silver deposition processes. Connector manufacturers serving European automotive OEMs face substance disclosure obligations across multi-tier supply chains. German plating facilities are absorbing capital equipment conversion costs ahead of RoHS exemption expiry reviews.
Automotive electrification programs are consolidating connector procurement decisions at platform-architecture level rather than module-subsystem level. Electric vehicle battery pack integrators in China and Germany now specify press fit families across high-voltage distribution, cell monitoring, and thermal management functions. This concentration elevates technical dialogue between OEM electrical architects and connector application engineering teams.
Press Fit Connector Market Segmentation
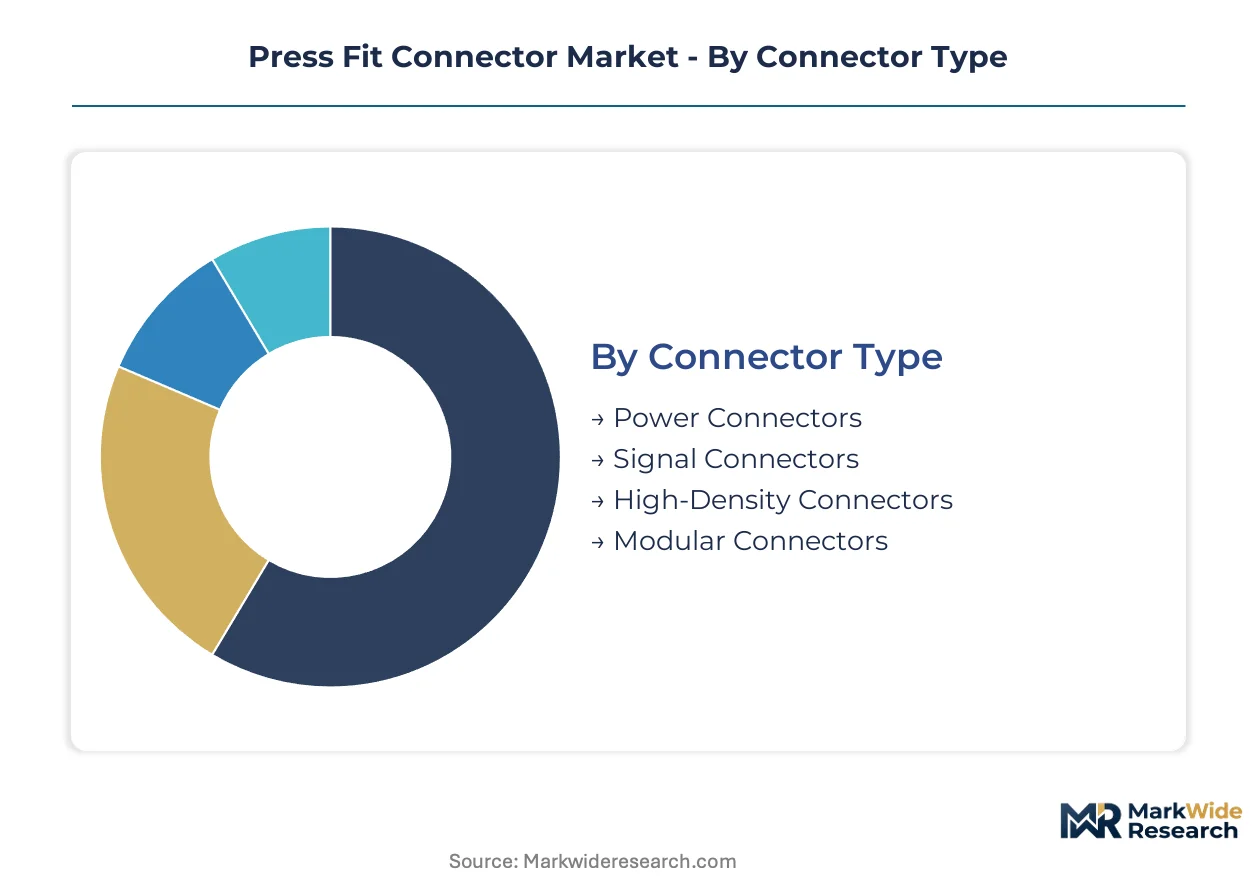
Press fit connector procurement decisions diverge sharply across electrical load requirements, assembly density constraints, and thermal cycling profiles. Segment boundaries determine plating chemistry selection, compliant pin geometry, and supplier qualification pathways.
Connector Type:
Cost tier stratification separates commodity signal interconnects from premium high-density architectures serving data center backplanes.
- Power Connectors:Heavy-gauge compliant pins handle 30-120 newtons insertion force for battery management system busbars. Electric vehicle powertrain modules in Germany and China specify oxygen-free copper grades for thermal cycling resilience.
- High-Density Connectors:Sub-0.8mm pitch arrays enable 112 Gbps PAM4 signaling lanes. South Korean semiconductor fabrication facilities are expanding press fit assembly lines for advanced node production backplanes.
- Signal Connectors:Lower insertion force designs dominate consumer electronics and telecommunications where cost sensitivity shapes procurement decisions.
- Modular Connectors:Configurable pin arrays allow field customization for industrial equipment retrofits.
Signal connectors command the established base. The steepest expansion runs through high-density connectors.
Application:
End-use voltage requirements and vibration exposure dictate compliant pin geometry selection and plating thickness specifications.
- Automotive:High-current interconnects for electric vehicle platforms face compressed qualification timelines. Battery pack integrators in China and Germany now specify press fit families across high-voltage distribution, cell monitoring, and thermal management functions.
- Telecommunications:Backplane density demands drive dual-beam eye-of-the-needle adoption. Data center manufacturers in South Korea and Taiwan are migrating toward these architectures for signal integrity at 112 Gbps.
- Consumer Electronics:Cost-optimized signal connectors serve high-volume portable device assembly lines.
- Industrial Equipment:Vibration-resistant designs target factory automation and heavy machinery control systems.
Consumer electronics anchors volume shipments. Automotive electrification programs are climbing the fastest.
Material:
Conductivity thresholds and corrosion resistance requirements determine raw material sourcing strategies and cost structures.
- Copper:Oxygen-free grades achieve thermal cycling resilience for power applications. Chilean and Peruvian mining output volatility transmits directly to connector material cost structures.
- Aluminum:Lightweight alternatives emerge for aerospace and weight-sensitive automotive subassemblies.
- Plastic:High-temperature thermoplastics form compliant pin housings and insulator bodies.
- Steel:Hardened substrates provide mechanical backing for high-insertion-force power connectors.
Copper commands the established base. Aluminum is gaining share fastest in weight-critical applications.
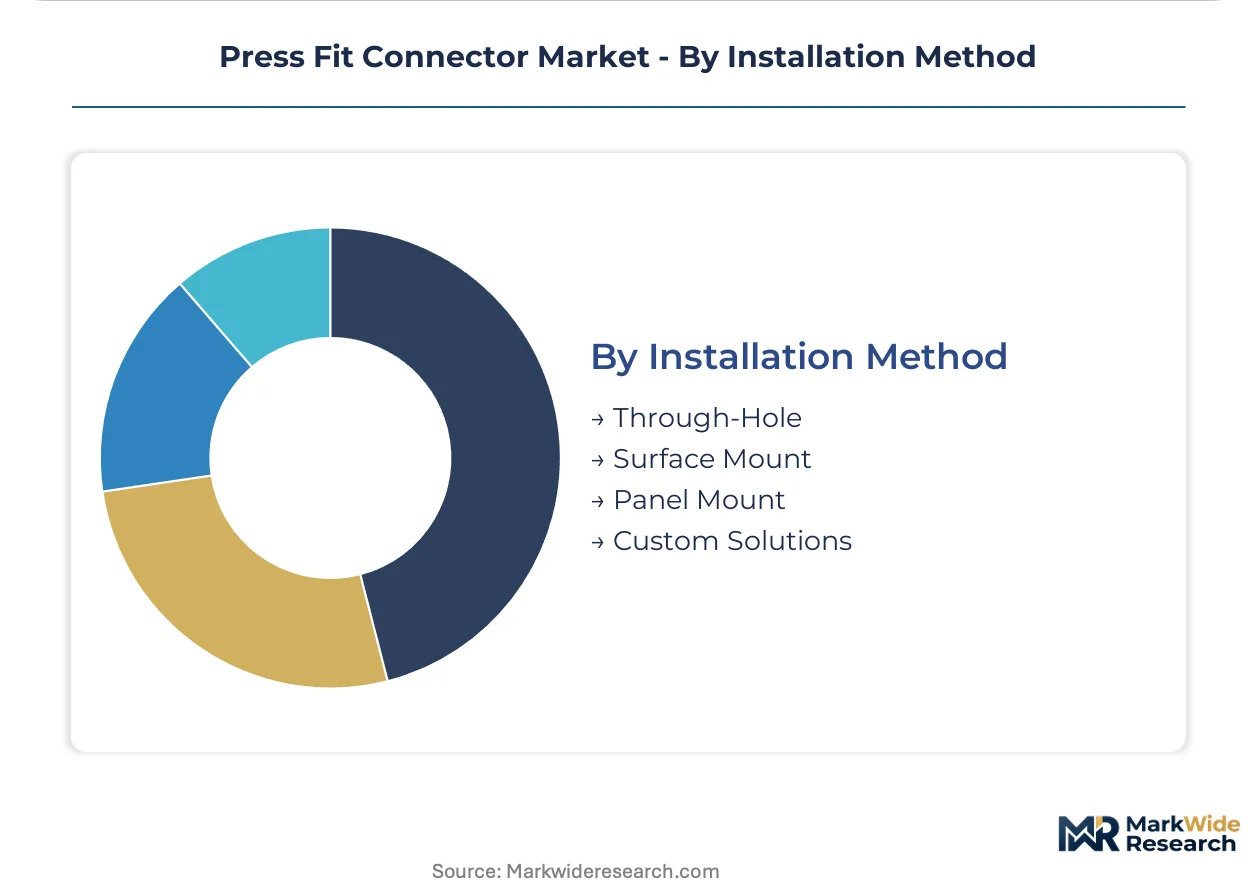
Installation Method:
Assembly process compatibility determines PCB design rules and rework economics across manufacturing footprints.
- Through-Hole:Plated barrel designs remain dominant for high-reliability applications. Extraction damage to PCB barrels limits field repairability and elevates total cost of ownership in telecommunications infrastructure.
- Surface Mount:Mixed-technology boards combine press fit zones with SMT components for hybrid assembly flows.
- Panel Mount:External enclosure interfaces serve industrial equipment and ruggedized telecommunications gear.
- Custom Solutions:Application-specific geometries address unique thermal or mechanical constraints in specialized equipment.
Through-hole retains the installed base. Surface mount hybrid configurations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Press fit connector fabrication clusters in Germany, China, South Korea, and Japan concentrate high-volume stamping and plating capacity. These four countries anchor the supply base while the United States retains significant demand pull from automotive and data center sectors.
Germany
Automotive electrification programs at BMW, Mercedes-Benz, and Volkswagen compress qualification timelines for high-current interconnects. REACH substance disclosure mandates and RoHS exemption reviews redirect procurement toward lead-free press fit architectures. Bavaria and Baden-Württemberg host specialized plating facilities converting hexavalent chromium lines ahead of regulatory deadlines.
China
Jiangsu province capacity expansion targets electric vehicle powertrain module assembly for BYD, NIO, and CATL battery integrators. MIIT electromagnetic compatibility certification requirements govern domestic telecommunications infrastructure deployments. Shenzhen and Suzhou industrial zones concentrate precision stamping operations serving both export and domestic qualification pathways.
South Korea
Samsung Electronics and SK Hynix semiconductor fabrication facilities expand press fit assembly lines for advanced node production backplanes. MFDS regulatory frameworks align with international standards but add domestic testing cycles for telecommunications equipment. Seoul Capital Area and Busan-Ulsan corridors host high-density connector packaging operations.
Japan
Fujitsu, Hitachi, and NEC server and storage system manufacturers sustain domestic demand for high-density backplane connectors. METI industrial standards and JIS certification requirements shape product development cycles. Kanto and Kansai regions maintain captive tool-and-die expertise for sub-micron tolerance compliant pin sections.
United States
Hyperscale data center operators in Northern Virginia and Dallas-Fort Worth drive 112 Gbps PAM4 signaling lane demand. EPA hazardous substance restrictions affect plating chemistries while NHTSA automotive safety standards influence electric vehicle interconnect specifications. TE Connectivity and Amphenol Corporation anchor North American supply through captive manufacturing and distribution networks.
Press Fit Connector Market Competitive Environment
Vertically integrated multinationals and specialized precision fabricators split the market across automotive and telecommunications verticals. The vendor base concentrates around three strategic archetypes: captive plating-and-stamping integrators serving high-volume automotive contracts; modular specialists supplying configurable pin arrays for industrial retrofits; and density-focused manufacturers targeting data center backplane migrations. Competitive moves center on backward integration into copper alloy sourcing and accelerated plating chemistry validation cycles.
Among precision fabricators with Japanese industrial heritage, Fujitsu Limited and Japan Aviation Electronics Industry occupy positions within the high-density backplane tier. TE Connectivity exemplifies the vertically integrated archetype through upstream control over material sourcing and stamping operations. Amphenol Corporation anchors North American supply chain positioning through captive facility networks.
| Leading Market Players |
|---|
| TE Connectivity |
| Amphenol Corporation |
| Samtec |
| Fujitsu Limited |
| HARTING Technology Group |
| Japan Aviation Electronics Industry |
| Radiall |
| J.S.T. Manufacturing |
| Interplex Holdings |
| Others |
Value Chain & Pricing Dynamics
Suzhou's precision stamping corridor concentrates high-volume press fit connector capacity, translating manufacturing scale into asymmetric pricing power for compliant pin geometries serving German automotive electrification programs.
Pricing Analysis
EU REACH substance disclosure mandates dictate the pricing tier structure across European automotive procurement channels. Three-tier pricing structure across premium, standard, and economy levels separates oxygen-free copper power connectors from commodity signal interconnects and aluminum-lightweight alternatives. Cost compression in standard-grade signal connectors is intensifying because Chilean mining volatility transmits directly to material cost structures. Consumer electronics OEMs exhibit highest price sensitivity, while German battery pack integrators prioritize thermal cycling resilience over unit economics.
Supply Chain Analysis
Foxconn, Jabil, and specialized EMS providers in Jiangsu province and Bavaria hold contract manufacturing capacity for automotive and telecommunications verticals. Supply concentrates in Germany, China, and South Korea for stamping and plating operations. Raw material flows draw from Chilean copper concentrate, Peruvian mining output, and domestic Chinese rare earth processing. Single-source vulnerability in high-purity oxygen-free copper grades threatens cost stability. Distribution runs through captive direct-OEM contracting models in automotive and tier-1 distributor networks in telecommunications infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Press fit connector incumbents face substitution pressure from solderless spring-contact architectures and laser-welded interconnect systems gaining traction in electric vehicle powertrain modules.
For Market Incumbents: Harden plating chemistry validation cycles ahead of RoHS exemption expiry reviews to defend automotive qualification pathways. TE Connectivity and Amphenol Corporation exemplify backward integration into copper alloy sourcing that compresses cost structures for high-volume contracts. Accelerate trivalent chromium line conversions in captive facilities to preempt REACH authorization disruptions.
For New Entrants and Emerging Players: India's PLI scheme for electronics manufacturing presents underpenetrated assembly equipment demand where domestic semiconductor packaging incentives are opening qualification pathways. Target modular connector configurations for industrial equipment retrofits where configurable pin arrays command pricing premiums over commodity signal interconnects. Pursue direct contracting with Chinese electric vehicle module integrators bypassing established distribution hierarchies.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because automotive electrification programs are compressing procurement decisions toward platform-architecture suppliers with captive plating-and-stamping integration. Acquisition focus should center on German and Japanese precision fabricators with sub-micron tolerance tool-and-die expertise. Monitor MIIT electromagnetic compatibility certification timelines as inflection indicator for Chinese domestic market access windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Plating Chemistry Transition | Trivalent chromium conversion ahead of REACH deadlines secures German automotive qualification pathways. |
| Backward Integration into Copper Sourcing | Captive oxygen-free copper supply hedges Chilean mining volatility for power connector margins. |
| Dual-Beam Eye-of-the-Needle Geometry Adoption | South Korean data center backplane demand collapses SKU proliferation across signal density tiers. |
| Direct OEM Contracting Model Expansion | Bypassing distribution captures volume commitments from Chinese electric vehicle platform architects. |
| India PLI Scheme Qualification | Domestic semiconductor packaging incentives open assembly equipment supplier pathways outside China concentration. |
Study Parameters
Operator-level perspectives from connector application engineers, automotive Tier 1 procurement officers, plating facility technical directors, and telecommunications infrastructure sourcing managers anchored the qualitative base. Primary fieldwork combined with secondary validation from SEC 10-K filings, MIIT certification registries, REACH substance disclosure databases, and customs trade data for copper alloy imports. Bottom-up segment sizing and top-down market triangulation cross-validated volume estimates across connector type, application, and material dimensions.
Scenario-bracketing framed optimistic and conservative trajectories across the analysis window without year-specific anchoring. Segmentation modeling incorporated connector type, application vertical, material grade, and installation method dimensions. CAGRs derived from slope-intercept analysis of historical shipment data and forward-looking procurement pipeline visibility. Industry-specific inputs included electric vehicle platform rollout schedules and data center backplane migration timelines toward 112 Gbps PAM4 architectures.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed connector consortia or sudden RoHS exemption withdrawals would shift outcomes. Quarterly review of MIIT electromagnetic compatibility certification queues and REACH authorization timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
China Connector Market
Connectors
PCI-E Connectors Market
Connectors
Asia-Pacific Connector Market
Connectors
Australia Connector Market
Connectors
Terminal Pins Market
Connectors
Connector Adapter Kits Market
Connectors
Middle East and Africa Hazardous Location Connectors Market
Connectors
Mexico Connector Market
Connectors
LCP Connectors Market
Connectors
USB Type-C Market
Connectors
Power Connector Market
Connectors
Pin Retainer Market
Connectors
Hybrid Fiber Optic Connectors Market
Connectors
Global Multi Coaxial Connectors Market
Connectors
Global Cables and Connector Market
Connectors
Line Clamp Market