
 Heavy-Duty Connector Market | 2026-2036
Heavy-Duty Connector Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy-Duty Connector Market Intelligence
Modular hybrid connector architectures is rewriting assembly protocols for high-vibration environments. TE Connectivity leverages captive supply chains for electromechanical hybrid assemblies across aerospace programs. HARTING Technology Group anchors European railway certification pathways through its rectangular connector dominance. Amphenol Aerospace specializes in mil-spec circular interfaces that sustain performance under extreme thermal cycling.
Heavy-duty connectors are electromechanical coupling devices rated for currents exceeding 10 A, engineered with aluminum or thermoplastic housings, multi-point contact systems, and IP65-to-IP69 sealing grades to ensure signal and power integrity in harsh industrial, transportation, and defense environments. Rectangular connectors command the largest installed base due to standardized DIN rail compatibility and field-replaceable module designs, while hybrid technology interfaces are gaining fastest traction as single-harness solutions consolidate optical data, electric power, and control signaling. Circular connectors retain premium positioning in aerospace and defense end uses where MIL-DTL-38999 compliance creates steep qualification barriers.
IEC 61984 governs connector safety and performance marking across EU industrial equipment deployments, while the EU Green Deal's industrial decarbonization mandates are accelerating electric drivetrain retrofits that demand higher-amperage connector specifications. China's GB standards and dual carbon goals are pushing domestic manufacturers toward sealed heavy-duty variants for rail and wind turbine applications. Stakeholders must monitor how regional certification divergence between European CE marking and Chinese compulsory GB testing reshapes product platform economics and factory footprint decisions.
Market Dynamics
Railway electrification mandates across Germany and China are compressing qualification timelines for high-amperage rectangular interfaces, forcing manufacturers to synchronize product roadmaps with infrastructure procurement cycles rather than traditional industrial equipment refresh rates.
Growth Catalysts
- IEC 61984 Compliance:EU industrial equipment deployments now require enhanced safety marking and performance verification, pulling demand toward certified heavy-duty variants with IP67 sealing.
- Wind Turbine Drivetrain Retrofits:China's dual carbon goals are accelerating replacement of legacy power distribution architectures in onshore and offshore installations.
- Aluminum Housing Adoption:Lightweight metallurgy is displacing cast iron in high-vibration rail applications, reducing connector mass without sacrificing current capacity.
Market Restraints
- Copper Price Volatility:Multi-point contact systems depend on stable copper alloy supply, with spot price swings compressing margin buffers for mid-tier assemblers.
- German Supply Concentration:DIN rail-compatible rectangular connector production clusters heavily in Baden-Württemberg and Bavaria, creating single-region exposure for European procurement.
- Optical-Electrical Integration Complexity:Hybrid interfaces demanding simultaneous signal integrity across fiber and copper channels extend validation timelines beyond traditional product cycles.
Strategic Opportunities
- Indian Railway Electrification:The country's 100% electrification target by 2024 creates procurement windows for sealed heavy-duty variants in locomotive and signaling applications.
- EU Green Deal Industrial Decarbonization:Electric drivetrain retrofits in heavy manufacturing are mandating higher-amperage connector specifications than legacy hydraulic systems required.
- Direct OEM Partnership Models:Aerospace and defense contractors are bypassing distribution layers to establish captive supply agreements for MIL-DTL-38999-qualified circular interfaces.
Industry Challenges
- Cross-Disciplinary Engineering Talent:Hybrid connector design demands simultaneous expertise in electromechanical, photonic, and thermal management disciplines, with qualified personnel concentrated at a handful of European and North American firms.
- CE-to-GB Certification Divergence:European manufacturers face redundant testing protocols when adapting CE-marked products for China's compulsory GB standards, fragmenting platform economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy-Duty Connector Market |
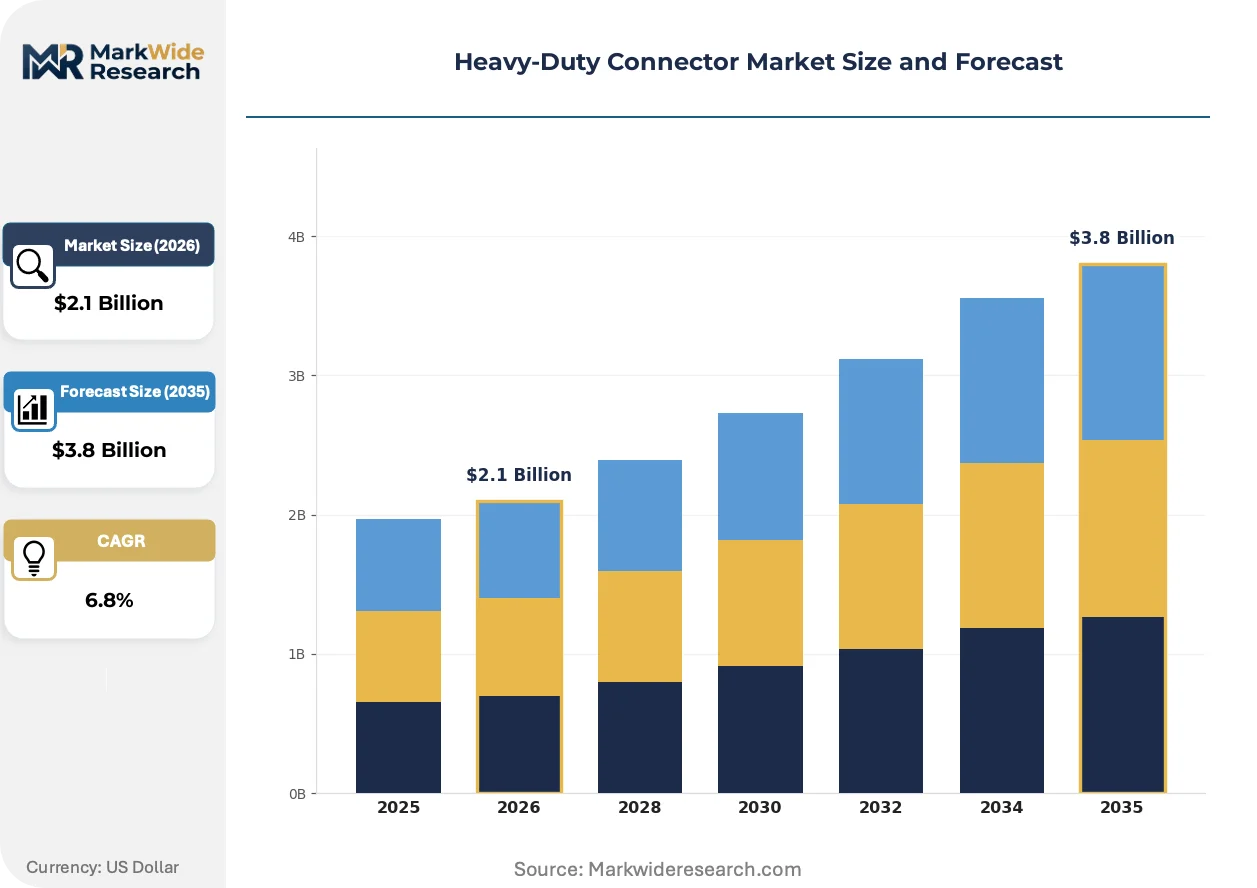
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rectangular Connectors, Circular Connectors, Modular Connectors, Accessories End User: Aerospace, Automotive OEMs, Industrial Equipment, Telecommunications Installation: Panel Mount, Cable Mount, Rack Mount, Docking Station Technology: Optical, Hybrid, Electric, Electromechanical |
| Companies Covered | HARTING Technology Group, Electric Cord Sets, TE Connectivity, Wieland Electric, Connective Design, Amphenol Aerospace, Samtec, ERNI Group, Molex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy-Duty Connector Market Strategic Shifts & Innovations
Modular hybrid architectures are compressing traditional boundaries between power distribution and data transmission, enabling single-harness solutions that consolidate previously separate connector families into unified electromechanical systems.
Integrated fiber-copper hybrid interfaces are collapsing the distinction between signal and power harness assemblies in high-vibration rail environments. Deutsche Bahn and Chinese State Railway Group procurement specifications now explicitly favor these consolidated architectures for new electrification corridors. The technology is collapsing supplier tier structures by eliminating discrete optical and electrical component vendors from qualified vendor lists.
REACH substance restrictions and RoHS recast directives are tightening material composition requirements for thermoplastic housings and contact plating alloys. German manufacturers face particular pressure as KBA railway certification pathways incorporate evolving chemical compliance benchmarks. Industrial equipment OEMs in the Ruhr manufacturing cluster are responding by accelerating qualification of halogen-free housing materials ahead of regulatory deadlines.
Consolidated procurement frameworks are replacing discrete component purchasing across European wind turbine OEMs. Vestas and Siemens Gamesa buyers now specify connector systems as integrated drivetrain subassemblies rather than standalone electrical components, compressing supplier negotiation leverage. This pattern is most visible in Danish and German offshore installation projects where total cost of ownership modeling dominates sourcing decisions.
Heavy-Duty Connector Market Segmentation
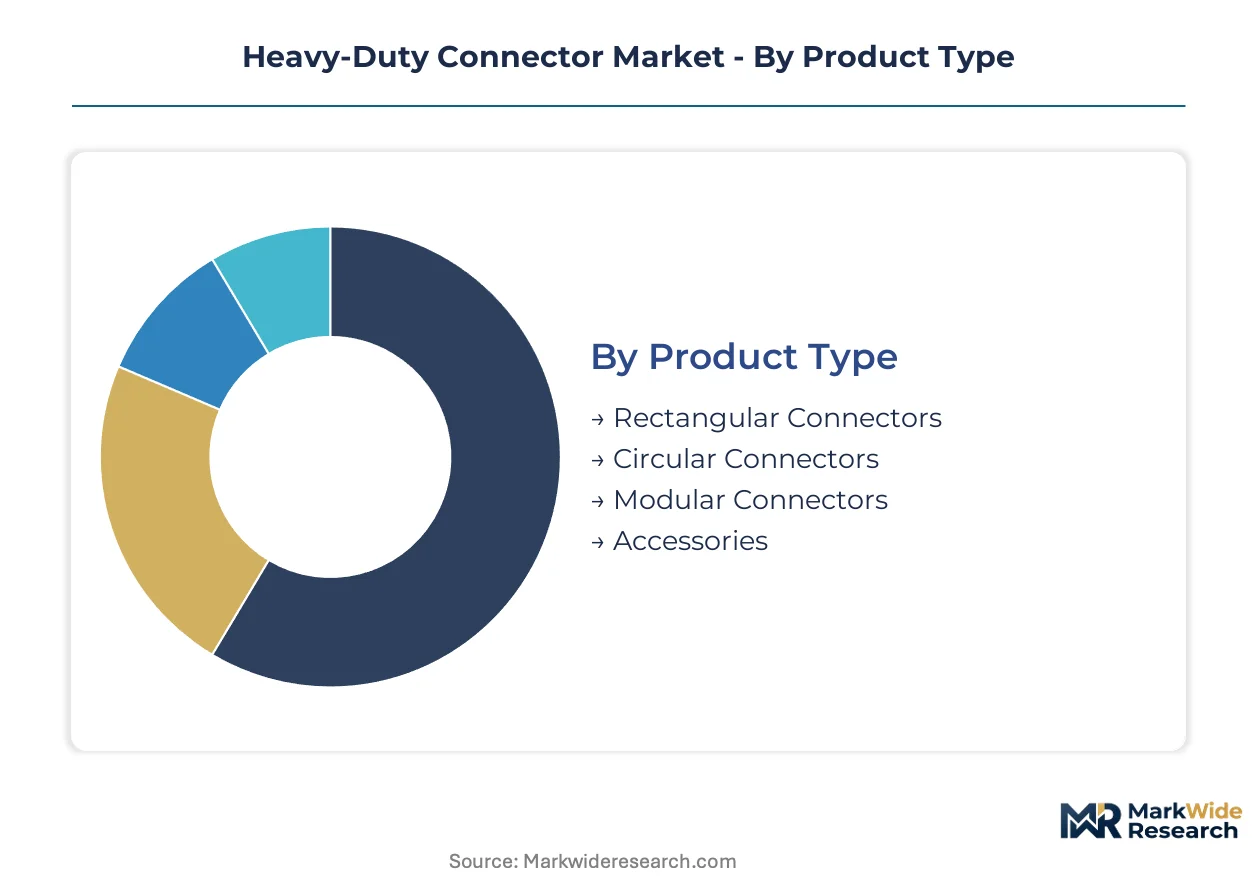
Segmentation in heavy-duty connectors reveals how technical specifications diverge across vibration tolerance, sealing grades, and current-carrying thresholds. Procurement patterns vary sharply between rail infrastructure programs demanding field-replaceable modules and aerospace contractors requiring mil-spec circular interfaces with decade-long qualification cycles.
Product Type:
After-sales service intensity varies dramatically across product architectures, with modular designs requiring ongoing reconfiguration support while sealed circular variants demand minimal field intervention once qualified.
- Rectangular Connectors:Aluminum and thermoplastic housings with multi-point contact systems dominate DIN rail-compatible industrial deployments. Railway electrification corridors in Germany and China concentrate procurement of high-amperage variants rated for IP67 sealing and sustained vibration exposure.
- Circular Connectors:MIL-DTL-38999-compliant interfaces sustain performance across extreme thermal cycling in defense and aerospace applications. Lockheed Martin and Northrop Grumman procurement specifications mandate these for avionics harnesses where qualification barriers eliminate second-source competition.
- Modular Connectors:Field-replaceable module designs reduce downtime in manufacturing automation.
- Accessories:Sealing gaskets, backshells, and locking mechanisms complete installation integrity.
By volume, rectangular connectors lead. By growth pace, modular architectures are gaining share fastest.
End User:
Cost tier stratification separates aerospace prime contractors paying qualification premiums from industrial OEMs optimizing total cost of ownership across multi-year replacement cycles.
- Industrial Equipment:Factory automation and process control systems drive standardized rectangular connector procurement with IEC 61984 compliance requirements. German Ruhr manufacturing clusters specify IP67-sealed variants for electric drivetrain retrofits under EU Green Deal decarbonization mandates.
- Aerospace:Extreme thermal cycling and vibration tolerance specifications create steep entry barriers. Boeing and Airbus supply chains enforce captive supplier agreements for MIL-DTL-38999-qualified circular interfaces with decade-long validation timelines.
- Automotive OEMs:Battery electric vehicle platforms demand higher-amperage distribution architectures than legacy internal combustion systems.
- Telecommunications:Data center power distribution favors standardized modular interfaces with hot-swap capability.
Industrial equipment commands the largest installed base. Aerospace exhibits the steepest expansion trajectory.
Installation:
Volume concentration favors panel mount configurations in stationary industrial equipment, while cable mount variants dominate mobile rail and defense applications where harness flexibility determines reliability.
- Panel Mount:Fixed industrial enclosures and electrical cabinets standardize on DIN rail-compatible rectangular interfaces. German manufacturing clusters in Baden-Württemberg specify these for automated production lines with decades-long operational lifespans.
- Cable Mount:Locomotive and rolling stock applications demand strain-relief engineering for constant flex and vibration exposure. Chinese State Railway Group procurement explicitly favors cable-mounted hybrid connectors for new electrification corridors.
- Rack Mount:Telecommunications and data center infrastructure favors standardized 19-inch compatibility.
- Docking Station:Automated guided vehicles and mobile industrial equipment require precision alignment mechanisms.
Panel mount configurations anchor current volume. Cable mount variants are climbing the fastest.
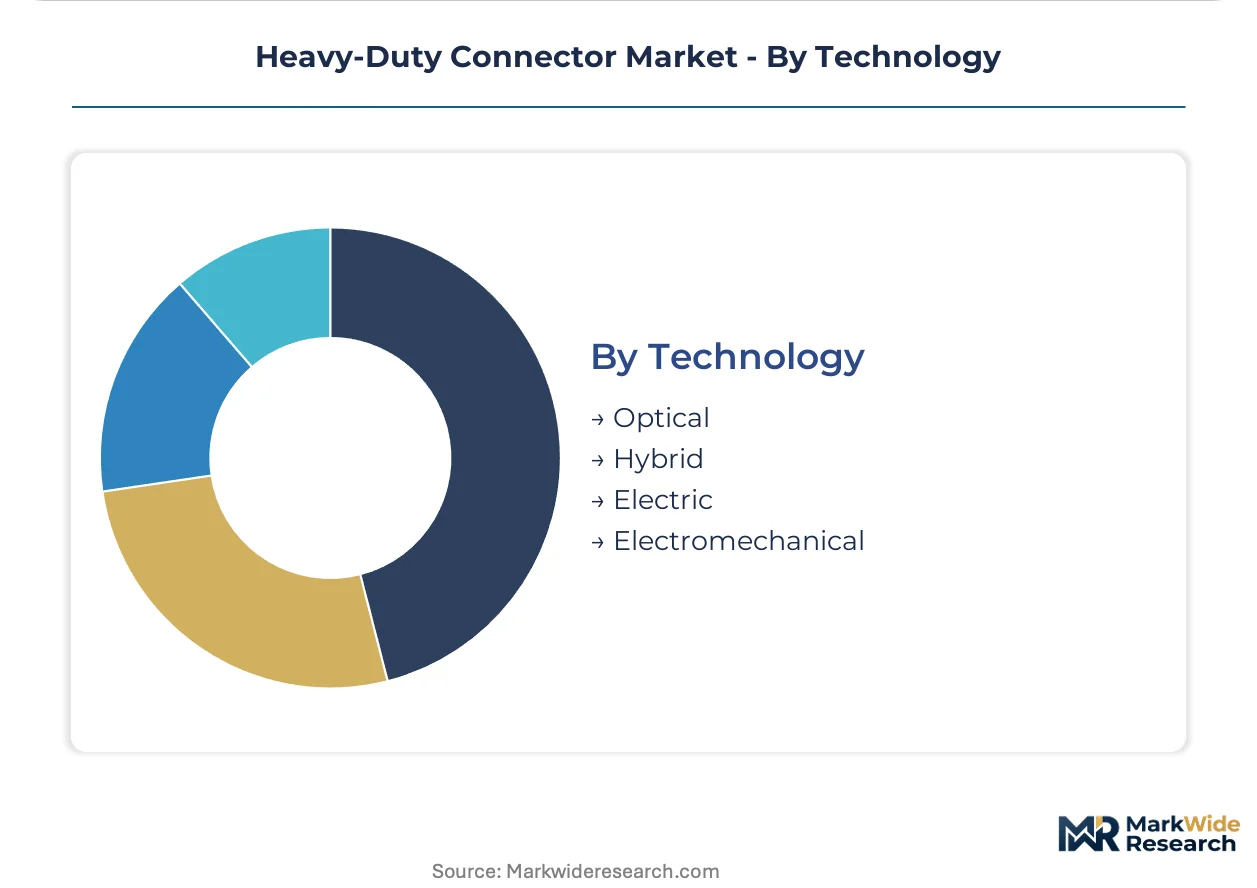
Technology:
Customer type bifurcation separates defense contractors accepting extended validation timelines for electromechanical reliability from industrial buyers prioritizing rapid deployment of hybrid fiber-copper consolidation.
- Hybrid:Integrated fiber-copper interfaces collapse previously separate power and data harness assemblies into single-connector solutions. Deutsche Bahn procurement specifications now mandate these for new rail corridors, eliminating discrete optical and electrical component vendors from qualified supplier lists.
- Electromechanical:TE Connectivity and HARTING anchor European supply chains for high-vibration aerospace and rail programs. These assemblies combine precision-machined contacts with thermoplastic housings rated for IP69 sealing in harsh environment deployments.
- Optical:Pure fiber interfaces serve high-bandwidth telecommunications backbones with immunity to electromagnetic interference.
- Electric:Conventional copper-only architectures retain cost advantages in legacy industrial retrofits.
Electric technology retains volume leadership. Hybrid interfaces show the steepest growth curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in heavy-duty connectors favor manufacturing economies with integrated rail and industrial equipment supply chains. Germany and China maintain structural trade surpluses in high-amperage rectangular interfaces. The United States, India, and Japan represent demand-side growth poles with varying degrees of domestic fabrication capacity.
Germany
Railway electrification corridors and Ruhr manufacturing clusters drive procurement of IP67-sealed rectangular connectors. KBA certification pathways incorporate REACH substance restrictions and evolving chemical compliance benchmarks for thermoplastic housings. Baden-Württemberg and Bavaria concentrate DIN rail-compatible production with captive supply chains serving Siemens Gamesa and Vestas wind turbine programs.
China
High-speed rail expansion and dual carbon mandates accelerate demand for sealed heavy-duty variants in wind turbine drivetrains. GB standards and compulsory testing protocols create divergent certification requirements from European CE marking. Domestic manufacturers in the Yangtze River Delta and Pearl River Delta regions scale aluminum housing production for State Railway Group procurement specifications.
United States
Aerospace prime contractors and defense programs sustain premium demand for MIL-DTL-38999-qualified circular interfaces. FAA and DOD qualification barriers eliminate second-source competition for avionics harness applications. Lockheed Martin and Northrop Grumman supply chains concentrate procurement through captive supplier agreements with decade-long validation timelines.
India
Indian Railways' electrification targets create procurement windows for sealed heavy-duty connectors in locomotive and signaling applications. CEA regulations and BIS standards govern industrial equipment electrical safety specifications. Manufacturing clusters in Maharashtra and Gujarat attract component assembly investments from European connector specialists seeking tariff-advantaged export platforms.
Japan
Automotive battery electric vehicle platforms and precision manufacturing automation sustain demand for high-reliability electromechanical interfaces. METI industrial decarbonization roadmaps push factory equipment retrofits requiring higher-amperage distribution architectures. Kansai and Chubu industrial corridors concentrate procurement from domestic suppliers with JIS-standard certification pathways.
Heavy-Duty Connector Market Key Industry Players
On the supply side, the industry is consolidating around three structural tiers: integrated electromechanical conglomerates with captive aerospace-rail portfolios, mid-scale specialists commanding regional certification pathways, and component assemblers exposed to copper price volatility. Strategic archetypes include DIN rail standard-setters, mil-spec qualification holders, and hybrid fiber-copper integrators. Dominant competitive moves center on backward integration into aluminum housing metallurgy and strategic partnerships with wind turbine OEMs for drivetrain subassembly sourcing.
Among German-based technology groups, HARTING Technology Group and Wieland Electric occupy positions within the European railway certification ecosystem, anchoring rectangular connector supply chains through KBA-validated production pathways. TE Connectivity represents the integrated conglomerate archetype with captive aerospace and rail programs spanning multiple qualification regimes. These three entities exemplify how geographic clustering around Baden-Württemberg manufacturing infrastructure creates defensive positioning against Asian cost competition.
| Leading Market Players |
|---|
| HARTING Technology Group |
| Electric Cord Sets |
| TE Connectivity |
| Wieland Electric |
| Connective Design |
| Amphenol Aerospace |
| Samtec |
| ERNI Group |
| Molex |
| Others |
Cost & Logistics Intelligence
The Rhine-Alpine freight corridor's container cost dynamics amplify supply concentration effects in Baden-Württemberg manufacturing clusters, compressing margin buffers for mid-tier assemblers while enabling premium pricing for KBA-certified producers serving Siemens Gamesa and Vestas procurement programs.
Pricing Analysis
Current-generation hybrid fiber-copper interfaces command substantial premiums over legacy electromechanical assemblies and next-generation optical-only architectures. Three-tier pricing structure across premium, standard, and economy levels separates MIL-DTL-38999-qualified circular connectors from DIN rail-compatible rectangular variants and unbranded component assemblies. Price differentiation hinges on certification grade and volume scale, with aerospace contractors accepting decade-long validation premiums while industrial OEMs optimize total cost of ownership. Cost compression in mid-tier rectangular connectors is intensifying because copper alloy spot price volatility erodes assembler margins. Automotive battery electric vehicle platforms exhibit highest price sensitivity; defense programs show least.
Supply Chain Analysis
Extended payment terms from European wind turbine OEMs now stretch to 90 days, forcing mid-scale specialists toward supply-chain finance facilities. Manufacturing concentrates in Germany, China, and the United States. Multi-point contact systems draw from copper alloy feedstock, thermoplastic housing resins, and precision-machined aluminum forgings. Single-source vulnerability in Baden-Württemberg DIN rail-compatible production clusters exposes European procurement to regional disruption. Distribution runs through direct OEM partnerships in aerospace and tiered distributor networks in industrial equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Heavy-duty connector markets are restructuring around service-attach revenue, with field-replaceable module reconfiguration support and predictive maintenance contracts expanding faster than hardware unit sales.
For Market Incumbents: Build certification moats through simultaneous KBA railway and MIL-DTL-38999 aerospace qualification pathways. Deepen backward integration into aluminum housing metallurgy to offset copper price volatility. Anchor captive supply agreements with Deutsche Bahn and Chinese State Railway Group procurement programs to lock out emerging hybrid integrators. For New Entrants and Emerging Players: Pursue Indian Railway electrification procurement windows before 100% electrification targets close to foreign suppliers. Target cable-mounted hybrid connectors for Chinese State Railway Group new corridor specifications as the most penetrable segment. Establish tariff-advantaged assembly platforms in Maharashtra and Gujarat manufacturing clusters to bypass European cost structures. For Investors and Strategic Acquirers: Regional certification pathway specialists with simultaneous CE marking and GB standards capability represent the highest-conviction acquisition archetype. Long-term viability centers on consolidation of hybrid fiber-copper integration expertise as single-harness architectures displace discrete component vendors. Watch for Deutsche Bahn and Chinese State Railway Group procurement specification shifts mandating consolidated architectures as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Housing Metallurgy | HARTING and TE Connectivity captive supply chains reduce mass in rail applications without current capacity sacrifice. |
| Hybrid Fiber-Copper Platform Development | Single-harness consolidation eliminates discrete optical and electrical vendors from Deutsche Bahn qualified supplier lists. |
| KBA Railway Certification Pathway Investment | German manufacturers incorporate REACH substance restrictions ahead of regulatory deadlines for thermoplastic housings. |
| Direct OEM Partnership Models | Lockheed Martin and Northrop Grumman bypass distribution layers for MIL-DTL-38999-qualified circular interface supply. |
| Tariff-Advantaged Assembly Footprint Expansion | European connector specialists establish Maharashtra and Gujarat platforms for Indian Railway procurement access. |
Research Approach
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings in this study. Conversations with maintenance directors at German Ruhr manufacturing clusters, OEM procurement teams at Siemens Gamesa and Vestas, aftermarket service heads at HARTING and TE Connectivity, and plant engineers at Chinese State Railway Group operations provided demand-side calibration. Secondary validation drew from IEC 61984 safety standard documentation, KBA railway certification pathway records, GB standards compulsory testing protocols, and SEC filings from publicly traded connector manufacturers. Bottom-up segment sizing and top-down macroeconomic triangulation ensured methodological consistency.
Calibration against historical volume trajectories and installed base replacement cycles shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, end-use industry, installation configuration, and technology interface type. CAGRs derive from regression analysis of procurement cycle timing, infrastructure investment waves, and regulatory compliance phase-in schedules. Forecast inputs incorporate railway electrification corridor completion timelines and wind turbine drivetrain retrofit acceleration patterns under EU Green Deal and China's dual carbon mandates.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by aluminum housing specialists or sudden certification pathway divergence between CE marking and GB standards would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
Underwater Mate Connectors Market
Connectors
Circular Waterproof Connector Market
Connectors
Middle East Connector Market
Connectors
SATA Connector Market
Connectors
IC Socket Market
Connectors
Hazardous Location Connectors Market
Connectors
Latin America Connector Market
Connectors
Liquid Cooling Connector Market
Connectors
Small Bore Connectors Market
Connectors
Space Grade Connectors Market
Connectors
Connector and Terminal Systems for Harsh Environment Wiring Market
Connectors
DIN Connectors Market
Connectors
Underwater Connectors Market
Connectors
Middle East and Africa Hazardous Location Connectors Market
Connectors
Hybrid Fiber Optic Connectors Market
Connectors
Cable Connectors and Adapters Market