
 Global Cables and Connector Market | 2026-2036
Global Cables and Connector Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cables and Connector Market Foresight
The capital-intensity divergence between integrated manufacturers and assembly-focused competitors is redrawing competitive boundaries in the cables and connector industry. TE Connectivity leverages deep vertical integration in precision stamping and polymer compounding to command pricing power in automotive connector segments. Prysmian sustains unmatched submarine cable installation fleets and marine survey capabilities that anchor its position in intercontinental power transmission projects.
Cables and connectors encompass conductive assemblies and mating interfaces engineered to transmit electrical power, analog signals, or digital data across specified impedance, bandwidth, and temperature parameters, typically manufactured through extrusion, drawing, plating, and precision molding processes to ensure signal integrity and mechanical durability in demanding environments. Fiber optic cables dominate margin pools in telecommunications and data center applications where single-mode silica cores support terabit-scale transmission with minimal attenuation, while USB and HDMI connectors face commoditization pressure in consumer electronics despite sustained volume throughput. Ethernet cables compete aggressively in enterprise networking upgrades as Power over Ethernet standards push copper conductor specifications toward higher gauge and shielding requirements.
FCC equipment authorization rules shape connector electromagnetic compatibility testing for US telecommunications deployments, while EU RoHS and REACH frameworks restrict hazardous substances in cable jacketing and contact plating materials, forcing reformulation of PVC and cadmium-bearing alloys. China's GB standards and MIIT certification requirements create localized compliance barriers for foreign connector suppliers seeking access to state-backed 5G and rail infrastructure tenders. Stakeholders must monitor divergence between regional material compliance regimes and next-generation signaling standards to align R&D roadmaps with procurement specifications that gate market access.
Market Dynamics
AI-driven data center buildouts are compressing upgrade cycles for fiber optic backbones while EU F-Gas Regulation mandates force rapid reformulation of halogen-free cable compounds across member states.
Growth Catalysts
- Submarine cable deployments:Intercontinental power transmission projects and transoceanic data links are absorbing specialized high-voltage and fiber assemblies from installation fleets.
- EU F-Gas Regulation:Halogen-free mandates are accelerating material substitution in building wire and industrial cable jacketing across Germany, France, and Italy.
- Single-mode fiber:Terabit-scale silica cores are replacing multimode infrastructure in hyperscale data centers managing generative AI traffic loads.
Market Restraints
- Copper price volatility:LME copper fluctuations compress margin visibility for power cable manufacturers dependent on conductor raw materials.
- Optical component concentration:Specialty fiber draw towers and preform suppliers cluster in Japan and the US, creating chokepoint risk for downstream cable integrators.
- REACH substance restrictions:ECHA candidate list expansions are forcing cadmium-free plating alloy reformulations that raise contact resistance in automotive connectors.
Strategic Opportunities
- India rail electrification:Dedicated freight corridors and metro expansions are opening procurement windows for high-tension overhead line cable and pantograph connectors.
- Power over Ethernet convergence:IEEE 802.3bt standardization is merging data and power transmission into single copper infrastructure for smart building retrofits.
- US IRA clean energy incentives:Domestic content bonuses for grid-scale solar and storage are reshoring demand for medium-voltage inter-array cable and DC connectors.
Industry Challenges
- Fiber splicing technician scarcity:Precision fusion splicing and OTDR certification requirements outpace vocational training pipeline output in multiple markets.
- Multi-standard certification timelines:Simultaneous FCC Part 15, CE marking, and GB/T compliance testing extends product launch cycles for universal connector platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cables and Connector Market |
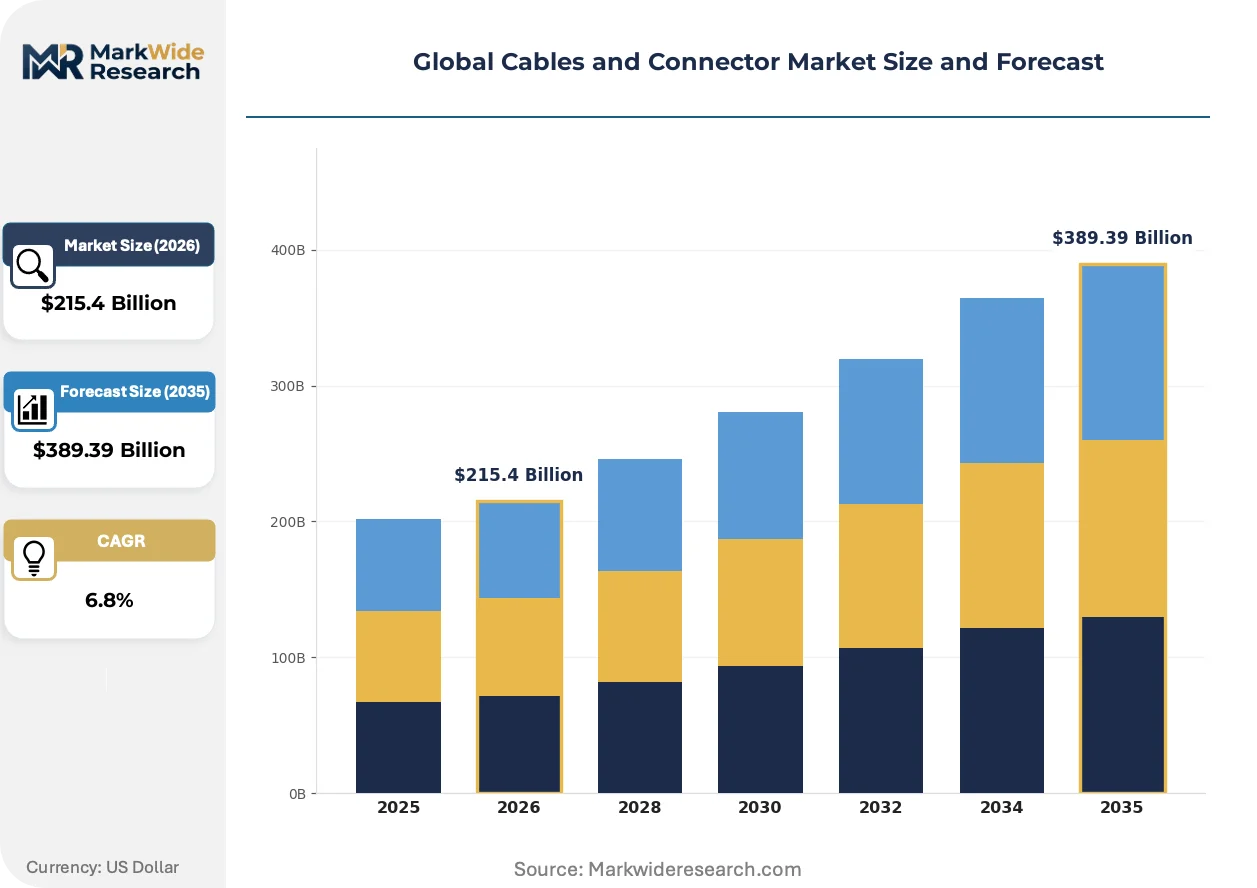
| Market Size in 2026 | $215.4 Billion |
| Market Size in 2035 | $389.39 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coaxial Cables, Fiber Optic Cables, USB Connectors, HDMI Connectors, Ethernet Cables, D-Sub Connectors Technology: Shielded Twisted Pair, Unshielded Twisted Pair, Fiber Optic, Soldered, Crimped, Snap-In Application: Telecommunications, Data Centers, Consumer Electronics, Aerospace Systems, Military Equipment, Power Transmission End User Industry: Telecom Operators, Data Storage Providers, Electronics Manufacturers, Defense Contractors, Renewable Energy Firms, Transportation Systems |
| Companies Covered | TE Connectivity, Amphenol Corporation, Molex, Aptiv, Yazaki Corporation, Fujitsu Limited, Huawei Technologies, Nexans, Prysmian, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cables and Connector Market Shifts & Advancements
Active optical cables and halogen-free material systems are compressing legacy product lifecycles while procurement patterns tilt toward certified pre-integrated assemblies over discrete component sourcing.
Silicon photonics transceivers packaged with fiber pigtails are displacing pluggable optical modules in hyperscale data center spine architectures. Cloud operators in Virginia and Oregon are specifying these co-packaged solutions for 800G lane aggregation. The shift is displacing traditional MPO connector volumes in favor of permanent fiber attachments that reduce link loss budgets.
EU F-Gas Regulation phase-down schedules are mandating low-global-warming-potential blowing agents in cable jacketing foams. Compounders in the Netherlands and Belgium are reformulating polyethylene and LSZH grades to meet ECHA compliance deadlines. Automotive wire harness suppliers face the steepest reformulation curves as OEMs anticipate 2027 fleet average targets.
Buyers are consolidating vendor relationships around pre-tested cable-connector assemblies carrying IEC 61300 and Telcordia GR-326 certifications. Distributors in Germany and South Korea are building regional certification labs to compress qualification timelines. The pattern is most pronounced in telecom infrastructure where single-source accountability reduces field failure liability.
Global Cables and Connector Market Segmentation
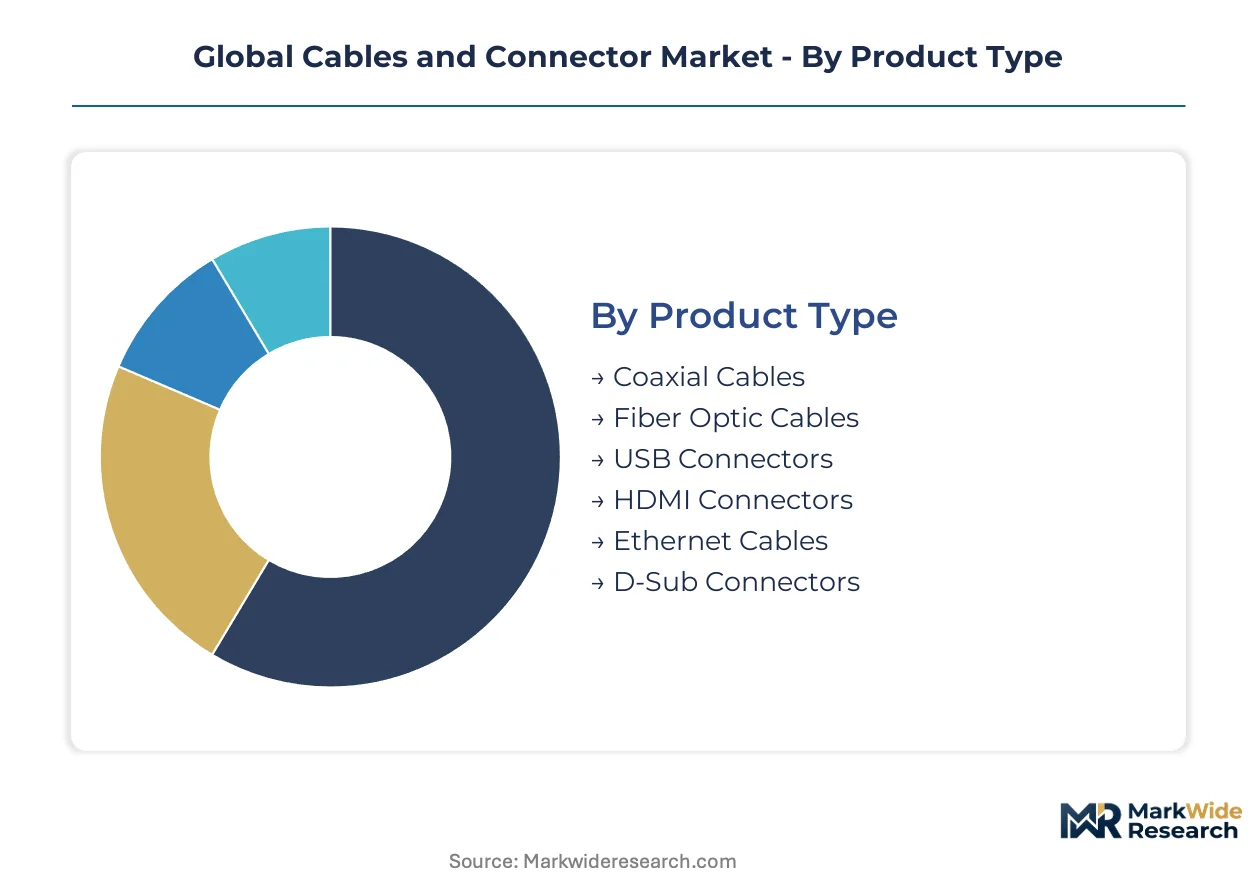
Cable and connector procurement specifications diver sharply across voltage classes, signaling frequencies, and environmental sealing requirements. Understanding substitution dynamics between copper and optical architectures helps suppliers align capacity investments with actual technology transitions rather than assumed replacement timelines.
Product Type:
Fiber optic assemblies face the most intense substitution pressure as silicon photonics and co-packaged optics displace discrete pluggable modules in hyperscale facilities.
- Fiber Optic Cables:Single-mode silica cores with terabit-scale bandwidth support dominate spine-layer deployments in Virginia and Oregon data centers. Generative AI traffic loads are compressing upgrade cycles from 400G to 800G lane aggregation faster than multimode infrastructure can accommodate.
- Ethernet Cables:Shielded and unshielded twisted-pair copper assemblies carry Power over Ethernet loads under IEEE 802.3bt standards. Smart building retrofits in Germany and South Korea are absorbing Cat 6A and above specifications for simultaneous data and DC power transmission.
- Coaxial Cables:RG-series and hardline constructions maintain RF signal integrity in legacy broadcast and cable television distribution networks.
- USB Connectors:Type-C reversible interfaces with USB4 signaling face commoditization despite sustained volume throughput in consumer electronics peripherals.
- HDMI Connectors:High-bandwidth multimedia interfaces support 8K video transmission in home theater and commercial display installations.
- D-Sub Connectors:DE-9 and DB-25 pin configurations persist in industrial automation and legacy computing equipment interfaces.
Ethernet cables anchor the volume base while fiber optic cables gain share at the steepest rate.
Technology:
Cost tier stratification separates premium shielded architectures from economy unshielded alternatives in enterprise networking procurement.
- Fiber Optic:Glass preform draw towers produce single-mode and multimode waveguides with attenuation specifications below 0.35 dB/km at 1310 nm. Japanese and US specialty fiber suppliers concentrate preform manufacturing, creating chokepoint risk for downstream cable integrators.
- Shielded Twisted Pair:Foil and braided shielding constructions suppress electromagnetic interference in industrial environments and medical imaging suites. EU F-Gas Regulation compliance deadlines are forcing compounders toward halogen-free jacketing formulations that maintain flexural durability.
- Unshielded Twisted Pair:Economy-grade copper conductors serve cost-sensitive residential and small office installations where crosstalk tolerance permits reduced shielding overhead.
- Soldered:Permanent metallurgical bonds between conductor and contact provide vibration resistance in aerospace and military applications.
- Crimped:Mechanical compression terminations enable field serviceability and rapid assembly in automotive wire harness production.
- Snap-In:Tool-free insertion mechanisms accelerate installation in dense patch panel and rack-mount connector configurations.
Unshielded twisted pair commands the highest shipment volumes while fiber optic technology expands most quickly in absolute revenue terms.
Application:
Application maturity curves separate established power transmission infrastructure from emerging data center buildouts with diverging procurement cadences.
- Data Centers:Hyperscale operators in Northern Virginia and Frankfurt specify pre-terminated fiber assemblies with MPO-16 and VSFF connectors for 400G/800G spine-leaf architectures. Active optical cables are displacing discrete transceiver-plus-cable combinations to reduce link loss budgets.
- Telecommunications:5G fronthaul and midhaul networks in China absorb massive volumes of weatherized fiber optic cable and hardened connector enclosures. MIIT certification requirements create localized compliance barriers for foreign suppliers seeking state-backed infrastructure tenders.
- Consumer Electronics:USB-C and HDMI 2.1 interfaces face margin compression despite sustained unit demand for smartphones, laptops, and display peripherals.
- Power Transmission:High-voltage underground and submarine cable systems link renewable generation assets to grid interconnection points.
- Aerospace Systems:Mil-spec qualified assemblies with temperature extremes ratings serve avionics and satellite payload applications.
- Military Equipment:Tactical communications and electronic warfare platforms require ruggedized connector systems with EMP hardening.
Telecommunications anchors the installed base while data center applications climb the fastest in procurement value.
End User Industry:
Customer type concentration varies sharply between capital-intensive infrastructure operators and cyclical electronics manufacturers with opposing inventory strategies.
- Telecom Operators:Tier-1 carriers in China, Germany, and the US negotiate multi-year framework agreements for outside plant cable and central office connector systems. REACH substance restrictions are forcing cadmium-free plating alloy reformulations that raise contact resistance in automotive-grade specifications.
- Data Storage Providers:Cloud operators consolidate vendor relationships around pre-tested assemblies carrying IEC 61300 and Telcordia GR-326 certifications to reduce field failure liability.
- Electronics Manufacturers:ODMs and OEMs in Taiwan and South Korea drive high-volume USB and HDMI connector demand with quarterly procurement cycles.
- Defense Contractors:Prime contractors serving US DoD and NATO programs require ITAR-controlled supply chains with traceable material certifications.
- Renewable Energy Firms:Solar and offshore wind developers specify medium-voltage inter-array cable and DC connector systems qualifying for US IRA domestic content bonuses.
- Transportation Systems:Indian Railways and European metro operators procure overhead line cable and pantograph connectors for electrification corridors.
Electronics manufacturers generate the highest transaction frequency while data storage providers deliver the steepest expansion trajectory in average contract value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across procurement contexts. Hyperscale data center operators in the United States prioritize performance over unit cost for fiber backbone upgrades, while residential construction markets in India and Southeast Asia drive hard bargains on copper building wire specifications.
United States
Northern Virginia and Oregon hyperscale clusters specify pre-terminated MPO-16 fiber assemblies for 800G spine architectures. FCC equipment authorization rules govern electromagnetic compatibility testing for telecommunications connector deployments. Cloud operators in Ashburn and Hillsboro consolidate vendor relationships around IEC 61300-certified assemblies to compress qualification timelines.
China
Domestic 5G infrastructure buildouts and submarine cable projects absorb massive connector volumes from state-backed tenders. MIIT certification requirements and GB standards create localized compliance barriers for foreign suppliers seeking rail and telecom procurement windows. Yangtze River Delta manufacturing clusters in Suzhou and Shanghai anchor fiber preform and specialty cable production capacity.
Germany
Industrial automation and automotive wire harness demand concentrates procurement for shielded connector systems and halogen-free cable compounds. EU F-Gas Regulation phase-down schedules mandate low-global-warming-potential blowing agents in jacketing foams by ECHA deadlines. Compounders in the Ruhr region and Bavaria reformulate LSZH grades to meet 2027 fleet average targets for automotive OEMs.
India
Dedicated freight corridors and metro electrification expansions open procurement windows for high-tension overhead line cable and pantograph connectors. Indian Railways and state metro corporations specify BIS-certified assemblies under CEA grid connectivity standards. Manufacturing clusters in Gujarat and Maharashtra scale domestic production of medium-voltage power cable to substitute imports.
Japan
Specialty fiber draw towers and preform suppliers concentrate upstream chokepoints for global cable integrators. METI industrial standards and JIS certification requirements govern precision connector specifications for automotive and robotics applications. Yokohama and Nagoya industrial corridors sustain captive supply of optical preforms that downstream assemblers depend upon.
Global Cables and Connector Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the cables and connector industry. Tier-one players command pricing power through captive supply of precision stamping, polymer compounding, and submarine installation fleets. Tier-two specialists concentrate on narrow application segments or regional procurement channels. Competitive dynamics revolve around vertical integration depth and certification breadth rather than manufacturing scale alone. M&A activity targets complementary certification portfolios and geographic coverage gaps. Strategic partnerships between compounders and cable integrators accelerate halogen-free material qualification timelines.
Among diversified industrial conglomerates, TE Connectivity and Amphenol Corporation exemplify the integrated archetype with broad certification coverage across automotive and aerospace segments. Molex occupies a position within the precision connector specialist tier, representing scale-driven manufacturing capabilities for high-volume electronics applications. Prysmian anchors the submarine and high-voltage transmission specialist segment, with fleet-based installation capabilities that differentiate project execution. These three players collectively illustrate the strategic segmentation between diversified industrial groups, precision component specialists, and infrastructure project integrators that defines competitive positioning in this market.
| Leading Market Players |
|---|
| TE Connectivity |
| Amphenol Corporation |
| Molex |
| Aptiv |
| Yazaki Corporation |
| Fujitsu Limited |
| Huawei Technologies |
| Nexans |
| Prysmian |
| Others |
Supply & Pricing Matrix
EU F-Gas Regulation phase-down schedules gate both supplier qualification and price differentiation simultaneously, forcing compounders toward halogen-free reformulations that compress margin pools for non-compliant producers while rewarding certified specialists with premium positioning in German and French procurement channels.
Pricing Analysis
After-sales service contracts and extended warranty bundles drive lifetime value for submarine cable installation fleets and precision connector specialists. Three-tier pricing structure across premium, standard, and economy levels separates IEC 61300-certified assemblies from commodity-grade alternatives, with certification tier and volume scale as primary differentiation levers. Cost compression in consumer-grade USB and HDMI segments intensifies because of Asian ODM oversupply, while hyperscale data center operators in Virginia and Oregon show minimal price sensitivity for terabit-scale fiber backbones.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for specialty fiber preforms and halogen-free polymer compounds. Manufacturing gravity centers on China, Japan, and the United States, with raw material dependencies spanning copper cathodes, optical glass preforms, and LSZH jacketing resins. Single-source vulnerability concentrates in Japanese specialty fiber draw towers, while distribution runs through authorized distributor networks carrying regional certification lab partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Cables and Connector Market sits at an inflection point where silicon photonics co-packaging and EU F-Gas halogen-free mandates are compressing legacy product lifecycles faster than incumbent reformulation cycles can accommodate.
For Market Incumbents: Compound certification breadth across FCC Part 15, CE marking, and GB/T standards to defend against emerging Asian challengers with narrower geographic coverage. Deepen backward integration into precision stamping and polymer compounding to preserve automotive connector margins against cadmium-free plating alloy cost inflation. Prioritize captive supply of optical preforms to offset chokepoint risk from Japanese specialty fiber suppliers. For New Entrants and Emerging Players: Lead with halogen-free cable compound qualification services for EU automotive wire harness suppliers facing 2027 fleet average deadlines. Target India's dedicated freight corridor electrification as the most penetrable infrastructure window, where BIS certification barriers remain lower than China's MIIT requirements. Build go-to-market credibility through regional certification lab partnerships in Gujarat or Maharashtra. For Investors and Strategic Acquirers: EU F-Gas Regulation reshapes the acquisition landscape toward compounders with validated LSZH formulations and automotive OEM qualification track records. Five-to-ten year viability favors vertically integrated specialists with submarine installation fleets or precision stamping capabilities rather than assembly-focused competitors. Watch fiber splicing technician training pipeline output as the inflection signal for field service capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Halogen-Free Material Qualification | EU F-Gas compliance deadlines force rapid reformulation of LSZH grades for automotive OEMs. |
| Submarine Cable Fleet Expansion | Prysmian and Nexans anchor intercontinental project execution through marine installation capabilities. |
| Silicon Photonics Integration | Co-packaged optics displace pluggable modules in Virginia and Oregon hyperscale spine architectures. |
| Regional Certification Lab Buildout | Distributors in Germany and South Korea compress qualification timelines for telecom infrastructure. |
| India Rail Electrification Partnership | Indian Railways and state metro corporations absorb high-tension overhead line cable volumes. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with fiber optic cable plant managers, automotive wire harness procurement leads, data center infrastructure engineers, and compounder R&D directors; and secondary validation through SEC 10-K filings, customs and trade data, FCC equipment authorization databases, and ECHA regulatory filings. Bottom-up and top-down triangulation cross-checked volume assumptions against capex disclosures from hyperscale operators and state-backed tender awards in China and India.
Across the analysis window, the forecast framework modeled segmentation dimensions including product type (fiber optic, Ethernet, coaxial, USB, HDMI, D-Sub), technology tier (shielded twisted pair, unshielded twisted pair, fiber optic), application (data center, telecommunications, consumer electronics, power transmission), and end-user industry (telecom operators, data storage providers, electronics manufacturers). CAGRs derived from installation fleet capacity expansion, 5G infrastructure deployment schedules, and AI data center buildout pipelines.
Forecasts assume regulatory continuity in EU F-Gas phase-down schedules, REACH substance restrictions, and China's MIIT certification requirements; material policy shifts would require re-modeling. Specific risk factors include copper price volatility on LME markets, optical component concentration in Japanese preform suppliers, and fiber splicing technician scarcity compressing field deployment timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
Asia-Pacific Connector Market
Connectors
Micro-Miniature Co-Axial Adapter Market
Connectors
Wire-To-Board Connector Market
Connectors
Relay Sockets Market
Connectors
Connector Market
Connectors
3C Electronics Precision Connectors Market
Connectors
Canada Connector Market
Connectors
Magnetic Connector Market
Connectors
AS-Interface Market
Connectors
Press Fit Connector Market
Connectors
Underwater Connectors Market
Connectors
LCP Connectors Market
Connectors
Small Bore Connectors Market
Connectors
India Connector Market
Connectors
Global Automotive Connector Market
Connectors
Global Multi Coaxial Connectors Market