
 Micro-Miniature Co-Axial Adapter Market | 2026-2036
Micro-Miniature Co-Axial Adapter Market Size, Share, and Industry Trends Forecast 2026-2036
Micro-Miniature Co-Axial Adapter Market Foresight
Modular packaging of adapter-to-cable assemblies is consolidating buyer preference toward pre-configured kits over discrete components. Amphenol RF leverages its vertical integration across connector and cable assembly lines to control lead times for aerospace primes. TE Connectivity sustains R&D intensity in high-frequency micro-miniature formats for 5G infrastructure. Rosenberger anchors European demand through specialized manufacturing of precision RF interfaces for automotive radar modules.
A micro-miniature co-axial adapter is a precision electromechanical interface, typically machined from beryllium copper or brass with gold-plated contacts, designed to transition signals between dissimilar coaxial geometries while maintaining impedance continuity below 3 millimeters in overall dimension. Its primary purpose is to preserve signal integrity in dense electronic assemblies where space constraints prohibit standard connector footprints. Coaxial adapters and micro-miniature links command the strongest margin pools due to tight tolerance requirements and limited qualified supplier bases. Surface mount installations are displacing panel mount configurations in consumer electronics and telecommunications equipment as device miniaturization accelerates.
FCC Part 15 emissions standards in the United States and the EU Radio Equipment Directive shape product certification requirements for micro-miniature co-axial adapters deployed in wireless and broadcast equipment. REACH restrictions on cadmium and lead content in the European Union compel manufacturers to reformulate plating chemistries and substrate alloys. Stakeholders must monitor evolving spectrum allocation decisions by national regulators and the transition toward millimeter-wave frequencies in telecommunications infrastructure.
Market Dynamics
Modular pre-configured adapter-to-cable kits are consolidating buyer preference and compressing margins for discrete component suppliers as aerospace primes and automotive radar developers prioritize integrated sourcing.
Growth Catalysts
- Satellite payload densification:Aerospace manufacturers are expanding procurement of micro-miniature formats for low-earth orbit constellations and inter-satellite links.
- EU Radio Equipment Directive:Tightening electromagnetic compatibility mandates are pushing suppliers toward higher-grade shielding designs and precision machining.
- Millimeter-wave telecommunications:5G infrastructure deployment is accelerating demand for sub-3-millimeter impedance-matched interfaces.
Market Restraints
- Beryllium copper supply concentration:Specialized copper-beryllium alloy sourcing clusters in limited qualified foundries, creating input cost volatility.
- REACH plating chemistry restrictions:European cadmium and lead content limits compel manufacturers to reformulate gold-plating processes at elevated compliance cost.
- Millimeter-wave insertion loss:Physical scaling limits in sub-2-millimeter geometries constrain signal integrity at frequencies above 40 GHz.
Strategic Opportunities
- Automotive radar module standardization:Precision RF interface demand from Stuttgart and Munich industrial clusters is expanding beyond premium vehicle segments.
- Surface mount displacement:Consumer electronics miniaturization is creating white space for tape-and-reel compatible micro-miniature formats.
- Avionics retrofit programs:Legacy aircraft electromagnetic compatibility upgrades are generating aftermarket pull for shielded adapter assemblies.
Industry Challenges
- Precision machining talent scarcity:Tolerance capabilities below 25 micrometers require specialized Swiss-turn operators with limited labor pool availability.
- FCC Part 15 certification timelines:Wireless equipment emissions testing creates extended product launch cycles for multi-band adapter families.
- Legacy panel mount integration:Existing telecommunications infrastructure retains threaded coupling interfaces, complicating surface mount transition roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micro-Miniature Co-Axial Adapter Market |
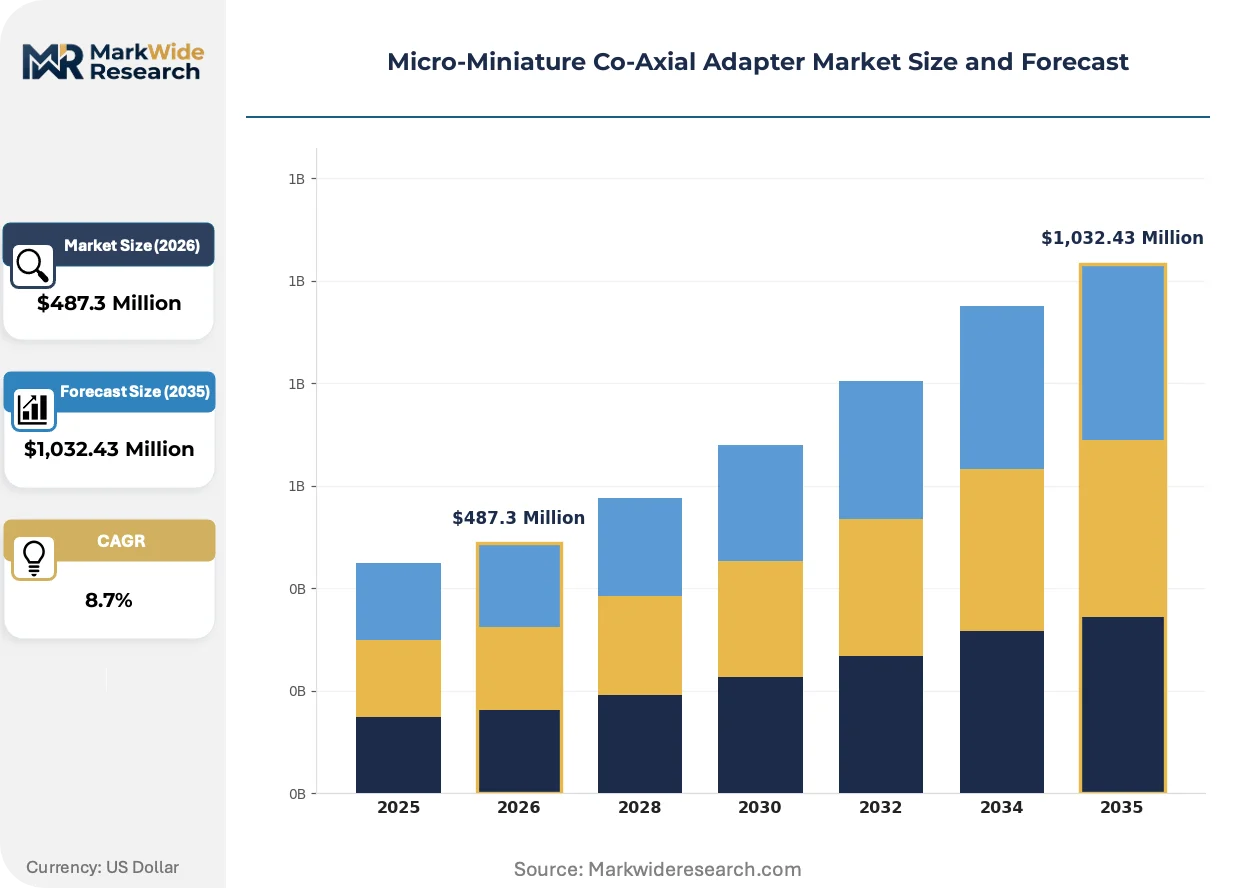
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coaxial Adapters, Coaxial Connectors, Coaxial Cables, Micro-Miniature Links End User: Aerospace, Telecommunications, Broadcasting, Consumer Electronics Installation: Surface Mount, Panel Mount, PCB Mount, Bulkhead Mount Application: Signal Transmission, Data Communication, RF Applications, Video Transmission |
| Companies Covered | Amphenol RF, TE Connectivity, HUBER+SUHNER, Radiall, Rosenberger, RF Industries, Emerson Electric, Molex, Pasternack Enterprises, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micro-Miniature Co-Axial Adapter Market Shifts & Advancements
Active developments across materials science, regulatory compliance frameworks, and procurement architectures are reconfiguring how micro-miniature co-axial adapters are specified, sourced, and deployed across end-use verticals.
Gold-over-nickel plating chemistries are expanding into aerospace and defense applications as REACH-compliant alternatives to legacy cadmium-bearing finishes. Prime contractors in satellite and avionics programs are qualifying these reformulated interfaces for multi-year operational lifecycles. The transition is expanding into high-reliability procurement specifications previously resistant to process change.
EU Radio Equipment Directive electromagnetic compatibility mandates are compelling manufacturers to redesign shielding geometries and grounding architectures. Industrial consequence includes elevated R&D allocation toward finite-element modeling of RF leakage paths. Automotive radar module suppliers in Germany are responding with dedicated validation laboratories for pre-certification testing.
Pre-configured adapter-to-cable assembly kits are displacing discrete component procurement across aerospace and telecommunications equipment manufacturers. Integrated sourcing reduces supplier qualification overhead and compresses incoming inspection workflows. The shift is most visible in Germany, where precision RF component clusters around Munich and Stuttgart serve both automotive radar and defense programs with consolidated kit deliveries.
Micro-Miniature Co-Axial Adapter Market Segmentation
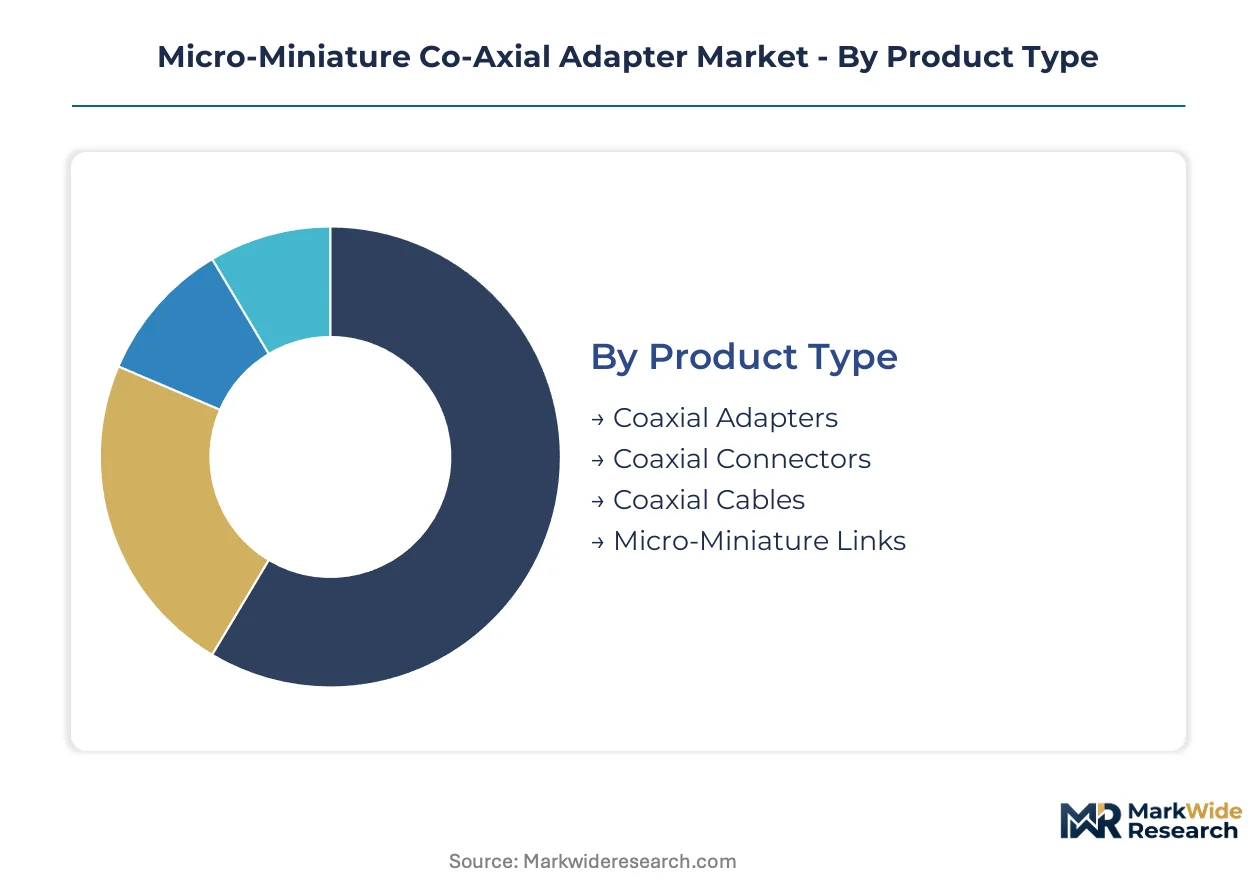
Segmentation in the micro-miniature co-axial adapter market reveals how supply chain concentration and technical specialization create distinct competitive arenas. Each dimension—product architecture, end-use requirements, mounting methodology, and signal application—carries unique margin profiles and supplier qualification barriers that shape procurement strategy.
Product Type:
Supply concentration varies sharply across product categories, with precision-machined interfaces commanding captive production networks while cable assemblies fragment across contract manufacturers.
- Coaxial Adapters:These impedance-matched transition interfaces, typically machined from beryllium copper with gold-plated contacts, maintain signal continuity between dissimilar connector geometries. German precision RF clusters around Munich and Stuttgart absorb the majority of European demand for automotive radar and satellite applications, driven by REACH-compliant plating mandates that disqualify lower-grade suppliers.
- Coaxial Connectors:Self-contained mating interfaces designed for repeated connection cycles in dense electronic assemblies. Aerospace manufacturers expanding procurement for low-earth orbit constellations concentrate orders with vertically integrated suppliers capable of Swiss-turn tolerance control below 25 micrometers.
- Coaxial Cables:Flexible or semi-rigid transmission lines with precision dielectric cores. Cable assembly integration into pre-configured kits is compressing discrete component margins as primes prioritize single-source accountability.
- Micro-Miniature Links:Sub-3-millimeter impedance-matched interfaces for extreme density applications. 5G infrastructure deployment in millimeter-wave bands is accelerating qualification programs for these formats.
Coaxial adapters absorb the bulk of installed capacity; micro-miniature links are expanding most quickly.
End User:
End-use segmentation maps directly to regulatory exposure and qualification intensity, with aerospace and automotive applications imposing the steepest supplier certification barriers.
- Aerospace:Satellite payload densification and avionics retrofit programs demand hermetic sealing, vibration resistance, and multi-year operational lifecycles. FCC Part 15 emissions standards and EU Radio Equipment Directive electromagnetic compatibility mandates extend product launch cycles for multi-band adapter families serving this segment.
- Telecommunications:Base station infrastructure and fiber-to-the-antenna deployments require high-volume, cost-optimized interfaces. The transition toward millimeter-wave frequencies in 5G infrastructure is reshaping specifications toward sub-2-millimeter geometries with constrained insertion loss budgets.
- Broadcasting:Professional video and radio transmission equipment maintains legacy threaded coupling interfaces while gradually adopting surface mount formats for new designs.
- Consumer Electronics:Smartphone, wearable, and IoT device manufacturers drive tape-and-reel compatible packaging requirements. Miniaturization acceleration is displacing panel mount configurations in favor of automated assembly-compatible formats.
Aerospace commands the premium tier of supplier margins; consumer electronics is climbing the fastest in absolute volume terms.
Installation:
Mounting methodology segmentation tracks the broader transition from mechanical fastening to automated assembly in electronics manufacturing.
- Surface Mount:Tape-and-reel compatible formats for pick-and-place assembly. Consumer electronics and telecommunications equipment manufacturers are consolidating procurement toward these configurations as device miniaturization accelerates.
- Panel Mount:Threaded or snap-in interfaces for chassis penetration. Legacy telecommunications infrastructure retains these configurations, complicating surface mount transition roadmaps for retrofit-focused suppliers.
- PCB Mount:Direct solder attachment to printed circuit boards with minimal above-board height. Avionics retrofit programs generate aftermarket pull for shielded PCB mount adapter assemblies.
- Bulkhead Mount:Flanged interfaces for sealed enclosure penetration. Aerospace applications requiring environmental sealing concentrate demand with specialized manufacturers.
Panel mount retains the largest installed base; surface mount is gaining share fastest across new design wins.
Application:
Application segmentation distinguishes between power handling, frequency range, and signal integrity requirements that dictate materials selection and shielding architecture.
- Signal Transmission:General-purpose analog and digital signal routing with moderate frequency requirements. Automotive radar module standardization in German industrial clusters is expanding precision RF interface demand beyond premium vehicle segments.
- Data Communication:High-speed digital interfaces with tight impedance control and low crosstalk specifications. Data center and enterprise networking equipment drives demand for controlled-geometry adapters.
- RF Applications:Radio frequency signal paths from sub-GHz through millimeter-wave bands. Finite-element modeling of RF leakage paths is elevating R&D allocation for shielding geometry optimization in this segment.
- Video Transmission:Broadcast-quality analog and digital video signal interfaces. Professional broadcasting equipment maintains steady demand for 75-ohm precision interfaces with return loss optimization.
RF applications concentrate the highest technical barriers to entry; data communication is showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in precision machining clusters across Germany, Japan, and the United States, while consumption disperses through aerospace programs in France, telecommunications infrastructure in South Korea, and automotive radar development in China. This geographic split creates complex supply chain coordination between high-tolerance manufacturing centers and application-specific demand nodes.
United States
FCC Part 15 emissions standards govern wireless equipment certification, extending product launch cycles for multi-band adapter families serving aerospace and telecommunications sectors. The Federal Communications Commission maintains strict electromagnetic compatibility testing protocols that disqualify non-compliant suppliers from defense and commercial aviation procurement. California's aerospace corridor and Massachusetts precision manufacturing belt absorb the majority of domestic demand for hermetically sealed avionics interfaces.
Germany
REACH restrictions on cadmium and lead content compel manufacturers to reformulate gold-plating chemistries for automotive radar and satellite applications. The EU Radio Equipment Directive mandates elevated shielding performance that pushes suppliers toward finite-element modeling investments. Munich and Stuttgart precision RF clusters serve both premium automotive radar programs and defense procurement with consolidated kit deliveries.
Japan
METI industrial policy supports domestic production of high-frequency micro-miniature formats for 5G infrastructure and satellite communications. The Ministry of Economy, Trade and Industry coordinates supply chain resilience initiatives for critical RF component manufacturing. Tokyo-Osaka industrial corridors maintain captive Swiss-turn machining capacity for sub-25-micrometer tolerance requirements.
China
MIIT spectrum allocation decisions shape millimeter-wave telecommunications infrastructure deployment and associated adapter specifications. The Ministry of Industry and Information Technology governs radio equipment type approval that filters market access for imported precision RF interfaces. Yangtze River Delta electronics manufacturing clusters drive tape-and-reel compatible packaging demand for consumer electronics integration.
South Korea
MFDS medical device regulations intersect with telecommunications equipment standards for wearable health monitoring devices requiring micro-miniature RF connectivity. The Ministry of Food and Drug Safety coordinates with radio regulators on converged product categories. Seoul Capital Area semiconductor and telecommunications equipment manufacturers represent the fastest-growing demand node for sub-3-millimeter impedance-matched interfaces.
Micro-Miniature Co-Axial Adapter Market Competitive Landscape
The competitive structure tilts toward vertically integrated connector specialists with captive precision machining capacity. Tier-one aerospace primes and automotive radar developers consolidate procurement with suppliers controlling Swiss-turn tolerance capabilities below 25 micrometers. Three archetypes dominate: integrated connector-cable assemblers, precision RF interface specialists, and diversified industrial component conglomerates. Capacity expansion in German and Japanese machining clusters and strategic partnerships for REACH-compliant plating chemistry access constitute the primary competitive moves.
Among integrated connector specialists, Amphenol RF and TE Connectivity occupy positions exemplifying backward integration into cable assembly lines and high-frequency format R&D intensity respectively. Rosenberger anchors European demand through specialized manufacturing archetypes serving automotive radar modules. These three entities represent distinct strategic postures: Amphenol RF exemplifies supply chain control through in-house production, TE Connectivity represents sustained technology investment in millimeter-wave formats, and Rosenberger occupies the precision RF interface specialist position within German industrial clusters.
| Leading Market Players |
|---|
| Amphenol RF |
| TE Connectivity |
| HUBER+SUHNER |
| Radiall |
| Rosenberger |
| RF Industries |
| Emerson Electric |
| Molex |
| Pasternack Enterprises |
| Others |
Supply & Pricing Matrix
Swiss-turn machining talent clusters in southern Germany and the Tokyo-Osaka corridor feed labor-cost differentials into pricing-tier spreads across precision RF component procurement. Aerospace primes absorbing REACH-compliant plating upgrades pass certification premiums through to tier-one suppliers, while automotive radar developers in Stuttgart negotiate volume-scale discounts that compress margins for discrete component vendors.
Pricing Analysis
Cost-down pressure on standard-grade adapters accelerates because telecommunications OEMs are consolidating procurement toward pre-configured kits with single-source accountability. Three-tier pricing structure across aerospace-qualified, automotive-grade, and consumer-electronics tiers separates gold-over-nickel plated hermetic interfaces from standard brass-body formats. REACH-compliant plating chemistry investments and Swiss-turn tolerance capabilities below 25 micrometers drive premium-tier pricing. Consumer electronics buyers exhibit highest price sensitivity; aerospace primes prioritize qualification reliability over unit cost.
Supply Chain Analysis
Domestic-content mandates in Japanese 5G infrastructure programs and European defense procurement are reshaping sourcing toward captive machining clusters in Japan, Germany, and the United States. Beryllium copper alloy feedstock draws from limited qualified foundries in the United States and Japan, while gold-plating chemistries hinge on ECHA-registered suppliers. Single-source vulnerability concentrates in Swiss-turn machining capacity for sub-25-micrometer tolerances. Distribution runs through authorized distributor networks serving aerospace primes and direct OEM contracts for automotive radar developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The micro-miniature co-axial adapter market sits in a technology-transition phase as surface mount formats displace legacy panel mount configurations across telecommunications and consumer electronics applications.
For Market Incumbents: Anchor certification leadership by qualifying gold-over-nickel plating chemistries for multi-year aerospace lifecycles before REACH restrictions harden. Deepen backward integration into cable assembly lines to defend kit-based procurement consolidation. Prioritize finite-element modeling capacity for millimeter-wave shielding optimization as 5G infrastructure specifications tighten.
For New Entrants and Emerging Players: Millimeter-wave test equipment specialization offers a technology-first wedge into pre-certification laboratory services for German automotive radar developers. Target tape-and-reel compatible surface mount formats for South Korean telecommunications equipment manufacturers where incumbent qualification timelines create white space. Pursue foundry partnerships for REACH-compliant plating chemistry access rather than captive process development.
For Investors and Strategic Acquirers: Re-rating potential sits with precision RF interface specialists possessing captive Swiss-turn capacity given EU Radio Equipment Directive shielding mandates. Five-to-ten-year viability favors suppliers with dual-use aerospace-automotive certification breadth. Monitor MIIT spectrum allocation decisions for millimeter-wave bands as inflection indicators for sub-3-millimeter format demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Finite-Element Modeling Investment | Elevated R&D allocation for RF leakage path simulation meets EU Radio Equipment Directive mandates. |
| Plating Chemistry Reformulation | Gold-over-nickel process qualification expands aerospace procurement access under REACH restrictions. |
| Cable Assembly Integration | Pre-configured kit delivery compresses supplier qualification overhead for aerospace primes. |
| Surface Mount Format Development | Tape-and-reel compatibility captures consumer electronics miniaturization acceleration. |
| Pre-Certification Laboratory Buildout | Dedicated validation capacity accelerates German automotive radar module time-to-market. |
Research Methodology
Multi-period observation of satellite payload procurement cycles, REACH compliance timelines, and 5G infrastructure deployment rates anchored the trend analysis, supplemented by interviews with RF component procurement managers at aerospace primes, Swiss-turn machining operators in German precision clusters, plating chemistry technical directors, and telecommunications equipment sourcing leads. Secondary validation drew from ECHA substance restriction filings, FCC Part 15 equipment authorization databases, MIIT spectrum allocation notices, and EU Radio Equipment Directive implementation guidance. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Segment-weighting across product architecture, end-use vertical, mounting methodology, and signal application dimensions structured the analytical framework across the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating millimeter-wave frequency adoption curves and automotive radar module penetration assumptions. Industry-specific forecast inputs included satellite constellation deployment schedules and EU defense procurement program timelines.
Several conditions sit outside the modeled scope, including geopolitical disruption to beryllium copper supply, unannounced regulatory revisions to electromagnetic compatibility testing protocols, and breakthrough displacement of coaxial interfaces by photonic interconnect technologies. Forecasts reflect documented assumptions regarding REACH enforcement intensity and 5G spectrum allocation continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
USB Type-C Market
Connectors
Global Multi Coaxial Connectors Market
Connectors
Circular Waterproof Connector Market
Connectors
Small Bore Connectors Market
Connectors
Global Board to Board (BTB) Connectors Market
Connectors
Cable Connectors and Adapters Market
Connectors
IC Socket Market
Connectors
Australia Connector Market
Connectors
Telecom Mounting Hardware Market
Connectors
Canada Connector Market
Connectors
Magnetic Connector Market
Connectors
Circular Connectors Market
Connectors
AS-Interface Market
Connectors
Connector Kits Market
Connectors
Press Fit Connector Market
Connectors
Hybrid Fiber Optic Connectors Market