
 Filtered Connectors Market | 2026-2036
Filtered Connectors Market Size, Share, and Industry Trends Forecast 2026-2036
Filtered Connectors Market Analysis
Defense prime contractors is rotating toward higher-reliability interconnect specifications as commercial telecom capital expenditure moderates. TE Connectivity leverages captive filter manufacturing to secure long-term military supply agreements. Amphenol anchors its position through backward integration into ceramic capacitor and ferrite assembly operations. Smiths Interconnect competes on hermetic sealing expertise for satellite and radar platforms.
Filtered connectors integrate passive electromagnetic interference suppression elements—typically ferrite beads, pi-filter arrays, or feedthrough capacitors—within a conductive shell to attenuate conducted and radiated noise across specified frequency bands while maintaining signal integrity in high-density electronic assemblies. RF Technology leads volume shipments due to proliferation of microwave and millimeter-wave defense systems, while Hybrid Technology represents the fastest-expanding segment as designers merge analog filtering with digital signal conditioning in single-package solutions. Band-Pass Filters command premium positioning where precise frequency selectivity protects sensitive receivers from adjacent-channel interference.
FCC Part 15 emissions limits in the United States, EU EMC Directive compliance frameworks, and MIL-STD-461G test methodologies collectively define the certification landscape for filtered connector suppliers. EMA and FDA requirements in Europe and the United States respectively extend into medical device applications where patient safety depends on isolation from power-line disturbances. Stakeholders must monitor evolving spectrum allocation decisions and defense procurement cycles to align R&D roadmaps with the next generation of platform-specific interconnect standards.
Market Dynamics
Defense procurement cycles and electromagnetic compatibility mandates are compressing supplier qualification timelines while elevating performance thresholds for interconnect systems across avionics, radar, and electronic warfare platforms.
Growth Catalysts
- MIL-STD-461G revisions:The United States Department of Defense tightened conducted emissions test limits, forcing platform integrators to specify higher-attenuation filtered connectors for ground and airborne systems.
- EU EMC Directive enforcement:European market surveillance authorities expanded factory inspections for industrial automation equipment, accelerating replacement of unfiltered interconnects in German automotive OEM production lines.
- GaN radar proliferation:Gallium nitride transmitters in next-generation phased arrays generate broader harmonic content, necessitating integrated pi-filter connectors to protect receiver chains from co-site interference.
Market Restraints
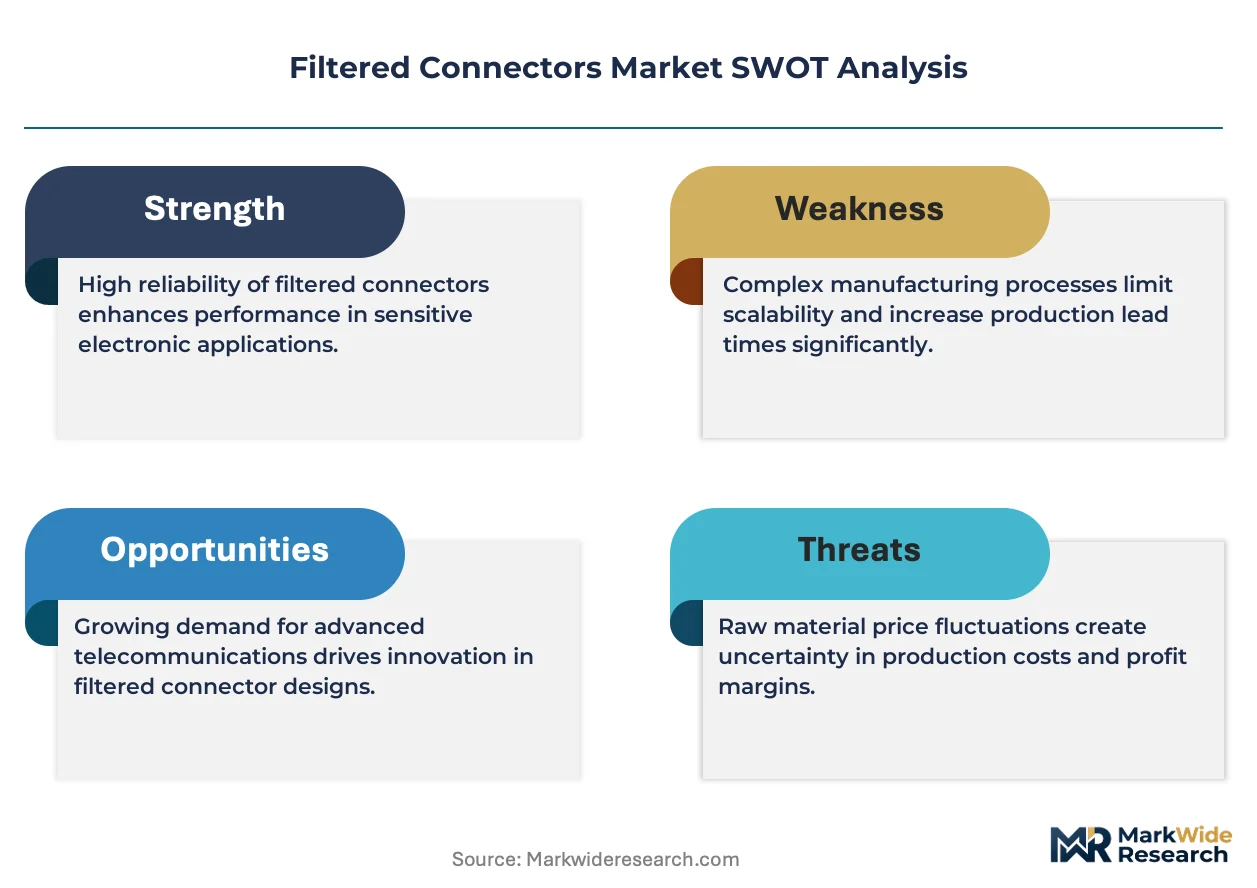
- Raw material concentration:High-purity ferrite powders and specialty ceramic dielectrics originate from limited East Asian suppliers, exposing connector manufacturers to input volatility and qualification delays.
- Hermetic sealing capability scarcity:Only a handful of facilities worldwide maintain the vacuum brazing and helium leak-testing infrastructure required for satellite-grade filtered feedthroughs.
- Substitution by board-level filtering:Dense surface-mount filter arrays on printed circuit boards reduce connector pin counts in some commercial telecom applications, though this fails in high-reliability military environments.
Strategic Opportunities
- Indian defense indigenization:The country's defense procurement policies prioritize domestic sourcing for avionics subsystems, creating openings for local connector assembly partnerships with technology transfer.
- Hybrid analog-digital integration:Combining ferrite-based EMI suppression with active signal conditioning electronics in single hermetic packages addresses emerging needs in software-defined radio architectures.
- Medical device isolation standards:FDA 510(k) requirements for patient leakage current in diagnostic imaging equipment extend filtered connector demand into magnetic resonance and computed tomography system upgrades.
Industry Challenges
- Interconnect physicist talent scarcity:The specialized knowledge bridging electromagnetic theory, materials science, and precision machining resides in an aging workforce with limited university pipeline replenishment.
- Platform-specific qualification timelines:Each defense prime contractor maintains proprietary test protocols, forcing suppliers to replicate validation campaigns rather than leverage cross-program certifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Filtered Connectors Market |
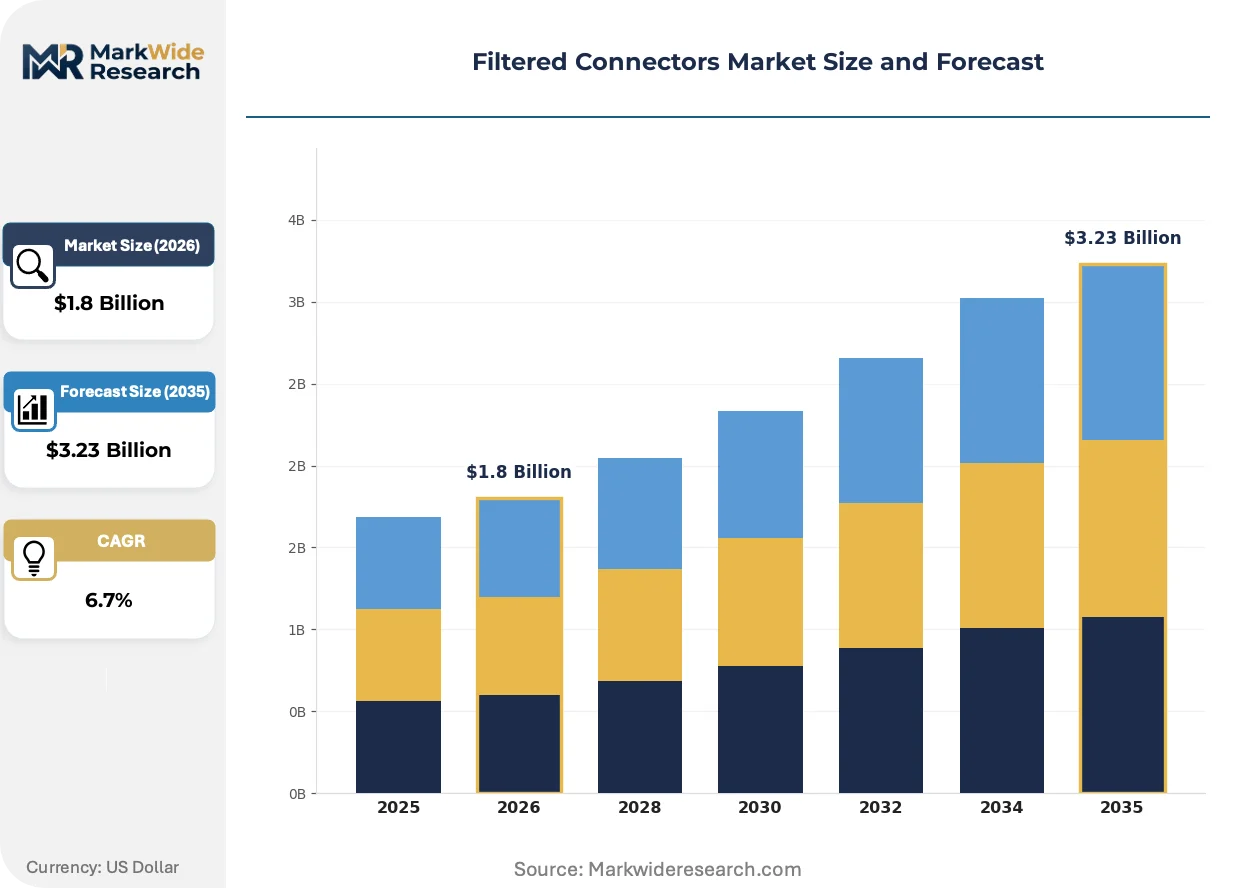
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low-Pass Filters, High-Pass Filters, Band-Pass Filters, Notch Filters End User: Telecommunications, Aerospace, Automotive, Medical Devices Technology: RF Technology, Analog Technology, Digital Technology, Hybrid Technology Application: Data Communication, Power Distribution, Signal Processing, Test Equipment |
| Companies Covered | Amphenol, TE Connectivity, Smiths Interconnect, Carlisle Companies, Glenair, HARTING Technology Group, ITT Cannon, Cristek Interconnects, AEI Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Filtered Connectors Market Emerging Trajectories
Material science breakthroughs and regulatory test-method evolutions are redefining how electromagnetic interference suppression integrates into physical interconnect architectures without sacrificing signal density or environmental sealing.
Additive manufacturing of complex ferrite geometries is displacing conventional pressed-powder cores in custom filter assemblies. Defense contractors in the United States are qualifying laser-sintered magnetic structures for satellite payloads where mass and volume constraints are absolute. This fabrication approach is displacing traditional machined housings by enabling integrated cooling channels and three-dimensional field shaping previously unattainable.
REACH substance restrictions on hexavalent chromium coatings are accelerating conversion to zinc-nickel plating and conductive polymer finishes across European supply chains. Connector shell manufacturers face reformulation of passivation chemistries to maintain salt-spray corrosion resistance without the banned hexavalent chromium conversion layers. Medical device and aerospace suppliers serving the European market are front-loading qualification budgets to complete alternative coating validation before sunset dates.
Platform prime contractors are consolidating vendor lists around suppliers offering captive filter design, environmental testing, and logistics integration as a bundled capability. The traditional model of discrete connector procurement followed by third-party filter integration is contracting in favor of single-source accountability. This consolidation pattern is most visible in United States Navy shipboard electronics and German rail signaling system upgrades.
Filtered Connectors Market Segmentation
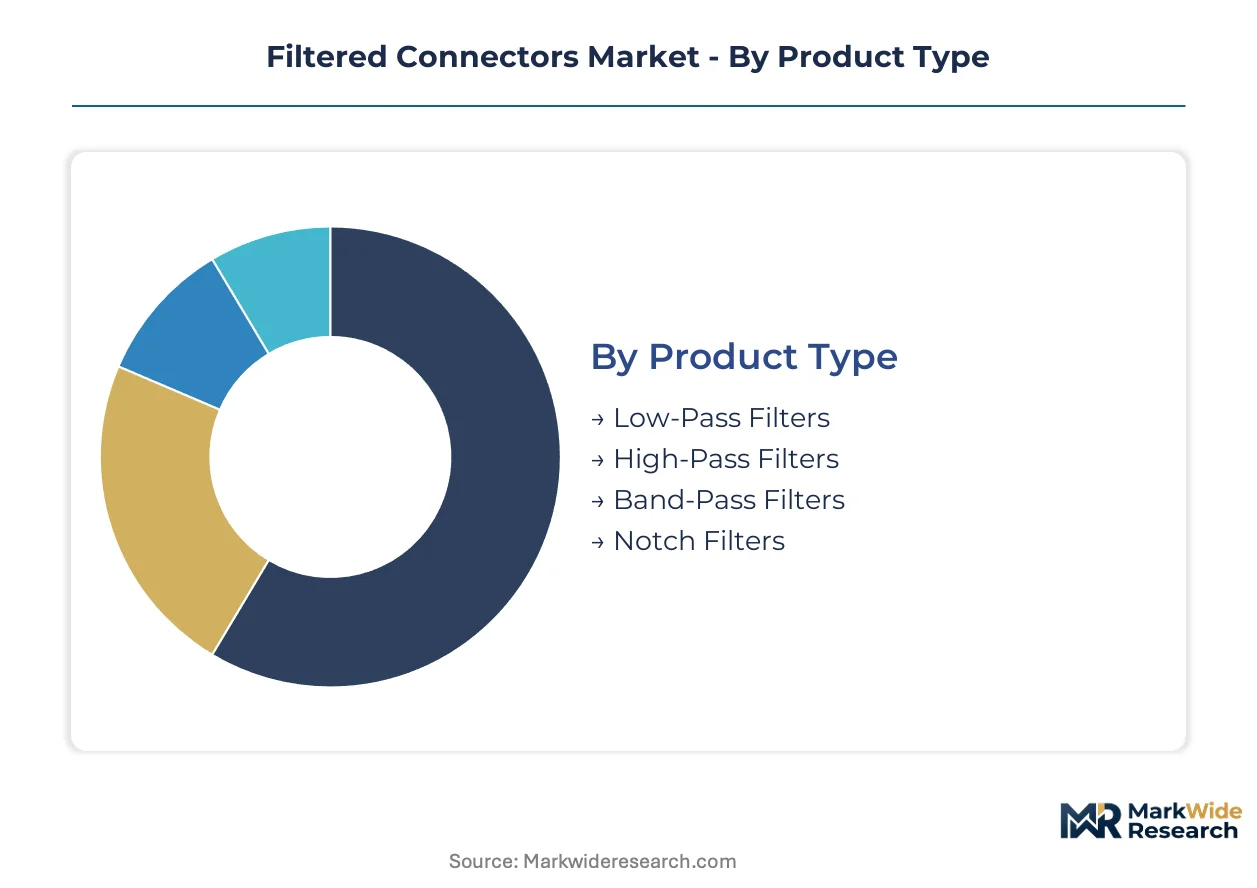
Filtered connectors serve fundamentally different electromagnetic interference suppression requirements across frequency domains, end-use platforms, and integration architectures. Segmentation reveals how regulatory thresholds, platform reliability grades, and signal density constraints reshape procurement specifications for each category.
Product Type:
FCC Part 15 emissions limits and MIL-STD-461G test methodologies impose distinct attenuation specifications that differentiate connector procurement across filter architectures.
- Low-Pass Filters:These configurations attenuate high-frequency noise above a defined cutoff while passing DC and low-frequency signals. Defense contractors specify these for ground vehicle power entry modules where conducted emissions testing under MIL-STD-461G mandates aggressive suppression of switching harmonics from motor drives and inverters.
- Band-Pass Filters:Precise frequency selectivity protects sensitive receiver chains from adjacent-channel interference in crowded electromagnetic environments. Satellite payload manufacturers command premium positioning for these connectors, as co-site interference from onboard transmitters threatens mission-critical telemetry links.
- High-Pass Filters:Block low-frequency interference while preserving microwave and millimeter-wave signal paths in radar front ends.
- Notch Filters:Target narrow interference bands at specific nuisance frequencies without degrading passband performance across the remainder of the spectrum.
Low-Pass Filters handle the majority of throughput; Band-Pass Filters is the fastest mover on share.
End User:
Platform reliability tiers and certification burdens segment demand across verticals with divergent qualification timelines and performance penalties for failure.
- Aerospace:Hermetic sealing requirements and outgassing constraints dominate specification sheets for satellite and manned aircraft applications. German automotive OEMs actually drive specialized connector requirements through industrial automation clusters, but aerospace primes impose the most exhaustive environmental testing protocols including thermal vacuum cycling and mechanical shock qualification.
- Telecommunications:Commercial capital expenditure moderation has compressed procurement volumes, though 5G base station densification sustains demand for outdoor-rated filtered interconnects. Tower-mounted electronics require IP67 environmental sealing combined with lightning surge protection integrated into the connector shell.
- Automotive:Electric vehicle inverter switching frequencies and onboard charger harmonics necessitate connector-level filtering to meet CISPR 25 vehicle emissions standards.
- Medical Devices:FDA 510(k) submissions for diagnostic imaging equipment mandate patient leakage current limits that filtered connectors help satisfy through enhanced isolation.
Aerospace commands the highest unit economics; Medical Devices is expanding most quickly as diagnostic imaging upgrade cycles accelerate.
Technology:
Integration depth and signal conditioning complexity separate technology tiers, with hybrid approaches commanding development attention from defense primes.
- Hybrid Technology:Merging ferrite-based EMI suppression with active signal conditioning electronics in single hermetic packages addresses software-defined radio architectures. Defense contractors in the United States are qualifying these for next-generation electronic warfare platforms where analog-digital boundaries blur.
- RF Technology:Volume shipments concentrate here due to proliferation of microwave and millimeter-wave defense systems. Phased array radar programs consume substantial quantities of precision RF filtered connectors with tight impedance control and minimal insertion loss.
- Analog Technology:Passive ferrite and ceramic filter elements dominate legacy platform sustainment and cost-constrained commercial applications.
- Digital Technology:Active filtering with programmable response characteristics enables field-configurable electromagnetic compatibility adaptation.
RF Technology maintains volume leadership; Hybrid Technology shows the steepest expansion trajectory as platform architects consolidate functions.
Application:
Signal integrity requirements and power handling specifications segment applications by the physical layer functions performed.
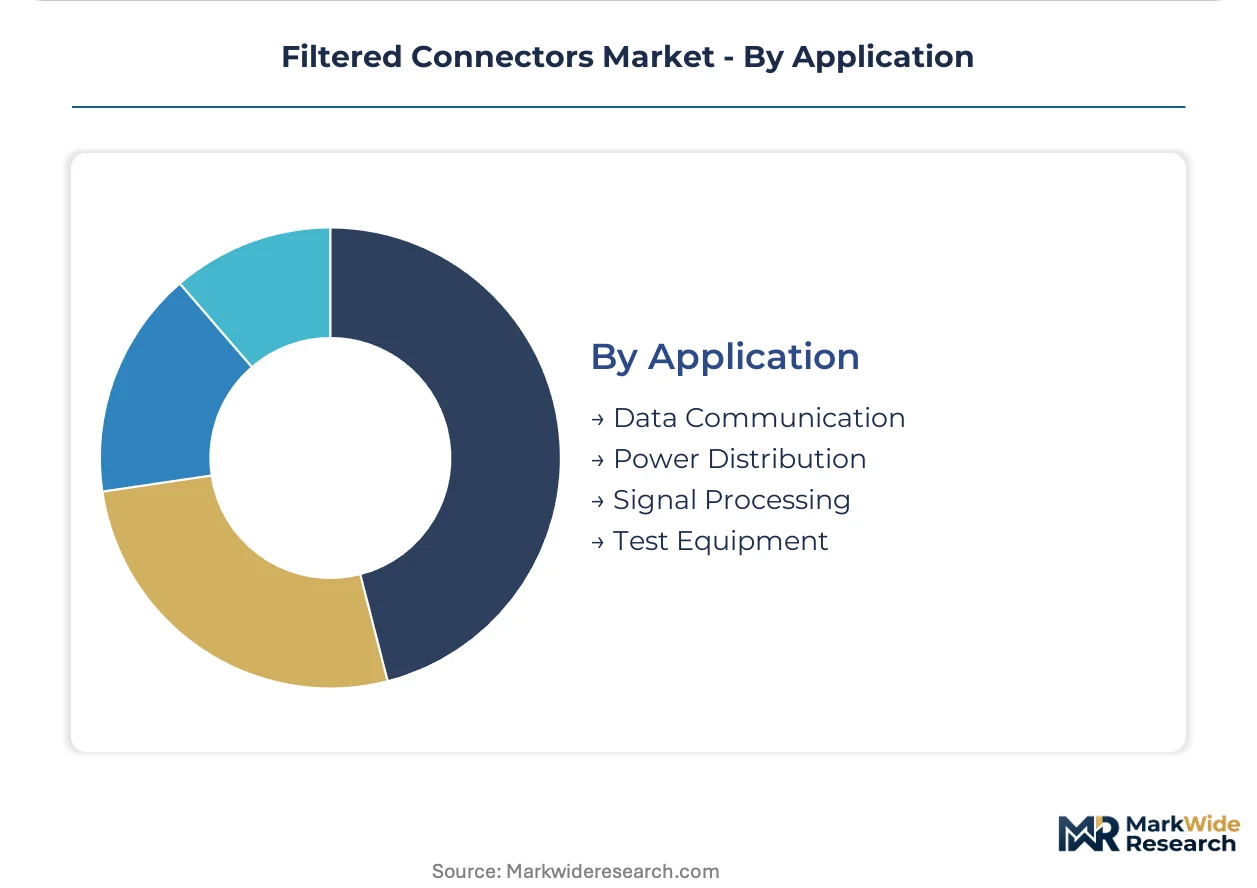
- Signal Processing:High-fidelity analog signal chains in radar and electronic warfare demand connectors with minimal phase distortion and flat group delay across operational bandwidths. Receiver protection from co-site interference drives specification of integrated pi-filter connectors in GaN transmitter environments.
- Data Communication:High-speed digital interfaces require controlled impedance and crosstalk suppression in dense backplane configurations. Data centers and military command systems prioritize these specifications for reliable throughput.
- Power Distribution:Current-carrying capacity and thermal management constrain filter integration in high-power applications.
- Test Equipment:Calibration-grade connectors with known, repeatable filter characteristics support measurement accuracy in electromagnetic compatibility test chambers.
Signal Processing absorbs the greatest engineering attention; Data Communication is climbing the fastest on investment priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty ferrite and ceramic suppliers cluster in East Asian manufacturing hubs, creating input dependencies for connector fabricators across defense and industrial verticals. German automotive OEMs and United States defense primes drive differentiated specification requirements. Regulatory divergence between FCC emissions frameworks and EU EMC Directive enforcement patterns fragments certification strategies.
United States
Defense procurement cycles for electronic warfare and satellite platforms sustain demand for hermetic filtered feedthroughs with MIL-STD-461G qualification. The Department of Defense's GaN radar investments expand harmonic suppression requirements. Southern California and Massachusetts defense corridors concentrate prime contractor engineering resources.
Germany
Automotive OEM inverter switching frequencies and industrial automation clusters drive specialized low-pass connector specifications. REACH substance restrictions on hexavalent chromium coatings accelerate plating chemistry transitions. Stuttgart and Munich engineering centers anchor EMC compliance testing infrastructure.
China
Domestic defense indigenization policies and commercial telecom infrastructure deployment sustain volume demand for RF filtered interconnects. MIIT spectrum allocation decisions reshape millimeter-wave filter bandwidth requirements. Shenzhen and Chengdu electronics manufacturing corridors concentrate assembly capacity.
Japan
Precision machining heritage and satellite component export controls position domestic suppliers in high-reliability niche segments. METI technology roadmaps prioritize additive manufacturing for ferrite geometries. Nagoya industrial automation and Tokyo aerospace engineering clusters maintain qualification expertise.
India
Defense procurement localization mandates under Make in India initiatives create openings for connector assembly partnerships with technology transfer provisions. BIS certification requirements for industrial equipment tighten EMC compliance verification. Bengaluru avionics and Hyderabad defense R&D corridors concentrate subsystem integration activity.
Filtered Connectors Market Vendor Landscape
Concentration sits with diversified interconnect conglomerates possessing captive filter manufacturing and hermetic sealing capabilities. The vendor base spans three tiers: integrated defense-aerospace specialists with platform qualification heritage, broad-line industrial connector houses with regional distribution density, and niche RF filter boutiques serving satellite and test equipment verticals. Strategic moves center on backward integration into ceramic capacitor and ferrite core supply chains, plus bundled design-test-logistics service packaging for prime contractor vendor consolidation programs.
Among United States-based defense-aerospace specialists, Amphenol and TE Connectivity exemplify the integrated archetype through in-house filter element production and multi-platform qualification portfolios. Smiths Interconnect occupies a position within the hermetic sealing specialist tier, anchoring expertise for satellite and radar feedthrough applications. These three entities represent the competitive core around which vendor consolidation patterns in United States Navy shipboard electronics and German rail signaling upgrades currently organize.
| Leading Market Players |
|---|
| Amphenol |
| TE Connectivity |
| Smiths Interconnect |
| Carlisle Companies |
| Glenair |
| HARTING Technology Group |
| ITT Cannon |
| Cristek Interconnects |
| AEI Group |
| Others |
Supply Flow & Price Mechanics
MIL-STD-461G qualification gates simultaneously constrain supplier pools and stratify price tiers, as defense primes demand traceable test documentation that only captive filter manufacturers can economically provide. This regulatory anchor forces procurement officers to balance unit cost against single-source accountability, compressing margins for undifferentiated catalog products while elevating premiums for platform-specific hermetic assemblies.
Pricing Analysis
MIL-STD-461G dictates the pricing tier structure across the filtered connector market, separating satellite-grade hermetic feedthroughs from commercial industrial variants. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden, with FDA 510(k) medical device connectors commanding mid-tier positioning between defense-aerospace premiums and cost-constrained telecom economy lots. Cost compression in standard-grade industrial automation connectors is intensifying because German automotive OEMs consolidate vendor lists around bundled design-test-logistics providers. Telecom infrastructure buyers exhibit highest price sensitivity due to capital expenditure moderation, while satellite payload integrators show least sensitivity given mission-critical failure costs.
Supply Chain Analysis
Container availability fluctuations on East Asian trade lanes periodically disrupt ferrite powder and specialty ceramic dielectric inbound flows to connector fabricators in the United States and Germany. Manufacturing concentration centers on Japan, China, and South Korea for high-purity ferrite cores and precision-machined conductive shells. Raw material dependencies include rare-earth-doped ferrite formulations, noble metal plating chemistries, and ceramic capacitor dielectrics. Single-source vulnerability persists for vacuum brazing equipment capable of satellite-grade hermetic sealing, with only a handful of qualified facilities worldwide. Distribution runs through authorized defense-aerospace distributors with MIL-STD-129 traceability requirements, plus direct OEM contracts for platform prime contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defense procurement cycles are recovering from commercial telecom capital expenditure troughs, with GaN radar investments and electronic warfare platform upgrades driving cyclical demand inflection. Platform prime contractor vendor consolidation programs reward suppliers offering captive filter design and environmental testing as bundled capabilities.
For Market Incumbents: Compound platform qualification heritage into long-term sole-source agreements with United States Navy shipboard electronics and German rail signaling upgrade programs. Threat from board-level surface-mount filter substitution in commercial telecom requires defensive certification investment in MIL-STD-461G hermetic capabilities that board-level alternatives cannot replicate. Backward integration into ceramic capacitor and ferrite core supply chains anchors margin control against East Asian input volatility.
For New Entrants and Emerging Players: Anchor in Indian defense indigenization partnerships under Make in India technology transfer provisions, where domestic sourcing mandates create white-space openings for connector assembly joint ventures. Medical device diagnostic imaging upgrades represent the most penetrable segment given FDA 510(k) patient leakage current requirements that filtered connectors uniquely satisfy. Go-to-market angle should emphasize rapid qualification support for OEMs facing REACH substance restriction deadlines on hexavalent chromium coatings.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hybrid analog-digital filtered connector architectures, where active signal conditioning electronics integration demands semiconductor packaging capabilities foreign to traditional passive filter suppliers. Five-to-ten-year viability favors acquirers of hermetic sealing specialists with satellite payload heritage, as low-Earth orbit constellation deployments sustain demand for qualified feedthrough manufacturers. Signal to monitor: additive manufacturing adoption rates for laser-sintered ferrite geometries, which may displace conventional pressed-powder core suppliers unable to retool.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Filter Manufacturing Integration | TE Connectivity and Amphenol secure long-term military supply agreements through in-house pi-filter and ferrite bead production. |
| Hermetic Sealing Capability Acquisition | Smiths Interconnect defends satellite and radar platform positioning through vacuum brazing expertise unavailable from broad-line competitors. |
| Additive Manufacturing Qualification | Defense contractors in the United States are qualifying laser-sintered ferrite structures for mass-constrained satellite payloads. |
| REACH Compliance Plating Transition | European automotive OEMs front-load qualification budgets to complete zinc-nickel alternative coating validation before hexavalent chromium sunset dates. |
| Hybrid Analog-Digital Filter Development | Software-defined radio architectures drive fastest-expanding technology segment as designers merge EMI suppression with active signal conditioning. |
Methodological Framework
A spread of perspectives from defense procurement officers, connector design engineers, platform qualification managers, and hermetic sealing specialists converged on the working assumptions underlying this analysis. Primary interviews with subsystem integrators at Southern California and Massachusetts defense corridors, plus Stuttgart automotive EMC testing centers, were cross-referenced against secondary validation from United States Department of Defense budget justification materials, EU EMC Directive enforcement bulletins, and FDA 510(k) clearance databases. Bottom-up build-ups of connector shipments by filter architecture were triangulated against top-down defense procurement cycle analysis.
Segmentation dimensions modeled include product type (low-pass, band-pass, high-pass, notch), end user (aerospace, telecommunications, automotive, medical devices), technology tier (RF, hybrid, analog, digital), and application (signal processing, data communication, power distribution, test equipment) across the projection horizon. CAGRs were derived from platform-specific qualification timeline analysis and defense procurement cycle phasing. Industry-specific forecast inputs include GaN radar deployment schedules and diagnostic imaging equipment upgrade cycles.
Material uncertainties — raw material concentration in East Asian ferrite suppliers, hermetic sealing facility scarcity, and substitution by board-level filtering in commercial segments — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory stability and defense budget continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
Mexico Connector Market
Connectors
Global Wired Interface Market
Connectors
Middle East Connector Market
Connectors
Global Automotive Connector Market
Connectors
Small Bore Connectors Market
Connectors
Australia Connector Market
Connectors
Connector Market
Connectors
Underwater Connectors Market
Connectors
Japan Connector Market
Connectors
Asia-Pacific Connector Market
Connectors
Micro-Miniature Co-Axial Adapter Market
Connectors
Circular Connectors Market
Connectors
Hazardous Location Connectors Market
Connectors
Smart Crimper Market
Connectors
Automotive Data Connectors Market
Connectors
India Connector Market