
 Underwater Mate Connectors Market | 2026-2036
Underwater Mate Connectors Market Size, Share, and Industry Trends Forecast 2026-2036
Underwater Mate Connectors Market Insights
REACH compliance is shifting the cost-of-entry calculus for underwater mate connectors sold into European offshore projects, forcing manufacturers to reformulate elastomer seals and surface coatings. TE Connectivity leverages its vertical integration across cable and connector assemblies to sustain pricing power in harsh-environment specifications. Amphenol Corporation anchors its position through military-aerospace crossover technologies, while Fischer Connectors SA specializes in miniature high-density configurations for underwater robotics.
Underwater mate connectors are pressure-rated electromechanical interfaces engineered to maintain signal and power integrity at depths exceeding 6,000 meters, typically constructed from titanium housings, glass-reinforced epoxy insulators, and fluorocarbon seals for seawater immersion. These devices serve the primary commercial purpose of linking subsea equipment—wellheads, sensors, vehicles, and communication nodes—to surface controls without breach of hydraulic or electrical continuity. Connector assembly products dominate current revenue flows due to their integration complexity and replacement frequency in permanent subsea installations. Optical fiber technology represents the fastest-expanding segment as bandwidth requirements for real-time seabed data transmission intensify across marine exploration and environmental monitoring applications.
ISO 13628-6 governs subsea production system interfaces and shapes procurement specifications for oil and gas extraction end users, while DNV-ST-F101 and API 17D establish complementary pressure-containment and materials standards that determine product qualification pathways. The US Coast Guard and Bureau of Safety and Environmental Enforcement enforce operational safety mandates that ripple through connector specification sheets for Gulf of Mexico deployments. Stakeholders must monitor how hybrid optical-electrical technology roadmaps from Teledyne Marine and Baker Hughes reshape R&D allocation and whether classification society rule harmonization accelerates or fragments certification requirements across major offshore basins.
Market Dynamics
Subsea electrification and digitalization are compressing replacement cycles for legacy hydraulic connectors while elevating qualification barriers for new entrants. Operators now specify hybrid optical-electrical interfaces for permanent seabed installations, forcing incumbent suppliers to recalibrate R&D roadmaps and certification timelines.
Growth Catalysts
- Deepwater pre-salt development:Brazil's prolific subsalt formations require pressure-rated connectors rated beyond 15,000 psi, sustaining demand for titanium-housed assemblies in ultra-deep deployments.
- ISO 13628-6 harmonization:Standardized interface specifications reduce engineering validation costs for subsea production systems, accelerating procurement decisions among integrated oil companies.
- Offshore wind inter-array cabling:Floating wind platforms in the North Sea and Celtic Sea deploy wet-mate connectors for dynamic power transmission, opening adjacent demand beyond oil and gas.
Market Restraints
- Titanium feedstock concentration:Sponge supply from Russian and Ukrainian sources faces sanctions-related disruption, elevating raw material cost volatility for housing manufacturers.
- REACH compliance burden:ECHA restrictions on fluorocarbon seal compounds force reformulation of elastomer specifications, extending product qualification timelines by 18-24 months for European projects.
- Hydraulic-to-electric substitution:All-electric subsea actuation systems eliminate traditional hydraulic flying leads, compressing addressable market for legacy wet-mate hydraulic connector families.
Strategic Opportunities
- Marine mineral extraction:Polymetallic nodule mining ventures in the Clarion-Clipperton Zone require ultra-reliable connectors for autonomous seabed vehicles operating at 4,500-6,000 meter depths.
- Carbon capture and storage monitoring:Subsea CO2 injection sites demand permanent sensor networks with 25-year design life, creating pull for hermetically sealed optical feedthrough assemblies.
- EU Green Deal offshore infrastructure:European hydrogen pipeline interconnectors and offshore electrolysis platforms will specify mateable electrical interfaces for modular expansion.
Industry Challenges
- DNV-ST-F101 certification timelines:Pressure-containment validation for novel connector geometries requires 12-18 months of subsea testing, delaying revenue recognition for product launches.
- Cross-disciplinary engineering scarcity:Combined expertise in marine corrosion science, high-voltage insulation, and subsea hydraulics concentrates in Stavanger, Aberdeen, and Houston, constraining workforce scaling.
- Legacy system integration:Brownfield tiebacks must interface with 1990s-vintage subsea distribution units using obsolete pin configurations, complicating retrofit engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Underwater Mate Connectors Market |
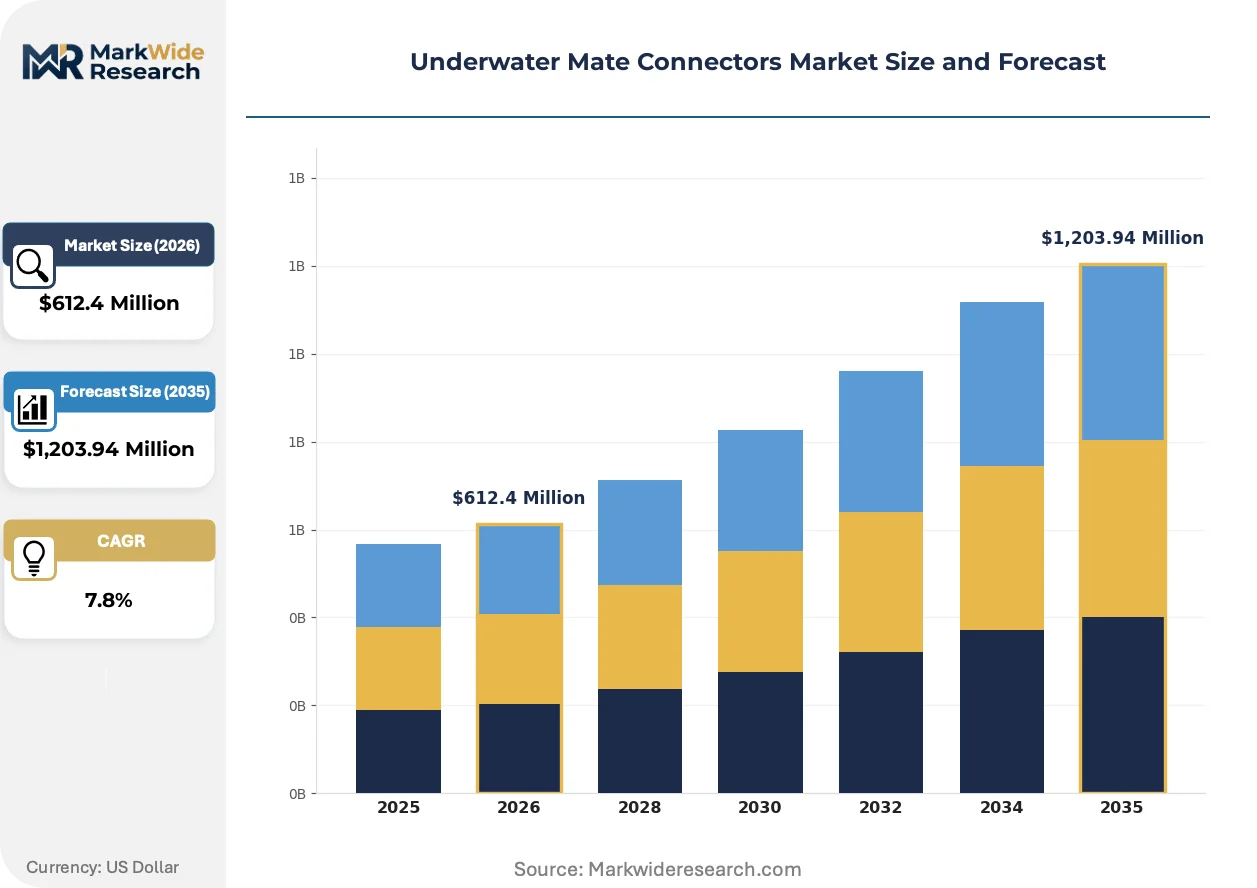
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,203.94 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Connector Assembly, Waterproof Coupling, Subsea Interface, Terminator Plug Application: Marine Exploration, Oil & Gas Extraction, Underwater Robotics, Environmental Monitoring Technology: Optical Fiber, Electrical Conductivity, Hybrid Solution, Pressure Resistant End User: Aerospace, Military, Research Institutions, Commercial Shipping |
| Companies Covered | Amphenol Corporation, TE Connectivity, Eaton Corporation, Teledyne Marine, Fischer Connectors SA, Baker Hughes, Hydro Group, BIRNS Aquamate LLC, Molex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Underwater Mate Connectors Market Trends and Innovations
Connector architectures are pivoting from discrete electrical or hydraulic functions toward convergent optical-electrical-mechanical platforms. This transformation is compressing supplier qualification cycles while fragmenting procurement specifications across end-use verticals.
Optical fiber wet-mate technology is expanding into permanent seabed installations. Single-mode fiber connectors with hermetic glass-to-metal seals now transmit real-time DTS and DAS data from subsea wells. Integrated operators in Norway's Johan Sverdrup field deploy these assemblies for reservoir surveillance. The technology is expanding into environmental monitoring arrays where bandwidth requirements exceed copper cable limitations.
REACH substance restrictions are reformulating seal compound specifications across European offshore projects. ECHA candidate list updates target perfluorinated elastomers used in high-pressure static seals. Manufacturers now qualify hydrogenated nitrile and thermoplastic polyurethane alternatives for North Sea deployments. German and Norwegian classification societies are developing parallel certification protocols for these replacement materials.
Buyer consolidation among integrated oil companies is compressing supplier negotiation leverage. ExxonMobil, Shell, and TotalEnergies now mandate outcome-based service contracts covering connector installation, retrieval, and replacement over field life. Engineering-procurement-construction firms absorb inventory risk through vendor-managed stock agreements. This restructuring is most visible in Gulf of Mexico ultra-deepwater projects where operator procurement teams have reduced qualified supplier lists from twelve to four vendors.
Underwater Mate Connectors Market Segmentation
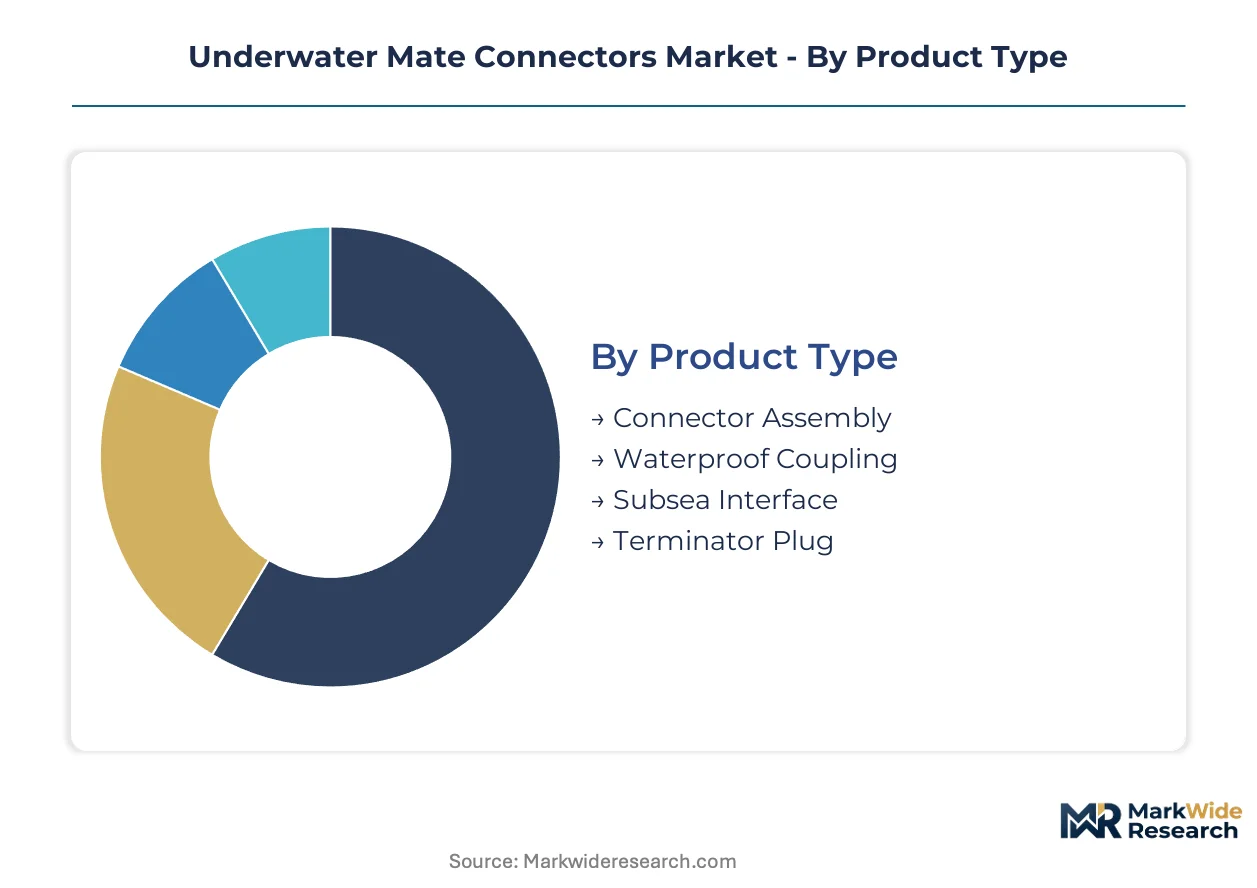
Underwater mate connectors serve divergent operational environments—from permanent subsea wellheads to temporary robotic deployments. Segmentation reveals how qualification requirements, replacement frequency, and technology roadmaps fragment procurement patterns across end-use verticals.
Product Type:
Upgrade cycles vary sharply by assembly complexity, with integrated systems demanding complete replacement while discrete components allow field-level refurbishment.
- Connector Assembly:Integrated electromechanical units combining titanium housings, glass-epoxy insulators, and fluorocarbon seals into pressure-rated interfaces. Brazil's pre-salt operators specify these for 25-year design life in 15,000 psi environments, driving specification toward API 17D certification tiers.
- Waterproof Coupling:Modular mating interfaces enabling rapid connection of flying leads and jumper assemblies without dry-docking. Norwegian North Sea wind farm developers procure these for floating platform inter-array cabling where dynamic motion stresses connection integrity.
- Subsea Interface:Permanent installation nodes linking distribution units to wellheads and manifolds.
- Terminator Plug:Protective sealing caps for unused connector positions during installation phases.
Connector Assembly sits at the top of the volume ranking, with Waterproof Coupling climbing the fastest.
Application:
End-use concentration determines margin structure, with oil and gas procurement absorbing premium pricing for qualification depth while adjacent verticals compete on delivery speed.
- Oil & Gas Extraction:Permanent subsea production systems requiring ISO 13628-6 compliant interfaces for wellhead control, chemical injection, and hydraulic actuation. Gulf of Mexico ultra-deepwater projects specify these for tieback distances exceeding 50 kilometers from host platforms.
- Marine Exploration:Temporary deployment configurations for seismic survey equipment and seabed sampling systems. Academic research vessels operating in the Clarion-Clipperton Zone demand rapid-mate compatibility with autonomous underwater vehicle docking stations.
- Underwater Robotics:Remotely operated and autonomous vehicles requiring miniature high-density pin configurations.
- Environmental Monitoring:Distributed sensor networks for oceanographic data collection and pollution detection.
Oil & Gas Extraction commands the dominant revenue share, though Marine Exploration is expanding most quickly as polymetallic nodule ventures advance.
Technology:
Material science investments separate incumbent suppliers from new entrants, with hermetic sealing capabilities and fiber optic termination expertise concentrating among established players.
- Optical Fiber:Single-mode and multimode wet-mate connectors with hermetic glass-to-metal seals transmitting real-time distributed temperature and acoustic sensing data. Johan Sverdrup field operators deploy these for reservoir surveillance exceeding copper bandwidth limitations.
- Hybrid Solution:Convergent optical-electrical-mechanical platforms consolidating power, signal, and data transmission through single mating interfaces. Offshore wind developers in the Celtic Sea specify these to reduce connection count on floating substation platforms.
- Electrical Conductivity:Copper-conductor assemblies for power transmission and analog control signaling.
- Pressure Resistant:Specialized mechanical-only sealing solutions for extreme depth ratings.
Electrical Conductivity maintains installed base dominance, yet Hybrid Solution is gaining share fastest as subsea digitalization compresses connector counts.
End User:
Procurement authority concentration shapes supplier access, with defense and aerospace channels requiring security clearance while commercial markets prioritize total cost of ownership.
- Military:Cross-domain specifications leveraging MIL-STD qualification pathways for seabed surveillance and undersea warfare systems. Classification society overlap with commercial standards accelerates technology transfer from defense to oil and gas applications.
- Research Institutions:Academic and government laboratory procurement emphasizing modularity and rapid reconfiguration. Scripps Institution of Oceanography and IFREMER specify open-architecture connector standards to avoid single-source dependency.
- Aerospace:Satellite and launch system applications requiring pressure-rated heritage for underwater recovery scenarios.
- Commercial Shipping:Hull-mounted sensors and dynamic positioning system interfaces for merchant vessels.
Military procurement leads qualification stringency, with Research Institutions showing the steepest expansion trajectory as marine science funding diversifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Subsea engineering talent clusters in Stavanger, Aberdeen, and Houston anchor procurement authority for underwater mate connectors. These workforce concentrations determine qualification standards and supplier access across major offshore basins. Regional deployment patterns reflect divergent regulatory regimes and feedstock availability.
Brazil
Deepwater pre-salt development drives specification toward 15,000 psi titanium-housed assemblies for 25-year design life. ANP regulatory frameworks mandate API 17D certification for subsea production equipment. Rio de Janeiro hosts Petrobras procurement headquarters and the dominant supplier qualification ecosystem for ultra-deep deployments.
Norway
North Sea electrification and Johan Sverdrup field digitalization accelerate hybrid optical-electrical connector adoption. DNV-ST-F101 and ISO 13628-6 shape pressure-containment validation pathways. Stavanger concentrates subsea engineering expertise and classification society technical committees setting regional standards.
United States
Gulf of Mexico ultra-deepwater tiebacks exceeding 50 kilometers from host platforms demand high-reliability wet-mate interfaces. The Bureau of Safety and Environmental Enforcement enforces operational safety mandates through connector specification sheets. Houston hosts integrated operator procurement teams that have compressed qualified supplier lists from twelve to four vendors.
United Kingdom
Celtic Sea floating wind platforms deploy wet-mate connectors for dynamic power transmission in inter-array cabling. REACH compliance through ECHA restricts fluorocarbon seal compounds, forcing elastomer reformulation. Aberdeen maintains brownfield retrofit engineering capability for legacy system integration challenges.
Germany
North Sea offshore wind inter-array cabling and emerging hydrogen pipeline interconnectors create demand for modular electrical interfaces. German classification societies develop parallel certification protocols for hydrogenated nitrile seal alternatives. Hamburg and Bremerhaven host marine engineering clusters advancing connector qualification for renewable energy applications.
Underwater Mate Connectors Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered procurement segments. The vendor base organizes around three strategic archetypes: diversified electrical interconnect conglomerates, defense-aerospace crossover specialists, and subsea-focused pure-plays. Incumbent suppliers defend position through backward integration into cable assemblies and captive titanium sourcing. New entrants face 12-18 month DNV-ST-F101 certification timelines that delay revenue recognition.
Among diversified electrical interconnect conglomerates, TE Connectivity and Amphenol Corporation exemplify scale-driven positioning across harsh-environment specifications. Fischer Connectors SA occupies a specialist tier focused on miniature high-density configurations. These three anchors represent divergent competitive vectors: vertical integration breadth, military-aerospace technology transfer, and robotics-focused miniaturization expertise.
| Leading Market Players |
|---|
| Amphenol Corporation |
| TE Connectivity |
| Eaton Corporation |
| Teledyne Marine |
| Fischer Connectors SA |
| Baker Hughes |
| Hydro Group |
| BIRNS Aquamate LLC |
| Molex |
| Others |
Pricing and Supply Chain Analysis
Buyer consolidation among Gulf of Mexico operators compressing qualified supplier lists from twelve to four vendors forces remaining manufacturers to absorb inventory risk through vendor-managed stock agreements while defending margin through captive titanium sourcing and backward integration into cable assemblies.
Pricing Analysis
Bundled outcome-based service contracts covering installation, retrieval, and replacement now dominate unbundled component sales in ultra-deepwater procurement. Price differentiation hinges on API 17D certification tier and after-sales service bundling depth. Cost compression in standard-grade connector assemblies intensifies because EPC firms shoulder inventory carrying costs under long-term field-life agreements. National oil companies in Brazil exhibit lowest price sensitivity due to 25-year design life specifications, while research institutions prioritize modularity over total cost optimization.
Supply Chain Analysis
Direct-to-OEM channels handle integrated operator demand in Houston, Stavanger, and Rio de Janeiro, while specialized distributors serve research and robotics segments. Titanium sponge supply draws from Russian, Ukrainian, and Japanese sources, with glass-reinforced epoxy insulators and fluorocarbon seal compounds anchoring in German and US chemical manufacturing. Single-source vulnerability in pressure-rated glass-to-metal seal technology concentrates among three qualified European suppliers. Distribution runs through engineering-procurement-construction firms that consolidate procurement authority for integrated oil companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as subsea infrastructure replacement cycles compress from electrification mandates while qualification barriers protect incumbent returns.
For Market Incumbents: Cement position through captive titanium sourcing alliances and backward integration into fiber optic cable termination capabilities. Hydraulic-to-electric substitution threatens legacy wet-mate hydraulic families; counter by accelerating hybrid optical-electrical platform certification under DNV-ST-F101 timelines. Prioritize Stavanger and Houston engineering talent retention as workforce scarcity intensifies. For New Entrants and Emerging Players: EU Green Deal offshore infrastructure in Germany and the Celtic Sea opens a window for modular electrical interface specialists lacking oil and gas qualification heritage. Target floating wind inter-array cabling as the most penetrable segment, where 12-18 month certification timelines compress against renewable energy deployment schedules. Pursue qualification partnerships with German classification societies developing hydrogenated nitrile seal protocols as a go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with subsea-focused pure-plays holding DNV-ST-F101 and API 17D certification portfolios. Five-to-ten year viability favors manufacturers with demonstrated 6,000-meter depth ratings and hermetic optical feedthrough production. Signal to watch: classification society rule harmonization accelerating or fragmenting certification requirements across Brazil, Norway, and US Gulf of Mexico basins.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Sourcing | Captive sponge supply from Japanese sources insulates against sanctions-driven volatility in Russian and Ukrainian feedstock. |
| Hermetic Optical Feedthrough Qualification | Glass-to-metal seal expertise unlocks Johan Sverdrup field deployments and carbon capture sensor network opportunities. |
| Vendor-Managed Inventory Agreements | EPC contractors absorbing stock risk align supplier cash conversion with integrated operator procurement consolidation. |
| Hybrid Platform Certification Investment | DNV-ST-F101 validation for convergent optical-electrical-mechanical interfaces captures offshore wind and pre-salt substitution demand. |
| Workforce Cluster Expansion | Subsea engineering presence in Aberdeen addresses brownfield retrofit capability gaps and REACH compliance reformulation expertise. |
Research Methodology
Bottom-up oil and gas extraction modeling reconciled against top-down subsea equipment manufacturing tracking forms the analytical core. Primary interviews with subsea project engineers, procurement leads at integrated operators, classification society technical committees, and EPC contract managers combined with secondary validation from API 17D certification registries, DNV-ST-F101 compliance databases, ANP regulatory filings, and Bureau of Safety and Environmental Enforcement incident reports. Triangulation across these sources anchors volume and value estimates.
Input-output matrices map connector assembly, waterproof coupling, and subsea interface demand against subsea tree installations, floating wind deployments, and autonomous vehicle fleet expansions across the projection horizon. Segmentation dimensions include product type, application vertical, technology platform, and end-user procurement authority. CAGRs derive from deployment schedule analysis and replacement cycle compression factors specific to electrification and digitalization roadmaps.
Revisions become necessary when titanium feedstock sanctions expand, classification societies fragment certification protocols, or all-electric subsea actuation adoption accelerates beyond modeled substitution curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
Heavy-Duty Connector Market
Connectors
Hybrid Fiber Optic Connectors Market
Connectors
Global Cables and Connector Market
Connectors
Pin Retainer Market
Connectors
Global Multi Coaxial Connectors Market
Connectors
Wire-To-Board Connector Market
Connectors
Asia-Pacific Connector Market
Connectors
AS-Interface Market
Connectors
Space Grade Connectors Market
Connectors
Line Clamp Market
Connectors
Connector and Terminal Systems for Harsh Environment Wiring Market
Connectors
Middle East Connector Market
Connectors
Australia Connector Market
Connectors
Magnetic Connector Market
Connectors
Connector Adapter Kits Market
Connectors
Automotive Data Connectors Market