
 Global Fiber Optic Connectors Market | 2026-2036
Global Fiber Optic Connectors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fiber Optic Connectors Market Intelligence
A procurement transition from single-source contracts to multi-vendor strategies for high-density connectors is shifting supply chain dependencies for network equipment manufacturers. Corning Incorporated leverages its deep expertise in glass and ceramic materials to lead in precision ferrule manufacturing. Amphenol Corporation competes effectively by offering a broad portfolio of customized and ruggedized interconnects for military and industrial applications.
A fiber optic connector is a mechanical device that aligns and joins optical fibers to enable light signal transmission between two points. These components are engineered for low insertion loss, often below 0.25 dB, and high return loss to ensure signal integrity. Within product types, LC connectors maintain a large installed base, but MTP connectors represent the fastest-growing segment due to data center deployments. Single-mode technology dominates long-haul telecommunications applications, while multimode fiber is prevalent in shorter-reach enterprise networks.
Product performance and market access are governed by multiple standards, including Telcordia specifications in the United States and IEC standards referenced for CE marking in Europe. China's MIIT enforces specific GB standards for domestic telecommunication infrastructure projects. Vendor selection will increasingly hinge on the ability to navigate these fragmented compliance requirements while managing component sourcing for new high-speed interfaces.
Market Dynamics
Escalating bandwidth demand from hyperscale data centers and 5G networks is the market's central force. This pressure compels rapid evolution in connector technology toward higher densities and improved signal integrity to support faster data rates.
Growth Catalysts
- Hyperscale Data Center Expansion:Data center build-outs for cloud and AI demand massive volumes of high-density connectors to support 400G and 800G Ethernet.
- National Broadband Initiatives:Government programs in China, overseen by the MIIT, accelerate 5G and fiber-to-the-home rollouts, driving connector procurement.
- Enterprise Network Upgrades:Corporate adoption of cloud services necessitates upgrades to internal campus networks using higher-capacity multimode fiber.
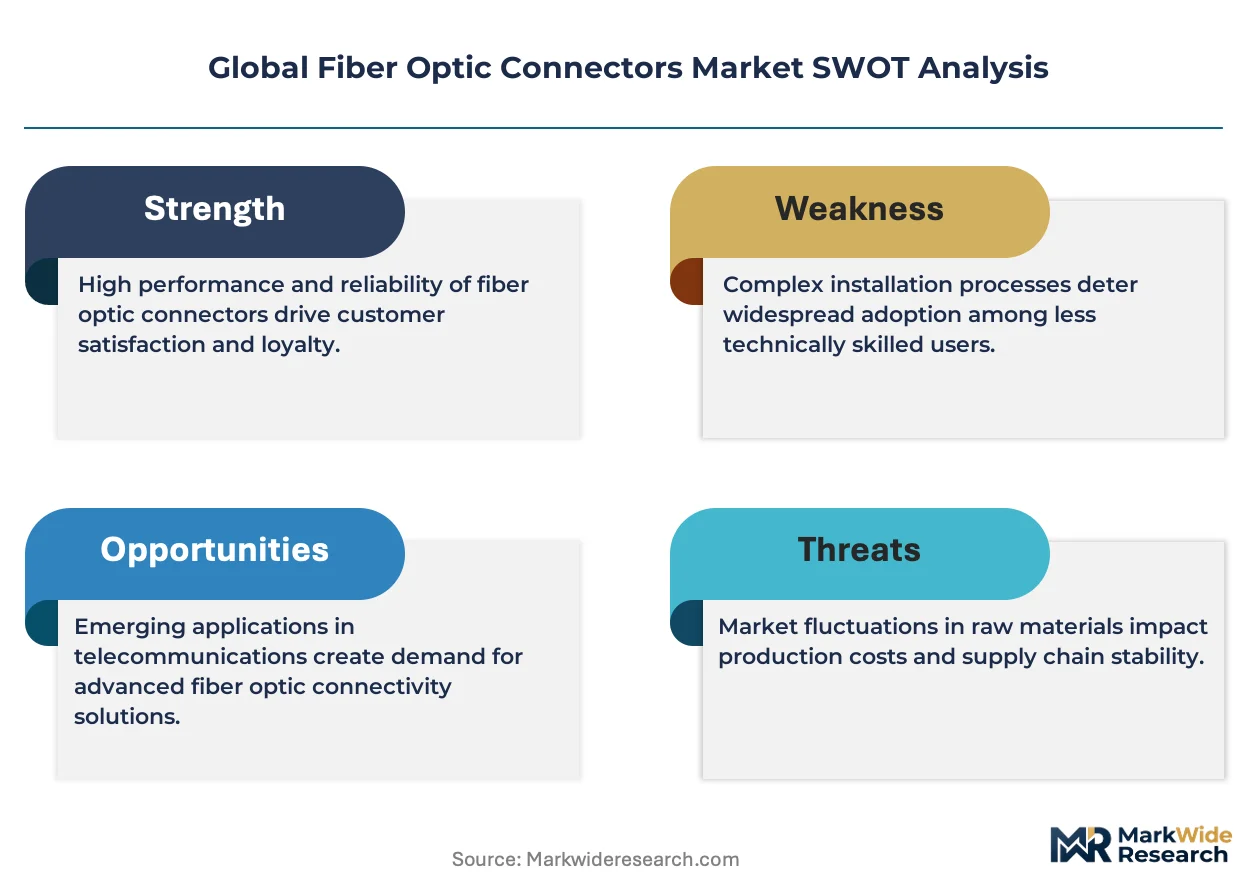
Market Restraints
- Precision Manufacturing Costs:The sub-micron tolerances for ceramic ferrules demand significant capital investment in specialized grinding and polishing equipment.
- Physical Signal Limits:Higher fiber counts in one connector increase crosstalk and insertion loss, a fundamental physics challenge for next-generation interfaces.
- Raw Material Bottlenecks:The supply of high-purity silica glass and specialty polymers is concentrated, creating price volatility and sourcing risks.
Strategic Opportunities
- Co-Packaged Optics (CPO):Integrating optical I/O onto silicon packages creates an opportunity for new connector form factors and blind-mating solutions for servers.
- Industrial and Harsh Environments:Industrial automation and military network programs in Germany and the US open niches for ruggedized, IP-rated connectors.
- Emerging Market Broadband:Infrastructure initiatives in India and Brazil present greenfield opportunities for cost-effective connectors in new fiber-to-the-premise networks.
Industry Challenges
- Fragmented Compliance Landscape:Vendors face significant overhead testing and certifying products to meet disparate standards like Telcordia, IEC, and China's GB specifications.
- Interoperability and Testing:Ensuring consistent performance between different manufacturers' high-density MTP/MPO connectors remains a persistent challenge for installers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fiber Optic Connectors Market |
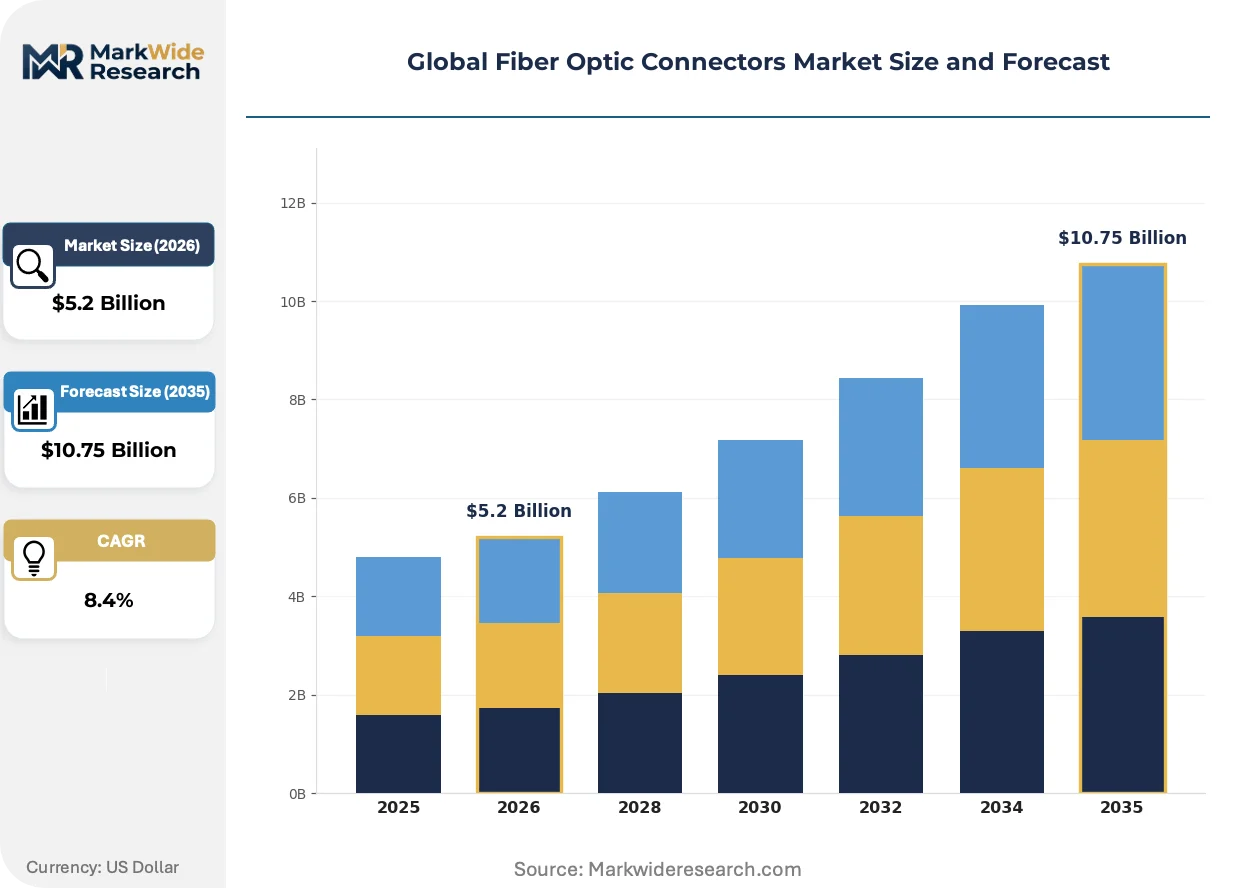
| Market Size in 2026 | $5.2 Billion |
| Market Size in 2035 | $10.75 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LC, SC, ST, MTP, FC, E2000 Technology: Multimode, Single-mode, Plastic Optical Fiber, Ribbon Fiber, Polarization Maintaining, Graded-Index Application: Telecommunications, Data Centers, Military Communications, Broadcasting, Aerospace, Test & Measurement End User: Network Equipment Manufacturers, System Integrators, Internet Service Providers, Cloud Services, Defense Agencies, Research Laboratories |
| Companies Covered | Molex LLC, Furukawa Electric Co. Ltd., Corning Incorporated, Diamond SA, Sumitomo Electric Industries, Amphenol Corporation, Hirose Electric Co. Ltd., Huber+Suhner, TE Connectivity Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fiber Optic Connectors Market Strategic Shifts & Innovations
The market's innovation focus is pivoting from purely mechanical precision toward integrated optical solutions that address power consumption and density at the system level. This evolution reflects the immense data processing demands of next-generation computing infrastructure.
Expanded beam connector technology uses lenses to collimate the light signal, making connections less sensitive to dust and physical misalignment. It is adopted primarily in military, broadcast, and industrial applications where reliability is paramount. This approach is modularizing the physical interface, separating the rugged external connection from the internal optical alignment.
European Union regulations, specifically the RoHS directive, influence material science in connector manufacturing. The directive restricts hazardous substances, forcing vendors to verify compliance for all plastic housings, epoxies, and metal components. This affects development of new flame-retardant compounds for connectors destined for European projects.
Buying patterns are evolving from component-level purchases to the acquisition of pre-terminated, factory-tested trunk assemblies. This shift reduces on-site labor, minimizes installation errors, and guarantees performance. The trend is most dominant within hyperscale data centers in the United States and China, where deployment velocity is key.
Global Fiber Optic Connectors Market Segmentation
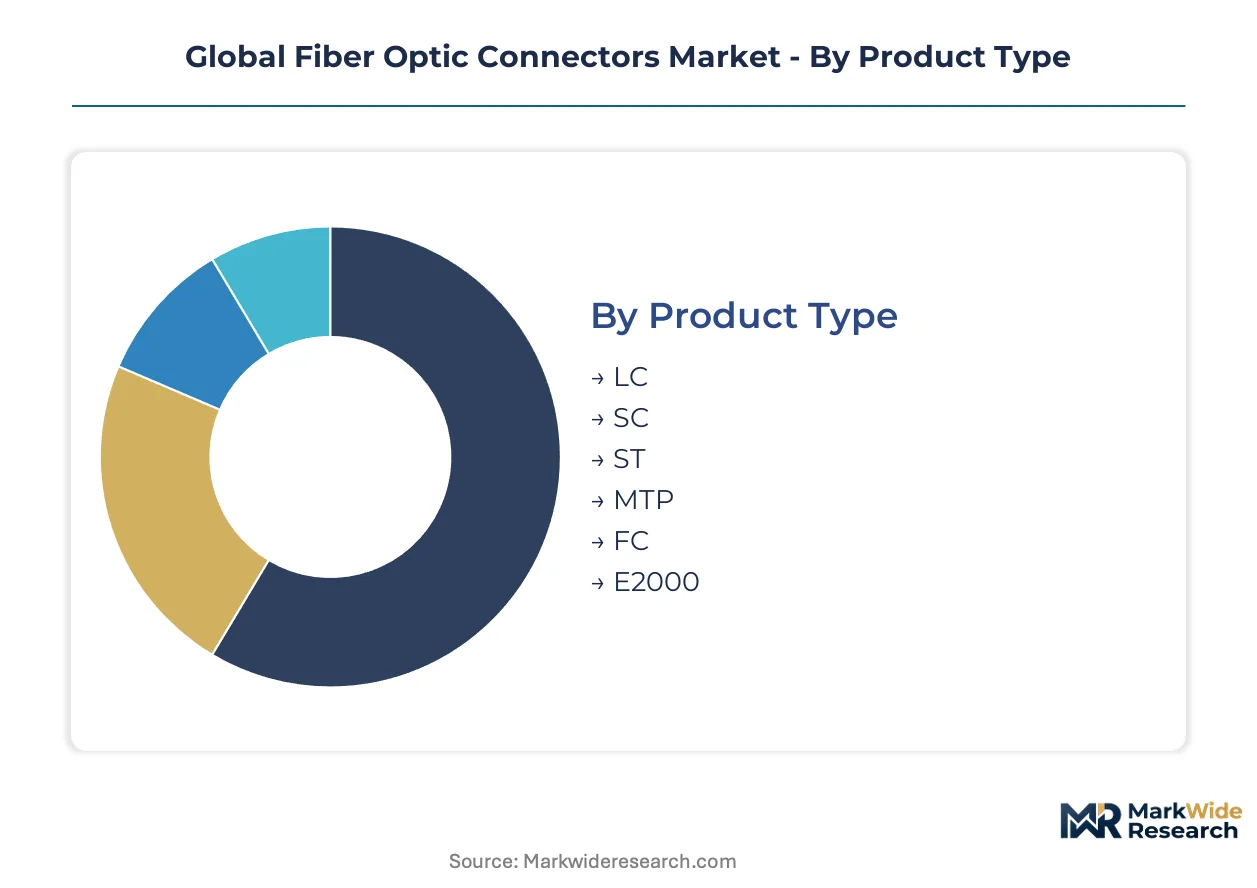
Market segmentation provides a critical framework for understanding the diverse performance requirements and application-specific demands within the fiber optic connectors industry. This breakdown helps stakeholders identify key growth pockets and navigate the varied compliance landscapes across different product types and end-use environments.
Product Type:
Different connector types must adhere to specific Telcordia or IEC standards to ensure interoperability and performance in diverse network environments, ranging from data centers to telecommunications infrastructure.
- MTP:This high-density, multi-fiber connector facilitates parallel optics transmission, crucial for supporting high-speed data rates like 400G and 800G Ethernet. Demand concentrates heavily in hyperscale data centers in the United States and China for backbone interconnects.
- LC:A small form-factor connector featuring a 1.25mm ferrule, it offers reliable performance and a compact design. Its extensive installed base continues to serve a wide array of enterprise networks and telecommunications access points.
- SC:A push-pull connector with a 2.5mm ferrule, widely utilized in telecommunications patch panels and passive optical networks due to its ease of use.
- ST:Characterized by its bayonet-style coupling mechanism, this connector is common in older campus networks and multimode fiber installations.
- FC:A screw-on connector providing robust, vibration-resistant connections, often found in industrial applications and test equipment.
- E2000:Features an integrated spring-loaded shutter that protects the ferrule from dust and laser exposure, making it suitable for high-performance and sensitive applications.
Leading the category by volume: LC. Growing fastest: MTP.
Technology:
Different fiber optic technologies are optimized for distinct transmission distances and data rate requirements across various network applications, influencing connector design and material selection.
- Single-mode:This technology employs a small core diameter (8-10 microns) that allows a single light path, enabling long-distance transmission with minimal signal loss. It is critical for long-haul telecommunications, submarine cables, and high-speed core networks.
- Multimode:Utilizing a larger core diameter (50 or 62.5 microns) for multiple light paths, multimode fiber is suitable for shorter distances within enterprise networks and data centers. It supports cost-effective, high-bandwidth links over limited ranges.
- Plastic Optical Fiber:A large core diameter plastic fiber used for very short-distance, low-cost data transmission in consumer electronics and automotive applications.
- Ribbon Fiber:Comprises multiple fibers arranged in a flat ribbon, enabling high-density cable assemblies and efficient mass termination for data center backbone connections.
- Polarization Maintaining:Designed to preserve the polarization state of light, this technology is crucial for sensitive optical sensors, gyroscopes, and coherent communication systems.
- Graded-Index:A type of multimode fiber with a refractive index profile that gradually decreases from the center, reducing modal dispersion over moderate distances.
Single-mode technology dominates market share in long-distance applications, while multimode is experiencing significant expansion in enterprise upgrades.
Application:
The volume requirements for fiber optic connectors vary significantly across applications, driven by network scale, environmental conditions, and specific performance demands.
- Data Centers:These facilities demand massive volumes of high-density, low-loss connectors to support 400G and 800G Ethernet interconnects. Hyperscale build-outs for cloud and AI services in the US and China fuel this demand.
- Telecommunications:This sector requires robust connectors for national broadband initiatives, including 5G network rollouts and fiber-to-the-home deployments. Government programs in China, overseen by the MIIT, drive substantial connector procurement.
- Military Communications:Requires ruggedized, IP-rated connectors for secure and reliable data transmission in harsh operational environments, particularly for defense agencies in the US and Germany.
- Broadcasting:Employs expanded beam connectors for high-definition video transmission, ensuring reliability in mobile production and studio setups.
- Aerospace:Demands lightweight, high-performance connectors capable of withstanding extreme temperatures and vibrations in aircraft and spacecraft systems.
- Test & Measurement:Utilizes high-precision connectors for accurate optical power and loss measurements in laboratory and field settings, ensuring system integrity.
Data Centers exhibit the highest demand for advanced connectors, with Telecommunications also showing rapid growth due to infrastructure investments.
End User:
End-user procurement patterns for fiber optic connectors range from direct component purchases to the acquisition of pre-terminated, factory-tested assemblies, influencing supply chain strategies and vendor selection.
- Network Equipment Manufacturers:These entities procure high-density connectors for integration into their networking hardware, increasingly shifting from single-source to multi-vendor strategies for supply chain resilience. They require components compliant with global standards like Telcordia and IEC.
- Cloud Services:Hyperscale cloud providers drive significant connector volume, opting for pre-terminated trunk assemblies to accelerate deployment velocity in their massive data centers. They prioritize performance for 400G and 800G Ethernet deployments.
- System Integrators:Purchase connectors for custom network installations, requiring flexibility and interoperability across different client environments in commercial and industrial sectors.
- Internet Service Providers:Acquire connectors for last-mile fiber-to-the-home deployments and backbone network expansions, particularly in regions with national broadband initiatives.
- Defense Agencies:Source ruggedized and secure connectors for military-grade communication systems, often with specialized compliance needs and harsh environment specifications.
- Research Laboratories:Demand high-precision, low-loss connectors for experimental setups and advanced optical component testing in academic and industrial research.
Cloud Services and Network Equipment Manufacturers are the largest volume consumers, significantly influencing procurement shifts towards pre-terminated solutions and multi-vendor sourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silica glass and specialty polymers, critical raw materials for fiber optic connectors, often originate from concentrated supply chains globally. This underpins the manufacturing capabilities and deployment velocities in key regions, influencing both cost structures and product availability. Demand patterns for fiber optic connectors vary significantly by geography, driven by distinct infrastructure priorities and technological adoption rates.
China
Massive 5G network rollouts and extensive fiber-to-the-home projects generate substantial connector demand. The MIIT enforces specific GB standards, influencing product design and market access for domestic telecommunication infrastructure. The Yangtze River Delta region, including cities like Shanghai and Nanjing, serves as a hub for both manufacturing and deployment of advanced optical components.
United States
Hyperscale data center build-outs for cloud computing and artificial intelligence drive significant volumes of high-density connectors. Telcordia specifications govern product performance and reliability for telecommunications and data center applications. Silicon Valley and Northern Virginia concentrate major data center campuses, leading to high consumption of 400G and 800G Ethernet interconnects.
Germany
Industrial automation and military network programs create niche demand for ruggedized and IP-rated connectors. European Union regulations like CE marking and RoHS influence material selection and compliance requirements for products sold across the continent. Bavaria and North Rhine-Westphalia house significant industrial manufacturing and defense technology clusters, driving specialized connector procurement.
India
National broadband initiatives and fiber-to-the-premise networks present greenfield opportunities for cost-effective fiber optic connectors. Government programs aim to expand digital connectivity, stimulating infrastructure development. Major metropolitan areas like Bangalore and Mumbai are experiencing rapid growth in data center capacity and telecommunications upgrades.
Japan
High-precision manufacturing and advanced optical sensing applications require specialized connectors with stringent performance characteristics. JIS standards guide product quality and interoperability within the domestic market for telecommunications and industrial uses. The Kanto region, including Tokyo, remains a center for research, development, and deployment of cutting-edge optical technologies.
Global Fiber Optic Connectors Market Key Industry Players
Global majors compete with regional champions across technology leadership and market access within the fiber optic connectors industry. The market demonstrates a tiered structure, encompassing large, diversified corporations alongside specialized solution providers. Strategic archetypes include integrated material science experts focusing on core components and broad-portfolio providers offering end-to-end solutions. Companies pursue portfolio diversification and strategic partnerships to expand their market footprint and address evolving customer needs.
Among integrated material science experts, Corning Incorporated represents deep expertise in glass and ceramic materials, particularly for precision ferrule manufacturing. Amphenol Corporation exemplifies broad portfolio solutions, offering customized and ruggedized interconnects for diverse applications, including military and industrial sectors. Japan-based Sumitomo Electric Industries occupies a position among diversified industrial conglomerates, providing a wide range of optical fiber and connector products.
| Leading Market Players |
|---|
| Molex LLC |
| Furukawa Electric Co. Ltd. |
| Corning Incorporated |
| Diamond SA |
| Sumitomo Electric Industries |
| Amphenol Corporation |
| Hirose Electric Co. Ltd. |
| Huber+Suhner |
| TE Connectivity Ltd. |
| Others |
Cost & Logistics Intelligence
Vertical integration into precision ferrule manufacturing anchors supply positions for key players like Corning Incorporated. This strategic control over core components directly influences their pricing power for high-performance fiber optic connectors.
Pricing Analysis
Warranty and service-level agreement bundling increasingly define value propositions for fiber optic connectors, moving beyond simple unit pricing. The dominant pricing structure involves contract-based long-term offtake agreements, especially for hyperscale data centers, with price differentiation stemming from precision manufacturing tolerances and adherence to standards like Telcordia or IEC. Pricing softness reflects intense competition for high-volume MTP connectors, particularly from Chinese manufacturers. Hyperscale cloud providers exhibit high price sensitivity due to massive procurement volumes, while military applications prioritize performance over cost.
Supply Chain Analysis
Dual-sourcing requirements from network equipment manufacturers are reshaping the fiber optic connector supply chain. Raw material dependencies center on high-purity silica glass and specialty polymers, with significant processing capabilities concentrated in China, Japan, and the United States. Single-source vulnerability for key components presents a structural risk, especially for precision ferrules. Distribution runs through a mix of direct sales to hyperscalers and equipment manufacturers, alongside a network of specialized distributors for smaller system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fiber optic connectors market operates under supply constraints, particularly in precision manufacturing for ceramic ferrules. This specialized capacity bottleneck props up pricing for high-performance, low-loss interconnects.
For Market Incumbents: Deploy advanced material science R&D to counter the physical signal limits of higher fiber counts, extending performance envelopes. Pursue strategic acquisitions of specialized component manufacturers to consolidate precision ferrule supply and mitigate raw material bottlenecks. This proactive stance addresses the threat of emerging co-packaged optics solutions displacing traditional connector form factors.
For New Entrants and Emerging Players: Price-point gaps between premium, high-performance connectors and cost-effective solutions offer entry opportunities in emerging markets. Target national broadband initiatives in India and Brazil, which prioritize cost-effective fiber-to-the-premise networks. A direct-to-installer sales model, emphasizing ease of installation and compliance with local GB standards, provides a strong go-to-market angle.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized component manufacturers with deep material science expertise or providers of pre-terminated trunk assemblies. The long-term viability of this market, over the next 5-10 years, remains strong due to persistent data growth and infrastructure upgrades. A key signal to watch is the adoption rate of 800G Ethernet in hyperscale data centers, indicating readiness for next-generation interconnects.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in 800G Ethernet-ready MTP connector R&D | Future-proofs product portfolios for hyperscale data center demand in the United States and China. |
| Expand precision ferrule manufacturing capacity | Secures critical component supply and reduces raw material bottleneck risks for global production. |
| Develop ruggedized IP-rated connectors | Captures niche opportunities in industrial automation and military applications in Germany and the US. |
| Form partnerships for co-packaged optics solutions | Positions companies for the next generation of optical interconnects in high-density computing environments. |
| Localize production in emerging markets | Facilitates market access and cost-effective supply for national broadband initiatives in India and Brazil. |
Research Approach
Independent corroboration across Telcordia specifications, IEC standards, and China's GB standards underwrites qualitative findings. Primary interviews engaged network equipment manufacturers, cloud service architects, and telecom infrastructure planners. Secondary validation utilized hyperscaler capex disclosures, national broadband initiative reports, and optical component industry publications, employing both bottom-up and top-down triangulation.
Comparable historical reference periods anchored the forecast window, extending projections across the analysis window. The quantitative model segmented the market by product type, technology, application, end-user, and regional infrastructure investment. Compound annual growth rates were derived from a multi-variant regression analysis, accounting for data center build-out schedules and 5G network deployment roadmaps.
Underlying measurement precision varies by segment; hyperscale data center deployments carry tighter precision than emerging market broadband initiatives. Forecasts reflect assumptions regarding technological advancements and global economic conditions. Deviation in government infrastructure spending or raw material supply chain disruptions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
Global Board to Board (BTB) Connectors Market
Connectors
USB Type-C Market
Connectors
SATA Connector Market
Connectors
Canada Connector Market
Connectors
Cable Connectors and Adapters Market
Connectors
Global Multi Coaxial Connectors Market
Connectors
Liquid Cooling Connector Market
Connectors
Heavy-Duty Connector Market
Connectors
Latin America Connector Market
Connectors
Connector for PV System Market
Connectors
Japan Connector Market
Connectors
Wire-To-Board Connector Market
Connectors
India Connector Market
Connectors
High-Reliability Connectors Market
Connectors
Press Fit Connector Market
Connectors
LCP Connectors Market