
 Circular Connectors Market | 2026-2036
Circular Connectors Market Size, Share, and Industry Trends Forecast 2026-2036
Circular Connectors Market Intelligence
Demand from system integrators for modular and field-configurable components is reorganizing procurement patterns away from traditional OEM purchasing cycles. TE Connectivity leverages its extensive portfolio and global manufacturing footprint to serve high-volume applications. In contrast, Lemo specializes in high-precision push-pull connectors for demanding medical and instrumentation sectors. Binder positions itself with a strong focus on M-series connectors tailored for European industrial automation clients.
Circular connectors are multi-pin electrical interfaces housed within a cylindrical shell, providing robust protection against environmental factors like dust, moisture, and vibration. These components utilize coupling mechanisms such as threaded, bayonet, or push-pull locks to ensure secure connections. Industrial automation applications represent the largest volume segment, while the aerospace and military defense sectors command higher margins due to stringent specifications. Waterproof and PCB mount technologies are seeing increased use in compact, sealed electronic enclosures.
Compliance with the EU's RoHS directive and CE marking requirements dictates material composition and European market access for commercial-grade connectors. In parallel, military-grade components must adhere to stringent MIL-SPEC standards in the United States, defining performance under extreme shock and vibration. Component selection increasingly balances the need for higher data transmission speeds against the imperative for enhanced ruggedization and power delivery.
Market Dynamics
The central tension shaping the market is the simultaneous demand for higher data transmission speeds and increased power delivery within compact, environmentally sealed connector shells. This conflict, driven by the proliferation of IIoT devices and robotics, is forcing a re-evaluation of material science and contact design.
Growth Catalysts
- Industrial Automation:Demand for standardized M-series connectors is accelerating, driven by robotics and automated production lines in advanced manufacturing centers like Germany and China that require reliable, vibration-resistant interconnections.
- EU Directives:The EU's RoHS directive mandates the use of lead-free solders and halogen-free plastics, creating a significant demand pull for compliant components and materials across the European market.
- Device Miniaturization:The need for smaller, lighter electronic systems in sectors like medical instrumentation and aerospace is driving innovation in high-density, PCB-mount circular connectors that save space and weight.
Market Restraints
- Input Cost Volatility:Fluctuations in the price of key raw materials, particularly gold and beryllium copper used for high-performance electrical contacts, create margin pressure and pricing instability for manufacturers.
- Signal Integrity Limits:As data rates increase, managing signal degradation from crosstalk and impedance mismatch becomes a significant technical barrier in high-density, multi-pin circular connector designs.
- Substitution Threats:In moderately harsh commercial environments, lower-cost, high-bandwidth rectangular connectors, including ruggedized USB Type-C versions, present a viable alternative to traditional circular formats.
Strategic Opportunities
- Hybrid Connectors:Integrating fiber optic and copper contacts in single shells simplifies wiring in complex systems like surgical robots, creating a distinct product opportunity for high-value applications.
- EV Infrastructure:The build-out of electric vehicle charging networks requires new high-amperage, weatherproof circular connectors, opening a major application segment with unique performance requirements.
- Medical Instrumentation:Ultra-miniature push-pull connectors address needs in the portable diagnostics market for devices requiring high mating cycles and compatibility with sterilization processes.
Industry Challenges
- MIL-SPEC Qualification:The extensive testing, documentation, and long lead times required for MIL-SPEC certification create a significant barrier to entry for new suppliers wishing to serve the military and aerospace sectors.
- Legacy System Integration:Ensuring new high-speed connectors are backward-compatible with the vast installed base of industrial equipment using older communication protocols presents a persistent engineering challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Circular Connectors Market |
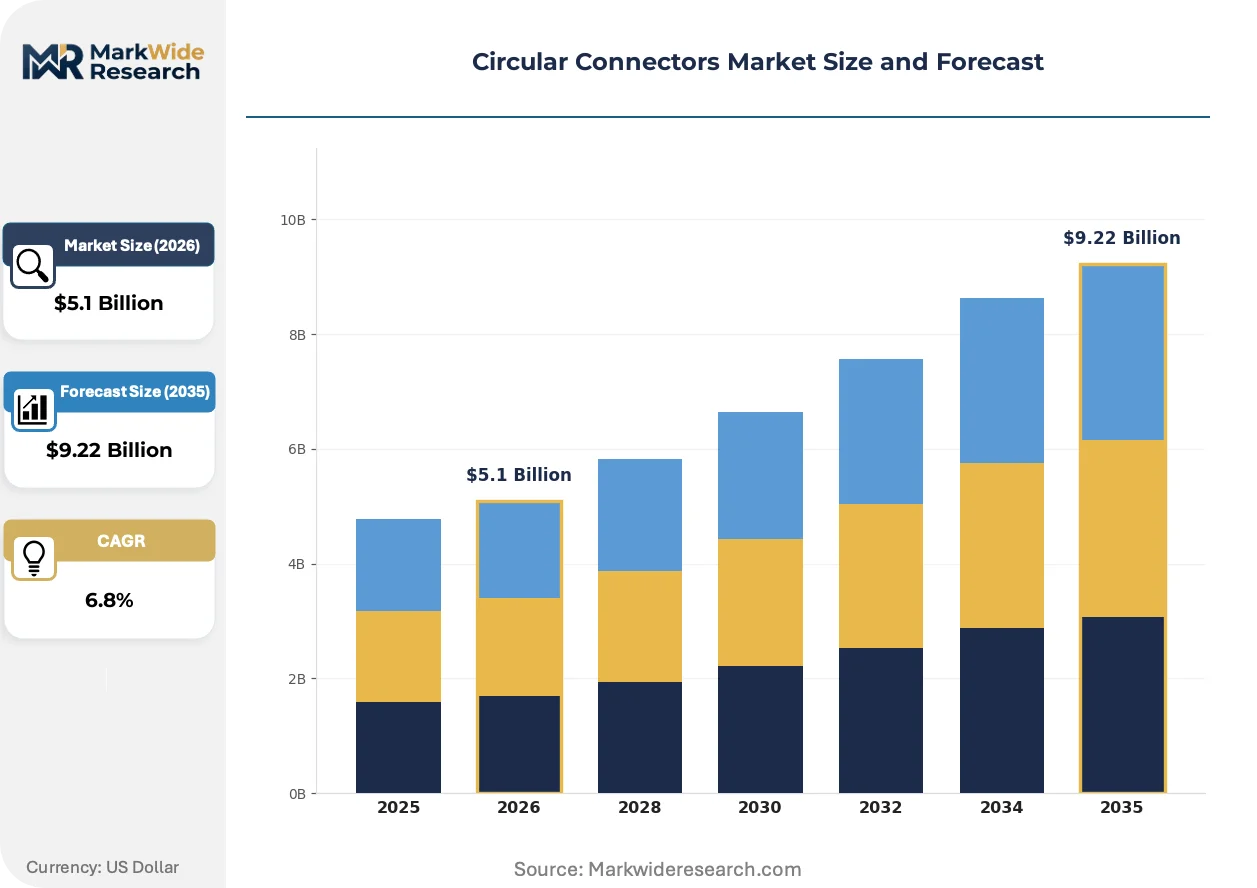
| Market Size in 2026 | $5.1 Billion |
| Market Size in 2035 | $9.22 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pin, Socket, Threaded, Bayonet, Push-Pull Technology: Crimp, Solder, PCB Mount, Wire-to-Wire, Waterproof Application: Aerospace, Military Defense, Telecommunications, Industrial Automation, Marine Systems End User: OEMs, Tier-1 Suppliers, System Integrators, Maintenance Providers, Aftermarket Services |
| Companies Covered | HARTING, Lemo, TE Connectivity, Binder, Phoenix Contact, Amphenol, ITT Cannon, Hirose, Molex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Circular Connectors Market Strategic Shifts & Innovations
The market's evolution is defined by the integration of high-speed data transmission capabilities into traditionally rugged, power-focused connector formats. This convergence creates new design trade-offs between signal integrity, power handling, and miniaturization for component manufacturers.
Single-Pair Ethernet (SPE) technology enables data transmission and power delivery over a single twisted pair of wires. Industrial automation and in-vehicle networks are rapidly adopting SPE for connecting sensors and control units. This technology is displacing legacy fieldbus protocols by offering a smaller footprint and IP-based communication down to the sensor level.
Compliance with the EU's RoHS directive is a fundamental market access requirement, restricting hazardous substances like lead and cadmium. This forces manufacturers to invest in alternative materials and soldering processes, impacting cost and reliability testing. The defense and aerospace sectors often receive exemptions, but commercial-grade products for the European market must fully adhere.
A significant shift in purchasing behavior sees system integrators demanding modular, field-configurable components from distributors. This model disrupts long-cycle, high-volume OEM procurement by prioritizing component availability and design flexibility over custom-engineered solutions. This trend is most visible in the fragmented European industrial automation sector, particularly within Germany's Mittelstand.
Circular Connectors Market Segmentation
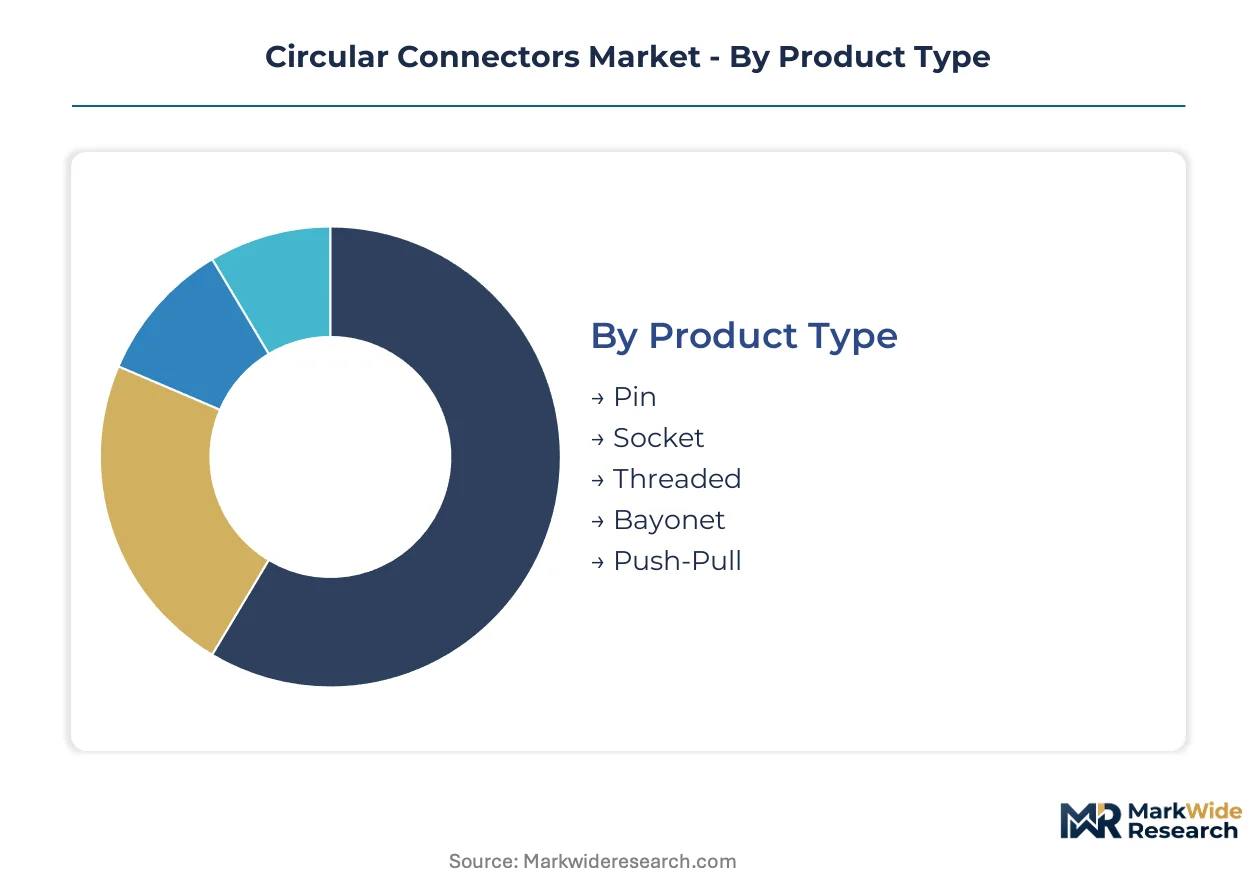
The circular connectors market divides across distinct product attributes, technological implementations, application environments, and end-user profiles. Understanding these segments helps manufacturers tailor offerings and optimize material sourcing strategies. This segmentation reveals varied performance requirements and procurement patterns across different industry verticals.
Product Type:
Margin pools within product types often concentrate in specialized locking mechanisms and high-reliability designs.
- Pin:These are the male contacts within a connector, crucial for electrical signal transmission.
- Socket:Socket contacts are the female receptacles designed to receive pins, ensuring reliable electrical continuity.
- Threaded:Threaded connectors use a screw-on mechanism for a highly secure and environmentally sealed connection, valued for their vibration resistance.
- Bayonet:Bayonet connectors offer a robust, quick-locking interface by twisting the coupling nut, providing strong resistance to vibration and accidental disconnection. Industrial automation applications in Germany and China heavily utilize bayonet types for connecting sensors and actuators, valuing their resilience in harsh factory environments.
- Push-Pull:These connectors feature a quick-mating mechanism that allows for rapid connection and disconnection, often favored in medical and instrumentation applications where frequent mating cycles are common. Demand for these precision components is accelerating in portable diagnostic devices and surgical robotics, driven by the need for secure, miniature interfaces.
Pin components hold installed capacity. Push-Pull designs are rotating up the share rankings.
Technology:
Cost structures for circular connector technologies vary significantly based on manufacturing complexity and material intensity.
- Crimp:Crimp technology provides a gas-tight, vibration-resistant electrical connection without soldering, simplifying field assembly.
- Solder:Solder connections offer a permanent, low-resistance electrical bond between wire and contact, ensuring long-term reliability.
- PCB Mount:These connectors are directly integrated onto printed circuit boards, enabling compact electronic designs and reducing overall device size. Miniaturization trends in medical instrumentation and aerospace drive demand for these high-density solutions, requiring precise manufacturing.
- Wire-to-Wire:These connectors facilitate direct electrical connection between two discrete wires or cable assemblies, commonly used for extending power or data lines.
- Waterproof:Engineered with seals and robust housings, these technologies prevent ingress of liquids and dust, maintaining electrical integrity in harsh environments. The build-out of electric vehicle charging infrastructure and marine systems is driving demand for these sealed interfaces.
Wire-to-Wire assemblies represent a foundational technology. PCB Mount solutions are experiencing the steepest expansion trajectory.
Application:
Volume distribution across applications is heavily skewed towards sectors undergoing rapid digital transformation.
- Aerospace:Connectors in aerospace applications must meet stringent specifications for weight, vibration resistance, and extreme temperature tolerance, ensuring reliable performance in aircraft and spacecraft. The need for higher data transmission speeds within compact designs presents a persistent engineering challenge for suppliers.
- Military Defense:This segment requires MIL-SPEC compliant connectors for ruggedness and performance in extreme conditions, often involving long qualification processes.
- Telecommunications:Circular connectors support network infrastructure, providing reliable connections for data and power transmission in outdoor and indoor settings.
- Industrial Automation:This sector utilizes circular connectors for robotics, automated production lines, and IIoT devices, requiring robust interconnections resistant to vibration and environmental factors. Demand is particularly strong in advanced manufacturing centers like Germany and China, supporting complex automated systems.
- Marine Systems:These applications demand highly waterproof and corrosion-resistant connectors for reliable operation in saline environments, such as offshore platforms and naval vessels.
Industrial Automation applications account for the largest volume. Aerospace commands premium pricing due to stringent specifications.
End User:
Procurement patterns among end-users reflect varying degrees of integration and specification control.
- OEMs:Original Equipment Manufacturers incorporate circular connectors directly into their products during initial design and assembly, often requiring custom or high-volume standardized components. Their purchasing cycles are typically long-term and driven by specific product development roadmaps.
- Tier-1 Suppliers:These companies provide sub-assemblies to OEMs, requiring connectors that meet both OEM specifications and production efficiency needs for mass production.
- System Integrators:These entities combine components from various manufacturers to create complete industrial or commercial solutions, demanding modular and field-configurable connectors. This shift in procurement away from traditional OEM cycles prioritizes design flexibility and immediate component availability.
- Maintenance Providers:These users require replacement parts and repair solutions, focusing on availability and compatibility with existing infrastructure for operational continuity.
- Aftermarket Services:This segment addresses post-sale support and upgrades, often demanding specialized connectors for longevity and performance enhancement in existing systems.
OEMs traditionally drive significant volume. System Integrators are increasingly influencing component design and availability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Concentration of advanced manufacturing centers for circular connectors is evident across several key regions. These areas drive significant demand, influenced by industrial automation growth and stringent regulatory compliance. Procurement patterns reflect the need for reliable, high-performance interconnection solutions in complex systems.
United States
Demand for circular connectors in the United States stems from aerospace and military defense sectors. MIL-SPEC standards dictate performance under extreme shock and vibration for critical applications. Silicon Valley and the defense industry hubs in California and Texas drive innovation in high-reliability components.
Germany
Germany's industrial automation sector significantly drives circular connector demand, particularly for M-series types. The EU's RoHS directive mandates lead-free solders and halogen-free plastics for market access. Manufacturing clusters in Bavaria and Baden-Württemberg focus on precision engineering for robotics and automated production lines.
China
China's rapid expansion in industrial automation and IIoT devices fuels substantial demand for circular connectors. Compliance with GB standards ensures product quality and safety within the domestic market. Production centers in the Yangtze River Delta and Pearl River Delta are critical for high-volume manufacturing and localized supply.
Japan
Advanced manufacturing and automotive industries propel demand for high-density circular connectors in Japan. JIS standards provide a framework for quality and performance in precision components. Industrial zones around Tokyo and Nagoya concentrate on miniaturization and high-speed data transmission solutions.
France
The French aerospace and defense industries require robust circular connectors for critical systems. Compliance with EU RoHS and CE marking is essential for commercial product entry. Toulouse, a major aerospace hub, and other industrial regions focus on high-reliability and custom connector solutions.
Circular Connectors Market Key Industry Players
Concentration sits with established global manufacturers and specialized niche players within the circular connectors market. The market exhibits a tiered structure, with a few large entities dominating high-volume and complex applications. Archetypes include comprehensive portfolio providers, regional industrial specialists, and precision component innovators. These larger players often leverage extensive distribution networks. Competitive moves involve portfolio diversification into adjacent technologies and strategic geographic expansion.
On the premium-tier vector, TE Connectivity exemplifies a global leader with a broad portfolio, anchoring high-volume applications across diverse industries and leveraging its extensive manufacturing footprint. Lemo occupies a distinct position as a specialist in high-precision push-pull connectors, serving demanding medical and instrumentation sectors with its intricate designs and high-mating cycle capabilities. Binder represents a focused regional player, concentrating on M-series connectors specifically tailored for European industrial automation clients and emphasizing robust, reliable solutions. These companies collectively illustrate the varied strategic approaches within the competitive landscape, from broad market coverage to deep niche specialization influencing component availability.
| Leading Market Players |
|---|
| HARTING |
| Lemo |
| TE Connectivity |
| Binder |
| Phoenix Contact |
| Amphenol |
| ITT Cannon |
| Hirose |
| Molex |
| Others |
Cost & Logistics Intelligence
The EU's RoHS directive gates both component qualification and price differentiation across European markets for commercial-grade circular connectors. This regulatory framework influences material sourcing and manufacturing processes for compliant products.
Pricing Analysis
The EU's RoHS directive dictates the pricing tier structure for commercial circular connectors, favoring compliant components. Pricing stratifies across premium, standard, and economy tiers based on certification level and customization requirements. Cost compression in standard industrial connectors is intensifying due to increasing competition and input cost volatility for materials like gold. Aerospace and military defense sectors exhibit the lowest price sensitivity, prioritizing performance and MIL-SPEC compliance over cost.
Supply Chain Analysis
Port congestion and container availability in key Asian trade lanes present ongoing challenges for inbound logistics. Supply concentration for circular connectors centers on advanced manufacturing hubs in Germany, China, and the United States. The industry relies heavily on specialized raw materials, including gold and beryllium copper for contacts, alongside high-performance plastics. Commodity price volatility for these inputs represents a significant structural risk. Distribution runs through a hybrid model, combining direct sales to OEMs with extensive networks of system integrators and distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers fragmentation opportunities as system integrators demand modular, field-configurable components, creating distinct niches. This shift reorganizes procurement patterns away from traditional OEM purchasing cycles.
For Market Incumbents: Fortify core market positions by investing in hybrid connector technologies that integrate fiber optic and copper contacts. Diversify global manufacturing footprints to mitigate geopolitical supply risks and leverage regional cost advantages. Address substitution threats from ruggedized rectangular connectors by enhancing the value proposition of circular formats through higher data rates and power delivery. Focus R&D on miniaturization and enhanced ruggedization for demanding applications.
For New Entrants and Emerging Players: Lead with specialized solutions for high-growth white-space opportunities like electric vehicle charging infrastructure. Target the medical instrumentation sector with ultra-miniature push-pull connectors for portable diagnostic devices. The build-out of EV charging networks represents a highly penetrable application segment. A go-to-market angle focused on rapid customization and localized technical support can differentiate offerings.
For Investors and Strategic Acquirers: Carve-out targets emerge from established manufacturers seeking to divest non-core connector product lines. The market offers long-term viability, spanning a 5-10 year window, driven by industrial automation and IIoT proliferation. Niche specialists in high-precision push-pull or hybrid connector technologies represent attractive acquisition archetypes. The adoption rate of Single-Pair Ethernet (SPE) in industrial applications is a specific signal to watch as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification into Hybrid Connectors | This move addresses the simultaneous demand for higher data transmission and increased power delivery in complex systems. |
| Investment in MIL-SPEC Qualification | This secures access to high-margin aerospace and military defense sectors with stringent performance requirements. |
| Expansion of PCB Mount Connector Production | This supports device miniaturization trends in medical and aerospace by enabling compact electronic designs. |
| Targeted R&D in Waterproofing Technologies | This addresses the growing demand from EV infrastructure and marine systems for sealed, robust interfaces. |
| Strategic Partnerships with System Integrators | This aligns with shifting procurement patterns towards modular and field-configurable components, enhancing market reach. |
Research Approach
Findings reconcile primary fieldwork against secondary review of industry reports, regulatory filings, patent databases, and trade association publications. This approach integrates insights from interviews with OEM engineers, system integrators, procurement managers, and material scientists. Bottom-up sizing estimates are validated against top-down market projections, ensuring comprehensive data triangulation.
Segmentation dimensions modeled across the analysis window include product type, technology, application, end-user, and regional demand trends. Compound annual growth rates are derived from historical data analysis and projected market drivers such as IIoT device proliferation and EV infrastructure growth. The analytical framework incorporates specific inputs like the adoption rate of M-series connectors in industrial automation.
Forecasts assume regulatory continuity in the EU's RoHS directive and US MIL-SPEC standards; material policy shifts would require re-modeling. The analysis reflects assumptions regarding raw material availability and geopolitical trade stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
Connector Kits Market
Connectors
Global Wired Interface Market
Connectors
Underwater Mate Connectors Market
Connectors
Hybrid Fiber Optic Connectors Market
Connectors
Connector Market
Connectors
LCP Connectors Market
Connectors
Mexico Connector Market
Connectors
Terminal Pins Market
Connectors
Telecom Mounting Hardware Market
Connectors
Canada Connector Market
Connectors
Circular Waterproof Connector Market
Connectors
Underwater Connectors Market
Connectors
Power Connector Market
Connectors
Small Bore Connectors Market
Connectors
Line Clamp Market
Connectors
PCI-E Connectors Market