
 5G Connector Market | 2026-2036
5G Connector Market Size, Share, and Industry Trends Forecast 2026-2036
5G Connector Market Analysis
RF engineering talent shortages in precision manufacturing hubs is unwinding capacity expansion timelines across the 5G connector supply base. TE Connectivity leverages captive microwave testing facilities to sustain design-to-production cycles for mmWave-rated interfaces. Amphenol Corporation anchors North American defense-telecom crossover demand through qualified mil-spec product lines. Molex competes in Asia-Pacific contract manufacturing channels with high-volume stamped-contact programs.
5G connectors are electromechanical interfaces engineered to transmit radio frequency, optical, or mixed signals between network elements with controlled impedance, typically operating from sub-6 GHz through mmWave spectrum bands up to 71 GHz depending on application grade. RF connectors dominate current procurement volumes given their ubiquity in antenna-to-radio links and base station internal cabling, while fiber optic connectors capture expanding share in fronthaul and midhaul aggregation where CPRI and eCPRI protocols demand optical backbones. Installation type splits reveal outdoor-hardened variants commanding premium positioning due to IP67 sealing and salt-spray certification requirements that indoor designs do not face.
FCC Part 27 licensing frameworks in the United States shape product roadmaps by defining permissible operating bands and power thresholds that connector electrical performance must support. ETSI EN 301 908 standards in Europe mandate harmonized spectrum use and interoperability testing that manufacturers must satisfy for CE marking access. China's MIIT radio transmission equipment type-approval rules govern domestic 5G infrastructure deployment and influence export-oriented production standards. Stakeholders should monitor regulatory band reallocation proceedings in major economies, as spectrum reassignment directly forces connector redesign cycles and inventory obsolescence risk.
Market Dynamics
Millimeter-wave spectrum commercialization is compressing design-to-production cycles for precision RF interfaces, forcing connector manufacturers to synchronize roadmaps with base station OEM release schedules rather than traditional component procurement timelines.
Growth Catalysts
- EU Radio Equipment Directive:Tightened electromagnetic compatibility mandates are accelerating replacement demand for legacy network hardware across European telecom infrastructure.
- FCC Part 27 licensing:Expanded mid-band spectrum allocations in the United States are driving connector redesigns to support 3.7-3.98 GHz C-band deployments.
- South Korean 5G densification:Telecom operators in Seoul and Busan are deploying small-cell architectures that multiply connector counts per base station site.
Market Restraints
- Copper-lithium alloy cost volatility:High-performance contact material prices swing with Chilean and Australian mining output, squeezing margin structures on precision-machined components.
- Guangdong-Shenzhen supply concentration:Over 60 percent of stamped-contact capacity sits within a 200-kilometer corridor, creating single-point-of-failure exposure for global procurement.
- Millimeter-wave insertion loss floors:Physical constraints on dielectric materials limit signal integrity above 28 GHz, capping addressable performance tiers.
Strategic Opportunities
- India DOT 5G spectrum policy:Domestic manufacturing-linked incentives under the PLI scheme are attracting connector producers to establish localized stamping and plating operations.
- Open RAN disaggregation:Interface standardization between radio units and distributed units is opening procurement to second-source connector vendors previously locked out by integrated OEM supply agreements.
- Photonic-electric hybrid integration:Converged RF-optical backplane connectors are capturing design wins in centralized RAN architectures where CPRI-over-optical meets millimeter-wave radio heads.
Industry Challenges
- RF simulation talent scarcity:Electromagnetic modeling expertise for 3D full-wave analysis of mmWave interconnects commands premium compensation in Shenzhen, Boston, and Munich labor markets.
- MIIT type-approval timelines:China's radio transmission equipment certification process extends 14-18 months for new connector families, delaying revenue recognition on R&D investments.
- Multi-generational inventory complexity:Simultaneous support for sub-6 GHz, 28 GHz, and 39 GHz variants fragments production scheduling and test fixture capital allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G Connector Market |
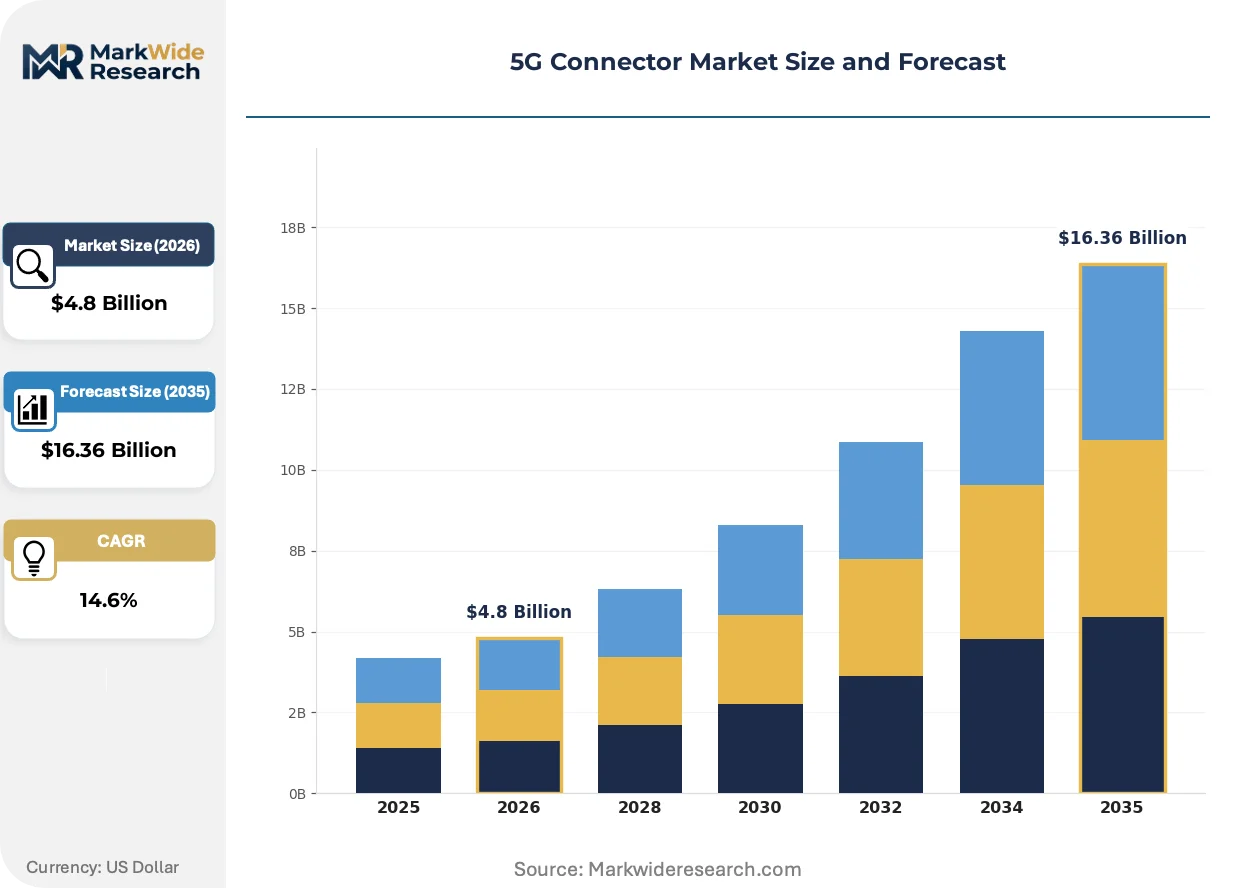
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: RF Connectors, Fiber Optic Connectors, Coaxial Connectors, USB Connectors Installation Type: Indoor, Outdoor, Hybrid, Rack-mounted End User: Telecom Operators, System Integrators, OEMs, Device Manufacturers Technology: Active, Passive, FTTx, Small Cells |
| Companies Covered | TE Connectivity, Amphenol Corporation, Molex, Rosenberger Group, Hirose Electric, Samtec, Luxshare Precision, I-PEX, JAE Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G Connector Market Emerging Trajectories
Active antenna system integration is collapsing the physical boundary between connector and antenna module, compressing component hierarchies and elevating subsystem-level design competition over discrete interface sourcing.
Multi-layer organic substrate technology is displacing traditional machined metal housings in sub-6 GHz base station connectors. Ericsson and Nokia procurement teams are qualifying these designs for massive MIMO radio units. The technology is miniaturizing footprint requirements by 40 percent while maintaining VSWR performance through 6 GHz.
ETSI EN 301 908 harmonized standards are mandating interoperability testing across European 5G equipment certifications. Connector electrical performance must now demonstrate cross-vendor compatibility in third-party test houses. High-frequency RF interface suppliers in Germany and Finland are restructuring quality assurance workflows to satisfy CE marking access requirements.
Telecom procurement teams are consolidating supplier panels from twelve-plus vendors to four-to-six strategic partners with captive testing capabilities. Direct sourcing relationships are displacing distribution intermediaries for volume connector programs. This concentration is most visible in China's coastal manufacturing clusters where Huawei and ZTE procurement organizations negotiate multi-year frame agreements.
5G Connector Market Segmentation
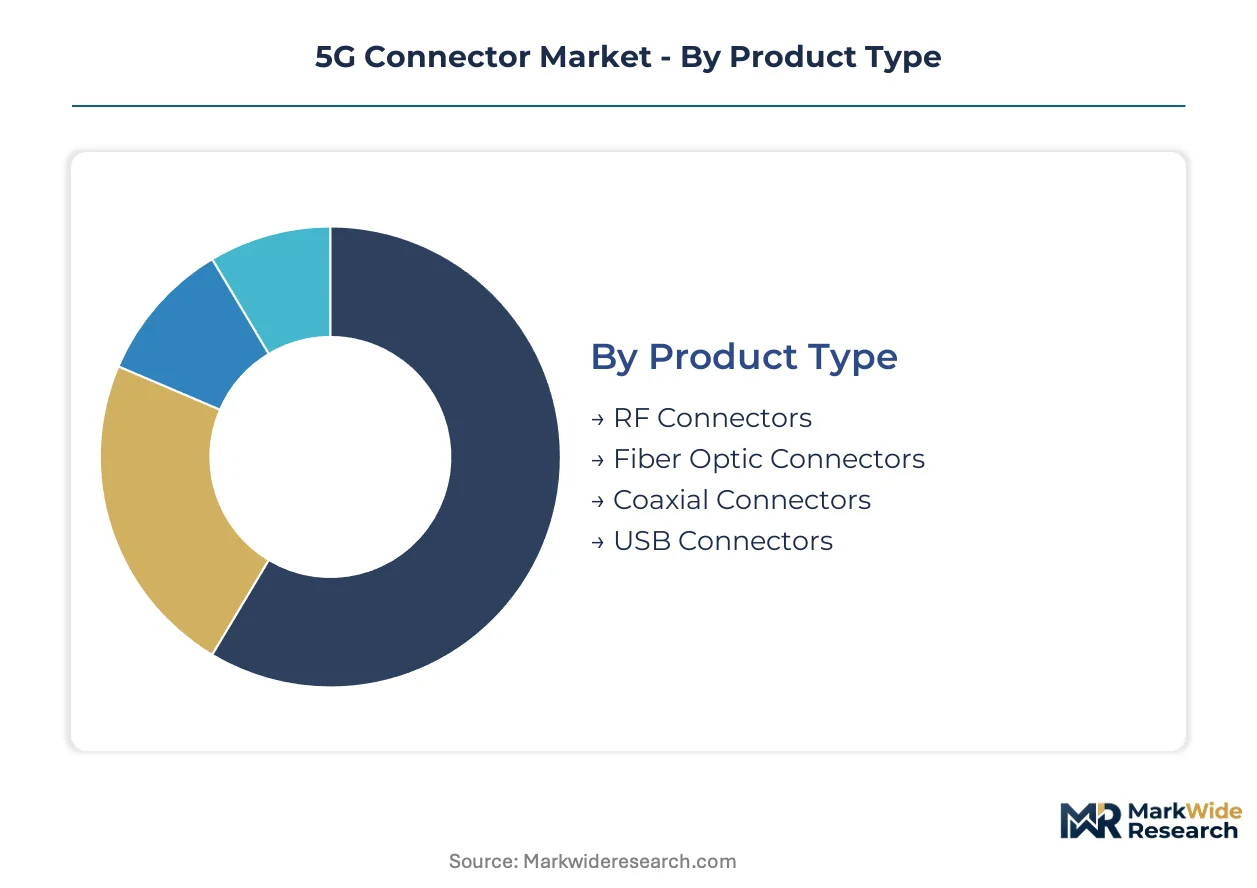
Connector procurement patterns diverge sharply across deployment contexts, with spectrum band requirements and environmental exposure dictating interface specifications. Understanding these segment boundaries clarifies where suppliers can defend margin premiums versus where price competition dominates.
Product Type:
Margin pools concentrate in millimeter-wave-rated interfaces where electromagnetic modeling complexity creates scarcity premiums.
- RF Connectors:Precision-machined electromechanical interfaces engineered for controlled impedance through 71 GHz, typically brass or beryllium copper housings with gold-plated contacts. Procurement volumes concentrate in South Korean small-cell densification projects where antenna-to-radio link densities multiply connector counts per site.
- Fiber Optic Connectors:Ceramic ferrule or expanded-beam designs terminating single-mode and multimode fiber in fronthaul aggregation links. Demand is accelerating in China's coastal manufacturing clusters where CPRI-over-optical backbones displace copper in centralized RAN architectures.
- Coaxial Connectors:Threaded or push-on interfaces for sub-6 GHz radio frequency transmission with standardized impedance matching.
- USB Connectors:Universal serial bus interfaces for diagnostic ports and power delivery in base station maintenance access panels.
The dominant share belongs to RF Connectors, while Fiber Optic Connectors is closing the gap fastest.
Installation Type:
Environmental hardening requirements split the market into indoor commodity supply and outdoor premium positioning.
- Outdoor:IP67-sealed housings with salt-spray certification and UV-resistant polymers for tower-top and pole-mounted deployments. Premium pricing sustains in European markets where ETSI EN 301 908 mandates extended temperature cycling validation for CE marking access.
- Indoor:Unsealed or basic dust-protected designs for climate-controlled equipment rooms and data center environments. Volume concentrates in China's Guangdong-Shenzhen corridor where stamped-contact manufacturing achieves economies of scale for domestic base station production.
- Hybrid:Modular designs supporting both indoor and outdoor deployment through interchangeable sealing configurations.
- Rack-mounted:High-density panel arrangements for centralized baseband processing equipment in macro cell aggregation sites.
Outdoor commands the steepest price premiums, yet Indoor captures the largest procurement volumes by unit count.
End User:
Procurement sophistication varies with technical integration depth and supply chain leverage.
- Telecom Operators:Direct purchasers with captive engineering teams specifying connector electrical performance for national network builds. South Korean operators in Seoul and Busan are consolidating supplier panels to four-to-six strategic partners with captive microwave testing capabilities.
- OEMs:Radio unit and base station manufacturers integrating connectors into subsystem assemblies for operator resale. Design win competition intensifies around mmWave-rated interfaces where 3D full-wave simulation expertise commands scarcity premiums in Shenzhen and Boston labor markets.
- System Integrators:Third-party deployment contractors procuring connectors for installation and maintenance services.
- Device Manufacturers:CPE and handset producers sourcing miniaturized connectors for consumer premise equipment.
Telecom Operators retain the dominant procurement value, while OEMs are expanding their specification influence fastest.
Technology:
Signal conditioning requirements differentiate passive commodity supply from active value-added integration.
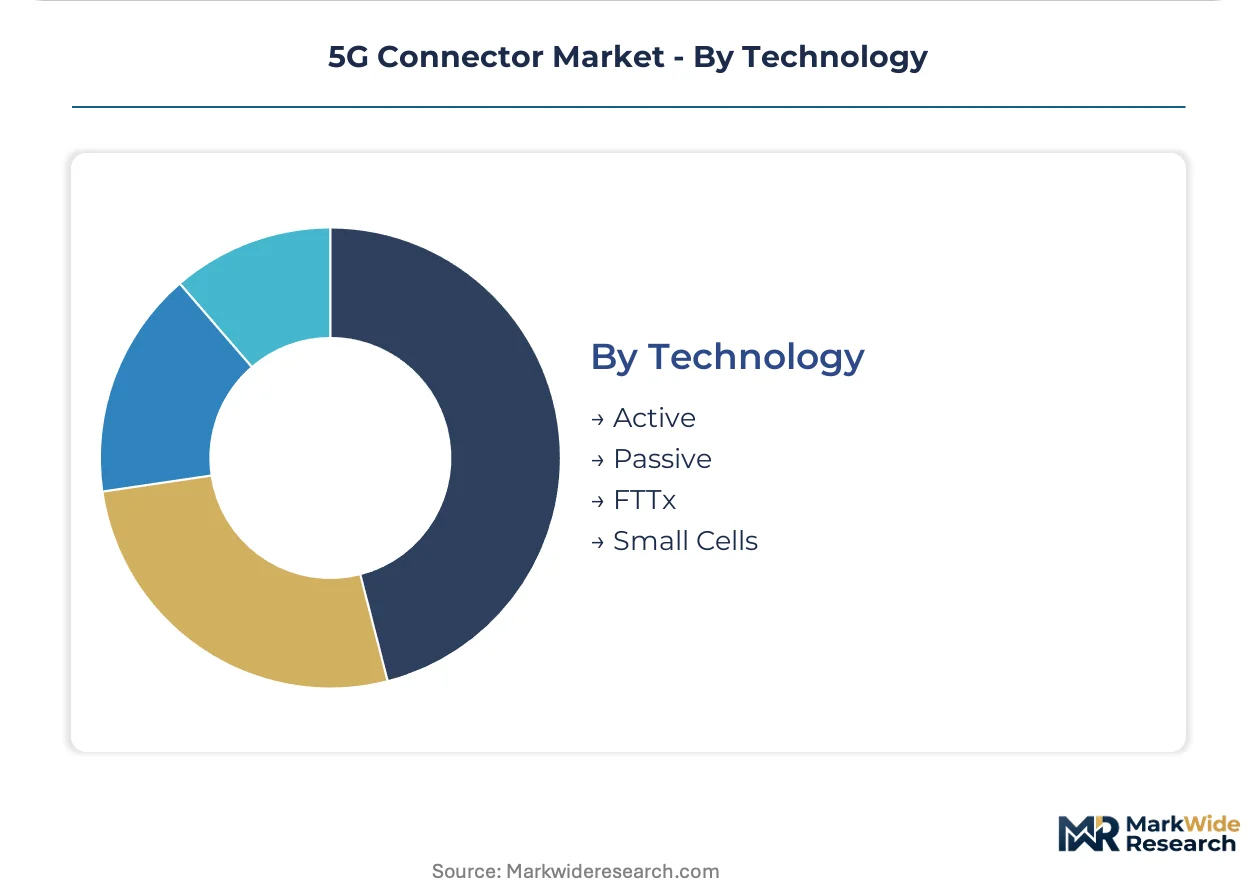
- Passive:Unpowered electromechanical interfaces relying on physical contact geometry for signal integrity. Sub-6 GHz massive MIMO deployments in India's emerging 5G infrastructure under DOT spectrum policy are driving volume demand for standardized stamped-contact designs.
- Active:Electronically compensated connectors with embedded signal conditioning circuits for loss mitigation at mmWave frequencies. Premium positioning sustains where 28 GHz and 39 GHz commercialization forces redesign cycles synchronized with base station OEM roadmaps.
- FTTx:Fiber-to-the-x optical termination technologies for last-mile connectivity integration.
- Small Cells:Compact form-factor connectors purpose-built for dense urban microcell and picocell deployments.
Passive retains volume leadership, while Active is capturing incremental value share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. South Korean operators prioritize small-cell density with premium mmWave-rated interfaces, while Chinese procurement emphasizes high-volume stamped-contact programs for sub-6 GHz massive MIMO deployments. European markets concentrate spending on regulatory-compliant outdoor-hardened variants with extended temperature validation.
United States
FCC Part 27 licensing frameworks are accelerating C-band infrastructure builds across metropolitan corridors. The Federal Communications Commission's mid-band spectrum auctions have forced connector redesigns supporting 3.7-3.98 GHz deployments. Boston-area RF engineering clusters are capturing design-to-production cycles for precision-machined interfaces serving domestic base station OEMs.
China
MIIT radio transmission equipment type-approval rules govern 5G infrastructure deployment timelines and export-oriented production standards. The Ministry of Industry and Information Technology certification process extends 14-18 months for new connector families. Guangdong-Shenzhen manufacturing clusters concentrate over 60 percent of global stamped-contact capacity within a 200-kilometer corridor.
South Korea
Telecom operators in Seoul and Busan are deploying small-cell architectures that multiply connector counts per base station site. The Korea Communications Commission spectrum policy supports millimeter-wave commercialization forcing compressed design cycles. Daegu-Gyeongbuk industrial zones are anchoring precision manufacturing capacity for antenna-to-radio link densities.
Germany
ETSI EN 301 908 harmonized standards mandate interoperability testing across European 5G equipment certifications. The European Telecommunications Standards Institute requirements are restructuring quality assurance workflows for CE marking access. Bavarian high-frequency RF interface suppliers are capturing scarcity premiums through captive microwave testing capabilities.
India
DOT 5G spectrum policy under the Department of Telecommunications is attracting connector producers through PLI scheme manufacturing-linked incentives. The Production Linked Incentive scheme supports localized stamping and plating operations for emerging 5G infrastructure. Maharashtra and Gujarat industrial corridors are anchoring contract manufacturing channels for passive connector programs.
5G Connector Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the 5G connector supply base. Three archetypes define competitive positioning: precision-machined RF specialists with captive electromagnetic modeling capabilities, high-volume stamped-contact manufacturers serving contract electronics channels, and hybrid RF-optical integrators capturing converged backplane designs. Consolidation pressure is intensifying as telecom procurement teams reduce supplier panels from twelve-plus vendors to four-to-six strategic partners with in-house testing facilities.
Among precision-machined specialists, TE Connectivity and Amphenol Corporation exemplify the integrated tier with established defense-telecom crossover positioning. Molex occupies a position within high-volume manufacturing channels serving Asia-Pacific contract electronics demand. These three anchors represent divergent strategic vectors: captive testing infrastructure, mil-spec qualification pathways, and stamped-contact scale economics.
| Leading Market Players |
|---|
| TE Connectivity |
| Amphenol Corporation |
| Molex |
| Rosenberger Group |
| Hirose Electric |
| Samtec |
| Luxshare Precision |
| I-PEX |
| JAE Electronics |
| Others |
Supply Flow & Price Mechanics
Stamped-contact manufacturing scale in China's Guangdong-Shenzhen corridor creates asymmetric pricing power where volume concentration depresses price floors for sub-6 GHz passive connectors while precision-machined mmWave interfaces sustain scarcity premiums. This dual-structure market forces procurement teams to navigate divergent cost dynamics across performance tiers.
Pricing Analysis
Long-term frame agreements dominate procurement for high-volume passive connectors, while spot-market spot-buying persists for specialized mmWave prototypes and emergency replacements. Price differentiation rests on certification grade—CE-marked outdoor-hardened variants command substantial premiums over unsealed indoor designs—and captive microwave testing capabilities that reduce third-party validation costs. Cost compression in stamped-contact tiers is intensifying because of copper-lithium alloy volatility tied to Chilean mining output. Telecom operators exhibit the highest price sensitivity for indoor passive connectors, whereas defense-telecom crossover buyers show minimal sensitivity for mil-spec qualified interfaces.
Supply Chain Analysis
Just-in-time inventory strategies dominate high-volume stamped-contact procurement from China's coastal manufacturing clusters, while strategic stockpiling of precision-machined brass and beryllium copper housings buffers against Australian and Chilean raw material volatility. Supply concentrates in China, South Korea, and Germany, with connector production drawing from copper alloy feedstocks, ceramic ferrules for optical variants, and specialized polymer compounds for dielectric insulation. Single-source vulnerability concentrates in the Guangdong-Shenzhen corridor where over sixty percent of global stamped-contact capacity sits within a two-hundred-kilometer radius. Distribution runs through direct sourcing relationships that displace distribution intermediaries as telecom procurement teams consolidate supplier panels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
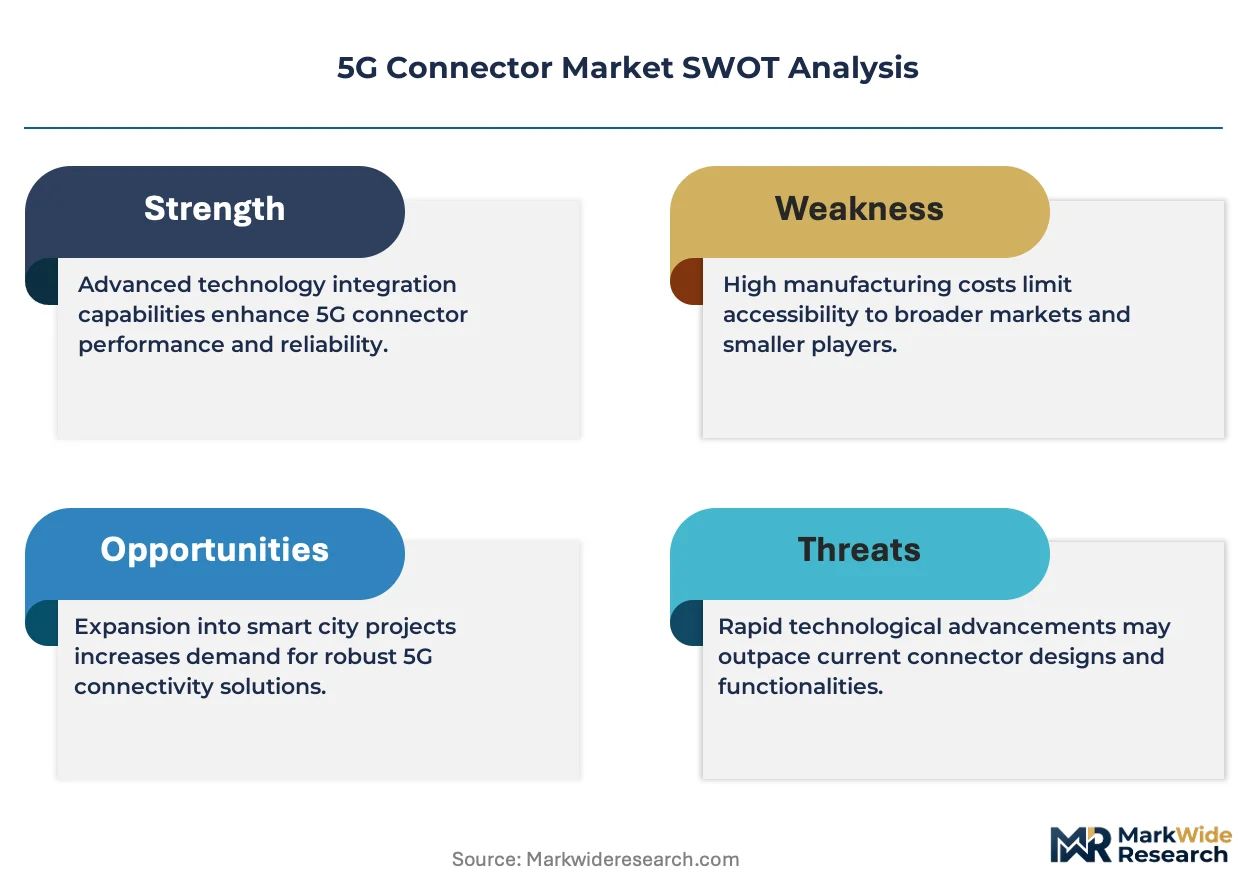
Open RAN interface standardization fragments procurement authority away from integrated base station OEMs, creating entry niches for second-source connector vendors previously locked out by exclusive supply agreements.
For Market Incumbents: Compound defensive positioning through captive microwave testing infrastructure investments that accelerate MIIT type-approval timelines for new connector families. Deepen backward integration into precision-machined brass and beryllium copper housing production to buffer against raw material volatility from Australian and Chilean mining sources. Certification leverage—particularly CE marking and mil-spec qualification pathways—remains the critical barrier against emerging Asian contract manufacturers. For New Entrants and Emerging Players: Anchor in India's DOT PLI scheme manufacturing corridors where localized stamping and plating operations qualify for domestic production-linked incentives. The most penetrable white-space sits in photonic-electric hybrid backplane connectors for centralized RAN architectures where CPRI-over-optical meets millimeter-wave radio heads. A design-win-first go-to-market strategy targeting Ericsson and Nokia procurement qualification programs offers faster revenue recognition than volume commodity plays. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision-machined RF specialists with embedded electromagnetic modeling capabilities over stamped-contact scale players facing margin compression. Long-term viability over the next decade rests on mmWave commercialization trajectories and spectrum band reallocation proceedings in major economies. The signal to monitor is FCC Part 27 and ETSI EN 301 908 regulatory band reallocation timelines, which force connector redesign cycles and inventory obsolescence risk that favors agile specialists over rigid volume manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Microwave Testing Facility Investment | Accelerates MIIT type-approval timelines and reduces third-party validation dependencies for CE marking access. |
| Backward Integration into Precision Alloy Feedstocks | Buffers margin structures against copper-lithium volatility from Chilean and Australian mining output swings. |
| Open RAN Interface Standardization Compliance | Unlocks procurement access previously blocked by integrated OEM exclusive supply agreements in European markets. |
| Photonic-Electric Hybrid Connector Development | Captures design wins in centralized RAN architectures where CPRI-over-optical converges with mmWave radio heads. |
| India PLI Scheme Manufacturing Localization | Qualifies for DOT production-linked incentives while positioning for emerging 5G infrastructure buildouts under TRAI spectrum policy. |
Methodological Framework
Initial hypotheses were tested against primary input from RF engineering directors at base station OEMs, telecom procurement leads, connector manufacturing operations heads, and regulatory affairs specialists at MIIT and FCC, then refined against secondary validation from ETSI EN 301 908 certification databases, SEC 10-K filings from listed component suppliers, MIIT radio transmission equipment type-approval registries, and customs trade data for copper alloy feedstock flows. Bottom-up demand modeling across installation types, spectrum bands, and end-user procurement channels triangulated with top-down market sizing from national 5G infrastructure deployment disclosures.
Variance decomposition across the projection horizon isolates volume drivers by product type, installation environment, technology tier, and regional regulatory cluster, with CAGRs derived from segmented growth rate reconciliation against aggregate market expansion. The analytical framework incorporates spectrum auction timelines, base station OEM product roadmaps, and raw material cost indices as industry-specific forecast inputs alongside macroeconomic baseline assumptions.
Material uncertainties—regulatory band reallocation proceedings, copper-lithium alloy price volatility, and Open RAN standardization adoption curves—sit outside the modeled envelope and could materially alter trajectory. Revision becomes warranted when FCC Part 27 or ETSI EN 301 908 proceedings force connector redesign cycles that accelerate inventory obsolescence beyond modeled replacement demand assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
Connector Adapter Kits Market
Connectors
Telecom Mounting Hardware Market
Connectors
Magnetic Connector Market
Connectors
USB Type-C Market
Connectors
Liquid Cooling Connector Market
Connectors
Global Fiber Optic Connectors Market
Connectors
Space Grade Connectors Market
Connectors
Connector Market
Connectors
Global Board to Board (BTB) Connectors Market
Connectors
PCI-E Connectors Market
Connectors
Middle East and Africa Hazardous Location Connectors Market
Connectors
Wire-To-Board Connector Market
Connectors
Micro-Miniature Co-Axial Adapter Market
Connectors
Circular Connectors Market
Connectors
Australia Connector Market
Connectors
Global Cables and Connector Market