
 PCI-E Connectors Market | 2026-2036
PCI-E Connectors Market Size, Share, and Industry Trends Forecast 2026-2036
PCI-E Connectors Market Analytics
The EU Green Deal is pivoting connector procurement toward halogen-free and recyclable material specifications across European OEM supply chains. TE Connectivity leverages its vertical manufacturing footprint to sustain cost leadership in high-pin-count backplane assemblies. Molex anchors North American supply security through captive stamping and plating operations in Mexico and the United States. Amphenol differentiates via aerospace-grade process discipline transferred into data center interconnect portfolios.
PCI-E connectors are electromechanical interfaces that transmit high-speed differential signals between a motherboard and peripheral expansion cards, typically manufactured from phosphor bronze or beryllium copper contacts with liquid crystal polymer housings rated for temperatures exceeding 85 degrees Celsius. Their primary commercial purpose is to provide standardized, hot-swappable connectivity for graphics processors, network adapters, and storage accelerators across computing platforms. Standard connector types occupy the largest volume position due to backward compatibility requirements across legacy server fleets, while low profile variants are capturing fastest growth as blade servers and compact AI training nodes compress vertical clearance budgets. Gaming and data center applications concentrate the highest margin pools because thermal cycling specifications and signal integrity tolerances command premium qualification testing.
The EPA enforces hazardous substance reporting that shapes material composition decisions for connectors sold into U.S. federal server contracts, while REACH compliance in Europe mandates full substance disclosure across multi-tier supplier networks. China's GB standards and MIIT technical directives establish mandatory electromagnetic compatibility thresholds for domestically deployed networking equipment. Japan's METI energy efficiency frameworks indirectly steer connector thermal performance benchmarks through downstream server power targets. Stakeholders must monitor diverging material restriction timelines across these jurisdictions when qualifying single-SKU global product platforms.
Market Dynamics
Server refresh cycles in the United States are compressing from five years to three years as data center operators chase AI training throughput gains, forcing connector suppliers to synchronize capacity ramps with hyperscaler procurement calendars.
Growth Catalysts
- AI Accelerator Deployment:Hyperscale data centers in China are installing PCI-E 5.0 backplanes at scale to support domestic GPU clusters, pulling connector volumes upward.
- REACH Compliance:Full substance disclosure mandates across European supplier networks are accelerating qualification of halogen-free contact platings for enterprise server contracts.
- Phosphor Bronze Substitution:Beryllium copper alloys are penetrating high-pin-count applications where signal integrity tolerances tighten with each PCI-E generation.
Market Restraints
- Copper Price Volatility:Contact material costs swing with LME copper futures, compressing margin visibility for stamping operations in Mexico and the United States.
- Concentrated Plating Capacity:Precious metal finishing for high-reliability connectors clusters in East Asian facilities, exposing supply chains to single-point disruption.
- Legacy Backplane Intertia:Backward compatibility requirements for PCI-E 3.0 server fleets delay full transition to 5.0 signaling architectures.
Strategic Opportunities
- India Server Assembly:PLI scheme incentives for domestic electronics manufacturing are creating captive demand for standard-density PCI-E interconnects.
- Optical PCI-E Convergence:Co-packaged optics and electrical backplane integration is opening socket opportunities in AI training nodes with 100G+ lane rates.
- EU Green Deal Procurement:Recyclable liquid crystal polymer specifications in European OEM tenders favor suppliers with closed-loop material flows.
Industry Challenges
- Signal Integrity Engineering Talent:Scarcity of high-speed differential modeling specialists delays 64 GT/s PCI-E 6.0 product qualification cycles.
- Multi-Jurisdiction Certification Overlap:Simultaneous EPA hazardous substance reporting and REACH substance disclosure create documentation redundancy for global SKU platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PCI-E Connectors Market |
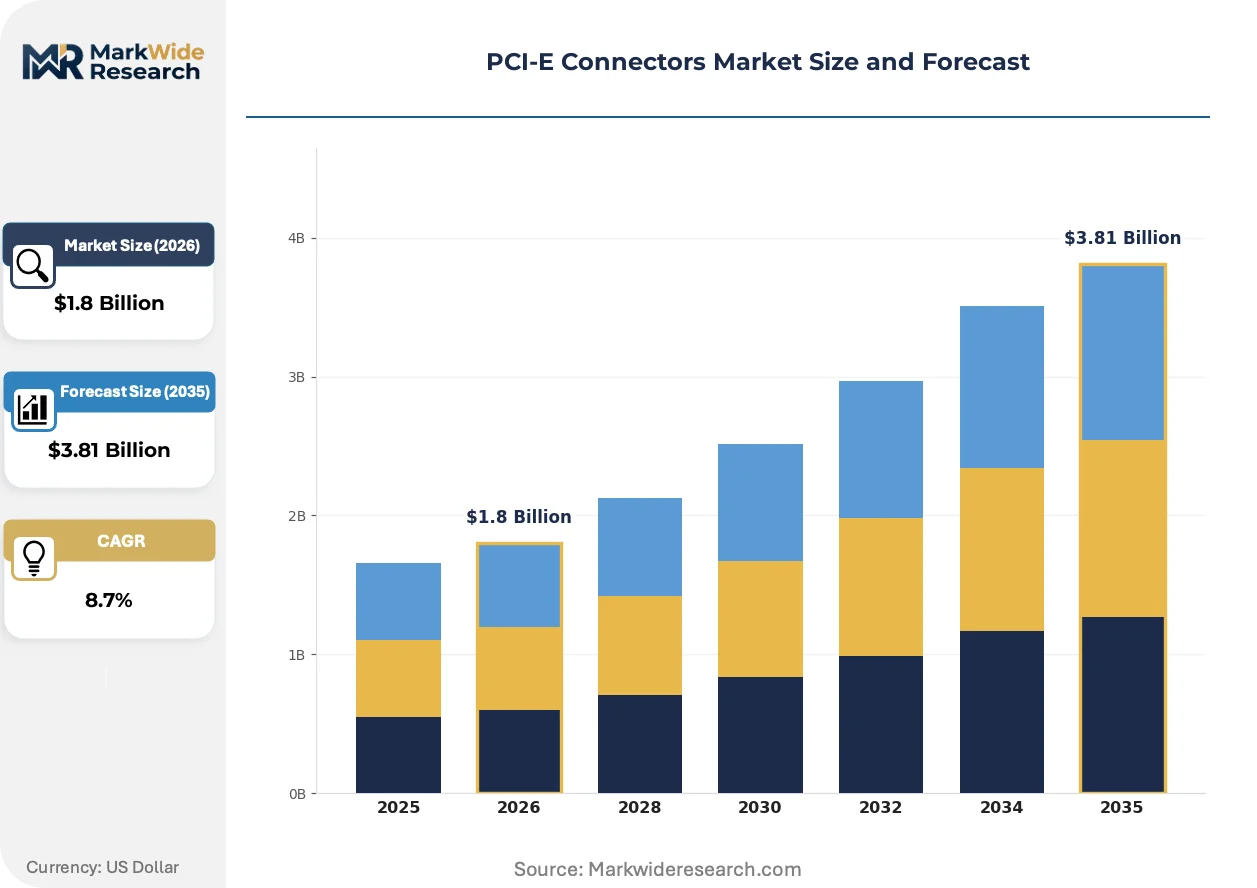
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Connector Type: Standard, Low Profile, Right Angle, Vertical Application: Gaming, Workstations, Servers, Data Centers Form Factor: Single Slot, Dual Slot, Multi Slot, Compact End User: OEMs, Enterprises, Individuals, Resellers |
| Companies Covered | TE Connectivity, Molex, Amphenol, Samtec, JAE Electronics, Hirose Electric, AVX (Kyocera), CJT Connectors, Foxconn, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PCI-E Connectors Market Evolving Landscape
Connector architectures are bifurcating between legacy-compatible standard densities and ultra-compact form factors purpose-built for thermal-constrained AI accelerators, with material science and regulatory chemistry driving the most consequential design pivots.
Press-fit compliant pin technology is electrifying backplane assembly workflows by eliminating solder reflow stages. Data center OEMs in the United States are adopting press-fit PCI-E connectors for blade server midplanes to compress manufacturing cycle times. This shift is electrifying demand for phosphor bronze contact alloys with calibrated insertion force profiles.
EU RoHS substance restrictions continue tightening cadmium and hexavalent chromium thresholds in electrical contacts. Connector suppliers serving European enterprise server markets are migrating to trivalent chromium and palladium-nickel plating stacks. German automotive-tier stamping houses are transferring these process disciplines into data center interconnect portfolios.
Hyperscalers are consolidating connector procurement around qualified manufacturer lists with pre-certified thermal cycling data. Direct sourcing teams at cloud operators in China and the United States are bypassing traditional distribution channels for PCI-E 5.0 backplane programs. This concentration is visible most acutely in Shenzhen and Santa Clara server assembly corridors.
PCI-E Connectors Market Segmentation
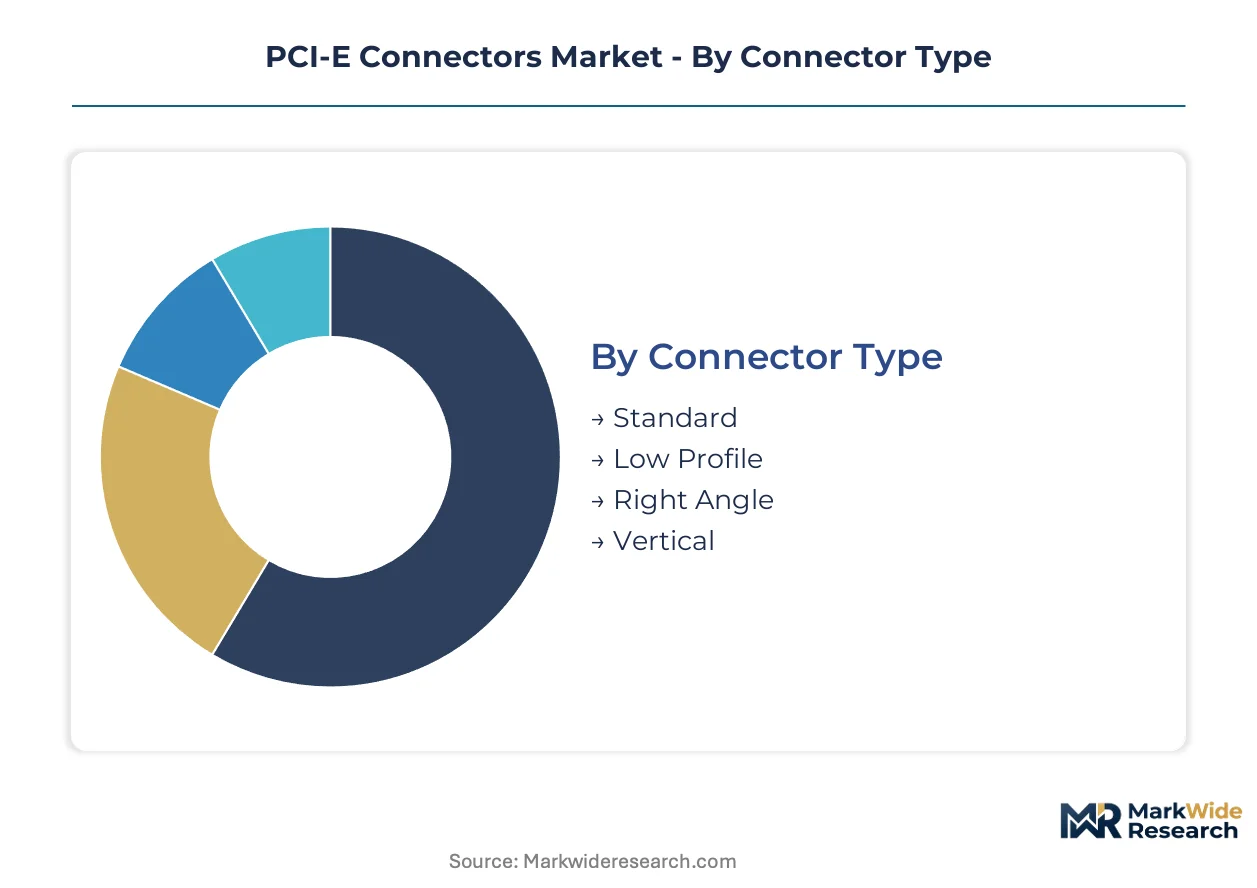
PCI-E connector procurement patterns diverge sharply between legacy server refresh programs and next-generation AI infrastructure deployments. Understanding these segment boundaries helps suppliers align plating capacity and material qualifications with diverging thermal and signal integrity specifications.
Connector Type:
Standard variants anchor standalone graphics card deployments where backward compatibility governs socket selection, while low-profile and right-angle formats embed into thermally constrained blade architectures.
- Standard:Phosphor bronze contacts with liquid crystal polymer housings rated for 85°C sustained operation. Data center operators in the United States specify these for five-to-three-year server refresh cycles where PCI-E 3.0 fleet compatibility remains mandatory.
- Low Profile:Compressed vertical clearance with identical pin assignments to standard densities. Hyperscale facilities in China are specifying these for AI training nodes where rack space efficiency governs interconnect selection.
- Right Angle:Horizontal board-mount orientation for constrained chassis layouts. Embedded system OEMs favor these for network appliance designs.
- Vertical:Perpendicular mounting for midplane backplane applications. Telecom infrastructure deployments specify these for line card architectures.
Standard connectors lead volumes today; low profile variants are gaining share fastest.
Application:
Margin structures bifurcate between consumer-grade gaming shipments and enterprise contracts demanding full REACH substance documentation.
- Gaming:High-volume discrete graphics card sockets with premium thermal cycling specifications. Add-in-board manufacturers in Taiwan drive procurement for overclocked GPU power delivery.
- Workstations:Professional visualization and CAD acceleration cards requiring extended qualification cycles. Dell and HP workstation divisions specify these for ISV-certified configurations.
- Servers:Enterprise storage and network acceleration cards with five-nines reliability requirements. Intel and AMD server platform roadmaps govern socket density selection.
- Data Centers:Hyperscale backplane assemblies with press-fit compliant pin technology. Cloud operators in China and the United States bypass distribution for direct PCI-E 5.0 procurement.
Data center applications command premium pricing; gaming volumes dominate unit shipments.
Form Factor:
Slot count determines housing material volume and contact plating costs per socket.
- Single Slot:Network adapters and entry-level storage controllers. Enterprise IT procurement favors these for standard rack server expansion.
- Dual Slot:Mid-range graphics and AI inference accelerators. Thermal design power between 150-250W drives heat sink retention bracket integration.
- Multi Slot:High-end GPU compute and training clusters. NVIDIA H100 and AMD MI300 deployments in Santa Clara and Shenzhen facilities specify these.
- Compact:Miniaturized variants for edge computing and embedded IoT gateways. Fanless industrial designs specify these for vibration-resistant locking mechanisms.
Dual slot configurations anchor current revenue; compact formats are expanding most quickly.
End User:
Procurement authority concentrates differently across direct OEM programs, enterprise IT refresh budgets, and aftermarket channels.
- OEMs:Original equipment manufacturers with qualified manufacturer lists and pre-certified thermal cycling data. Direct sourcing teams at server OEMs consolidate PCI-E 5.0 backplane procurement.
- Enterprises:Corporate IT departments with three-year depreciation schedules. Financial services and healthcare verticals specify these for HIPAA-compliant infrastructure.
- Individuals:Enthusiast builders and small system integrators. E-commerce channels and specialty retailers serve this fragmented demand.
- Resellers:Distribution and value-added reseller networks for replacement and upgrade markets. Arrow and Avnet maintain connector inventories for legacy server support.
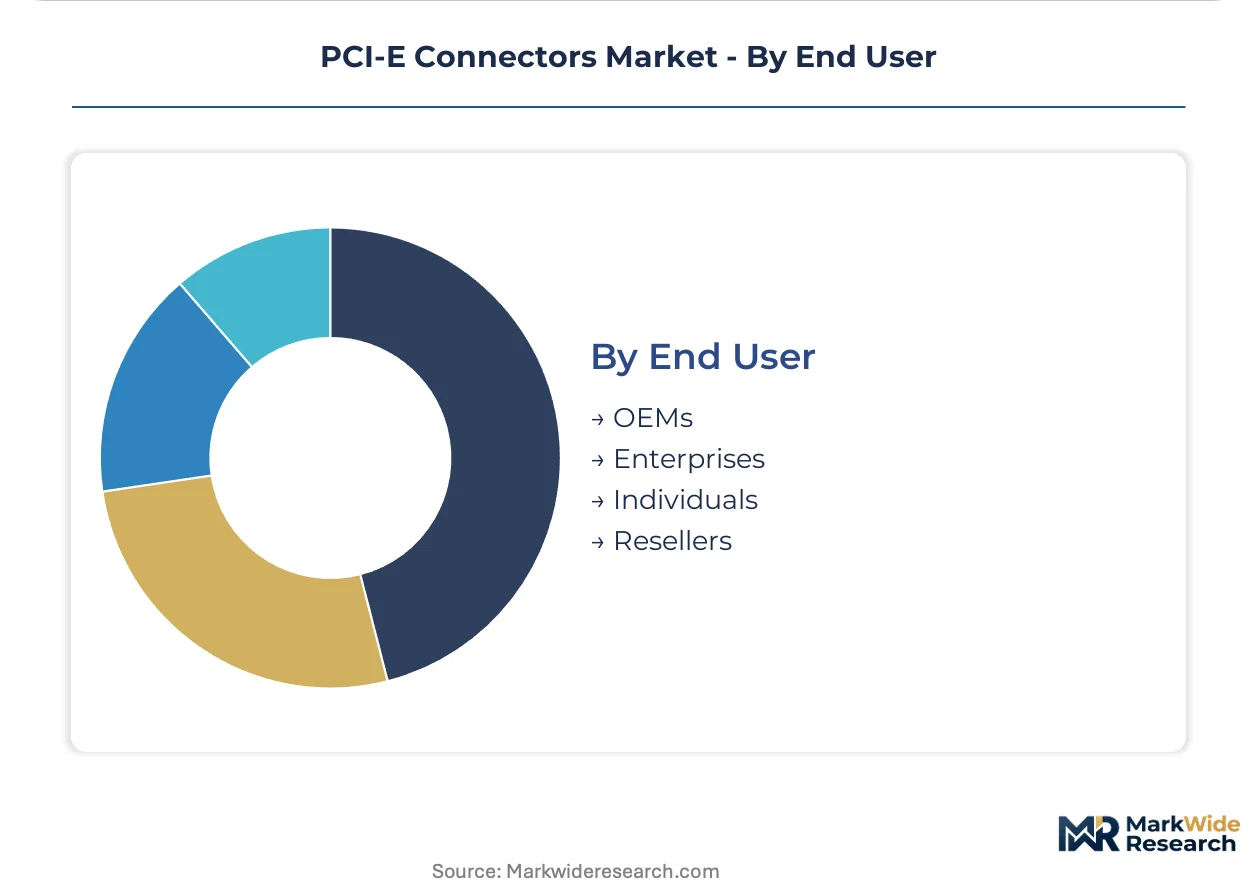
OEM direct procurement leads absolute spend; enterprise IT represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PCI-E connector manufacturing traces its industrial lineage to post-war electronics corridors in the United States and Japan, where precision stamping and plating techniques developed for military avionics migrated into commercial computing interconnects during the 1980s personal computer expansion.
United States
Hyperscale cloud operators in Santa Clara and Seattle corridors compress server refresh cycles from five years to three years to capture AI training throughput gains. EPA hazardous substance reporting requirements shape material composition decisions for connectors sold into federal server contracts. Texas and Arizona assembly facilities concentrate press-fit backplane production for blade server midplanes.
China
Domestic GPU cluster deployment pulls PCI-E 5.0 backplane volumes upward as hyperscalers scale AI infrastructure in Beijing and Shenzhen. MIIT technical directives establish mandatory electromagnetic compatibility thresholds for domestically deployed networking equipment. Yangtze River Delta stamping houses supply captive plating capacity for high-pin-count server interconnects.
Germany
Automotive-tier process discipline from Stuttgart stamping houses transfers into data center interconnect portfolios requiring REACH-compliant substance documentation. ECHA mandates accelerate qualification of halogen-free contact platings for enterprise server contracts. Bavarian industrial clusters anchor European procurement of recyclable liquid crystal polymer specifications.
Japan
METI energy efficiency frameworks indirectly steer connector thermal performance benchmarks through downstream server power targets. Domestic precision metalworking heritage supports high-reliability contact alloy development for 64 GT/s signaling architectures. Nagoya and Osaka manufacturing corridors specialize in beryllium copper stamping for aerospace-grade process discipline.
India
PLI scheme incentives for domestic electronics manufacturing create captive demand for standard-density PCI-E interconnects in Tamil Nadu and Karnataka assembly corridors. Central government production-linked incentive structures attract connector stamping operations to Chennai and Bengaluru industrial zones. Enterprise IT procurement from Mumbai financial services verticals drives premium qualification requirements.
PCI-E Connectors Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the PCI-E connector landscape. The vendor base concentrates around integrated stamping-and-plating operations versus specialized assembly houses. Three archetypes dominate: vertically integrated backplane specialists, captive electronics manufacturing services with in-house connector production, and precision component houses serving multiple interconnect protocols. Capacity expansion and strategic partnerships constitute the dominant competitive moves as suppliers synchronize with hyperscaler procurement calendars.
Among North American integrated suppliers, TE Connectivity and Molex exemplify the vertically integrated archetype through captive stamping and plating operations. Amphenol occupies a position transferring aerospace-grade process discipline into data center interconnect portfolios. Samtec represents the precision component specialist model with focus on high-speed signaling architectures.
| Leading Market Players |
|---|
| TE Connectivity |
| Molex |
| Amphenol |
| Samtec |
| JAE Electronics |
| Hirose Electric |
| AVX (Kyocera) |
| CJT Connectors |
| Foxconn |
| Others |
Value Network & Pricing Analysis
EU RoHS substance restrictions gate qualified supply and premium-tier pricing access by mandating trivalent chromium and palladium-nickel plating stacks for European enterprise contracts. Connector suppliers lacking certified halogen-free material flows face exclusion from OEM qualified manufacturer lists, compressing their addressable market to standard-density gaming and aftermarket channels with thinner margins.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies PCI-E connector markets by certification grade and thermal cycling specification. Premium tiers command substantial markups for REACH-compliant substance documentation and aerospace-grade process discipline transferred from automotive-tier stamping houses. Cost compression in standard-density segments is intensifying because phosphor bronze contact alloys face beryllium copper substitution pressure in high-pin-count applications. Enterprise IT procurement teams exhibit lowest price sensitivity due to five-nines reliability requirements, while individual enthusiast builders and small system integrators drive volume through e-commerce channels at economy tiers.
Supply Chain Analysis
Pre-certified thermal cycling data gates supplier qualification for hyperscale direct procurement programs in China and the United States. Manufacturing gravity centers on Yangtze River Delta stamping houses for captive plating capacity, Mexico and United States facilities for North American supply security, and Bavarian industrial clusters for REACH-compliant European demand. Raw material dependencies draw from LME copper futures for contact alloys, liquid crystal polymer resin for high-temperature housings, and precious metal salts for finishing baths. Single-point disruption risk concentrates in East Asian precious metal finishing facilities for high-reliability connectors. Distribution runs through direct sourcing teams at cloud operators bypassing traditional channels for PCI-E 5.0 backplane programs, with Arrow and Avnet maintaining legacy server support inventories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PCI-E connector markets offer margin-expansion pathways through beryllium copper alloy penetration in high-pin-count AI accelerator sockets and closed-loop liquid crystal polymer recycling flows qualifying for EU Green Deal procurement.
For Market Incumbents: Deepen backward integration into captive stamping and plating operations to defend margin position against phosphor bronze substitution pressure and concentrated East Asian finishing capacity. TE Connectivity and Molex anchor North American supply security through Mexico and United States facilities; Amphenol transfers aerospace-grade process discipline into data center portfolios. Priority lever rests on synchronizing capacity ramps with hyperscaler three-year refresh calendars in Santa Clara and Shenzhen corridors. For New Entrants and Emerging Players: E-commerce direct-to-manufacturer channels open white-space access in fragmented aftermarket replacement demand and India's PLI-scheme-driven server assembly corridors. Target Tamil Nadu and Karnataka industrial zones where production-linked incentive structures attract connector stamping operations with lower qualification barriers than hyperscale direct programs. Go-to-market angle emphasizes standard-density PCI-E 3.0 compatibility for legacy fleet support with faster lead times than integrated incumbents. For Investors and Strategic Acquirers: Roll-up economics work for precision component specialists with high-speed signaling expertise because signal integrity engineering talent scarcity delays 64 GT/s PCI-E 6.0 qualification cycles and creates acquisition currency. Five-to-ten-year viability hinges on optical PCI-E convergence positioning for 100G+ lane rate AI training nodes. Signal to watch is press-fit compliant pin technology adoption velocity in United States blade server midplane production.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Plating | Molex and TE Connectivity sustain cost leadership through Mexico and United States stamping operations. |
| Halogen-Free Material Qualification | REACH-compliant substance documentation gates European OEM procurement and commands premium pricing tiers. |
| Press-Fit Technology Adoption | Data center OEMs in Texas and Arizona compress manufacturing cycle times for blade server midplanes. |
| Optical PCI-E Convergence R&D | Co-packaged optics integration opens socket opportunities in 100G+ lane rate AI training nodes. |
| India PLI Corridor Expansion | Tamil Nadu and Karnataka assembly zones create captive demand for standard-density PCI-E interconnects. |
Research Methodology
Bottom-up data center and gaming application modeling reconciled against top-down stamping and plating capacity tracking forms the analytical core of this study. Primary interviews with connector procurement managers at hyperscale cloud operators, OEM platform engineers at server manufacturers, and plating process specialists at Yangtze River Delta facilities combined with secondary validation from EPA hazardous substance filings, ECHA REACH substance databases, MIIT technical directive publications, and SEC 10-K disclosures from integrated suppliers. Triangulation across these sources calibrated volume estimates against hyperscaler capex disclosure patterns.
Historical trendline analysis of server refresh cycle compression and PCI-E generation transition rates informed projection frameworks across the analysis window. Segmentation dimensions modeled include connector type, application tier, form factor slot count, and end-user procurement authority. CAGRs derived from elasticity-adjusted demand curves incorporating AI accelerator deployment trajectories and regulatory compliance timeline shifts. Industry-specific inputs encompassed thermal cycling qualification data from aerospace-grade process disciplines and liquid crystal polymer material flow certification status.
The model assumes a particular technology adoption path; alternative pathways for optical PCI-E convergence would alter the outlook if 100G+ lane rate deployment accelerates beyond electrical backplane physical limits. Forecasts reflect assumptions regarding hyperscaler procurement calendar synchronization and REACH substance restriction timeline adherence. A model refresh is warranted upon material change in EPA hazardous substance reporting thresholds or MIIT electromagnetic compatibility mandate revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
Global Cables and Connector Market
Connectors
Pin Retainer Market
Connectors
Global Multi Coaxial Connectors Market
Connectors
Power Connector Market
Connectors
LCP Connectors Market
Connectors
Cable Connectors and Adapters Market
Connectors
5G Connector Market
Connectors
Hazardous Location Connectors Market
Connectors
3C Electronics Precision Connectors Market
Connectors
Asia-Pacific Connector Market
Connectors
Connector Adapter Kits Market
Connectors
Circular Waterproof Connector Market
Connectors
Terminal Pins Market
Connectors
Global Automotive Connector Market
Connectors
Mexico Connector Market
Connectors
Magnetic Connector Market