
 Global Hydrolyzed Collagen Market | 2026-2036
Global Hydrolyzed Collagen Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hydrolyzed Collagen Market Foresight
Modular single-serve sachet bundling is pivoting how fitness centers and wellness clinics purchase hydrolyzed collagen, shifting bulk powder buyers toward pre-portioned convenience formats. GELITA AG leverages its multi-continent gelatin extraction infrastructure to sustain supply continuity for pharmaceutical-grade peptide lines. Rousselot anchors European demand through its porcine and bovine-derived collagen specialization. Nitta Gelatin Inc. competes on marine-sourced collagen differentiation for cosmetics manufacturers seeking non-mammalian inputs.
Hydrolyzed collagen comprises enzymatically cleaved collagen peptides with molecular weights typically below 10 kDa, rendering them cold-water soluble and bioavailable for skin matrix support and joint tissue maintenance. Powder formats dominate volume flows into dietary supplements and sports nutrition, while liquid collagen concentrates command premium positioning in functional beverages where rapid absorption claims drive purchase decisions. Capsule and tablet segments occupy stable pharmacy and wellness clinic channels where dosing precision matters more than formulation flexibility.
The FDA's New Dietary Ingredient framework and the EU's EFSA health claims regulation jointly constrain how collagen peptide benefits may be marketed across North American and European jurisdictions. China's SAMR and NMPA enforce GB standards for collagen sourced from domestic and imported raw materials, affecting cross-border ingredient flows. Japan's FOSHU system creates a distinct regulatory pathway for functional food collagen claims that diverges from supplement classification elsewhere. Stakeholders must monitor evolving peptide-specific purity thresholds as regulators tighten contaminant testing protocols without harmonized international standards.
Market Dynamics
Enzymatic hydrolysis technology maturation is compressing peptide molecular weight distribution bands, enabling manufacturers to target specific bioavailability thresholds for nutraceutical and pharmaceutical applications.
Growth Catalysts
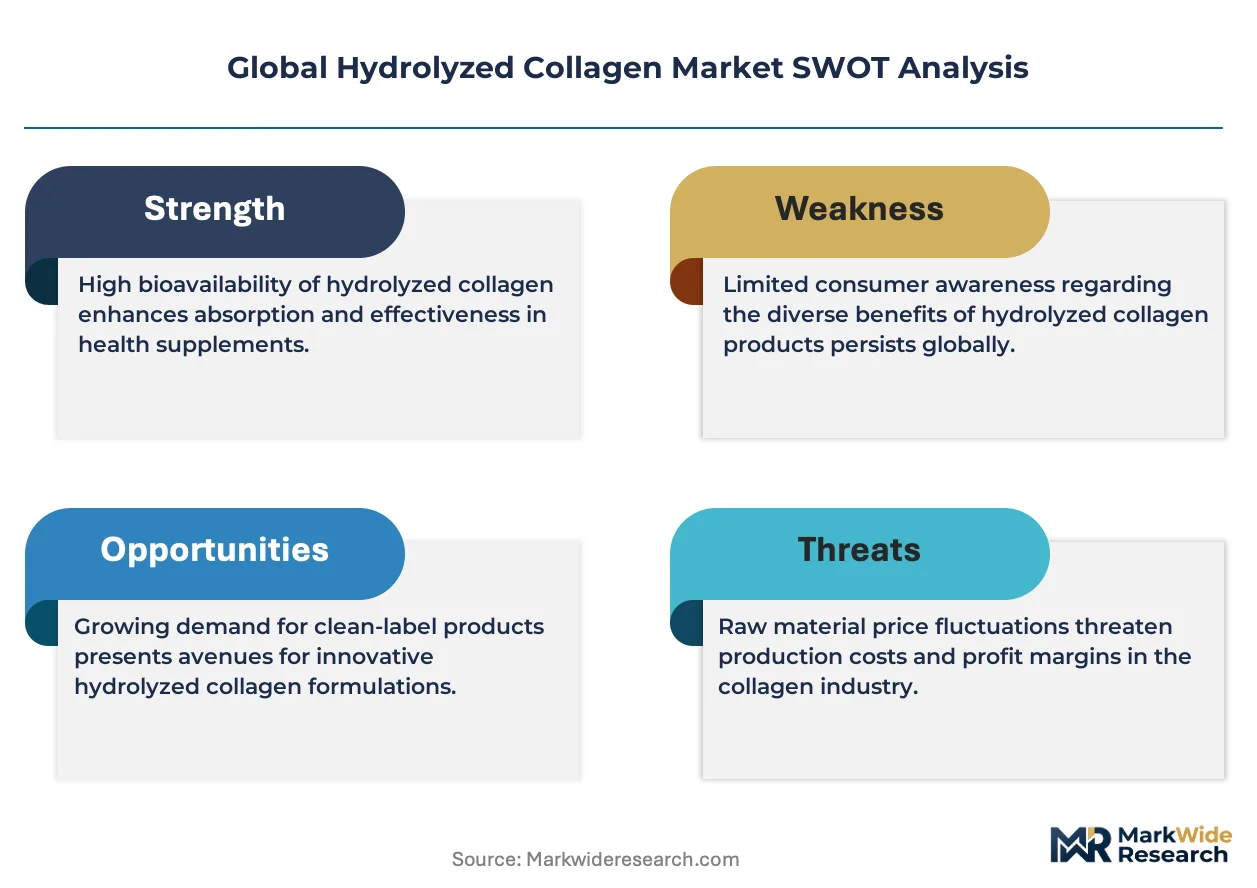
- Japan's FOSHU system:Functional food claims for skin and joint health create a differentiated regulatory pathway that rewards clinical substantiation with premium positioning in convenience store and pharmacy channels.
- Cosmeceutical formulation demand:Marine-sourced collagen peptides from cold-water fish species satisfy clean-label preferences among prestige skincare manufacturers seeking non-mammalian provenance.
- Ready-to-mix sachet bundling:Sports nutrition brands combine hydrolyzed collagen with branched-chain amino acids in single-serve formats, shifting gym and clinic procurement toward pre-portioned convenience.
Market Restraints
- Raw material cost volatility:Bovine hide and porcine skin prices fluctuate with meat processing volumes and rendering industry capacity, squeezing margin stability for mid-tier peptide producers.
- Supply concentration risk:Pharmaceutical-grade collagen peptide extraction capacity clusters in Germany and Brazil, creating geographic vulnerability to energy cost spikes and logistics disruptions.
- Substitution threat from plant proteins:Pea and rice protein isolates with added proline and glycine claim functional parity at lower input costs in mass-market sports nutrition.
Strategic Opportunities
- Underpenetrated Brazilian interior:Wellness clinic chains in Minas Gerais and Rio Grande do Sul lack consistent bulk powder supply, creating first-mover advantage for distributors with cold-chain logistics.
- Regulatory tailwind from China's dual carbon goals:SAMR incentives for low-energy enzymatic processing favor domestic manufacturers investing in membrane filtration over traditional thermal methods.
- Technology convergence of AI-driven peptide sequencing:Machine learning prediction of collagenase cleavage sites accelerates development of bioactive peptide fractions with targeted receptor binding.
Industry Challenges
- Peptide characterization skill scarcity:Analytical chemists with mass spectrometry expertise for molecular weight distribution verification command premium salaries, constraining quality control scaling.
- Certification timeline compression:EFSA health claim substantiation requires 12-18 month clinical study cycles, delaying product launches in European markets.
- Cross-border GB standards compliance:China's NMPA testing protocols for heavy metals and microbiological contaminants vary by province, complicating import documentation for foreign suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hydrolyzed Collagen Market |
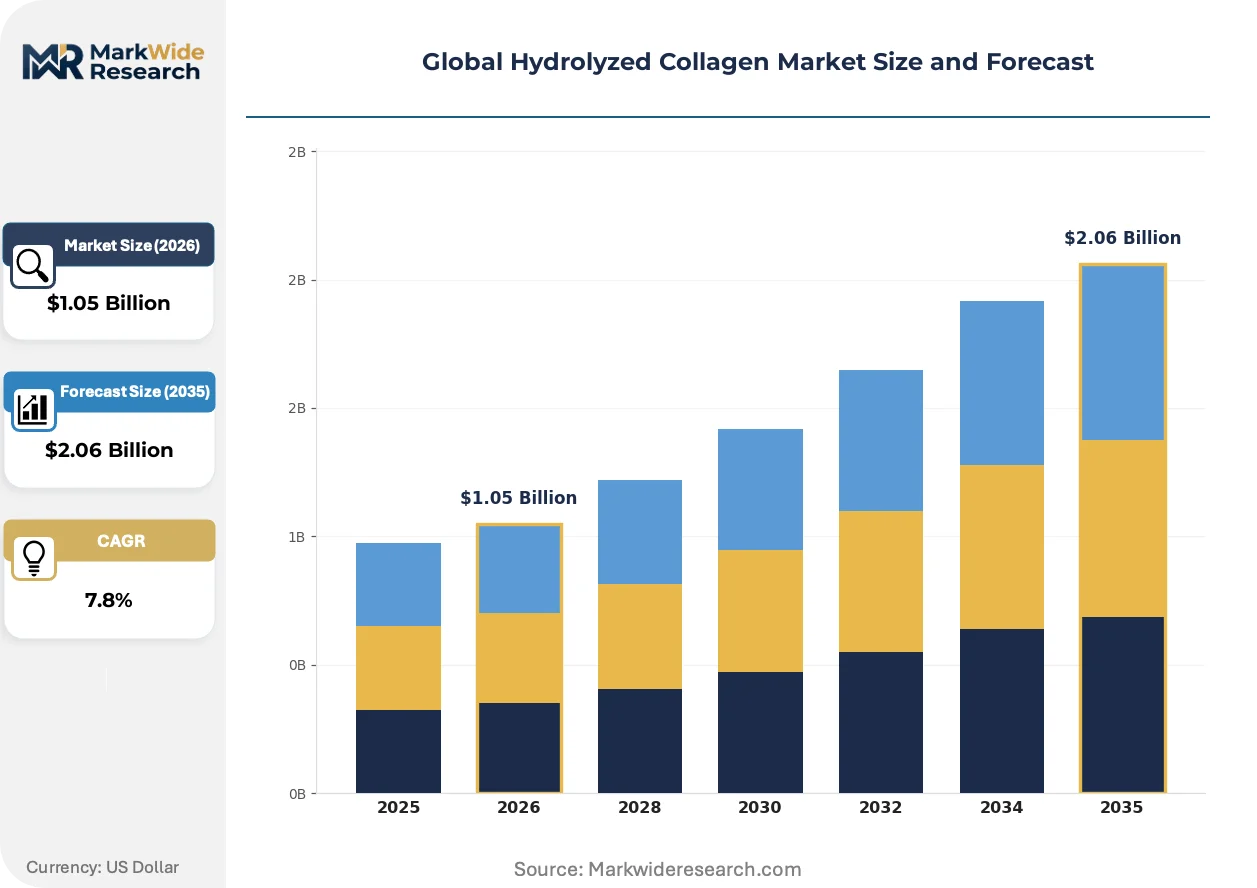
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $2.06 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gelatin, Powder, Capsules, Liquid, Tablets Application: Dietary Supplements, Sports Nutrition, Functional Foods, Cosmetics, Personal Care End User: Nutritionists, Cosmetic Manufacturers, Fitness Centers, Pharmacies, Wellness Clinics Manufacturing Stage: Raw Material Sourcing, Extraction, Purification, Packaging |
| Companies Covered | GELITA AG, Rousselot, Nitta Gelatin Inc., Weishardt, Gelnex, PB Gelatins, Nippi Inc., Collagen Solutions Plc, Amicogen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hydrolyzed Collagen Market Shifts & Advancements
Peptide bioavailability optimization is displacing crude yield metrics as the primary R&D investment criterion, with manufacturers competing on cold-water solubility and specific amino acid ratios rather than bulk tonnage.
Enzyme-directed hydrolysis is converging with precision fermentation for collagen peptide production. Biotech startups in California and the Netherlands deploy engineered yeast strains to express recombinant collagen sequences without animal-derived inputs. Cosmetics formulators in South Korea and France accelerate adoption of these fermentation-derived peptides to circumvent mammalian sourcing restrictions in halal and vegan product lines.
EFSA's tightening evidentiary standards for health claims is compressing marketing flexibility for joint and skin benefit assertions. Collagen peptide suppliers must now commission randomized controlled trials with measurable biomarker endpoints to support label statements. German and Italian brands with established clinical portfolios defend shelf positioning, while newer entrants face 18-24 month substantiation delays before European commercialization.
Clinic-directed personalization is fragmenting bulk procurement patterns. São Paulo wellness chains now specify molecular weight ranges and amino acid profiles per patient protocol, rejecting standardized SKUs. This specification creep forces manufacturers to maintain multiple peptide fractions in inventory, raising working capital requirements while enabling price premiums for certified custom batches in Brazil's affluent urban corridors.
Global Hydrolyzed Collagen Market Segmentation
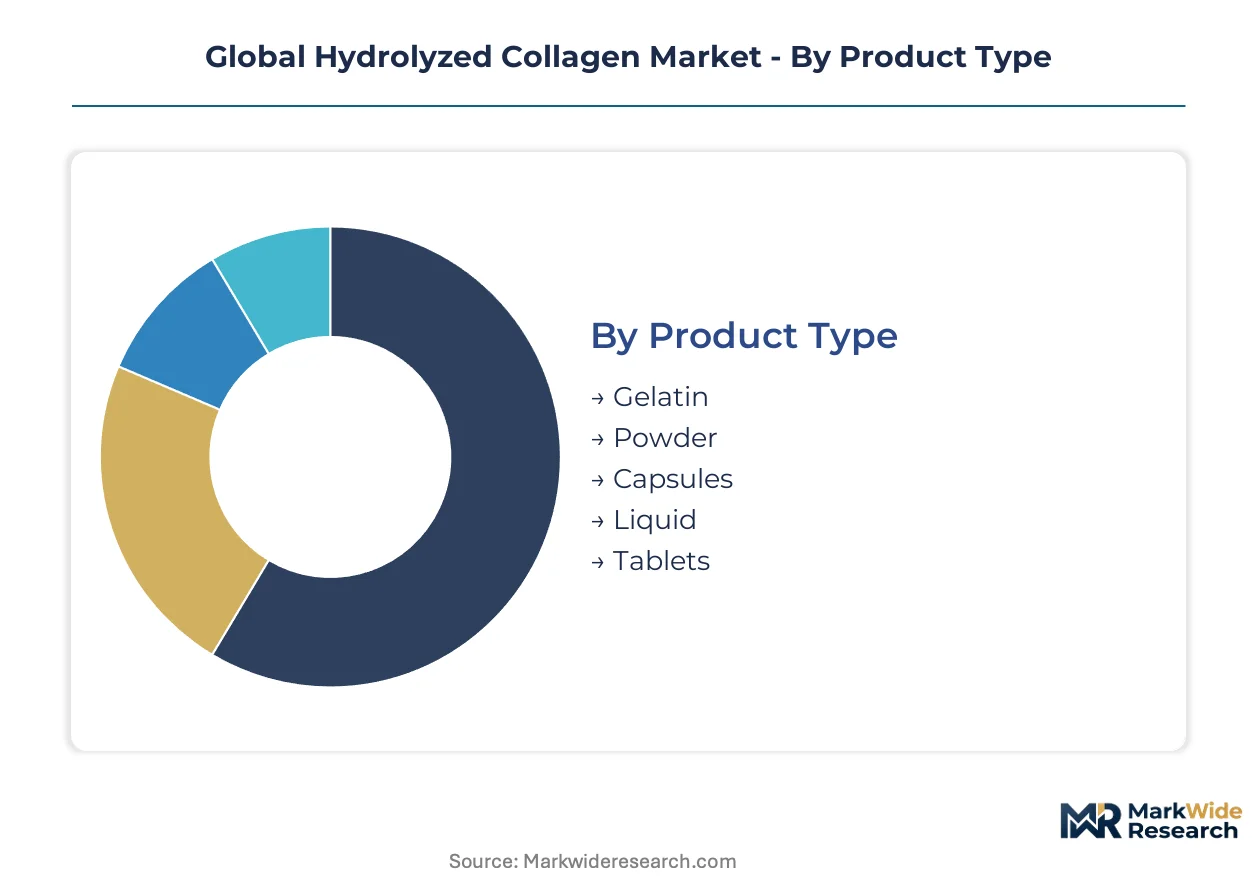
Hydrolyzed collagen manufacturers compete across molecular weight specifications, formulation formats, and channel-specific delivery systems. Segment boundaries blur as sports nutrition brands bundle powder sachets for gym distribution while cosmetics formulators demand marine-derived peptides with non-mammalian certification.
Product Type:
Molecular weight distribution and cold-water solubility specifications differentiate product tiers, with enzymatic hydrolysis depth determining end-use compatibility.
- Powder:Enzymatically cleaved peptides below 10 kDa molecular weight dissolve in ambient water without agitation. Demand concentrates in Brazil's São Paulo wellness clinic chains sourcing bulk powder for customized patient protocols where dosing flexibility outweighs convenience premiums.
- Liquid:Pre-hydrolyzed concentrates with rapid absorption claims command premium positioning in functional beverage channels. South Korean cosmetics manufacturers favor liquid formats for sheet mask infusion where viscosity control and batch consistency reduce formulation complexity.
- Gelatin:Partially hydrolyzed collagen with gelling properties serves food and pharmaceutical capsule applications.
- Capsules:Pre-measured dosing precision targets pharmacy and clinic channels where protocol adherence matters.
- Tablets:Compressed formats with binding agents occupy stable over-the-counter supplement shelves.
Mature deployment sits with powder formats in bulk procurement channels. Newer deployment is concentrated in liquid concentrates for functional beverage premiumization.
Application:
End-use applications diverge on bioavailability claims, regulatory substantiation requirements, and formulation integration complexity.
- Sports Nutrition:Ready-to-mix sachets bundling hydrolyzed collagen with branched-chain amino acids pivot gym and clinic procurement toward pre-portioned convenience. German fitness chains specify molecular weight bands for post-workout recovery positioning.
- Cosmetics:Marine-sourced peptides from cold-water fish species satisfy clean-label preferences among prestige skincare manufacturers in France and South Korea seeking non-mammalian provenance for halal and vegan product lines.
- Dietary Supplements:Capsule and tablet formats dominate pharmacy channel flow with EFSA health claim substantiation requirements.
- Functional Foods:Japan's FOSHU system creates a distinct regulatory pathway for skin and joint health claims in convenience store channels.
- Personal Care:Topical collagen peptides in hair and skin formulations compete with ceramide and hyaluronic acid alternatives.
Volume concentration remains in dietary supplements. Steepest expansion trajectory is appearing in sports nutrition bundling strategies.
End User:
Procurement sophistication varies from bulk powder specification to finished goods retail, with certification requirements scaling accordingly.
- Wellness Clinics:São Paulo clinic chains now reject standardized SKUs in favor of molecular weight ranges and amino acid profiles per patient protocol. This specification creep forces manufacturers to maintain multiple peptide fractions in inventory.
- Cosmetic Manufacturers:South Korean and French formulators accelerate adoption of fermentation-derived peptides to circumvent mammalian sourcing restrictions.
- Nutritionists:Individual practitioners source certified custom batches for client-specific dietary protocols.
- Fitness Centers:Gym chains bundle collagen with protein products for member retail programs.
- Pharmacies:European pharmacy channels enforce EFSA-substantiated health claim documentation for shelf placement.
Established procurement patterns persist in pharmacies. Emerging specification complexity is concentrated in wellness clinic chains.
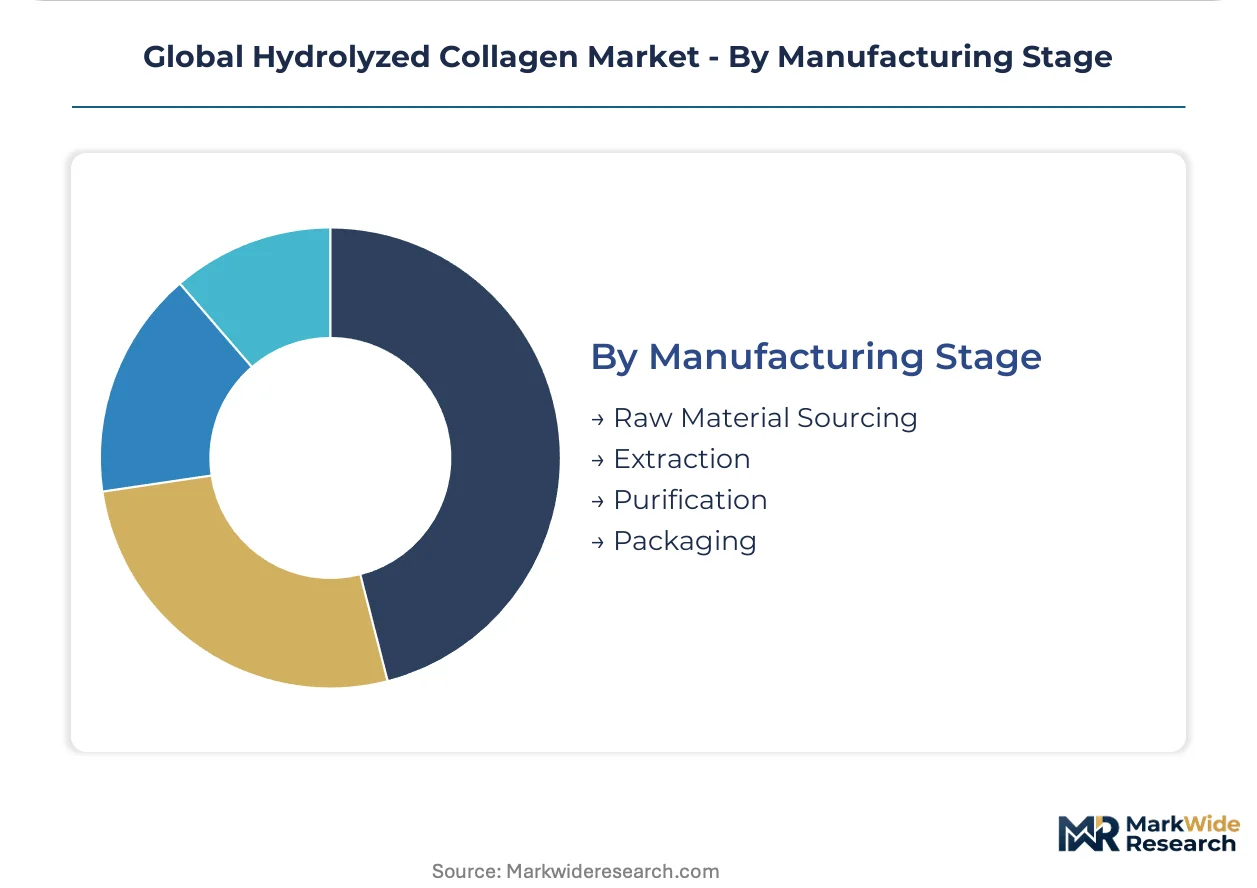
Manufacturing Stage:
Process control points determine peptide bioactivity retention and contaminant compliance across regulatory jurisdictions.
- Extraction:Enzymatic hydrolysis technology maturation compresses peptide molecular weight distribution bands, enabling targeting of specific bioavailability thresholds. China's SAMR incentives for low-energy enzymatic processing favor domestic manufacturers investing in membrane filtration.
- Purification:Mass spectrometry verification of molecular weight distribution commands premium analytical chemist salaries, constraining quality control scaling for mid-tier producers.
- Raw Material Sourcing:Bovine hide and porcine skin prices fluctuate with meat processing volumes and rendering industry capacity.
- Packaging:Single-serve sachet formats require nitrogen flushing and moisture barriers to prevent peptide oxidation.
Capital deployment concentrates in extraction technology. Process innovation is accelerating most quickly in purification analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Germany and Brazil while consumption fragments across clinic chains in São Paulo, sports nutrition channels in the United States, and FOSHU-authorized functional foods in Japan. This geographic split creates logistics complexity for peptide suppliers balancing bulk powder shipments against finished goods distribution.
United States
Sports nutrition brands drive demand for ready-to-mix sachets bundling hydrolyzed collagen with branched-chain amino acids. The FDA's New Dietary Ingredient notification pathway constrains how novel collagen peptides enter commerce, requiring pre-market safety documentation. California biotech startups deploy engineered yeast strains for recombinant collagen production, circumventing mammalian sourcing restrictions.
Germany
Pharmaceutical-grade peptide extraction capacity clusters here, serving European nutraceutical and medical device manufacturers. EFSA health claim substantiation requirements enforce 12-18 month clinical study cycles before skin and joint benefit assertions reach labels. Bavaria hosts analytical chemistry laboratories specializing in mass spectrometry verification for molecular weight distribution compliance.
Brazil
Wellness clinic chains in São Paulo state source bulk powder for customized patient protocols specifying molecular weight ranges and amino acid profiles. ANVISA regulates collagen as a food supplement with distinct purity thresholds from pharmaceutical applications. Minas Gerais and Rio Grande do Sul present underpenetrated interior markets lacking consistent cold-chain logistics for peptide distribution.
Japan
The FOSHU system creates a differentiated regulatory pathway for functional food collagen claims in convenience store and pharmacy channels, rewarding clinical substantiation with premium positioning. METI oversees standards compliance for both domestic production and imported raw materials. Tokyo-based cosmetics formulators accelerate adoption of fermentation-derived peptides for halal and vegan product lines.
China
SAMR and NMPA enforce GB standards for collagen sourced from domestic and imported raw materials, with provincial variation in heavy metals and microbiological contaminant testing protocols. Dual carbon goals incentivize low-energy enzymatic processing and membrane filtration investments over traditional thermal methods. Yangtze River Delta manufacturers supply peptide fractions for cosmetics export to South Korean prestige skincare brands.
Global Hydrolyzed Collagen Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across molecular weight specification tiers and sourcing provenance categories. Market structure tilts toward consolidation at the pharmaceutical-grade extraction level while fragmenting in cosmetic and sports nutrition applications. Three archetypes dominate: multi-continent gelatin extractors with captive peptide lines, marine-sourced collagen differentiation specialists, and regional distributors with clinic-direct customization capabilities. Capacity expansion and enzymatic hydrolysis technology licensing represent the dominant competitive moves.
Within the multi-continent infrastructure tier, GELITA AG anchors supply continuity for pharmaceutical-grade peptide production across multiple regulatory jurisdictions. Rousselot occupies a position exemplifying European porcine and bovine-derived collagen specialization. Nitta Gelatin Inc. represents the marine-sourced differentiation archetype, serving cosmetics manufacturers seeking non-mammalian inputs.
| Leading Market Players |
|---|
| GELITA AG |
| Rousselot |
| Nitta Gelatin Inc. |
| Weishardt |
| Gelnex |
| PB Gelatins |
| Nippi Inc. |
| Collagen Solutions Plc |
| Amicogen |
| Others |
Supply & Pricing Matrix
Family-owned rendering cooperatives in Brazil and Germany anchor upstream bovine hide supply, translating livestock processing cycles directly into peptide input cost volatility and constraining mid-tier producers' margin discipline. Their collective pricing power in raw material procurement forces downstream manufacturers to absorb fluctuations or push premium positioning.
Pricing Analysis
Cost-down pressure on pharmaceutical-grade peptide fractions accelerates because EFSA health claim substantiation timelines stretch working capital requirements. Three-tier pricing structure across premium, standard, and economy levels separates FOSHU-authorized functional food claims from bulk powder clinic procurement. Price differentiation hinges on molecular weight certification and cold-chain logistics integration. Wellness clinic chains in São Paulo exhibit lowest price sensitivity due to protocol customization premiums, while mass-market sports nutrition buyers in the United States drive hardest bargaining on per-kilogram contracts.
Supply Chain Analysis
Dual-sourcing qualification requirements from European cosmetics formulators mandate simultaneous certification of German and Brazilian extraction facilities, compressing supplier onboarding timelines. Supply concentrates in Germany, Brazil, and China, with enzymatic hydrolysis capacity clustering around rendering industry proximity. Raw material flows draw from bovine hide, porcine skin, and cold-water fish species, each tethered to distinct seasonal processing volumes. Single-source vulnerability persists in pharmaceutical-grade membrane filtration equipment. Distribution runs through wellness clinic direct procurement, sports nutrition distributor networks, and cosmetics ingredient broker channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Analytical chemist scarcity constrains quality control scaling, propping pricing for certified custom batches as manufacturers compete for limited mass spectrometry expertise.
For Market Incumbents: Deploy enzymatic hydrolysis technology licensing to capture revenue from mid-tier producers unable to fund in-house R&D. Deepen backward integration into rendering operations in Minas Gerais to secure bovine hide supply continuity against meat processing volume fluctuations. Certification investment in China's GB standards compliance defends position against domestic membrane filtration specialists capturing Yangtze River Delta cosmetics export flows. For New Entrants and Emerging Players: Wellness clinic chains in Rio Grande do Sul represent an underserved buyer archetype lacking consistent cold-chain logistics for peptide distribution. Fermentation-derived recombinant collagen production circumvents mammalian sourcing restrictions that constrain incumbent supply flexibility. Direct-to-clinic specification partnerships bypass established distributor markups in Brazil's interior states. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier peptide producers with stranded inventory in European markets facing EFSA substantiation delays. Long-term viability centers on clinical trial portfolio depth rather than bulk tonnage capacity. Watch for SAMR enforcement actions on GB standard deviations as inflection indicator for Chinese import policy tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Hydrolysis Technology Licensing | Revenue capture from capacity-constrained mid-tier producers accelerates without capital-intensive facility construction. |
| Backward Integration into Rendering Operations | Brazilian bovine hide supply security insulates margin stability against meat processing cyclicality. |
| Fermentation-Derived Recombinant Collagen Scale-Up | California and Netherlands biotech startups circumvent mammalian sourcing restrictions for halal and vegan product lines. |
| EFSA Health Claim Clinical Substantiation | German and Italian brands with established trial portfolios defend European shelf positioning against delayed entrants. |
| Direct-to-Clinic Custom Batch Certification | São Paulo wellness chains specify molecular weight ranges per patient protocol, enabling price premiums. |
Research Methodology
Independent corroboration across peptide manufacturing executives, analytical chemistry laboratory directors, wellness clinic procurement managers, and cosmetics formulator R&D leads underwrites the qualitative findings. Secondary validation draws from FDA New Dietary Ingredient notifications, EFSA health claim submissions, SAMR GB standard filings, and customs trade data on collagen peptide imports. Bottom-up facility capacity assessments and top-down end-use demand modeling complete the triangulation.
Rate-of-change decomposition separates volume growth from pricing dynamics across the analysis window. Segmentation dimensions include molecular weight tier, formulation format, application channel, and regulatory jurisdiction cluster. CAGRs derive from weighted average of historical trajectory and demand elasticity estimates. Industry-specific forecast inputs incorporate enzymatic hydrolysis technology maturation curves and FOSHU authorization timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to peptide characterization skill scarcity and evolving EFSA evidentiary standards. Deviation in China's provincial GB testing protocol harmonization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
GCC Specialty Chemicals Market
Specialty Compounds
North America Polyphenylene Sulfide Compounds Market
Specialty Compounds
Thionyl Chloride Market
Specialty Compounds
Hydrotalcite Market
Specialty Compounds
Global Heat Stabilizers Market
Specialty Compounds
Global Sulfur Hexafluoride Market
Specialty Compounds
Thermoset Molding Compounds Market
Specialty Compounds
3-Hydroxyphenyl Phosphinyl Propanoic Acid Market
Specialty Compounds
Gulf Collagen Market
Specialty Compounds
Specialty Sorbents Market
Specialty Compounds
Methyl Anthranilate Market
Specialty Compounds
Thiocolchicoside Market
Specialty Compounds
Global Polymer Clay Market
Specialty Compounds
Collagen Hydrolysates Market
Specialty Compounds
Quinoline Yellow WS Market
Specialty Compounds
Opacifiers Market