
 Rigid Polyurethane Foams Market | 2026-2036
Rigid Polyurethane Foams Market Size, Share, and Industry Trends Forecast 2026-2036
Rigid Polyurethane Foams Market Analysis
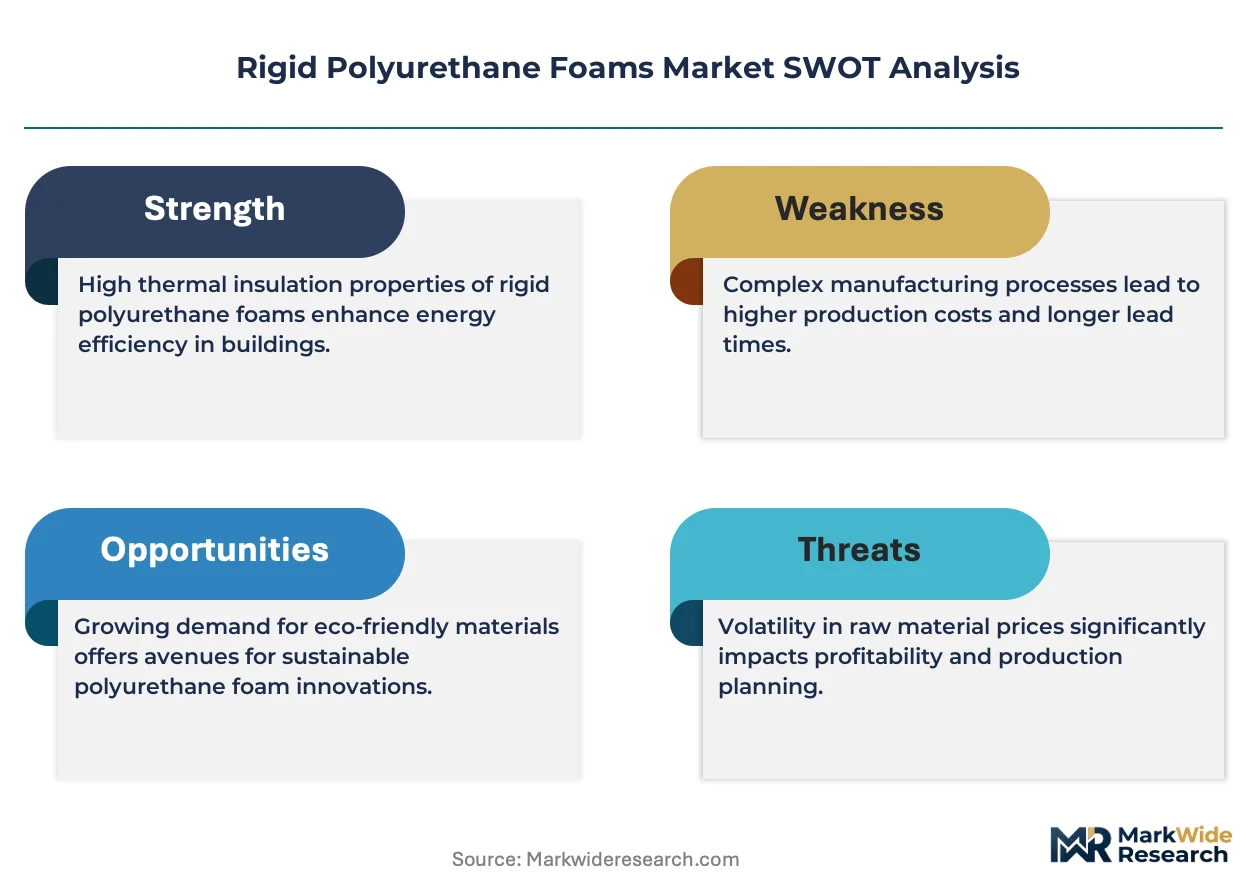
Commercial cold chain operators is bifurcating demand away from traditional construction buyers as perishable logistics networks expand refrigerated warehouse capacity across Asia-Pacific and North America. BASF SE leverages its integrated polyol and isocyanate supply chain to secure feedstock cost advantages in European and Chinese production hubs. Covestro AG anchors its position through proprietary CO2-based polyol technology that reduces reliance on petroleum-derived feedstocks. Dow Inc. competes on manufacturing scale, operating multiple world-scale plants that serve both appliance OEMs and spray foam contractors with tailored formulation grades.
Rigid polyurethane foam comprises a thermoset polymer system formed by reacting polyols with polymeric methylene diphenyl diisocyanate, typically achieving closed-cell densities of 32-48 kg/m³ and thermal conductivity values below 0.024 W/m·K, which makes it the dominant insulation material for refrigerated transport containers and building envelopes. Structural foam commands premium positioning in composite panel applications where load-bearing capacity must coexist with thermal performance, while spray foaming technology leads installation growth in retrofit markets due to its ability to conform to irregular substrates and eliminate thermal bridging. High-density foam occupies a specialized niche in industrial pipe insulation where compressive strength requirements exceed 200 kPa.
EPA Significant New Alternatives Policy program and EU F-Gas Regulation are jointly accelerating the commercialization of hydrofluoroolefin and hydrocarbon blowing agent formulations, forcing reformulation investments across all major producers. REACH compliance in Europe and evolving GB standards in China are raising the regulatory threshold for flame-retardant additive packages, particularly in high-rise building applications where smoke toxicity standards are tightening. Stakeholders must monitor the pace of Kigali Amendment implementation across emerging economies, as delayed adoption in major construction markets would prolong demand for legacy formulations and create stranded technology risk for early movers in next-generation chemistry.
Market Dynamics
The Kigali Amendment's hydrofluorocarbon phase-down is decomposing legacy formulation economics, forcing producers to rebuild supply chains around hydrofluoroolefin and hydrocarbon blowing agents while appliance OEMs and cold chain operators simultaneously tighten thermal performance specifications.
Growth Catalysts
- EU F-Gas Regulation:The 2024 quota reductions on high-global-warming-potential blowing agents are accelerating reformulation investments across European panel manufacturers, creating first-mover advantages for producers with commercialized low-GWP chemistry.
- Cold chain infrastructure buildout:Perishable logistics networks in Vietnam, Indonesia, and Thailand are expanding refrigerated warehouse capacity, concentrating procurement of high-performance insulation panels in Southeast Asian manufacturing hubs.
- CO2-based polyol technology:Proprietary catalyst systems that incorporate recycled carbon dioxide into polyol backbones are reducing petroleum feedstock exposure while meeting appliance OEM cost targets for energy-efficient refrigerator cabinets.
Market Restraints
- MDI supply concentration:Polymeric methylene diphenyl diisocyanate production clusters in China, Germany, and the United States, exposing foam manufacturers to feedstock price volatility when regional crackers undergo maintenance turnarounds.
- Technical limitation in spray foam retrofit:Hydrocarbon-blown formulations exhibit higher flammability characteristics than legacy HFC systems, restricting their deployment in high-rise building envelopes where ASTM E84 Class A ratings remain mandatory.
- Substitution threat from vacuum insulation panels:VIP technology achieves thermal conductivity below 0.007 W/m·K, capturing premium appliance segments where cabinet thickness constraints override material cost considerations.
Strategic Opportunities
- Underpenetrated Indian cold chain:India's food processing sector operates only 8,000 refrigerated transport vehicles against estimated demand for 50,000 units, creating white space for high-performance container insulation as FSSAI traceability mandates expand.
- Regulatory tailwind from China's dual carbon goals:Provincial building retrofit programs in Jiangsu and Zhejiang are subsidizing substitution of expanded polystyrene with polyurethane panels in existing commercial envelopes.
- Technology convergence of digital twin and foam dispensing:Real-time viscosity monitoring integrated with robotic spray application is enabling outcome-based installation contracts that guarantee thermal performance rather than material volume.
Industry Challenges
- Formulation chemistry skill gap:The transition from HFC to hydrofluoroolefin and hydrocarbon systems requires expertise in flammability suppression and cell structure optimization that exceeds the capabilities of legacy technical service teams.
- Certification timeline compression:REACH registration updates for novel flame-retardant additive packages extend 18-24 months, delaying commercialization of building-code-compliant formulations in European high-rise applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rigid Polyurethane Foams Market |
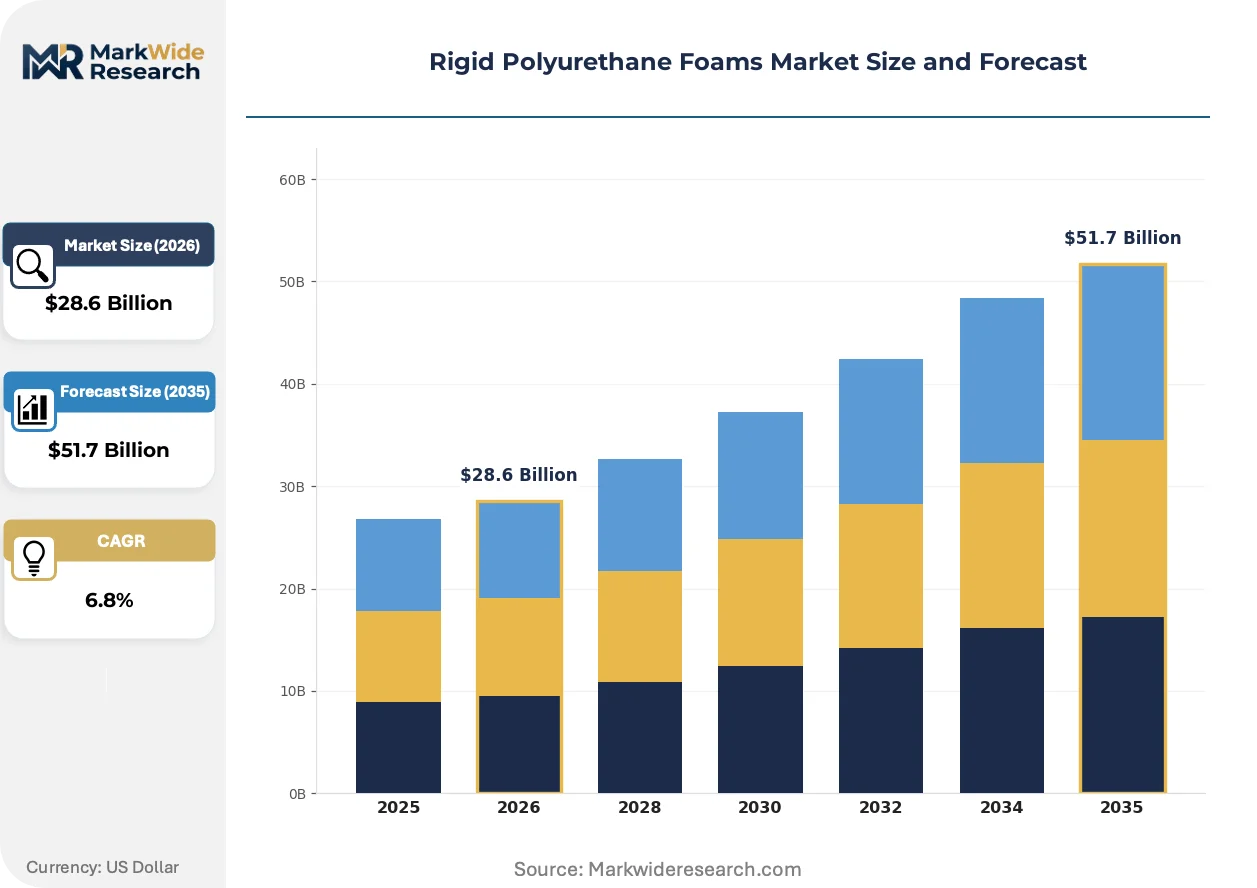
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Foam, Structural Foam, Integral Skin Foam, High-Density Foam End User: Construction, Automotive, Appliances, Furniture Application: Insulation, Soundproofing, Packaging, Cushioning Technology: Spray Foaming, Pour Foaming, Trim Method, Injection Foaming |
| Companies Covered | BASF SE, Covestro AG, Dow Inc., Huntsman Corporation, Recticel NV/SA, Armacell International S.A., Sekisui Chemical Co., Ltd., INOAC Corporation, Carpenter Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rigid Polyurethane Foams Market Emerging Trajectories
Formulation chemistry, regulatory compliance architecture, and procurement specifications are simultaneously pivoting, compressing the window for competitive differentiation from years to quarters.
Water-blown foam systems incorporating catalyzed CO2 generation are decomposing the cost premium associated with petroleum-derived blowing agents. Refrigerator manufacturers in Turkey and Mexico are adopting these formulations at scale for export-oriented production. The structural consequence is margin compression for producers without integrated polyol capabilities or proprietary catalyst intellectual property.
EPA Significant New Alternatives Policy program approvals for next-generation hydrofluoroolefin blends are redirecting capital toward compliant formulation assets. The industrial consequence is stranded technology risk for plants configured solely for HFC-245fa chemistry. Appliance OEMs serving California and New York markets are now specifying SNAP-listed formulations exclusively, forcing supply base rationalization.
Buyers are consolidating panel procurement through integrated cold chain developers rather than fragmented general contractors. This channel compression eliminates distributor markups but demands direct technical service relationships with foam producers capable of customizing formulations for specific climate zones. The shift is most visible in Southeast Asian logistics corridors where Japanese trading houses are vertically integrating warehouse development with long-term insulation supply agreements.
Rigid Polyurethane Foams Market Segmentation
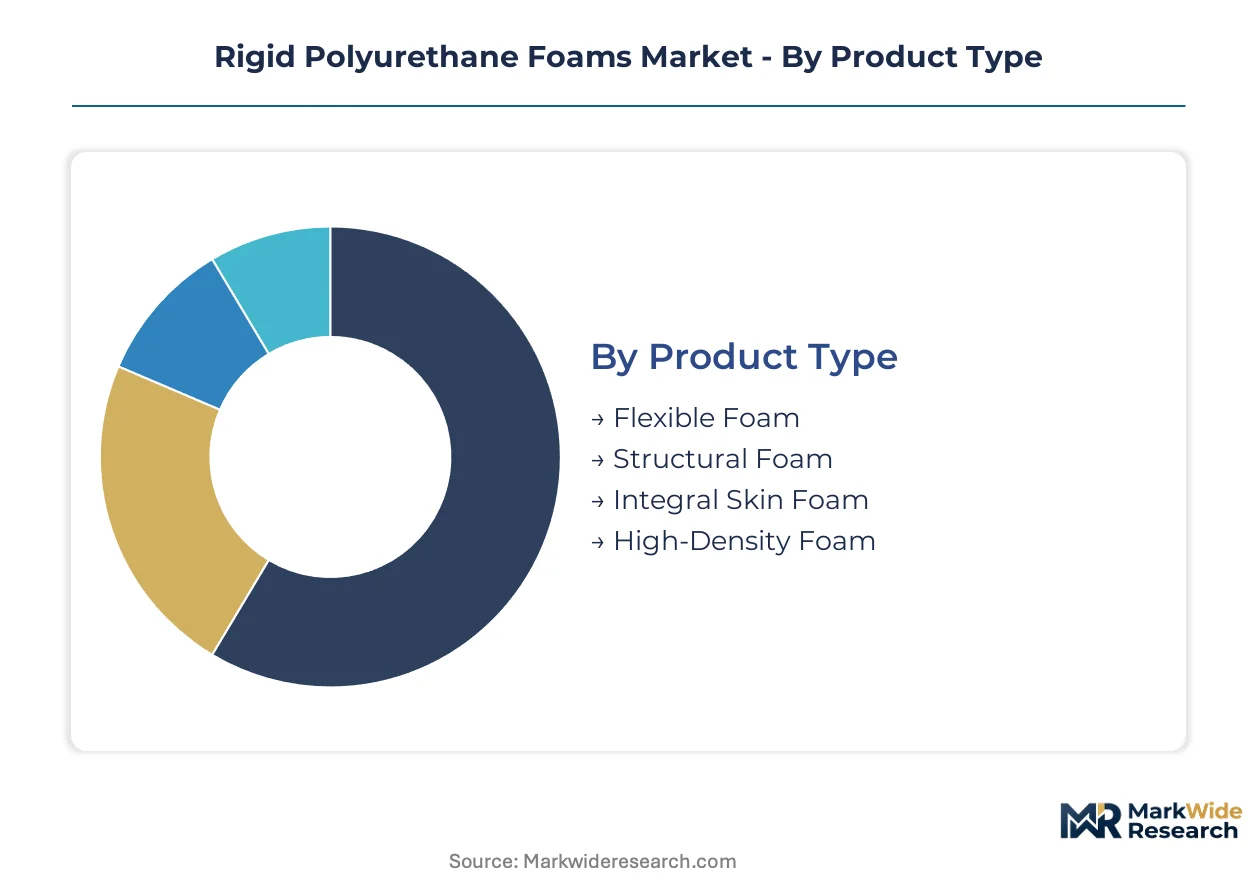
Segmentation in rigid polyurethane foams separates commodity insulation from engineered solutions where thermal conductivity specifications and fire performance ratings command price premiums. Procurement patterns diverge sharply between construction specifiers who prioritize compressive strength and appliance OEMs who optimize for thin-wall molding cycles.
Product Type:
Margin pools concentrate in structural and high-density grades where load-bearing requirements eliminate commodity substitution, while flexible foam competes on volume throughput with thinner conversion economics.
- Flexible Foam:Open-cell polyurethane with density ranges of 16-32 kg/m³ dominates furniture cushioning and mattress cores. Turkish and Mexican manufacturers are adopting water-blown formulations at scale for export-oriented bedding production, compressing margins for producers without integrated polyol capabilities.
- Structural Foam:Rigid closed-cell systems achieving 80-200 kg/m³ densities with fiber-reinforced skins command premium positioning in composite panels for refrigerated transport containers. Cold chain operators in Vietnam and Thailand are specifying these grades for warehouse rack-load compatibility where thermal performance must coexist with mechanical strength.
- Integral Skin Foam:Self-skinning polyurethane with density gradients from 200-800 kg/m³ serves automotive steering wheels and appliance handles where surface aesthetics eliminate secondary finishing operations.
- High-Density Foam:Specialized grades exceeding 250 kg/m³ and compressive strengths above 200 kPa occupy industrial pipe insulation niches where ASTM E84 Class A ratings remain mandatory despite hydrocarbon blowing agent flammability challenges.
Structural foam holds installed capacity in European and Chinese panel manufacturing hubs. High-density foam is rotating up the share rankings as energy infrastructure retrofit programs accelerate.
End User:
Volume concentration sits with construction and appliances, though automotive specifications are tightening thermal conductivity targets for electric vehicle battery enclosures.
- Construction:Building envelope applications specify spray foam for retrofit markets and preformed panels for new commercial construction. China's provincial retrofit programs in Jiangsu and Zhejiang are subsidizing polyurethane substitution for expanded polystyrene in existing commercial envelopes.
- Appliances:Refrigerator cabinet and freezer insulation demands thin-wall molding with thermal conductivity below 0.020 W/m·K. Appliance OEMs serving California and New York markets now specify SNAP-listed hydrofluoroolefin formulations exclusively, forcing supply base rationalization.
- Automotive:NVH applications and lightweight structural cores are expanding into battery pack thermal management where compression set resistance at elevated temperatures determines specification compliance.
- Furniture:Mattress and seating applications compete on comfort density indexing against latex and memory foam alternatives, with limited pricing power in mass-market retail channels.
Construction maintains the largest installed demand base. Automotive is climbing the fastest as electrification reshapes thermal management material specifications.
Application:
Insulation generates the highest value per kilogram where building code compliance and energy efficiency mandates create specification stickiness.
- Insulation:Closed-cell rigid foam dominates refrigerated transport containers and building envelopes with thermal conductivity values below 0.024 W/m·K. India's food processing sector operates only 8,000 refrigerated transport vehicles against estimated demand for 50,000 units, creating white space for high-performance container insulation as FSSAI traceability mandates expand.
- Soundproofing:Open-cell flexible foam serves architectural acoustics and automotive NVH where absorption coefficients at mid-frequency ranges determine specification.
- Packaging:Molded foam inserts for electronics and medical devices compete against expanded polystyrene on cushioning efficiency per unit cost.
- Cushioning:Furniture and bedding applications prioritize indentation force deflection curves and durability testing under ASTM D3574 protocols.
Insulation holds the deepest installed specification base across building codes and transport regulations. Soundproofing is gaining share fastest in urban high-rise construction where IBC acoustic rating requirements are tightening.
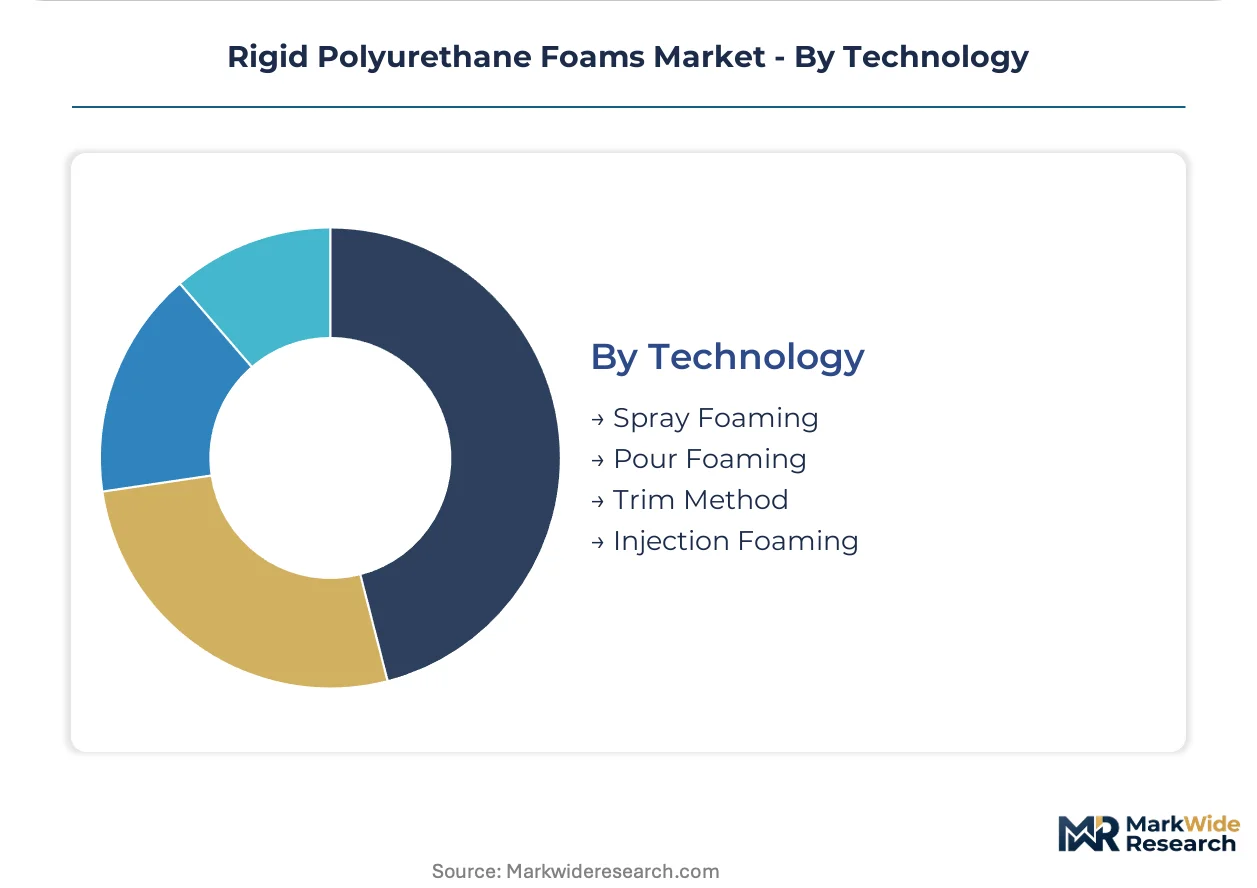
Technology:
Process selection determines labor content and material yield, with spray foaming capturing retrofit growth and injection foaming dominating OEM appliance production.
- Spray Foaming:On-site application technology eliminates thermal bridging by conforming to irregular substrates. Robotic spray application with real-time viscosity monitoring is enabling outcome-based installation contracts that guarantee thermal performance rather than material volume.
- Pour Foaming:Open-mold casting serves architectural decorative elements and limited-series automotive components where tooling investment must stay minimal.
- Trim Method:Block cutting from continuously produced buns yields standardized dimensions for furniture and packaging applications with high volume throughput.
- Injection Foaming:High-pressure impingement mixing dominates appliance cabinet production where cycle times under 120 seconds and dimensional tolerances of ±0.5 mm are mandatory.
Spray foaming holds the broadest contractor-installed base. Injection foaming is expanding most quickly as appliance OEMs consolidate supply agreements with technology-integrated foam producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MDI and polyol production clusters concentrate in China, Germany, and the United States, exposing foam manufacturers to feedstock price volatility when regional crackers undergo maintenance turnarounds. Cold chain infrastructure buildouts and building retrofit mandates are redirecting demand toward high-performance insulation specifications across divergent regulatory timelines.
China
Provincial building retrofit programs in Jiangsu and Zhejiang subsidize polyurethane panel substitution for expanded polystyrene in existing commercial envelopes. GB standards for appliance energy efficiency tighten thermal conductivity specifications for refrigerator cabinet insulation. State-led construction in Chengdu and Xi'an concentrates procurement of spray foam systems for cold storage facilities serving domestic food e-commerce networks.
Germany
The 2024 EU F-Gas Regulation quota reductions on high-GWP blowing agents accelerate reformulation investments across European panel manufacturers. REACH compliance updates for flame-retardant additive packages extend certification timelines for high-rise building applications. Industrial clusters in North Rhine-Westphalia and Bavaria anchor production of CO2-based polyol systems that reduce petroleum feedstock exposure.
United States
EPA SNAP program approvals for hydrofluoroolefin blends redirect capital toward compliant formulation assets serving California and New York markets. Appliance OEMs in these states now specify SNAP-listed formulations exclusively, forcing supply base rationalization. Manufacturing concentration along the Gulf Coast exposes foam producers to MDI feedstock disruptions when regional petrochemical complexes schedule turnarounds.
India
FSSAI traceability mandates expand procurement of refrigerated transport container insulation as the food processing sector operates only 8,000 vehicles against estimated demand for 50,000 units. BIS certification requirements for building materials raise technical barriers for imported panel systems. Cold chain development in Maharashtra and Gujarat concentrates warehouse construction activity where state-level warehousing incentives attract integrated logistics developers.
Vietnam
Perishable logistics networks expand refrigerated warehouse capacity across Ho Chi Minh City and Hanoi logistics corridors, concentrating procurement of structural foam panels. Japanese trading houses vertically integrate warehouse development with long-term insulation supply agreements in these markets. The country's national construction regulator tightens fire performance standards for high-rise building envelopes where hydrocarbon-blown formulations face deployment restrictions.
Rigid Polyurethane Foams Market Vendor Landscape
Concentration sits with integrated chemical conglomerates that control polyol and isocyanate supply chains across multiple continental production hubs. Three archetypes define competitive positioning: petrochemical majors with backward integration into MDI feedstocks, specialty foam fabricators with proprietary catalyst intellectual property, and regional panel manufacturers with direct technical service relationships to cold chain developers. Dominant competitive moves include capacity expansion in Southeast Asian manufacturing hubs and technology licensing agreements for low-GWP blowing agent formulations.
Within the integrated chemical tier, BASF SE and Covestro AG exemplify archetypes that leverage captive polyol production to secure feedstock cost advantages in European and Chinese markets. Dow Inc. occupies a position among scale-driven producers operating multiple world-scale plants. Among Asia-Pacific specialists, Sekisui Chemical Co., Ltd. and INOAC Corporation represent fabricators with established technical service networks for appliance OEMs and spray foam contractors. These named entities anchor competitive dynamics without exhausting the full vendor landscape.
| Leading Market Players |
|---|
| BASF SE |
| Covestro AG |
| Dow Inc. |
| Huntsman Corporation |
| Recticel NV/SA |
| Armacell International S.A. |
| Sekisui Chemical Co., Ltd. |
| INOAC Corporation |
| Carpenter Co. |
| Others |
Supply Flow & Price Mechanics
Ninety-day inventory cycles for polymeric methylene diphenyl diisocyanate expose foam manufacturers to feedstock price spikes when crackers in China, Germany, or the United States undergo unplanned turnarounds. This lead-time vulnerability concentrates pricing power with integrated producers who maintain captive MDI supply, while forcing non-integrated fabricators to absorb margin compression or pass through volatile input costs to cold chain operators and appliance OEMs.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure across European panel manufacturing, separating SNAP-listed hydrofluoroolefin formulations at premium levels from legacy hydrofluorocarbon grades facing quota constraints. Certification grade and volume scale drive price differentiation, with REACH-compliant flame-retardant packages commanding substantial markups in high-rise applications. Cost compression in standard insulation tiers is intensifying because water-blown CO2 systems are decomposing petroleum-derived blowing agent premiums. Appliance OEMs serving California and New York markets exhibit the least price sensitivity due to regulatory mandates, while Southeast Asian warehouse developers remain highly price-sensitive and consolidate procurement through long-term supply agreements.
Supply Chain Analysis
Strategic stockpile preferences dominate MDI procurement, with major foam producers maintaining 60-90 day safety stocks against feedstock disruption. Manufacturing concentrates in China, Germany, and the United States, where integrated petrochemical complexes anchor polyol and isocyanate output. Raw material dependencies rest on petroleum-derived feedstocks, recycled CO2 streams for proprietary polyol systems, and hydrofluoroolefin blowing agents subject to regulatory allocation. Single-source vulnerability from concentrated MDI crackers in the Gulf Coast and North Rhine-Westphalia exposes downstream foam plants to unplanned outage risk. Distribution runs through direct technical service relationships with cold chain developers, bypassing fragmented general contractor channels in Southeast Asian logistics corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vacuum insulation panels threaten premium appliance segments where thermal conductivity below 0.007 W/m·K overrides material cost considerations, forcing rigid polyurethane foam incumbents to defend specification stickiness through regulatory compliance and installation ecosystem control.
For Market Incumbents: Shield market position by deepening backward integration into CO2-based polyol production to neutralize petroleum feedstock volatility, while accelerating REACH certification for novel flame-retardant additive packages before EU F-Gas Regulation quotas fully constrain high-GWP formulation alternatives. Channel control through direct technical service relationships with integrated cold chain developers eliminates distributor markups and locks out commodity substitution. For New Entrants and Emerging Players: Anchor in India's underpenetrated refrigerated transport sector, where FSSAI traceability mandates against only 8,000 operational vehicles against 50,000-unit demand create procurement white space for high-performance container insulation. Target Maharashtra and Gujarat warehouse construction clusters where state-level warehousing incentives attract integrated logistics developers seeking long-term insulation supply agreements rather than spot procurement. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory compliance play because Kigali Amendment implementation timelines across emerging economies will determine stranded technology risk for early movers in low-GWP chemistry. Acquisition candidates should exhibit proprietary catalyst intellectual property for hydrofluoroolefin formulations and established appliance OEM supply relationships in California and New York markets. The signal to watch is BIS certification timeline compression in India, which would accelerate import substitution and favor domestic panel manufacturing capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into CO2-Based Polyol Production | Covestro AG's proprietary catalyst systems reduce petroleum feedstock exposure while meeting appliance OEM cost targets. |
| REACH Certification for Flame-Retardant Additives | Eighteen-month registration timelines for high-rise building applications delay commercialization of compliant formulations. |
| Direct Technical Service Relationships with Cold Chain Developers | Japanese trading houses in Vietnam and Thailand bypass distributor markups through vertical integration of warehouse development. |
| Long-Term Supply Agreements with Appliance OEMs | California and New York markets now specify SNAP-listed hydrofluoroolefin formulations exclusively, forcing supply base consolidation. |
| Capacity Expansion in Southeast Asian Manufacturing Hubs | Ho Chi Minh City and Hanoi logistics corridors concentrate procurement of structural foam panels for refrigerated warehouse buildout. |
Methodological Framework
Cross-validation between primary interviews with plant managers at European and Chinese panel manufacturers and secondary validation through customs data and SEC filings anchors the qualitative findings on formulation chemistry transitions. Technical R&D directors at major polyol producers, procurement leads at appliance OEMs, distribution channel partners in Southeast Asian logistics corridors, and cold chain operators in India and Vietnam provided operational perspectives. Bottom-up demand modeling triangulates against top-down regulatory impact assessments across EU F-Gas Regulation, EPA SNAP program, and China's GB standards evolution.
Sensitivity analysis on hydrofluoroolefin blowing agent adoption rates and Kigali Amendment implementation timelines frames the projection envelope across the analysis window. Segmentation dimensions include product grade tier, end-use industry concentration, regional production hub configuration, and blowing agent chemistry class. CAGRs derive from installed capacity utilization rates, substitution elasticities against vacuum insulation panels, and regulatory compliance cost pass-through coefficients. Modeled inputs incorporate MDI feedstock price volatility bands and REACH certification timeline distributions.
Material uncertainties — delayed Kigali Amendment adoption in major construction markets, unplanned MDI cracker outages, and vacuum insulation panel cost curves — sit outside the modeled envelope. Forecasts reflect assumptions on regulatory enforcement consistency and cold chain infrastructure investment commitments. Revision becomes warranted when hydrocarbon-blown formulation flammability restrictions expand beyond high-rise applications or when BIS certification timelines compress India's import substitution trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Advanced Green Septa Market
Specialty Materials
Battery Separator Films Market
Specialty Materials
Medical Grade Silicone Market
Specialty Materials
Acrylic Fine Particle Market
Specialty Materials
Electrode Paste Market
Specialty Materials
Semiconductor O-Rings Market
Specialty Materials
Global PE Films Market
Specialty Materials
Engineered Foam Market
Specialty Materials
Global Conductive Silicone Market
Specialty Materials
Vegan Wax Market
Specialty Materials
Dura Substitute Market
Specialty Materials
Ballistic Protection Materials Market
Specialty Materials
Recyclable Thermosets Market
Specialty Materials
Nanocapsules Market
Specialty Materials
Global Supplementary Cementitious Materials Market
Specialty Materials
Global Synthetic Zeolite Market