
 China Collagen Market | 2026-2036
China Collagen Market Size, Share, and Industry Trends Forecast 2026-2036
China Collagen Market Analysis
Chinese gelatin and peptide producers is restructuring capacity around higher-grade extraction to serve pharmaceutical and nutraceutical buyers. Xiamen Huaxuan Gelatin Co., Ltd. leverages bovine sourcing scale to anchor supply contracts with domestic capsule manufacturers. Glory (Wuxi) Nutrition Technology Co., Ltd. specializes in hydrolyzed collagen for functional beverage brands. YASIN competes through marine-derived peptide lines targeting cosmetics formulators.
Collagen comprises triple-helix protein structures extracted through acid or enzymatic hydrolysis of animal connective tissues, yielding molecular weights from 300 kDa native forms down to 2-5 kDa bioactive peptides for enhanced absorption. Its primary purpose spans edible gelling, skin-barrier repair matrices, and joint-support supplements. Hydrolyzed collagen and collagen peptides command premium positioning in nutritional supplements as consumers prioritize bioavailability claims. Gelatin retains volume dominance in food and beverage applications where cost-sensitive gelling function matters more than molecular specificity. Marine and bovine sources split the high-purity segment, with marine collagen occupying cosmetics-grade supply chains due to lower immunogenicity profiles.
NMPA registration requirements for collagen-based medical devices and SAMR food-ingredient standards are elevating documentation burdens for new market entrants. GB standards for heavy-metal limits and microbiological purity directly shape extraction technology investments across Shandong and Zhejiang production bases. Stakeholders must monitor how China's dual carbon goals reshape rendering and wastewater compliance costs for animal-derived protein processors.
Market Dynamics
NMPA ingredient registration rules are tightening purity requirements for collagen-based medical devices and food additives, forcing producers to restructure extraction capacity around pharmaceutical-grade standards. This regulatory compression is reshaping competitive positioning across Shandong and Zhejiang production bases.
Growth Catalysts
- NMPA Medical Device Registration:Stricter documentation requirements for collagen-based wound dressings and implants are filtering out low-purity suppliers and consolidating demand around certified producers.
- Nutraceutical Formulation:Functional beverage brands in Shanghai and Guangzhou are expanding hydrolyzed collagen portfolios to capture wellness-oriented consumers seeking bioavailable protein.
- Marine Peptide Technology:Enzymatic hydrolysis of fish-scale collagen is penetrating cosmetics-grade supply chains due to lower immunogenicity profiles preferred by premium skincare formulators.
Market Restraints
- Bovine Raw Material Volatility:Rendering capacity constraints and livestock cycle fluctuations in North China are creating input cost instability for gelatin and peptide producers.
- Coastal Manufacturing Concentration:Over 70% of pharmaceutical-grade extraction capacity clusters around Shanghai and Guangzhou, exposing supply chains to regional logistics disruptions.
- Plant-Based Substitution:Fermented microbial collagen alternatives are capturing share in vegan-certified cosmetics applications where animal-derived proteins face formulation restrictions.
Strategic Opportunities
- Inland Province Penetration:Sichuan and Hubei markets remain underdeveloped for collagen-fortified nutritional supplements, presenting first-mover expansion potential for direct-to-consumer brands.
- Dual Carbon Policy Tailwinds:SAMR green manufacturing incentives are rewarding producers who deploy closed-loop wastewater systems and renewable energy in extraction facilities.
- Cross-Sector Convergence:Integration of collagen matrices with 3D bioprinting platforms is opening tissue-engineering applications beyond traditional medical device categories.
Industry Challenges
- Pharmaceutical-Grade Certification Timelines:NMPA medical device registration cycles now exceed 18 months for novel collagen formulations, compressing product launch windows.
- Legacy Equipment Retrofit Costs:GB standards for heavy-metal limits are forcing acid-extraction facilities to replace corrosion-resistant processing lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Collagen Market |
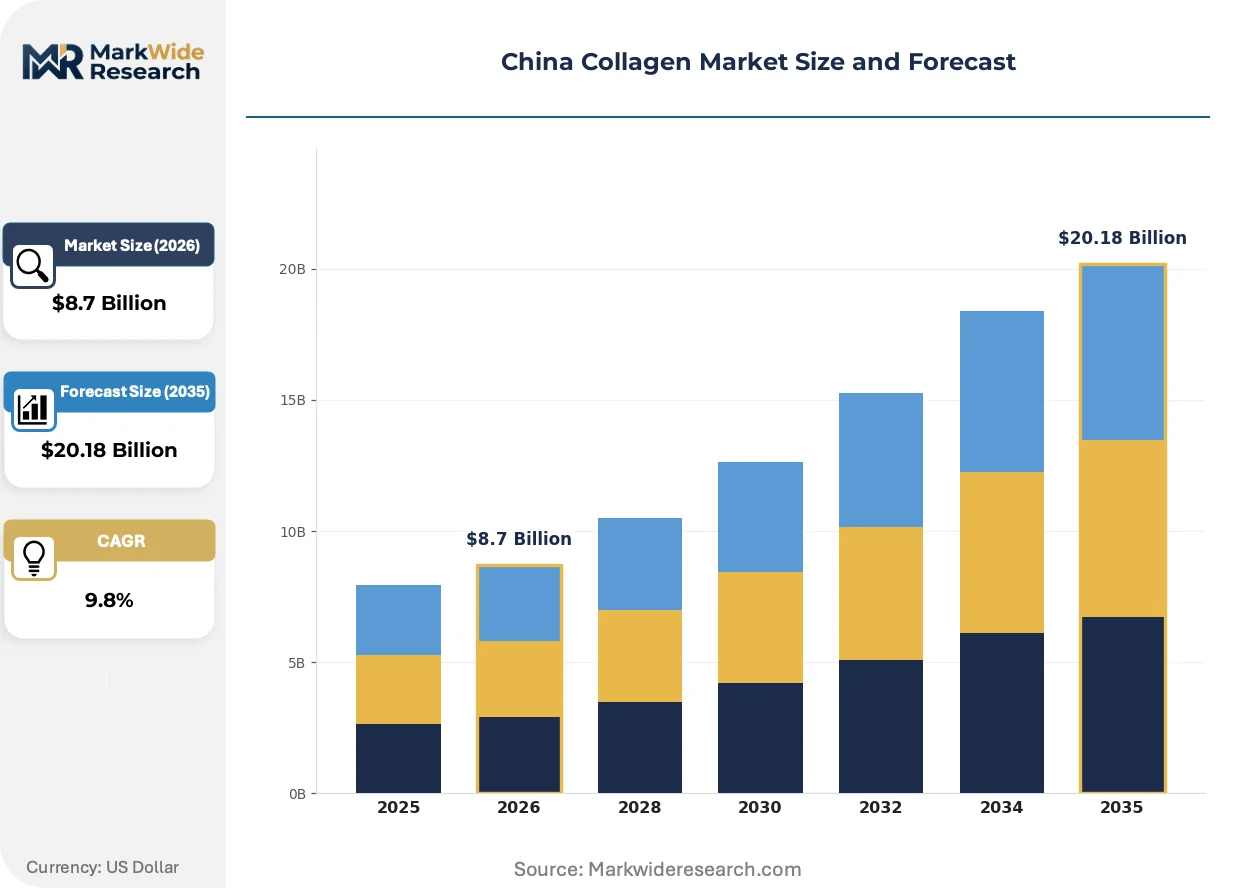
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $20.18 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Collagen, Gelatin, Collagen Peptides, Native Collagen Application: Food & Beverage, Cosmetics, Nutritional Supplements, Pharmaceuticals Source: Bovine, Porcine, Marine, Poultry Form: Powder, Liquid, Capsule, Gel |
| Companies Covered | Xiamen Huaxuan Gelatin Co., Ltd., Wuhan Sen Lan Biological Technology Co., Ltd., Jiangxi Hanfei Biotechnology Co., Ltd., Glory (Wuxi) Nutrition Technology Co., Ltd., Guangdong Victory Biotech Co., Ltd., YASIN, Hunan Jiayi Biotechnology Co., Ltd., Kaifeng Red Maple Leaf Biotechnology Co., Ltd., Xiamen Gelken Gelatin Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Collagen Market Emerging Trajectories
Enzymatic hydrolysis protocols are displacing acid-based extraction across premium peptide production, altering cost structures and purity benchmarks simultaneously. This technological rotation is compressing margins for conventional gelatin specialists while rewarding biotech-integrated processors.
Membrane filtration systems with molecular-weight cutoff precision are overtaking traditional precipitation methods in hydrolyzed collagen manufacturing. Nutraceutical contract manufacturers in Guangdong province are adopting these systems at accelerated pace to meet NMPA bioavailability documentation requirements. This shift is overtaking legacy batch-processing economics and enabling continuous-flow production models that reduce solvent waste.
SAMR food-ingredient standards for collagen peptide labeling are tightening disclosure requirements for molecular-weight distribution and heavy-metal content. The industrial consequence is mandatory investment in third-party testing infrastructure for all producers supplying functional food brands. Nutritional supplement manufacturers are responding by consolidating supplier bases around vertically integrated extractors with in-house analytical capabilities.
Direct-to-consumer subscription models are disrupting traditional pharmaceutical and cosmetics distribution channels for collagen supplements. E-commerce platforms and social commerce live-streaming are replacing hospital and clinic procurement for wellness-oriented peptide products. This channel rotation is most visible in tier-one cities where influencer-driven purchasing decisions now dominate premium marine collagen selection.
China Collagen Market Segmentation
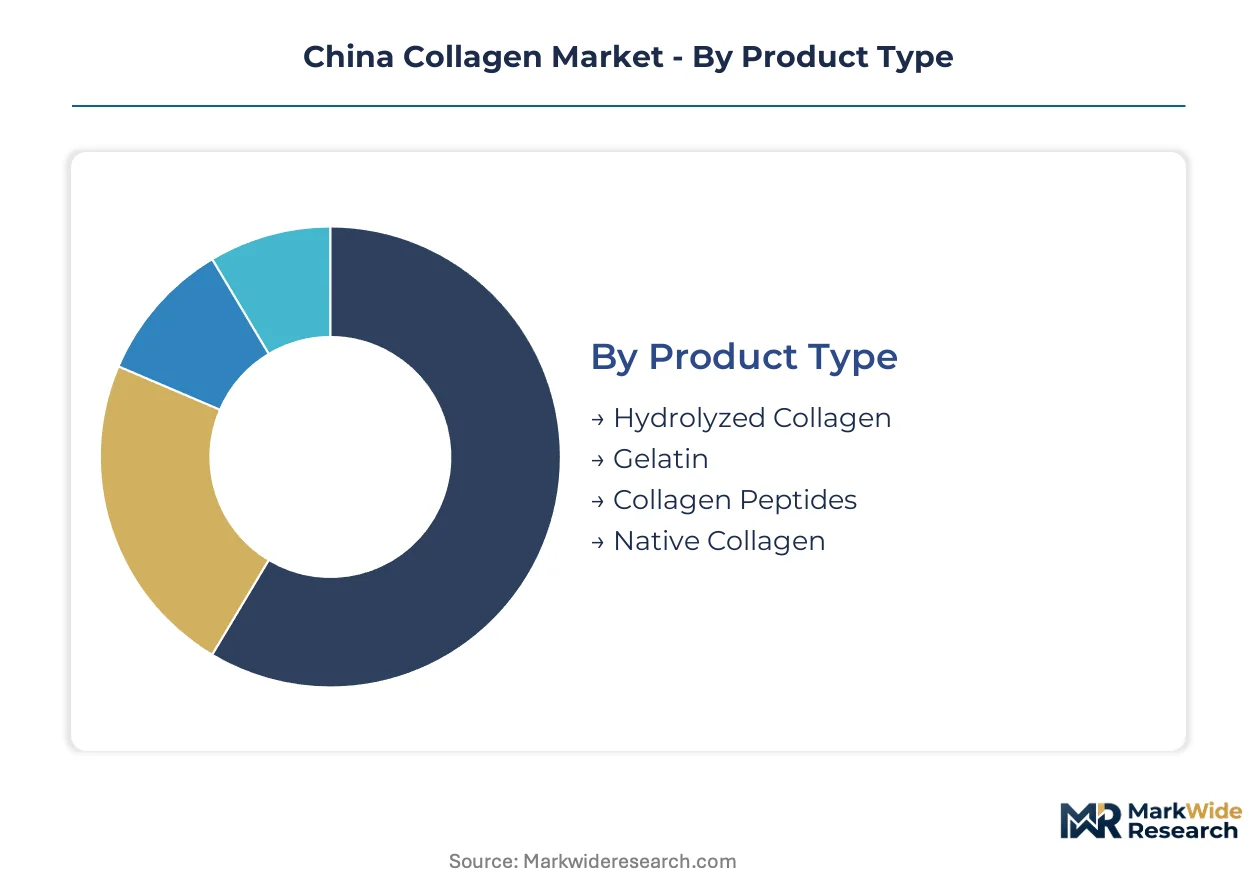
Collagen buyers in China segment sharply by molecular specificity and regulatory certification requirements. Pharmaceutical-grade extraction commands pricing multiples over food-grade gelatin, while marine-derived peptides capture premium positioning in cosmetics formulations.
Product Type:
Buyers in this category differentiate primarily by bioavailability claims and molecular weight specifications.
- Hydrolyzed Collagen:Enzymatic hydrolysis yields 2-5 kDa peptides optimized for dermal absorption and joint-support supplements. Functional beverage brands in Shanghai and Guangzhou are expanding hydrolyzed collagen portfolios to capture wellness-oriented consumers seeking bioavailable protein delivery.
- Gelatin:Acid-extracted protein with 100-300 kDa molecular weight retains gelling functionality for confectionery and capsule manufacturing. Xiamen Huaxuan Gelatin Co., Ltd. leverages bovine sourcing scale to anchor supply contracts with domestic capsule manufacturers in coastal manufacturing clusters.
- Collagen Peptides:Ultra-low molecular weight fractions below 3 kDa target nutraceutical absorption benchmarks.
- Native Collagen:Triple-helix structures above 300 kDa serve biomedical scaffold applications requiring structural integrity.
Gelatin leads volumes today; hydrolyzed collagen is gaining share fastest.
Application:
End-use concentration in this category tracks regulatory pathway complexity and margin structure.
- Nutritional Supplements:Direct-to-consumer peptide powders and functional beverages dominate revenue concentration. E-commerce platforms and social commerce live-streaming are replacing hospital procurement for wellness-oriented products in tier-one cities where influencer-driven purchasing decisions now dominate premium marine collagen selection.
- Cosmetics:Marine-derived peptides penetrate skincare formulations due to lower immunogenicity profiles preferred by premium formulators. Glory (Wuxi) Nutrition Technology Co., Ltd. specializes in hydrolyzed collagen for functional beverage brands while YASIN competes through marine-derived peptide lines targeting cosmetics formulators.
- Food & Beverage:Cost-sensitive gelling applications in confectionery and dairy retain volume dominance.
- Pharmaceuticals:NMPA medical device registration requirements for wound dressings and implants filter out low-purity suppliers.
Food & Beverage anchors volume scale; Nutritional Supplements climbs the fastest.
Source:
Raw material selection in this category hinges on religious dietary restrictions and immunogenicity risk profiles.
- Bovine:Scale rendering infrastructure across North China supplies gelatin and peptide producers despite livestock cycle volatility. Rendering capacity constraints and livestock cycle fluctuations in North China are creating input cost instability for gelatin and peptide producers serving pharmaceutical and nutraceutical buyers.
- Marine:Fish-scale and skin enzymatic hydrolysis occupies cosmetics-grade supply chains with premium positioning. Enzymatic hydrolysis of fish-scale collagen is penetrating cosmetics-grade supply chains due to lower immunogenicity profiles preferred by premium skincare formulators.
- Porcine:Halal certification barriers limit penetration in Muslim-majority western provinces.
- Poultry:Emerging alternative for collagen peptide extraction with lower capital intensity.
Bovine leads volumes today; Marine expands most quickly.
Form:
Delivery format preferences in this category track consumption occasion and shelf-stability requirements.
- Powder:Bulk peptide concentrates serve contract manufacturers and direct-to-consumer brands with dose flexibility. SAMR food-ingredient standards for collagen peptide labeling are tightening disclosure requirements for molecular-weight distribution and heavy-metal content, forcing mandatory investment in third-party testing infrastructure.
- Liquid:Ready-to-drink functional beverages capture on-the-go consumption in urban tier-one markets. Nutraceutical contract manufacturers in Guangdong province are adopting membrane filtration systems with molecular-weight cutoff precision to meet NMPA bioavailability documentation requirements.
- Capsule:Hard-shell gelatin and HPMC encapsulation for pharmaceutical and supplement dosing.
- Gel:Topical delivery matrices for wound care and cosmetic applications.
Powder leads volumes today; Liquid shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity migrates inland as coastal compliance costs rise under SAMR environmental enforcement, creating arbitrage opportunities for extractors willing to absorb GB standards retrofit expenses.
Shandong Peninsula
Bovine rendering clusters around Jinan and Qingdao supply gelatin volumes to domestic capsule manufacturers. GB standards for heavy-metal limits are forcing acid-extraction facilities to replace corrosion-resistant processing lines. Weifang industrial zones concentrate legacy gelatin capacity undergoing pharmaceutical-grade certification upgrades.
Yangtze River Delta
Shanghai functional beverage brands drive hydrolyzed collagen demand for wellness-positioned products. NMPA medical device registration cycles now exceed 18 months for novel formulations, compressing launch windows for wound-dressing developers. Wuxi biotechnology parks host peptide specialists serving nutraceutical contract manufacturers.
Pearl River Delta
Guangzhou cosmetics formulators source marine-derived peptides for premium skincare lines. SAMR green manufacturing incentives reward closed-loop wastewater systems in extraction facilities. Dongguan membrane filtration adoption is accelerating to meet NMPA bioavailability documentation requirements.
Sichuan-Chongqing
Underdeveloped nutritional supplement penetration creates first-mover expansion potential for direct-to-consumer brands. Dual carbon policy tailwinds favor renewable energy deployment in new extraction facilities. Chengdu logistics hubs enable distribution reach into western provinces with limited incumbent collagen brand presence.
Zhejiang Coastal Belt
Ningbo and Wenzhou production bases face tightening MEE wastewater discharge standards for animal-derived protein processors. Coastal manufacturing concentration exposes supply chains to regional logistics disruptions. Hangzhou e-commerce platforms are displacing traditional pharmaceutical distribution for wellness-oriented peptide products.
China Collagen Market Vendor Landscape
Shandong producers anchor the volume tier; Yangtze Delta specialists hold the premium peptide segment. The vendor base stratifies across certified pharmaceutical-grade extractors, commodity gelatin suppliers, and marine biotechnology entrants. Three archetypes dominate: vertically integrated render-to-peptide processors, nutraceutical-focused hydrolysis specialists, and cosmetics-grade marine peptide purveyors. Capacity expansion and backward integration into rendering assets constitute the primary competitive moves.
Among Shandong-based fabricators, Xiamen Huaxuan Gelatin Co., Ltd. and Xiamen Gelken Gelatin Co., Ltd. occupy positions within the bovine-sourced volume tier, while Glory (Wuxi) Nutrition Technology Co., Ltd. sits within the Yangtze Delta hydrolyzed peptide specialization cluster. YASIN represents the marine-derived cosmetics-grade archetype competing through enzymatic hydrolysis positioning.
| Leading Market Players |
|---|
| Xiamen Huaxuan Gelatin Co., Ltd. |
| Wuhan Sen Lan Biological Technology Co., Ltd. |
| Jiangxi Hanfei Biotechnology Co., Ltd. |
| Glory (Wuxi) Nutrition Technology Co., Ltd. |
| Guangdong Victory Biotech Co., Ltd. |
| YASIN |
| Hunan Jiayi Biotechnology Co., Ltd. |
| Kaifeng Red Maple Leaf Biotechnology Co., Ltd. |
| Xiamen Gelken Gelatin Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Enzymatic hydrolysis displacement of acid-based extraction is compressing unit economics for legacy gelatin specialists while rewarding biotech-integrated processors with pricing power over pharmaceutical-grade peptide buyers. This technological rotation simultaneously concentrates supply around membrane filtration adopters in Guangdong and Zhejiang and widens cost spreads between certified and uncertified producers serving NMPA-registered medical device manufacturers.
Pricing Analysis
Distributor margins on hydrolyzed collagen powders absorb 18-25 percentage points before reaching functional beverage brands, while direct-to-consumer subscription channels bypass this layer entirely. Three-tier pricing structure across pharmaceutical-grade, nutraceutical-grade, and food-grade levels tracks NMPA certification status and molecular weight documentation precision. Cost compression in food-grade gelatin runs through bovine rendering capacity constraints across North China. Nutraceutical contract manufacturers show highest price sensitivity; cosmetics formulators sourcing marine peptides demonstrate lowest.
Supply Chain Analysis
Skilled enzymatic hydrolysis technicians concentrate in Shanghai, Guangzhou, and Wuxi biotechnology parks, constraining capacity expansion for inland entrants. Raw material flows draw from Shandong bovine rendering clusters, Zhejiang fish-scale processors, and emerging poultry collagen extraction lines in Sichuan. Single-source vulnerability sits with coastal manufacturing concentration exceeding 70 percent of pharmaceutical-grade capacity. Distribution runs through e-commerce platforms displacing traditional pharmaceutical procurement for wellness-oriented peptide products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in China's collagen market rests on enzymatic hydrolysis yield improvements and premium-tier peptide positioning for NMPA medical device registrations. Enzyme cost curves and membrane filtration scale economies provide the cost-down pathway.
For Market Incumbents: Hedge rendering volatility through backward integration into North China livestock supply contracts or captive marine sourcing partnerships with Zhejiang fish processors. Accelerate NMPA medical device registration timelines to defend against emerging biotech-integrated entrants with native collagen scaffold capabilities. Prioritize closed-loop wastewater retrofit investments ahead of MEE enforcement tightening in coastal zones. For New Entrants and Emerging Players: Enter via Sichuan-Chongqing nutritional supplement white space where direct-to-consumer brand presence remains limited and logistics infrastructure now supports western province distribution. Target marine peptide cosmetics applications where immunogenicity advantages command premium positioning over bovine alternatives. Pursue influencer-driven social commerce live-streaming channels to bypass incumbent pharmaceutical distribution relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among uncertified food-grade gelatin producers facing GB standards retrofit burdens, while enzymatic hydrolysis specialists with in-house analytical capabilities trade at scarcity premiums. Long-term viability favors vertically integrated render-to-peptide processors with NMPA registration track records and renewable energy deployment in extraction facilities. Watch NMPA medical device registration cycle compression as inflection signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Medical Device Registration Acceleration | Filters low-purity suppliers and consolidates demand around certified peptide producers with documentation capabilities. |
| Enzymatic Hydrolysis Capacity Expansion | Displaces acid-extraction economics and enables continuous-flow production models reducing solvent waste compliance costs. |
| Backward Integration into Rendering Assets | Secures bovine raw material supply chains against livestock cycle volatility in North China production bases. |
| Marine Peptide Cosmetics-Grade Certification | Captures premium positioning in skincare formulations leveraging lower immunogenicity profiles preferred by formulators. |
| Closed-Loop Wastewater System Deployment | Qualifies producers for SAMR green manufacturing incentives ahead of MEE discharge standard tightening. |
Methodological Framework
Coverage spans Shandong, Zhejiang, Guangdong, and Sichuan provinces, with primary inputs from each production base. Conversations with enzymatic hydrolysis specialists, NMPA regulatory consultants, functional beverage brand managers, and cosmetics formulators combined with secondary validation from SAMR food-ingredient filings, NMPA medical device registration databases, and provincial environmental compliance disclosures. Bottom-up capacity modeling and top-down demand triangulation anchored market size estimation.
Rate-of-change decomposition across molecular weight segments, application verticals, and source material categories shaped the analytical framework. Segmentation dimensions modeled include product type, application, source, and form across the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating NMPA regulatory timeline impacts and enzymatic hydrolysis adoption S-curves. Industry-specific forecast inputs captured marine peptide cosmetics penetration rates and direct-to-consumer channel share shifts.
Inputs from NMPA registration databases and SAMR enforcement bulletins were available through the study window; gaps in private-label contract manufacturer volume data introduce uncertainty bands around nutraceutical segment estimates. Forecasts reflect documented assumptions regarding regulatory timeline stability and enzyme cost curve trajectories. Material deviation in NMPA medical device registration cycle lengths or MEE wastewater enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Europe Polypropylene Compounds Market
Specialty Compounds
Polyurea Market
Specialty Compounds
Potassium Monopersulfate (KMPS) Market
Specialty Compounds
Ready Mix Joint Compound Market
Specialty Compounds
Global Specialty Zeolites Market
Specialty Compounds
Spackling Paste Market
Specialty Compounds
Global Polymer Clay Market
Specialty Compounds
Chromium Phosphate Market
Specialty Compounds
Middle East and Africa Color Masterbatch Market
Specialty Compounds
Oxygen Scavenger Masterbatch Market
Specialty Compounds
Global Heat Stabilizers Market
Specialty Compounds
Galactoarabinan Market
Specialty Compounds
Fluoropolymer Masterbatch Market
Specialty Compounds
Conductive Plastic Compounds Market
Specialty Compounds
Argan Oil Market
Specialty Compounds
Acrylic Pad Market