
 Industrial Waste Management Market | 2026-2036
Industrial Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Waste Management Market Intelligence
The bundling of collection, recycling, and disposal services into single-source contracts is shifting procurement patterns for large industrial clients. Veolia Environnement S.A. leverages its global scale to offer these integrated solutions across multiple continents. In North America, Waste Management, Inc. dominates with its extensive landfill and transfer station network. Meanwhile, Clean Harbors, Inc. specializes in the complex logistics and treatment of hazardous industrial byproducts, differentiating itself through technical expertise.
Industrial waste management encompasses the systematic handling of materials generated by industrial operations, from collection to final disposal. The process involves characterizing waste streams, such as chemical or biomedical waste, to ensure safe and compliant treatment. While non-hazardous waste constitutes the largest volume, the hazardous waste segment commands higher service margins due to complex handling requirements. Advanced treatment technologies like incineration and pyrolysis are displacing landfilling for resource recovery and energy generation from specific industrial outputs.
Regulatory mandates from bodies like the U.S. EPA and the European Chemicals Agency (ECHA) define material classifications and disposal protocols. In parallel, directives from China's Ministry of Ecology and Environment (MEE) enforce stricter emission controls on waste-to-energy facilities, shaping technology investments. Service providers must therefore navigate a complex web of national standards while positioning for growth in circular economy models.
Market Dynamics
Intensifying global regulatory pressure, from China's Ministry of Ecology and Environment to the EU Green Deal, is the central force compelling a structural pivot from landfill disposal toward resource recovery and circular economy models in industrial waste management.
Growth Catalysts
- Circular Economy Mandates:Stricter emission controls on waste-to-energy facilities, enforced by China's MEE, are compelling investment in higher-efficiency incineration and gasification technologies to meet national dual carbon goals and recover energy from industrial refuse.
- Biomedical Sector Expansion:Growth in pharmaceutical manufacturing and healthcare services generates larger volumes of regulated medical and chemical waste, requiring specialized collection, treatment, and disposal services that command premium pricing.
- Resource Recovery Technology:The maturation of advanced thermal treatments like pyrolysis allows for the conversion of previously non-recyclable plastic and chemical sludge into valuable syngas and oils, creating new revenue streams from waste inputs.
Market Restraints
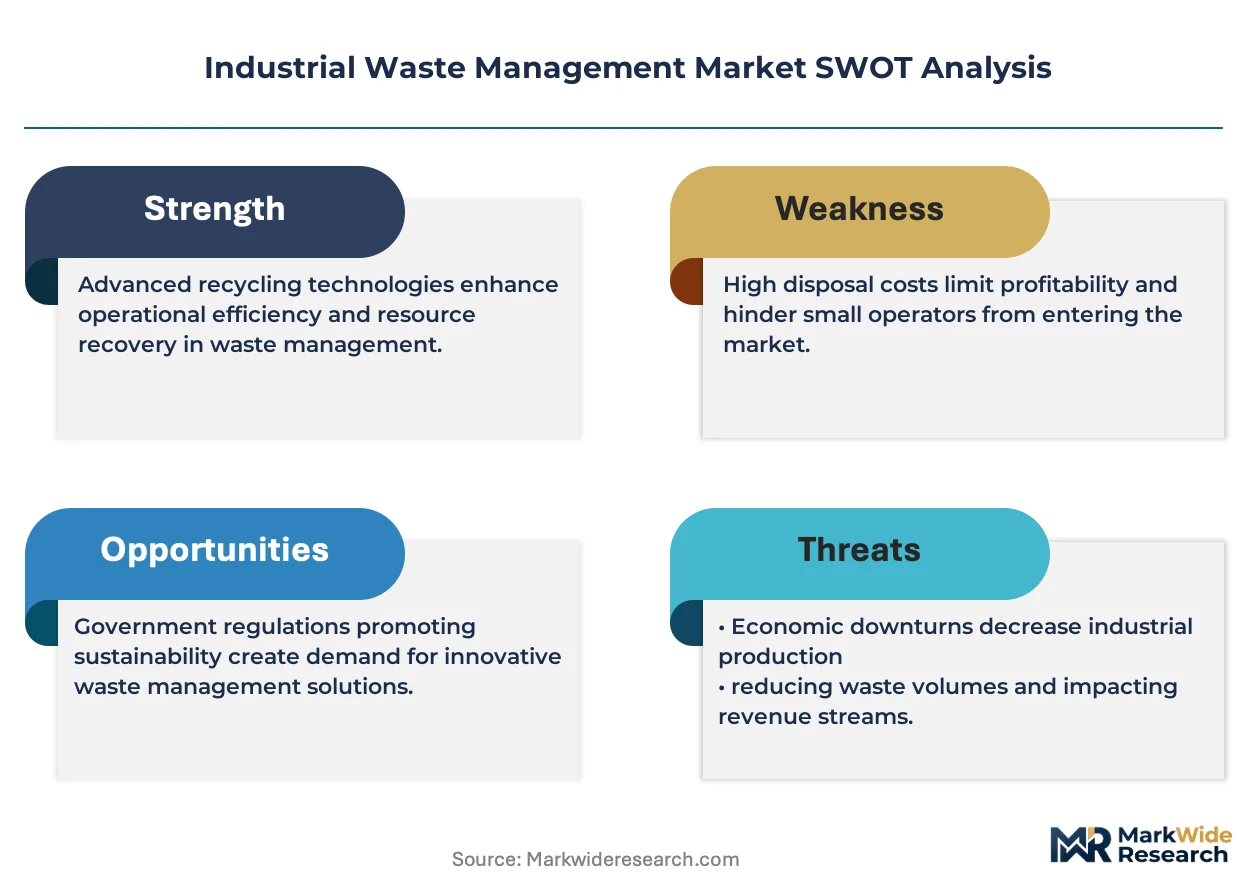
- High Capital Expenditure:The construction of advanced treatment facilities, including high-temperature incinerators and secure landfills for hazardous materials, requires significant upfront investment, creating a high barrier to entry for new service providers.
- Regulatory Fragmentation:Divergent and evolving waste classification standards between jurisdictions, such as those governed by the U.S. EPA and the European Chemicals Agency, increase compliance complexity and costs for multinational industrial clients.
- Logistical Hurdles:The transportation of hazardous waste from industrial production sites to distant, specialized treatment centers is logistically complex, costly, and carries significant public safety and environmental liability risks.
Strategic Opportunities
- Emerging Market Penetration:Rapid industrialization in Southeast Asian nations offers significant greenfield opportunities for establishing modern, integrated waste management infrastructure and services where local capabilities are underdeveloped.
- Modular Treatment Systems:Development of containerized or mobile treatment units enables on-site processing of specific waste streams, reducing transportation costs and liability while offering a flexible service model for industrial plants.
- Specialized Recycling Services:A growing focus on the circular economy creates demand for niche services targeting the recovery of critical materials from complex post-industrial products like electric vehicle batteries and solar panels.
Industry Challenges
- Skilled Labor Scarcity:A persistent shortage of qualified environmental engineers, chemists, and certified technicians capable of operating and maintaining sophisticated waste treatment and analysis equipment constrains service capacity and quality.
- Standardization Gaps:The absence of globally harmonized protocols for waste stream characterization and data reporting complicates service delivery for multinational corporations seeking consistent management practices across their global operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Waste Management Market |
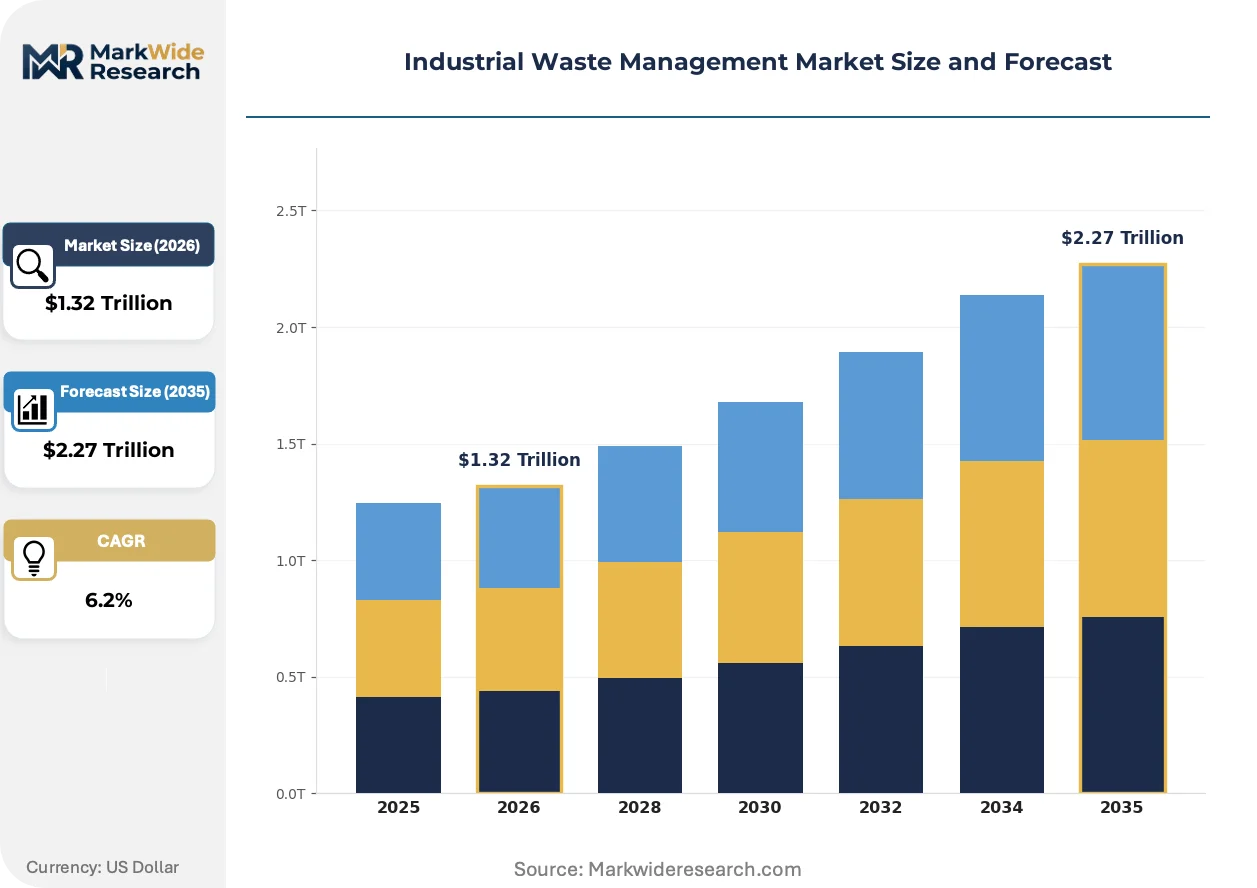
| Market Size in 2026 | $1.32 Trillion |
| Market Size in 2035 | $2.27 Trillion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Waste Type: Hazardous Waste, Non-Hazardous Waste, E-Waste, Biomedical Waste, Chemical Waste Treatment Technology: Incineration, Composting, Recycling, Landfilling, Pyrolysis End User Industry: Manufacturing Plants, Mining Operations, Construction Sites, Power Generation Units, Food Processing Facilities Service Model: Collection & Transportation, Waste Recycling, Treatment & Disposal, Resource Recovery, Consulting Services |
| Companies Covered | Waste Connections, Inc., Suez S.A., Waste Management, Inc., Stericycle, Inc., Remondis SE & Co. K.G., Republic Services, Inc., Clean Harbors, Inc., Casella Waste Systems, Inc., Veolia Environnement S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Waste Management Market Strategic Shifts & Innovations
The market's evolution reflects a fundamental re-evaluation of waste from a liability to a potential asset. Technological innovation and stringent environmental mandates are accelerating the transition from simple disposal to sophisticated material and energy recovery systems.
Digitalization of waste tracking through Internet of Things sensors and analytics software provides real-time characterization of industrial refuse. Manufacturing and chemical processing plants adopt this technology to enhance regulatory compliance and identify opportunities for waste reduction at the source. This real-time data capability is expanding into predictive analytics for optimizing collection logistics and maximizing resource recovery yields from heterogeneous waste streams.
Implementation of the European Union's Corporate Sustainability Reporting Directive (CSRD) is creating new compliance-driven demand. The directive forces large industrial companies to provide detailed, audited disclosures on their waste generation, recycling rates, and disposal methods. The manufacturing and energy sectors are most affected, now prioritizing service providers who can deliver the granular, verifiable data needed to meet these new reporting obligations.
Clients in specialized sectors are increasingly favoring best-of-breed service contracts over single-source bundled agreements. Industrial firms in pharmaceuticals and electronics unbundle hazardous waste treatment from general disposal to access niche technical expertise. This pattern is most pronounced in North America and Europe for chemical or e-waste recycling, where capability is a key differentiator.
Industrial Waste Management Market Segmentation
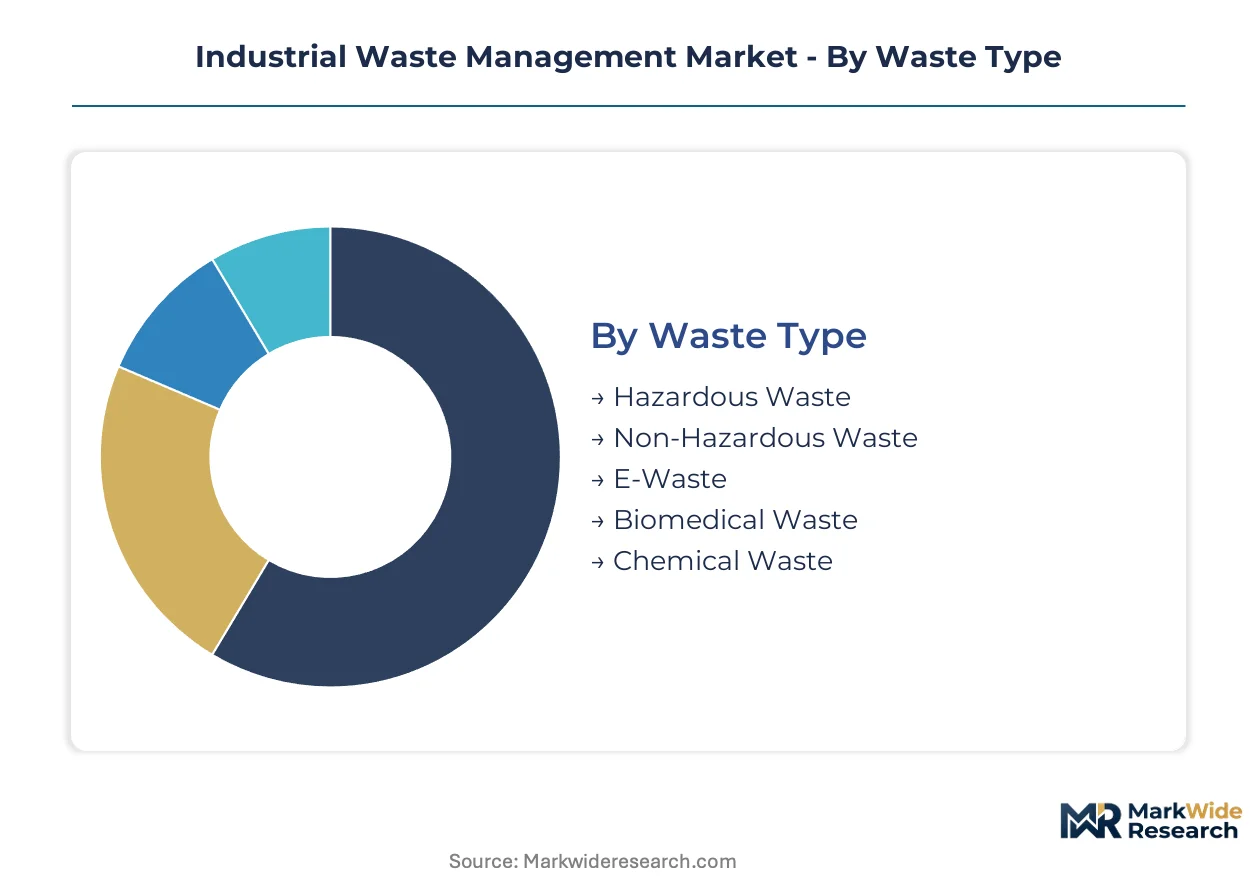
The industrial waste management market requires precise segmentation to understand its varied operational and regulatory landscapes. Different waste streams, treatment methods, and end-user demands shape service provision. Analyzing these segments helps identify investment priorities and specialized service opportunities across the value chain.
Waste Type:
Segmentation by waste type highlights the varying capital intensity required for safe and compliant handling.
- Hazardous Waste:This category includes toxic, corrosive, flammable, or reactive industrial byproducts requiring specialized containment and treatment. Demand concentrates in chemical manufacturing and pharmaceutical plants due to stringent EPA and ECHA regulations on disposal.
- Non-Hazardous Waste:Comprising general industrial refuse like packaging, construction debris, and non-toxic process waste, this segment represents the largest volume of industrial waste. Growth in manufacturing plants drives collection and recycling services, especially in China and India.
- E-Waste:This segment covers discarded electronic equipment from industrial operations, necessitating specialized processes for critical material recovery.
- Biomedical Waste:This includes infectious, pathological, or pharmaceutical waste from healthcare and research facilities, demanding stringent sterilization and disposal protocols.
- Chemical Waste:Industrial byproducts from chemical processes often require neutralization, detoxification, or secure landfilling due to their reactive properties.
Most installed capacity flows through Non-Hazardous Waste. Expansion is steepest in Hazardous Waste.
Treatment Technology:
Treatment technology segmentation reveals distinct approaches based on waste composition and desired environmental outcomes.
- Incineration:Advanced thermal treatment converts industrial waste into ash, flue gas, and heat, often for energy recovery. Stricter MEE emission controls in China drive investment in higher-efficiency incineration for energy generation from specific industrial outputs.
- Recycling:This process reintroduces industrial byproducts into the production cycle, reducing raw material consumption and landfill volumes. Circular economy mandates and CSRD reporting obligations in Europe compel manufacturing firms to prioritize material recovery.
- Composting:Organic industrial waste, such as food processing byproducts, is biologically decomposed into nutrient-rich soil amendments.
- Landfilling:Engineered sites provide secure containment for non-recyclable or non-treatable industrial waste, adhering to environmental regulations.
- Pyrolysis:Thermal decomposition of organic materials in the absence of oxygen converts industrial waste into bio-oil, syngas, and char.
The market is prioritizing Recycling for its resource conservation benefits. Pyrolysis is gaining traction due to its ability to convert non-recyclable plastics into valuable products.
End User Industry:
Segmentation by end-user industry reflects the diverse scales and complexities of waste generation across industrial operations.
- Manufacturing Plants:These facilities generate a wide array of industrial waste, from general refuse to specialized chemical byproducts. Pronounced growth in manufacturing across India and Southeast Asia drives demand for integrated waste management services.
- Power Generation Units:This segment produces significant volumes of ash, sludge, and other byproducts from energy production. Regulations enforcing stricter emission controls on waste-to-energy facilities shape technology investments in this sector.
- Mining Operations:Large volumes of overburden, tailings, and process water require specialized management, often involving land reclamation and water treatment.
- Construction Sites:This sector generates substantial demolition debris, excavation waste, and packaging materials, requiring efficient collection and recycling services.
- Food Processing Facilities:Organic waste, wastewater, and packaging materials are the primary waste streams, with a focus on composting and anaerobic digestion.
Demand from Manufacturing Plants drives significant volume. Specialized requirements from Mining Operations command premium service.
Service Model:
Segmentation by service model illustrates the evolving scope of provider offerings, from basic logistics to comprehensive resource management.
- Waste Recycling:This service focuses on processing industrial waste streams to recover valuable materials for reuse or reprocessing. Circular economy initiatives and Corporate Sustainability Reporting Directive (CSRD) requirements in the EU are driving this segment.
- Treatment & Disposal:This core service involves the safe and compliant processing and ultimate placement of industrial waste, including hazardous materials. Technical expertise in managing complex chemical and biomedical waste streams differentiates providers.
- Collection & Transportation:This foundational service involves the safe and efficient movement of industrial waste from generation sites to treatment or disposal facilities.
- Resource Recovery:This advanced service extracts valuable materials or energy from waste streams, often using technologies like waste-to-energy or material reclamation facilities.
- Consulting Services:Providers offer expertise in waste characterization, regulatory compliance, waste reduction strategies, and sustainability reporting for industrial clients.
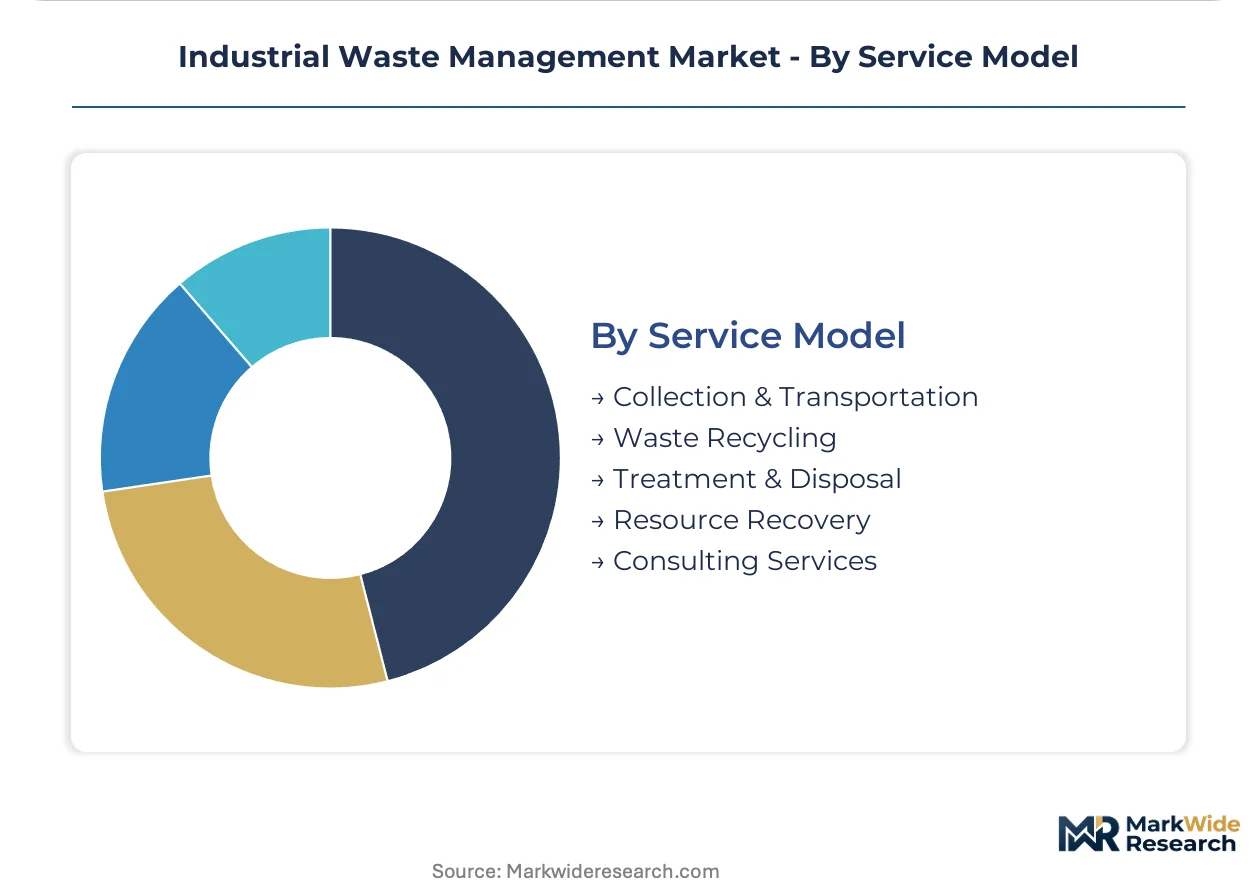
Service providers are differentiating through Waste Recycling. Growth in Resource Recovery reflects evolving client needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The industrial waste management sector first scaled in industrialized nations with established manufacturing bases. Early regulatory frameworks in Europe and North America compelled industries to manage hazardous byproducts, laying the groundwork for specialized treatment services. This historical development concentrated early market expertise and infrastructure.
United States
Pharmaceutical manufacturing and chemical processing generate significant volumes of regulated waste, driving demand for specialized treatment. U.S. EPA regulations define strict disposal protocols for various industrial byproducts. The Gulf Coast region, with its extensive petrochemical complexes, requires advanced hazardous waste treatment and disposal infrastructure.
China
Manufacturing growth and the nation's dual carbon goals accelerate demand for efficient waste-to-energy solutions. China's Ministry of Ecology and Environment (MEE) enforces stricter emission controls on waste-to-energy facilities. Yangtze River Delta manufacturing hubs are investing in higher-efficiency incineration technologies for industrial refuse.
Germany
Circular economy mandates and advanced manufacturing processes fuel demand for material recovery and recycling services. The EU Green Deal and ECHA directives drive sustainable waste practices across industrial sectors. The Ruhr industrial area focuses on resource efficiency and material recovery for its heavy industries.
India
Rapid industrialization and expanding manufacturing plants create a substantial need for integrated waste management services. National environmental policies promote waste reduction and recycling initiatives for industrial outputs. Gujarat's industrial corridors are establishing modern, integrated waste management infrastructure to support new facilities.
Vietnam
Emerging market industrialization, particularly in electronics manufacturing, generates diverse and complex waste streams. Local environmental protection laws are developing to manage increasing industrial refuse effectively. Ho Chi Minh City's industrial parks seek integrated solutions for diverse waste streams, including e-waste and chemical byproducts.
Industrial Waste Management Market Key Industry Players
The competitive structure tilts toward a tiered model, balancing global scale providers with specialized regional players. The market exhibits consolidation among large, diversified environmental service firms that offer comprehensive solutions. Fragmentation exists within niche hazardous waste treatment and specialized recycling segments. Geographic expansion and portfolio diversification are common strategies employed by market participants.
Global integrators like Veolia Environnement S.A. offer comprehensive waste management solutions across multiple continents. Waste Management, Inc. exemplifies a North American leader, leveraging an extensive landfill and transfer station network to serve industrial clients. Clean Harbors, Inc., operating as a specialized service provider, focuses on complex hazardous industrial byproduct treatment, differentiating itself through technical expertise.
| Leading Market Players |
|---|
| Waste Connections, Inc. |
| Suez S.A. |
| Waste Management, Inc. |
| Stericycle, Inc. |
| Remondis SE & Co. K.G. |
| Republic Services, Inc. |
| Clean Harbors, Inc. |
| Casella Waste Systems, Inc. |
| Veolia Environnement S.A. |
| Others |
Cost & Logistics Intelligence
The EU Green Deal and China's MEE mandates gate both qualified supply and premium-tier pricing access for advanced industrial waste treatment services. These regulations compel industries to invest in compliant, high-efficiency solutions.
Pricing Analysis
Contract-based long-term agreements often dominate industrial waste management pricing, reflecting the specialized nature of services. Technical expertise in hazardous waste treatment and stringent regulatory compliance drive significant price differentiation. Pricing pressure stems from the high capital expenditure required for advanced treatment facilities and the scarcity of skilled labor. Industrial clients in the non-hazardous waste segment exhibit higher price sensitivity, while pharmaceutical and chemical manufacturers prioritize compliant hazardous waste treatment over cost.
Supply Chain Analysis
Logistics and freight costs represent a substantial component of industrial waste management, particularly for hazardous materials requiring specialized transport. Geographic supply concentration for advanced treatment technologies centers on industrial hubs in China, India, and the United States. The supply chain relies on specialized treatment chemicals and high-efficiency incinerator components. Regulatory fragmentation, with divergent waste classification standards between the U.S. EPA and the European Chemicals Agency, poses a structural risk. Distribution runs through a hub-and-spoke model for collection, leading to specialized treatment facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial waste management market operates as a stable compounder, with intensifying global regulatory pressure driving consistent, long-term growth. This consistent demand underpins strategic investment and operational planning.
For Market Incumbents: Deepen integration of digital waste tracking systems to enhance compliance and optimize operational efficiency. Invest in advanced thermal treatment technologies like pyrolysis to address resource recovery mandates and mitigate landfill reliance. Address skilled labor scarcity through targeted training programs and university partnerships to maintain service capacity and technical leadership. Consolidate regional expertise to counter competitive pressures from specialized entrants.
For New Entrants and Emerging Players: Industrial park operators offer a concentrated entry point, providing access to diverse waste streams from multiple manufacturing tenants. Target emerging markets in Southeast Asia for establishing modern, integrated waste management infrastructure due to underdeveloped local capabilities. Focus on specialized recycling services for critical materials from complex industrial products like EV batteries. Develop flexible, modular treatment systems for on-site processing to reduce client transportation costs.
For Investors and Strategic Acquirers: Roll-up economics work for regional specialists because of structural fragmentation in hazardous waste treatment and specialized recycling. Focus on acquiring companies with niche technical expertise in advanced resource recovery or complex chemical waste processing. Long-term viability over a 5-10 year window is sustained by evolving circular economy mandates and corporate sustainability reporting requirements. Increased corporate sustainability reporting compliance (CSRD) serves as a key signal to watch for accelerating demand for verifiable waste management data.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Industrial clients seek partners enabling lower emissions and higher resource efficiency to meet environmental targets. |
| Capacity Expansion | Increased processing capacity for hazardous waste supports growing pharmaceutical and chemical manufacturing output. |
| Technology Licensing | Licensing advanced thermal treatment technologies accelerates market penetration in regions with strict emission controls. |
| Strategic Partnership | Partnerships with industrial park developers secure long-term waste collection contracts in rapidly industrializing areas. |
| Green Certification Program | Offering certified waste management services provides a competitive edge for manufacturing firms facing CSRD obligations. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, forming a robust data foundation. Primary research involved discussions with environmental engineers, plant managers, regulatory affairs specialists, and waste management consultants. Secondary validation drew from U.S. EPA reports, ECHA directives, China MEE publications, and industrial association reports, ensuring comprehensive market understanding. This approach leveraged both bottom-up and top-down triangulation for data accuracy.
The segment-weighting approach informed the analytical framework across the analysis window, modeling market dynamics for various waste types, treatment technologies, end-user industries, and service models. Regional regulatory clusters were also integrated into the framework. Compound annual growth rates were derived from historical growth trends and projected impacts of evolving environmental policies. Industrial production indices and environmental policy changes served as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to unforeseen regulatory shifts and rapid technological advancements. Forecasts reflect assumptions regarding sustained industrial growth and continued investment in sustainable practices. A model refresh is warranted upon material change in global trade policies affecting manufacturing output.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
GCC Pneumatic Waste Management System Market
Waste Management & Pollution Control
South American Waste Management Market
Waste Management & Pollution Control
Global Waste Management Equipment Market
Waste Management & Pollution Control
Qatar Waste Management Market
Waste Management & Pollution Control
Europe Municipal Solid Waste Management Market
Waste Management & Pollution Control
Asia-Pacific Hazardous Waste Handling Automation Market
Waste Management & Pollution Control
United States Trash Bags Market
Waste Management & Pollution Control
India Waste Management Market
Waste Management & Pollution Control
US Municipal Solid Waste Management Market
Waste Management & Pollution Control
India Bio-Medical Waste Management Market
Waste Management & Pollution Control
Europe Waste Recycling Services Market
Waste Management & Pollution Control
GCC Industrial Waste Management Market
Waste Management & Pollution Control
Saudi Arabia Waste Management Market
Waste Management & Pollution Control
Metal Recycling Baler Market
Waste Management & Pollution Control
Global Smart Trash Bin Market
Waste Management & Pollution Control
Europe Bio-Medical Waste Management Market