
 South American Waste Management Market | 2026-2036
South American Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
South American Waste Management Market Analytics
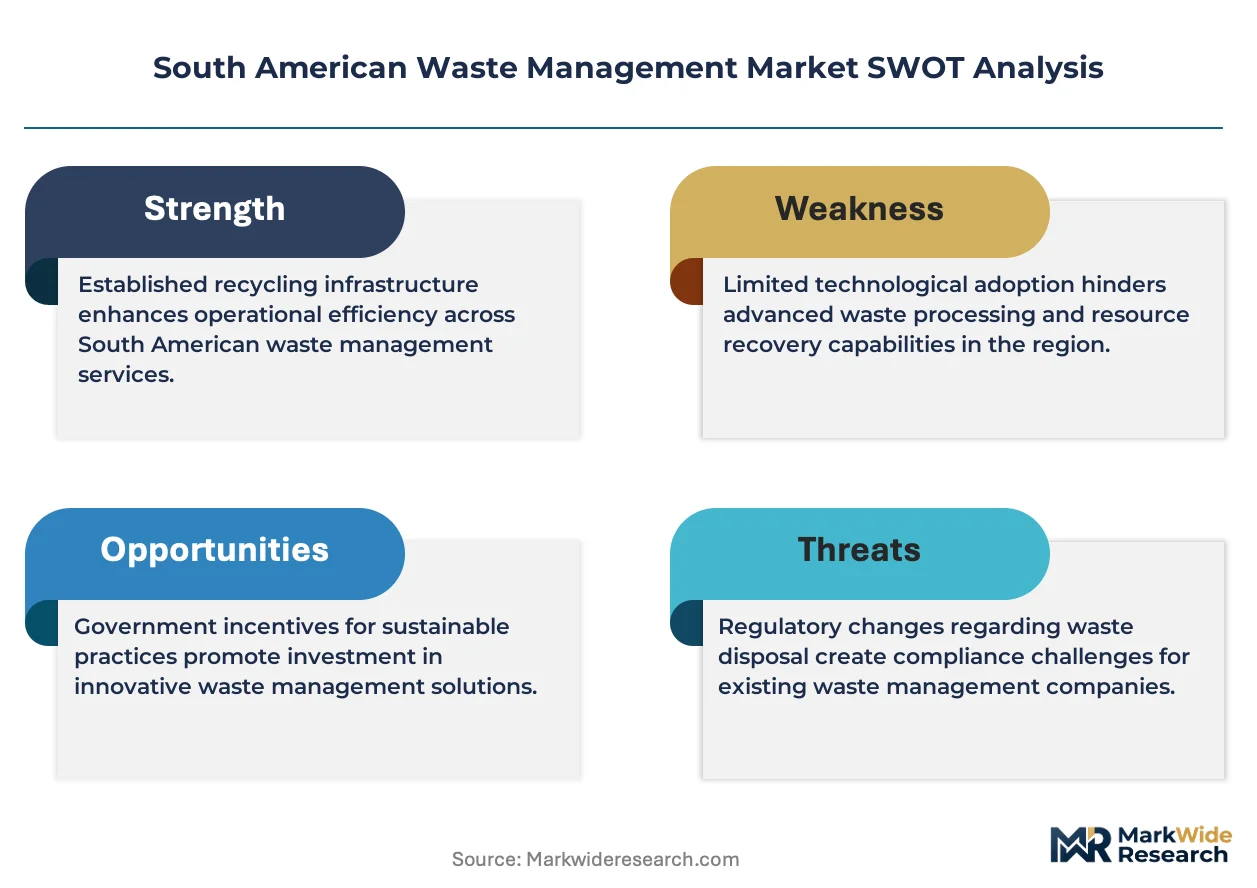
Multi-source contracting for municipal waste services is consolidating across South American capitals as city governments exit direct operations. Estre Ambiental leverages its integrated landfill-to-energy footprint across Brazilian states to anchor long-term service agreements. Solví Participações competes through specialized hazardous waste treatment capabilities that differentiate its portfolio from generalist operators.
Waste management encompasses the systematic collection, transportation, processing, recycling, and disposal of solid and liquid refuse, with engineered landfills requiring composite liner systems, leachate collection pipes, and methane gas extraction wells to prevent soil and groundwater contamination. The primary purpose spans public health protection, environmental remediation, and resource recovery for circular material flows. Collection services occupy the largest revenue pool given their recurring municipal contract structure, while anaerobic digestion represents the fastest-expanding technology segment as landfill diversion targets tighten across the region. Industrial end users sustain premium pricing for hazardous waste handling due to stringent manifesting and cradle-to-grave liability requirements.
Brazil's PNRS framework and Argentina's Federal Law on Waste Management shape operational licensing, extended producer responsibility compliance, and landfill closure bonding requirements that directly determine market access for new entrants. ANVISA regulates healthcare waste sterilization standards, while state environmental agencies in São Paulo and Buenos Aires provinces enforce leachate discharge limits that upgrade treatment plant specifications. Stakeholders must monitor regulatory harmonization progress under Mercosur environmental protocols and assess concession renewal timelines in cities where initial contract periods approach expiration.
Market Dynamics
Landfill capacity exhaustion across Brazil's southeastern industrial corridor is forcing municipalities toward anaerobic digestion and mechanical-biological treatment infrastructure, compressing capital deployment timelines from ten-year master plans to emergency procurement cycles.
Growth Catalysts
- Extended Producer Responsibility Mandates:Brazil's PNRS framework obliges packaging producers to finance post-consumer collection and recycling, creating guaranteed revenue streams for waste service operators.
- São Paulo State Leachate Discharge Limits:Stricter enforcement by CETESB is accelerating upgrades to biological treatment and reverse osmosis systems at existing landfill complexes.
- Biogas-to-Energy Economics:Rising industrial natural gas prices are improving project finance returns for landfill gas capture and anaerobic digestion facilities serving manufacturing clusters.
Market Restraints
- Composite Liner Import Dependency:HDPE geomembrane supply concentrates among three multinational petrochemical suppliers, exposing project budgets to polymer price volatility and dollar-denominated contract exposure.
- State-Level Licensing Fragmentation:Brazil's CONAMA resolutions establish federal baselines, but state environmental agencies impose divergent technical standards that multiply compliance costs for multi-state operators.
- Informal Sector Competition:Unregistered waste pickers in Buenos Aires and São Paulo metropolitan areas capture 15-30% of recyclable volumes, compressing formal sector feedstock security.
Strategic Opportunities
- Colombia's Pacific Coast Infrastructure Gap:Buenaventura and Tumaco lack engineered landfill capacity, creating first-mover advantage for integrated waste-to-energy developers with port logistics capabilities.
- Healthcare Waste Sterilization:ANVISA's updated resolution on infectious waste treatment is expanding mandatory autoclave and microwave sterilization requirements for hospital networks outside major capitals.
- Digital Waste Tracking Convergence:Integration of RFID bin tagging with route optimization software is unifying collection fleet telemetry with landfill weighbridge data for municipal pay-as-you-throw billing.
Industry Challenges
- Specialized Equipment Technician Scarcity:Maintenance of landfill gas engines and anaerobic digesters requires mechanical-electrical hybrid skills that vocational programs in Argentina and Brazil have not scaled to match deployment.
- Legacy Contract Renegotiation Friction:Municipalities locked into 15-20 year concession agreements signed during 2000s privatization waves resist rate adjustments needed to cover post-closure care and leachate treatment cost inflation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South American Waste Management Market |
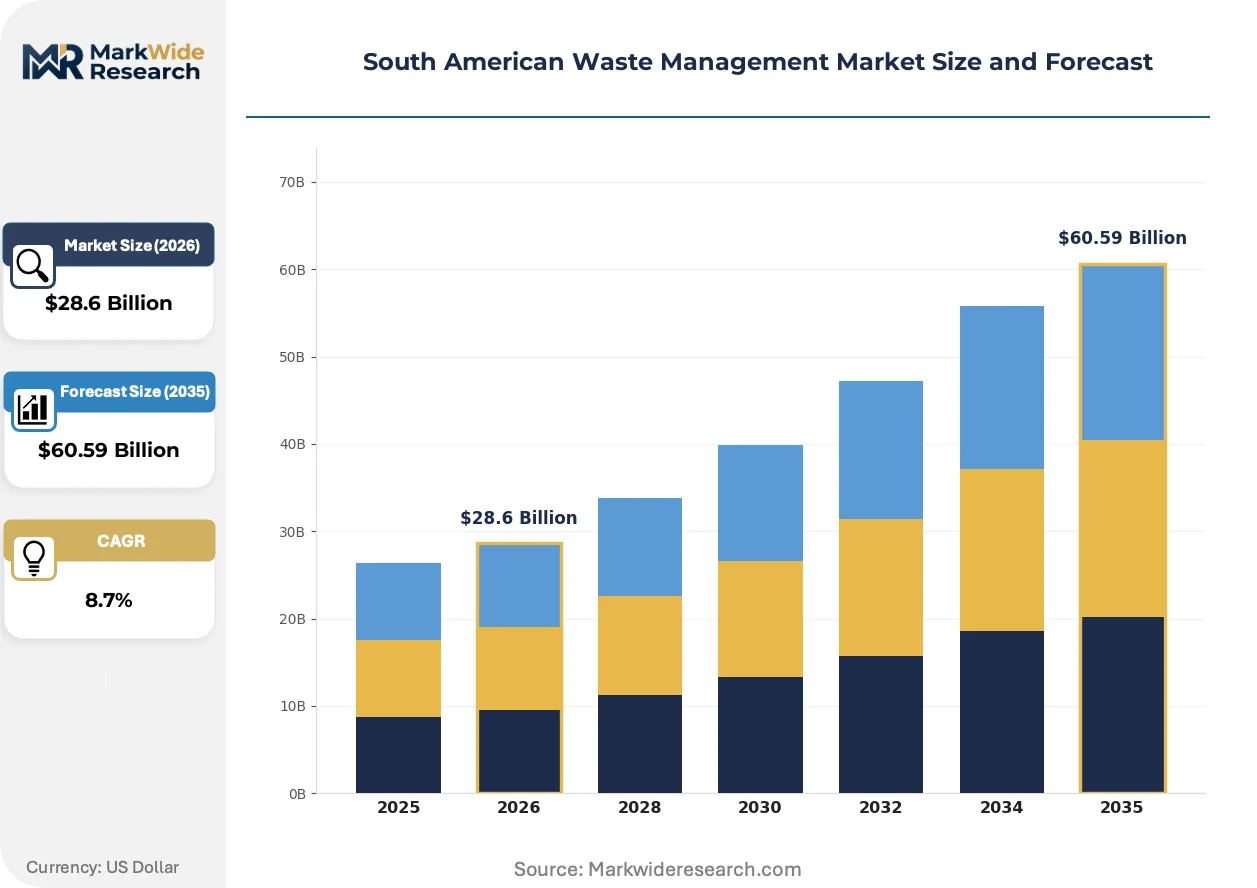
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Collection, Recycling, Disposal, Treatment Technology: Landfill, Incineration, Anaerobic Digestion, Composting End User: Municipalities, Commercial, Industrial, Residential Waste Type: Hazardous, Non-Hazardous, Organic, E-Waste |
| Companies Covered | Estre Ambiental, Solví Participações, Cliba, Veolia Argentina, KDM Empresas, Interaseo, Petramás, EMASEO EP, Companhia de Saneamento Basico do Estado de Sao Paulo, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South American Waste Management Market Evolving Landscape
Waste management technology in South America is pivoting from disposal-centric infrastructure toward integrated resource recovery platforms, with digital traceability and circular material mandates compressing traditional collection-to-landfill value chains.
Mechanical-biological treatment is unifying waste sorting, composting, and refuse-derived fuel production within single facility footprints. Brazilian operators in Minas Gerais and Paraná are retrofitting existing landfill sites with MBT front-ends to meet diversion targets without greenfield permitting delays. This convergence is compressing capital requirements for municipalities that previously needed separate composting and landfill facilities.
Argentina's Federal Law on Waste Management is tightening cradle-to-grave hazardous waste manifesting requirements for industrial generators. The regulation forces chemical manufacturers and automotive assemblers to contract only with licensed treatment-storage-disposal facilities carrying federal environmental authority accreditation. Buenos Aires province's petrochemical corridor is responding fastest, with refineries consolidating waste service contracts to reduce vendor audit burdens.
Industrial buyers are consolidating waste service procurement under single-source environmental management contracts that bundle hazardous and non-hazardous streams. Argentine automotive assemblers in Córdoba and Brazilian food processors in Rio Grande do Sul are replacing fragmented spot contracts with five-to-seven year integrated service agreements. This concentration rewards operators with multi-license geographic coverage and penalizes single-site specialists.
South American Waste Management Market Segmentation
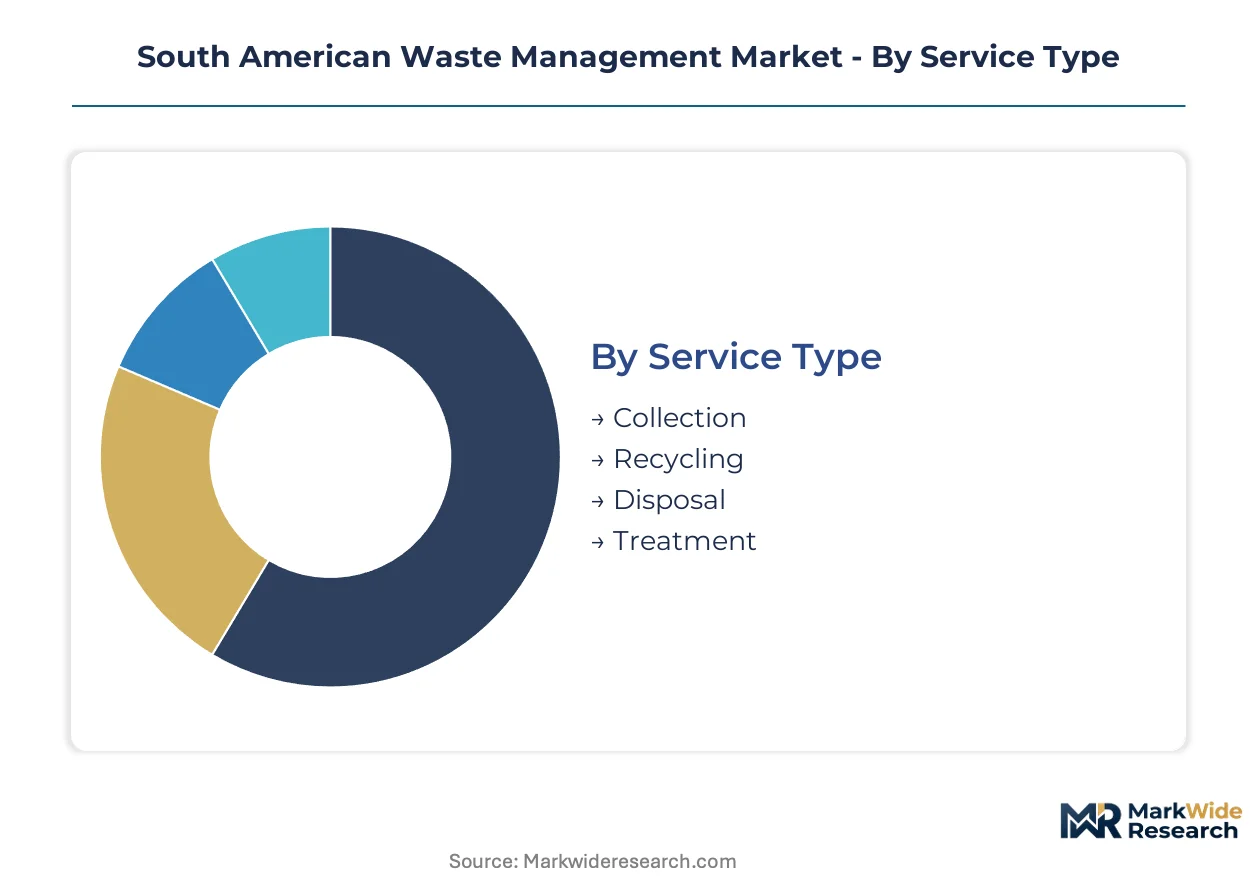
Waste management procurement in South America diverges sharply across customer types and regulatory exposure, with municipal contracts favoring recurring collection services while industrial buyers prioritize hazardous waste liability coverage. Technology selection reflects landfill capacity constraints in Brazil's southeastern corridor and emerging biogas economics in Argentina's agricultural zones.
Service Type:
Municipal buyers prioritize service reliability and regulatory compliance over unit cost, locking in decade-long concessions that bundle collection with disposal infrastructure.
- Collection:Door-to-door and containerized pickup services dominate municipal contracting, with São Paulo's CETESB-mandated source separation expanding separate organic waste streams. Brazilian municipalities in Minas Gerais and Paraná are consolidating fragmented district contracts into metropolitan-wide concessions to capture fleet efficiency gains.
- Recycling:Post-consumer material recovery operates under Brazil's PNRS extended producer responsibility framework, with packaging consortia financing selective collection networks. PET and aluminum streams concentrate in São Paulo and Buenos Aires metropolitan areas where informal picker integration programs secure feedstock volumes.
- Disposal:Engineered landfill operations require composite liner systems and leachate treatment infrastructure, with site permitting timelines stretching across multiple electoral cycles in Argentina's federal system.
- Treatment:Hazardous waste sterilization and stabilization services command premium pricing due to ANVISA manifesting requirements and cradle-to-grave liability exposure for industrial generators.
Volume sits with Collection; growth tilts toward Treatment as hazardous waste regulations tighten across the region.
Technology:
Capital deployment timelines compress where landfill exhaustion forces emergency procurement, favoring modular anaerobic digestion over greenfield landfill permitting.
- Landfill:Engineered disposal sites with methane capture and leachate collection systems remain the baseline infrastructure, though São Paulo state capacity constraints are accelerating site closure schedules. Existing complexes in Rio de Janeiro and Buenos Aires provinces are retrofitting biogas-to-energy systems to extend operational viability.
- Anaerobic Digestion:Wet fermentation systems processing organic fractions from source-separated municipal waste are expanding fastest in Brazil's sugarcane belt, where proximity to industrial natural gas buyers improves project returns. Paraná and São Paulo states lead deployment with feed-in tariff mechanisms.
- Incineration:Mass-burn and refuse-derived fuel combustion capacity concentrates in Chile's Santiago metropolitan area, with medical waste streams providing baseload feedstock.
- Composting:Windrow and in-vessel aerobic processing of green waste and food residuals serves agricultural offtake markets in Argentina's Córdoba and Santa Fe provinces.
Capacity concentrates in Landfill; steepest expansion trajectory belongs to Anaerobic Digestion.
End User:
Pricing power varies inversely with buyer concentration, with fragmented residential households paying regulated tariffs while consolidated industrial accounts negotiate environmental management bundles.
- Municipalities:City governments across Brazil and Argentina are exiting direct waste operations, tendering integrated concessions that transfer landfill construction risk to private operators. Buenos Aires and São Paulo metropolitan regions are consolidating district-level contracts into unified metropolitan service areas.
- Industrial:Manufacturing clusters in Rio Grande do Sul and São Paulo states generate hazardous waste streams requiring licensed treatment-storage-disposal facilities with ANVISA or federal environmental authority accreditation. Automotive and chemical sectors are consolidating vendor panels under single-source environmental management contracts.
- Commercial:Retail and hospitality generators in Santiago and Montevideo are adopting pay-as-you-throw billing structures linked to RFID bin tagging and digital weighing systems.
- Residential:Household waste generation per capita varies across income strata, with formal collection penetration incomplete in peripheral urban zones and informal settlements.
Revenue concentrates with Municipalities; margin expansion favors Industrial accounts bundling hazardous and non-hazardous streams.
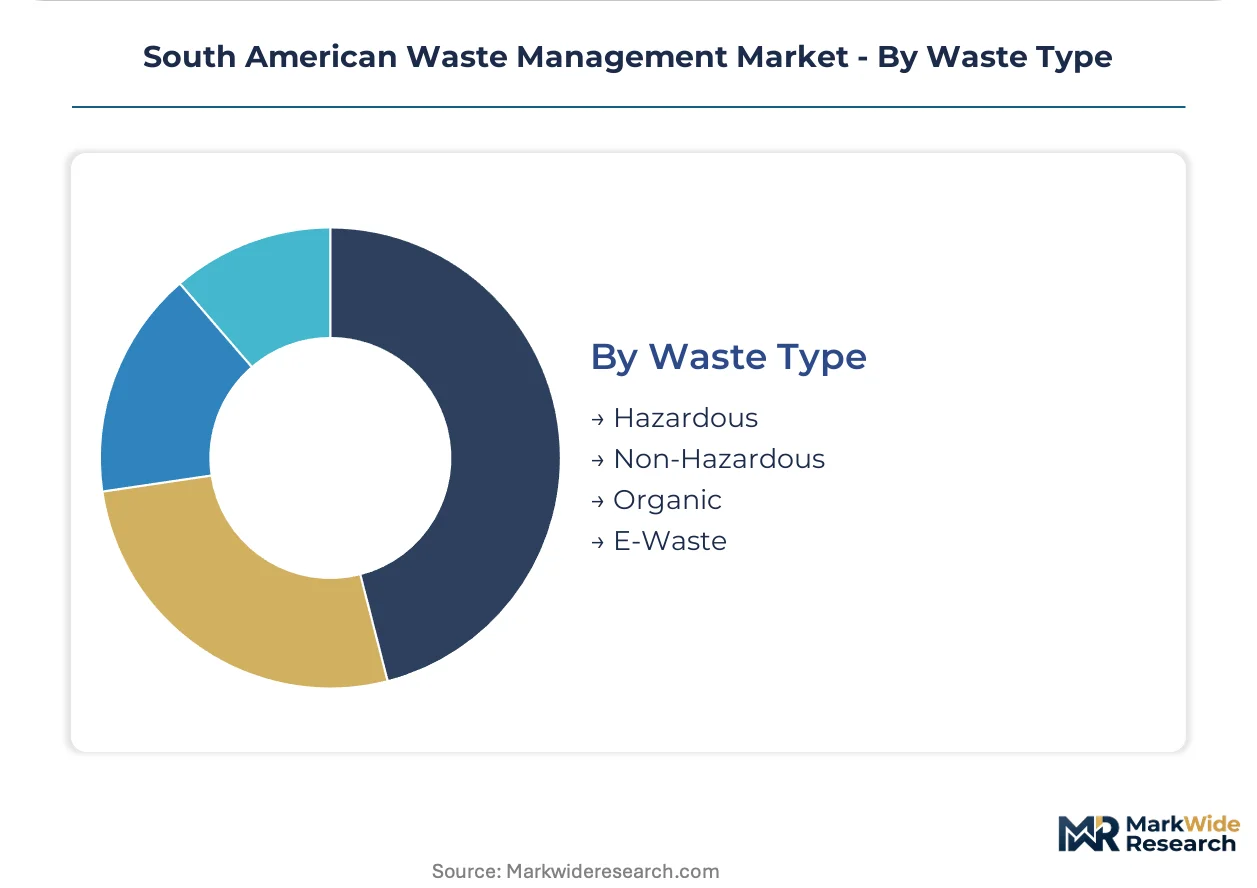
Waste Type:
Regulatory classification determines handling protocols, with hazardous designations triggering manifesting requirements and specialized treatment infrastructure investments.
- Non-Hazardous:Municipal solid waste and commercial refuse comprise the volume base, with diversion targets under Brazil's PNRS and Argentina's Federal Law on Waste Management redirecting organic fractions toward composting and anaerobic digestion. São Paulo state's leachate discharge limits are upgrading biological treatment at existing landfill complexes.
- Hazardous:Industrial chemicals, contaminated soils, and healthcare waste require autoclave, microwave, or chemical stabilization processing under ANVISA and subnational environmental agency licensing. Buenos Aires province's petrochemical corridor is consolidating treatment contracts to reduce vendor audit burdens.
- Organic:Food waste, green waste, and agricultural residues are gaining value as biogas feedstock and compost output, with source separation mandates expanding in Brazilian state capitals.
- E-Waste:Discarded electronics containing precious metals and rare earth elements are subject to emerging extended producer responsibility frameworks, with informal recovery operations competing for circuit board and battery fractions in urban peripheries.
Throughput concentrates in Non-Hazardous; regulatory intensity and pricing premiums concentrate in Hazardous.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's sugarcane belt and Argentina's Pampas grain corridor anchor feedstock availability for anaerobic digestion infrastructure, while the Andean spine shapes logistics constraints for hazardous waste transport across the continent.
Brazil
São Paulo state's landfill capacity exhaustion and CETESB leachate discharge limits are accelerating anaerobic digestion and composting investments. The National Solid Waste Policy mandates shared producer responsibility for packaging waste, creating guaranteed revenue pools for collection operators. The ABC Paulista industrial corridor and Rio de Janeiro metropolitan area concentrate hazardous waste treatment demand from petrochemical and pharmaceutical clusters.
Argentina
Buenos Aires province's petrochemical corridor generates concentrated hazardous waste streams requiring federal environmental authority accreditation under tightened cradle-to-grave manifesting rules. The Federal Law on Waste Management shapes operational licensing and landfill closure bonding requirements. Córdoba's automotive assembly plants and Santa Fe's agricultural processing zones are consolidating vendor panels under single-source environmental management contracts.
Chile
Santiago's medical waste streams provide baseload feedstock for incineration capacity concentrated in the metropolitan area. The country's extended producer responsibility frameworks for e-waste and packaging are expanding formal collection networks. Antofagasta's mining chemical residues and Valparaíso's port logistics create specialized treatment demand for contaminated soils and industrial sludge.
Colombia
Buenaventura and Tumaco lack engineered landfill capacity along the Pacific coast, creating first-mover openings for integrated waste-to-energy developers with port logistics capabilities. The national policy on integrated waste management is harmonizing municipal contracting standards. Bogotá's metropolitan area is consolidating district-level collection contracts into unified service areas to capture fleet efficiency gains.
Peru
Lima's coastal desert geography limits landfill siting options, compressing capital deployment timelines for alternative treatment infrastructure. The Ministry of Environment's regulations on hazardous waste are tightening licensing requirements for industrial generators. Callao's port complex and Arequipa's mining services cluster generate concentrated demand for chemical stabilization and contaminated soil remediation services.
South American Waste Management Market Competitive Landscape
Capacity expansion dominates the current landscape as landfill exhaustion across Brazil's southeastern corridor forces emergency procurement cycles. The market structures around three tiers: integrated national operators with landfill-to-energy footprints, specialized hazardous waste treatment firms with federal accreditation, and regional collection concessionaires locked into municipal contracts. Geographic coverage breadth and multi-license compliance capabilities determine competitive positioning. M&A activity concentrates on consolidating fragmented municipal concessions, while strategic partnerships with packaging consortia secure feedstock under extended producer responsibility frameworks.
Among Brazilian operators, Estre Ambiental exemplifies the integrated landfill-to-energy archetype with multi-state service agreements, while Solví Participações occupies a position within the specialized hazardous waste tier distinguished by treatment-storage-disposal accreditation. Cliba and Veolia Argentina represent the multinational-backed concessionaire model, anchoring metropolitan-scale contracts through technology transfer and capital access. KDM Empresas and Interaseo sit within the regional specialist category, competing on municipal relationship depth and fleet efficiency rather than vertical integration.
| Leading Market Players |
|---|
| Estre Ambiental |
| Solví Participações |
| Cliba |
| Veolia Argentina |
| KDM Empresas |
| Interaseo |
| Petramás |
| EMASEO EP |
| Companhia de Saneamento Basico do Estado de Sao Paulo |
| Others |
Value Network & Pricing Analysis
Captive liner production at Brazilian landfill operators anchors both supply security and pricing power against dollar-denominated HDPE geomembrane imports. This backward integration into composite barrier manufacturing insulates project budgets from petrochemical volatility while positioning integrated operators to bid aggressively on municipal concessions.
Pricing Analysis
Post-closure care warranties bundled into 15-20 year municipal concessions command premium pricing against spot hazardous waste treatment contracts. Three-tier pricing structure across integrated concessions, specialized industrial services, and regional collection contracts reflects liability exposure and certification grade. Cost compression in collection services is intensifying because fleet efficiency gains lag fuel price inflation. Municipal buyers exhibit lowest price sensitivity due to regulatory compliance mandates, while commercial generators adopting pay-as-you-throw models show highest elasticity.
Supply Chain Analysis
Regional distribution centers for leachate treatment chemicals and spare parts concentrate in São Paulo and Buenos Aires metropolitan hubs feeding satellite landfill complexes. HDPE geomembrane supply draws from petrochemical producers in the United States, Brazil, and the Middle East. Single-source vulnerability in specialized biogas engine components creates maintenance bottlenecks. Distribution runs through state-licensed logistics operators with hazardous waste manifesting capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's PNRS extended producer responsibility framework transforms compliance cost into a structural moat, forcing packaging consortia to finance collection infrastructure that only licensed operators can access.
For Market Incumbents: Acquire distressed municipal concessions approaching renewal to consolidate metropolitan service areas. CETESB's tightening leachate discharge limits threaten non-compliant competitors, creating acquisition targets with stranded assets. Retrofit existing landfill footprints with anaerobic digestion front-ends to capture biogas revenue streams and extend site viability against closure mandates. For New Entrants and Emerging Players: Capture healthcare waste sterilization contracts in secondary Brazilian cities where ANVISA's updated resolution is expanding mandatory autoclave requirements. Colombia's Pacific coast landfill gap offers first-mover positioning in Buenaventura and Tumaco for developers with port logistics capabilities. Partner with agricultural processors in Paraná's sugarcane belt to secure organic waste feedstock agreements ahead of anaerobic digestion buildout. For Investors and Strategic Acquirers: Exit pathways concentrate in consolidation plays for fragmented regional concessionaires lacking vertical integration. Long-term viability hinges on operators with multi-state licensing and landfill-to-energy footprints spanning the analysis window. Watch for CETESB enforcement actions against leachate violators as a signal for distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into HDPE Geomembrane Production | Captive liner manufacturing insulates Brazilian operators from dollar-denominated import exposure and polymer price volatility. |
| Anaerobic Digestion Retrofit at Existing Landfills | MBT front-ends in Minas Gerais and Paraná meet diversion targets without greenfield permitting delays. |
| Healthcare Waste Sterilization Network Expansion | ANVISA's updated resolution mandates autoclave capacity in hospital networks outside São Paulo and Rio de Janeiro. |
| Metropolitan Concession Consolidation | São Paulo and Buenos Aires district-level contract unification captures fleet efficiency gains and route optimization. |
| Digital Waste Tracking Platform Deployment | RFID bin tagging integration with CETESB reporting requirements enables pay-as-you-throw billing accuracy. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study. Primary interviews with landfill operations directors, municipal procurement officers, hazardous waste treatment facility managers, and CETESB compliance auditors combined with ANVISA resolution texts, CONAMA regulatory databases, and Brazilian customs import records. Bottom-up service contract value aggregation triangulated against top-down macroeconomic indicators.
Granularity-level modeling tracked collection, recycling, disposal, and treatment services across municipal, industrial, commercial, and residential end users. Technology segments including landfill, anaerobic digestion, incineration, and composting were projected across the analysis window with waste type splits for non-hazardous, hazardous, organic, and e-waste streams. CAGRs derived from contract renewal timelines, capacity expansion announcements, and regulatory enforcement schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Mercosur environmental protocol harmonization and electoral cycle disruptions to concession continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Wheeled Bins Market
Waste Management & Pollution Control
North America Solid Waste Management Market
Waste Management & Pollution Control
Asia Pacific Medical Waste Management Market
Waste Management & Pollution Control
Reusable Sediment Control Wattles Market
Waste Management & Pollution Control
Retail Food Waste-to-Biogas Logistics and Treatment Networks in Europe Market
Waste Management & Pollution Control
Radioactive Waste Management System Market
Waste Management & Pollution Control
Waste Recycling Services Market
Waste Management & Pollution Control
Global Automated Marine Debris Collection Equipment Market
Waste Management & Pollution Control
Waste Paper Management Market
Waste Management & Pollution Control
North America Municipal Solid Waste Management Market
Waste Management & Pollution Control
Singapore Waste Management Market
Waste Management & Pollution Control
Scrap Metal Recycling Market
Waste Management & Pollution Control
United States Trash Bags Market
Waste Management & Pollution Control
India Municipal Solid Waste Management Market
Waste Management & Pollution Control
Saudi Arabia Waste Management Market
Waste Management & Pollution Control
Industrial Waste Management Market