
 Animal Waste Incinerator Market | 2026-2036
Animal Waste Incinerator Market Size, Share, and Industry Trends Forecast 2026-2036
Animal Waste Incinerator Market Insights
After-sales maintenance contracts is expanding as the dominant revenue layer in the animal waste incinerator sector, shifting vendor economics from single-unit sales toward multi-year service agreements. Waste Spectrum Incineration Systems leverages its UK engineering base to sustain long-term parts contracts across European livestock operations. Inciner8 anchors its competitive stance through remote monitoring software that extends equipment uptime guarantees. Addfield Environmental Systems dominates the veterinary clinic channel with compact footprint designs that compete on installation speed.
Animal waste incinerators are thermal destruction systems engineered to combust organic byproducts at temperatures typically exceeding 850 degrees Celsius, reducing carcasses, bedding, and biological refuse to inert ash while neutralizing pathogens. Their primary purpose is to enforce biosecurity protocols on agricultural and veterinary premises by eliminating disease vectors without off-site transport. Batch incinerators occupy the mature installed base across small farms where intermittent throughput matches seasonal mortality patterns, while continuous incinerators lead margin pools in large integrated poultry operations that generate steady waste streams. Mobile incinerators represent the fastest-growing configuration as emergency response teams and government culling programs prioritize rapid deployment over fixed infrastructure.
The EPA enforces Maximum Achievable Control Technology standards that shape combustion chamber design and afterburner specifications for units sold into US jurisdictions. The EU's Industrial Emissions Directive and associated Best Available Techniques reference documents mandate continuous emissions monitoring, filtering market access to only certified equipment manufacturers. China's Ministry of Ecology and Environment applies GB standards that tighten particulate limits for livestock-dense provinces. Stakeholders must monitor how fragmented national approval timelines affect cross-border equipment deployment strategies.
Market Dynamics
The EPA's Maximum Achievable Control Technology standards and the EU's Industrial Emissions Directive are compressing equipment upgrade cycles across livestock-dense regions, forcing capital redeployment toward continuous monitoring systems and advanced afterburner configurations.
Growth Catalysts
- Biosecurity mandates:The USDA's National Animal Health Reporting System requirements and state-level carcass disposal regulations in Iowa, North Carolina, and Texas compel on-farm thermal destruction capacity.
- Emergency response protocols:Government culling programs for avian influenza and African swine fever outbreaks drive mobile incinerator procurement across Germany, Poland, and Vietnam.
- Emissions compliance technology:Continuous emissions monitoring systems are integrating into new unit specifications as the EU's Best Available Techniques reference documents tighten particulate thresholds.
Market Restraints
- Refractory material cost volatility:Supply concentration for high-alumina ceramics in China creates input price instability for combustion chamber manufacturers.
- Capital intensity barriers:Smallholder farms in India and Brazil face prohibitive upfront costs for certified units, limiting addressable market penetration.
- Permitting timeline friction:The EPA's Title V operating permit process and state air quality reviews extend deployment timelines by 8-14 months in US jurisdictions.
Strategic Opportunities
- Remote diagnostics convergence:IoT sensors and predictive maintenance algorithms are opening recurring revenue streams for incinerator OEMs serving distributed livestock operations.
- Veterinary clinic channel:Compact footprint designs under 500 kg capacity address underpenetrated small-animal cremation demand across Japan, South Korea, and Australia.
- Carbon accounting integration:The EU's Corporate Sustainability Reporting Directive creates demand for emissions-verified thermal destruction documentation in integrated poultry supply chains.
Industry Challenges
- Combustion engineering talent scarcity:Specialized expertise in high-temperature gasification and scrubber design concentrates among aging workforces in Germany and the United Kingdom.
- Cross-border certification complexity:Divergent approval timelines between the EPA, EU notified bodies, and China's MEE fragment equipment deployment strategies for multinational livestock corporations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal Waste Incinerator Market |
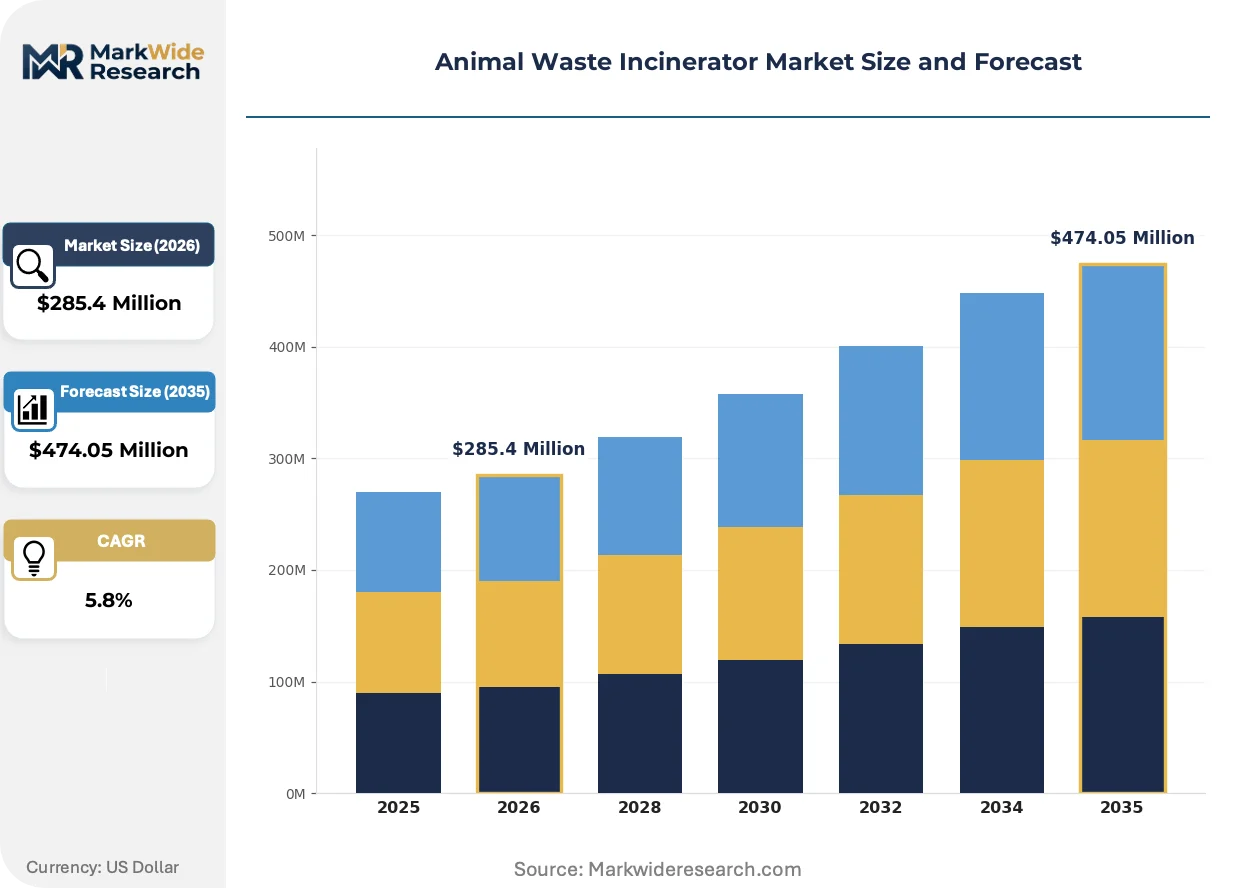
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $474.05 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Incinerator, Continuous Incinerator, Mobile Incinerator, Modular Incinerator Feedstock Type: Livestock Waste, Poultry Waste, Equine Waste, Aquaculture Waste End User: Farms, Veterinary Clinics, Zoos, Research Institutions Technology: Gasification, Pyrolysis, Direct Combustion, Indirect Combustion |
| Companies Covered | Waste Spectrum Incineration Systems, Inciner8, Scientico, HICLOVER, Firelake Manufacturing, USGR Addfield, Addfield Environmental Systems, Clover Incinerator, Matthews Environmental Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal Waste Incinerator Market Trends and Innovations
Active thermal destruction technologies are converging with digital monitoring platforms and circular economy frameworks, compressing equipment lifecycles while expanding service revenue attachment rates.
Advanced ceramic fiber insulation systems are integrating alumina-silica composite linings that reduce heat loss by one-third compared to traditional refractory brick. Large integrated poultry operators in the United States and Netherlands are specifying these materials for continuous-feed units running 20-hour cycles. This materials shift is integrating energy recovery modules into standard configurations, enabling waste heat capture for facility heating.
The EU's Industrial Emissions Directive 2010/75/EU and its 2023 Best Available Techniques review are mandating real-time stack monitoring for all units above 50 kg/hour throughput. Equipment manufacturers must now pre-certify control systems with notified bodies before market entry. Poultry and swine operations in Denmark, Spain, and Italy face the steepest retrofit obligations, compressing replacement demand into 2024-2027.
After-sales service contracts are displacing transactional equipment sales as the primary revenue anchor. Livestock integrators in Germany and China now demand 10-year parts availability guarantees and remote diagnostics inclusion. Veterinary clinic chains across France and Canada are consolidating procurement through single-source maintenance agreements rather than capital purchase models.
Animal Waste Incinerator Market Segmentation
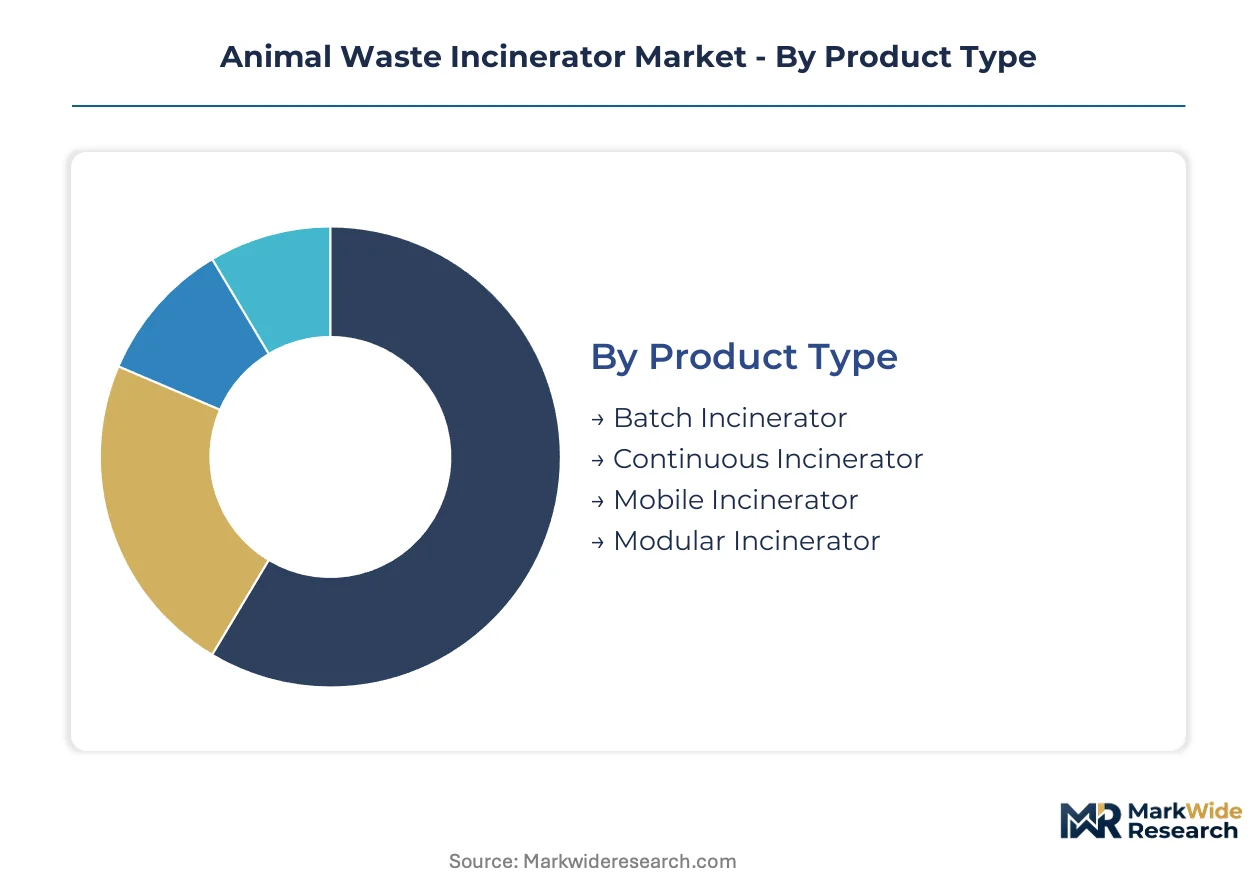
Animal waste incinerator procurement patterns diverge sharply across operational scales and waste stream characteristics. Technology selection, feedstock composition, and end-user regulatory exposure collectively determine equipment specifications and vendor matching.
Product Type:
Thermal destruction systems vary by throughput architecture and deployment flexibility, with chamber design dictating capital intensity and operating economics.
- Batch Incinerator:Intermittent combustion cycles process discrete loads through refractory-lined chambers with manual loading systems. Small farms in Iowa and Texas favor these units for seasonal mortality peaks where daily throughput stays below 500 kg.
- Continuous Incinerator:Automated feed mechanisms maintain steady combustion temperatures for 16-20 hour operating cycles. Large integrated poultry operators in North Carolina and the Netherlands specify these for biosecurity-critical facilities with constant waste generation.
- Mobile Incinerator:Trailer-mounted units enable rapid deployment to outbreak sites without fixed infrastructure. Government veterinary services in Germany and Poland procure these for emergency culling protocols under EU animal health directives.
- Modular Incinerator:Scalable chamber configurations allow capacity expansion through parallel unit installation. Livestock cooperatives in Denmark deploy these to match herd growth trajectories without full system replacement.
Continuous incinerators lead on scale; mobile incinerators lead on momentum.
Feedstock Type:
Waste composition determines combustion temperature requirements, ash handling systems, and emissions control specifications.
- Livestock Waste:Bovine and swine carcasses with high moisture content demand extended dwell times at 850-1000°C. Cattle feedlots in Texas and dairy operations in Wisconsin drive specification standards for heavy-duty grate systems.
- Poultry Waste:Lower moisture and higher fat content enable faster combustion cycles with reduced auxiliary fuel needs. Broiler integrators in Georgia and Arkansas specify compact units optimized for feather and viscera processing.
- Equine Waste:Large carcass dimensions require oversized primary chambers and specialized loading equipment. Thoroughbred breeding facilities in Kentucky and racehorse veterinary hospitals in Japan drive demand for high-capacity batch configurations.
- Aquaculture Waste:Fish mortalities with unique protein decomposition profiles necessitate corrosion-resistant chamber materials. Salmon farming operations in Norway and shrimp producers in Vietnam are expanding thermal destruction capacity for disease containment.
Poultry waste dominates unit volume; aquaculture waste shows the steepest expansion trajectory.
End User:
Procurement authority and regulatory exposure shape purchasing criteria across facility types.
- Farms:Owner-operated livestock facilities prioritize capital efficiency and minimal permitting complexity. Family-owned hog operations in North Carolina and cattle ranches in Nebraska represent the core installed base for entry-level batch units.
- Veterinary Clinics:Small-animal hospitals and equine surgical centers require odor containment and rapid cycle completion. Clinic chains across France and Canada are consolidating procurement through single-source maintenance agreements.
- Zoos:Exotic species mortality management demands pathogen-neutralization assurance for public health authorities. AZA-accredited facilities in California and Texas specify EPA-compliant units with documented destruction temperatures.
- Research Institutions:Biocontainment laboratories and agricultural universities require validated sterilization documentation for audit trails. USDA research stations and veterinary colleges in Georgia and Kansas drive demand for data-logging integration.
Farms anchor procurement volume; veterinary clinics are shifting fastest toward service-based acquisition models.
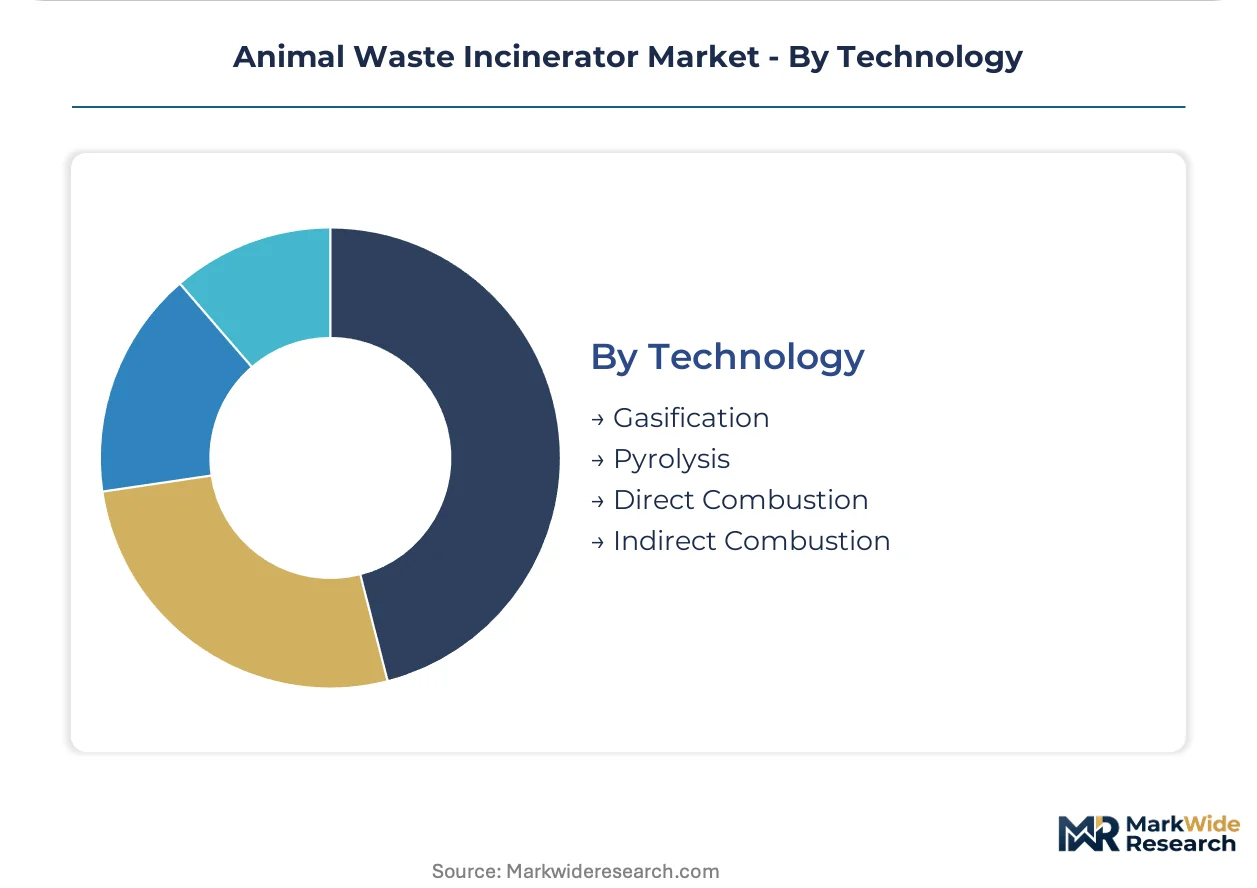
Technology:
Combustion chemistry and heat transfer mechanisms determine efficiency profiles and regulatory compliance pathways.
- Gasification:Partial oxidation in oxygen-starved environments produces syngas for secondary combustion. Advanced livestock operations in Germany pilot these systems for potential energy recovery integration under EU circular economy frameworks.
- Pyrolysis:Thermal decomposition in absence of oxygen yields biochar and combustible vapors. Research applications in agricultural universities explore this pathway for carbon sequestration documentation.
- Direct Combustion:Excess-air oxidation remains the dominant configuration for pathogen destruction assurance. EPA Maximum Achievable Control Technology standards shape afterburner specifications for US-market units.
- Indirect Combustion:Heat exchanger separation of flue gas from combustion air enables specialized waste stream handling. Pharmaceutical research facilities specify these for contaminated bedding destruction with minimal atmospheric release.
Direct combustion commands installed base dominance; gasification gains share fastest among sustainability-focused operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany enforces stricter emissions monitoring than the United States, while China concentrates livestock density in provinces with evolving environmental standards. Regulatory divergence across these three markets shapes equipment specification requirements and vendor certification timelines.
United States
Integrated poultry operations in North Carolina and Georgia drive continuous incinerator procurement for biosecurity-critical facilities. EPA Maximum Achievable Control Technology standards mandate afterburner specifications and Title V operating permits that extend deployment timelines. Cattle feedlots in Texas and dairy clusters in Wisconsin anchor demand for heavy-duty batch configurations.
Germany
Large livestock cooperatives in Lower Saxony and Bavaria specify modular incinerator systems to match herd expansion trajectories. The EU Industrial Emissions Directive and 2023 Best Available Techniques review mandate real-time stack monitoring for units above 50 kg/hour throughput. Government veterinary services maintain mobile incinerator fleets for emergency culling protocols under animal health directives.
China
Provincial livestock density in Shandong and Sichuan provinces generates steady waste streams requiring thermal destruction capacity. Ministry of Ecology and Environment GB standards tighten particulate limits in livestock-dense regions, filtering market access to certified manufacturers. Integrated pork producers in Guangdong pilot gasification systems for potential energy recovery integration.
Netherlands
Intensive poultry operations in Gelderland and North Brabant specify continuous-feed units with advanced ceramic fiber insulation for 20-hour operating cycles. EU Corporate Sustainability Reporting Directive creates demand for emissions-verified thermal destruction documentation in integrated supply chains. Wageningen agricultural research clusters explore pyrolysis pathways for carbon sequestration validation.
Poland
Emergency response teams procure trailer-mounted mobile units for rapid deployment to avian influenza outbreak sites. EU animal health directives govern procurement specifications for government veterinary services. Swine production concentration in Greater Poland Voivodeship drives demand for pathogen-neutralization capacity without off-site transport.
Animal Waste Incinerator Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with engineering-intensive configurations favoring established incumbents while standardized units attract fabrication competitors. The vendor base organizes into three tiers: full-service OEMs with certification capabilities, regional fabricators serving price-sensitive agricultural markets, and emergency-response specialists optimizing for deployment speed. Consolidation pressure concentrates among mid-scale European manufacturers seeking geographic coverage expansion. Technology licensing agreements and multi-year service contract structures represent the dominant competitive moves reshaping vendor economics.
Within the full-service OEM tier, Waste Spectrum Incineration Systems and Inciner8 occupy positions exemplifying divergent strategic anchors. Waste Spectrum leverages UK engineering heritage to sustain long-term parts contracts across European livestock operations. Inciner8 represents the remote diagnostics convergence archetype through software-enabled uptime guarantees. Among veterinary clinic specialists, Addfield Environmental Systems sits within the compact footprint design segment competing on installation speed. These three companies illustrate how vendor positioning stratifies across service attachment models, geographic certification breadth, and end-user scale specialization.
| Leading Market Players |
|---|
| Waste Spectrum Incineration Systems |
| Inciner8 |
| Scientico |
| HICLOVER |
| Firelake Manufacturing |
| USGR Addfield |
| Addfield Environmental Systems |
| Clover Incinerator |
| Matthews Environmental Solutions |
| Others |
Pricing and Supply Chain Analysis
Advanced ceramic fiber insulation systems are displacing traditional refractory brick across continuous-feed configurations, simultaneously compressing heat-loss coefficients and concentrating procurement leverage among alumina-silica composite suppliers in China and Germany. This materials transition is reshaping cost economics for combustion chamber manufacturers while creating tiered input dependencies that stratify equipment pricing across certification levels.
Pricing Analysis
Capacity additions in China's refractory ceramics sector are reshaping price floors for combustion chamber linings, though EPA and EU certification tiers maintain differentiation premiums. Three-tier pricing structure across EPA-compliant, CE-marked, and uncertified economy levels separates livestock integrators from smallholder farms. Cost compression in the economy tier is intensifying because regional fabricators in India and Brazil compete on stripped-down afterburner specifications. Veterinary clinic chains exhibit lowest price sensitivity due to bundled maintenance demands, while family-owned cattle operations in Nebraska and Texas anchor the most price-elastic segment.
Supply Chain Analysis
Single-source vulnerability sits with high-alumina ceramic production concentrated in Shandong province, Henan province, and selected German industrial clusters. Combustion chamber fabrication draws from specialty steel grades, precision burner assemblies, and emissions monitoring sensors. Tariff exposure on Chinese refractory exports to US and EU jurisdictions threatens margin stability for OEMs without captive supply arrangements. Distribution runs through certified equipment dealers serving livestock-dense counties, with aftermarket parts contracts increasingly dislodging transactional equipment sales as the dominant revenue anchor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
After-sales service attachment and remote diagnostics integration are expanding margin pools beyond equipment sales, justifying premium-tier positioning through predictive maintenance algorithms that reduce livestock operator downtime costs.
For Market Incumbents: Acquire specialized IoT sensor engineering teams to fortify predictive maintenance capabilities against emerging software-native entrants. Cement multi-year parts availability guarantees with German and Chinese livestock cooperatives to lock out regional fabricators. Prioritize EPA pre-certification investments to compress deployment timelines against competitors facing Title V permitting friction. For New Entrants and Emerging Players: Enter via compact veterinary clinic configurations under 500 kg capacity across Japan, South Korea, and Australia where installation speed outweighs brand heritage. Target aquaculture waste processing in Norway and Vietnam, where corrosion-resistant chamber specifications remain underpenetrated by incumbent poultry-optimized designs. Lead with subscription-based maintenance models rather than capital sales to bypass incumbent financing relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale European manufacturers lacking remote diagnostics capabilities but holding CE certification breadth. Five-to-ten-year viability hinges on service revenue attachment rates displacing equipment transaction dependency. Watch mobile incinerator procurement spikes from government veterinary services as inflection indicators for emergency-response specialization premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Remote Diagnostics Platform Launch | Inciner8's software-enabled uptime guarantees establish recurring revenue benchmarks across European livestock operations. |
| CE Pre-Certification Investment | EU Industrial Emissions Directive compliance filters market access to notified-body-approved equipment manufacturers. |
| Ceramic Fiber Insulation Backward Integration | Waste Spectrum's UK engineering base secures captive supply of alumina-silica composites for long-term parts contracts. |
| Veterinary Clinic Channel Consolidation | Addfield's compact footprint designs capture clinic chain procurement shifting toward single-source maintenance agreements. |
| Mobile Unit Fleet Expansion | Government culling programs in Germany and Poland prioritize rapid-deployment configurations for avian influenza response. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with livestock operations managers, veterinary clinic procurement leads, incinerator OEM technical directors, and aftermarket service heads with secondary validation against EPA Title V permit databases, EU ETS emissions registries, and Chinese MEE GB standard filings. Bottom-up equipment shipment tallies and top-down thermal destruction capacity estimates were triangulated across the analysis window.
Historical reference periods anchored volume and value projections across the modeling period, with segmentation dimensions spanning product architecture, feedstock moisture content, end-user regulatory exposure, and combustion technology chemistry. CAGRs were derived from fitted growth curves applied to livestock density trajectories and biosecurity mandate enforcement timelines, incorporating refractory material cost indices and permitting timeline distributions as industry-specific forecast inputs.
Inputs from regulatory filing databases and equipment certification registries were available through the study window; gaps in smallholder farm informal disposal volumes and unreported emergency culling deployments introduce uncertainty bands around mobile incinerator demand estimates. Forecasts reflect underlying assumptions about EPA and EU enforcement continuity and ceramic fiber insulation adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
UAE Industrial Waste Management Market
Waste Management & Pollution Control
North America Waste Recycling Services Market
Waste Management & Pollution Control
Industrial Waste Management Market
Waste Management & Pollution Control
Asia Pacific Medical Waste Management Market
Waste Management & Pollution Control
Construction Waste Management Market
Waste Management & Pollution Control
Alkaline Solid Waste Market
Waste Management & Pollution Control
Global Automated Marine Debris Collection Equipment Market
Waste Management & Pollution Control
India Waste-To-Energy Market
Waste Management & Pollution Control
Global Waste Disposal Equipment Market
Waste Management & Pollution Control
Wood Recycling Market
Waste Management & Pollution Control
Waste Recycling Services Market
Waste Management & Pollution Control
Waste Management Market
Waste Management & Pollution Control
Global Waste Management Equipment Market
Waste Management & Pollution Control
APAC Bio-Medical Waste Management Market
Waste Management & Pollution Control
Hazardous Waste Management Market
Waste Management & Pollution Control
Automated Waste Collection System (AWCS) Market