
 North America Industrial Waste Management Market | 2026-2036
North America Industrial Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
North America Industrial Waste Management Market Insights
A shortage of certified hazardous waste technicians is redrawing competitive boundaries across the North America industrial waste management landscape. Waste Management Inc leverages its national landfill network and rail-served disposal assets to sustain volume leadership in high-BTU industrial streams. Republic Services Inc anchors its position through integrated collection and recycling infrastructure serving Midwest manufacturing belts. Clean Harbors Inc specializes in complex remediation and emergency response capabilities that differentiate its service portfolio from commodity-oriented competitors.
Industrial waste management encompasses the systematic handling, treatment, and disposal of byproducts generated by manufacturing, energy production, and construction activities, with operations governed by waste characterization protocols, manifest documentation, and thermal destruction efficiency thresholds exceeding 99.99% for principal organic hazardous constituents. The primary purpose centers on ensuring regulatory compliance while minimizing environmental liability and recovering secondary materials for reintroduction into production cycles. Non-hazardous waste collection and disposal occupies the largest revenue share due to sheer volume scale across manufacturing and construction end users, though hazardous waste treatment commands premium pricing power tied to EPA permitting scarcity and specialized infrastructure requirements. Recycling services represent the fastest-expanding service type as extended producer responsibility frameworks and raw material cost volatility push industrial generators toward circular feedstock strategies.
EPA RCRA subtitle C requirements, DOT hazardous materials transportation rules, and OSHA process safety management standards collectively shape operational compliance burdens and capital deployment decisions across the value chain. The US regulatory framework mandates cradle-to-grave liability chains that favor vertically integrated service providers with permitted treatment, storage, and disposal facility networks. Canadian federal and provincial environmental regulations, including Ontario's Waste Diversion Act and British Columbia's extended producer responsibility programs, add cross-border complexity for multi-jurisdictional operators. Stakeholders must monitor emerging per- and polyfluoroalkyl substances designation decisions and corresponding treatment technology investments that will determine next-generation competitive positioning in the industrial waste services landscape.
Market Dynamics
EPA's tightening cradle-to-grave tracking under RCRA Subtitle C is forcing hazardous waste generators across Texas and Louisiana petrochemical corridors to consolidate vendor relationships with vertically integrated service providers possessing permitted treatment, storage, and disposal infrastructure.
Growth Catalysts
- RCRA Subtitle C enforcement:Stricter manifest documentation requirements are pushing chemical manufacturers toward outsourced waste handling contracts with full-service environmental firms.
- Petrochemical corridor expansion:Gulf Coast facility buildouts are generating concentrated demand for high-BTU industrial stream processing and rail-served disposal assets.
- Circular feedstock mandates:Extended producer responsibility frameworks in Ontario and British Columbia are accelerating industrial generator adoption of recycling services over landfill disposal.
Market Restraints
- Permitted TSDF scarcity:EPA licensing bottlenecks for new hazardous waste treatment facilities constrain capacity additions despite rising generator volumes.
- Specialized labor shortages:Certified hazardous waste technician pipelines cannot match retirement rates across US Gulf Coast and Canadian industrial zones.
- PFAS treatment uncertainty:Pending EPA designation decisions for per- and polyfluoroalkyl substances are freezing capital deployment for next-generation destruction technologies.
Strategic Opportunities
- Midwest manufacturing belt penetration:Integrated collection and recycling infrastructure remains underdeveloped across Ohio, Michigan, and Indiana industrial corridors.
- Pyrolysis-oxidation convergence:Advanced thermal destruction systems combining plasma arc with rotary kiln designs are opening hazardous waste volume previously deemed non-treatable.
- Carbon border adjustment alignment:EU CBAM compliance requirements for US exporters are creating demand for verified waste diversion documentation and circularity certification.
Industry Challenges
- Technician certification pipelines:OSHA process safety management training programs cannot produce qualified hazardous waste operators at the pace of facility retirements.
- Legacy manifest system integration:Paper-based tracking infrastructure at smaller generators creates data reconciliation friction with electronic reporting mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Industrial Waste Management Market |
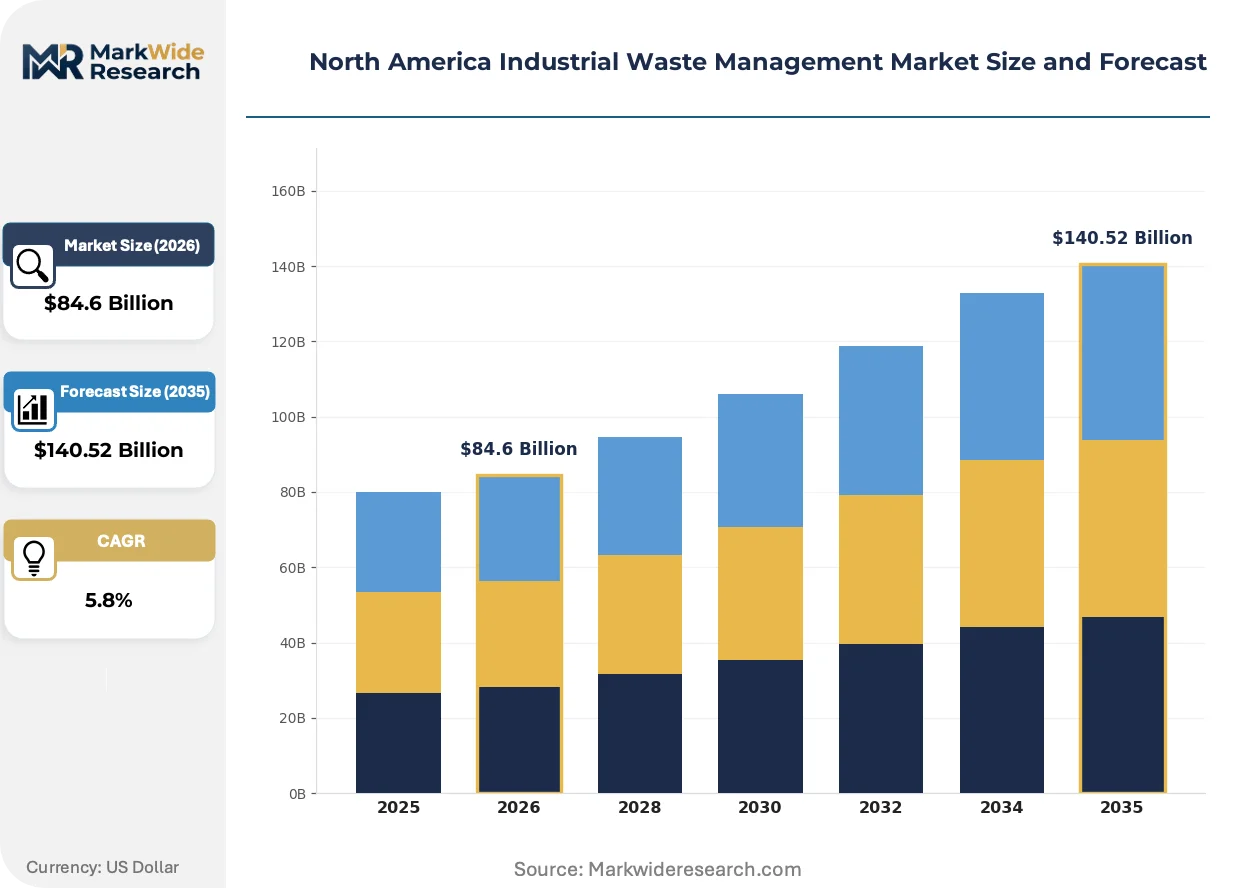
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $140.52 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Waste Type: Hazardous Waste, Non-Hazardous Waste, E-Waste, Medical Waste Service Type: Collection, Treatment, Recycling, Disposal End User: Manufacturing, Construction, Healthcare, Energy Technology: Incineration, Landfilling, Composting, Anaerobic Digestion |
| Companies Covered | Waste Management Inc, Republic Services Inc, Veolia North America, Waste Connections Inc, Clean Harbors Inc, Stericycle Inc, GFL Environmental Inc, Casella Waste Systems Inc, Rumpke Waste & Recycling, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Industrial Waste Management Market Trends and Innovations
Digital tracking platforms and advanced thermal processing systems are restructuring how industrial generators select and retain waste service partners across North American manufacturing belts.
Plasma arc gasification is supplanting traditional rotary kiln incineration for complex organic hazardous constituents requiring destruction and removal efficiency above 99.99%. Petrochemical facilities in Texas and Louisiana are piloting these systems at scale. The technology is compressing acceptable waste feedstock specifications and enabling on-site treatment that reduces transportation liability exposure.
EPA's emerging PFAS hazardous substance designation under CERCLA is forcing treatment facility operators to invest in precursor destruction capabilities ahead of formal rulemaking. Industrial laundries and metal finishers in the Great Lakes region face the steepest compliance cost escalations. These sectors are accelerating vendor consolidation to secure guaranteed offtake capacity.
Service unbundling is fragmenting traditional full-service contracts as large generators separate collection, transportation, and treatment procurement to optimize unit economics. Automotive and aerospace manufacturers in the US Southeast are driving this pattern most aggressively. Third-party logistics providers are capturing transportation segments previously held by integrated environmental service firms.
North America Industrial Waste Management Market Segmentation
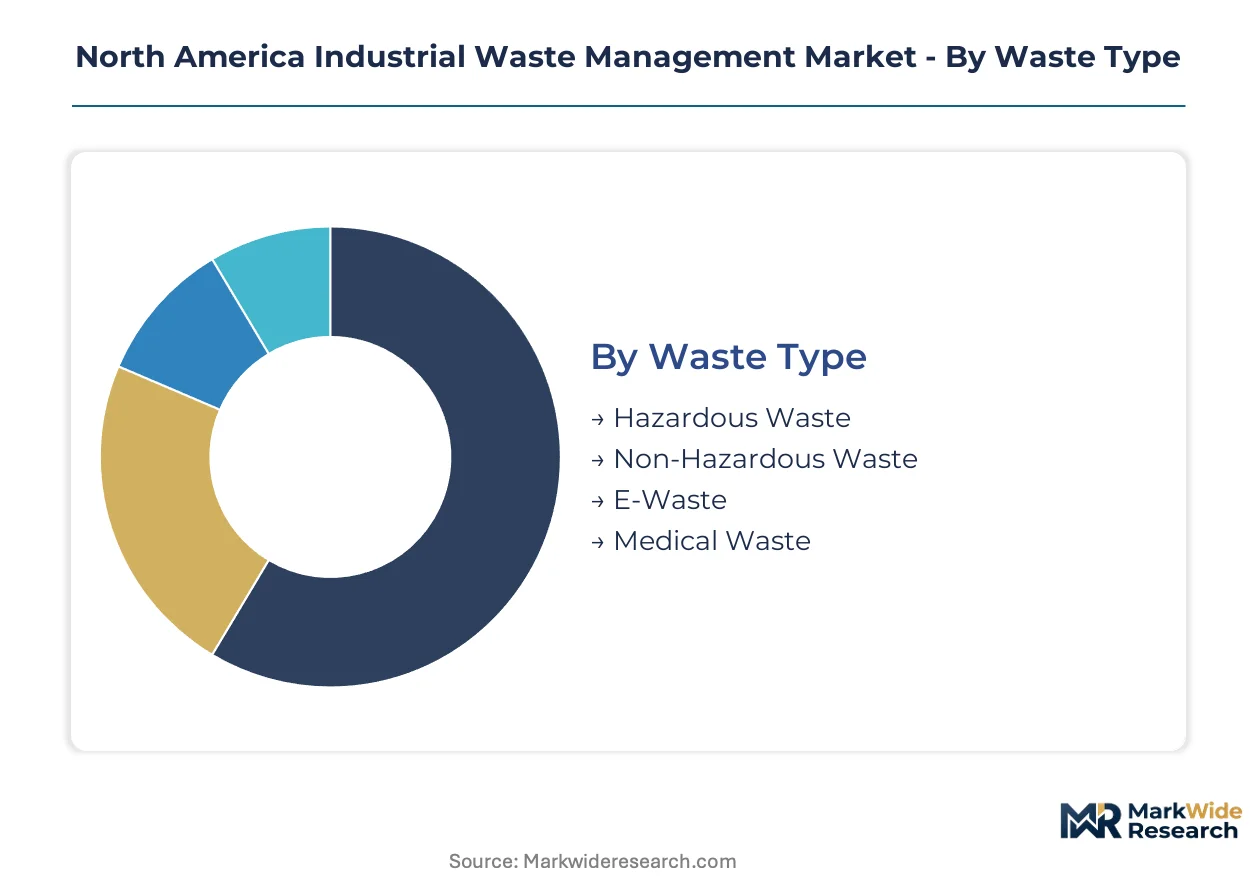
Industrial waste management segmentation reveals distinct margin architectures across waste streams, service modalities, and technology platforms. Each category carries unique regulatory compliance burdens and capital intensity profiles that reshape competitive positioning.
Waste Type:
Highest margin capture concentrates in streams requiring specialized handling certifications and cradle-to-grave liability chains.
- Hazardous Waste:Corrosive, flammable, reactive, and toxic byproducts from chemical manufacturing and metal finishing operations. Demand clusters along the Texas-Louisiana petrochemical corridor where EPA RCRA Subtitle C enforcement is tightening manifest documentation requirements.
- Non-Hazardous Waste:Industrial sludge, packaging debris, and construction debris lacking hazardous characteristics under EPA definitions. Manufacturing belts across Ohio, Michigan, and Indiana generate volume scale that supports integrated collection and recycling infrastructure investments.
- E-Waste:Discarded electronic equipment and circuit board assemblies containing recoverable precious metals and rare earth elements.
- Medical Waste:Biohazardous materials from hospitals, laboratories, and pharmaceutical manufacturing requiring sterilization or thermal destruction.
The dominant share belongs to Non-Hazardous Waste, while E-Waste is closing the gap fastest.
Service Type:
Revenue concentration tracks capital intensity gradients, with asset-heavy treatment and disposal commanding premium pricing over logistics-dependent collection.
- Collection:Scheduled pickup, container provisioning, and transportation logistics connecting generator sites to downstream processing facilities. Third-party logistics providers are capturing segments previously held by integrated environmental service firms as large generators unbundle procurement.
- Treatment:Chemical stabilization, thermal destruction, and biological processing to neutralize hazardous characteristics or reduce waste volume. EPA permitting scarcity for new treatment, storage, and disposal facilities constrains capacity expansion despite rising generator volumes across the US Gulf Coast.
- Recycling:Material recovery and feedstock reprocessing for reintroduction into manufacturing cycles.
- Disposal:Final placement in permitted landfills, surface impoundments, or injection wells.
Treatment commands the steepest pricing power, while Recycling is expanding most quickly.
End User:
Demand patterns diverge sharply between continuous-process manufacturing and project-based construction waste generation.
- Manufacturing:Systematic byproduct streams from assembly operations, chemical synthesis, and metal fabrication. Automotive and aerospace producers in the US Southeast are driving service unbundling patterns that separate collection, transportation, and treatment procurement.
- Construction:Debris from demolition, renovation, and new build activities including concrete, wood, and insulation materials. Project cyclicality and site dispersion create logistics complexity that favors regional collection networks over national scale operators.
- Healthcare:Hospitals, clinics, and pharmaceutical manufacturing generating regulated medical waste streams.
- Energy:Power generation facilities and oil and gas operations producing combustion residuals and drilling wastes.
Manufacturing anchors volume leadership, while Energy is gaining share fastest.
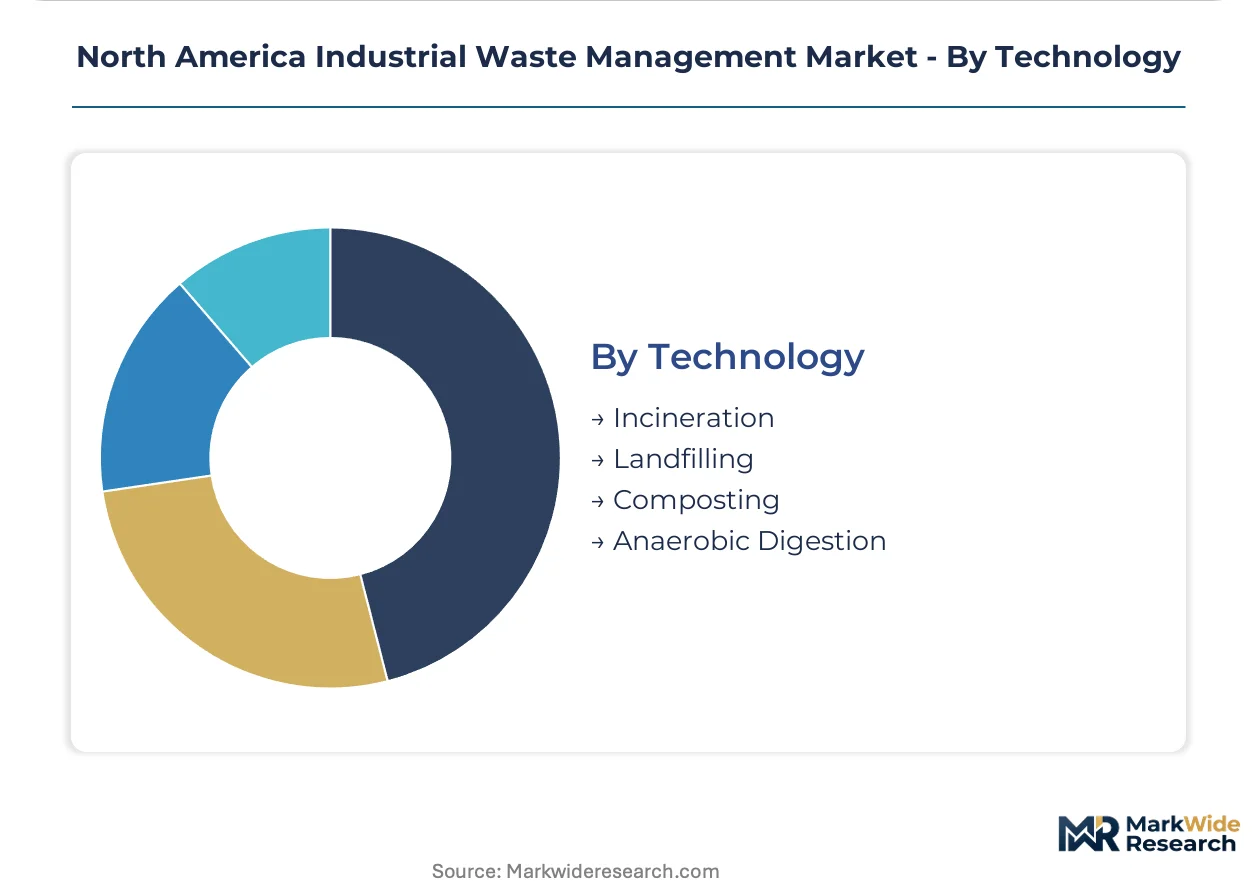
Technology:
Capital deployment tilts toward thermal destruction systems achieving destruction and removal efficiency above 99.99% for principal organic hazardous constituents.
- Incineration:Rotary kiln and plasma arc gasification systems for hazardous organic constituents. Petrochemical facilities in Texas and Louisiana are piloting plasma arc systems at scale to enable on-site treatment that reduces transportation liability exposure.
- Landfilling:Engineered disposal cells with leachate collection and groundwater monitoring systems. Permitted hazardous waste landfill capacity scarcity across the US Gulf Coast is forcing generators toward rail-served remote disposal assets.
- Composting:Aerobic biological decomposition of organic industrial residuals.
- Anaerobic Digestion:Microbial processing in oxygen-free environments producing biogas from organic waste streams.
Landfilling retains the dominant share, while Incineration is climbing the fastest on advanced thermal system deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA enforcement of RCRA Subtitle C cradle-to-grave tracking requirements is redrawing operational boundaries across the United States, while Canadian provincial extended producer responsibility programs and Mexican industrial zone regulations add cross-border complexity for multi-jurisdictional operators.
United States
Chemical manufacturing expansions along the Texas-Louisiana petrochemical corridor are generating concentrated demand for high-BTU industrial stream processing. EPA's tightening manifest documentation requirements under RCRA Subtitle C favor vertically integrated service providers with permitted treatment, storage, and disposal facility networks. Houston and Lake Charles anchor hazardous waste volume generation, with rail-served disposal assets becoming critical for managing transportation liability exposure.
Canada
Ontario's Waste Diversion Act and British Columbia's extended producer responsibility programs are accelerating industrial generator adoption of recycling services over landfill disposal. Provincial environmental regulations create compliance complexity for operators serving manufacturing belts across the Great Lakes region. The Sarnia-Lambton petrochemical complex and Vancouver industrial port zones concentrate demand for specialized hazardous waste handling certifications.
Mexico
Manufacturing growth in Nuevo León and the Bajío Region is expanding non-hazardous industrial waste volumes from automotive and aerospace assembly operations. Federal environmental regulations under SEMARNAT are gradually aligning with US manifest documentation standards for cross-border waste movements. Monterrey and Querétaro industrial corridors are attracting integrated collection infrastructure investments from North American service providers.
North America Industrial Waste Management Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the North America industrial waste management structure. National-scale operators leverage permitted landfill networks and rail-served disposal assets to capture high-BTU industrial streams, while regional specialists compete on emergency response capabilities and complex remediation expertise. Three archetypes dominate: vertically integrated full-service firms, commodity-focused collection and disposal operators, and technical specialists in hazardous waste treatment. Consolidation through asset acquisitions and strategic partnerships for technology licensing represent the primary competitive vectors reshaping market boundaries.
Among integrated environmental service firms, Waste Management Inc, Republic Services Inc, and Clean Harbors Inc exemplify distinct positioning archetypes. Waste Management Inc represents the scale-driven national network model with extensive landfill and rail infrastructure. Republic Services Inc anchors the integrated collection-recycling orientation serving manufacturing density corridors. Clean Harbors Inc occupies the technical specialization tier focused on complex remediation and emergency response capabilities that command premium pricing outside commodity waste streams.
| Leading Market Players |
|---|
| Waste Management Inc |
| Republic Services Inc |
| Veolia North America |
| Waste Connections Inc |
| Clean Harbors Inc |
| Stericycle Inc |
| GFL Environmental Inc |
| Casella Waste Systems Inc |
| Rumpke Waste & Recycling |
| Others |
Pricing and Supply Chain Analysis
Ninety-day inventory cycles for specialized hazardous waste containers concentrate pricing power among EPA-permitted treatment, storage, and disposal facility operators in Texas and Louisiana. This lead-time compression reinforces contract-based long-term offtake structures while squeezing spot-market flexibility for petrochemical generators facing cradle-to-grave liability exposure.
Pricing Analysis
Price spreads between Gulf Coast and Midwest industrial corridors exceed transportation cost differentials alone, reflecting EPA permitting scarcity premiums in concentrated petrochemical zones. Contract-based long-term offtake dominates, with pricing stratifying across certified hazardous, non-hazardous industrial, and recycling recovery tiers. Cost compression in non-hazardous collection is intensifying because third-party logistics unbundling fragments volume consolidation. Small and mid-sized metal finishers exhibit highest price sensitivity, while integrated chemical manufacturers prioritize liability transfer over unit cost minimization.
Supply Chain Analysis
Port congestion at Houston and Corpus Christi elevates inbound logistics costs for specialized thermal destruction equipment and hazardous waste container fleets sourced from Germany, Japan, and South Korea. The supply chain draws from precision manufacturing hubs in these countries for plasma arc gasification components and rotary kiln refractory systems. Single-source vulnerability concentrates in EPA-certified equipment fabricators with limited North American licensing partnerships. Distribution runs through rail-served disposal assets connecting Gulf Coast generation clusters to permitted landfill networks in Texas, Louisiana, and remote western sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
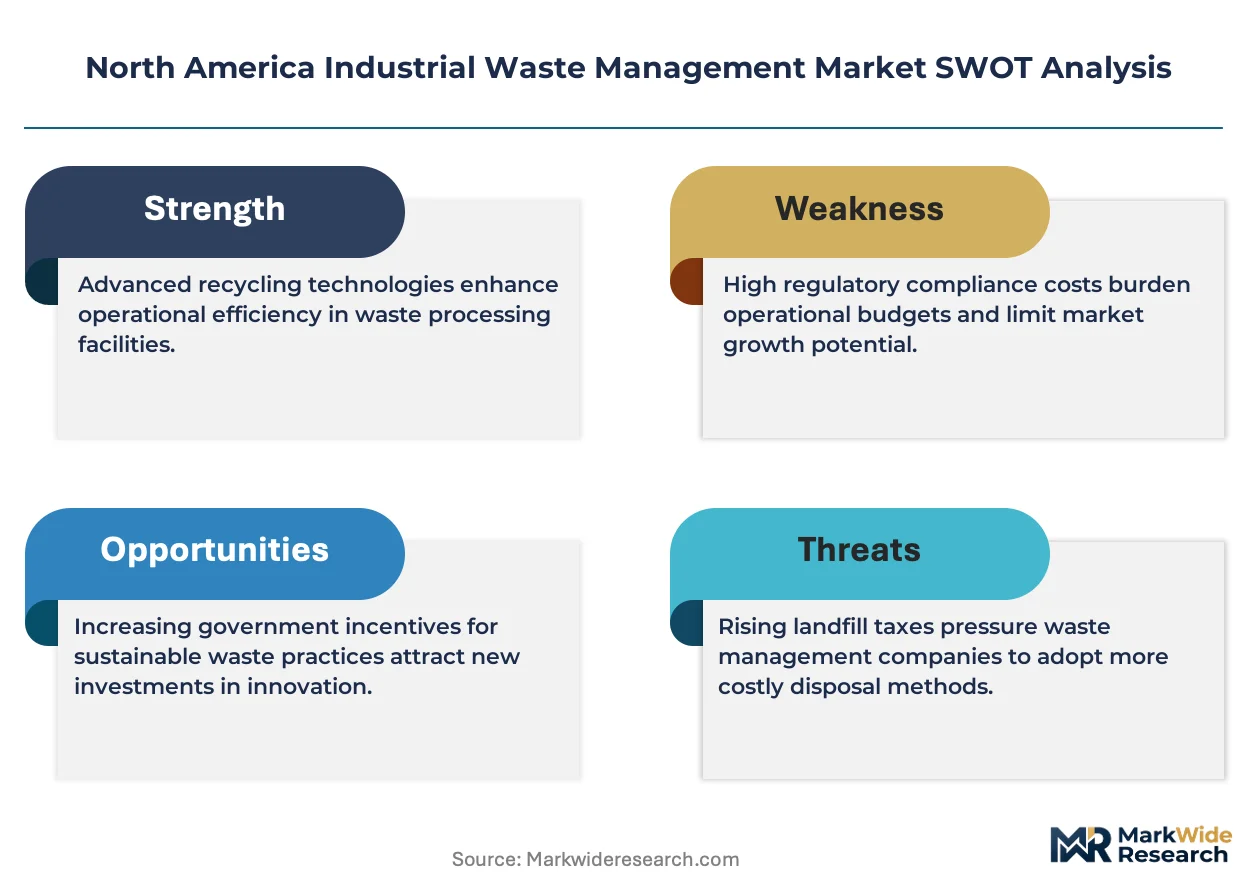
On-site treatment technologies threaten traditional transportation-dependent service models, forcing incumbents to defend substitution risk through asset repositioning and capability acquisition.
For Market Incumbents: Consolidate permitted treatment capacity in the Texas-Louisiana corridor to capture expanding petrochemical generator volumes under tightening RCRA Subtitle C enforcement. Acquire certified hazardous waste technician training pipelines to offset retirement-driven labor scarcity. Plasma arc gasification deployment represents the critical capability lever for defending high-BTU industrial stream market share against on-site treatment substitution.
For New Entrants and Emerging Players: Midwest manufacturing belt collection infrastructure gaps offer white-space entry points across Ohio, Michigan, and Indiana industrial corridors. Target under-served automotive and aerospace generators in the US Southeast where service unbundling separates transportation from treatment procurement. Partner with third-party logistics providers to capture fragmented collection segments without capital-intensive TSDF investments.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat infrastructure play because EPA permitting scarcity creates durable barriers against capacity expansion despite rising generator demand. Acquisition targets should emphasize permitted landfill networks with rail access and existing hazardous waste certifications. Monitor EPA PFAS designation timing as the critical inflection signal for next-generation destruction technology deployment requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Additional permitted TSDF capacity in Gulf Coast corridor captures concentrated petrochemical generator demand growth. |
| Backward Integration | In-house plasma arc gasification equipment manufacturing reduces dependency on German and Japanese component suppliers. |
| Green Manufacturing Transition | Circular feedstock certification aligns with Ontario and British Columbia extended producer responsibility compliance requirements. |
| Long-term Supply Agreement | Rail-served disposal contracts with Texas-Louisiana chemical manufacturers lock in high-BTU waste stream volumes. |
| Joint Venture | Technology partnerships with European thermal destruction specialists accelerate PFAS-capable system deployment ahead of EPA rulemaking. |
Research Methodology
Cross-validation between EPA enforcement action databases and state-level waste manifest filings anchors the qualitative findings in documented regulatory compliance patterns. Primary interviews with hazardous waste facility operators, petrochemical plant EHS managers, and rail logistics coordinators combine with secondary validation through EPA RCRAInfo system extracts, DOT hazardous materials incident reports, and SEC 10-K disclosures from publicly traded environmental services firms. Bottom-up generator volume estimates and top-down service provider revenue triangulation establish market sizing boundaries.
Sensitivity analysis around EPA PFAS designation timing and permitted TSDF capacity addition scenarios shapes the projection framework across the analysis window. Segmentation dimensions modeled include waste type classification, service modality, technology platform, and end-user industry vertical. CAGRs derive from regression analysis against industrial production indices and regulatory enforcement intensity metrics. Forecast inputs incorporate petrochemical capacity expansion announcements and hazardous waste technician certification pipeline data.
Forecasts assume regulatory continuity in EPA RCRA Subtitle C enforcement and Canadian provincial extended producer responsibility programs; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
PET Recycling Market
Waste Management & Pollution Control
Recyclate PET Market
Waste Management & Pollution Control
Asia-Pacific Municipal Solid Waste Management Market
Waste Management & Pollution Control
India Municipal Solid Waste Management Market
Waste Management & Pollution Control
Household Composters Market
Waste Management & Pollution Control
UAE Biomedical Waste Management Market
Waste Management & Pollution Control
Municipal Solid Waste Management Market
Waste Management & Pollution Control
GCC Waste Management Market
Waste Management & Pollution Control
Food Waste Management Market
Waste Management & Pollution Control
Scrap Metal Recycling Market
Waste Management & Pollution Control
Reusable Oil Absorbents Market
Waste Management & Pollution Control
India E-Waste Management Market
Waste Management & Pollution Control
Europe Municipal Solid Waste Management Market
Waste Management & Pollution Control
Waste Management Market
Waste Management & Pollution Control
Polyfluoroalkyl Substances (PFAS) Waste Management Market
Waste Management & Pollution Control
Recycled Ocean Plastics Market