
 Saudi Arabia Waste Management Market | 2026-2036
Saudi Arabia Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Waste Management Market Insights
Municipal authorities are rotating demand toward integrated treatment providers as landfill capacity tightens across major Saudi cities. Saudi Investment Recycling Company leverages its state-backed mandate to build domestic recycling infrastructure. Veolia Middle East anchors long-term service contracts with industrial clients in Jubail and Yanbu. Averda competes through specialized hazardous waste handling capabilities aligned with petrochemical sector requirements.
Waste management encompasses the systematic collection, transportation, processing, recycling, and disposal of solid and liquid refuse materials, with modern facilities achieving landfill diversion rates above 60 percent through mechanical biological treatment and energy recovery systems. Collection services dominate current revenue flows due to population concentration in Riyadh, Jeddah, and Dammam metropolitan zones. Recycling is accelerating fastest as SAMA green financing guidelines and extended producer responsibility pilots create structural pull for post-consumer material recovery. Anaerobic digestion holds concentrated margin pools where organic waste from food processing clusters generates biogas for captive industrial energy use.
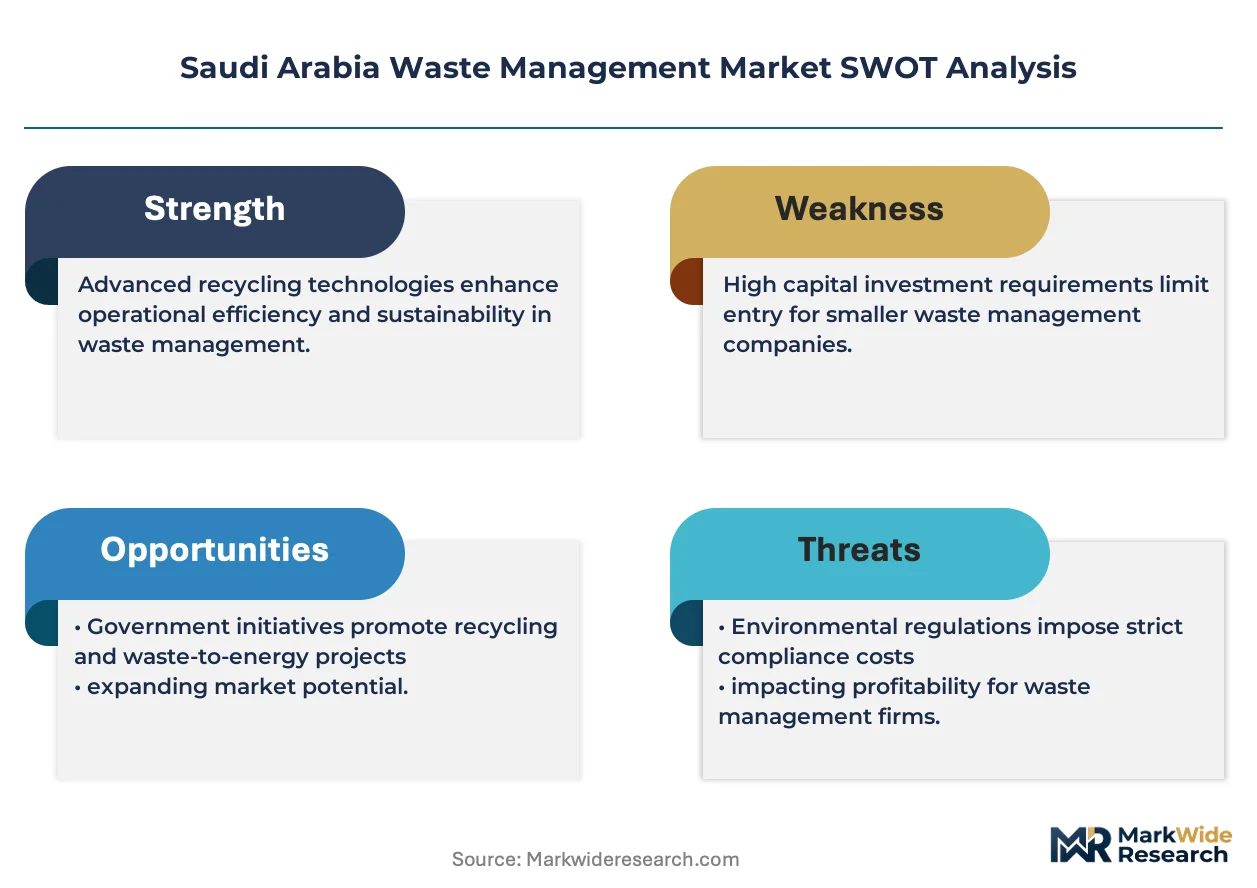
SFDA and the National Center for Waste Management enforce medical waste sterilization protocols and landfill siting restrictions that elevate compliance costs for unlicensed operators. MEE dual carbon goals and SASO technical regulations on waste-to-energy equipment imports are reshaping procurement specifications for municipal tenders. Stakeholders must monitor how circular economy procurement mandates in NEOM and the Red Sea Project redefine performance benchmarks before standardization spreads to legacy municipal contracts.
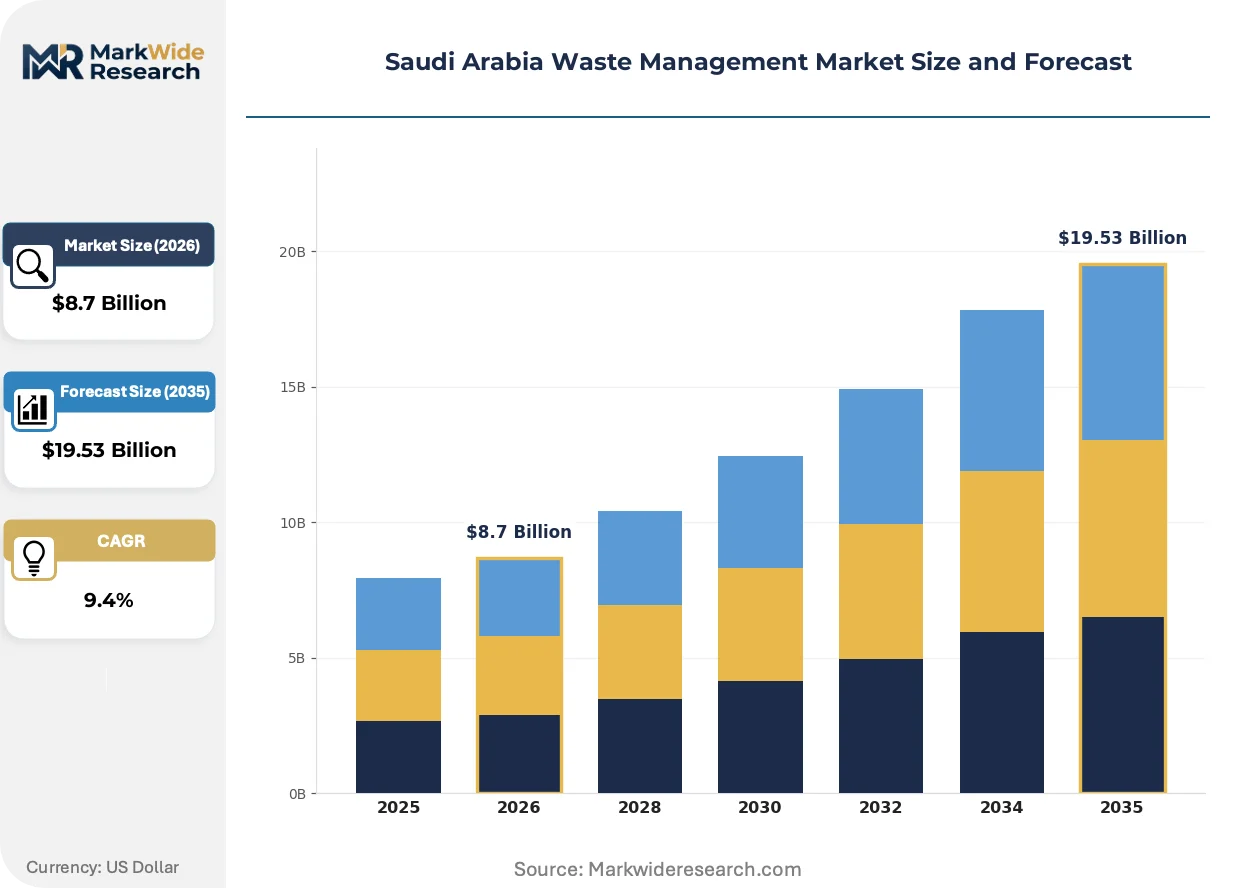
Market Dynamics
Landfill diversion mandates from the National Center for Waste Management are compressing traditional disposal economics and forcing municipal authorities toward integrated treatment infrastructure. This regulatory pressure is decomposing the historical fragmentation between collection, sorting, and processing services.
Growth Catalysts
- SAMA Green Financing Guidelines:Extended producer responsibility pilots are channeling institutional capital into post-consumer material recovery infrastructure across Riyadh and Jeddah metropolitan zones.
- Industrial Cluster Concentration:Petrochemical corridors in the Eastern Province generate concentrated hazardous waste streams requiring specialized sterilization and treatment capabilities.
- Mechanical Biological Treatment:Energy recovery systems achieving landfill diversion rates above sixty percent are capturing municipal procurement preference in major Saudi cities.
Market Restraints
- Import Equipment Dependencies:SASO technical regulations on waste-to-energy equipment create procurement friction and extend tender timelines for municipal authorities.
- Landfill Siting Restrictions:SFDA and National Center for Waste Management protocols elevate compliance costs and limit greenfield disposal capacity expansion near urban centers.
- Organic Waste Volatility:Seasonal fluctuations in food processing cluster output destabilize biogas yield predictability for anaerobic digestion operators.
Strategic Opportunities
- NEOM Circular Economy Procurement:Performance benchmark redefinition in giga-projects creates template contracts for legacy municipal systems to adopt.
- Red Sea Project Infrastructure:Zero-landfill mandates in tourism developments are piloting closed-loop material flows replicable across coastal municipalities.
- Anaerobic Digestion Convergence:Integration of biogas capture with captive industrial energy use is opening margin pools in food processing and dairy clusters.
Industry Challenges
- Technical Certification Bottlenecks:Medical waste sterilization protocol compliance creates extended licensing timelines for new market entrants seeking SFDA authorization.
- Legacy Collection Fleet Integration:Municipal authorities face capital intensity in retrofitting existing logistics networks for source-segregated collection models.
- Specialized Technician Scarcity:Hazardous waste handling and energy recovery system maintenance require skills concentrated among a limited pool of certified operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Waste Management Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Collection, Recycling, Treatment, Disposal Waste Type: Municipal Solid Waste, Industrial Waste, Hazardous Waste, Medical Waste Technology: Landfill, Incineration, Anaerobic Digestion, Composting End User: Residential, Commercial, Healthcare, Manufacturing |
| Companies Covered | Saudi Investment Recycling Company, Averda, Veolia Middle East, SUEZ Middle East, BEEAH Group, Waste Collection and Recycling Co., National Environmental Recycling Company, CIT Group Ltd, Al-Fahhad Zegwaard Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Waste Management Market Trends and Innovations
Digital tracking systems and automated sorting technologies are compressing the cost structure of material recovery while policy mandates accelerate the shift from linear disposal to circular resource flows. These forces are reconfiguring competitive advantage toward integrated technology platforms.
Artificial intelligence-powered optical sorting is decomposing manual labor dependencies in material recovery facilities. Municipal operators in Riyadh and Jeddah are deploying these systems at scale to meet diversion targets. The technology is decomposing historical cost barriers between mechanical recycling and virgin material economics.
SFDA sterilization protocols for medical waste are tightening containment and treatment standards across healthcare facilities. These rules are elevating capital requirements for autoclave and incineration infrastructure. Private operators are consolidating to spread compliance costs across larger volume bases.
Performance-based service contracts are displacing traditional per-ton collection fees in municipal procurement. Integrated providers now assume diversion risk and share revenue from recovered materials. This shift is most visible in Eastern Province industrial zones where petrochemical clients demand outcome guarantees.
Saudi Arabia Waste Management Market Segmentation
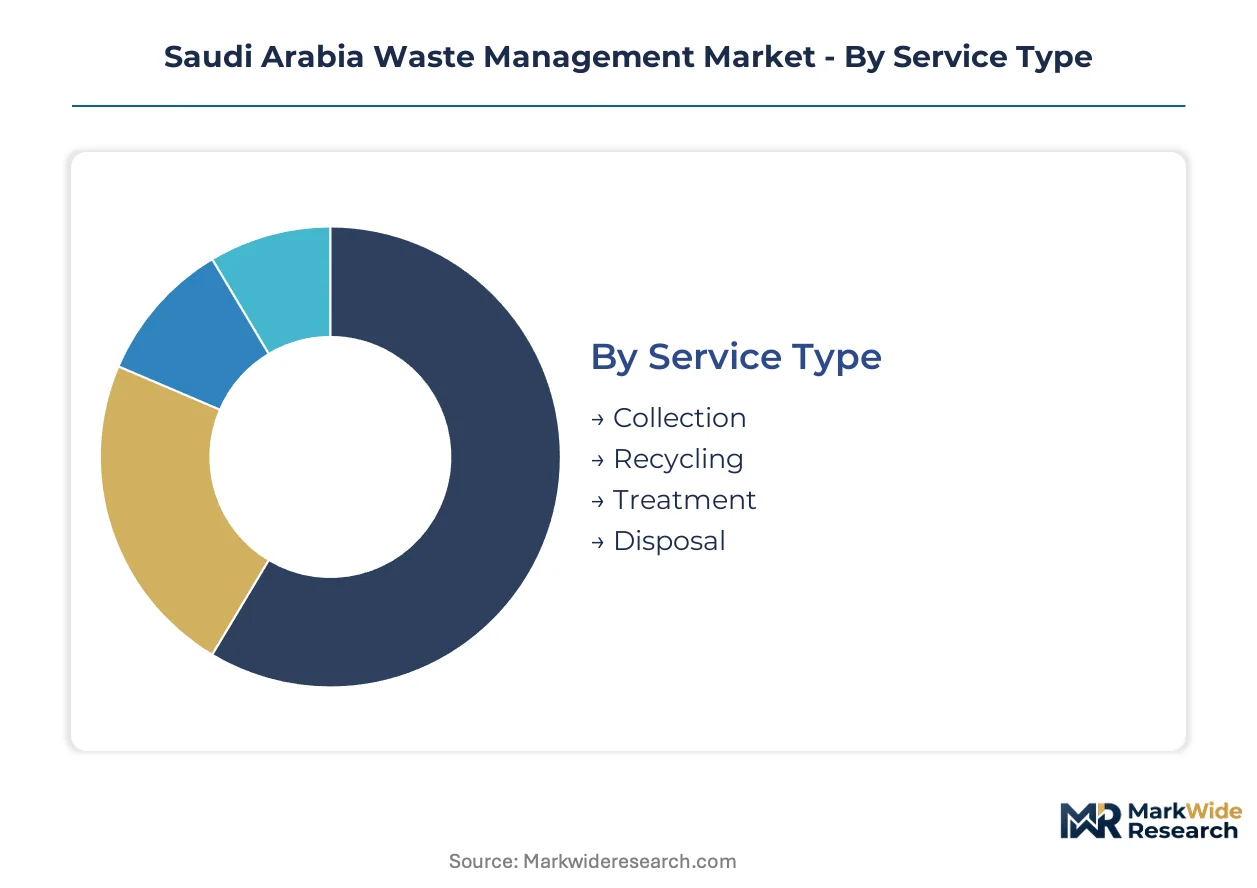
Service specialization determines margin capture in Saudi Arabia's waste management sector, with technology-enabled segments commanding premium pricing against commoditized collection operations. Regulatory mandates from the National Center for Waste Management are fragmenting historical service bundles into discrete procurement categories.
Service Type:
Margin pools concentrate in treatment and recycling where landfill diversion mandates create structural scarcity, while collection services face price compression from municipal procurement standardization.
- Collection:Door-to-door and containerized pickup services dominate revenue volumes across Riyadh, Jeddah, and Dammam metropolitan zones. Municipal authorities in these cities are expanding fleet capacity under Saudi Vision 2030 circular economy targets, though per-ton fees face downward pressure from standardized tender specifications.
- Recycling:Post-consumer material recovery infrastructure is capturing institutional capital flows through SAMA green financing guidelines. Extended producer responsibility pilots in Riyadh and Jeddah are accelerating demand for integrated sorting and processing facilities that achieve mechanical recovery rates above sixty percent.
- Treatment:Mechanical biological treatment and sterilization services command specialized pricing in Eastern Province petrochemical corridors.
- Disposal:Landfill operations face tightening capacity constraints from SFDA siting restrictions near urban centers.
Collection holds installed capacity. Recycling is rotating up the share rankings.
Waste Type:
Volume concentration follows population density for municipal streams, while hazardous and medical categories generate concentrated margin pools through compliance-driven specialization requirements.
- Municipal Solid Waste:Household and commercial refuse streams account for the largest tonnage volumes across Saudi Arabia's major metropolitan zones. Riyadh Municipality and Jeddah Municipality are deploying source-segregated collection models to feed mechanical biological treatment facilities with predictable organic fractions.
- Industrial Waste:Petrochemical sector effluents and manufacturing byproducts concentrate demand in Jubail and Yanbu industrial cities. Veolia Middle East anchors long-term service contracts in these zones where specialized handling capabilities filter competitive entry.
- Hazardous Waste:Flammable, corrosive, and toxic materials require certified transport and treatment protocols under National Center for Waste Management mandates.
- Medical Waste:SFDA sterilization protocols for sharps, pharmaceuticals, and infectious materials elevate capital barriers for autoclave infrastructure.
Municipal solid waste holds installed capacity. Medical waste is rotating up the share rankings.
Technology:
Capital intensity separates mature disposal methods from emerging recovery systems, with anaerobic digestion opening captive energy revenue streams in food processing clusters.
- Landfill:Engineered containment and leachate management systems remain the dominant disposal pathway despite tightening diversion mandates. The National Center for Waste Management's landfill siting restrictions are compressing greenfield capacity expansion near Riyadh and Jeddah, elevating gate fees at remaining facilities.
- Anaerobic Digestion:Biogas capture systems integrated with captive industrial energy use are opening margin pools in food processing and dairy clusters. Organic waste volatility from seasonal production fluctuations destabilizes yield predictability for operators lacking diversified feedstock contracts.
- Incineration:High-temperature combustion with energy recovery addresses medical and hazardous waste streams under SFDA sterilization protocols.
- Composting:Aerobic decomposition of organic fractions serves agricultural end-markets with lower capital requirements than anaerobic systems.
Landfill holds installed capacity. Anaerobic digestion is rotating up the share rankings.
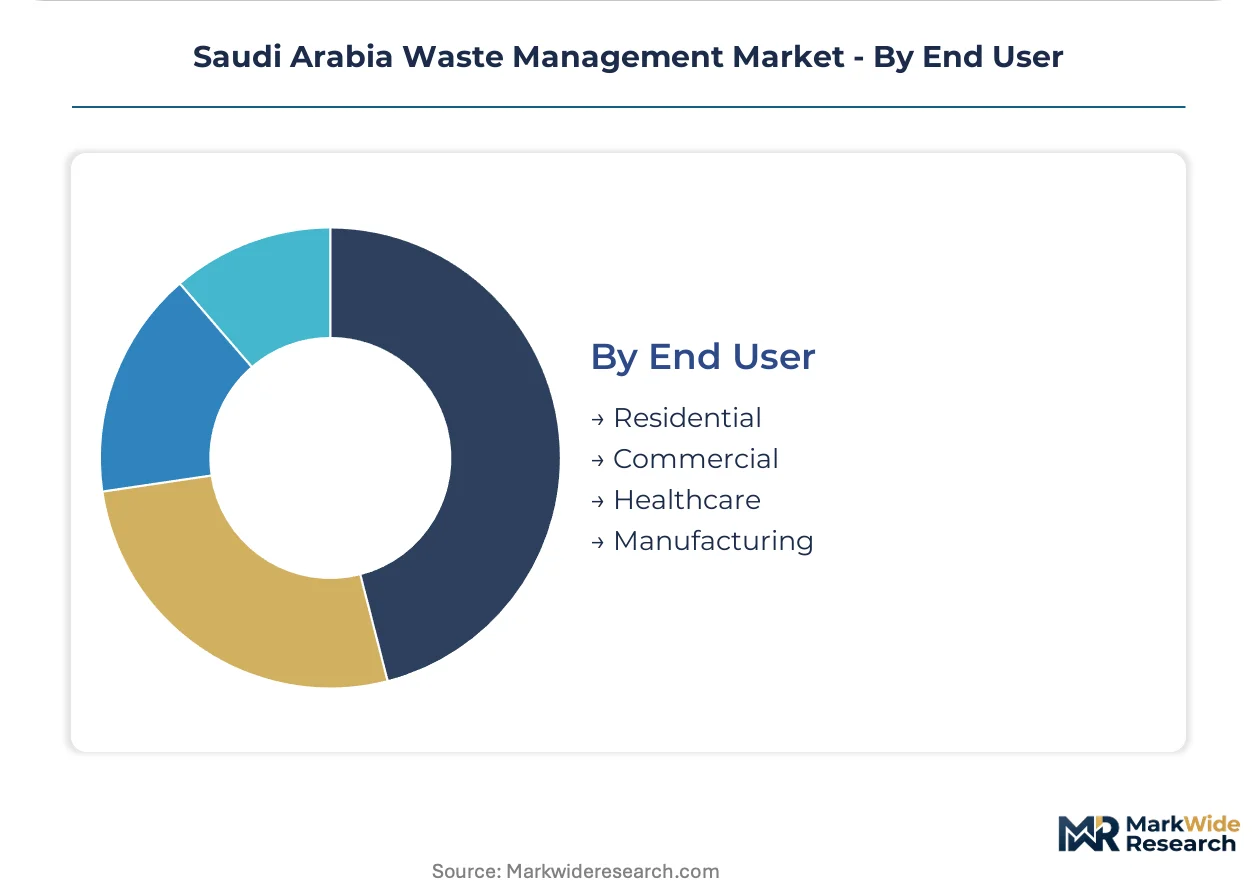
End User:
Procurement sophistication varies sharply across customer categories, with healthcare and manufacturing segments demanding outcome-based contracts versus residential ratepayer models.
- Residential:Household waste generation concentrates in Riyadh, Jeddah, and Dammam where population density supports collection route efficiency. Municipal authorities bear collection costs through utility billing structures that limit direct price signals to ratepayers.
- Manufacturing:Petrochemical and food processing facilities in the Eastern Province generate concentrated industrial waste streams requiring specialized treatment capabilities. Performance-based service contracts are displacing per-ton fees as these clients demand diversion guarantees and material recovery revenue sharing.
- Commercial:Retail and hospitality operations in urban centers face emerging extended producer responsibility obligations.
- Healthcare:Hospitals and clinics operate under strict SFDA medical waste sterilization protocols that mandate certified treatment vendor relationships.
Residential holds installed capacity. Manufacturing is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's waste management infrastructure links Gulf petrochemical output with circular economy financing from Riyadh-based institutional investors. Cross-border service contracts from UAE and Bahrain operators concentrate technical expertise in the Eastern Province industrial corridor.
Riyadh
Riyadh Municipality is deploying source-segregated collection fleets to feed mechanical biological treatment facilities. The National Center for Waste Management mandates landfill diversion rates above sixty percent for capital region operators. Saudi Investment Recycling Company anchors domestic recycling infrastructure development across the metropolitan zone.
Eastern Province
Jubail and Yanbu industrial cities generate concentrated hazardous waste streams from petrochemical processing clusters. SFDA protocols and National Center for Waste Management regulations enforce specialized sterilization requirements for flammable and toxic materials. Veolia Middle East maintains long-term service contracts with manufacturing clients in these zones.
Western Region
Jeddah Municipality faces tightening landfill capacity constraints from urban siting restrictions under coastal protection frameworks. Extended producer responsibility pilots channel SAMA green financing into post-consumer material recovery infrastructure. Red Sea Project developments are piloting zero-landfill closed-loop systems replicable across coastal municipalities.
NEOM Northwest
The giga-project's circular economy procurement mandates are redefining performance benchmarks for integrated treatment providers. Outcome-based service contracts displace traditional per-ton collection fees in municipal procurement templates. Anaerobic digestion systems are capturing organic fractions for captive biogas energy use in food processing clusters.
Saudi Arabia Waste Management Market Competitive Landscape
Player mix skews toward state-backed entities and international specialists with Gulf operational experience. Market structure concentrates around three tiers: sovereign wealth-funded domestic champions, European multinationals with regional headquarters, and specialized hazardous waste handlers. Strategic archetypes include integrated platform operators, niche technical specialists, and asset-light service contractors. Competitive moves center on long-term municipal tender anchoring and technology licensing partnerships for automated sorting systems.
Within the state-backed tier, Saudi Investment Recycling Company occupies a position as the domestic infrastructure anchor mandated under Saudi Vision 2030 circular economy targets. Among international specialists with Middle East regional headquarters, Veolia Middle East and SUEZ Middle East exemplify the integrated service model combining collection logistics with treatment asset ownership. Averda represents the specialized hazardous waste archetype, with capabilities aligned to petrochemical sector sterilization protocols enforced by SFDA and the National Center for Waste Management.
| Leading Market Players |
|---|
| Saudi Investment Recycling Company |
| Averda |
| Veolia Middle East |
| SUEZ Middle East |
| BEEAH Group |
| Waste Collection and Recycling Co. |
| National Environmental Recycling Company |
| CIT Group Ltd |
| Al-Fahhad Zegwaard Co. |
| Others |
Pricing and Supply Chain Analysis
Long-term service contracts with take-or-pay provisions dominate municipal and industrial procurement in Saudi Arabia, locking in supply access for integrated treatment providers while anchoring price visibility across multi-year tenors. These structures insulate operators from feedstock volatility while exposing them to performance penalties under tightening National Center for Waste Management diversion mandates.
Pricing Analysis
Current-generation mechanical biological treatment commands premium pricing against legacy landfill disposal, while next-generation anaerobic digestion with captive biogas capture is capturing margin pools in food processing clusters. The dominant pricing structure runs through performance-based service contracts where operators assume diversion risk and share material recovery revenue. Price differentiation hinges on certification tier under SFDA sterilization protocols and the scale of integrated sorting infrastructure. Cost compression in standard collection services is intensifying because municipal tender standardization erodes per-ton fees. Residential ratepayers show highest price sensitivity through utility-billing pass-through limits, while petrochemical manufacturing clients accept premium pricing for outcome guarantees.
Supply Chain Analysis
Strategic stockpiling of specialized treatment chemicals and spare parts characterizes operator inventory strategy given extended lead times for SASO-certified waste-to-energy equipment imports. Supply concentration rests on Germany, Japan, and South Korea for advanced sorting and sterilization hardware. Raw material dependencies include stainless steel containment vessels, high-temperature refractories, and optical sensor arrays. Single-source vulnerability runs through European OEMs for automated sorting technology. Distribution runs through municipal tender awards in Riyadh and Jeddah, with industrial zones in Jubail and Yanbu commanding direct bilateral negotiations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified hazardous waste handling capabilities represent the critical scarcity layer in this market, with SFDA sterilization protocol compliance creating extended licensing timelines that constrain new entrant supply. The gap between permitted capacity and diversion mandate targets is widening fastest in medical and industrial waste streams.
For Market Incumbents: Compound municipal contract density in Riyadh and Jeddah through fleet modernization bids that bundle source-segregated collection with mechanical biological treatment assets. Anchor long-term service agreements in Eastern Province petrochemical corridors before specialized hazardous waste handling permits saturate. Vertical integration into anaerobic digestion infrastructure captures biogas revenue streams that offset collection margin erosion. For New Entrants and Emerging Players: SFDA certification fast-track partnerships with established healthcare facility networks open medical waste sterilization market access without full infrastructure buildout. White-space concentration sits in food processing cluster organic waste streams where seasonal feedstock contracts destabilize incumbent biogas yield predictability. Target NEOM and Red Sea Project circular economy procurement templates as reference customers for legacy municipal contract migration. For Investors and Strategic Acquirers: Capital is best deployed toward integrated platform operators with existing SFDA permits and municipal tender track records rather than greenfield development plays. Long-term viability across the analysis window favors asset owners with captive energy recovery revenue diversification. Watch landfill diversion mandate enforcement intensity as the inflection signal for pricing power migration toward treatment-heavy service models.| Strategic Initiative | Industry Significance |
|---|---|
| Mechanical Biological Treatment Capacity Buildout | Captures municipal diversion mandates under National Center for Waste Management protocols. |
| SFDA Sterilization Certification Investment | Unlocks medical waste service contracts with hospital systems and healthcare clusters. |
| Anaerobic Digestion Integration | Converts food processing organic fractions into captive biogas for industrial energy use. |
| Automated Sorting Technology Licensing | Compresses material recovery facility operating costs below virgin material economics. |
| Long-term Municipal Service Contract Anchoring | Secures revenue base across Saudi Vision 2030 circular economy infrastructure rollout. |
Research Methodology
The analysis maps collection services, recycling infrastructure, treatment technologies, and disposal assets, each validated through municipal procurement officers, plant engineers at petrochemical facilities, SFDA compliance managers, and waste logistics operators. Primary interview data triangulates against secondary sources including National Center for Waste Management regulatory filings, SAMA green financing disclosure guidelines, municipal tender documentation from Riyadh and Jeddah authorities, and customs records for waste-to-energy equipment imports. Bottom-up segment sizing cross-checks against top-down macroeconomic anchoring in population growth and industrial output projections.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models service type, waste category, technology platform, and end-user procurement sophistication as core segmentation dimensions. CAGRs derive from regression analysis of historical contract award values and announced capacity additions. Industry-specific forecast inputs include petrochemical sector output trajectories in the Eastern Province and municipal budget allocations under Saudi Vision 2030 targets.
Underlying assumptions cover regulatory enforcement continuity for landfill diversion mandates, with deviation risk concentrated in SASO equipment import timeline extensions and seasonal organic waste feedstock volatility. Revision becomes warranted when NEOM circular economy procurement benchmarks accelerate standardization across legacy municipal contracts beyond modeled adoption curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Biomedical Waste Management Market
Waste Management & Pollution Control
Solid Waste Management Market
Waste Management & Pollution Control
Asia-Pacific Waste Management Market
Waste Management & Pollution Control
Waste Recycling Services Market
Waste Management & Pollution Control
India Bio-Medical Waste Management Market
Waste Management & Pollution Control
Alkaline Solid Waste Market
Waste Management & Pollution Control
Europe Bio-Medical Waste Management Market
Waste Management & Pollution Control
Global Automated Marine Debris Collection Equipment Market
Waste Management & Pollution Control
Asia Pacific Medical Waste Management Market
Waste Management & Pollution Control
Europe Industrial Waste Management Market
Waste Management & Pollution Control
Asia-Pacific Industrial Waste Management Market
Waste Management & Pollution Control
North America Municipal Solid Waste Management Market
Waste Management & Pollution Control
Trash Pump Market
Waste Management & Pollution Control
Paper Recycling Market
Waste Management & Pollution Control
Smart Waste Sorting Bin Market
Waste Management & Pollution Control
Landfill Compactor Market