
 Paper Recycling Market | 2026-2036
Paper Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Recycling Market Outlook
EU Green Deal compliance is broadening the cost-of-entry calculus for new recycling capacity across Europe. UPM leverages its integrated pulp-to-paper network to secure long-term recovered fiber contracts. DS Smith anchors containerboard production through dedicated recycling subsidiaries in multiple countries. Stora Enso specializes in high-grade deinked pulp for magazine and catalog applications.
Paper recycling converts post-consumer fiber into repulpable stock through mechanical or chemical defibration, with deinking removing inks and coatings to achieve brightness thresholds above 80 ISO for graphic grades. Cardboard dominates volume flows due to e-commerce corrugated demand, while office paper commands premium pricing through superior fiber length retention. Mechanical pulping leads installed capacity, though deinking capacity expansion is accelerating fastest in markets with stringent contamination limits.
EPA landfill diversion targets in the United States, EU Waste Framework Directive recycling mandates, and China's MEE import restrictions on recovered paper collectively reshape global fiber trade routes and quality standards. Stakeholders must monitor how regulatory divergence between jurisdictions affects cross-border fiber pricing and sorting technology investment requirements.
Market Dynamics
The EU Green Deal's tightening virgin pulp restrictions are forcing packaging converters to reconfigure fiber sourcing strategies, while China's MEE import bans redirect recovered paper flows toward domestic processing hubs.
Growth Catalysts
- EU Waste Framework Directive:Mandatory recycling targets for municipal paper waste are compelling municipalities across Germany, France, and Italy to upgrade collection infrastructure and expand deinking capacity.
- E-commerce corrugated demand:Cardboard volume from online retail fulfillment centers is surging, creating dedicated reverse logistics streams that feed directly into mill-scale repulping operations.
- Near-infrared sorting:Advanced optical separation technology is reducing contamination rates in mixed paper streams, enabling higher-grade fiber recovery from previously rejected feedstocks.
Market Restraints
- Recovered fiber price volatility:China's MEE import restrictions eliminated a major export destination for US and European recovered paper, collapsing regional pricing benchmarks and destabilizing collector economics.
- Deinking chemical cost exposure:Specialty surfactants and bleaching agents for high-brightness pulp production face supply concentration from German and Japanese chemical producers.
- Contamination technical ceiling:Food residue and plastic film adherence in post-consumer cardboard creates fiber quality degradation that mechanical pulping cannot fully remediate.
Strategic Opportunities
- India's packaging board deficit:Domestic containerboard production capacity lags behind FMCG and pharma demand, creating import substitution potential for deinked pulp exporters with ISPM-15 compliant shipping.
- CSRD disclosure requirements:The EU Corporate Sustainability Reporting Directive mandates Scope 3 emissions tracking, incentivizing brand owners to source certified recycled content with verified chain-of-custody documentation.
- Digital watermark integration:Invisible markers embedded during original paper manufacturing are converging with AI-powered sorting systems to enable automated grade separation at municipal facilities.
Industry Challenges
- Deinking chemist shortage:Specialized expertise in pulp brightness optimization and contaminant chemistry is concentrated among retiring workforce cohorts in Nordic and German mill regions.
- Legacy baling equipment incompatibility:Decades-old municipal collection infrastructure produces non-standard bale densities that jam automated feeding systems at modern continuous pulping lines.
- EN 643 certification timeline:European standard compliance for recovered paper grades requires extended third-party verification cycles that delay contract finalization with anxious converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Recycling Market |
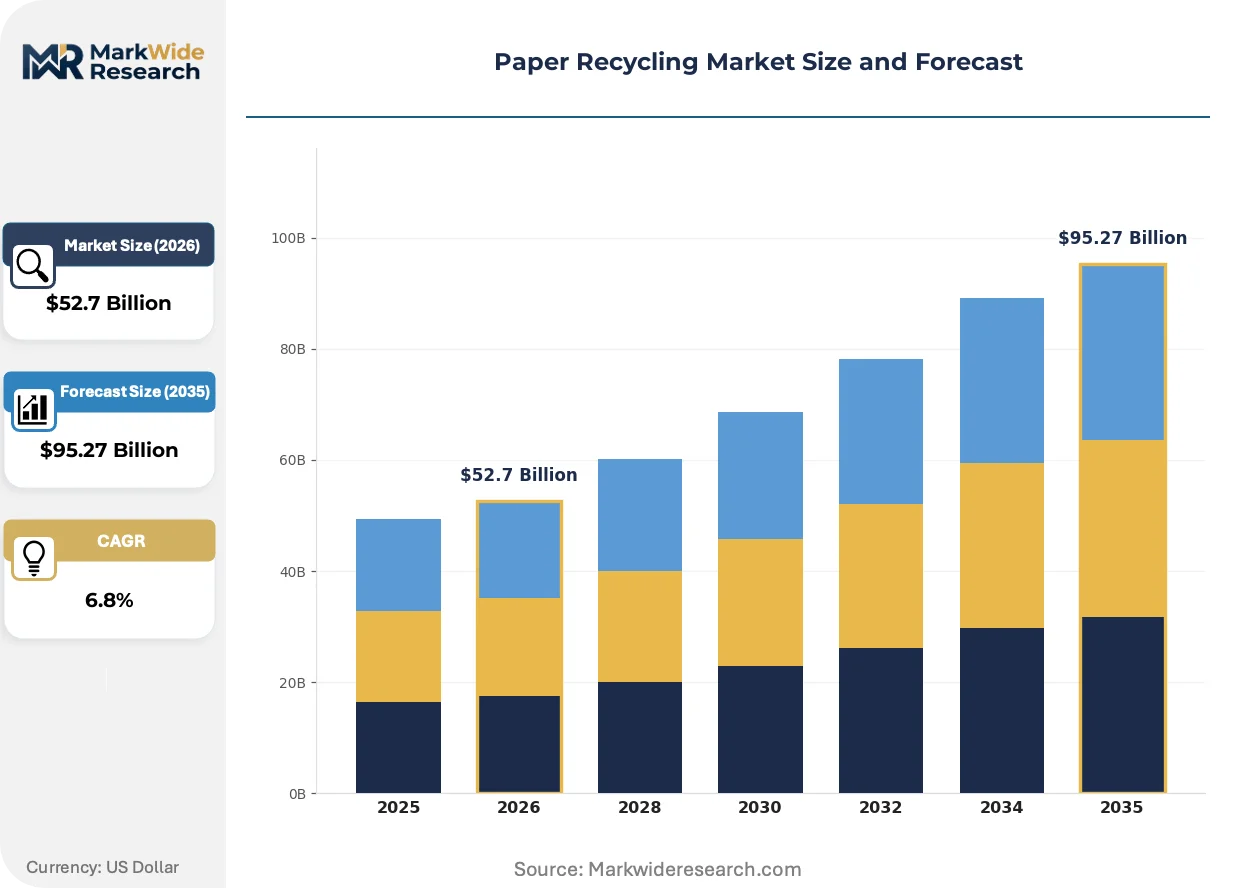
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Newspaper, Cardboard, Office Paper, Mixed Paper End User: Commercial, Residential, Educational Institutions, Government Collection Method: Curbside Pickup, Drop-off Centers, Buyback Programs, Deposit Refund Processing Technology: Mechanical Pulping, Chemical Pulping, Deinking, Recycling with Additives |
| Companies Covered | UPM, Smurfit Kappa Group, International Paper, Kimberly Clark, DS Smith, WestRock, Stora Enso, Sonoco Products, Oji Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Recycling Market Strategic Shifts
Active transformation in paper recycling centers on three vectors: process intensification technologies that compress production cycles, regulatory frameworks that embed circularity into procurement mandates, and demand-side restructuring that reconfigures who controls fiber flows.
Enzymatic deinking is rewriting grade economics for magazine and catalog producers. Cellulase and lipase formulations now achieve ISO brightness above 82 without oxidative bleaching stages. Nordic graphic paper mills are adopting these systems at pilot scale, with full-line conversions planned for facilities serving premium publishing accounts. The technology is compressing chemical cost structures while expanding the addressable pool of lower-grade recovered feedstocks.
REACH authorization requirements for process chemicals are tightening input specifications across EU deinking operations. ECHA's evolving restrictions on surfactant classifications are forcing reformulation of standard pulping chemistries. German and Dutch mills are responding by accelerating partnerships with bio-based chemical suppliers to secure pre-authorized alternative inputs ahead of sunset date enforcement.
Brand-led fiber procurement consortia are displacing spot-market purchasing for major packaging accounts. Consumer goods manufacturers in beverage and electronics verticals are pooling volume commitments to secure multi-year recycled fiber supply with fixed-price mechanisms. This concentration is most visible in the Benelux region, where coordinated buying groups now represent substantial containerboard off-take from integrated recycling-to-packaging producers.
Paper Recycling Market Segmentation
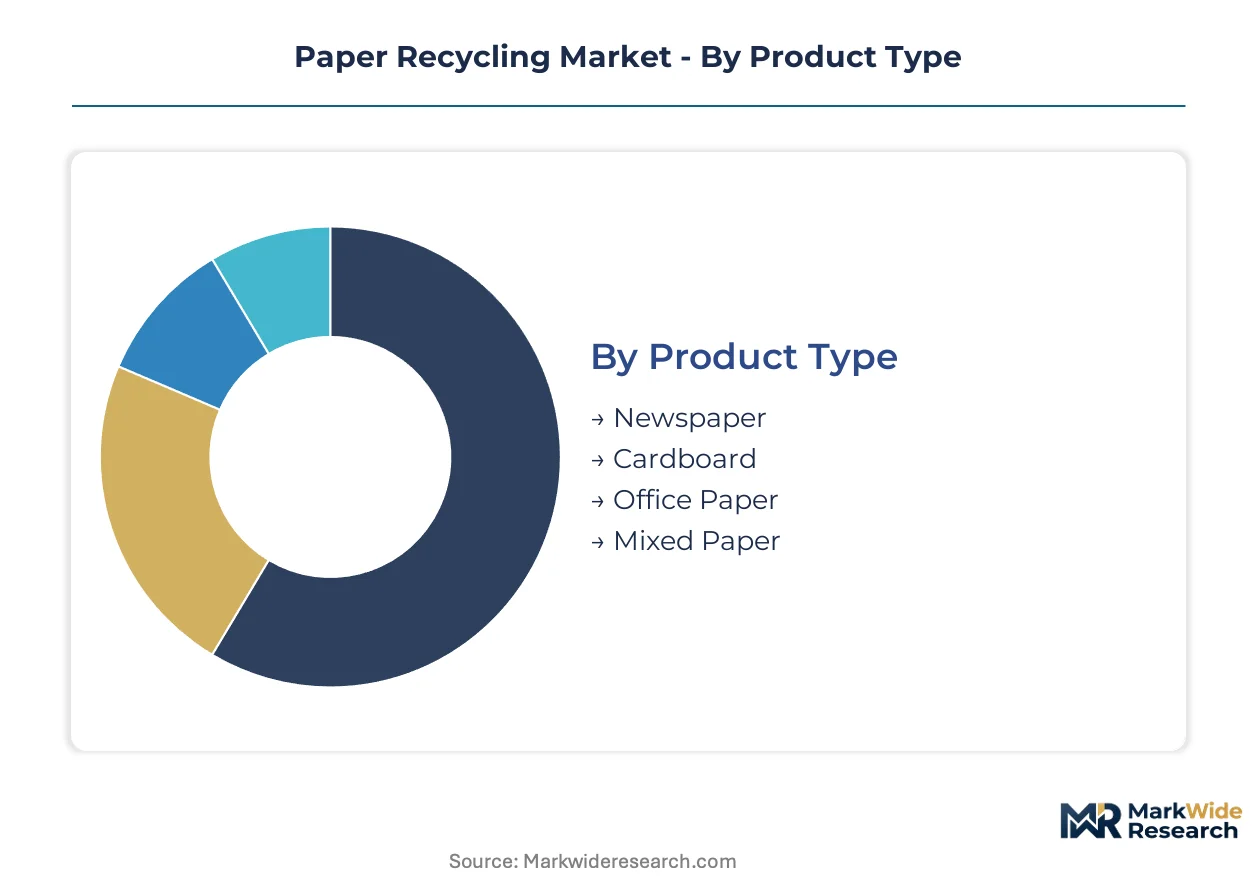
Segmentation in paper recycling reveals how fiber quality, collection infrastructure, and processing technology intersect to determine value capture. Each axis shapes capital deployment decisions and margin structures differently across the value chain.
Product Type:
Specification thresholds for brightness, fiber length, and contamination tolerance define grade boundaries and end-market eligibility.
- Cardboard:Corrugated containers and boxboard deliver long, unbleached kraft fibers ideal for linerboard production. E-commerce fulfillment centers in Germany and the Netherlands generate concentrated volume streams that bypass municipal sorting entirely. Contamination from plastic tape and food residue limits closed-loop recycling cycles to 5-7 iterations.
- Office Paper:High-grade copier and printer stock retains superior fiber length through multiple repulping cycles. Premium deinked pulp from this feedstock serves magazine and catalog producers requiring ISO brightness above 80. Supply concentrates in corporate campus collection programs rather than residential streams.
- Newspaper:Groundwood mechanical pulp degrades rapidly through repulping, limiting applications to lower-grade packaging or insulation products.
- Mixed Paper:Commingled residential streams require intensive sorting and yield variable quality output suited primarily to containerboard filler applications.
Cardboard leads on scale; office paper leads on momentum.
End User:
Customer type determines collection density, contamination rates, and contract structures for fiber procurement.
- Commercial:Retail chains, warehouses, and distribution centers generate clean, source-separated cardboard in predictable volumes. Direct mill contracts with fixed-price mechanisms bypass spot market volatility entirely.
- Residential:Municipal curbside programs capture fragmented supply with higher contamination exposure. Germany's dual-stream collection infrastructure achieves lower rejection rates than single-stream US equivalents.
- Educational Institutions:Campus-based programs concentrate office paper supply during academic calendar peaks.
- Government:Administrative facilities generate secure-document shredding streams requiring specialized chain-of-custody handling before pulping.
Commercial channels dominate volume throughput; educational programs expand most quickly.
Collection Method:
Logistics configuration shapes fiber recovery rates and preprocessing cost structures before mill delivery.
- Curbside Pickup:Municipal fleets with dedicated compartments for paper fractions achieve highest participation rates in dense urban zones. Collection frequency and contamination control vary significantly between German cities implementing pay-as-you-throw pricing versus flat-fee US municipalities.
- Drop-off Centers:Self-service depots in rural and suburban zones reduce per-ton collection costs through resident transportation. France's eco-organisme network coordinates center placement with mill proximity to minimize baling and transport expenditure.
- Buyback Programs:Scrap dealers and informal collectors aggregate small volumes from commercial generators lacking direct mill relationships.
- Deposit Refund:Container deposit systems for beverage packaging generate limited paper fractions alongside dominant plastic and metal streams.
Curbside pickup commands the largest tonnage; drop-off centers gain share fastest in peri-urban expansion zones.
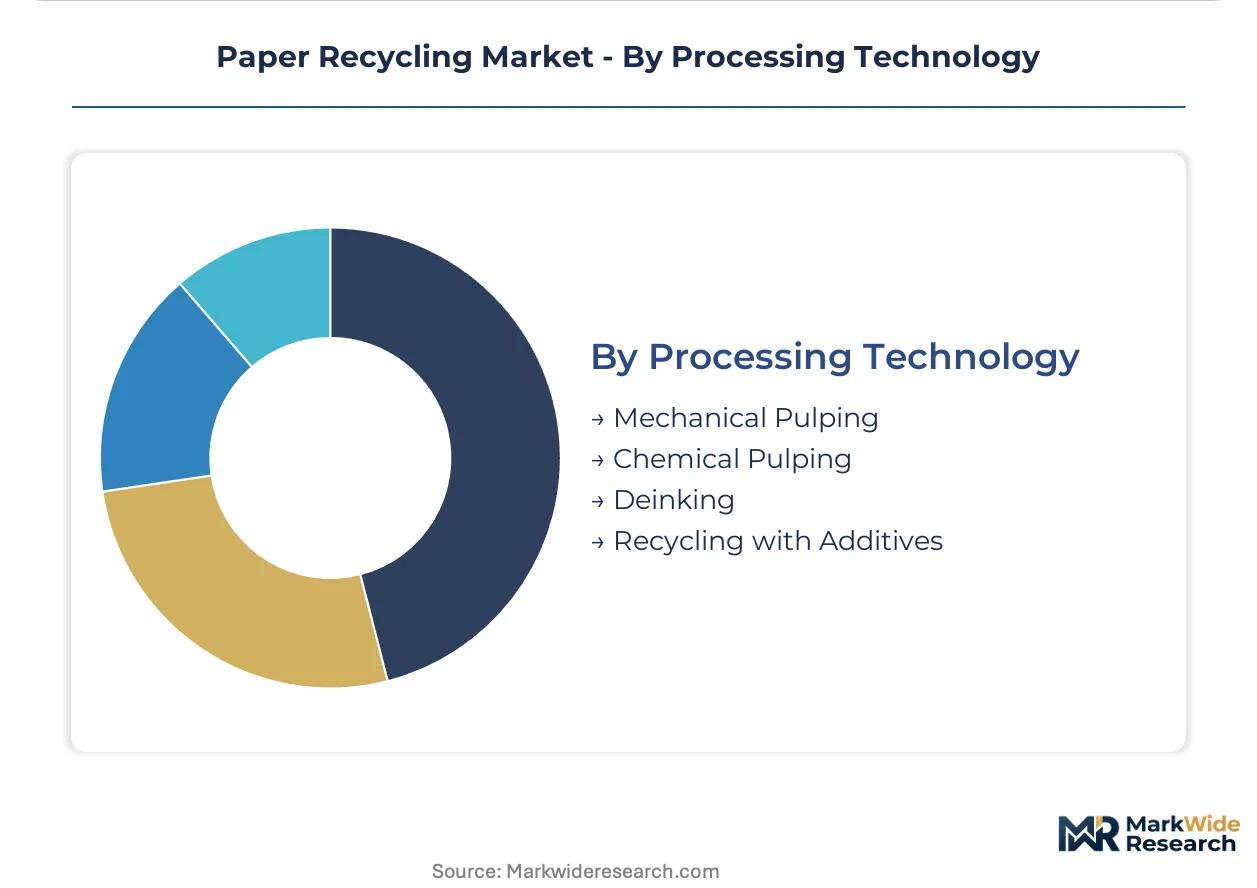
Processing Technology:
Pulping chemistry and separation intensity determine output grade specifications and energy intensity profiles.
- Deinking:Flotation and washing stages remove inks, coatings, and adhesives to achieve graphic-grade brightness thresholds. Enzymatic formulations using cellulase and lipase are displacing oxidative bleaching in Nordic mill conversions, compressing chemical cost structures while expanding feedstock flexibility.
- Mechanical Pulping:Refiner-based fiber separation without chemical delignification dominates installed capacity for packaging grades. Lower capital intensity and energy requirements suit high-volume containerboard production with relaxed brightness specifications.
- Chemical Pulping:Kraft and sulfite processes for recovered fiber remain limited to specialty applications requiring maximum strength retention.
- Recycling with Additives:Functional fillers, wet-strength agents, and dyes blended during repulping create customized pulp properties for specific end-uses.
Mechanical pulping retains volume leadership; deinking climbs the fastest as EU graphic paper mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German mill operators anchor the talent pool for deinking chemistry and fiber processing engineering, concentrating specialized workforce development in the Rhine-Ruhr corridor.
Germany
Municipal collection infrastructure and deinking capacity expansion drive fiber recovery volumes. The EU Green Deal's virgin pulp restrictions force packaging converters toward recovered fiber sourcing. The Rhine-Ruhr corridor hosts integrated recycling-to-packaging complexes serving Benelux export markets.
United States
EPA landfill diversion targets and e-commerce corrugated waste streams reshape collection economics. State-level extended producer responsibility laws in California and Oregon mandate post-consumer recycled content minimums. The Southeast pulp and paper belt—Georgia and the Carolinas—absorbs redirected fiber flows following China's MEE import restrictions.
China
Domestic processing hub construction accelerates as MEE import bans eliminate external recovered paper dependency. The dual carbon goals framework imposes energy intensity caps on repulping operations. The Yangtze River Delta cluster around Shanghai concentrates new deinking capacity serving domestic containerboard demand.
India
Packaging board deficit in FMCG and pharma verticals creates import substitution openings for deinked pulp exporters. BIS quality standards for recovered paper grades remain under development, creating certification uncertainty. The Gujarat industrial corridor attracts containerboard investments with captive recycling integration.
Japan
METI circular economy roadmaps mandate industrial waste paper recovery rates above 90 percent for large generators. JIS standards for deinked pulp brightness enforce strict quality thresholds limiting feedstock flexibility. The Kanto region around Tokyo maintains dense collection networks feeding integrated pulp-to-paper complexes.
Paper Recycling Market Competitive Environment
The competitive structure tilts toward integrated pulp-to-paper conglomerates with captive recycling subsidiaries. Market concentration remains moderate, with tier-one players controlling deinking capacity and tier-two operators specializing in mechanical pulping for packaging grades. Strategic archetypes span integrated forest products groups, packaging-focused converters, and specialty deinking technology providers. Capacity expansion and strategic partnerships dominate competitive moves as players secure long-term recovered fiber contracts.
Among Nordic-based integrated producers, Stora Enso and UPM exemplify the forest-to-recycling archetype with dedicated deinking operations. DS Smith represents the packaging-converter model, anchoring containerboard production through recycling subsidiary networks across multiple jurisdictions. These three occupy positions defined by backward integration into fiber supply and geographic diversification of processing assets.
| Leading Market Players |
|---|
| UPM |
| Smurfit Kappa Group |
| International Paper |
| Kimberly Clark |
| DS Smith |
| WestRock |
| Stora Enso |
| Sonoco Products |
| Oji Holdings |
| Others |
Value Chain & Pricing Dynamics
Captive recycling-to-packaging integration anchors both supply security and pricing power for European containerboard producers. DS Smith and UPM leverage dedicated fiber collection subsidiaries to lock in deinked pulp volumes at contract rates insulated from spot-market volatility triggered by China's MEE import restrictions.
Pricing Analysis
Bundled long-term offtake contracts dominate premium deinked pulp transactions, while unbundled spot trading governs mixed paper and cardboard grades. Price differentiation rests on EN 643 certification tier and ISO brightness thresholds, with graphic-grade office paper commanding substantial premiums over packaging feedstocks. Cost compression in standard-grade cardboard is intensifying because China's import ban eliminated export outlets for US and European collectors. Commercial e-commerce generators exhibit lowest price sensitivity due to direct mill relationships, while municipal residential programs face acute margin pressure from contamination-related rejection penalties.
Supply Chain Analysis
Direct-to-mill channels handle commercial cardboard volumes from German and Dutch fulfillment centers, bypassing municipal sorting infrastructure entirely. Fiber supply concentrates in Germany, the United States, and China, with the Rhine-Ruhr corridor, the Southeast US pulp belt, and the Yangtze River Delta anchoring deinking capacity expansion. Raw material flows draw from post-consumer collection streams, specialty surfactant inputs from German and Japanese chemical producers, and enzymatic formulations for brightness optimization. Single-source vulnerability in deinking chemical supply creates exposure to REACH authorization delays. Distribution runs through integrated recycling-to-packaging complexes, independent mechanical pulping operators, and export-oriented deinked pulp traders serving India's containerboard deficit.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Paper recycling functions as a stable compounder under EU regulatory mandates that embed circular procurement into packaging supply chains. The EU Green Deal's virgin pulp restrictions create durable demand tailwinds for recovered fiber infrastructure.
For Market Incumbents: Extend backward integration into municipal collection infrastructure to secure feedstock access ahead of EN 643 certification mandates. Incumbents should anchor containerboard margins by acquiring distressed mechanical pulping assets in the US Southeast where China's MEE restrictions have collapsed regional pricing benchmarks. Capacity addition in India's Gujarat corridor offers geographic diversification against European energy cost exposure. For New Entrants and Emerging Players: Near-infrared sorting technology paired with AI-powered grade separation offers a technology-first wedge into municipal contract markets dominated by legacy baling equipment. White-space targets include India's packaging board deficit for ISPM-15 compliant deinked pulp exports, and enzymatic deinking services for Nordic graphic paper mills seeking to eliminate oxidative bleaching stages. A go-to-market angle emphasizing CSRD-compliant chain-of-custody documentation attracts brand-led procurement consortia in the Benelux region. For Investors and Strategic Acquirers: Roll-up economics work for regional mechanical pulping operators because EN 643 certification timelines create extended due diligence windows that favor consolidated platforms with established verification relationships. Target mid-cap European recyclers with captive fiber contracts and deinking capacity serving premium publishing accounts. Watch for inflection in India's BIS quality standard finalization, which would trigger import substitution investment in domestic containerboard recycling integration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Infrastructure | Secures fiber supply ahead of EU Green Deal tightening and EN 643 mandates. |
| Enzymatic Deinking Technology Deployment | Eliminates oxidative bleaching costs for Nordic graphic paper mills serving premium publishing. |
| Geographic Expansion into India | Captures packaging board deficit in FMCG and pharma verticals with ISPM-15 compliant exports. |
| CSRD-Compliant Chain-of-Custody Certification | Unlocks brand-led procurement consortia pooling volume commitments in the Benelux region. |
| Near-Infrared Sorting Capacity Addition | Reduces contamination rates in mixed residential streams, expanding addressable feedstock pools. |
Study Parameters
Bottom-up end-use modeling reconciled against top-down recovered fiber supply tracking forms the analytical core of this study. Primary interviews with deinking plant managers, packaging converter procurement leads, municipal collection program administrators, and specialty chemical suppliers were validated against trade flow data, EPA diversion statistics, EU Waste Framework Directive implementation reports, and ECHA REACH authorization filings. Secondary sources include customs records for recovered paper and deinked pulp shipments, SEC 10-K disclosures from integrated forest products groups, and BIS draft standards for Indian recovered paper grades.
Historical trendline analysis of fiber price benchmarks, collection infrastructure investment cycles, and deinking capacity utilization rates informed projection modeling across the analysis window. Segmentation dimensions span product type, end-user channel, collection method, and processing technology, with additional granularity on enzymatic versus oxidative deinking chemistry adoption. CAGRs were derived from elasticity-adjusted demand curves incorporating e-commerce corrugated volume trajectories and regulatory mandate compliance timelines. Forecast inputs include EU Green Deal implementation pace, China's dual carbon goals enforcement intensity, and India's packaging board capacity buildout schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH chemical authorization delays, India's BIS certification finalization, and divergence between EU and US extended producer responsibility implementation. Forecasts reflect assumptions on collection infrastructure upgrade rates, deinking chemical cost trajectories, and brand-led procurement consortium formation velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
GCC Industrial Waste Management Market
Waste Management & Pollution Control
Hazardous Waste Handling Automation Market
Waste Management & Pollution Control
Global Waste Oil Market
Waste Management & Pollution Control
India Bio-Medical Waste Management Market
Waste Management & Pollution Control
Animal Waste Incinerator Market
Waste Management & Pollution Control
GCC Waste Management Market
Waste Management & Pollution Control
Automated Waste Collection System (AWCS) Market
Waste Management & Pollution Control
Household Composters Market
Waste Management & Pollution Control
Metal Recycling Baler Market
Waste Management & Pollution Control
Waste Compactor Bins Market
Waste Management & Pollution Control
India Commercial Food Waste Decomposer Market
Waste Management & Pollution Control
Solid Waste Management Market
Waste Management & Pollution Control
Alkaline Solid Waste Market
Waste Management & Pollution Control
Waste Recycling Services Market
Waste Management & Pollution Control
APAC Bio-Medical Waste Management Market
Waste Management & Pollution Control
Global Waste Management Equipment Market